
 Electron Beam Linear Accelerators Market | 2026-2036
Electron Beam Linear Accelerators Market Size, Share, and Industry Trends Forecast 2026-2036
Electron Beam Linear Accelerators Market Foresight
Buyer consolidation among large hospital networks is repositioning procurement leverage toward integrated delivery systems. Varian Medical Systems leverages its installed base across radiation oncology to sustain service revenue streams. Elekta AB competes through specialized workflow software that anchors clinical protocol standardization. Jiangsu Dasheng Electron Accelerator differentiates by dominating manufacturing scale in industrial sterilization systems for export markets.
Electron beam linear accelerators generate high-energy electrons through radiofrequency electromagnetic fields in evacuated waveguides, typically achieving beam energies from 4 MeV to 25 MeV for therapeutic or materials-processing applications. These systems serve primarily to deliver precise ionizing radiation for cancer treatment or to induce molecular cross-linking in polymers and sterilization of medical devices. Medical Accelerators command the largest revenue pool due to reimbursement-backed clinical adoption, while Research Accelerators represent the fastest-expanding category as national laboratories upgrade synchrotron and free-electron laser infrastructure. Compact Technology is displacing conventional standing-wave designs in emerging markets where facility footprint and shielding costs constrain deployment.
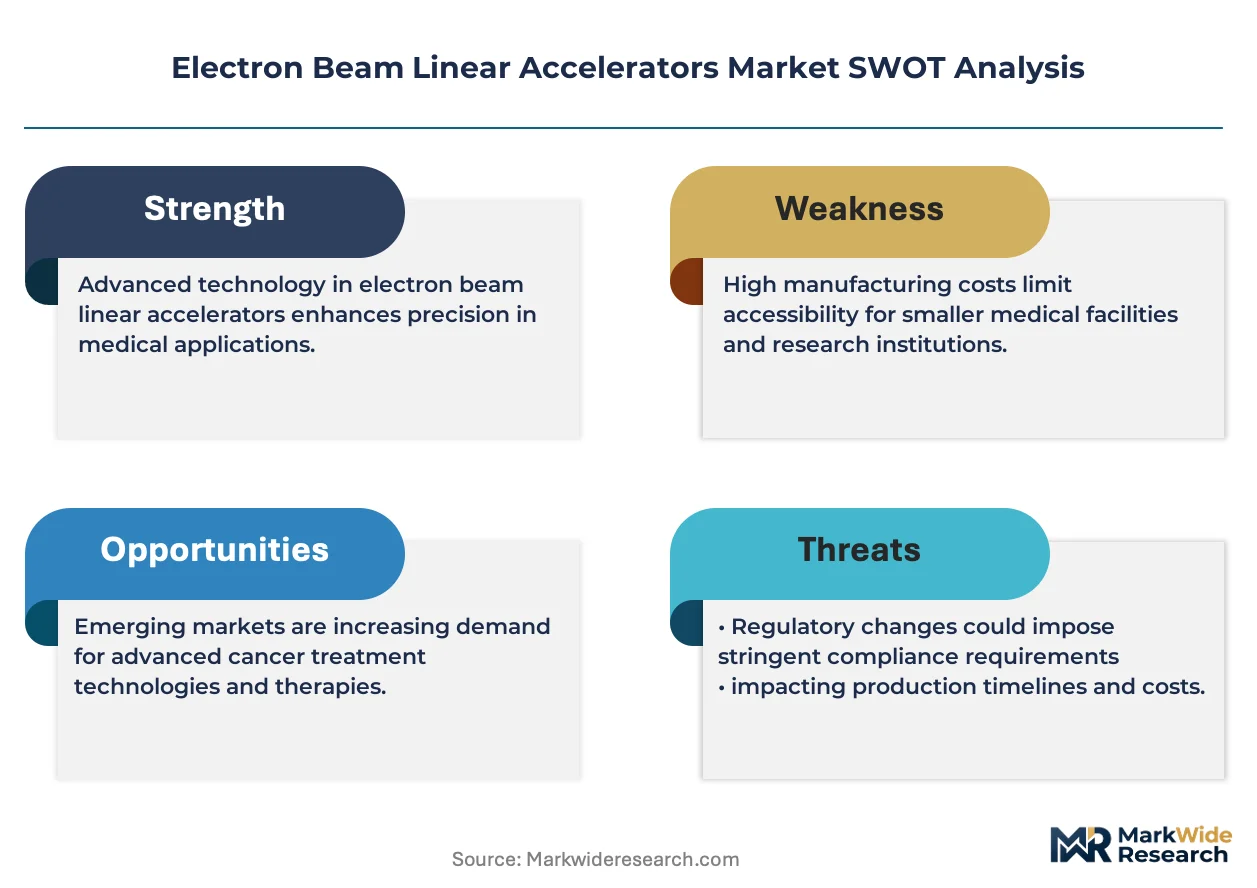
FDA radiation-emitting product regulations, EPA industrial effluent standards for accelerator facilities, and ISO 13485 quality management requirements collectively shape product design cycles and market access timelines. The EU Medical Device Regulation and CE marking requirements add compliance layers for manufacturers targeting European hospital procurement frameworks. Stakeholders must monitor evolving CMS reimbursement codes for hypofractionated therapy protocols and anticipate how superconducting technology transitions will reshape capital expenditure planning across buyer segments.
Market Dynamics
Buyer consolidation among large hospital networks is repositioning procurement leverage toward integrated delivery systems, while superconducting cavity technology is compressing the capital expenditure planning cycles of national laboratories and academic medical centers alike.
Growth Catalysts
- Hypofractionated therapy protocols:CMS reimbursement code expansions for accelerated treatment regimens are pulling electron beam systems into community oncology networks across the United States.
- EPA industrial effluent standards:Stricter discharge requirements for sterilization facilities are forcing medical device manufacturers toward electron beam alternatives to chemical processing.
- Compact standing-wave designs:Footprint-constrained installations in emerging markets are electrifying demand for shielding-reduced accelerator architectures.
Market Restraints
- Superconducting niobium supply concentration:Cavity fabrication depends on a handful of Japanese and European specialty metal suppliers, creating input cost volatility.
- FDA 510(k) radiation-emitting product reviews:Compressed timelines still impose clinical testing burdens that stretch smaller manufacturers' cash reserves.
- Proton therapy substitution:Heavy-ion treatment centers in South Korea and Germany are capturing premium oncology cases that once defaulted to electron modalities.
Strategic Opportunities
- Vietnam and Indonesia medical device sterilization:Export-oriented manufacturing zones lack electron beam infrastructure, presenting greenfield installation prospects.
- EU Medical Device Regulation Annex XVI expansion:New coverage of aesthetic and reconstructive devices is mandating sterilization upgrades across Portuguese and Polish contract manufacturers.
- Free-electron laser convergence with cryogenic cooling:National laboratories in Switzerland and Japan are integrating superconducting RF with next-generation photon science, opening accelerator upgrade cycles.
Industry Challenges
- RF engineer scarcity:The specialized skill set for klystron and magnetron maintenance is concentrating among aging workforces in the United States and Germany.
- ISO 13485 certification timelines:Quality management system audits for medical accelerator production are stretching 14-18 months, delaying market entry for new entrants.
- Legacy cobalt-60 facility retrofits:Shielding infrastructure from gamma-based sterilization plants requires complete reconstruction to accommodate electron beam penetration depths.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electron Beam Linear Accelerators Market |
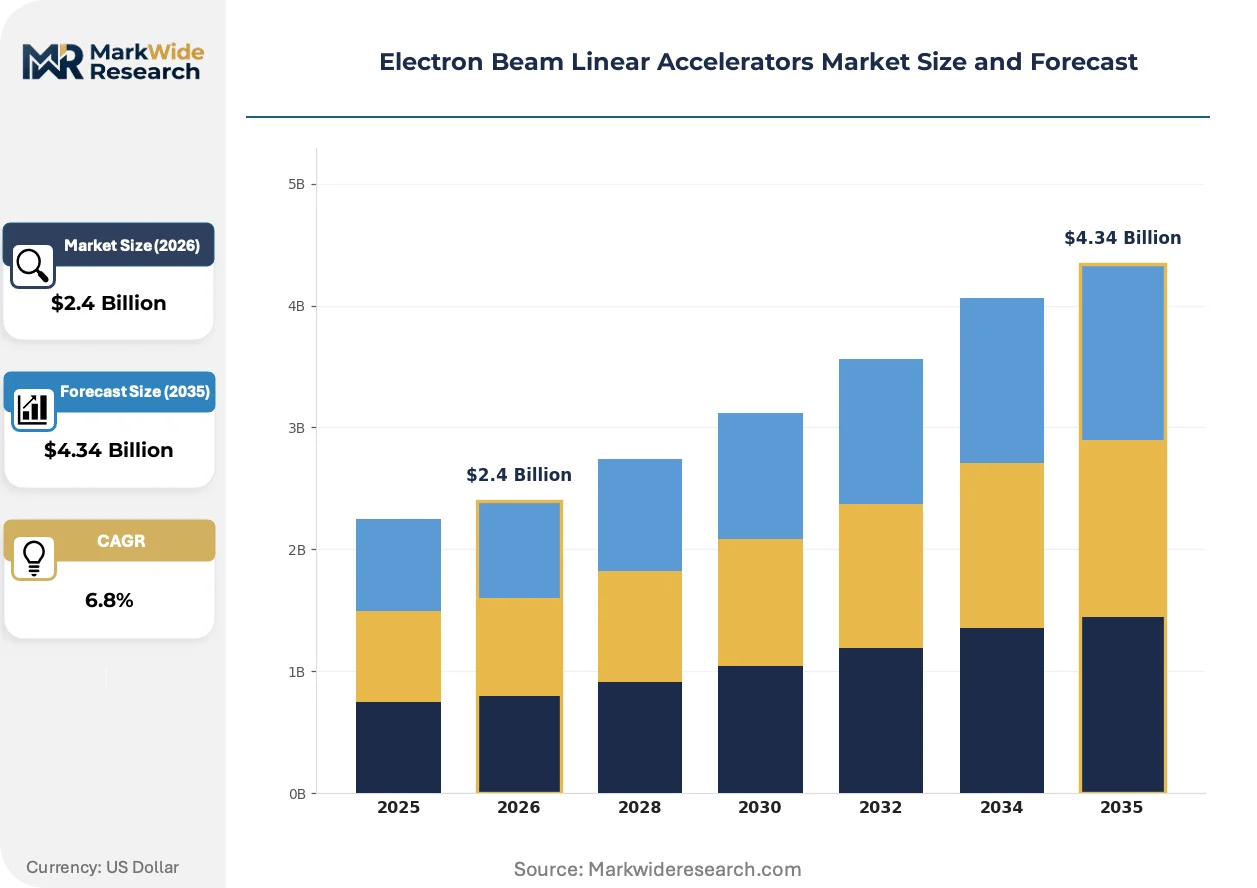
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Accelerators, Medical Accelerators, Research Accelerators, Radiation Therapy Systems End User: Hospitals, Research Institutions, Manufacturing Companies, Defense Sector Technology: Superconducting Technology, Conventional Technology, Hybrid Technology, Compact Technology Application: Medical Treatments, Materials Processing, Food Irradiation, Scientific Research |
| Companies Covered | IBA Industrial, ViewRay Inc., Varian Medical Systems, Jiangsu Dasheng Electron Accelerator, United Imaging Healthcare Co. Ltd., Elekta AB, Shinva Medical Instruments Co. Ltd., Mevex Corporation, Accuray Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electron Beam Linear Accelerators Market Shifts & Advancements
Radiofrequency source miniaturization and cryogenic efficiency gains are rewriting the capital intensity equations for both clinical and industrial deployment, while regulatory harmonization efforts are compressing multi-market approval timelines.
Superconducting radiofrequency cavities are electrifying the high-energy physics infrastructure landscape. These niobium-lined structures enable sustained gradient fields with dramatically reduced power consumption. National laboratories in Japan, Switzerland, and the United States are prioritizing SRF retrofits in their next funding cycles. The technology is electrifying the competitive positioning of accelerator vendors capable of delivering turnkey cryogenic systems.
REACH restrictions on ethylene oxide sterilization are accelerating electron beam adoption across European medical device supply chains. The ECHA authorization process has eliminated chemical alternatives for porous device categories. German and Irish contract sterilizers are now specifying 10 MeV accelerator capacity in new facility builds. The regulatory pressure is compressing the technology substitution timeline from decades to single-digit years.
Integrated delivery systems are unbundling equipment procurement from long-term service contracts. Large United States hospital networks now separate capital committees from clinical engineering oversight, creating dual-vendor opportunities. Academic medical centers in Texas and Massachusetts are piloting performance-based maintenance agreements that tie uptime guarantees to reimbursement flows. This behavioral shift is most visible in radiation oncology departments where beam reliability directly impacts patient throughput metrics.
Electron Beam Linear Accelerators Market Segmentation
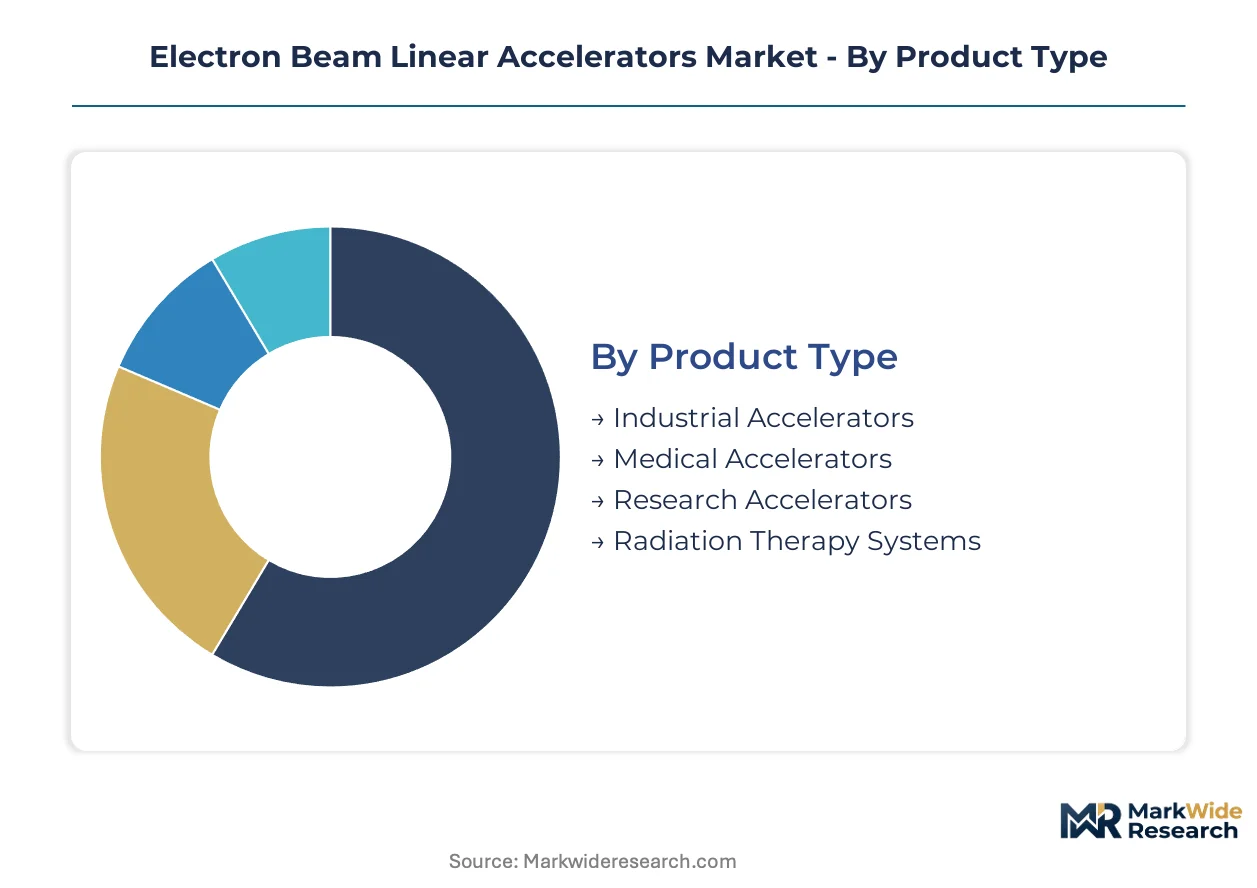
Capital allocation across electron beam accelerator segments follows divergent depreciation schedules and facility requirements. Procurement committees weigh shielding infrastructure costs against reimbursement velocity or production throughput. Each segmentation dimension reveals distinct buyer risk profiles and vendor margin structures.
Product Type:
Capital intensity peaks with radiation therapy systems requiring vault construction and clinical commissioning, while industrial sterilization units demand less civil works but higher throughput engineering.
- Medical Accelerators:These systems generate electron beams from 4 MeV to 25 MeV for precision oncology, incorporating multi-leaf collimators and image-guidance subsystems. Demand concentrates at academic medical centers in the United States, particularly around the Texas Medical Center cluster, where proton and electron therapy protocol expansion drives replacement cycles. CMS reimbursement code expansions for hypofractionated regimens are pulling these systems into community oncology networks.
- Radiation Therapy Systems:Integrated platforms combine beam generation with treatment planning software and patient positioning hardware. German and South Korean heavy-ion treatment centers are capturing premium oncology cases that once defaulted to standalone electron modalities, compressing addressable market boundaries for conventional configurations.
- Industrial Accelerators:10 MeV systems dominate medical device sterilization, inducing molecular cross-linking without chemical residues. REACH restrictions on ethylene oxide are accelerating specification in German and Irish contract sterilizer facilities.
- Research Accelerators:Synchrotron and free-electron laser infrastructure upgrades at national laboratories in Japan and Switzerland represent the steepest expansion trajectory in this category.
Most installed capacity flows through Medical Accelerators. Expansion is steepest in Research Accelerators.
End User:
Procurement authority varies sharply across buyer types, with integrated delivery systems wielding consolidated negotiating leverage against fragmented manufacturing purchasers.
- Hospitals:Radiation oncology departments at large United States hospital networks now separate capital committees from clinical engineering oversight, creating dual-vendor opportunities. Performance-based maintenance agreements piloted in Texas and Massachusetts tie uptime guarantees to patient throughput metrics and reimbursement flows.
- Research Institutions:National laboratories prioritize superconducting radiofrequency retrofits in next funding cycles, with cryogenic efficiency gains rewriting capital intensity equations for high-energy physics infrastructure.
- Manufacturing Companies:Export-oriented medical device producers in Vietnam and Indonesia lack electron beam sterilization infrastructure, presenting greenfield installation prospects as EPA industrial effluent standards tighten globally.
- Defense Sector:Specialized applications in materials testing and radiation hardening require customized beam parameters and security-cleared maintenance protocols.
Volume concentrates with Hospitals. Procurement sophistication is climbing fastest among Research Institutions.
Technology:
Power consumption and cryogenic infrastructure requirements create tiered operational cost structures that reshape total cost of ownership calculations across deployment contexts.
- Compact Technology:Shielding-reduced standing-wave architectures address facility footprint constraints in emerging markets where civil construction costs dominate project economics. These designs are displacing conventional configurations in Southeast Asian hospital procurement.
- Superconducting Technology:Niobium-lined cavities enable sustained gradient fields with dramatically reduced power consumption. Japanese and European specialty metal suppliers concentrate cavity fabrication inputs, creating cost volatility that stretches manufacturer cash reserves.
- Conventional Technology:Mature magnetron and klystron-based systems retain installed base dominance but face RF engineer scarcity as aging workforces in the United States and Germany concentrate maintenance expertise.
- Hybrid Technology:Configurations blending superconducting and conventional elements target mid-energy applications requiring operational flexibility without full cryogenic infrastructure.
Installed base remains concentrated in Conventional Technology. New order intake is shifting fastest toward Compact Technology.
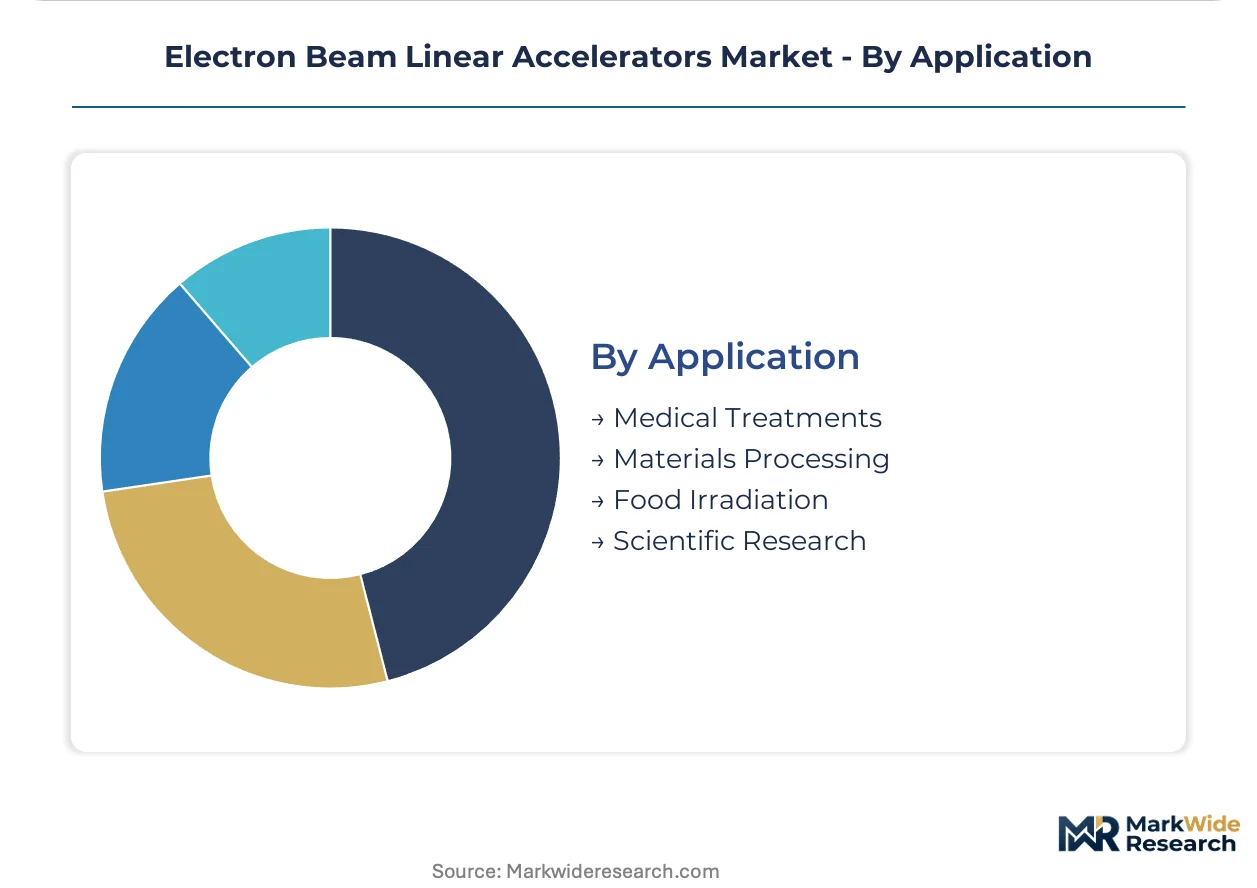
Application:
Regulatory compliance burdens vary by end-use, with medical treatments subject to FDA 510(k) radiation-emitting product reviews and ISO 13485 quality management requirements that stretch 14-18 months.
- Medical Treatments:Precision ionizing radiation delivery for cancer treatment commands the largest revenue pool due to reimbursement-backed clinical adoption. FDA clearance pathways are compressing product development timelines while imposing clinical testing burdens.
- Materials Processing:Polymer cross-linking and composite curing applications in automotive and aerospace supply chains demand beam stability metrics distinct from medical protocols.
- Food Irradiation:Phytosanitary treatment and pathogen reduction applications face consumer acceptance barriers that constrain deployment despite technical efficacy.
- Scientific Research:Free-electron laser convergence with cryogenic cooling at Swiss and Japanese national laboratories is opening accelerator upgrade cycles tied to photon science infrastructure.
Revenue concentration sits with Medical Treatments. Regulatory tailwinds are strongest for Materials Processing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates proton and electron therapy infrastructure while Germany drives industrial sterilization upgrades under REACH mandates. Japan and Switzerland anchor superconducting RF research investment cycles. China scales compact accelerator manufacturing for emerging market export.
United States
FDA 510(k) clearance pathways compress radiation therapy device timelines while CMS hypofractionated reimbursement codes expand community oncology procurement. The Texas Medical Center cluster anchors proton and electron therapy protocol development. Massachusetts academic medical centers pilot performance-based maintenance agreements tying beam uptime to patient throughput metrics.
Germany
ECHA REACH restrictions on ethylene oxide sterilization accelerate electron beam specification in medical device supply chains. German contract sterilizers now mandate 10 MeV accelerator capacity in new facility builds. The Rhine-Ruhr industrial corridor concentrates polymer cross-linking applications serving automotive and aerospace supply chains.
Japan
METI funding cycles prioritize superconducting radiofrequency retrofits at national laboratories for free-electron laser infrastructure. Japanese specialty metal suppliers concentrate niobium cavity fabrication inputs. The Kanto region around Tsukuba anchors photon science accelerator upgrade programs with cryogenic cooling integration.
Switzerland
Swissmedic medical device regulations align with EU MDR sterilization upgrade requirements for contract manufacturers. Swiss national laboratories integrate superconducting RF with next-generation photon science at Paul Scherrer Institute facilities. The Zurich-Bern corridor concentrates research accelerator engineering expertise.
China
NMPA medical device registration pathways streamline domestic accelerator approval for hospital procurement. Compact standing-wave designs from Chinese manufacturers penetrate Southeast Asian markets where facility footprint constraints dominate project economics. The Yangtze River Delta anchors industrial sterilization system export manufacturing.
Electron Beam Linear Accelerators Market Competitive Landscape
United States producers anchor the premium-tier radiation therapy segment; Chinese and European specialists hold industrial sterilization and research accelerator positions. The vendor base concentrates around integrated oncology platforms, compact industrial systems, and superconducting research infrastructure. Three archetypes dominate: therapy-focused integrated delivery vendors, industrial-scale sterilization equipment builders, and national laboratory research system suppliers. Competitive moves center on unbundling equipment procurement from long-term service contracts and superconducting technology licensing partnerships.
Within the integrated oncology platform tier, Varian Medical Systems and Elekta AB exemplify vendors leveraging installed base density to sustain service revenue streams. Jiangsu Dasheng Electron Accelerator represents the industrial-scale archetype dominating manufacturing capacity for sterilization system export markets. Among research infrastructure specialists, IBA Industrial occupies a position aligned with superconducting RF and proton therapy technology convergence.
| Leading Market Players |
|---|
| IBA Industrial |
| ViewRay Inc. |
| Varian Medical Systems |
| Jiangsu Dasheng Electron Accelerator |
| United Imaging Healthcare Co. Ltd. |
| Elekta AB |
| Shinva Medical Instruments Co. Ltd. |
| Mevex Corporation |
| Accuray Incorporated |
| Others |
Supply & Pricing Matrix
Superconducting niobium cavity fabrication is compressing production economics while concentrating supplier leverage among Japanese and European specialty metal producers. This technology transition simultaneously elevates input cost volatility and rewards accelerator vendors with captive cryogenic engineering capabilities.
Pricing Analysis
Capacity additions in China are reshaping price floors for compact standing-wave systems in Southeast Asian hospital procurement. Three-tier pricing structure across premium superconducting, standard conventional, and economy compact configurations dominates the vendor landscape. Price differentiation rests on ISO 13485 certification tier and after-sales service bundling. Margins are tightening in the conventional tier due to RF engineer scarcity in the United States and Germany. Community oncology networks exhibit highest price sensitivity; national laboratories demonstrate lowest.
Supply Chain Analysis
Dual-sourcing requirements for niobium ingots are mandating multi-supplier qualification across Japanese and European specialty metal vendors. Geographic supply concentration centers on Japan, Germany, and China for cavity fabrication and RF source components. Raw material dependencies include high-purity niobium, klystron vacuum tubes, and cryogenic cooling systems. Single-source vulnerability in superconducting cavity supply creates procurement risk for research accelerator programs. Distribution runs through direct OEM sales for medical systems and regional integrators for industrial sterilization deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers geographic-arbitrage value through sterilization infrastructure gaps between REACH-regulated Europe and export-oriented manufacturing zones in Vietnam and Indonesia lacking electron beam capacity.
For Market Incumbents: Lock in service revenue streams through performance-based maintenance agreements tied to beam uptime guarantees. Defend against proton therapy substitution by deepening clinical protocol integration at academic medical centers. Prioritize backward integration into niobium cavity fabrication to offset input cost volatility from Japanese suppliers.
For New Entrants and Emerging Players: Digital-channel route through cloud-based treatment planning software offers lower-friction entry into community oncology networks. Target industrial sterilization greenfield installations in Vietnamese and Indonesian export zones. Pursue regulatory-fast-track positioning via FDA 510(k) pre-submission pathways for compact system categories.
For Investors and Strategic Acquirers: Valuations sit cheapest among industrial-scale sterilization equipment builders with export manufacturing footprints. Long-term viability over the next decade hinges on superconducting technology transition execution and REACH regulatory tailwinds. Monitor CMS reimbursement code expansions for hypofractionated therapy as inflection indicator for medical accelerator demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Superconducting RF Technology Licensing | Enables niobium cavity fabrication capabilities for national laboratory contracts in Japan and Switzerland. |
| Compact System Manufacturing Scale-Up | Addresses facility footprint constraints driving Southeast Asian hospital procurement decisions. |
| REACH Compliance Certification Program | Positions sterilization systems for mandatory ethylene oxide replacement in German supply chains. |
| Performance-Based Service Contracting | Ties maintenance revenue to beam uptime metrics at Texas and Massachusetts academic centers. |
| Hypofractionated Therapy Protocol Development | Aligns product roadmaps with CMS reimbursement expansion for accelerated treatment regimens. |
Research Methodology
Coverage spans the United States, Germany, Japan, Switzerland, and China, with primary inputs from each market cluster. The study combines structured interviews with radiation oncology department heads, biomedical engineers at academic medical centers, contract sterilization facility managers, and national laboratory procurement officers with secondary validation. Sources include FDA 510(k) radiation-emitting product filings, ECHA REACH authorization databases, METI funding cycle disclosures, CMS Medicare reimbursement code updates, and hospital procurement database extracts. Bottom-up unit demand estimates triangulate against top-down capital expenditure surveys.
Granularity-level modeling operates at the intersection of product type, end-user category, technology tier, and application segment. The analytical framework projects volume and value across the projection horizon through installed base replacement cycles and greenfield penetration rates. CAGRs derive from regression analysis against historical capital equipment procurement patterns. Industry-specific forecast inputs incorporate superconducting technology adoption curves and EPA industrial effluent standard enforcement timelines.
The model assumes a particular technology adoption path; alternative pathways for superconducting RF convergence with cryogenic cooling would alter the outlook for research accelerator upgrade cycles. Forecasts reflect assumptions regarding CMS reimbursement continuity and REACH regulatory enforcement stringency. Deviation in niobium supply concentration or proton therapy substitution rates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Global Medical Refrigerators Market
Medical Equipment
Embedded Disinfection Cabinet Market
Medical Equipment
Proctologic Table Market
Medical Equipment
Solar Powered Vaccine Refrigerator Market
Medical Equipment
Cryochambers Market
Medical Equipment
Medical Equipment Rental Market
Medical Equipment
North America Durable Medical Equipment Market
Medical Equipment
Medical Gas Equipment Market
Medical Equipment
Urodynamic Equipment and Consumables Market
Medical Equipment
Hybrid Operating Room Market
Medical Equipment
Medical Equipment Leasing Market
Medical Equipment
Medical Oxygen Concentrators and Oxygen Cylinders Market
Medical Equipment
Global Surgical Table Market
Medical Equipment
Global Medical Vacuum System Market
Medical Equipment
Operating Table Parts Market
Medical Equipment
Refurbished MRI Systems Market