
 Bone Broth Protein Powder Market | 2026-2036
Bone Broth Protein Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Bone Broth Protein Powder Market Analytics
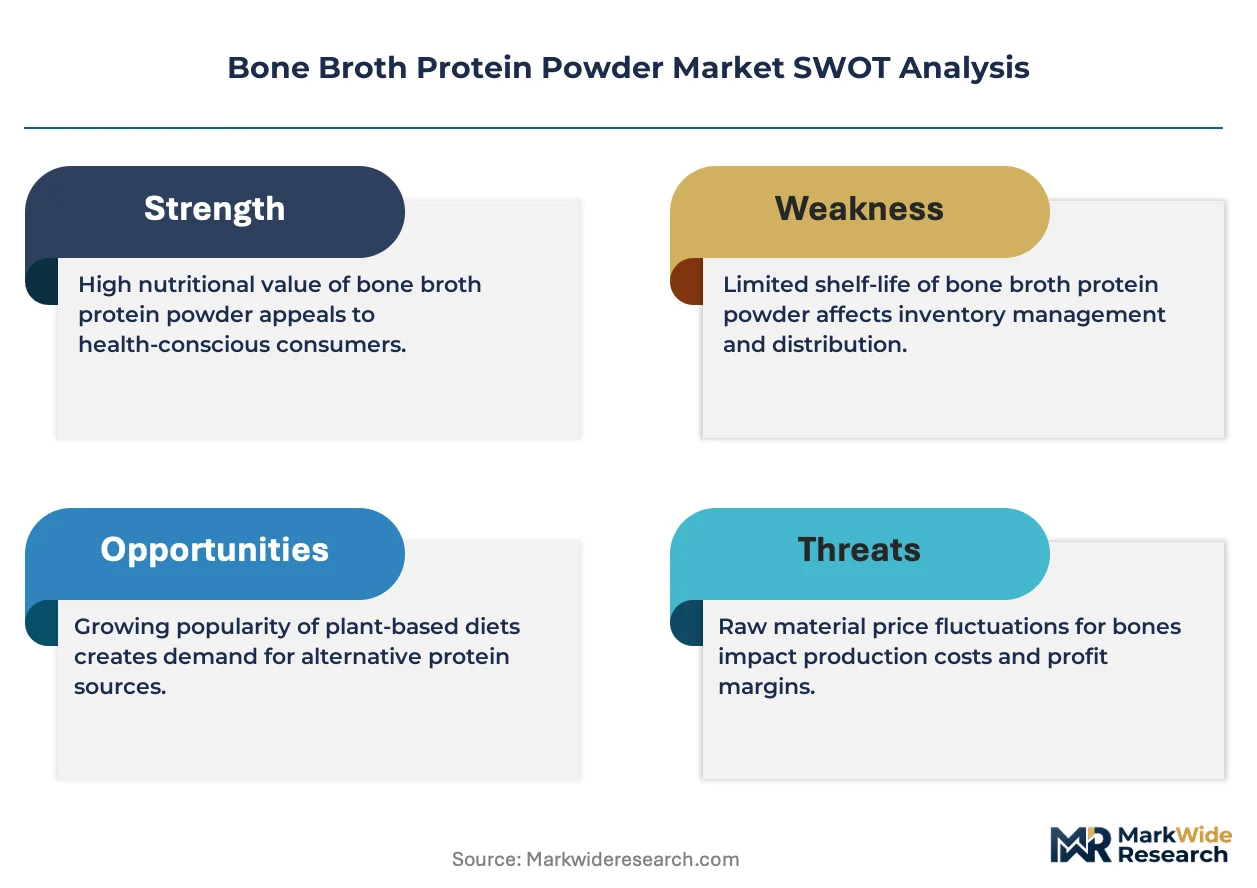
Supply of certified food-grade collagen processing technicians is collapsing across North American and European manufacturing hubs, constraining batch consistency and slowing capacity expansion for premium bone broth protein isolates. Ancient Nutrition leverages its vertically integrated supply chain from grass-fed cattle sourcing to finished powder packaging. Vital Proteins sustains dominant shelf presence through aggressive retail distribution partnerships with mass-market and specialty grocers. Kettle & Fire differentiates via ready-to-drink liquid bone broth extensions that feed powder brand recognition.
Bone broth protein powder consists of dehydrated, concentrated protein extracted from simmered animal bones and connective tissues, typically yielding 15-20 grams of protein per serving with collagen types I and II, glycine, and proline as principal amino constituents; manufacturers employ low-temperature spray drying or freeze-drying to preserve heat-sensitive peptide bioactivity for sports recovery and gut health applications. Beef-derived variants anchor the product type landscape due to higher collagen density and established consumer preference for bovine sourcing transparency. Sports nutrition applications capture the fastest expansion trajectory within the application matrix, while dietary supplements remain the mature revenue base with slower velocity but higher per-unit margins.
FDA oversight of structure-function claims and USDA organic certification requirements shape permissible marketing language and ingredient sourcing protocols for domestic manufacturers, while EFSA novel food assessments govern European market entry for non-traditional protein isolates. Compliance costs with evolving allergen labeling rules and heavy metal testing thresholds under state-level California Proposition 65 enforcement are redirecting R&D spending toward purification technology investments. Stakeholders must monitor pending FDA guidance on collagen peptide health claim substantiation, as this determination will reshape competitive positioning across powder and ready-to-mix formats.
Market Dynamics
Clean-label certification mandates from FDA and EFSA are compressing formulation flexibility while simultaneously creating tiered market access based on compliance depth. This regulatory bifurcation rewards vertically integrated producers with captive sourcing documentation while marginalizing contract manufacturers dependent on opaque supply chains.
Growth Catalysts
- Sports Nutrition Demand:Athletes and fitness enthusiasts seek collagen-dense recovery formulations with transparent amino acid profiles. This segment commands premium positioning through performance-linked structure-function claims.
- California Proposition 65 Enforcement:Heavy metal testing thresholds are accelerating purification technology investments among domestic manufacturers. Compliance infrastructure now functions as a competitive moat against import competition.
- Direct-to-Consumer Infrastructure:Subscription platforms and specialized e-commerce channels bypass traditional retail gatekeepers. Brands capture margin expansion through controlled customer acquisition and loyalty programming.
Market Restraints
- Collagen Processing Technician Scarcity:North American and European manufacturing hubs face collapsing supply of certified food-grade specialists. Batch consistency suffers and capacity expansion stalls for premium isolates.
- Grass-Fed Cattle Input Volatility:Pasture-raised sourcing requirements constrain raw material availability during seasonal drought cycles. Price premiums for verified supply chains compress mid-tier producer margins.
- EFSA Novel Food Assessments:European market entry for non-traditional protein isolates requires extensive safety documentation. Timeline uncertainty deters smaller manufacturers from cross-border expansion.
Strategic Opportunities
- Ready-to-Drink Liquid Extensions:Kettle & Fire's format diversification demonstrates brand recognition transfer from liquid to powder categories. Manufacturers can capture dual-channel presence with integrated liquid-powder portfolios.
- Gut Health Positioning:Emerging clinical validation of glycine and proline for intestinal barrier function opens therapeutic adjacent markets. Medical food and clinical nutrition channels remain underdeveloped for bone broth derivatives.
- USDA Organic Certification Tailwinds:Federal procurement preferences and retailer shelf-space allocation increasingly favor certified organic positioning. Early compliance investments yield downstream distribution advantages.
Industry Challenges
- Peptide Bioactivity Preservation:Low-temperature spray drying and freeze-drying equipment requires specialized capital deployment. Technical staff training for thermal process optimization extends facility commissioning timelines.
- Structure-Function Claim Substantiation:Pending FDA guidance on collagen peptide health claims creates marketing language uncertainty. Legal review cycles lengthen and campaign launch windows compress.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bone Broth Protein Powder Market |
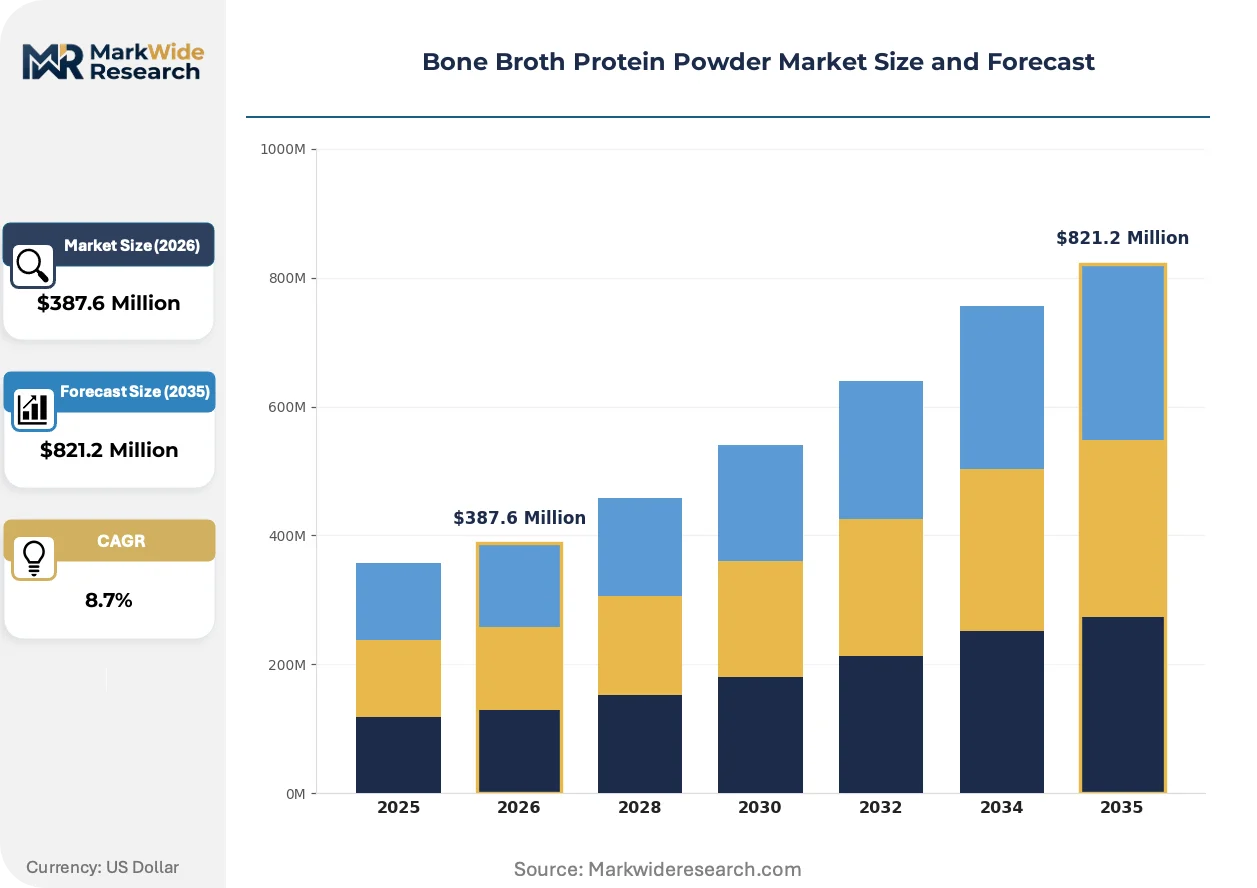
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beef, Chicken, Seafood, Vegetarian Application: Dietary Supplements, Sports Nutrition, Culinary Use, Health Foods End User: Health-Conscious Consumers, Athletes, Fitness Enthusiasts, Culinary Professionals Packaging Type: Pouches, Jars, Sachets, Tubs |
| Companies Covered | Kettle & Fire, Ancient Nutrition, Vital Proteins, Bonafide Provisions, Epic Provisions, Bare Bones, Swanson, Sports Research, Essentia Proteins, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bone Broth Protein Powder Market Evolving Landscape
Processing technology convergence and regulatory documentation requirements are elevating capital barriers while simultaneously opening format diversification pathways. Manufacturers must balance bioactivity preservation with scale economics.
Enzymatic hydrolysis protocols are fragmenting traditional heat-extraction methods across premium tier production. Sports nutrition formulators adopt these cold-processing approaches to maximize peptide molecular weight retention for recovery applications. Equipment suppliers report extended order backlogs as facility retrofits accelerate.
EFSA novel food assessment frameworks are reshaping European import protocols for non-traditional protein isolates. Documentation burdens for bone-derived collagen sources now rival those for insect or algae proteins. Domestic European manufacturers leverage proximity advantages for faster regulatory clearance cycles.
Athlete procurement patterns increasingly favor certified clean-label suppliers with batch-level heavy metal documentation. Institutional sports programs and professional team nutritionists conduct direct supplier audits bypassing traditional distributor relationships. United States collegiate athletic departments demonstrate the most rigorous verification standards.
Bone Broth Protein Powder Market Segmentation
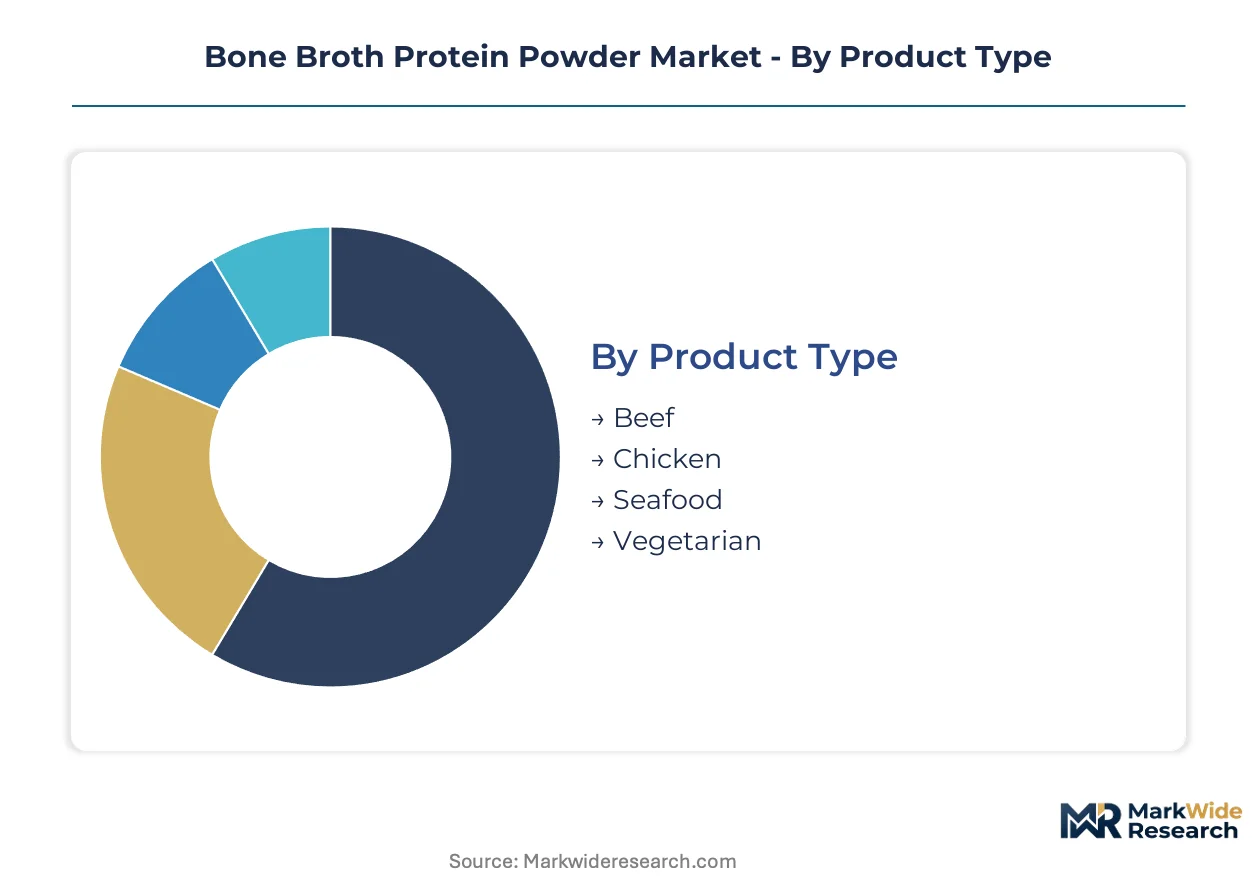
Segmentation in bone broth protein powder reveals how sourcing transparency and application-specific bioactivity requirements create distinct competitive arenas. Manufacturers must align purification investments with the verification standards of each user cohort.
Product Type:
Plant-based protein isolates and marine collagen alternatives exert substitution pressure on traditional animal-derived segments, forcing bovine and poultry sourcing to emphasize transparency documentation.
- Beef:Higher collagen density in bovine bones yields 15-20 gram protein servings with dominant type I and III collagen profiles. Demand concentrates among CrossFit athletes and functional medicine practitioners in the United States who prioritize grass-fed verification and heavy metal batch testing. Pasture-raised sourcing requirements create supply bottlenecks during seasonal drought cycles.
- Chicken:Type II collagen predominates in avian-derived isolates, supporting joint health positioning distinct from beef's skin and recovery applications. Procurement from collegiate athletic departments favors chicken sourcing for its lower environmental footprint narrative and competitive unit economics. EFSA novel food assessments treat chicken collagen more favorably than non-traditional isolates.
- Seafood:Marine collagen appeals to pescatarian-adjacent consumers seeking alternatives to mammalian sources.
- Vegetarian:Fermented amino acid blends and plant protein combinations serve consumers with religious or ethical restrictions on animal derivatives.
Beef anchors the volume base while chicken gains share at the steepest rate.
Application:
Cost tier differentiation separates premium clinical-grade isolates from commodity bulk powders, with sports nutrition commanding the highest per-unit investment in bioactivity preservation.
- Dietary Supplements:Capsule and tablet formulations dominate this mature revenue channel with slower velocity but higher margin retention. Direct-to-consumer subscription platforms bypass retail gatekeepers for recurring revenue capture. FDA structure-function claim scrutiny lengthens legal review cycles for new product launches.
- Sports Nutrition:Ready-to-mix powders with enzymatic hydrolysis processing maximize peptide molecular weight for post-workout recovery applications. Institutional procurement from professional team nutritionists demands batch-level heavy metal documentation and third-party certification. This segment climbs the fastest as athlete influencers drive clean-label preference formation.
- Culinary Use:Flavor-neutral isolates integrate into soups, sauces, and baked goods for stealth protein fortification.
- Health Foods:Functional bar and beverage applications leverage bone broth positioning for gut health and immunity claims.
Dietary supplements retain the widest margin spread while sports nutrition expands most quickly.
End User:
Volume concentration tracks fitness infrastructure density, with metropolitan wellness corridors generating disproportionate per-capita consumption.
- Health-Conscious Consumers:This cohort drives subscription platform adoption and loyalty programming investments. Gut health positioning and glycine-rich formulations attract functional medicine adherents seeking intestinal barrier support. California Proposition 65 awareness elevates heavy metal documentation requirements for this segment.
- Athletes:Collegiate and professional programs conduct direct supplier audits bypassing traditional distribution. Peptide bioactivity preservation commands premium pricing through performance-linked recovery claims. USDA organic certification functions as a procurement filter for institutional buyers.
- Fitness Enthusiasts:Boutique gym affiliations and influencer recommendations shape brand selection for this price-sensitive tier.
- Culinary Professionals:Restaurant and foodservice applications prioritize flavor neutrality and solubility under thermal stress.
Health-conscious consumers anchor the volume base while athletes gain share at the steepest rate.
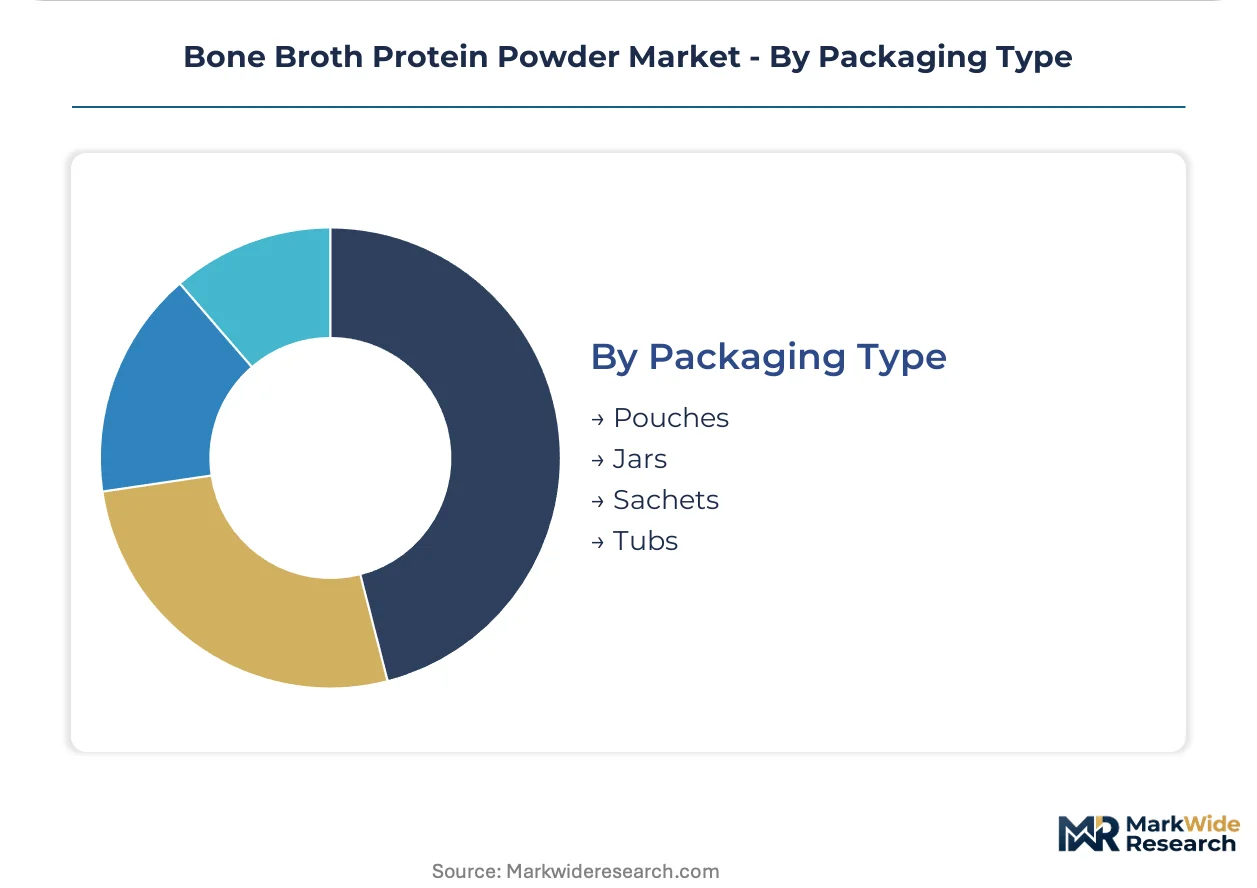
Packaging Type:
Margin structure favors larger-format containers for established users and single-serve convenience for trial and travel occasions.
- Pouches:Flexible packaging reduces shipping cube and supports subscription logistics optimization.
- Jars:Premium positioning with resealability for kitchen counter visibility and repeat access.
- Sachets:Single-serve portability targets travel and gym bag occasions with controlled dosing.
- Tubs:Bulk formats capture household volume with lowest per-serving packaging cost.
Tubs anchor the volume base while sachets gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA structure-function claim oversight and California Proposition 65 enforcement anchor the United States as the dominant geography, while EFSA novel food assessments govern European market entry protocols for bone-derived protein isolates.
United States
CrossFit athletes and functional medicine practitioners drive concentrated demand for grass-fed bovine collagen with batch-level heavy metal documentation. California Proposition 65 enforcement accelerates purification technology investments among domestic manufacturers. The Austin-San Antonio corridor hosts multiple direct-to-consumer brands leveraging subscription platform infrastructure.
Germany
EFSA novel food assessment frameworks reshape import protocols for non-traditional protein isolates, favoring domestic European manufacturers with faster regulatory clearance cycles. Sports nutrition formulators in Bavaria adopt enzymatic hydrolysis protocols to maximize peptide molecular weight retention for recovery applications. Munich-based ingredient suppliers report extended equipment order backlogs as facility retrofits accelerate.
United Kingdom
Collegiate athletic departments and professional team nutritionists conduct direct supplier audits bypassing traditional distributor relationships for certified clean-label suppliers. The country's national food standards regulator maintains alignment with EFSA frameworks while enforcing additional allergen labeling requirements. London wellness corridors generate disproportionate per-capita consumption of gut health positioned formulations.
Canada
Health Canada oversight of natural health product licensing creates distinct pathways for bone broth protein powder market entry separate from US FDA protocols. Prairie province cattle ranching supplies pasture-raised sourcing for premium tier manufacturers. Toronto and Vancouver metropolitan clusters concentrate direct-to-consumer brand headquarters and e-commerce fulfillment infrastructure.
Australia
TGA therapeutic goods administration governs structure-function claim substantiation for collagen peptide products marketed with recovery or joint health benefits. Grass-fed cattle abundance from Queensland and New South Wales ranches supports transparent sourcing documentation requirements. Sydney and Melbourne functional food retail channels demonstrate advanced development comparable to US coastal markets.
Bone Broth Protein Powder Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the former commanding captive supply chain documentation and the latter competing on format innovation or channel focus. Three archetypes populate the competitive terrain: vertically integrated ranch-to-powder operators, retail-dominant mass-market brands, and liquid-format originators extending into powder categories. Capacity expansion and portfolio diversification represent the dominant competitive moves, with manufacturers retrofitting facilities for enzymatic hydrolysis and launching ready-to-drink liquid extensions.
Within the integrated supply chain tier, Ancient Nutrition exemplifies backward integration from grass-fed cattle sourcing through finished powder packaging. Vital Proteins occupies a position as the retail-dominant archetype with mass-market and specialty grocer shelf presence. Kettle & Fire anchors the liquid-originator segment, demonstrating brand recognition transfer from ready-to-drink bone broth into powder format diversification.
| Leading Market Players |
|---|
| Kettle & Fire |
| Ancient Nutrition |
| Vital Proteins |
| Bonafide Provisions |
| Epic Provisions |
| Bare Bones |
| Swanson |
| Sports Research |
| Essentia Proteins |
| Others |
Value Network & Pricing Analysis
Enzymatic hydrolysis equipment replacing traditional heat-extraction infrastructure simultaneously concentrates production in Germany and the United States while compressing mid-tier margins through capital intensity requirements. This substitution dynamic elevates pricing power for certified manufacturers with captive low-temperature processing capabilities while contract operators face volume discount pressure from retail consolidators.
Pricing Analysis
Geographic price spreads between North American and European markets reflect California Proposition 65 compliance cost differentials and EFSA novel food assessment documentation burdens. Three-tier pricing structure across premium enzymatic-hydrolyzed, standard spray-dried, and economy heat-extracted levels separates batch-certified clinical grades from commodity bulk powders. Pricing pressure stems from grass-fed cattle input volatility during seasonal drought cycles. Health-conscious consumers demonstrate highest price sensitivity while institutional athletic programs prioritize certification over unit cost.
Supply Chain Analysis
Strategic stockpiling of pasture-raised cattle bones dominates manufacturer inventory strategy given seasonal sourcing constraints and batch consistency requirements. Supply concentrates in United States prairie provinces, Australian Queensland ranches, and German Bavarian processing hubs. Raw material dependencies include grass-fed bovine bones, avian cartilage, and marine collagen sources. Single-source vulnerability runs through certified food-grade collagen processing technician availability. Distribution runs through direct-to-consumer subscription platforms bypassing traditional retail gatekeepers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as athlete procurement patterns shift toward direct supplier audits, creating niche openings for certified regional operators outside mass-market retail concentration.
For Market Incumbents: Secure captive supply chain documentation through backward integration into grass-fed cattle sourcing partnerships. Expand enzymatic hydrolysis capacity in Texas and Bavaria to defend against import competition from EFSA-favored domestic European manufacturers. Certification investment in USDA organic and batch-level heavy metal testing functions as the primary defensive lever against contract manufacturer price erosion. For New Entrants and Emerging Players: White-space clinical nutrition channel penetration offers lowest competitive density as medical food applications for gut health positioning remain underdeveloped. Target collegiate athletic departments with direct procurement relationships bypassing distributor markups. Launch with subscription-based direct-to-consumer platforms featuring transparent amino acid profiling and third-party certification documentation. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated operators with captive sourcing and regulatory clearance infrastructure. Long-term viability hinges on enzymatic processing capabilities and EFSA documentation depth across the projection horizon. Acquisition target archetype includes regional enzymatic hydrolysis specialists with existing athlete procurement relationships. Watch for FDA guidance finalization on collagen peptide health claim substantiation as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Hydrolysis Facility Retrofit | Maximizes peptide bioactivity retention for sports nutrition recovery applications. |
| Grass-Fed Cattle Sourcing Partnership | Secures pasture-raised supply chain documentation for California Proposition 65 compliance. |
| Direct-to-Consumer Subscription Launch | Bypasses retail gatekeepers to capture margin expansion through controlled customer acquisition. |
| EFSA Novel Food Assessment Completion | Accelerates European market entry against import documentation burdens for non-traditional isolates. |
| Clinical Nutrition Channel Development | Opens therapeutic adjacent markets through glycine and proline intestinal barrier function positioning. |
Research Methodology
Cross-validation between primary interviews with sports nutrition formulators, regulatory affairs specialists at collagen processing facilities, direct-to-consumer brand executives, and collegiate athletic procurement officers anchors the qualitative findings. Secondary validation draws from FDA structure-function claim filings, EFSA novel food assessment databases, USDA organic certification records, and California Proposition 65 enforcement actions. Bottom-up segmentation modeling triangulates against top-down market sizing from trade flow analysis.
Sensitivity analysis across enzymatic hydrolysis adoption rates, grass-fed cattle supply volatility, and regulatory clearance timeline variations informs the projection framework. Segmentation dimensions include product type, application, end user, and packaging format across the analysis window. CAGRs derive from elasticity-adjusted demand curves incorporating athlete influencer adoption patterns and institutional procurement shift trajectories. Forecast inputs capture purification technology investment cycles and certified technician training pipeline constraints.
Underlying assumptions cover sustained clean-label certification preference formation, with deviation risk concentrated in pending FDA collagen peptide health claim guidance and EFSA assessment framework evolution. Forecasts reflect these documented conditions. Revision becomes warranted when regulatory clearance timelines or grass-fed sourcing verification standards cross material threshold shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Spirulina Purple Blend Market
Nutritional Supplements
Spirulina Extract Market
Nutritional Supplements
Isolate Whey Protein Market
Nutritional Supplements
US Hangover Cure Products Market
Nutritional Supplements
Multi Nutritional Supplement Market
Nutritional Supplements
Middle East and Africa Nutraceutical Excipients Market
Nutritional Supplements
Omega-3 Fatty Acids Market
Nutritional Supplements
Vegetable Capsules Market
Nutritional Supplements
Nutrition Powder Market
Nutritional Supplements
Chaga Mushroom Extract Market
Nutritional Supplements
Plant Based Protein Supplements Market
Nutritional Supplements
Human Nutrition Market
Nutritional Supplements
CBD Nutraceuticals Market
Nutritional Supplements
Liquid Dietary Supplements Market
Nutritional Supplements
Nicotine Gum Market
Nutritional Supplements
Calcium HMB Market