
 Ear Piercing Guns Market | 2026-2036
Ear Piercing Guns Market Size, Share, and Industry Trends Forecast 2026-2036
Ear Piercing Guns Market Insights
Chinese OEM capacity for precision-molded plastic piercing mechanisms is broadening the global supply base for entry-level instruments. Studex leverages its captive manufacturing network to sustain price competitiveness across mass retail channels. Inverness Corporation anchors its position through proprietary cartridge systems that lock out unauthorized needle refills. Blomdahl Medical differentiates via nickel-free alloy specialization that targets pediatric and allergy-sensitive segments.
An ear piercing gun is a handheld mechanical or spring-loaded device designed to insert a stud or hollow needle through earlobe or cartilage tissue with controlled depth and minimal trauma, typically constructed from medical-grade plastics or stainless steel housings with disposable or sterilizable contact components. The instrument serves commercial cosmetic piercing, clinical procedures, and retail event applications where speed, consistency, and hygiene compliance determine operational viability. Disposable guns command expanding share among hospital and beauty salon end users seeking to eliminate autoclave dependency and liability exposure. Manual guns retain dominance in jewelry stores and specialty shops where cost sensitivity and operator tradition outweigh convenience premiums. Titanium and nickel-free alloy materials capture margin concentration as regulatory scrutiny on dermal metal sensitivity intensifies across major markets.
FDA Class I device exemptions and EU MDR general safety requirements shape material selection, labeling, and sterility assurance protocols for piercing instruments distributed in the United States and European Union. Japan's PMDA and METI coordinate on import inspection standards that restrict non-certified piercing devices from entering clinical and retail channels. China's NMPA and GB standards impose additional biocompatibility testing on metal components destined for domestic beauty salon chains. Stakeholders must monitor evolving national medical device reclassifications that could shift piercing guns from cosmetic tools to regulated instruments, altering compliance costs and channel access rules.
Market Dynamics
Disposable cartridge systems are compressing replacement cycles across retail piercing operations, forcing manufacturers to prioritize sterility assurance over mechanical durability in product design.
Growth Catalysts
- EU MDR sterilization mandates:Jewelry chains in Germany and France accelerate equipment turnover to meet instrument traceability requirements, expanding replacement demand for compliant piercing systems.
- Nickel-free alloy specialization:Pediatric clinics and allergy-sensitive segments drive premium material adoption as dermal sensitivity awareness spreads through consumer channels.
- Chinese precision molding capacity:Entry-level instrument supply broadens as OEM manufacturers in Zhejiang and Guangdong scale medical-grade plastic component production for export markets.
Market Restraints
- Stainless steel price volatility:Surgical-grade 316L input costs fluctuate with nickel market movements, compressing margins for metal-housing manufacturers.
- FDA Class I reclassification risk:Potential shift from cosmetic tool to regulated medical device status would impose clinical trial burdens and channel access restrictions on domestic distributors.
- Manual gun operator tradition:Jewelry store owners resist disposable premiums where autoclave infrastructure already exists, slowing category conversion in cost-sensitive retail tiers.
Strategic Opportunities
- Japan medical aesthetic clinic expansion:Tokyo and Osaka dermatology chains seek piercing services as ancillary revenue, creating demand for clinical-grade disposable systems.
- Biocompatibility certification convergence:ISO 10993 testing alignment with EU MDR and Japan PMDA requirements enables single-SKU regulatory coverage across high-value markets.
- Event-based mobile piercing:Festival and pop-up retail channels adopt single-use guns to eliminate sterilization logistics in temporary locations.
Industry Challenges
- Autoclave technician certification gaps:Beauty salons face operator training bottlenecks as sterilization competency requirements tighten under state-level health department inspections.
- Patent thickets around cartridge locking mechanisms:Proprietary refill prevention systems create licensing friction for manufacturers seeking compatible aftermarket components.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ear Piercing Guns Market |
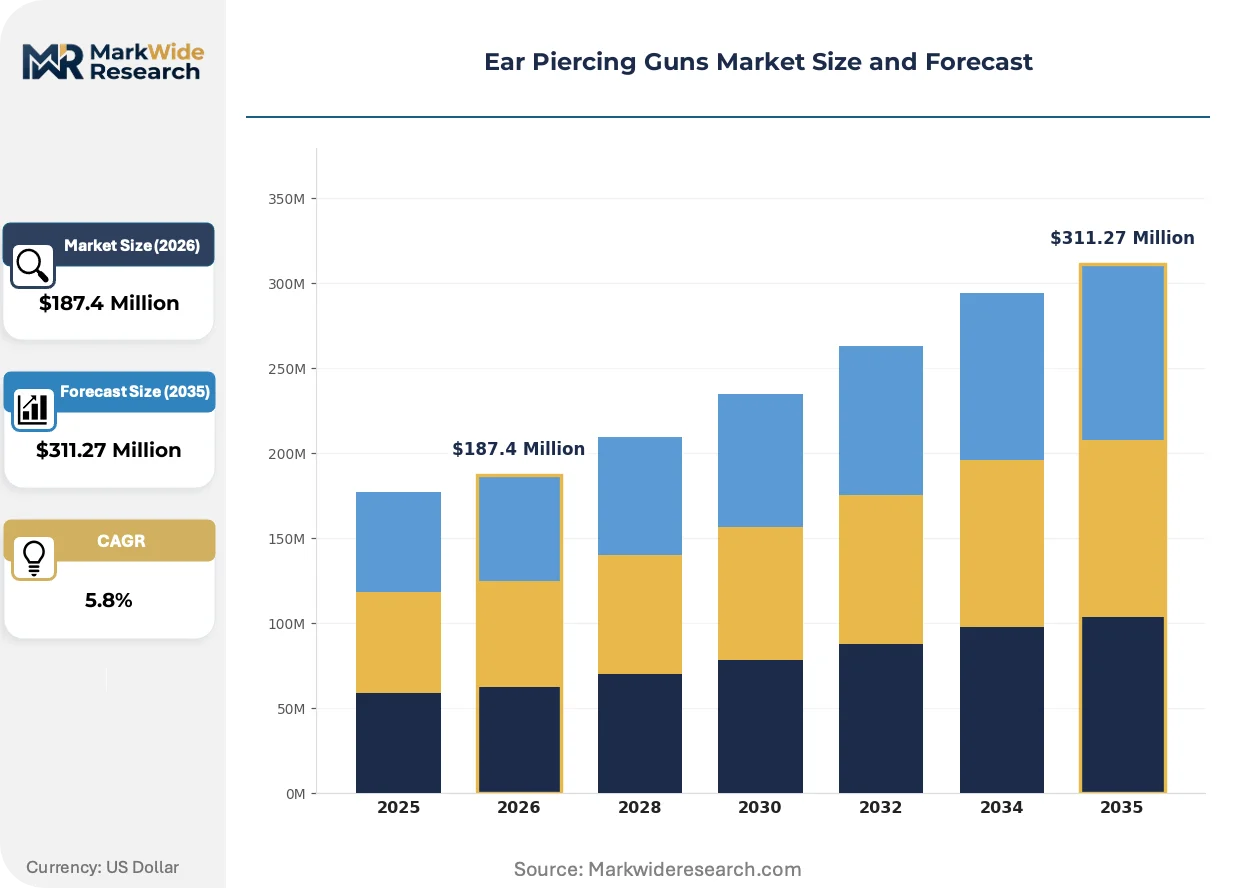
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Guns, Automatic Guns, Disposable Guns, Piercing Instruments End User: Jewelry Stores, Hospitals, Beauty Salons, Specialty Shops Material: Plastic, Stainless Steel, Titanium, Nickel-Free Alloys Application: Cosmetic, Medical, Retail Sales, Events |
| Companies Covered | Studex, Inverness Corporation, Blomdahl Medical, Caflon, Piercing Pagoda, System75, Claire's, Medisept, Lorinser Piercing Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ear Piercing Guns Market Trends and Innovations
Material science advances and regulatory harmonization are compressing product development timelines while fragmenting procurement authority across new buyer segments.
Pre-sterilized disposable piercing guns are decentralizing service delivery by eliminating capital equipment dependencies. Mobile retail operators and temporary event vendors adopt these systems at accelerating rates. The technology is decentralizing piercing service provision from fixed retail locations into pop-up and on-demand formats.
EU MDR instrument traceability requirements are forcing sterilization documentation upgrades across European supply chains. Manufacturers must implement unique device identification and post-market surveillance systems. German jewelry retail chains bear the heaviest compliance burden, driving consolidation toward suppliers with established quality management systems.
Hospital procurement departments are assuming purchasing authority previously held by individual clinic managers, consolidating vendor selection and standardizing on disposable platforms. Group purchasing organizations negotiate enterprise contracts that displace fragmented spot buying. This concentration is most visible in United States outpatient surgery center networks seeking liability reduction through single-use instrument policies.
Ear Piercing Guns Market Segmentation
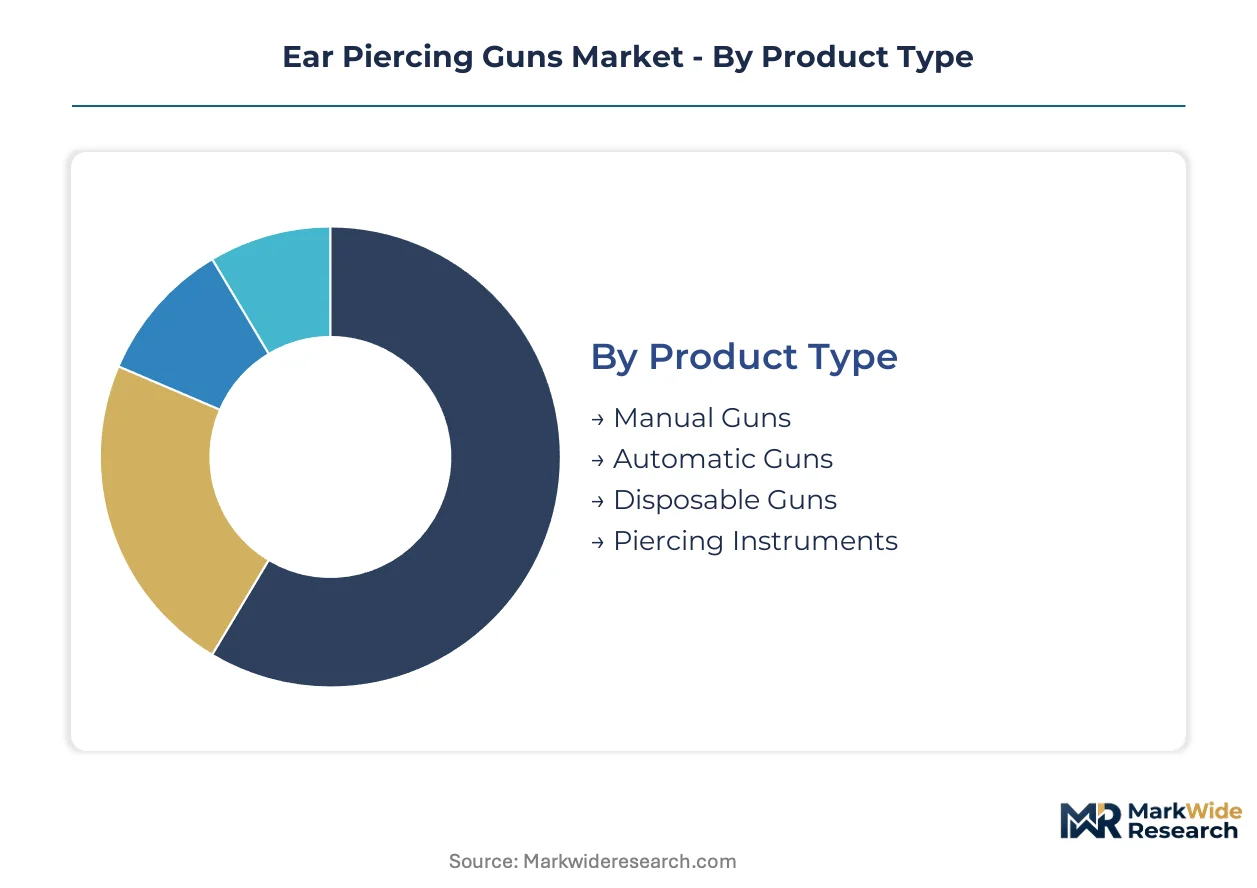
Ear piercing gun procurement divides sharply between liability-conscious institutional buyers and cost-driven independent retailers, with certification requirements determining channel eligibility. Material specifications and sterility protocols create tiered compliance burdens that reshape vendor selection across each segment cluster.
Product Type:
EU MDR traceability mandates and FDA device exemptions create divergent certification pathways—disposable systems face sterility documentation requirements while manual guns navigate cosmetic tool classifications with lighter oversight.
- Manual Guns:Spring-loaded mechanical housings constructed from medical-grade plastics or stainless steel require operator skill for depth control. Jewelry stores in Germany and Japan retain these systems where autoclave infrastructure already exists, though EU MDR instrument tracking is forcing documentation upgrades even for non-disposable platforms.
- Disposable Guns:Pre-sterilized single-use cartridges eliminate cross-contamination liability and autoclave dependency. Hospitals in the United States and medical aesthetic clinics in Tokyo adopt these fastest as group purchasing organizations consolidate procurement around single-use policies.
- Automatic Guns:Motorized or battery-powered insertion mechanisms with programmable depth settings. United States outpatient surgery centers specify these for cartilage procedures requiring precision control.
- Piercing Instruments:Broader category encompassing forceps, needles, and auxiliary tools used alongside gun systems. Beauty salon chains in France integrate these into comprehensive service protocols.
Manual guns sit at the top of the volume ranking, with disposable guns climbing the fastest.
End User:
Procurement authority is shifting from individual operators to centralized purchasing departments, with liability exposure driving divergence between institutional and retail buying patterns.
- Jewelry Stores:Traditional channel commanding replacement cycles through operator tradition and cost sensitivity. Chains in the United States resist disposable premiums where capital equipment is already amortized.
- Hospitals:Clinical-grade disposable systems dominate as infection control committees mandate single-use instruments. United States outpatient networks and Japanese dermatology departments drive specification tightening.
- Beauty Salons:Mixed procurement with autoclave-dependent manual guns in established locations and disposable adoption in new entrants. French and German operators face tightening state-level sterilization competency inspections.
- Specialty Shops:Niche retailers focusing on pediatric or allergy-sensitive segments. Nickel-free alloy specialization captures margin concentration in these channels.
Hospitals command the highest per-unit pricing tier, with beauty salons expanding most quickly as regulatory harmonization enables cross-border supplier qualification.
Material:
Biocompatibility certification costs stratify material selection, with ISO 10993 testing alignment enabling single-SKU regulatory coverage across high-value markets.
- Plastic:Precision-molded medical-grade polymers for disposable housings and manual gun bodies. Chinese OEM capacity in Zhejiang and Guangdong broadens supply for entry-level instruments.
- Stainless Steel:Surgical-grade 316L housings and components for reusable systems. Nickel market volatility compresses margins for metal-housing manufacturers.
- Titanium:Premium biocompatible metal for allergy-sensitive and pediatric applications. Japanese medical aesthetic clinics specify these for ancillary piercing revenue streams.
- Nickel-Free Alloys:Specialized compositions targeting dermal sensitivity regulations. EU dermal metal scrutiny intensifies demand for these formulations.
Plastic dominates unit volume through disposable gun adoption, with nickel-free alloys gaining share fastest on regulatory tailwinds.
Application:
Service delivery decentralization is fragmenting procurement authority across fixed retail, clinical, and temporary event formats.
- Cosmetic:Standard earlobe and cartilage piercing for aesthetic purposes. Jewelry stores and beauty salons in the United States and Germany anchor this segment.
- Medical:Clinically supervised procedures with documentation requirements. Japanese dermatology chains and United States outpatient surgery centers drive specification.
- Retail Sales:Product bundling with jewelry purchases. United States specialty retail chains integrate piercing as loss-leader customer acquisition.
- Events:Festival and pop-up retail channels adopting single-use guns to eliminate sterilization logistics. Mobile operators in temporary locations favor disposable platforms.
Cosmetic applications hold the largest installed base, with events expanding most quickly as service delivery decentralizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping manufacturing footprints as Chinese OEMs exploit cost-of-compliance gaps to capture entry-level instrument supply, while EU MDR sterilization mandates force European jewelry chains toward premium-tier sourcing.
United States
FDA Class I device exemptions currently limit clinical trial burdens, though reclassification risk looms. Hospital outpatient networks and specialty retail chains in Texas and Florida drive disposable gun adoption as group purchasing organizations consolidate procurement. California dermatology clinics increasingly specify titanium-alloy instruments for allergy-sensitive pediatric segments.
Germany
EU MDR instrument traceability requirements are compressing replacement cycles for jewelry retail chains. Baden-Württemberg precision manufacturers face margin pressure from sterilization documentation upgrades. Frankfurt and Munich-based medical aesthetic clinics anchor demand for clinical-grade disposable systems with ISO 10993-certified components.
China
NMPA biocompatibility testing on metal components restricts non-certified devices from domestic beauty salon chains. Zhejiang and Guangdong precision-molding clusters scale medical-grade plastic production for export markets. Shenzhen OEMs supply entry-level instruments to Southeast Asian and Middle Eastern distributors seeking cost-optimized alternatives.
Japan
METI and PMDA coordinate import inspection standards that restrict uncertified piercing devices from clinical channels. Tokyo and Osaka dermatology chains are expanding piercing services as ancillary revenue streams. Kanto region medical aesthetic clinics specify disposable cartridge systems to eliminate autoclave dependency.
France
ANSM enforcement of state-level sterilization competency inspections is forcing beauty salon operator retraining. Paris and Lyon jewelry retail chains accelerate equipment turnover to meet EU MDR compliance deadlines. Île-de-France specialty shops capture margin concentration through nickel-free alloy specialization for pediatric segments.
Ear Piercing Guns Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue disposable cartridge specialization and biocompatibility certification as differentiation vectors. The vendor base stratifies across captive manufacturing networks, proprietary locking mechanism specialists, and regional OEM fabricators. Three archetypes dominate: vertically integrated mass-market suppliers, medical-grade material specialists, and precision-molding contract manufacturers. Competitive moves center on sterilization documentation convergence across EU MDR and Japan PMDA requirements, plus cartridge system patent licensing to circumvent refill-prevention thickets.
Within the medical-grade specialization tier, Blomdahl Medical exemplifies nickel-free alloy positioning for allergy-sensitive segments, while Studex anchors mass-market supply through scale-driven manufacturing networks. Inverness Corporation occupies a position defined by proprietary cartridge architecture. These three entities represent distinct competitive vectors—material science premiumization, production scale defense, and intellectual property moat construction—rather than overlapping strategic postures.
| Leading Market Players |
|---|
| Studex |
| Inverness Corporation |
| Blomdahl Medical |
| Caflon |
| Piercing Pagoda |
| System75 |
| Claire's |
| Medisept |
| Lorinser Piercing Systems |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap precision manufacturers in Baden-Württemberg and Zhejiang anchor supply-side discipline, translating captive tooling investments into pricing power over jewelry retail chains while Chinese OEM roll-ups compress entry-level tiers through scale-driven molding capacity.
Pricing Analysis
Distributor margin layers separate captive-manufacturing specialists from third-party OEM aggregators, with Studex leveraging in-house production to command 15-20 point premiums over contract-manufactured alternatives. Three-tier pricing structure across premium nickel-free alloys, standard surgical-grade stainless, and economy-grade medical plastics reflects ISO 10993 certification burden dispersion. Cost compression in economy tiers intensifies because Zhejiang molding clusters flood export channels with unbranded alternatives. Hospital procurement committees exhibit lowest price sensitivity, prioritizing liability reduction over per-unit cost, while independent jewelry store owners in cost-sensitive U.S. markets resist disposable premiums.
Supply Chain Analysis
Single-source vulnerability sits with Zhejiang precision-molding clusters for medical-grade polymer housings and German specialty steel mills for surgical-grade 316L feedstock. Manufacturing concentrates in China, Germany, and Japan, with each node feeding distinct certification tiers. Raw material dependencies center on nickel-priced stainless alloys, medical-grade ABS polymers, and titanium sponge for biocompatible variants. Tariff exposure on Chinese-molded components threatens margin stability for U.S.-bound distributors. Distribution runs through medical device wholesalers serving hospital GPOs, beauty salon supply cooperatives in France and Germany, and direct OEM relationships with retail jewelry chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR instrument traceability mandates compound replacement demand across European jewelry retail chains, transforming compliance burden into recurring revenue streams for certified suppliers.
For Market Incumbents: Deploy cartridge system patent licensing to monetize refill-prevention intellectual property against low-cost aftermarket competitors. Consolidate sterilization documentation capabilities to capture German and French jewelry chain turnover forced by EU MDR deadlines. Vertical integration into Zhejiang molding capacity defends margin position against Chinese OEM price aggression in entry-level tiers. For New Entrants and Emerging Players: FDA Class I reclassification risk in the United States opens a window for clinical-grade disposable specialists to preempt channel access restrictions through early 510(k) pathway investment. Target Tokyo and Osaka medical aesthetic clinics as the most penetrable geography, where dermatology chains seek ancillary piercing revenue without autoclave infrastructure. Lead with biocompatibility certification convergence across ISO 10993, EU MDR, and Japan PMDA requirements to enable single-SKU regulatory coverage. For Investors and Strategic Acquirers: Valuations sit cheapest among precision-molding contract manufacturers lacking captive brand distribution. Five-to-ten year viability hinges on regulatory harmonization accelerating consolidation toward quality-system-certified suppliers. Watch FDA device classification proceedings as the critical inflection signal; reclassification from cosmetic tool to regulated medical device status would abruptly devalue non-compliant inventory across U.S. distributor networks.| Strategic Initiative | Industry Significance |
|---|---|
| Biocompatibility Certification Convergence | ISO 10993 alignment with EU MDR and Japan PMDA enables single-SKU regulatory coverage across high-value markets. |
| Disposable Cartridge System Development | Pre-sterilized single-use platforms eliminate autoclave dependency for hospital outpatient networks and mobile event operators. |
| Patent Licensing for Locking Mechanisms | Proprietary refill-prevention systems create recurring royalty streams from aftermarket component manufacturers. |
| Precision Molding Capacity Expansion | Zhejiang and Guangdong medical-grade polymer production scales supply for entry-level instrument export markets. |
| Nickel-Free Alloy Specialization | Pediatric and allergy-sensitive segments command margin premiums as EU dermal metal scrutiny intensifies. |
Research Methodology
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with hospital infection control officers, jewelry store procurement managers, beauty salon sterilization technicians, and medical aesthetic clinic operators informed demand segmentation. Secondary validation drew from FDA device classification databases, EU MDR technical documentation filings, Japan PMDA import inspection records, and Chinese NMPA biocompatibility test registries. Cross-referencing bottom-up channel estimates against top-down production data from Zhejiang and Guangdong molding clusters ensured figure integrity.
Historical trendline analysis of replacement cycles across jewelry retail chains and hospital procurement patterns established baseline growth assumptions. Segmentation dimensions modeled include product type, end-user category, material specification, and application format across the projection horizon. CAGRs derived from fitted growth curves adjusted for regulatory milestone impacts and channel penetration saturation points. Industry-specific forecast inputs incorporated EU MDR compliance deadline clustering and FDA reclassification risk probability assessments.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA Class I reclassification scenarios or acute nickel price volatility affecting surgical-grade 316L input costs. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Grooming Products
Cotton Buds Market
Personal Grooming Products
Handheld Massager Market
Personal Grooming Products
Heated Razor Starter Kit Market
Personal Grooming Products
Sneaker Deodorant Market
Personal Grooming Products
Shaving Pen Market
Personal Grooming Products
Electric Massagers Market
Personal Grooming Products
Foot Care Products Market
Personal Grooming Products
Razor Blade Market
Personal Grooming Products
Massage Fascia Gun Market
Personal Grooming Products
North America Hair Styling Tools Market
Personal Grooming Products
Bamboo Toothbrush Market
Personal Grooming Products
Feminine Hygiene Products Market
Personal Grooming Products
China Beard Trimmer Market
Personal Grooming Products
Baby Oil Market
Personal Grooming Products
Mexico Beard Trimmer Market
Personal Grooming Products
Hand Massager Market