
 Floss Picks Market | 2026-2036
Floss Picks Market Size, Share, and Industry Trends Forecast 2026-2036
Floss Picks Market Intelligence
Household buyers is bifurcating from occasional users toward daily ritual adopters who integrate floss picks into structured oral care routines. Procter & Gamble leverages its retail shelf dominance to anchor premium positioning in mass-market channels. Colgate-Palmolive competes through dental professional endorsement programs that sustain clinician loyalty. The Humble Co. differentiates via biodegradable material specialization that occupies the sustainability-forward segment.
Floss picks are handheld dental hygiene devices combining a short tensioned filament with a rigid handle, typically manufactured through injection molding of polypropylene or polylactic acid with nylon threading, designed to remove interdental plaque where brushing fails. Disposable variants dominate volume while biodegradable materials represent the fastest-growing margin pool as regulatory pressure intensifies. Flavored picks lead household impulse purchases whereas unflavored formats sustain dental clinic procurement contracts where clinical neutrality governs selection.
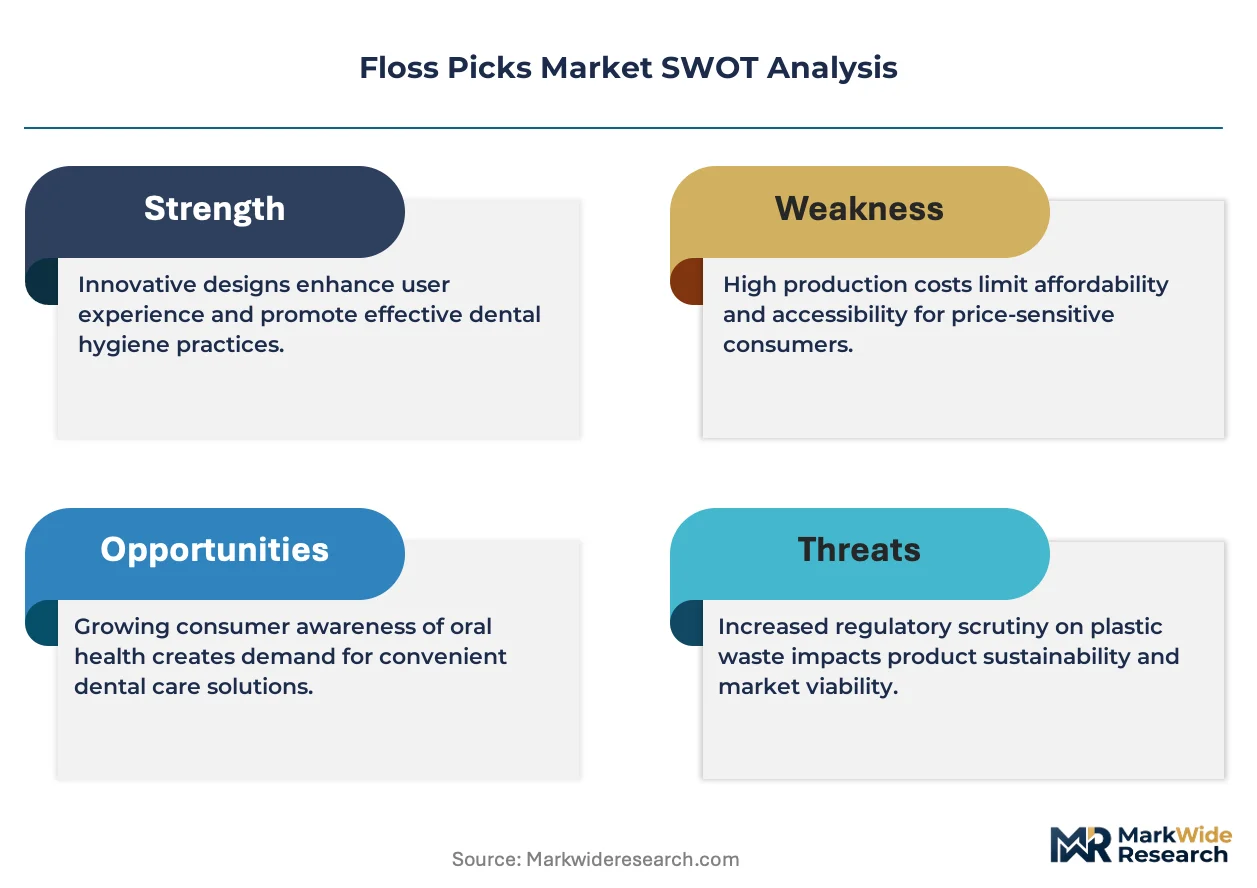
The EPA regulates plastic manufacturing emissions from floss pick production facilities while the FDA oversees oral care device classification and safety labeling requirements for products sold in the United States. REACH compliance in Europe restricts certain polymer additives, forcing reformulation of conventional plastic handles for export markets. Stakeholders must monitor evolving extended producer responsibility frameworks that will determine which material technologies achieve scalable market access.
Market Dynamics
The EU Single-Use Plastics Directive is forcing material transitions across the floss picks supply chain, compressing conventional polypropylene demand while accelerating polylactic acid and bamboo fiber adoption among contract manufacturers serving European retail channels.
Growth Catalysts
- REACH polymer reformulation mandates:European chemical safety rules are pushing manufacturers toward certified biodegradable handles, creating compliant supply pools for export-bound producers.
- Dental clinic bulk procurement:Clinical settings in Germany and France are consolidating single-use pick purchasing through group purchasing organizations, anchoring volume commitments for sterilized unflavored formats.
- Polylactic acid compounding advances:Improved injection molding temperatures for plant-based resins are reducing production defect rates, narrowing the unit cost gap with fossil-derived alternatives.
Market Restraints
- Nylon filament supply concentration:Specialty polymer thread production clusters in Zhejiang Province, exposing brands to freight cost volatility and customs processing delays.
- Biodegradable certification timelines:TÜV Austria and BPI compostability validation requires 12-18 month testing cycles, freezing product launch schedules for reformulated handles.
- Interdental brush substitution:Reusable silicone picks and water flosser attachments are capturing daily ritual adopters seeking durable alternatives to disposable formats.
Strategic Opportunities
- Subscription direct-to-consumer channels:Recurring delivery models bypass retail slotting fees and capture household buyer lifetime value through flavor rotation programs.
- Extended producer responsibility frameworks:France's Citeo packaging compliance scheme rewards biodegradable material adoption with reduced eco-modulation fees, tilting procurement decisions.
- Smart packaging integration:Near-field communication tags on premium pick dispensers enable usage tracking apps, converging oral care hardware with digital hygiene coaching platforms.
Industry Challenges
- Biopolymer processing expertise gaps:Injection mold technicians trained on polypropylene require re-certification for polylactic acid temperature sensitivity, constraining production line conversions.
- Multi-jurisdiction labeling compliance:Simultaneous FDA device classification, EPA manufacturing emission disclosures, and EU plastic content declarations fragment packaging design workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Floss Picks Market |
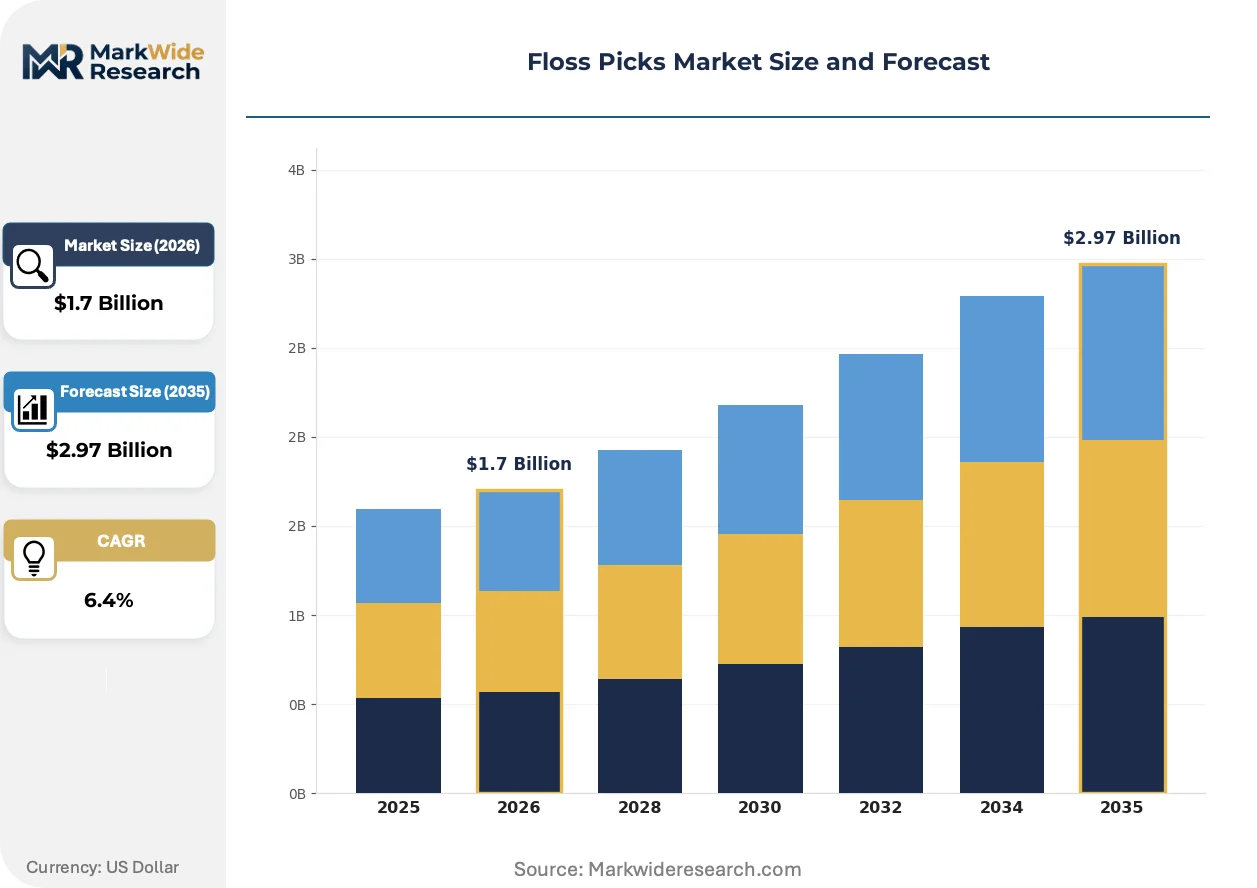
| Market Size in 2026 | $1.7 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable, Reusable, Flavored, Unflavored Material: Plastic, Biodegradable, Nylon, Wood End User: Dental Clinics, Households, Schools, Travel Packaging Type: Box, Bag, Dispenser, Bulk |
| Companies Covered | Sunstar, Ranir, Procter & Gamble, The Humble Co., Church & Dwight, Colgate-Palmolive, Prestige Consumer Healthcare, Dr. Wild & Co. AG, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Floss Picks Market Strategic Shifts & Innovations
Material science advances and regulatory compliance automation are restructuring competitive advantage in floss pick manufacturing, shifting value capture from brand marketing toward supply chain certification and sustainable material sourcing capabilities.
Polylactic acid resin formulations are decomposing the cost-performance tradeoff that historically favored petroleum-based handles. German dental clinic procurement teams are specifying certified compostable picks in tender documents, compressing the addressable market for conventional polypropylene variants and forcing molders to retool or exit European contracts.
REACH restrictions on phthalate plasticizers are compelling handle reformulation for any product touching EU consumers. Manufacturers serving multiple geographies now maintain parallel resin inventories, with the regulatory friction highest for mid-size brands lacking dedicated compliance teams to manage substance of very high concern screening protocols.
Household buyers are consolidating oral care purchasing through pharmacy subscription programs, displacing impulse-driven supermarket aisle selection. This pattern concentrates volume with private-label house brands and certified sustainable specialists, compressing shelf space for undifferentiated national brands in United States drugstore channels and German apotheek networks.
Floss Picks Market Segmentation
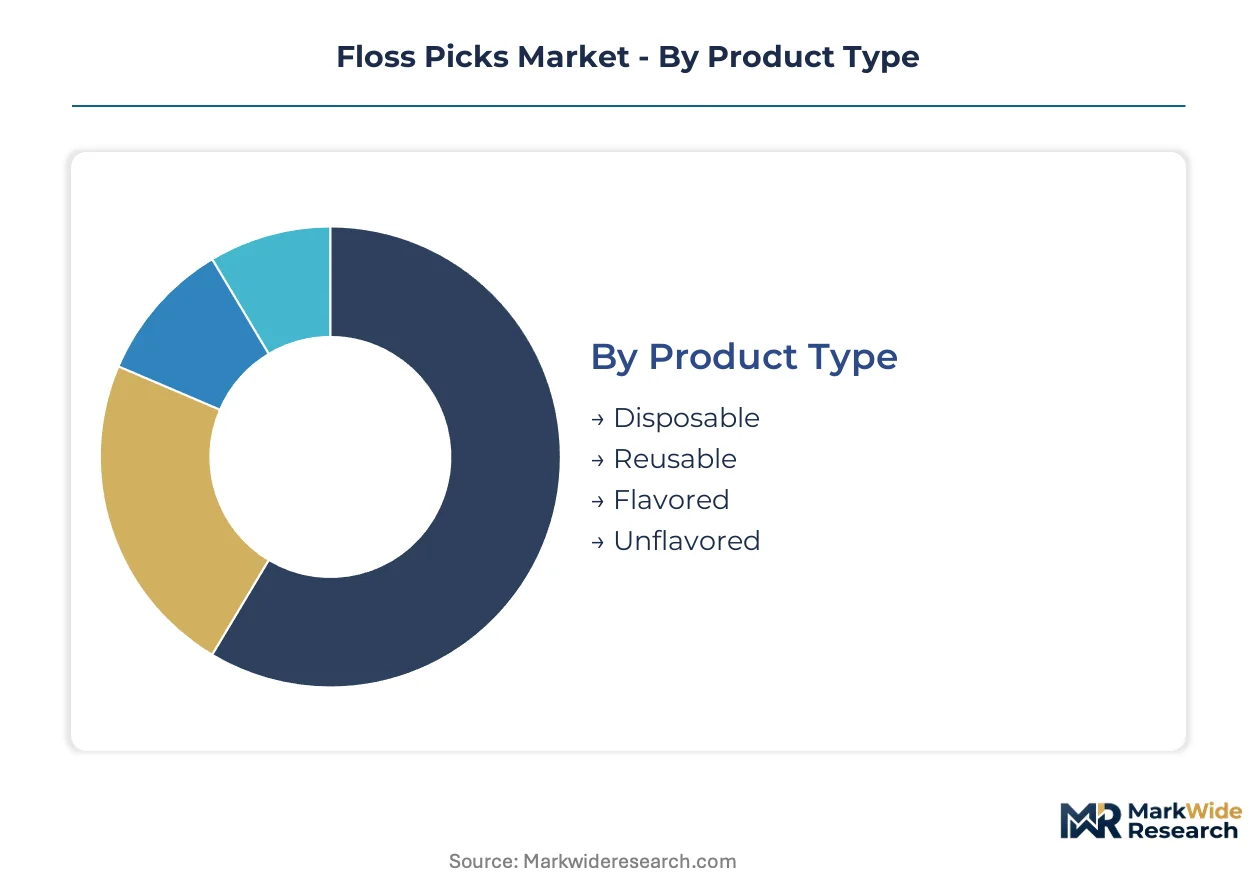
Segmentation in the floss picks market reveals divergent supply chain configurations, with material composition and end-use channel determining whether production serves domestic pharmacy networks or export-bound retail contracts. Understanding these divides exposes where margin pools concentrate and where regulatory compliance costs reshape competitive viability.
Product Type:
Disposable formats dominate household impulse purchasing across United States drugstore channels, while reusable variants concentrate in German sustainability-forward retail. Flavored picks anchor subscription direct-to-consumer growth; unflavored formats sustain clinical procurement in France and Belgium.
- Disposable:Single-use polypropylene or polylactic acid handles with nylon threading dominate volume through mass-market retail. Demand clusters in United States private-label household buyers where pharmacy subscription programs displace supermarket aisle selection.
- Reusable:Silicone or stainless steel frames with replaceable filament cartridges target daily ritual adopters seeking durable alternatives. German dental clinic procurement teams increasingly specify these for patient take-home kits, compressing disposable format growth in clinical channels.
- Flavored:Mint, cinnamon, or fruit-infused handles drive impulse purchases in United States travel retail and pharmacy endcaps.
- Unflavored:Clinical neutrality governs selection for sterilized formats in French and Belgian group purchasing organization contracts.
Disposable holds the largest share; momentum sits with flavored variants in subscription channels.
Material:
Cost tiers separate fossil-derived from plant-based alternatives, with certification premiums determining access to European retail. Nylon filament supply concentration in Zhejiang Province shapes input cost volatility across all handle substrates.
- Plastic:Conventional polypropylene handles face compressed demand as EU Single-Use Plastics Directive accelerates transitions. Mid-size brands lacking dedicated compliance teams struggle with parallel resin inventories for multi-jurisdiction shipments.
- Biodegradable:Polylactic acid and bamboo fiber formulations represent the expanding margin pool as TÜV Austria and BPI certification unlocks French Citeo eco-modulation fee reductions. German dental clinic tender documents now specify certified compostable picks exclusively.
- Nylon:Specialty polymer threading production clusters expose brands to freight cost volatility and customs processing delays from Zhejiang Province.
- Wood:Birch or bamboo handles serve sustainability-forward segments in Scandinavian pharmacy networks and German apotheek channels.
Plastic retains volume dominance; biodegradable materials are climbing the fastest as REACH polymer reformulation mandates tighten.
End User:
Application patterns split between clinical sterilization requirements and household convenience preferences, with procurement concentration determining pricing power. School and travel segments operate as volume overflow channels for production capacity not absorbed by core dental and household demand.
- Dental Clinics:Sterilized unflavored formats purchased through German and French group purchasing organizations anchor volume commitments. Clinical neutrality requirements and bulk procurement consolidation favor suppliers with validated cleanroom production capabilities.
- Households:Private-label buyers in United States pharmacy subscription programs concentrate oral care purchasing, displacing national brand shelf space. Daily ritual adopters integrate picks into structured routines, sustaining recurring revenue models.
- Schools:Bulk bag formats for hygiene education programs in United States public health initiatives.
- Travel:Single-dispenser and pocket-size packaging for airport retail and hospitality amenity channels.
Households generate the highest absolute volume; dental clinics command the steepest expansion trajectory through European tender specifications.
Packaging Type:
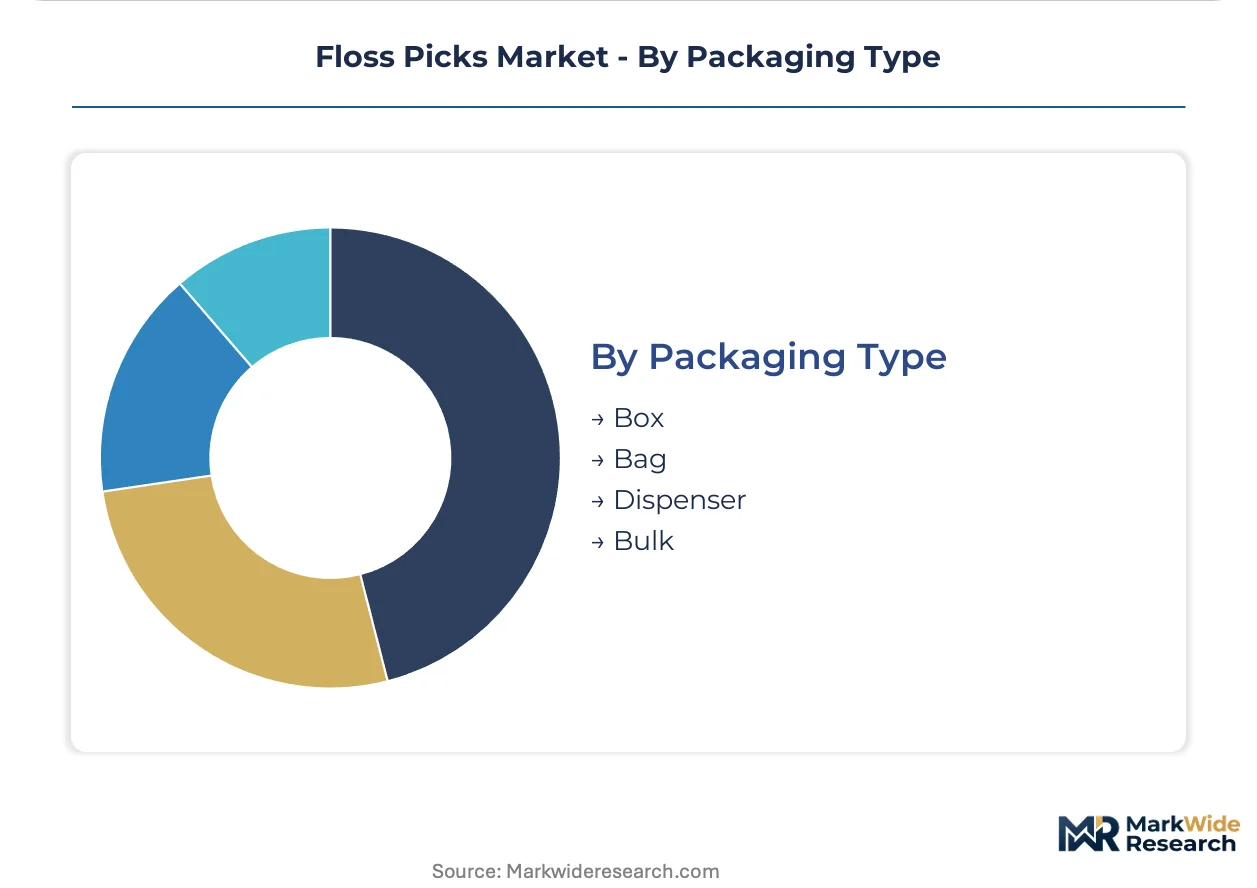
Packaging configuration signals channel positioning, with dispenser and bulk formats separating premium subscription plays from commodity clinical supply. Smart packaging integration with near-field communication tags concentrates in dispenser formats for United States premium household segments.
- Box:Standard retail packaging for pharmacy and supermarket channels, typically 50-90 count units. United States drugstore private-label dominance compresses branded box format margins.
- Bag:Value-oriented flexible packaging for mass-market discount retail and school procurement programs. Lowest per-unit packaging cost supports price-competitive positioning.
- Dispenser:Countertop or wall-mounted units with 100-200 count capacity target daily ritual adopters. Near-field communication tag integration enables usage tracking apps in United States premium subscription models.
- Bulk:Unbranded 500-1000 count formats for dental clinic group purchasing organizations and French Citeo-compliant institutional buyers.
Box formats hold the largest share; dispenser configurations gain share fastest through smart packaging convergence with digital hygiene platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's container throughput underwrites Europe's role as the primary conduit for biodegradable resin imports serving floss pick molders. Distribution networks radiate from this hub to contract manufacturers across the continent.
United States
Pharmacy subscription programs concentrate household demand through CVS and Walgreens private-label channels. FDA device classification rules govern oral care safety labeling for all products crossing state lines. Injection molding clusters in Ohio and Indiana supply mass-market retailers with polypropylene handles.
Germany
Dental clinic group purchasing organizations in Bavaria and North Rhine-Westphalia consolidate sterilized unflavored pick procurement. REACH polymer reformulation mandates from ECHA force handle reformulation for EU market access. Stuttgart-area molders specialize in polylactic acid compounding for biodegradable variants.
France
Citeo packaging compliance schemes reward certified compostable materials with reduced eco-modulation fees. ANSM oversees medical device classifications for clinical-grade picks. Lyon-based contract manufacturers serve French and Belgian dental tender specifications.
China
Nylon filament production concentrates in Zhejiang Province, exposing brands to freight cost volatility and customs delays. MIIT industrial standards govern plastics manufacturing emissions. Shenzhen molders supply export-bound biodegradable handles for European retail channels.
Japan
PMDA regulates oral care device safety for domestic and export markets. METI sustainability guidelines accelerate plant-based material adoption among Osaka-based consumer goods manufacturers. Tokyo pharmacy chains consolidate purchasing through centralized procurement platforms.
Floss Picks Market Key Industry Players
Concentration sits with diversified consumer health conglomerates anchoring mass-market shelf space. The vendor base spans three tiers: multinational oral care giants with retail dominance, mid-size sustainability specialists capturing pharmacy subscription channels, and regional contract manufacturers serving private-label programs. Strategic moves center on material certification acquisition and direct-to-consumer channel bypass of traditional retail slotting fees.
Among diversified consumer health conglomerates, Procter & Gamble and Colgate-Palmolive exemplify scale-driven archetypes occupying mass-market positions. The Humble Co. represents the sustainability-specialist tier focused on biodegradable material differentiation. Sunstar and Dr. Wild & Co. AG sit within European-focused regional fabricators serving dental professional channels. These anchors illustrate how competitive positioning fragments across retail dominance, material certification, and clinical endorsement vectors.
| Leading Market Players |
|---|
| Sunstar |
| Ranir |
| Procter & Gamble |
| The Humble Co. |
| Church & Dwight |
| Colgate-Palmolive |
| Prestige Consumer Healthcare |
| Dr. Wild & Co. AG |
| Johnson & Johnson |
| Others |
Cost & Logistics Intelligence
Long-term offtake contracts with Zhejiang Province nylon filament producers lock in supply access and price visibility for brands serving European retail channels, insulating procurement teams from freight cost volatility while compressing margin flexibility for spot-market buyers.
Pricing Analysis
Volume-discount tiering structures separate dental clinic group purchasing organizations from household pharmacy subscription buyers, with the former extracting steepest unit reductions through consolidated tender specifications. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with TÜV Austria compostable picks commanding 40-60% premiums over conventional polypropylene. Pricing pressure stems from REACH polymer reformulation mandates forcing parallel resin inventory maintenance. Dental clinics exhibit lowest price sensitivity due to sterilization requirements; mass-market discount retail channels show highest elasticity.
Supply Chain Analysis
China and Germany anchor floss pick manufacturing, with Zhejiang Province housing specialty nylon threading production and Stuttgart-area molders specializing in polylactic acid compounding for biodegradable handles. Raw material dependencies center on petroleum-derived polypropylene, plant-based polylactic acid resin, and specialty nylon polymer. Single-source vulnerability concentrates in Zhejiang filament production, exposing brands to customs processing delays. Distribution runs through pharmacy subscription platforms and dental clinic group purchasing organizations, bypassing traditional retail slotting fees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Floss pick demand is recovering from pandemic-era channel disruptions as pharmacy subscription programs renormalize household purchasing patterns and European regulatory deadlines accelerate material transition investments.
For Market Incumbents: Shield market position by acquiring TÜV Austria and BPI certifications ahead of French Citeo eco-modulation fee adjustments, and deepen backward integration into polylactic acid compounding to capture margin from biodegradable material premiums. Water flosser substitution and silicone reusable picks threaten disposable format volume; certification investment and upstream resin control provide defensive moats. For New Entrants and Emerging Players: Differentiate on biodegradable material specialization targeting German dental clinic tender specifications, where certified compostable requirements are displacing conventional polypropylene suppliers. White-space sits with subscription direct-to-consumer channels offering flavor rotation programs to United States daily ritual adopters. Penetrate through pharmacy private-label partnerships bypassing retail slotting fee barriers. For Investors and Strategic Acquirers: European-focused contract manufacturers with validated cleanroom production capabilities represent the most attractive acquisition archetype, capturing dental clinic procurement consolidation and REACH compliance expertise. Long-term viability hinges on material certification portfolios rather than brand equity. Monitor French Citeo fee schedule revisions as inflection indicator for biodegradable material adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Material Certification | TÜV Austria validation unlocks French Citeo eco-modulation fee reductions and German dental tender access. |
| Direct-to-Consumer Subscription Launch | Recurring delivery models bypass CVS and Walgreens slotting fees while capturing household lifetime value. |
| Backward Integration into Resin Compounding | In-house polylactic acid production narrows cost gap with petroleum-based handles amid REACH mandates. |
| Smart Packaging Integration | Near-field communication tags on dispensers enable usage tracking apps converging with digital hygiene platforms. |
| Dental Clinic GPO Partnership | Group purchasing organization contracts in Bavaria anchor sterilized unflavored format volume commitments. |
Research Approach
The analysis maps biodegradable material transitions, disposable versus reusable format splits, and pharmacy subscription channel growth, each validated through procurement managers at dental clinic group purchasing organizations, sustainability officers at consumer health conglomerates, injection molding technicians, and pharmacy category buyers. Primary interview insights triangulate against FDA device classification filings, ECHA REACH substance registrations, French Citeo packaging compliance databases, and United States customs import records. Bottom-up volume builds from contract manufacturer capacity assessments cross-check against top-down retail audit data.
Consistency checks validate volume and value outputs against external benchmarks across the analysis window. The forecast framework models material composition, end-use channel, packaging configuration, and geographic regulatory cluster as core segmentation dimensions. CAGRs derive from unit shipment trajectories weighted by certification premium capture rates and substitution elasticity between disposable and reusable formats. Polylactic acid resin price curves and nylon filament freight cost indices feed scenario-specific projections.
The analysis sits within stated boundaries; outcomes outside sustained EU Single-Use Plastics Directive enforcement or abrupt nylon supply disruptions would require recalibration. Forecasts reflect assumptions regarding certification timeline completion rates and pharmacy subscription program retention curves. Recalibration cycles align with material shifts in REACH polymer reformulation mandates and extended producer responsibility framework implementations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Grooming Products
Global Sex Toys Market
Personal Grooming Products
Smart Water Bottle Market
Personal Grooming Products
Hair Scissors Market
Personal Grooming Products
Shoe Deodorizer Market
Personal Grooming Products
US Percussion Massage Gun Market
Personal Grooming Products
Toothbrush Market
Personal Grooming Products
Global Tampons Market
Personal Grooming Products
Lice Combs Market
Personal Grooming Products
Heated Razor Starter Kit Market
Personal Grooming Products
Razor Blade Market
Personal Grooming Products
Global Posture Corrector Market
Personal Grooming Products
Personal Lubricants Market
Personal Grooming Products
Portable Massage Devices Market
Personal Grooming Products
Antibacterial Soap Market
Personal Grooming Products
Europe Hair Styling Tools Market
Personal Grooming Products
Hand Massager Market