
 Latin America Hand Soap Market | 2026-2036
Latin America Hand Soap Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Hand Soap Market Foresight
The divergence between premium and commodity tiers is realigning shelf positioning across Latin American retail channels. Procter & Gamble leverages its distribution depth to anchor premium liquid soap placements in Brazilian supermarkets. Colgate-Palmolive differentiates through antibacterial positioning in Mexican pharmacies. Kimberly-Clark sustains institutional contracts across Colombian healthcare facilities with bulk-container formats.
Latin America hand soap comprises surfactant-based cleansing formulations, typically combining sodium lauryl sulfate or cocamidopropyl betaine with emollients and antimicrobial agents, manufactured through continuous saponification or cold-process batching for skin-compatible hygiene applications. Liquid soap leads volume across households and commercial establishments, while foam soap captures faster growth in healthcare facilities where dispenser compatibility reduces water consumption and waste volume. Antibacterial soap commands premium positioning in educational institutions and clinics, though regulatory scrutiny on triclosan and alternative biocides is reshaping active ingredient portfolios.
Brazil's ANVISA and Mexico's Ministry of Economy enforce hygiene product registration and labeling standards that dictate permissible antimicrobial claims and packaging safety requirements. Colombia's INVIMA and Argentina's ANMAT maintain parallel cosmetic-drug classification frameworks that influence market access timelines and reformulation costs. Stakeholders must monitor evolving biocide restrictions across Mercosur and Pacific Alliance harmonization talks, as regulatory misalignment threatens cross-border product standardization strategies.
Market Dynamics
Healthcare procurement mandates across Brazil, Mexico, and Colombia are compressing purchasing cycles for antibacterial formulations as hospital-acquired infection protocols tighten and institutional buyers consolidate vendor lists around compliant suppliers.
Growth Catalysts
- ANVISA Sanitation Mandates:Brazil's regulatory tightening on hospital hygiene standards is forcing facility-wide soap upgrades, creating captive demand for alcohol-free antibacterial variants in São Paulo's healthcare corridor.
- Foam Dispenser Technology:Water-reduction compatibility in healthcare settings is accelerating foam soap penetration across Colombian clinics and Mexican emergency care networks.
- Southeast Brazil Commercial Density:São Paulo's concentrated corporate and retail footprint sustains bulk institutional contracts for liquid soap formats with integrated dispenser systems.
Market Restraints
- Palm Kernel Oil Volatility:Surfactant feedstock price swings tied to Southeast Asian supply disruptions compress margin buffers for Brazilian formulators dependent on imported oleochemicals.
- Biocide Registration Friction:Colombia's INVIMA and Argentina's ANMAT maintain divergent cosmetic-drug classification frameworks that extend product launch timelines by 8-14 months for cross-border standardization.
- Alcohol-Based Sanitizer Substitution:Gel hand sanitizer availability in Mexican retail channels captures hygiene occasions that soap formulations previously dominated in transit and workplace settings.
Strategic Opportunities
- Peru and Chile Underpenetration:Pacific Alliance harmonization talks could unlock streamlined market access for Brazilian and Mexican manufacturers with established biocide compliance documentation.
- Educational Institution Mandates:Mexican state-level school hygiene programs are creating specification demand for child-safe antibacterial formats with documented triclosan-free formulations.
- E-Commerce Direct-to-Institution:Healthcare procurement platforms in Colombia are bypassing traditional distributor markups, enabling margin capture for manufacturers with logistics integration.
Industry Challenges
- Formulation Chemist Scarcity:Brazil's specialized workforce for surfactant-antimicrobial compatibility testing is concentrated in São Paulo and Rio de Janeiro, creating recruitment bottlenecks for regional production expansion.
- Mercosur Harmonization Delays:Divergent biocide restriction timelines between Brazil and Argentina force parallel formulation tracks that inflate R&D overhead and inventory complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Hand Soap Market |
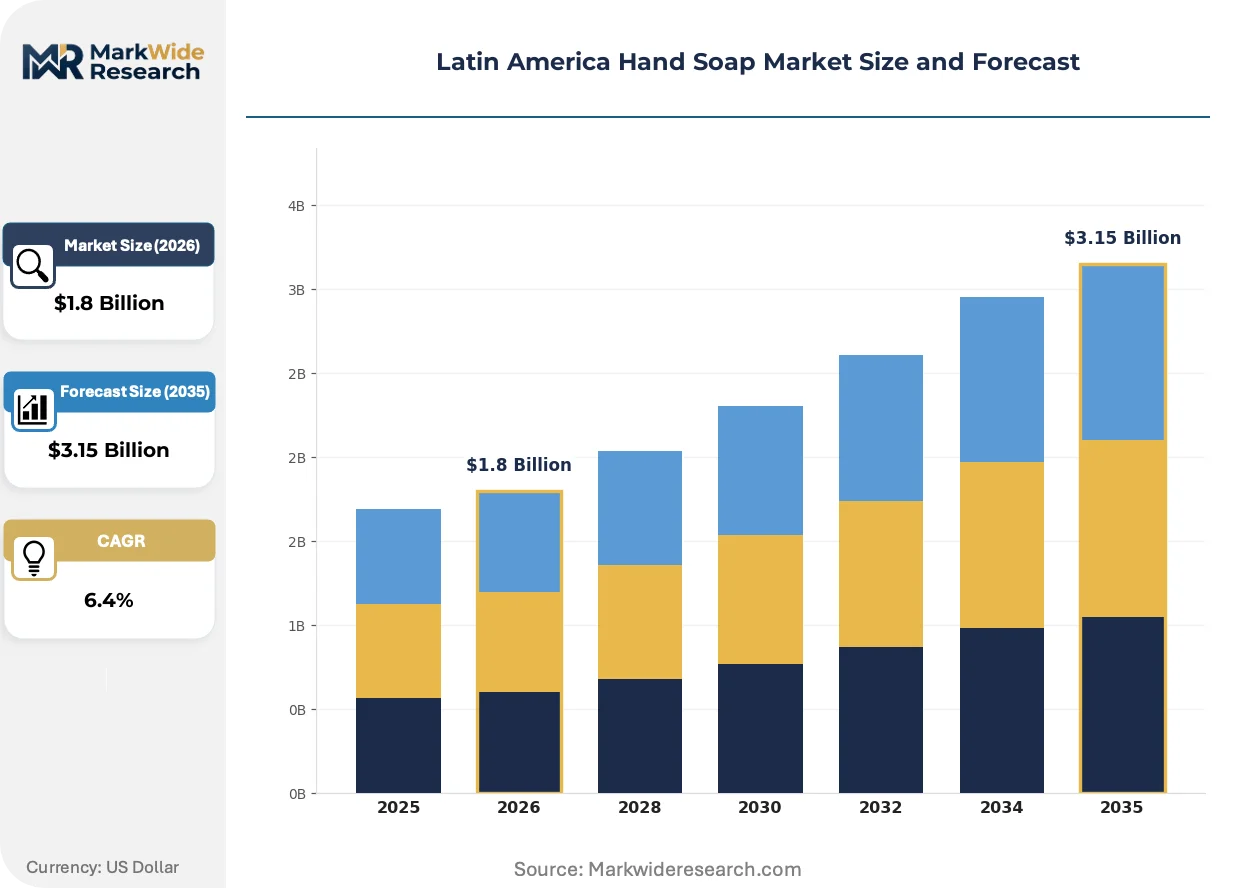
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Soap, Foam Soap, Gel Soap, Antibacterial Soap End User: Households, Commercial Establishments, Healthcare Facilities, Educational Institutions Packaging Type: Plastic Bottles, Pump Dispensers, Refill Pouches, Bulk Containers Distribution Channel: Supermarkets, Online Retailers, Pharmacies, Specialty Stores |
| Companies Covered | Kimberly-Clark, Henkel AG & Co. KGaA, Colgate-Palmolive Company, Procter & Gamble, GOJO Industries, 3M, Mex-Ar Productos, Daryza, Prolimp del Centro, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Hand Soap Market Shifts & Advancements
Active ingredient portfolios are pivoting away from legacy antimicrobials toward plant-derived alternatives as regulatory scrutiny intensifies across Latin American health ministries and institutional procurement specifications harden.
Quaternary ammonium compounds are expanding into premium healthcare and foodservice applications as triclosan phase-outs accelerate under ANVISA and NOM-005 guidance. São Paulo's private hospital networks are specifying benzalkonium chloride formulations for surgical scrub compatibility. This chemistry shift is expanding into institutional contracts previously captured by alcohol-heavy alternatives, compressing the addressable market for traditional antibacterial actives.
REACH-aligned biocide restrictions are filtering into Mercosur technical discussions, with Brazil's ANVISA referencing EU hazard classifications in draft updates to cosmetic preservative limits. Mexican manufacturers reformulating for NOM-005 compliance are pre-emptively excluding CMR-category candidates to maintain export eligibility. The regulatory convergence is most visible in antibacterial soap segments, where active ingredient disclosure requirements now exceed baseline cosmetic labeling standards.
Healthcare procurement centralization is consolidating vendor relationships around full-service hygiene suppliers capable of dispenser provisioning, technical training, and consumption monitoring. Colombian hospital networks are shifting from product-only tenders to multi-year facility hygiene partnerships. The transformation is most advanced in Bogotá's tertiary care cluster, where integrated service contracts now specify soap chemistry, dispenser hardware, and refill logistics as bundled procurement units.
Latin America Hand Soap Market Segmentation
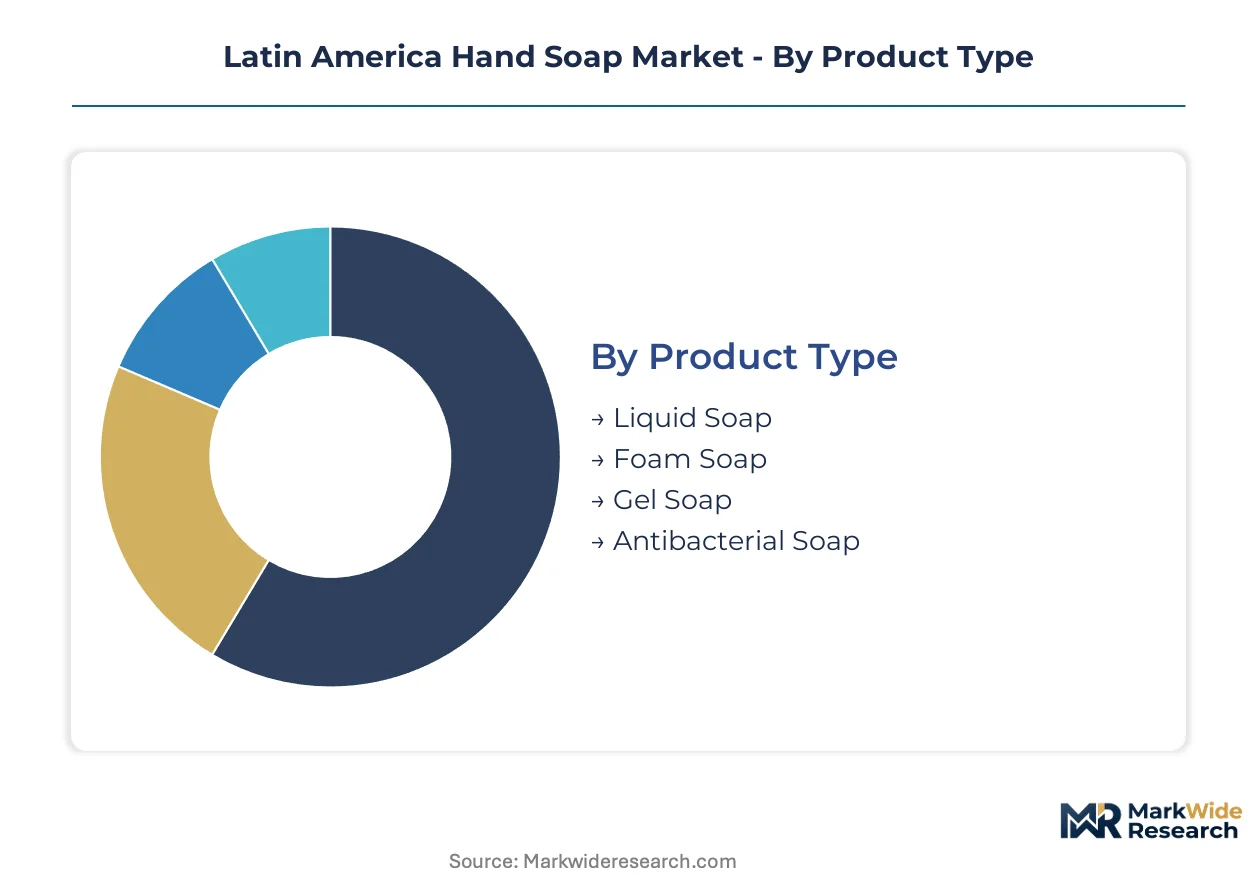
Hand soap segmentation in Latin America reflects divergent regulatory burdens across product chemistry and end-use contexts. ANVISA and NOM-005 requirements reshape formulation strategies differently for healthcare versus household applications, while dispenser compatibility drives packaging selection in institutional procurement.
Product Type:
ANVISA's cosmetic-drug boundary determines which formulations carry antimicrobial registration requirements versus standard cosmetic notification. Benzalkonium chloride and quaternary ammonium variants trigger extended approval timelines compared to basic surfactant cleansers.
- Liquid Soap:Sodium lauryl sulfate or cocamidopropyl betaine formulations dominate household and commercial applications. São Paulo's corporate corridor sustains bulk institutional contracts with integrated dispenser systems for this format.
- Antibacterial Soap:Triclosan-free biocide formulations command premium positioning in Brazilian healthcare facilities and Mexican educational institutions. Active ingredient disclosure requirements now exceed baseline cosmetic labeling standards under evolving ANVISA guidance.
- Foam Soap:Pre-lathered surfactant systems reduce water consumption in Colombian clinics and Mexican emergency care networks.
- Gel Soap:Viscous formulations occupy niche positioning in specialty retail channels with premium skin-conditioning additives.
Leading the category by volume: Liquid Soap. Expanding most quickly: Antibacterial Soap.
End User:
Cost stratification separates commodity household consumption from specification-driven institutional procurement where compliance documentation carries premium pricing power.
- Healthcare Facilities:Brazilian hospitals and Colombian clinics mandate alcohol-free antibacterial formulations with documented surgical scrub compatibility. Centralized procurement in Bogotá's tertiary care cluster now bundles soap chemistry with dispenser hardware and refill logistics.
- Households:São Paulo and Rio de Janeiro residential corridors drive volume for standard liquid formats through supermarket and online channels. Price sensitivity concentrates demand in mid-tier surfactant formulations without antimicrobial actives.
- Commercial Establishments:Corporate offices and foodservice operators across Mexico specify foam soap compatibility for water-reduction targets.
- Educational Institutions:Mexican state-level school hygiene programs generate specification demand for child-safe antibacterial formats with verified triclosan-free chemistry.
Highest margin concentration: Healthcare Facilities. Steepest volume expansion: Educational Institutions.
Packaging Type:
Dispenser technology integration determines packaging selection, with refill economics favoring pouch systems in high-throughput institutional settings versus bottle convenience in household retail.
- Pump Dispensers:Integrated hardware-soap systems lock in multi-year contracts across Colombian hospital networks. Bogotá procurement platforms specify dispenser provisioning alongside chemistry as bundled tender requirements.
- Refill Pouches:Flexible packaging reduces per-unit shipping costs for Brazilian institutional buyers with captive dispenser infrastructure. São Paulo healthcare clusters favor this format for consumption monitoring compatibility.
- Plastic Bottles:Standard retail format dominates Mexican and Brazilian household channels through supermarket placement.
- Bulk Containers:Industrial-scale formats serve foodservice and manufacturing facility hygiene stations with minimal packaging overhead.
Fastest institutional adoption: Pump Dispensers. Strongest household presence: Plastic Bottles.
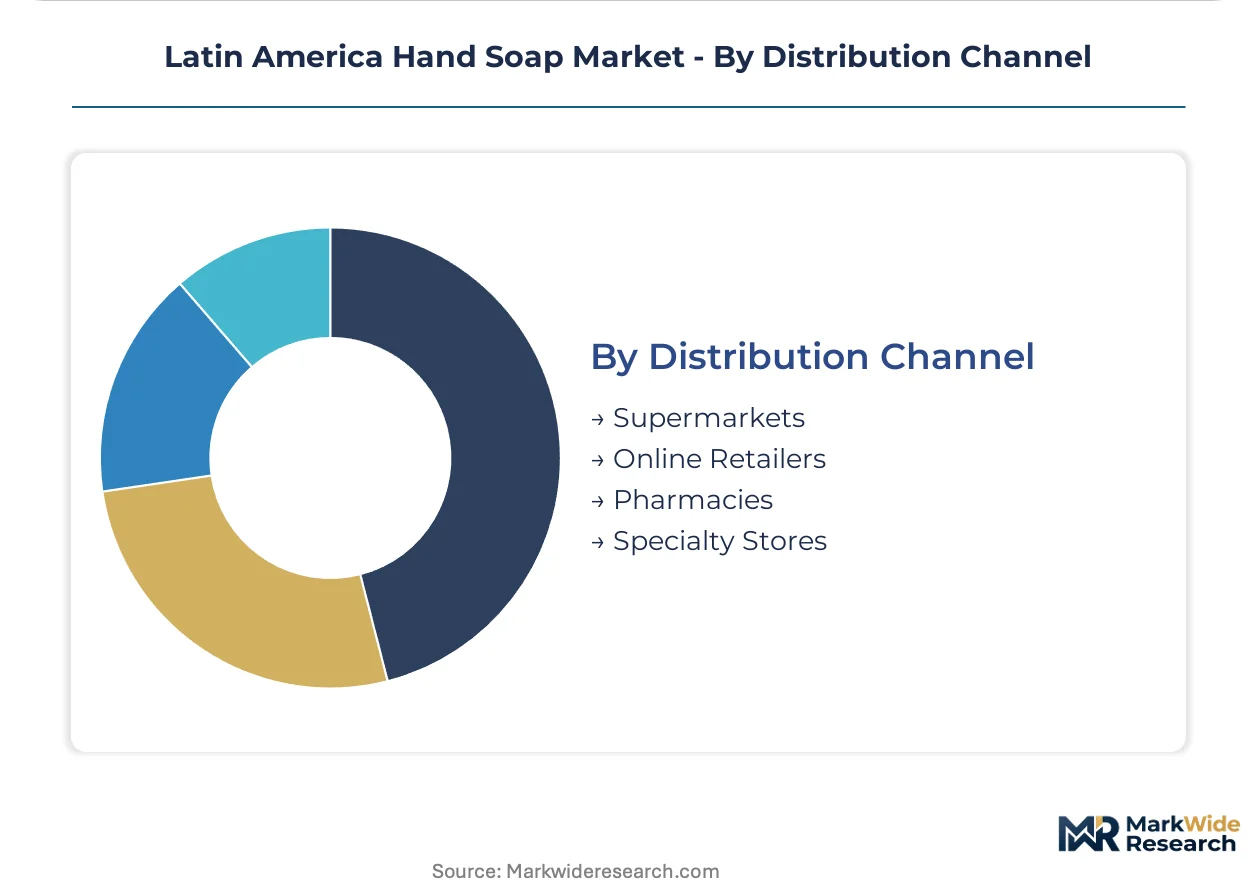
Distribution Channel:
Channel selection reflects end-user procurement centralization trends, with healthcare platforms bypassing traditional distributor markups while pharmacies retain antibacterial specification authority.
- Supermarkets:Brazilian retail chains anchor liquid soap volume through São Paulo's dense commercial corridor. Shelf positioning separates premium antibacterial variants from commodity surfactant tiers.
- Pharmacies:Mexican pharmacy networks retain specification influence for antibacterial positioning, particularly in child-safe and dermatologist-recommended segments. Colgate-Palmolive leverages this channel for differentiated antimicrobial claims.
- Online Retailers:Direct-to-institution platforms in Colombia enable manufacturer margin capture through logistics integration, bypassing traditional distributor layers.
- Specialty Stores:Premium and organic-positioned formats occupy niche positioning in urban Brazilian and Mexican markets with elevated price tolerance.
Dominant volume channel: Supermarkets. Gaining share fastest: Online Retailers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo's dense commercial corridor anchors Latin American hand soap demand through concentrated healthcare procurement and retail distribution infrastructure. The Southeast Brazil metro sustains bulk institutional contracts for liquid soap formats with integrated dispenser systems across its hospital and corporate networks.
Brazil
ANVISA sanitation mandates on hospital hygiene standards force facility-wide soap upgrades across São Paulo and Rio de Janeiro healthcare clusters. Brazil's national health surveillance agency tightens registration requirements for antibacterial formulations containing quaternary ammonium compounds. The Southeast region concentrates manufacturing capacity for alcohol-free variants serving captive institutional demand.
Mexico
NOM-005 hygiene standards accelerate product reformulation toward alcohol-free antibacterial variants in Mexico City and Monterrey hospital networks. The Ministry of Economy enforces labeling requirements that dictate permissible antimicrobial claims for educational institution procurement. State-level school hygiene programs generate specification demand for child-safe formats in Jalisco and Nuevo León.
Colombia
INVIMA maintains divergent cosmetic-drug classification frameworks that extend product launch timelines for cross-border standardization. Bogotá's tertiary care cluster shifts from product-only tenders to multi-year facility hygiene partnerships bundling soap chemistry with dispenser hardware. Centralized procurement platforms enable direct-to-institution margin capture for manufacturers with logistics integration.
Argentina
ANMAT biocide restrictions force parallel formulation tracks that inflate R&D overhead for manufacturers serving both Brazilian and Argentine markets. Buenos Aires healthcare facilities maintain distinct procurement specifications from Mercosur neighbors due to regulatory misalignment. The capital's hospital networks concentrate demand for imported surfactant formulations pending domestic production scaling.
Chile
Pacific Alliance harmonization talks position Santiago as a potential regulatory bridge for Brazilian and Mexican manufacturers with established biocide compliance documentation. Chile's Ministry of Health references EU hazard classifications in draft cosmetic preservative limits, creating pre-emptive reformulation pressure. The Santiago-Valparaíso corridor underperforms in per-capita institutional hand soap consumption relative to regional peers.
Latin America Hand Soap Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation chemistry and institutional certification depth. The market structure fragments across multinational consumer goods conglomerates with distribution scale, regional specialists with regulatory agility, and private-label manufacturers serving price-sensitive retail channels. Three archetypes dominate: full-service hygiene suppliers bundling hardware and chemistry, surfactant formulators with ANVISA registration expertise, and dispenser-integrated system providers. Competitive moves concentrate on strategic partnerships with healthcare procurement platforms and portfolio diversification into alcohol-free antibacterial actives.
Among U.S.-based multinationals, Procter & Gamble and Kimberly-Clark occupy positions exemplifying distribution-depth archetypes, while Colgate-Palmolive represents the antimicrobial-positioning specialist tier. These entities anchor competitive dynamics through divergent channel strategies rather than direct product confrontation.
| Leading Market Players |
|---|
| Kimberly-Clark |
| Henkel AG & Co. KGaA |
| Colgate-Palmolive Company |
| Procter & Gamble |
| GOJO Industries |
| 3M |
| Mex-Ar Productos |
| Daryza |
| Prolimp del Centro |
| Others |
Supply & Pricing Matrix
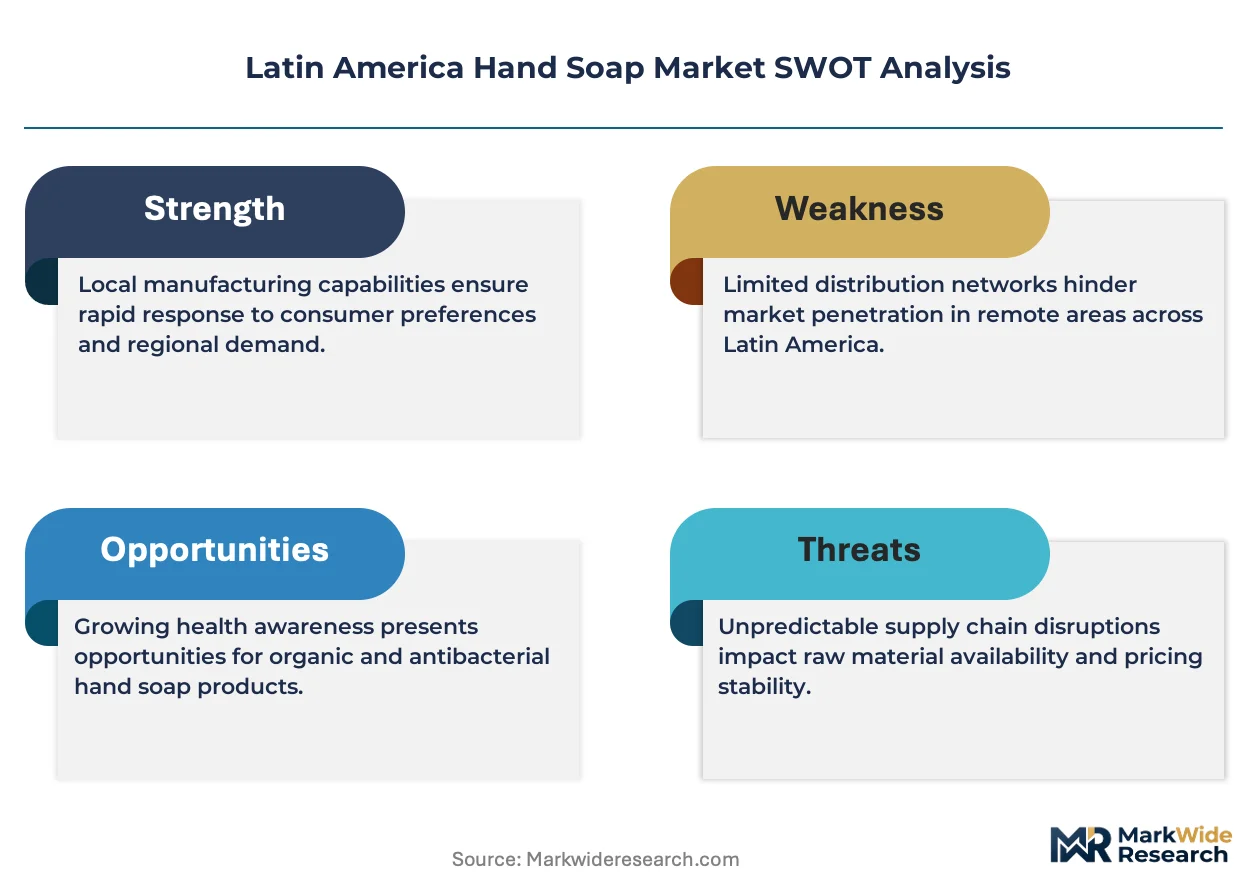
Captive backward integration into surfactant production anchors pricing power for Brazilian manufacturers serving São Paulo's healthcare corridor, while Mexican formulators without oleochemical assets absorb palm kernel oil volatility through contract structures. This integration asymmetry separates margin-stable institutional suppliers from price-pressed commodity players across Latin American procurement channels.
Pricing Analysis
Throughput-based pricing tied to dispenser system deployment dominates institutional contracts across Colombian hospital networks, where multi-year hygiene partnerships bundle chemistry with hardware provisioning. Certification grade and ANVISA registration depth drive price differentiation between alcohol-free antibacterial variants and standard surfactant cleansers. Cost compression in commodity liquid soap intensifies as palm kernel oil feedstock swings compress margin buffers for import-dependent Brazilian formulators. Household segments through São Paulo supermarkets exhibit highest price sensitivity, while healthcare procurement committees prioritize compliance documentation over unit cost.
Supply Chain Analysis
ANVISA and INVIMA registration requirements gate market access for antimicrobial formulations, extending lead times for cross-border product standardization between Brazil, Mexico, and Colombia. Surfactant feedstock draws from Southeast Asian palm kernel oil suppliers, Brazilian domestic oleochemical producers, and imported sodium lauryl sulfate from U.S. Gulf Coast refiners. Single-source vulnerability concentrates in Southeast Asian oleochemical shipments subject to climate-related production disruptions. Distribution runs through healthcare procurement platforms in Bogotá, pharmacy networks across Mexican urban centers, and supermarket chains anchoring São Paulo's retail corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Latin American hand soap sits in a formulation-transition phase as quaternary ammonium compounds displace legacy triclosan actives under tightening ANVISA and NOM-005 guidance. This chemistry shift rewards regulatory agility over manufacturing scale.
For Market Incumbents: Anchor institutional contract renewal through integrated dispenser-logistics bundling in Bogotá and São Paulo healthcare clusters, defending against full-service hygiene suppliers capturing procurement centralization. Deepen backward integration into surfactant production to offset palm kernel oil volatility squeezing Brazilian formulators without captive oleochemical supply. Prioritize benzalkonium chloride registration depth as INVIMA extends antimicrobial approval timelines. For New Entrants and Emerging Players: NOM-005 compliance pathways in Mexico open a window for specialized antibacterial positioning in Jalisco and Nuevo León educational procurement, where state-level school hygiene programs generate specification demand for verified triclosan-free chemistry. Pacific Alliance harmonization talks position Chilean market access as the most penetrable geography for Brazilian manufacturers with established biocide documentation. Pursue direct-to-institution platform integration in Colombian healthcare procurement, bypassing traditional distributor markups. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by full-service hygiene conglomerates seeking ANVISA registration portfolios and dispenser system integration capabilities. Long-term viability favors surfactant formulators with backward integration into oleochemicals and established institutional contract structures across the analysis window. Monitor Pacific Alliance biocide harmonization progress as the signal for cross-border standardization feasibility and inventory complexity reduction.| Strategic Initiative | Industry Significance |
|---|---|
| Alcohol-Free Antibacterial Reformulation | ANVISA and NOM-005 mandates force chemistry pivots toward quaternary ammonium compounds in hospital networks. |
| Dispenser System Integration | Bogotá procurement platforms specify bundled hardware-soap tenders locking in multi-year institutional relationships. |
| Backward Integration into Surfactants | Brazilian manufacturers with captive oleochemical production buffer palm kernel oil volatility compressing import-dependent competitors. |
| Direct-to-Institution Platform Access | Colombian healthcare procurement platforms enable margin capture bypassing traditional distributor layers. |
| Pacific Alliance Regulatory Harmonization | Chile's Ministry of Health referencing EU hazard classifications creates pre-emptive compliance pathways for Brazilian exporters. |
Research Methodology
Independent corroboration across ANVISA registration filings, INVIMA cosmetic-drug classification records, and NOM-005 compliance documentation underwrites the qualitative findings on antimicrobial formulation shifts. Primary interviews with procurement directors at Colombian hospital networks, category buyers at Brazilian supermarket chains, and regulatory affairs leads at Mexican manufacturers combined with secondary validation from customs trade data, Pacific Alliance harmonization communiqués, and hospital procurement platform disclosures. Bottom-up volume modeling across product type, end user, and distribution channel segments triangulated against top-down macroeconomic indicators.
Comparable-period anchoring to pre-pandemic baseline consumption patterns established the forecast framework, with projection horizon modeling spanning product type segmentation across liquid, antibacterial, foam, and gel formats. End-user stratification incorporated healthcare facility procurement centralization, household price sensitivity gradients, and educational institution mandate expansion. CAGRs derived from volume trajectory analysis incorporating dispenser technology penetration rates and biocide registration timeline assumptions. Industry-specific inputs included palm kernel oil price elasticity coefficients and ANVISA approval queue duration estimates.
The model assumes a particular technology adoption path; alternative pathways for foam dispenser compatibility would alter the outlook if water-reduction targets accelerate beyond healthcare into commercial segments. Forecasts incorporate assumptions on Pacific Alliance harmonization progress and Mercosur biocide alignment that material regulatory divergence would revise. A model refresh is warranted upon material change in ANVISA antimicrobial registration guidance or Pacific Alliance technical harmonization timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Grooming Products
Europe Electric Toothbrush Market
Personal Grooming Products
Charcoal Bristle Toothbrush Market
Personal Grooming Products
Military Hydration Products Market
Personal Grooming Products
Underarm Sweat Pads Market
Personal Grooming Products
Gel Socks Market
Personal Grooming Products
Electric Tooth Polisher Market
Personal Grooming Products
India Beard Trimmer Market
Personal Grooming Products
Handheld Massager Market
Personal Grooming Products
India Sexual Wellness Market
Personal Grooming Products
Global Massage Guns Market
Personal Grooming Products
Personal Hygiene Market
Personal Grooming Products
Sneaker Deodorant Market
Personal Grooming Products
Ear Piercing Guns Market
Personal Grooming Products
Global Hairbrush Market
Personal Grooming Products
Horsehair Clippers Market
Personal Grooming Products
Nose & Ear Hair Trimmers Market