
 Shaving Market | 2026-2036
Shaving Market Size, Share, and Industry Trends Forecast 2026-2036
Shaving Market Intelligence
The gap between premium and commodity tiers is shifting from blade count to full grooming system integration, with subscription models and dermatological testing now separating the segments. Edgewell Personal Care leverages its Schick and Wilkinson Sword portfolios to sustain mass-market shelf dominance across North American retailers. Koninklijke Philips N.V. anchors the electric segment through GroomTribe app connectivity and sensor-driven motor controls. Harry's Inc. differentiates via direct-to-consumer verticality and limited retail partnerships that preserve margin structure.
Shaving encompasses the mechanical removal of facial and body hair using bladed or powered devices engineered with specific cutting angles, typically between 30 and 45 degrees, and coatings such as chromium, PTFE, or diamond-like carbon to reduce friction and extend edge retention. Electric razors lead value generation due to replacement part cycles and lithium-ion battery refresh demand, while safety razors occupy a resurgent niche driven by zero-waste consumer preferences and stainless steel durability. The customer-type dimension shows salons as a concentrated professional channel where blade hygiene standards and bulk procurement terms create distinct margin pools separate from retail.
The FDA regulates shaving devices as cosmetic or medical products depending on intended claims, while the EU MDR and REACH frameworks govern blade material composition and skin-contact biocompatibility. These standards elevate compliance costs for new entrants but protect incumbent positions by forcing reformulation of lubricating strips and handle polymers. Stakeholders must monitor how evolving state-level packaging laws and extended producer responsibility schemes reshape cost structures before committing to regional manufacturing footprints.
Market Dynamics
The shaving market's central structural force is the migration from standalone blade sales to integrated grooming ecosystems, where hardware margins compress while recurring consumables and digital services capture lifetime value.
Growth Catalysts
- EU REACH nickel-release limits:Metal blade manufacturers accelerate ceramic and polymer composite adoption to meet skin-contact biocompatibility thresholds, creating material innovation spillover.
- Salon professional channel consolidation:Barbershops and grooming lounges standardize on bulk cartridge procurement with sterilization protocols, locking in recurring B2B volume.
- Lithium-ion cell chemistry advances:Electric razor motor density improvements extend cordless runtime, reducing replacement cycle frequency while expanding travel-use occasions.
Market Restraints
- Stainless steel price volatility:Safety razor and traditional blade producers face margin compression from commodity metal input swings.
- Single-source PTFE coating supply:Blade lubrication strip chemistry concentrates among specialty fluoropolymer processors in Germany and Japan.
- FDA cosmetic-versus-medical classification ambiguity:Claims around ingrown-hair prevention or sensitive-skin relief trigger extended approval timelines.
Strategic Opportunities
- India tier-two urban expansion:Cartridge system penetration lags in secondary cities like Pune and Jaipur versus saturated Mumbai-Delhi corridors.
- Dermatologist-validated formulations:Pre-shave skincare preparation creates white space between pharmacy and mass retail positioning.
- Extended producer responsibility mandates:EU packaging waste directives incentivize refillable handle systems with take-back logistics.
Industry Challenges
- Precision grinding technician scarcity:Blade edge geometry expertise concentrates among aging workforces in Solingen and Sheffield.
- Multi-jurisdiction labeling complexity:Simultaneous FDA, ECHA, and BIS compliance requires parallel certification tracks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shaving Market |
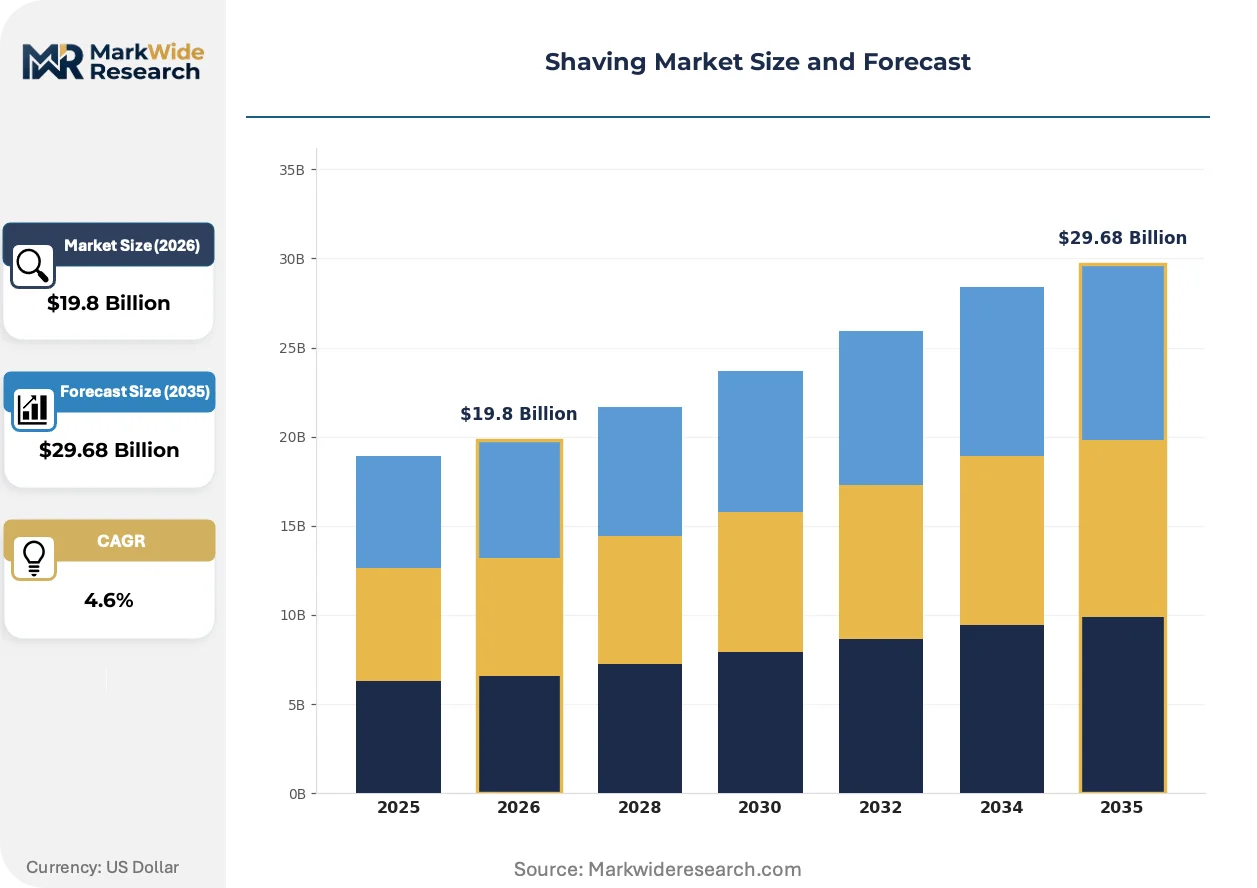
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $29.68 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Safety Razors, Electric Razors, Disposable Razors, Straight Razors Customer Type: Men, Women, Salons, Retailers Price Tier: Premium, Mid-range, Budget, Discount Material: Stainless Steel, Plastic, Aluminum, Ceramics |
| Companies Covered | Edgewell Personal Care, Spectrum Brands Holdings, The Procter & Gamble Company, Wahl Clipper Corporation, Harry’s Inc., Koninklijke Philips N.V., Société BIC SA, Conair Corporation, Panasonic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shaving Market Strategic Shifts & Innovations
Sensor-embedded hardware and subscription replenishment models are collapsing the traditional purchase-replacement cycle into continuous engagement architectures.
Diamond-like carbon coatings are expanding into mid-tier cartridge blades, reducing friction coefficients below PTFE alternatives. Premium and mass-market manufacturers alike adopt this deposition technology to extend edge retention claims. The shift is compressing differentiation windows between price tiers while raising baseline consumer performance expectations.
ECHA REACH substance restrictions on nickel and chromium VI compounds are forcing blade alloy reformulation across European supply chains. Manufacturers substitute surgical-grade stainless grades or ceramic composites to maintain skin-contact compliance. Electric segment producers face parallel pressure on motor housing alloys, accelerating polymer-over-metal redesigns.
Direct replenishment via connected devices is displacing retail repurchase cycles in the electric segment. Grooming apps track blade wear through motor load sensors and auto-trigger consumable shipments. Subscription attach rates concentrate in North American and Western European markets where logistics infrastructure supports predictable delivery windows.
Shaving Market Segmentation
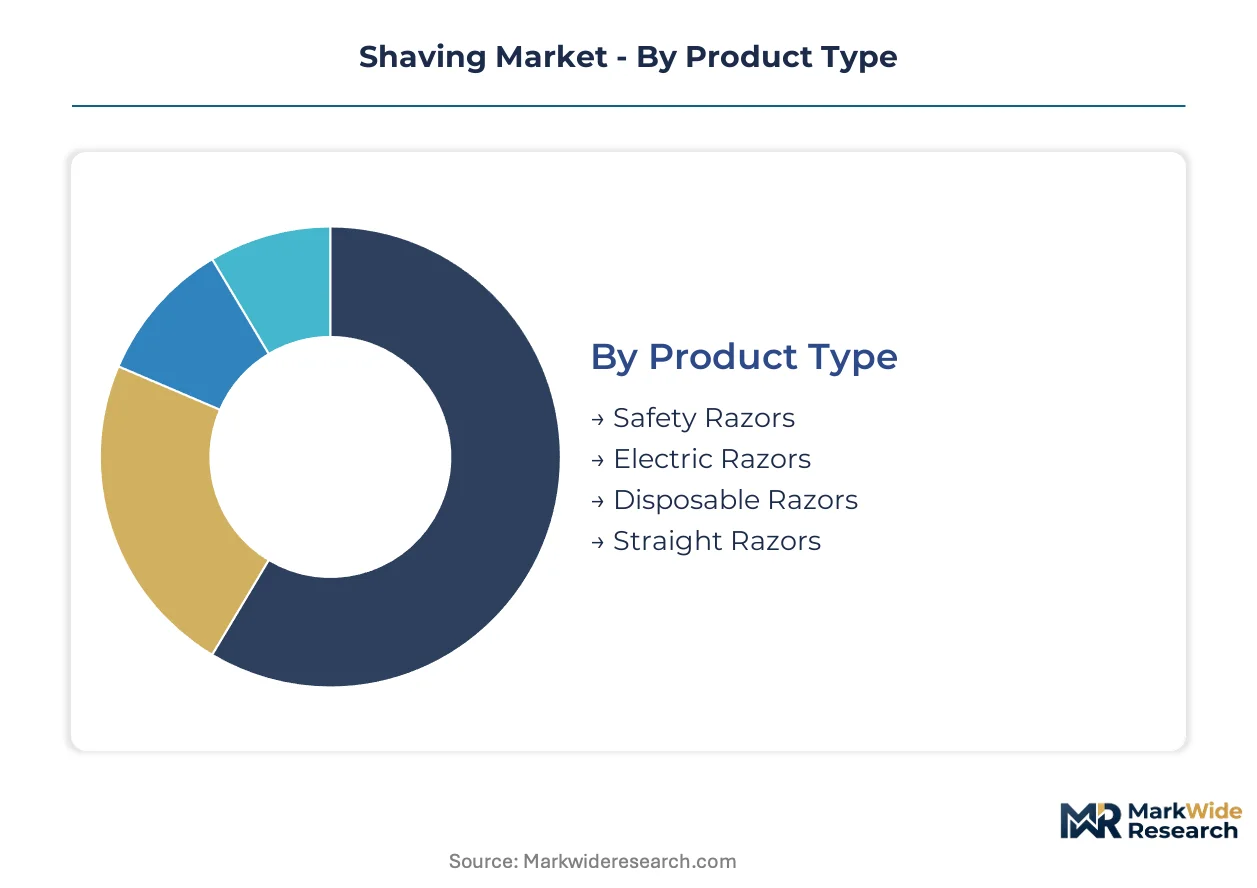
Segmentation in the shaving market reveals how hardware specifications, procurement channels, and material compliance requirements create distinct margin pools. Each dimension carries regulatory and supply-chain implications that shape competitive positioning.
Product Type:
Cutting mechanism and power source differentiate performance characteristics, maintenance cycles, and replacement revenue models across the hardware spectrum.
- Electric Razors:Rotary and foil systems with lithium-ion power cells generate recurring revenue through replacement blade cartridges and battery refresh cycles. Sensor-enabled motor controls from Philips and Braun concentrate demand in Germany, Japan, and the United States where connected-device adoption runs highest.
- Safety Razors:Double-edge blade systems with stainless steel construction appeal to zero-waste consumer segments seeking durable hardware. Sheffield and Solingen manufacturers face stainless steel price volatility while serving niche demand in France, the United Kingdom, and urban India.
- Disposable Razors:Single-use plastic-handle systems with fixed blade heads dominate mass-market retail in India and Southeast Asia where price sensitivity shapes procurement.
- Straight Razors:Fixed-blade cutthroat designs with carbon or stainless steel edges persist in professional barbershop channels requiring sterilization protocols.
Electric razors lead on scale; safety razors lead on momentum.
Customer Type:
Procurement patterns and volume concentration separate individual consumers from institutional channels with distinct hygiene and bulk-purchasing requirements.
- Salons:Professional grooming establishments standardize on bulk cartridge procurement with sterilization protocols and blade hygiene standards. Barbershops in Turkey, the United States, and the United Kingdom lock in recurring B2B volume through distributor relationships.
- Men:Individual male consumers drive cartridge system adoption in urban India and Southeast Asia where multi-step skincare preparation now precedes shaving routines.
- Women:Female consumers concentrate demand for body-specific razor designs with ergonomic handles and moisture strips across North American and Western European retail.
- Retailers:Mass-market and specialty retail channels manage inventory turns and shelf-space allocation between premium and commodity tiers.
Salons command the highest per-unit margins; men contribute the largest absolute volume base.
Price Tier:
Cost positioning aligns with material specification, dermatological validation, and distribution channel density across the purchasing spectrum.
- Premium:Dermatologist-tested systems with ceramic coatings and subscription replenishment models. Harry's and Dollar Shave Club built direct-to-consumer verticality here before selective retail expansion.
- Mid-range:Cartridge systems with lubricating strips and ergonomic polymer handles distributed through mass retail. Schick and Gillette maintain shelf dominance in this band across Walmart and Target in the United States.
- Budget:Private-label and store-brand disposables with basic blade counts serve price-sensitive segments in India, Brazil, and Southeast Asian markets.
- Discount:Bulk-packaged single-blade systems for developing market entry-level consumers trading up from traditional straight razors.
Premium tier captures lifetime value through subscriptions; budget tier drives penetration in emerging urban corridors.
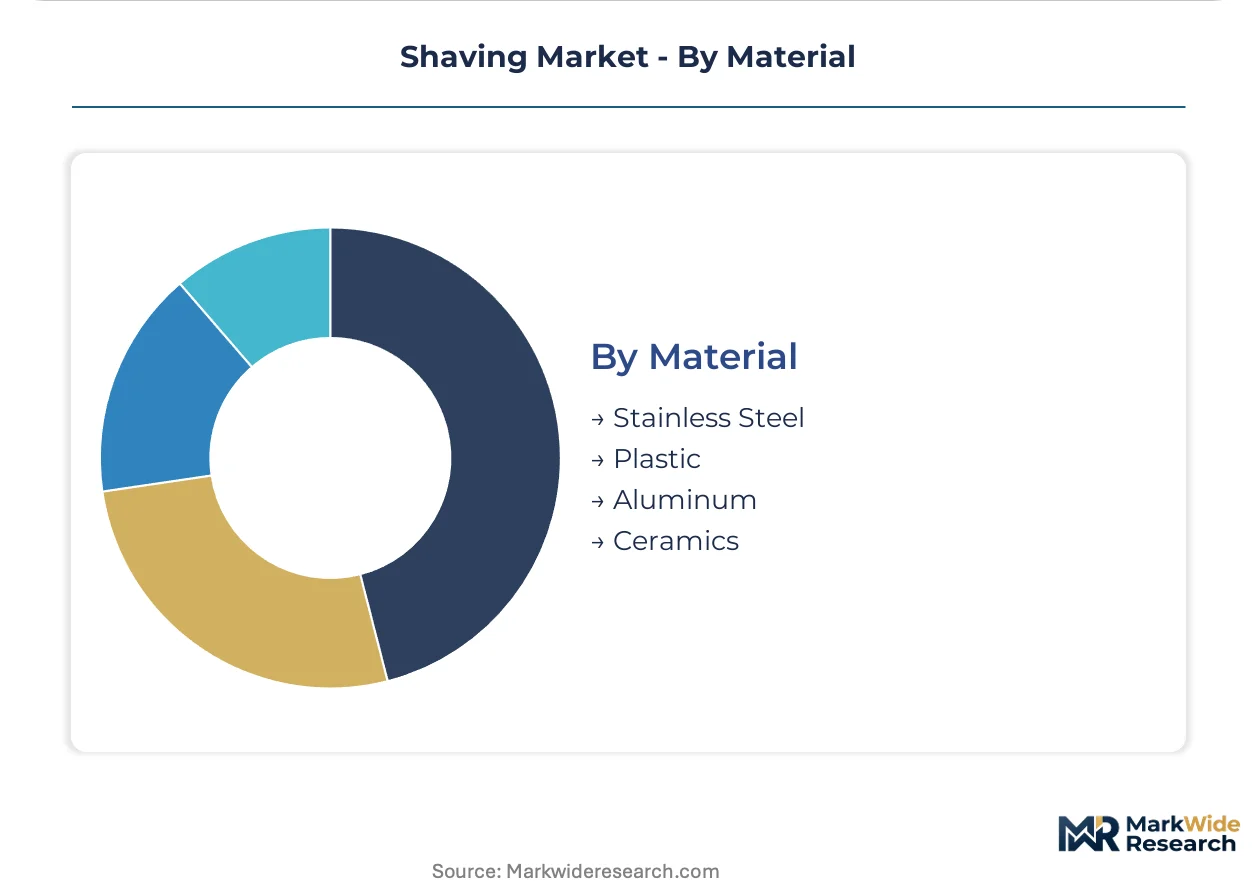
Material:
Substrate selection determines regulatory compliance pathways, manufacturing cost structures, and end-of-life disposal requirements.
- Stainless Steel:Surgical-grade alloys dominate blade production with REACH nickel-release compliance driving reformulation. Solingen and Sheffield grinding expertise concentrates in aging workforces.
- Plastic:Polymer handle systems and disposable chassis face EU packaging waste directive pressure. Extended producer responsibility schemes incentivize design-for-recycling.
- Aluminum:Lightweight metal handles with anodized finishes occupy mid-premium positioning between plastic and steel alternatives.
- Ceramics:Zirconium dioxide and alumina composites emerging as nickel-free blade substrates for EU REACH compliance in skin-contact applications.
Stainless steel maintains supply concentration; ceramics gain share fastest on regulatory tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision grinding expertise concentrates among aging workforces in Solingen and Sheffield, anchoring European blade quality standards while Asian manufacturing scales meet volume demand.
United States
Subscription replenishment models and connected-device adoption drive electric razor demand in metropolitan corridors. FDA cosmetic-versus-medical classification governs claims around sensitive-skin formulations. Boston and San Francisco anchor direct-to-consumer verticals with GroomTribe app connectivity penetrating professional grooming lounges.
Germany
Engineering heritage and sensor-driven motor controls sustain premium electric razor positioning. ECHA REACH nickel-release limits force blade alloy reformulation across Solingen manufacturing clusters. Bavaria and North Rhine-Westphalia concentrate PTFE coating supply relationships with specialty fluoropolymer processors.
India
Urban male consumers trade up from single-blade disposables to cartridge systems in tier-two cities. BIS standards govern metal blade import quality and skin-contact safety thresholds. Pune and Jaipur lag Mumbai-Delhi penetration rates, creating whitespace for mid-tier cartridge expansion.
Japan
Rotary and foil system refinement targets discerning consumers with lithium-ion runtime expectations. METI energy efficiency guidelines shape battery chemistry selection and motor density improvements. Osaka and Nagoya manufacturing clusters supply precision blade assemblies to regional OEM networks.
United Kingdom
Zero-waste consumer preferences sustain safety razor resurgence through stainless steel durability appeals. Sheffield grinding expertise faces workforce succession challenges as traditional blade geometry knowledge concentrates among aging technicians. London barbershops standardize on bulk cartridge procurement with sterilization protocols.
Shaving Market Key Industry Players
Top-tier vendors anchor premium subscription tiers, while mass-market shelf dominance concentrates among legacy personal care conglomerates. The vendor base spans three strategic archetypes: direct-to-consumer verticals preserving margin structure through limited retail partnerships; engineering-driven electric specialists leveraging app connectivity and sensor integration; and diversified consumer goods portfolios sustaining mass-market distribution density. Competitive moves concentrate on dermatological validation partnerships and extended producer responsibility compliance for EU packaging directives.
Among diversified personal care conglomerates, Edgewell Personal Care and The Procter & Gamble Company occupy positions exemplifying mass-market shelf dominance across North American retailers. Koninklijke Philips N.V. anchors the engineering-driven electric specialist archetype through GroomTribe app connectivity and sensor-driven motor controls. Harry's Inc. represents direct-to-consumer verticality with selective retail expansion preserving margin structure.
| Leading Market Players |
|---|
| Edgewell Personal Care |
| Spectrum Brands Holdings |
| The Procter & Gamble Company |
| Wahl Clipper Corporation |
| Harry's Inc. |
| Koninklijke Philips N.V. |
| Société BIC SA |
| Conair Corporation |
| Panasonic Corporation |
| Others |
Cost & Logistics Intelligence
Captive coating technology ownership anchors both supply security and premium pricing power for blade manufacturers navigating EU REACH nickel-release compliance. This backward integration into PTFE and diamond-like carbon deposition capabilities separates subscription-tier vendors from commodity competitors dependent on German and Japanese specialty processors.
Pricing Analysis
Bundled subscription services versus unbundled transactional hardware sales define the pricing architecture across consumer segments. Three-tier pricing structure across premium, standard, and economy levels reflects dermatological validation, connected-device features, and replacement cartridge attach rates. Cost compression in budget disposables intensifies because private-label competition concentrates in Indian and Southeast Asian mass retail. Price-sensitive entry-level consumers in tier-two Indian cities contrast with least-sensitive professional salon buyers securing bulk sterilization-compliant cartridges.
Supply Chain Analysis
Reverse-logistics flows for refillable handle take-back programs and blade cartridge recycling reshape distribution economics under EU extended producer responsibility mandates. Manufacturing concentrates in China, Germany, and Japan for precision grinding and motor assembly. Raw material dependencies center on surgical-grade stainless steel, lithium-ion cells, and fluoropolymer coatings. Single-source vulnerability in Solingen and Sheffield grinding expertise threatens blade geometry quality continuity. Distribution runs through mass retail chains in North America, direct-to-consumer platforms in Western Europe, and traditional trade networks in emerging Asian markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in dermatologist-validated pre-shave formulations and connected-device subscription attach rates, with ceramic coating substitution reducing EU compliance cost burdens.
For Market Incumbents: Acquire precision grinding technician training assets and apprenticeship programs to secure Solingen and Sheffield knowledge transfer before workforce retirement accelerates. Consolidate sterilization-protocol cartridge supply relationships with Turkish and United Kingdom barbershop distributors to lock B2B volume against direct-to-consumer entrants. Channel control through exclusive salon distributor contracts defends against Harry's-style verticality.
For New Entrants and Emerging Players: Begin with dermatologist partnership formulations targeting the pharmacy-retail gap between mass-market cartridges and clinical skincare. White space concentrates in Pune and Jaipur cartridge penetration lagging Mumbai-Delhi corridors. Go-to-market leverage through regional Indian e-commerce platforms bypasses established retail slotting fee barriers.
For Investors and Strategic Acquirers: Roll-up economics work for regional barbershop supply distributors because professional channel consolidation creates recurring B2B revenue pools with sterilization compliance moats. Long-term viability frames around subscription attach rate sustainability and ceramic substrate patent positions. Monitor EU packaging waste directive enforcement timelines as inflection indicator for refillable system adoption acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Dermatological Validation Partnership | FDA cosmetic-versus-medical classification clarity unlocks pharmacy channel positioning for pre-shave formulations. |
| Ceramic Blade Substrate Transition | ECHA REACH nickel-release compliance eliminates European market access risk for metal-alloy dependent producers. |
| Connected-Device Platform Launch | GroomTribe-style motor sensor integration enables consumable auto-replenishment and lifetime value capture. |
| Salon Distribution Channel Expansion | Bulk sterilization-protocol procurement in Turkey and United Kingdom locks recurring B2B volume with superior per-unit margins. |
| Extended Producer Responsibility Compliance | EU packaging waste directive adherence preserves market access and enables refillable handle take-back program differentiation. |
Research Approach
Bottom-up cartridge system adoption modeling reconciled against top-down electric razor replacement cycle tracking forms the analytical core of this study. Primary interviews with brand managers at personal care conglomerates, category buyers at North American mass retailers, barbershop procurement heads in Turkey and the United Kingdom, and supply planners at coating technology providers combined with secondary validation from FDA 510(k) filings, ECHA REACH substance restriction updates, BIS metal blade import standards, and Nielsen retail audit data. Triangulation between consumer demand signals and manufacturing capacity disclosures ensures segmentation accuracy.
Input-output matrices connect lithium-ion cell chemistry advances, PTFE coating supply availability, and precision grinding workforce demographics to volume and value projections across the analysis window. Segmentation dimensions span cutting mechanism type, customer procurement channel, price tier positioning, and blade material substrate. CAGRs derive from replacement frequency modeling by device category and urban penetration rate differentials between Indian tier-one and tier-two cities. Forecast inputs incorporate EU regulatory compliance cost trajectories and salon professional channel consolidation velocity.
Several conditions sit outside the modeled scope, including sudden stainless steel commodity price spikes, unilateral FDA reclassification of ingrown-hair prevention claims, and disruptive battery chemistry substitutions beyond lithium-ion. Forecasts reflect assumptions about regulatory enforcement consistency and consumer subscription retention patterns. Practitioners should monitor ECHA substance restriction expansion timelines and Indian urban disposable income trajectories for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Grooming Products
Asia Pacific Hair Styling Tools Market
Personal Grooming Products
Compostable Toothbrush Market
Personal Grooming Products
Shoe Deodorizer Market
Personal Grooming Products
Razor Market
Personal Grooming Products
Global Consumer Use IPL Hair Removal Devices Market
Personal Grooming Products
Baby Oil Market
Personal Grooming Products
Global Organic and Natural Feminine Care Market
Personal Grooming Products
Hair Styling Tools Market
Personal Grooming Products
Electric Toothbrush Market
Personal Grooming Products
Global Aligner Sheet Market
Personal Grooming Products
Heated Razor Starter Kit Market
Personal Grooming Products
Bamboo Toothbrush Market
Personal Grooming Products
Smart Bathroom Scale Market
Personal Grooming Products
Organic Tampons Market
Personal Grooming Products
Disposable Slippers Market
Personal Grooming Products
Epilators Market