
 Europe and MEA Condom Market | 2026-2036
Europe and MEA Condom Market Size, Share, and Industry Trends Forecast 2026-2036
Europe and MEA Condom Market Intelligence
The EU Green Deal's chemical sustainability targets is realigning procurement criteria for intimate health products across European healthcare systems. Reckitt Benckiser Group plc leverages its pharmacy and supermarket shelf presence to sustain volume leadership in Western Europe. Karex Berhad anchors supply security through integrated natural rubber sourcing from Southeast Asian plantations. LifeStyles Healthcare Pte. Ltd. differentiates via polyurethane and polyisoprene formulations that compete directly with traditional latex offerings.
Europe and MEA condoms comprise barrier contraceptive sheaths manufactured from natural rubber latex, synthetic polymers, or processed lamb membrane, typically measuring 170-200mm in length with wall thickness of 0.04-0.08mm, designed to prevent pregnancy and pathogen transmission during sexual intercourse. The latex segment dominates unit volume across price-sensitive MEA markets where public health programs drive bulk procurement, while polyisoprene and polyurethane variants command premium positioning in European retail channels targeting consumers with latex sensitivities. Online retail represents the fastest-expanding distribution channel, particularly in Gulf Cooperation Council states where digital payment infrastructure and discreet delivery preferences reshape purchasing behavior.
EMA's medical device oversight and the EU MDR classification of condoms as Class IIa devices enforce rigorous biocompatibility and mechanical testing standards that shape manufacturer compliance investments. France's ANSM and South Africa's national health regulator apply additional national labeling and import certification requirements that filter market access for non-compliant suppliers. Stakeholders must monitor evolving Extended Producer Responsibility frameworks for single-use intimate products and anticipate how MEA national HIV prevention programs rebalance between donor-funded commodity distribution and commercial retail expansion.
Market Dynamics
The EU Medical Device Regulation is compressing compliance timelines for intimate health products while healthcare procurement across France and South Africa pivots toward non-latex alternatives, creating dual pressure on manufacturer formulation portfolios and certification investments.
Growth Catalysts
- EU Green Deal chemical targets:Sustainability mandates are realigning public health procurement criteria toward low-carbon manufacturing processes for barrier contraceptives.
- South Africa's HIV prevention programs:Government bulk purchasing of male condoms for distribution through public clinics sustains baseline volume demand across price-sensitive segments.
- Polyurethane and polyisoprene formulations:Synthetic polymer alternatives are capturing consumers with latex sensitivities in European pharmacy and supermarket channels.
Market Restraints
- Natural rubber price volatility:Southeast Asian plantation supply disruptions transmit directly to raw material costs for latex-dominant producers serving MEA public health contracts.
- EU MDR Class IIa device classification:Rigorous biocompatibility and mechanical testing documentation requirements filter market access for smaller manufacturers lacking regulatory affairs capacity.
- Extended Producer Responsibility frameworks:Emerging single-use intimate product disposal regulations in France and Germany threaten to impose end-of-life cost burdens on manufacturers.
Strategic Opportunities
- UAE digital retail infrastructure:Gulf Cooperation Council states with mature payment systems and discreet delivery preferences represent underexploited direct-to-consumer expansion territory.
- Pharmacy-dominant German distribution:Professional channel credibility offers premium positioning potential for clinically positioned synthetic polymer variants.
- WHO prequalification pathways:Alignment with international procurement standards opens donor-funded commodity channels across MEA national prevention programs.
Industry Challenges
- Biocompatibility testing capacity:EMA-mandated cytotoxicity and sensitization studies require specialized laboratory partnerships that concentrate among limited European service providers.
- Dual formulation manufacturing:Parallel production of latex and non-latex sheaths demands segregated production lines and distinct quality management systems.
- ANSM labeling compliance:France's national regulator applies supplementary French-language packaging requirements that extend product registration timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe and MEA Condom Market |
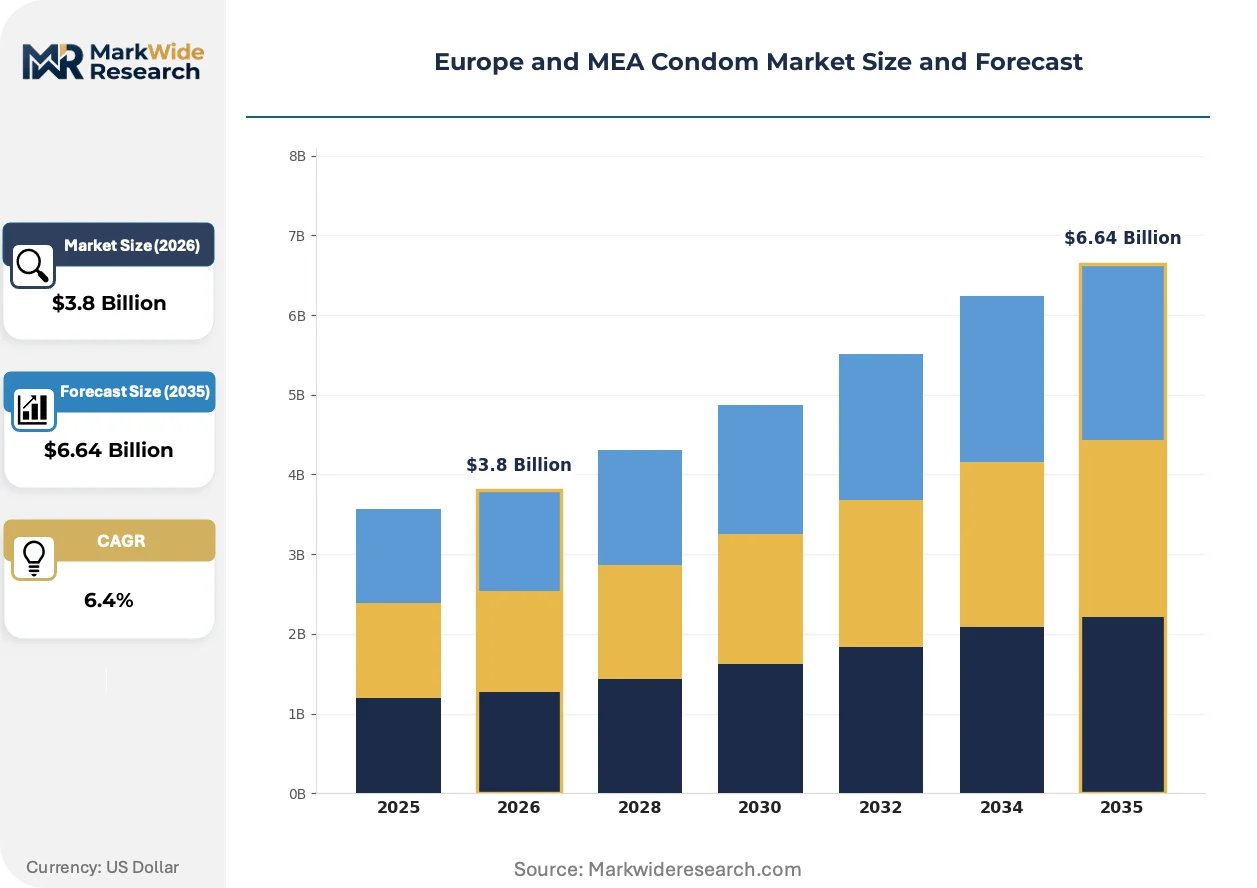
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Latex, Polyurethane, Polyisoprene, Lambskin Application: Pregnancy Prevention, STD Prevention, Sexual Wellness, Personal Lubrication End User: Individuals, Couples, Healthcare Providers, Retailers Distribution Channel: Pharmacies, Supermarkets, Online Retail, Convenience Stores |
| Companies Covered | Reckitt Benckiser Group plc, Church & Dwight Co., Inc., LifeStyles Healthcare Pte. Ltd., Karex Berhad, Pasante Healthcare Ltd., Fuji Latex Co., Ltd., Ansell Ltd, Sagami Rubber Industries, Okamoto Industries, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe and MEA Condom Market Strategic Shifts & Innovations
Material science advances and regulatory digitization are reshaping competitive requirements across European and MEA condom markets, compressing the gap between commodity and premium positioning.
Polyisoprene synthetic elastomer is expanding into European retail pharmacy channels as the primary latex alternative for consumers with Type I hypersensitivity reactions. German and French pharmacy buyers are accelerating shelf-space allocation for these formulations. The technology is expanding into premium positioning that commands 40-60% price elevation over standard latex equivalents.
REACH chemical substance restrictions and EU MDR technical documentation requirements are forcing reformulation of lubricant additives and packaging adhesives. Manufacturers must now submit complete supply chain chemical inventories for intimate health products. French ANSM and German BfArM national implementations are creating staggered compliance deadlines that fragment product launch sequencing.
Digital pharmacy platforms and telehealth-integrated subscription models are displacing traditional retail purchasing across Gulf Cooperation Council urban centers. UAE and Saudi consumers increasingly favor app-based ordering with unmarked delivery packaging. This channel shift is most visible among 25-40 year old demographics in Dubai and Riyadh where smartphone penetration exceeds 95%.
Europe and MEA Condom Market Segmentation
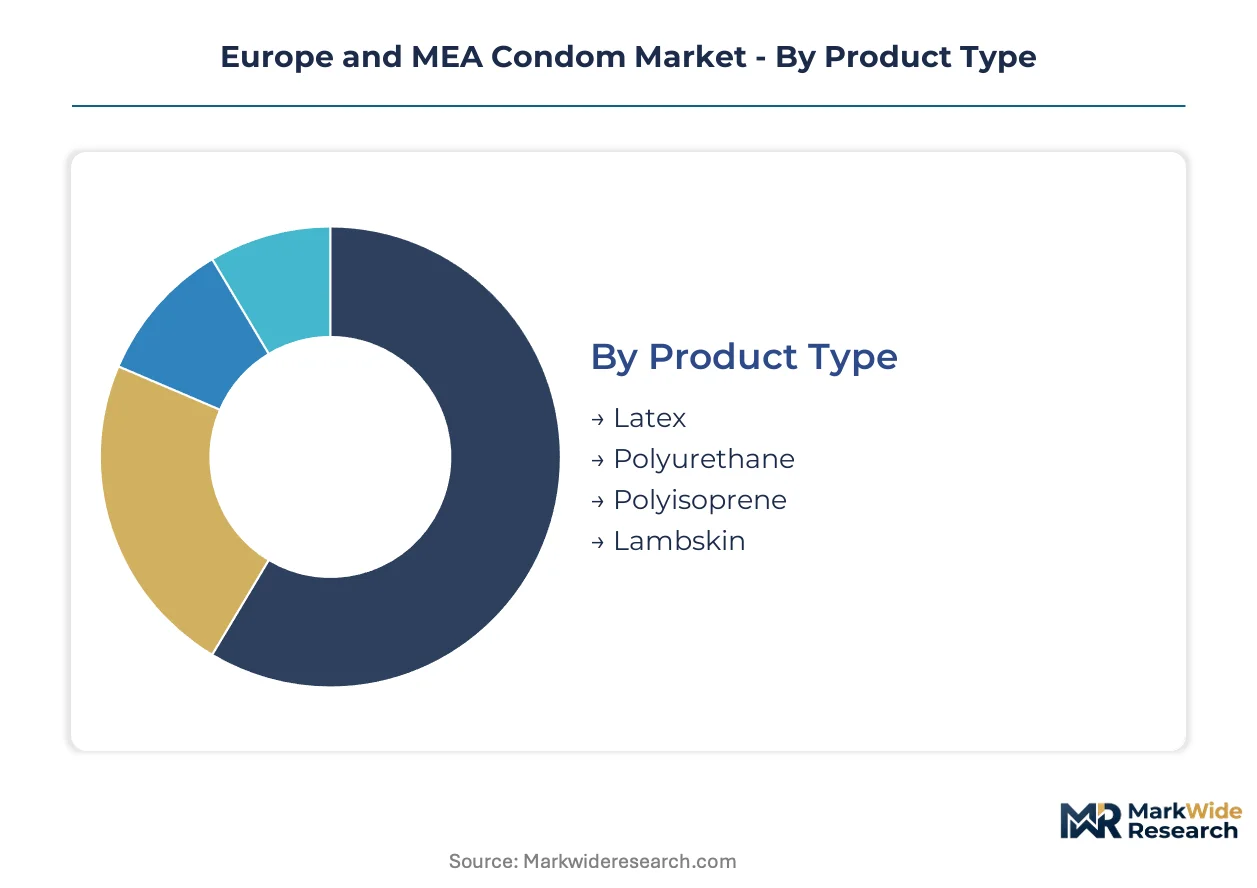
Material composition and distribution infrastructure define competitive positioning across European and MEA condom markets. Procurement patterns diverge sharply between public health bulk purchasing and premium retail channels, requiring manufacturers to maintain parallel formulation portfolios.
Product Type:
Barrier sheath technology separates into natural rubber derivatives and synthetic polymer alternatives, with biocompatibility profiles determining channel access and price positioning.
- Latex:Natural rubber latex sheaths dominate unit volume across price-sensitive MEA markets where South Africa's HIV prevention programs and other public health initiatives drive bulk procurement of standard 0.06-0.07mm wall thickness products. Supply security depends on Southeast Asian plantation sourcing that exposes manufacturers to raw material price volatility.
- Polyisoprene:Synthetic elastomer formulations engineered for Type I latex hypersensitivity capture premium positioning in German and French pharmacy channels, commanding substantial price elevation over standard latex equivalents while meeting EU MDR Class IIa biocompatibility documentation requirements.
- Polyurethane:Thermoplastic polymer sheaths offer alternative synthetic option for latex-sensitive consumers, with thinner wall construction enabling distinct tactile properties.
- Lambskin:Processed lamb membrane products serve niche demand segments seeking natural material alternatives, though pathogen barrier limitations restrict clinical positioning.
Mature deployment sits with Latex. Newer deployment is concentrated in Polyisoprene.
Application:
Functional use cases span clinical prevention objectives and lifestyle-oriented consumption, with regulatory classification hinging on intended therapeutic claims.
- Pregnancy Prevention:Contraceptive efficacy claims trigger medical device classification under EU MDR and national regulators including France's ANSM, requiring mechanical integrity testing and biocompatibility documentation that shapes manufacturer compliance investments.
- STD Prevention:Pathogen barrier indications for HIV and STI transmission reduction anchor procurement specifications for South African public health programs and other MEA donor-funded distribution initiatives, with WHO prequalification pathways opening institutional purchasing channels.
- Sexual Wellness:Lifestyle-positioned products emphasizing pleasure enhancement and intimacy improvement bypass stringent medical device requirements in European retail channels, enabling faster product iteration and premium pricing.
- Personal Lubrication:Lubricated sheath variants with specialized additive formulations face evolving REACH chemical substance restrictions that force reformulation of coating compounds and packaging adhesives.
Institutional procurement concentrates in STD Prevention. Consumer-driven expansion is accelerating fastest in Sexual Wellness.
End User:
Customer archetypes range from individual consumers through institutional procurement agents, each demanding distinct packaging, labeling, and distribution configurations.
- Individuals:Single-consumer purchasing through pharmacies, supermarkets, and digital platforms drives premium segment demand across European urban centers, with discreet delivery preferences reshaping channel selection in Gulf Cooperation Council states.
- Couples:Joint purchasing decisions favor subscription models and multi-pack formats, particularly visible in UAE and Saudi telehealth-integrated platforms targeting 25-40 year old demographics.
- Healthcare Providers:Public clinics in France and South Africa anchor bulk procurement volumes, with procurement criteria pivoting toward non-latex alternatives as EU Green Deal sustainability targets realign purchasing specifications.
- Retailers:Pharmacy and supermarket buyers control shelf-space allocation and category management decisions that determine brand visibility in Germany's pharmacy-dominant distribution network.
Volume concentration rests with Healthcare Providers. Digital channel migration is expanding fastest among Individuals.
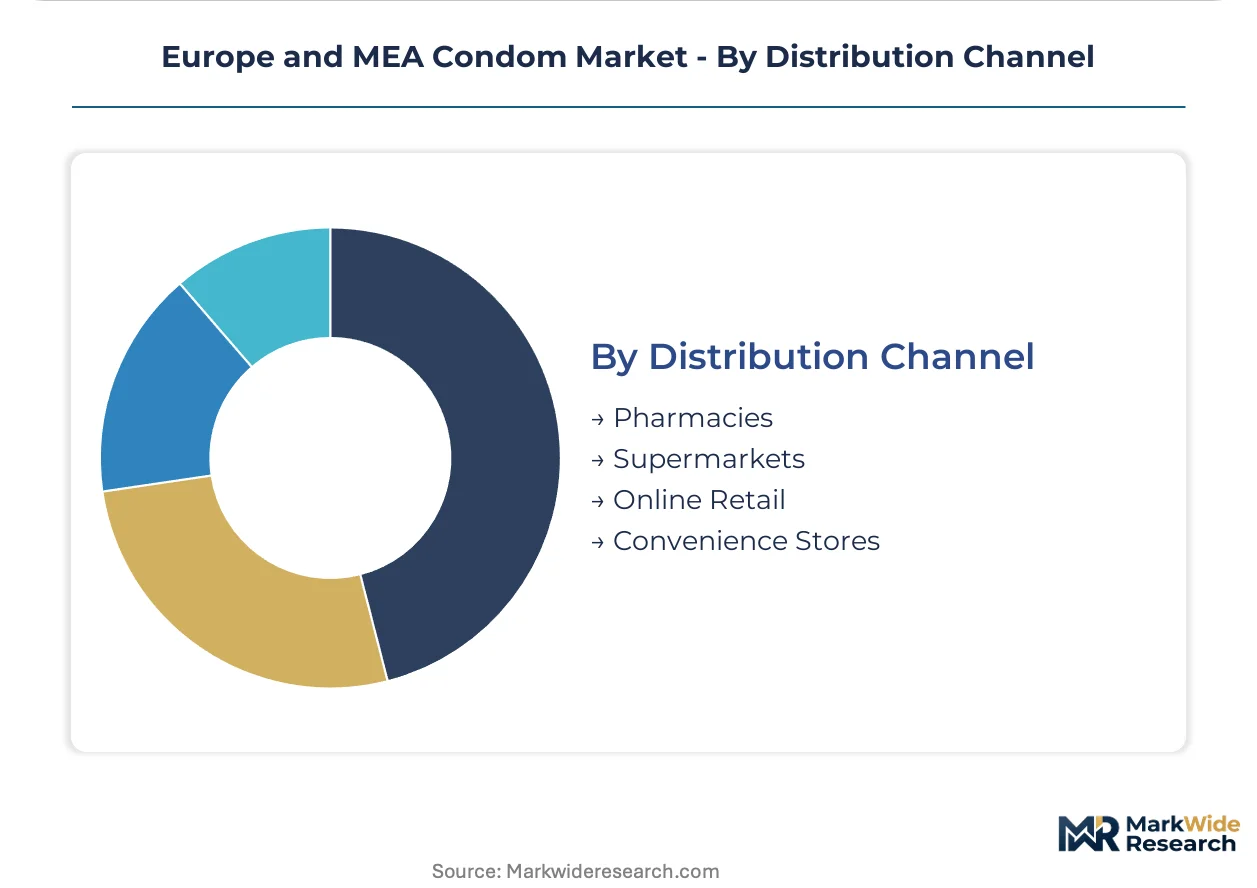
Distribution Channel:
Route-to-market structures fragment between professional healthcare channels and consumer retail formats, with digital infrastructure maturity varying sharply across geographies.
- Pharmacies:Professional channel credibility in Germany and France enables premium positioning for clinically positioned synthetic polymer variants, with ANSM and BfArM national implementations creating staggered compliance deadlines that fragment product launch sequencing.
- Supermarkets:Mass retail shelf presence sustains volume leadership for established manufacturers serving Western European consumer markets, with Reckitt Benckiser leveraging extensive distribution networks.
- Online Retail:Digital pharmacy platforms and app-based ordering with unmarked delivery packaging are displacing traditional retail across Gulf Cooperation Council urban centers where smartphone penetration exceeds 95% and payment infrastructure supports discreet transactions.
- Convenience Stores:Impulse-oriented small-format retail captures emergency purchasing occasions, though limited SKU depth constrains premium product visibility.
Established volume flows through Pharmacies. Channel expansion is climbing the fastest in Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai's digital commerce corridor is redefining condom distribution across Gulf Cooperation Council states, while Johannesburg anchors public health procurement volumes for Southern Africa.
Germany
Pharmacy-dominant distribution networks in Berlin and Munich concentrate demand for polyisoprene alternatives serving latex-sensitive consumers. The Federal Institute for Drugs and Medical Devices enforces staggered EU MDR compliance timelines that filter smaller manufacturers from professional channels. Baden-Württemberg's chemical clusters supply specialized polymer formulations to domestic producers.
France
Paris and Lyon public clinics are expanding non-latex procurement under EU Green Deal sustainability targets. The National Agency for Food, Environmental and Occupational Health Safety applies supplementary French-language labeling requirements that extend registration timelines. Île-de-France's healthcare procurement consortiums negotiate centralized contracts for synthetic polymer variants.
South Africa
Johannesburg and Cape Town public health clinics drive bulk procurement through national HIV prevention programs. The South African Health Products Regulatory Authority mandates import certification standards that align with WHO prequalification pathways. Gauteng province's distribution hubs handle commodity flows to regional clinics across nine provinces.
United Arab Emirates
Dubai and Abu Dhabi consumers are migrating to app-based ordering with unmarked delivery packaging. The Ministry of Health and Prevention oversees medical device registration while digital payment infrastructure matures. Dubai Internet City's e-commerce platforms serve as regional launch points for subscription-based intimate health services.
United Kingdom
London and Manchester retail pharmacies sustain premium positioning for clinically marketed synthetic alternatives. The Medicines and Healthcare products Regulatory Agency implements EU MDR technical documentation requirements post-Brexit. Southeast England's logistics corridors facilitate cross-channel distribution to continental European markets.
Europe and MEA Condom Market Key Industry Players
Premium-margin players sit above commodity-margin players across material formulation and channel certification dimensions. The vendor base clusters around three strategic archetypes: integrated natural rubber processors with plantation supply control, synthetic polymer specialists targeting latex-sensitive segments, and diversified consumer health conglomerates leveraging retail shelf dominance. Competitive moves concentrate on dual-formulation manufacturing capacity and regulatory affairs capability building.
Within the integrated supply tier, Karex Berhad and Fuji Latex Co., Ltd. represent plantation-anchored production models. Reckitt Benckiser Group plc exemplifies the consumer health conglomerate archetype with pharmacy and supermarket channel penetration. These three entities occupy distinct competitive positions: Malaysian and Japanese integrated processors secure raw material supply chains, while the UK-based conglomerate leverages brand equity and retail relationships across Western European markets.
| Leading Market Players |
|---|
| Reckitt Benckiser Group plc |
| Church & Dwight Co., Inc. |
| LifeStyles Healthcare Pte. Ltd. |
| Karex Berhad |
| Pasante Healthcare Ltd. |
| Fuji Latex Co., Ltd. |
| Ansell Ltd |
| Sagami Rubber Industries |
| Okamoto Industries |
| Others |
Cost & Logistics Intelligence
EU Green Deal chemical sustainability targets gate qualified supply and premium-tier pricing access for condom manufacturers across European and MEA markets. Procurement officers in French public clinics and German pharmacy chains now demand documented low-carbon manufacturing processes, filtering out suppliers unable to substantiate environmental claims.
Pricing Analysis
Value-based pricing anchored to biocompatibility certification and latex sensitivity outcomes stratifies the Europe and MEA condom market. Three-tier pricing structure across premium polyisoprene, standard latex, and economy bulk procurement separates clinical-grade synthetic formulations from commodity public health contracts. Price differentiation hinges on EU MDR Class IIa documentation completeness and brand equity in pharmacy channels. Cost compression in MEA bulk procurement intensifies as Southeast Asian natural rubber volatility transmits to raw material costs. Healthcare providers in South Africa's HIV programs exhibit highest price sensitivity, while German pharmacy consumers demonstrate lowest sensitivity to premium positioning.
Supply Chain Analysis
EU MDR and REACH qualification requirements filter supplier access, concentrating certified manufacturing capacity among integrated natural rubber processors and synthetic polymer specialists. Malaysia, Thailand, and Japan anchor upstream supply through plantation-controlled latex production and advanced polymer formulation capabilities. Raw material flows draw from Southeast Asian rubber plantations, German chemical clusters for polyisoprene precursors, and UAE logistics hubs for Gulf distribution. Single-source vulnerability concentrates in natural rubber supply chains exposed to climate-driven plantation disruptions. Distribution runs through Germany's pharmacy-dominant professional network, UAE digital retail platforms, and South African public health procurement corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe and MEA condom market operates as a vertical-integration race where plantation supply control and dual-formulation manufacturing capacity determine competitive survival. Players are pursuing backward integration into Southeast Asian rubber sourcing to secure raw material cost stability.
For Market Incumbents: Hedge against synthetic polymer displacement by securing segregated production lines for both latex and non-latex formulations. Invest in EU MDR technical documentation capabilities before staggered national deadlines fragment market access. Karex Berhad's plantation-anchored model and Reckitt Benckiser's pharmacy shelf dominance represent defensive templates against emerging synthetic specialists.
For New Entrants and Emerging Players: Begin with UAE digital retail infrastructure where app-based ordering and discreet delivery preferences create white-space expansion territory. Target 25-40 year old demographics in Dubai and Riyadh through telehealth-integrated subscription models. Leverage WHO prequalification pathways to access donor-funded MEA public health procurement channels.
For Investors and Strategic Acquirers: ANSM's supplementary French-language labeling requirements extending registration timelines is the leading indicator that regulatory affairs capacity scarcity will concentrate acquisition value in compliant mid-tier manufacturers. Synthetic polymer specialists with established EU MDR documentation and Gulf digital channel partnerships represent priority target archetypes. Watch for EMA-mandated biocompatibility testing bottlenecks as the inflection signal for laboratory service provider consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Formulation Manufacturing Scale-Up | Segregated latex and non-latex production lines enable access to both MEA bulk procurement and European premium pharmacy channels. |
| EU MDR Certification Investment | Class IIa biocompatibility documentation opens Germany's BfArM-regulated pharmacy distribution network to synthetic polymer entrants. |
| Backward Integration into Plantation Supply | Captive Southeast Asian rubber sourcing insulates margin structures from commodity price volatility affecting latex-dominant producers. |
| Digital Pharmacy Platform Partnership | UAE Ministry of Health and Prevention-registered e-commerce integrations capture Gulf Cooperation Council subscription revenue streams. |
| WHO Prequalification Alignment | International procurement standard compliance unlocks donor-funded South African HIV prevention program volumes. |
Research Approach
Trade databases, EU MDR submission registries, and WHO prequalification listings formed the secondary backbone of this analysis. Primary interviews with regulatory affairs directors at condom manufacturers, procurement managers at French public health consortiums, pharmacy category buyers in Germany, and UAE digital platform operators validated supply chain and pricing assumptions. Bottom-up volume modeling across material type, distribution channel, and end-user segments was cross-checked against top-down market sizing from customs records and healthcare procurement disclosures.
Historical trendline analysis of natural rubber price indices, EU MDR implementation timelines, and Gulf digital payment penetration rates informed projection assumptions across the modeling period. Segmentation dimensions modeled include material composition, application type, end-user archetype, and distribution channel maturity. CAGRs were derived from elasticity-adjusted demand curves incorporating synthetic polymer substitution rates and public health program budget trajectories. Forecast inputs included REACH chemical restriction evolution and Extended Producer Responsibility framework adoption patterns.
Natural rubber supply disruptions, EU MDR deadline acceleration, and MEA currency volatility are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding procurement policy continuity and regulatory implementation pacing. A model refresh is warranted upon material change in EU Green Deal chemical sustainability enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Grooming Products
Global Aligner Sheet Market
Personal Grooming Products
Global Mosquito Repellent Products Market
Personal Grooming Products
Shavers Market
Personal Grooming Products
Feminine Hygiene Products Market
Personal Grooming Products
US Percussion Massage Gun Market
Personal Grooming Products
Tattoo Accessories Market
Personal Grooming Products
Infant Mosquito Repellent Market
Personal Grooming Products
Insoles Market
Personal Grooming Products
Europe Electric Toothbrush Market
Personal Grooming Products
Epilators Market
Personal Grooming Products
Nose & Ear Hair Trimmers Market
Personal Grooming Products
Smart Water Bottle Market
Personal Grooming Products
Toothpaste Tablet Market
Personal Grooming Products
Portable Massage Devices Market
Personal Grooming Products
Global Tampons Market
Personal Grooming Products
Smart Bathroom Scale Market