
 Global Organic and Natural Feminine Care Market | 2026-2036
Global Organic and Natural Feminine Care Market Size, Share, and Industry Trends Forecast 2026-2036
Global Organic and Natural Feminine Care Market Outlook
EU REACH is decoupling legacy formulations from shelf eligibility across European retail channels. Procter & Gamble leverages its global distribution infrastructure to sustain conventional brand loyalty while navigating reformulation timelines. Natracare anchors its competitive position through certified organic cotton supply chains and transparent ingredient disclosure. Essity AB differentiates via vertical control over sustainable fiber sourcing and biodegradable product development.
Organic and natural feminine care encompasses menstrual hygiene products manufactured without synthetic pesticides, chlorine bleach, or petrochemical-derived absorbents, typically utilizing certified organic cotton or plant-based cellulose with compostability targets exceeding 90% in controlled environments. The primary commercial purpose centers on reducing dermal exposure to endocrine-disrupting chemicals while addressing waste accumulation from conventional plastic-based disposables. Sanitary pads and panty liners occupy the dominant revenue position given higher per-unit consumption frequency and established retail placement, though menstrual cups are recording the fastest volume expansion among reusable alternatives. Organic cotton as a material category commands premium positioning due to GOTS certification requirements and constrained agricultural supply, while online retail channels are capturing disproportionate growth through subscription models and direct-to-consumer transparency.
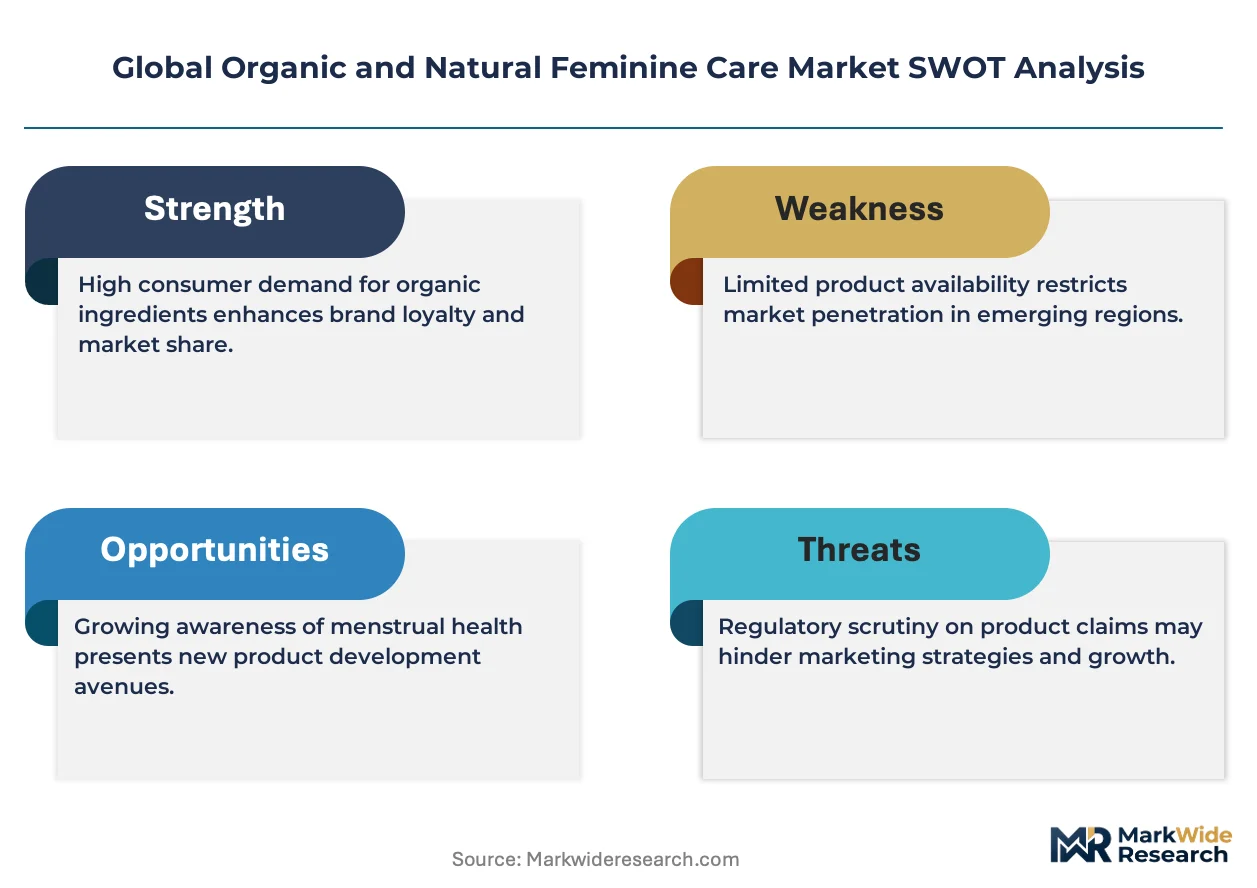
EMA cosmetic ingredient assessments, FDA Center for Drug Evaluation and Research oversight of medicated claims, and ISO 10993 biocompatibility protocols collectively establish the multi-layered compliance architecture governing product entry and consumer trust. These frameworks elevate testing expenditures for new entrants while rewarding incumbents with established quality management systems and regulatory dossiers. Stakeholders must monitor evolving state-level ingredient disclosure mandates and compostability certification standards as the next determinants of competitive access and pricing power.
Market Dynamics
REACH compliance deadlines in Europe are forcing simultaneous reformulation across legacy product portfolios, compressing development timelines while certified organic cotton supply chains struggle to scale output fast enough to meet repositioned demand.
Growth Catalysts
- EU REACH chemical restrictions:Banned substances in conventional absorbents are redirecting formulation investment toward plant-based alternatives. Manufacturers face 2026-2028 phase-out windows.
- Gen Z dermatological sensitivity:Younger buyers prioritize endocrine-disruptor avoidance, creating pull-through for GOTS-certified products in Germany and Japan.
- Compostability infrastructure expansion:Industrial composting facilities in the Netherlands and California now accept certified biodegradable pads, closing the waste-loop value proposition.
Market Restraints
- Organic cotton acreage constraints:GOTS-certified fiber supply concentrates in Turkey and India, creating input bottlenecks when demand spikes.
- FDA medicated-claim friction:Products with herbal additives face Center for Drug Evaluation and Research scrutiny, extending approval timelines versus conventional positioning.
- Menstrual cup substitution:Reusable silicone alternatives capture cost-conscious buyers, limiting repeat-purchase revenue for disposable organic lines.
Strategic Opportunities
- Brazil ANVISA pathway opening:Latin America's largest market lacks mature organic feminine care penetration; early entrants capture shelf space before local formulation standards harden.
- Subscription-direct channel:Recurring delivery models bypass retail slotting fees and build ingredient-transparency relationships with millennial subscribers.
- EU Green Deal public procurement:Government healthcare facilities across France and Sweden now mandate sustainable-period-product tenders, creating institutional volume anchors.
Industry Challenges
- ISO 10993 biocompatibility testing backlog:Third-party laboratories face 14-18 month queues for intimate-contact device clearance, delaying new product launches.
- Legacy ERP integration:Batch-level organic certification tracking requires supply-chain software upgrades that mid-tier manufacturers struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Organic and Natural Feminine Care Market |
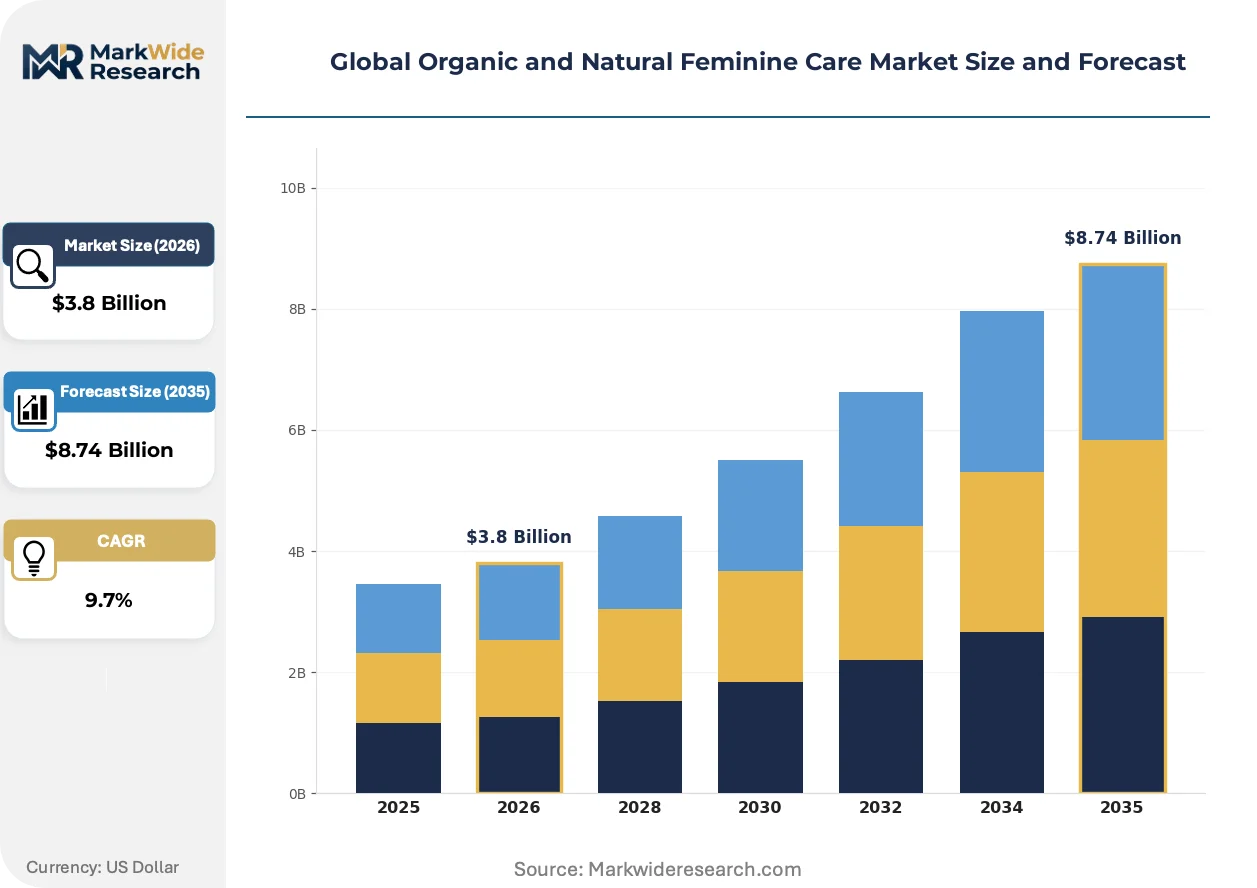
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sanitary Pads, Tampons, Menstrual Cups, Panty Liners Material: Cotton, Bamboo, Organic Cotton, Biodegradable Materials Distribution Channel: Online Retail, Supermarkets, Health Stores, Pharmacies End User: Adolescents, Adults, Seniors, Eco-conscious Consumers |
| Companies Covered | Unilever plc, The Honest Company, Procter & Gamble, Ontex International, Seventh Generation, Unicharm Corporation, Natracare, Essity AB, Kimberly-Clark Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Organic and Natural Feminine Care Market Strategic Shifts
Formulation transparency and material traceability are compressing competitive differentiation cycles, with certification standards now functioning as both market-entry barriers and brand-equity accelerators.
Plant-based absorbent cores derived from agricultural residues are modularizing product architecture. European manufacturers adopt these materials fastest, enabling component substitution without full line redesign. This modularity is compressing reformulation costs when regulators add new restricted substances.
EMA cosmetic ingredient assessments now require expanded dermal-sensitization data for intimate-care applications. Manufacturers must submit chronic-exposure studies that conventional products never faced. Premium organic lines in Germany and France absorb these costs more easily than economy-positioned competitors.
Ingredient-disclosure mandates from California's Department of Public Health are reshaping packaging requirements. Brands now list all components down to 0.01% concentration, replacing vague "natural fragrance" claims. This transparency pivot is most visible in US direct-to-consumer channels where buyers compare certificates of analysis before subscribing.
Global Organic and Natural Feminine Care Market Segmentation
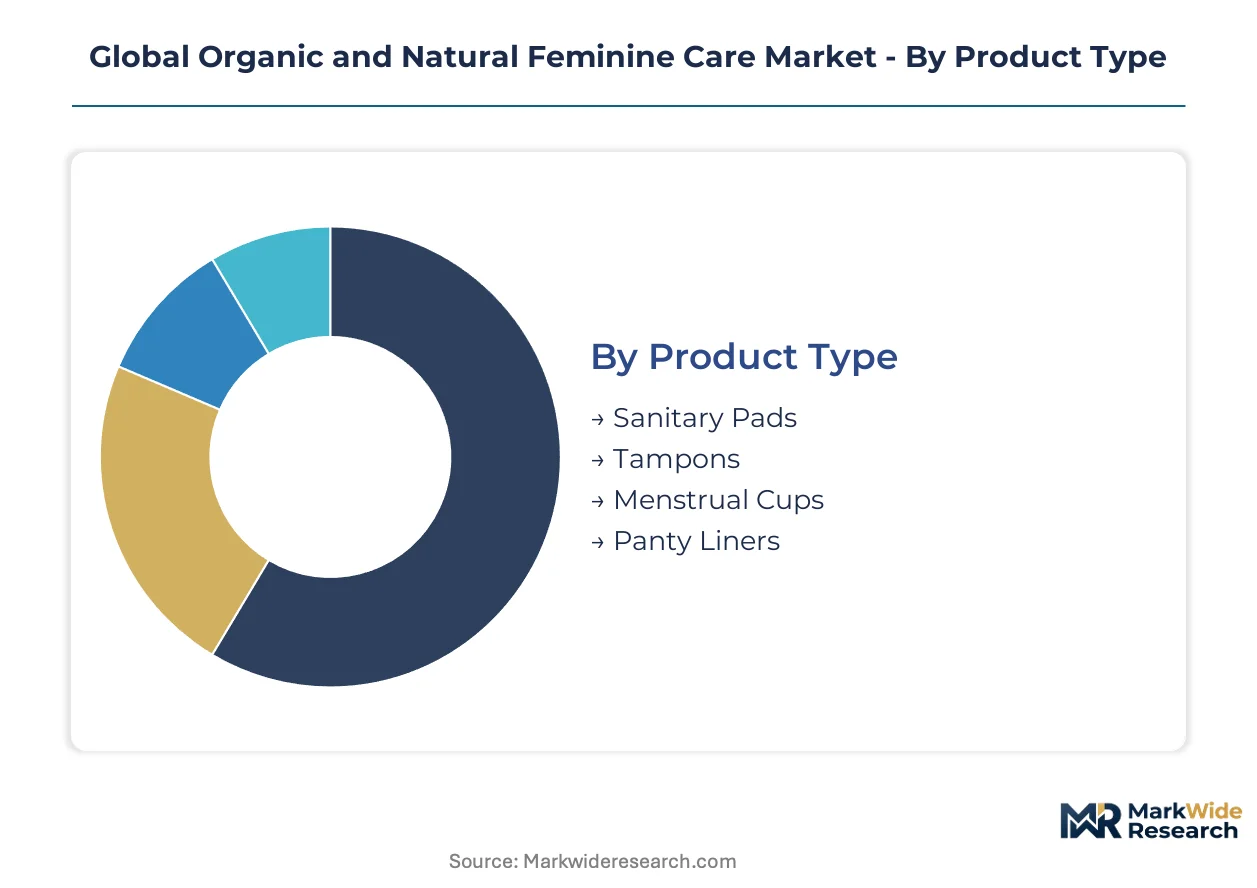
Segmentation in organic feminine care reveals how certification requirements, material sourcing constraints, and channel economics create divergent margin profiles across product categories. Understanding these divides enables manufacturers to allocate R&D investment toward segments where regulatory compliance generates sustainable pricing power rather than commoditization pressure.
Product Type:
GOTS certification and ISO 10993 biocompatibility protocols impose tiered compliance burdens: disposables require batch-level organic fiber tracking, while reusables face medical-device classification in multiple jurisdictions.
- Sanitary Pads:Multi-layer construction utilizing organic cotton topsheets and plant-based absorbent cores dominates revenue concentration. Demand clusters in Germany and California where industrial composting infrastructure validates biodegradability claims and municipal procurement mandates favor certified products.
- Tampons:Internal-use classification triggers stringent FDA Center for Drug Evaluation and Research oversight for medicated variants and EMA cosmetic ingredient assessments for standard formulations. Organic cotton sourcing from Turkey concentrates supply risk during harvest volatility.
- Menstrual Cups:Medical-grade silicone construction bypasses agricultural supply constraints while capturing cost-conscious buyers through multi-year reuse cycles.
- Panty Liners:Lower absorbency requirements enable thinner profiles with reduced organic cotton content per unit, compressing material costs for daily-use positioning.
Leading the category by volume: Sanitary Pads. Growing fastest: Menstrual Cups.
Material:
Input certification tiers stratify manufacturing cost structures, with agricultural-origin materials carrying GOTS traceability premiums against processed alternatives.
- Organic Cotton:GOTS-certified fiber from Turkey and India commands price premiums reflecting constrained acreage and multi-year conversion timelines for conventional farmland. EU REACH chemical restrictions amplify demand displacement from synthetic alternatives.
- Bamboo:Rapid-regrowth grass species enables faster supply scaling without organic certification delays, though processing into rayon fibers requires chemical disclosure under California Department of Public Health mandates.
- Cotton:Conventional cultivation permits higher yields and lower unit costs, though pesticide residue concerns limit penetration in dermatologically sensitive consumer segments concentrated in Japan.
- Biodegradable Materials:Agricultural residue-derived absorbent cores from European manufacturers enable modular component substitution when regulators expand restricted substance lists.
Organic Cotton captures the steepest expansion trajectory as REACH phase-outs accelerate. Cotton maintains volume leadership through cost accessibility.
Distribution Channel:
Channel selection determines transparency requirements and customer acquisition economics, with direct relationships enabling ingredient disclosure that retail intermediaries obscure.
- Online Retail:Subscription models bypass slotting fees while building certificate-of-analysis transparency with millennial subscribers. California and Netherlands consumers demonstrate highest conversion rates for recurring delivery.
- Supermarkets:Mass-market placement requires formulation compromises to hit price points, limiting organic certification penetration to premium-tier SKUs.
- Health Stores:Curated assortments favor GOTS and compostability certifications, with staff education driving conversion among endocrine-disruptor-avoidant buyers.
- Pharmacies:Medicated product positioning triggers FDA Center for Drug Evaluation and Research oversight, extending approval timelines versus conventional channel placement.
Online Retail gains share fastest through subscription stickiness. Supermarkets retain volume dominance via impulse purchase accessibility.
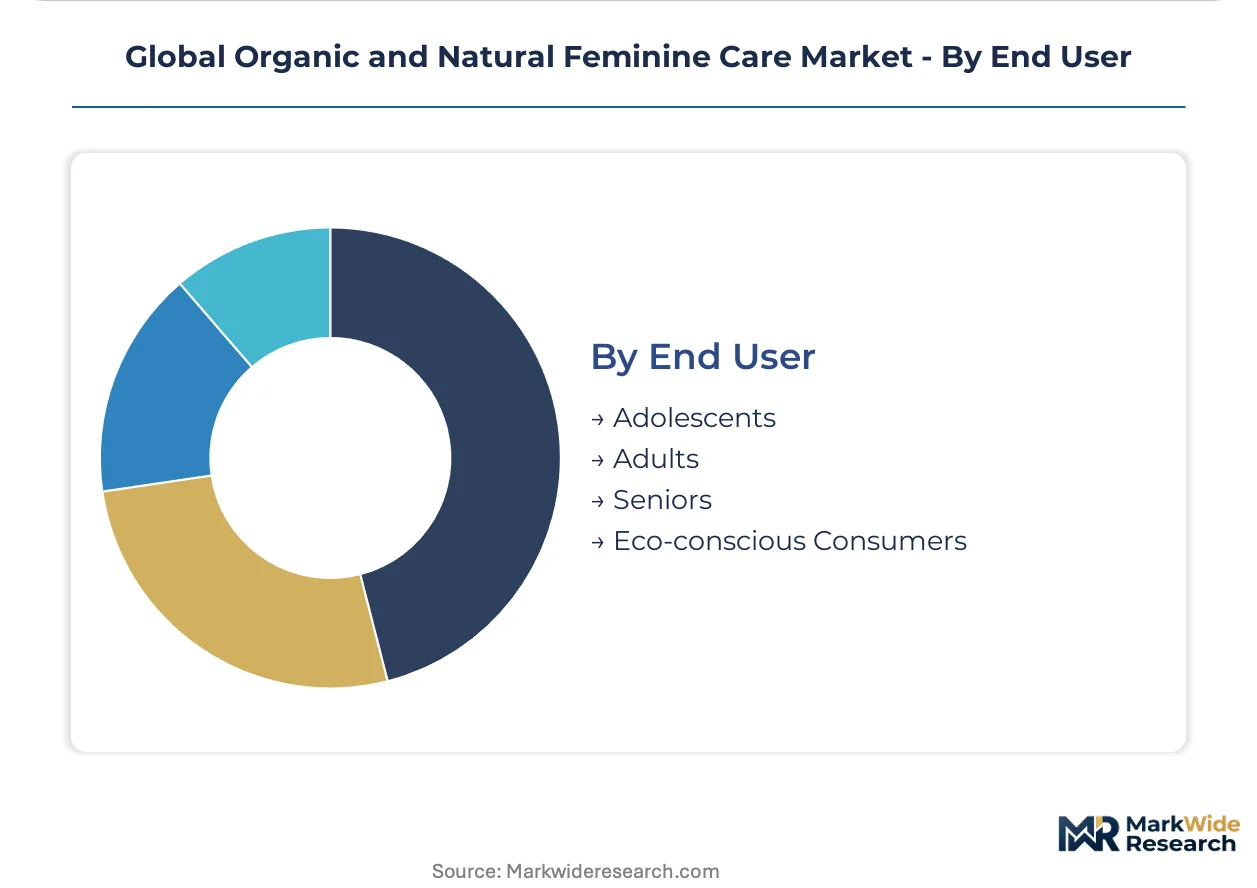
End User:
Life-stage and values-based segmentation determines sensitivity to price premiums and willingness to navigate certification complexity.
- Eco-conscious Consumers:Values-driven purchasing prioritizes compostability certifications and supply chain transparency, accepting price multiples for verified organic positioning concentrated in German and Swedish urban markets.
- Adolescents:First-product selection occasions create brand loyalty anchors, with parental purchasing emphasizing dermatological safety claims and ingredient disclosure.
- Adults:Established consumption patterns show highest price elasticity, driving channel migration toward subscription models as convenience premiums offset product premiums.
- Seniors:Light incontinence overlap expands addressable market, though conventional product familiarity limits organic conversion without physician recommendation.
Adults generate the highest absolute volume through purchase frequency. Eco-conscious Consumers exhibit the steepest per-capita spending trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Turkey's Aegean Region concentrate GOTS-certified organic cotton ginning capacity, drawing EU-bound feminine care manufacturers seeking REACH-compliant fiber traceability. Tax incentives in India's Telangana State accelerate certified organic acreage conversion for export-oriented absorbents.
United States
California's Department of Public Health mandates ingredient disclosure down to 0.01% concentration, reshaping packaging requirements for direct-to-consumer brands. Industrial composting facilities in the Netherlands now accept certified biodegradable pads, validating waste-loop claims for US exporters targeting European sustainability standards. Subscription models concentrate in San Francisco and Los Angeles metro areas where millennial buyers prioritize certificate-of-analysis transparency.
Germany
ECHA REACH phase-out windows for restricted absorbent chemicals compress reformulation timelines through 2026-2028. The EU Green Deal public procurement framework mandates sustainable-period-product tenders across French and Swedish government healthcare facilities, creating institutional volume anchors for German manufacturers. Berlin and Hamburg anchor retail placement for GOTS-certified premium lines serving endocrine-disruptor-avoidant consumers.
Japan
METI guidelines on intimate care product safety elevate formulation standards for dermal-sensitization testing. PMDA oversight of medicated claims extends approval timelines for herbal-additive products versus conventional positioning. Tokyo and Osaka metropolitan areas concentrate dermatologically sensitive consumer segments driving demand for pesticide-residue-free cotton alternatives.
Brazil
ANVISA regulatory pathways for organic feminine care remain underdeveloped, creating first-mover shelf space advantages before local formulation standards harden. São Paulo and Rio de Janeiro retail channels show accelerating millennial adoption of chemical-free menstrual products. Import tariff structures currently favor early entrants establishing local distribution partnerships.
India
FSSAI and CDSCO frameworks govern intimate care product safety while BIS standards address textile contact applications. Telangana and Maharashtra concentrate GOTS-certified organic cotton ginning capacity serving EU-bound export contracts. Bangalore and Mumbai anchor direct-to-consumer subscription growth among urban professional women prioritizing ingredient transparency.
Global Organic and Natural Feminine Care Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Consumer goods multinationals leverage global distribution infrastructure to sustain conventional brand loyalty while navigating reformulation timelines. Pure-play organic specialists anchor competitive positions through certified supply chains and transparent ingredient disclosure. Vertical control over sustainable fiber sourcing and biodegradable product development represents a dominant competitive move, alongside subscription-direct channel investments that bypass retail slotting fees.
Within the pure-play specialist tier, Natracare and Essity AB exemplify archetypes built on GOTS certification and supply chain transparency. Procter & Gamble occupies a position representing diversified conglomerate adaptation to REACH compliance pressures. These three entities collectively illustrate the strategic divergence between legacy portfolio reformulation and native organic positioning.
| Leading Market Players |
|---|
| Unilever plc |
| The Honest Company |
| Procter & Gamble |
| Ontex International |
| Seventh Generation |
| Unicharm Corporation |
| Natracare |
| Essity AB |
| Kimberly-Clark Corporation |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal public procurement mandates in France and Sweden are pulling certified organic cotton supply toward institutional tenders, compressing spot availability for retail channels and amplifying price premiums for GOTS-verified fiber.
Pricing Analysis
Short lead-time premiums dominate spot purchasing for GOTS-certified organic cotton, with Turkish ginners commanding 15-20% markups over contract offtake. Three-tier pricing structure across premium certified, standard natural, and conventional economy levels separates buyers by dermatological sensitivity and compostability requirements. Pricing pressure stems from menstrual cup substitution capturing cost-conscious volume and limiting repeat-purchase premiums for disposable lines. Eco-conscious consumers in German urban markets exhibit lowest price elasticity, while adolescents via parental purchasing show highest sensitivity to per-unit cost multiples.
Supply Chain Analysis
Direct-to-consumer subscription channels handle millennial demand clusters in California and Netherlands, bypassing retail slotting fees that compress margins for mass-market placement. Geographic supply concentrates in Turkey and India for GOTS-certified organic cotton ginning, with Telangana State tax incentives accelerating certified acreage conversion. Raw material dependencies center on agricultural fiber traceability, biodegradable absorbent core resins, and medical-grade silicone for reusable alternatives. Single-source vulnerability runs through Turkish organic cotton harvest volatility, where climate-driven yield fluctuations transmit directly to formulation costs. Distribution runs through online retail fastest, though supermarkets retain volume dominance via impulse accessibility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GOTS-certified organic cotton acreage constraints prop pricing power for incumbent holders of multi-year supply contracts, creating a supply-constrained market structure favoring early capacity commitments.
For Market Incumbents: To counter menstrual cup substitution eroding disposable repeat-purchase revenue, lock multi-year GOTS supply contracts in Turkey's Aegean Region before acreage conversion timelines lengthen. Backward integration into certified ginning capacity defends margin position against spot fiber volatility, while ISO 10993 biocompatibility dossier maintenance creates regulatory moats delaying new entrant launches. For New Entrants and Emerging Players: Subscription-direct channel partners in São Paulo and Rio de Janeiro offer lowest competitive density for chemical-free positioning before ANVISA formulation standards harden. Brazil's underdeveloped organic feminine care penetration presents white-space capture opportunity, with millennial adoption curves mirroring early-phase California demand. Target institutional procurement tenders under EU Green Deal frameworks in Sweden and France for volume anchors that fund retail expansion. For Investors and Strategic Acquirers: The window for entry favors pure-play specialists with captive GOTS supply chains and established ISO 10993 clearance timelines. Long-term viability hinges on certification asset durability rather than brand equity alone, given regulatory escalation across EMA and FDA jurisdictions. Watch compostability infrastructure buildout in Netherlands and California industrial facilities as inflection signal for biodegradable premium realization.| Strategic Initiative | Industry Significance |
|---|---|
| GOTS Certification Investment | REACH compliance deadlines in Europe decouple non-certified formulations from shelf eligibility across retail channels. |
| Subscription-Direct Channel Launch | Recurring delivery models bypass supermarket slotting fees while building certificate-of-analysis transparency with millennial subscribers. |
| Backward Integration into Organic Cotton Ginning | Turkey's Aegean Region tax incentives reward captive supply control amid constrained GOTS-certified acreage expansion. |
| Biodegradable Product Line Extension | Industrial composting facilities in Netherlands and California validate waste-loop claims for premium positioning. |
| ANVISA Regulatory Pathway Establishment | Early entrant shelf space capture in São Paulo precedes local formulation standard hardening. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across supply chain directors at organic cotton ginners, brand managers at pure-play feminine care specialists, procurement leads at EU healthcare facilities, and certification auditors at GOTS-accredited bodies. FDA Center for Drug Evaluation and Research medicated-claim submissions, ECHA REACH restriction updates, and ISO 10993 biocompatibility laboratory queues provided regulatory trajectory inputs. Bottom-up SKU-level volume builds triangulated against top-down category spend estimates from retail audit databases.
Reconciliation of shipment data, import manifests, and subscription platform disclosures informed volume and value outputs across the analysis window. Segmentation dimensions modeled include product type, material certification tier, distribution channel, and end-user values orientation, with CAGRs derived from slope-consistency checks against historical regulatory phase-out patterns. Organic cotton acreage conversion timelines and compostability infrastructure buildout curves served as industry-specific forecast anchors.
Several conditions sit outside the modeled scope, including ANVISA regulatory finalization timelines in Brazil and FDA guidance evolution on intimate care product safety. Forecasts reflect documented assumptions regarding GOTS supply elasticity and REACH enforcement intensity. Practitioners should monitor EMA cosmetic ingredient assessment expansion and state-level ingredient disclosure mandate proliferation for early signals of compliance cost escalation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Grooming Products
Antibacterial Soap Market
Personal Grooming Products
Europe and MEA Condom Market
Personal Grooming Products
AI Toothbrush Market
Personal Grooming Products
Baby Grooming Kits Market
Personal Grooming Products
Global Sex Toys Market
Personal Grooming Products
Toothbrush Market
Personal Grooming Products
Razor Market
Personal Grooming Products
Disposable Shower Caps Market
Personal Grooming Products
Electric Hair Clipper and Trimmer Market
Personal Grooming Products
Electrical Neck Warmer Market
Personal Grooming Products
Heated Razor Starter Kit Market
Personal Grooming Products
Razor Blade Market
Personal Grooming Products
Hand Hygienic Product Market
Personal Grooming Products
Global Aligner Sheet Market
Personal Grooming Products
Massage Fascia Gun Market
Personal Grooming Products
Latin America Hand Soap Market