
 Baby Grooming Kits Market | 2026-2036
Baby Grooming Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Baby Grooming Kits Market Insights
A capital-intensity divergence between mass-market manufacturers and premium specialists is reorganizing competitive dynamics in baby grooming kits. Philips Avent leverages integrated electronics capabilities to dominate digital thermometer segments within bundled offerings. Pigeon Corporation anchors its position through material science expertise in silicone-based grooming tools. Fridababy differentiates via clinical-grade positioning and healthcare channel partnerships.
Baby grooming kits comprise curated collections of infant hygiene instruments—nail clippers, hair brushes, thermometers, and scissors—typically manufactured from medical-grade stainless steel, BPA-free plastics, or food-safe silicone with rounded-tip safety engineering. These products serve parents, guardians, and childcare providers seeking consolidated, travel-ready solutions for routine infant care. Nail clippers and thermometers command the largest revenue share within product type segments due to replacement frequency and safety-critical design requirements. Stainless steel and silicone materials capture expanding margin pools as consumers prioritize durability and hypoallergenic properties over basic plastic alternatives. Boxed sets and travel kits represent the fastest-growing packaging formats, reflecting channel shifts toward gift-registry and e-commerce subscription models.
FDA oversight of infant medical devices and CE marking under EU MDR govern thermometer accuracy claims and electrical safety standards, compelling manufacturers to maintain dual-certification portfolios. REACH compliance and EU Green Deal sustainability mandates increasingly restrict phthalate content in plastic components while pushing bamboo and bio-based material adoption. Stakeholders must monitor evolving state-level chemical disclosure laws in the US and emerging extended producer responsibility frameworks in Europe to anticipate reformulation costs and packaging redesign cycles.
Market Dynamics
Capital-intensity divergence between mass-market contract manufacturers and premium specialists is reorganizing competitive dynamics in baby grooming kits, with integrated electronics capabilities becoming the decisive capability threshold for thermometer segments.
Growth Catalysts
- Dual-child policy effects:China's revised family planning regulations sustain elevated birth rates in tier-1 cities, concentrating demand for bundled premium kits among first-time urban parents.
- FDA medical device oversight:Infant thermometer accuracy requirements under 21 CFR Part 880 create compliance barriers that favor established manufacturers with dual-certification portfolios.
- Silicone material science:Food-grade silicone formulations with rounded-tip safety engineering are capturing margin pools as hypoallergenic properties displace basic plastic alternatives.
Market Restraints
- Medical-grade stainless steel supply concentration:Specialty steel mills in Germany and Japan control premium alloy supply, exposing kit assemblers to input cost volatility and extended lead times.
- REACH phthalate restrictions:ECHA's evolving substance restrictions under EU chemicals policy compel reformulation cycles that compress margins on plastic-component manufacturers.
- Digital thermometer substitution:Smartphone-integrated temperature monitoring applications threaten standalone thermometer unit sales within bundled kit configurations.
Strategic Opportunities
- Extended producer responsibility frameworks:EU packaging waste directives incentivize bamboo and bio-based material adoption, opening premium positioning for sustainable kit designers.
- Healthcare channel partnerships:Clinical-grade positioning through hospital discharge gift programs creates sticky demand among new parents seeking trusted recommendations.
- E-commerce subscription models:Direct-to-consumer replenishment services for replacement nail clippers and brush heads capture recurring revenue from sleep-deprived urban households.
Industry Challenges
- Dual-certification timeline compression:Simultaneous FDA 510(k) clearance and CE marking under EU MDR extends product launch cycles by 8-14 months for thermometer-integrated kits.
- Electronics integration complexity:Bluetooth-enabled thermometer modules require firmware validation protocols that strain traditional grooming tool manufacturers without captive semiconductor expertise.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baby Grooming Kits Market |
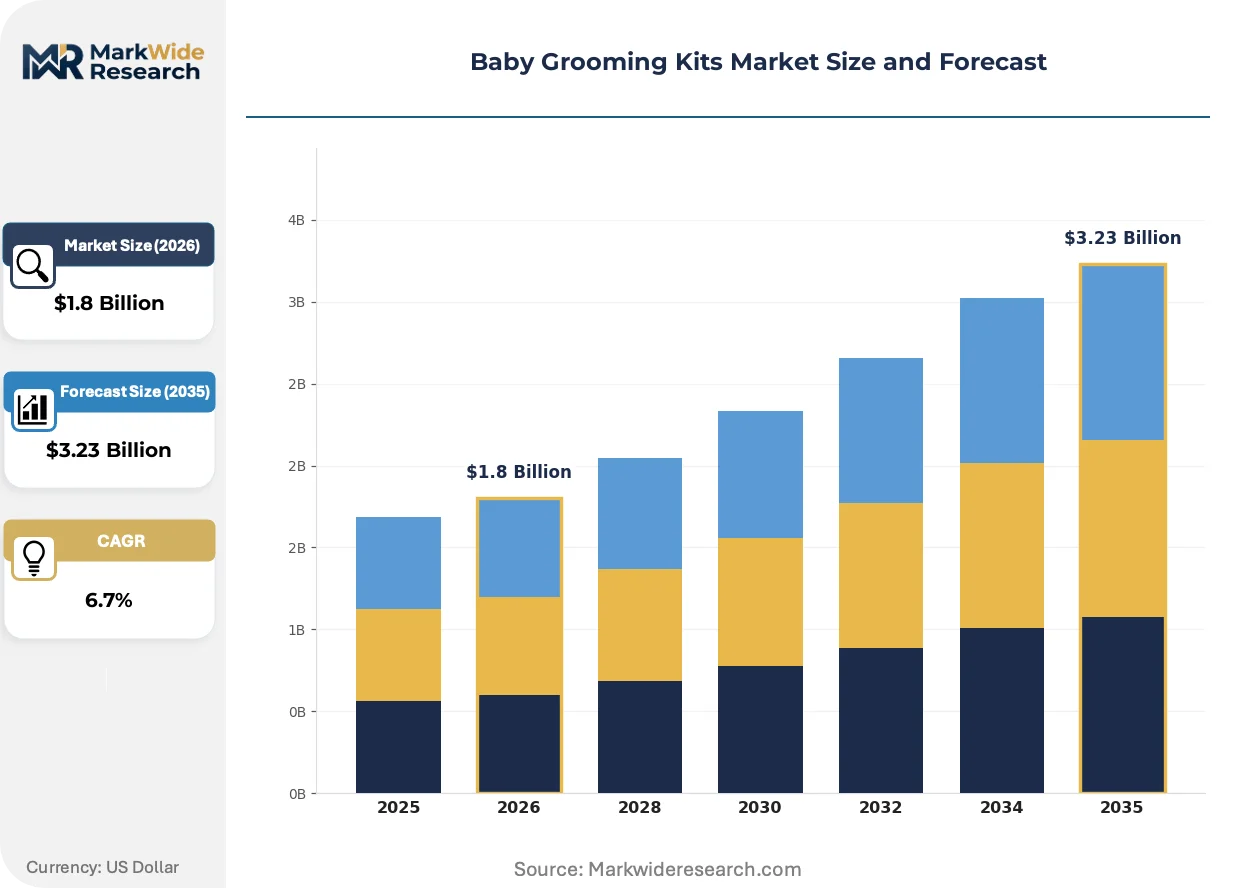
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nail Clippers, Hair Brushes, Thermometers, Scissors Material: Plastic, Stainless Steel, Silicone, Bamboo Packaging Type: Boxed Sets, Travel Kits, Pouches, Cases End User: Parents, Guardians, Childcare Providers, Hospitals |
| Companies Covered | Philips Avent, Summer Infant, Pigeon Corporation, Fridababy, Fisher-Price, Safety 1st, Chicco, The First Years, Munchkin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baby Grooming Kits Market Trends and Innovations
Material substitution and regulatory stringency are converging to reshape product architecture in baby grooming, with sustainability mandates and digital integration demanding simultaneous capability upgrades from incumbent suppliers.
Silicone-based grooming tools with integrated antimicrobial additives are supplanting conventional plastic nail files and brush bristles in premium kit configurations. First-time parents in Shanghai, London, and New York metropolitan areas are specifying these materials in gift registry selections at accelerating rates. This material transition is compressing margins for injection-molders without silicone processing capabilities while rewarding chemical specialists with medical-grade formulation expertise.
EU Green Deal sustainability mandates and REACH chemical disclosure requirements are forcing systematic phthalate elimination from plastic kit components. Manufacturers serving European distribution channels must now maintain dual material streams—compliant bio-based formulations for EU markets and conventional plastics for less regulated geographies. Thermometer housing and brush handle segments face the steepest reformulation cost burdens under these frameworks.
Subscription-based replenishment services for consumable grooming components are displacing traditional retail repurchase patterns among millennial parent cohorts. Direct-to-consumer platforms and hospital discharge partnerships are capturing demand that drugstore and big-box channels previously dominated. This channel rotation is most pronounced in US coastal metropolitan markets and Chinese tier-1 cities where delivery logistics infrastructure supports just-in-time replacement cycles.
Baby Grooming Kits Market Segmentation
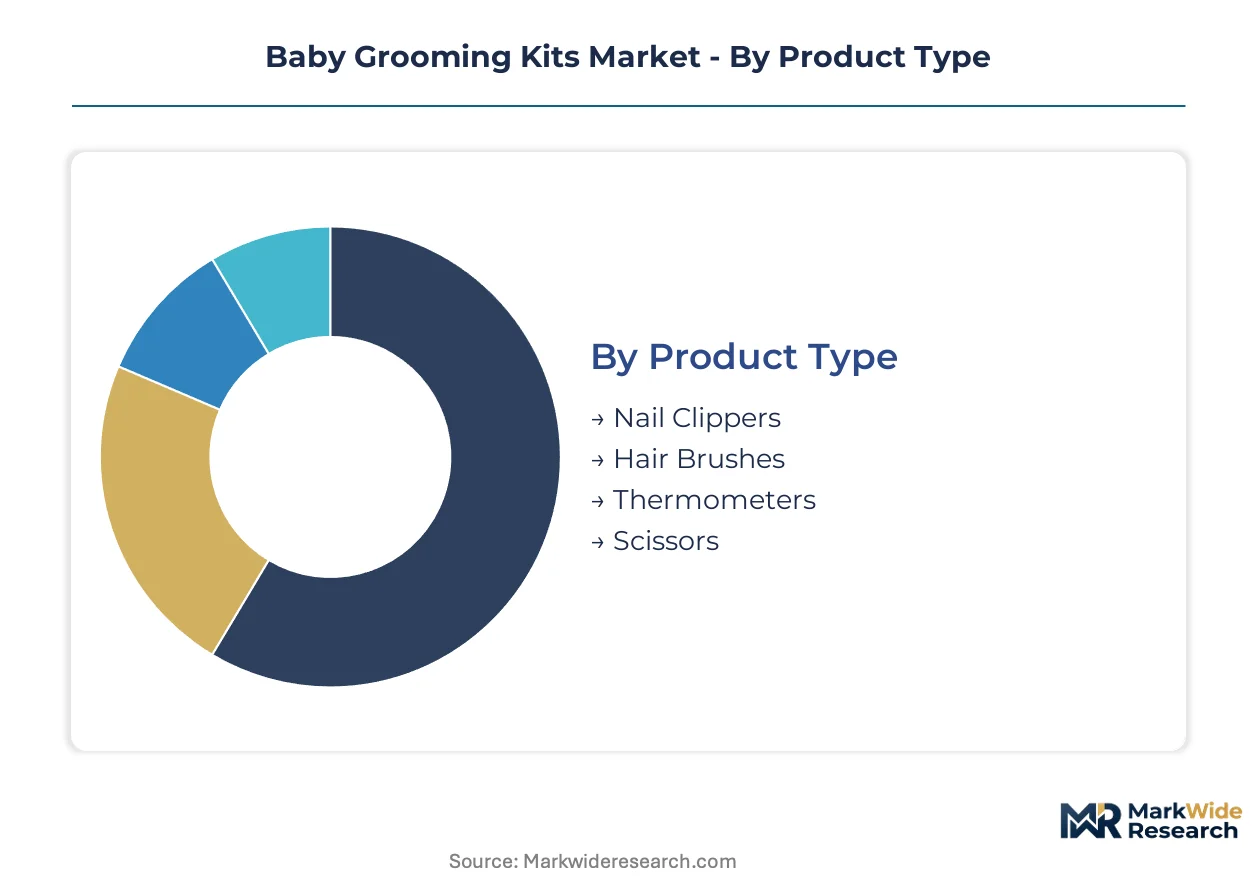
Segmentation in baby grooming kits reveals how safety-critical design requirements and material substitution pressures create divergent margin profiles across product categories. Understanding these fracture lines helps manufacturers allocate certification investments and channel resources toward the highest-return configurations.
Product Type:
Nail clippers and thermometers face the most acute substitution threats from smartphone-enabled alternatives and standalone digital devices, forcing bundled kit assemblers to differentiate through integration convenience.
- Nail Clippers:Medical-grade stainless steel construction with rounded-tip safety engineering prevents accidental laceration during infant nail trimming. Demand concentrates among first-time parents in Chinese tier-1 cities where safety anxiety drives premium kit purchases.
- Thermometers:Digital infrared and contact models require FDA 510(k) clearance under 21 CFR Part 880 for accuracy claims, creating compliance barriers that favor established manufacturers with dual-certification capabilities. Replacement frequency and safety-critical positioning sustain revenue concentration despite smartphone temperature app proliferation.
- Hair Brushes:Soft-bristle designs using silicone or natural materials for cradle cap management and scalp stimulation.
- Scissors:Rounded-tip safety variants for trimming delicate infant hair and nails.
Nail clippers retain volume leadership; thermometers hold the steepest expansion curve.
Material:
Cost tier stratification separates premium positioning strategies, with hypoallergenic and sustainable materials commanding margin premiums over commodity alternatives.
- Silicone:Food-grade formulations with antimicrobial additives and rounded-tip safety engineering displace conventional plastics in premium configurations. Shanghai and New York metropolitan parents specify silicone grooming tools in gift registries at accelerating rates.
- Stainless Steel:Medical-grade alloys from German and Japanese specialty mills provide durability and corrosion resistance for nail clippers and scissors. REACH phthalate restrictions and EU Green Deal mandates push European channel partners toward metal alternatives.
- Plastic:BPA-free polymers remain dominant in mass-market kits despite sustainability headwinds.
- Bamboo:Bio-based material adoption accelerates under extended producer responsibility frameworks in EU markets.
Plastic retains volume leadership; silicone holds the steepest expansion curve.
Packaging Type:
Customer type dynamics shift procurement toward gift-oriented and subscription-friendly formats that reduce friction for sleep-deprived urban households.
- Boxed Sets:Curated collections with branded presentation target gift-registry and baby shower segments. Hospital discharge partnerships in US coastal metros create sticky demand for clinical-grade boxed configurations.
- Travel Kits:Compact, TSA-compliant designs with secure closures address mobile parenting needs. Direct-to-consumer subscription services for replacement components favor travel kit formats with modular refill architecture.
- Pouches:Lightweight fabric organizers for single-item or minimal configurations.
- Cases:Rigid-shell protection for premium instrument storage and transport.
Boxed sets retain volume leadership; travel kits hold the steepest expansion curve.
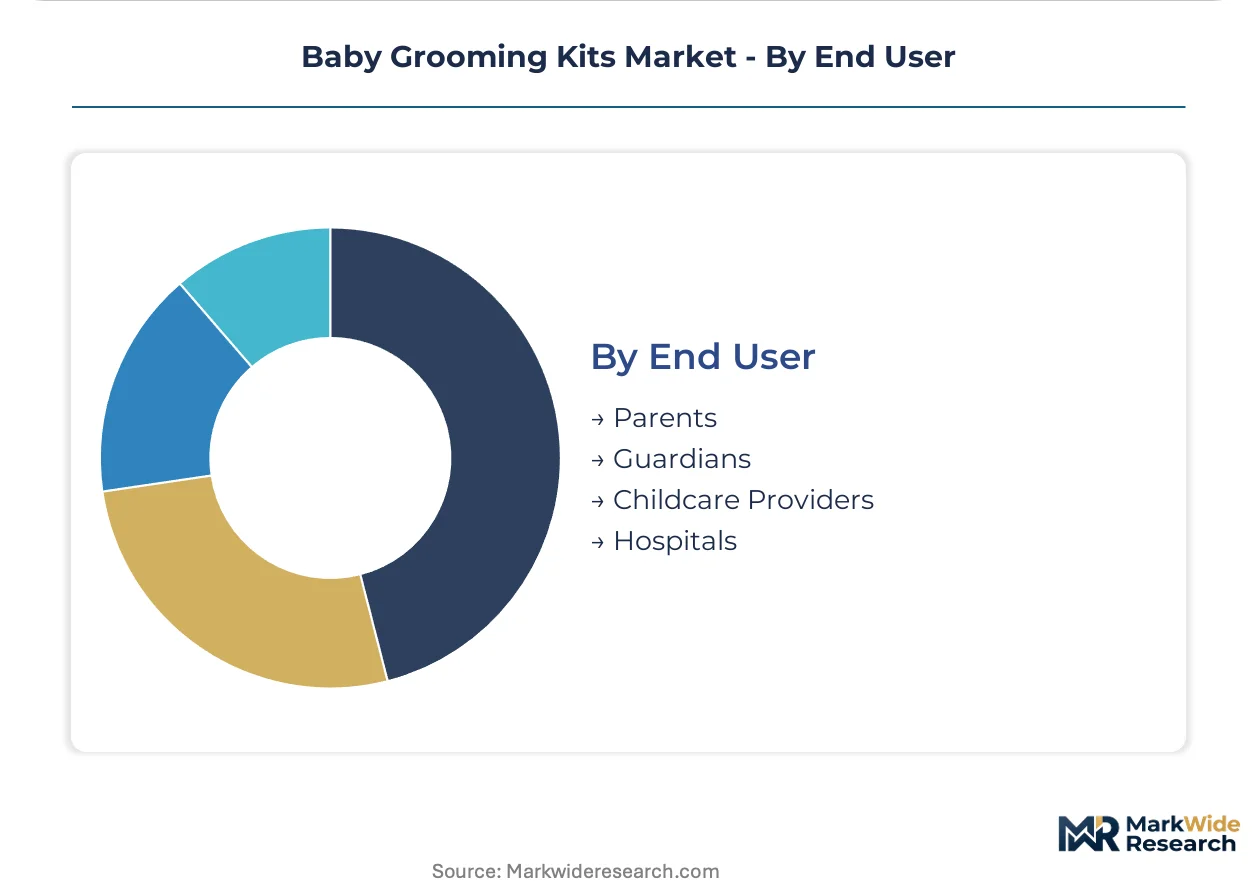
End User:
Application intensity varies sharply across user types, with institutional procurement demanding clinical-grade specifications that reshape product architecture.
- Parents:First-time urban parents drive premium kit adoption through bundled convenience preferences and safety anxiety. E-commerce subscription models capture recurring replacement demand from millennial cohorts in Chinese tier-1 cities and US coastal metros.
- Hospitals:Clinical-grade positioning through discharge gift programs requires FDA-cleared thermometers and sterilizable materials. Healthcare channel partnerships create trusted recommendation effects that persist through early childhood.
- Guardians:Grandparents and extended family members purchasing gift-registry items.
- Childcare Providers:Licensed facilities with standardized hygiene protocols and bulk procurement requirements.
Parents retain volume leadership; hospitals hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Chinese tier-1 cities where dual-child policy effects sustain premium kit premiums, while cost-sensitive mass-market demand clusters in Southeast Asian manufacturing hubs. This asymmetry rewards manufacturers with dual-certification capabilities and penalizes single-market players.
United States
FDA 510(k) clearance requirements for infant thermometers create compliance moats that favor established manufacturers with dual-certification portfolios. Hospital discharge gift programs in coastal metropolitan markets generate sticky demand for clinical-grade boxed configurations. Boston and Seattle clusters concentrate healthcare channel partnerships and e-commerce subscription fulfillment infrastructure.
China
Dual-child policy effects sustain elevated birth rates in Shanghai, Beijing, and Shenzhen, concentrating demand for bundled premium kits among first-time urban parents. SAMR oversight of infant product safety and GB standards compliance shape domestic manufacturing investments. Yangtze River Delta industrial zones anchor silicone processing and medical-grade stainless steel assembly operations.
Germany
REACH phthalate restrictions and EU Green Deal sustainability mandates compel systematic material reformulation for European distribution channels. Specialty steel mills in the Ruhr region control premium medical-grade alloy supply for nail clipper and scissor components. Bavaria-based precision manufacturers dominate CE marking expertise under EU MDR for thermometer-integrated kits.
Japan
PMDA medical device regulations govern thermometer accuracy claims and electrical safety standards for domestic and export markets. METI industrial policy supports silicone material science R&D for hypoallergenic grooming tool applications. Osaka-Kobe industrial corridor concentrates food-grade silicone formulation expertise and antimicrobial additive processing capabilities.
India
BIS certification requirements for infant care products and rising disposable incomes in metropolitan markets elevate organized sector penetration. CDSCO medical device rules increasingly align with international standards for thermometer accuracy claims. Maharashtra and Gujarat manufacturing clusters assemble mass-market plastic-based kits for domestic consumption and export to African and Middle Eastern markets.
Baby Grooming Kits Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes in baby grooming kits, with integrated electronics capabilities separating premium thermometer suppliers from mass-market assemblers. The market structure shows moderate consolidation around dual-certification specialists, with long-tail fragmentation among regional plastic-component fabricators. Three archetypes dominate: multinational healthcare conglomerates with captive semiconductor expertise, Asian material science specialists with silicone processing capabilities, and clinical-grade positioning specialists with healthcare channel access. Competitive dynamics center on M&A activity targeting thermometer module suppliers and strategic partnerships with hospital discharge programs.
Among multinational healthcare conglomerates, Philips Avent represents the integrated electronics archetype with its digital thermometer segment dominance. Pigeon Corporation anchors the material science specialist tier through its silicone-based grooming tool expertise. Fridababy exemplifies clinical-grade positioning through healthcare channel partnerships and hospital discharge gift program penetration. These three companies occupy distinct strategic positions that reward different capability investments: semiconductor integration, chemical formulation, and institutional sales infrastructure respectively.
| Leading Market Players |
|---|
| Philips Avent |
| Summer Infant |
| Pigeon Corporation |
| Fridababy |
| Fisher-Price |
| Safety 1st |
| Chicco |
| The First Years |
| Munchkin |
| Others |
Pricing and Supply Chain Analysis
Ninety-day inventory cycles for medical-grade stainless steel from German and Japanese specialty mills concentrate pricing power with upstream alloy suppliers and compress margins for downstream kit assemblers. This lead-time structure forces bundled product manufacturers to absorb input volatility or pass through costs to price-sensitive mass-market tiers.
Pricing Analysis
The customization-premium spread between configured-to-order silicone grooming tools and standard plastic-based kits reaches three-to-one multiples across Chinese tier-1 city retail channels. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and material composition, with FDA-cleared thermometer configurations commanding substantial premiums over basic alternatives. Price differentiation stems from dual-certification investment requirements and silicone material science capabilities. Cost compression in mass-market plastic segments is intensifying because REACH phthalate restrictions force reformulation cycles. First-time parents in urban centers show least price sensitivity; bulk procurement by childcare facilities exhibits highest elasticity.
Supply Chain Analysis
Ruhr Valley specialty steel output and Yangtze River Delta silicone processing capacity constitute twin chokepoints that constrain premium kit production scaling. Geographic supply concentration centers on Germany for medical-grade stainless alloys, China for food-grade silicone formulations, and Japan for precision thermometer module assembly. Raw material dependencies rest on antimicrobial additive supply from Osaka-Kobe chemical corridors, BPA-free polymer feedstock from Gulf Coast petrochemical complexes, and bamboo fiber from Zhejiang sustainable forestry operations. Single-source vulnerability in German-Japanese steel mill relationships exposes assemblers to allocation risk during demand surges. Distribution runs through hospital discharge partnerships, direct-to-consumer subscription platforms, and mass retail pharmacy chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks birth rate cyclicality in Chinese tier-1 cities, with dual-child policy effects sustaining demand recovery through elevated first-time parent cohorts.
For Market Incumbents: Fortify dual-certification portfolios against FDA 510(k) timeline compression and EU MDR transition complexity. Secure captive silicone processing capabilities or long-term offtake agreements with Yangtze River Delta formulators to defend margin position against material substitution acceleration. Prioritize hospital discharge partnership lock-ins before clinical-grade positioning becomes saturated. For New Entrants and Emerging Players: Lead with sustainable material innovation targeting EU Green Deal compliance premiums rather than competing on thermometer electronics integration. White-space opportunity concentrates in bamboo-based travel kits for European extended producer responsibility frameworks and subscription-compatible modular refill architectures for US coastal metropolitan parents. Go-to-market angle should emphasize clinical-grade unboxing experience at mid-tier price positioning. For Investors and Strategic Acquirers: Long-term, this sits as a certification-moat play because regulatory stringency in infant medical devices creates durable barriers against commoditization. Acquisition target archetype: mid-cap specialists with existing FDA clearances and underutilized healthcare channel relationships. Signal to watch is thermometer module supplier consolidation activity as electronics integration demands strain traditional grooming tool manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Investment | FDA 510(k) and CE marking under EU MDR create compliance moats against low-cost imports. |
| Silicone Processing Backward Integration | Captive food-grade formulation capabilities secure margin pools in hypoallergenic premium tiers. |
| Hospital Discharge Partnership Expansion | Clinical-grade positioning through trusted recommendation channels generates sticky recurring demand. |
| Subscription Platform Development | Direct-to-consumer replenishment captures replacement cycles from sleep-deprived urban households. |
| Sustainable Material Repositioning | Bamboo and bio-based adoption aligns with EU Green Deal mandates and extended producer responsibility frameworks. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) clearances, SAMR infant product safety registrations, and EU MDR technical documentation databases. Primary interviews engaged product development directors at thermometer manufacturers, procurement leads at hospital gift program administrators, silicone formulation chemists, and e-commerce category managers for baby care. Secondary sources encompassed customs trade data for grooming tool imports, SEC filings of listed parent companies, and REACH substance restriction updates from ECHA. Bottom-up unit economics triangulated against top-down market sizing from birth rate projections and disposable income elasticity models.
Segmentation dimensions modeled span product type, material composition, packaging format, and end-user archetype across the analysis window. Analytical framework incorporated replacement frequency curves for consumable components, certification timeline distributions by regulatory pathway, and channel shift velocity from retail to subscription. CAGR derivation rested on elasticity-adjusted volume projections and premium tier penetration scenarios. Industry-specific forecast inputs included dual-child policy demographic effects and silicone material substitution adoption curves in gift registry selections.
The analysis sits within stated boundaries; outcomes outside sustained birth rate recovery in Chinese tier-1 cities or accelerated EU MDR enforcement timelines would require recalibration. Forecasts reflect documented assumptions regarding certification approval velocities and raw material supply continuity. Revision becomes warranted when FDA 510(k) backlog severity or German-Japanese steel mill allocation constraints cross thresholds that disrupt premium kit production scaling.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Grooming Products
Foot Care Products Market
Personal Grooming Products
Electric Shavers Market
Personal Grooming Products
Horsehair Clippers Market
Personal Grooming Products
Self-Tanning Products Market
Personal Grooming Products
Shaving Care Market
Personal Grooming Products
Handheld Massager Market
Personal Grooming Products
Insoles Market
Personal Grooming Products
Global Sex Toys Market
Personal Grooming Products
Disposable Shower Caps Market
Personal Grooming Products
Electric Hair Clipper and Trimmer Market
Personal Grooming Products
Europe Electric Toothbrush Market
Personal Grooming Products
Global Massage Guns Market
Personal Grooming Products
Toothpaste Tablet Market
Personal Grooming Products
Smart Body Scales Market
Personal Grooming Products
Shaving Pen Market
Personal Grooming Products
Disposable Razor Blades Market