
 Baby Oil Market | 2026-2036
Baby Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Baby Oil Market Outlook
Multi-source procurement for base oils is shifting toward vertically integrated refiners with cosmetic-grade certification. Johnson & Johnson leverages its captive supply chain to secure pharmaceutical-grade white mineral oil volumes. Himalaya Wellness Company anchors its positioning through Ayurvedic botanical formulations that bypass petroleum-derived inputs entirely. Dabur Ltd. competes on cold-pressed sesame and almond oil heritage, targeting consumers who reject synthetic bases.
Baby oil comprises highly refined mineral oil or plant-derived lipids formulated for infant epidermal barrier support, typically achieving kinematic viscosities between 25 and 80 centistokes at 40°C to ensure spreadability without occlusive trapping. The product serves primary commercial purposes in infant massage therapy, cradle cap management, and post-bath moisture retention across hospital nurseries and home care settings. Coconut oil and almond oil segments command premium shelf positioning in European and North American retail, while mineral oil retains volume leadership in price-sensitive Asian markets. Organic-grade products capture expanding margin pools as ECHA REACH restrictions on polycyclic aromatic hydrocarbon residues push reformulation costs upward.
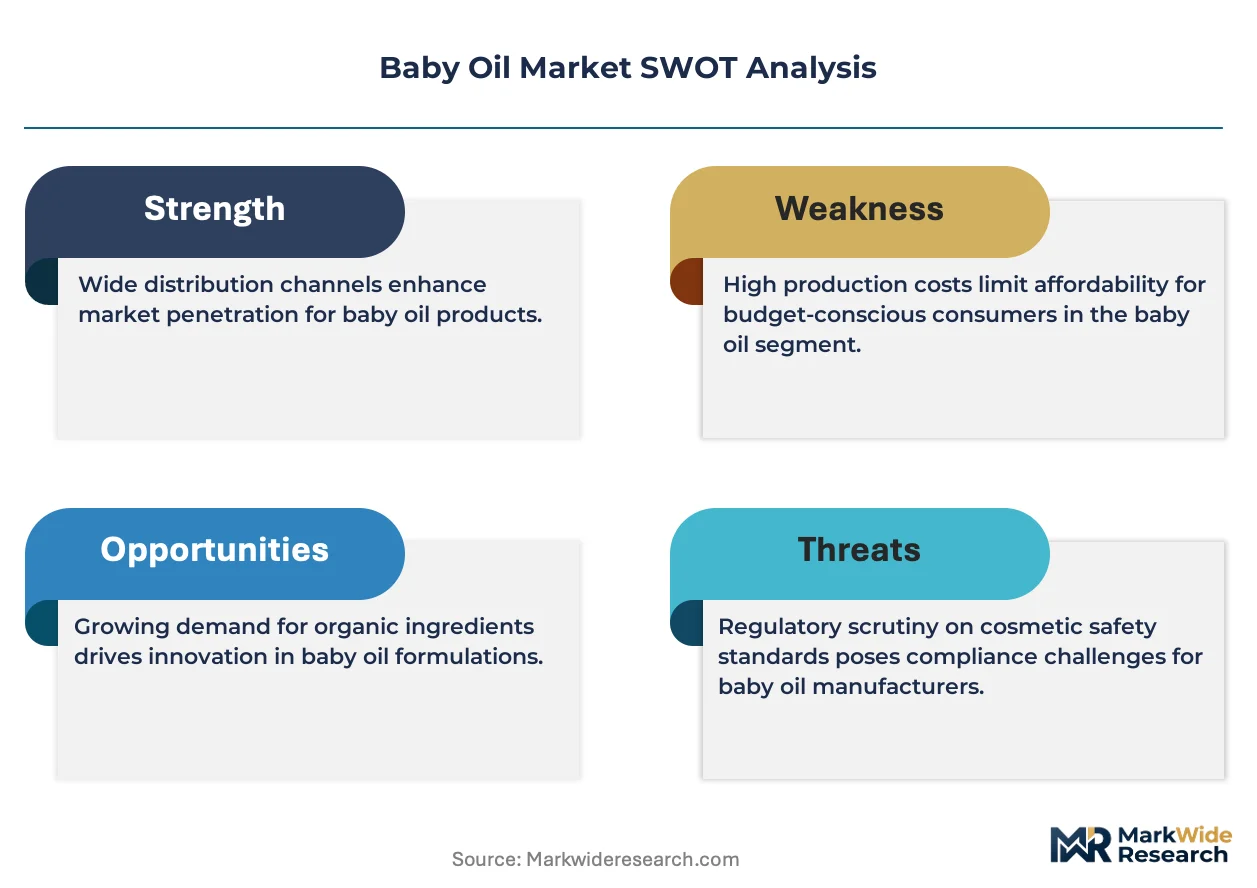
FDA monograph oversight for infant topical products governs labeling claims and safety substantiation in the United States, while ECHA REACH and EU Cosmetic Regulation (EC) No 1223/2009 set compositional limits across Europe. India's BIS certification requirements for cosmetic safety and the FSSAI framework for edible-grade oils used in baby formulations add compliance layers for cross-category suppliers. Stakeholders must monitor evolving PAH threshold reductions and botanical allergen disclosure mandates that will determine which base oil portfolios retain market access.
Market Dynamics
ECHA REACH polycyclic aromatic hydrocarbon threshold reductions are forcing base oil reformulation across European supply chains, compressing margins for non-vertically integrated blenders while creating certification premiums for compliant refiners.
Growth Catalysts
- Pediatric dermatology protocol expansion:Southeast Asian clinics are integrating mineral-based emollients into standardized infant skincare regimens, creating institutional demand pull.
- REACH compliance premium:Stricter cosmetic-grade mineral oil purity mandates in Europe are disqualifying uncertified suppliers and concentrating volume with qualified refiners.
- Organized retail penetration:India's tier-two cities are deepening mother-and-baby product shelf space, expanding addressable consumer base beyond metropolitan centers.
Market Restraints
- Base oil input cost volatility:Pharmaceutical-grade white mineral oil supply concentrates with vertically integrated refiners, exposing non-integrated blenders to price squeezes.
- Botanical substitution threat:Cold-pressed sesame and almond oil heritage positioning in South Asia is capturing consumers rejecting petroleum-derived bases.
- Regulatory friction from ECHA:REACH PAH residue threshold tightening is accelerating reformulation costs and disqualifying legacy supplier portfolios.
Strategic Opportunities
- Ayurvedic formulation white space:Botanical oil segments bypassing petroleum inputs are capturing premium positioning in wellness-oriented consumer segments.
- Hospital nursery channel expansion:Post-bath moisture retention protocols in institutional settings are creating bulk procurement contracts for compliant suppliers.
- Organic certification tailwind:ECHA restrictions on synthetic residues are expanding margin pools for certified organic-grade product lines.
Industry Challenges
- Cosmetic-grade certification timeline compression:BIS and FSSAI dual compliance requirements in India are extending product launch cycles for cross-category suppliers.
- Supply chain reconfiguration friction:Multi-source procurement shifts toward captive supply relationships are stranding legacy distributor networks.
- Allergen disclosure complexity:Botanical formulation mandates for allergen labeling are increasing packaging compliance costs for heritage oil blenders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baby Oil Market |
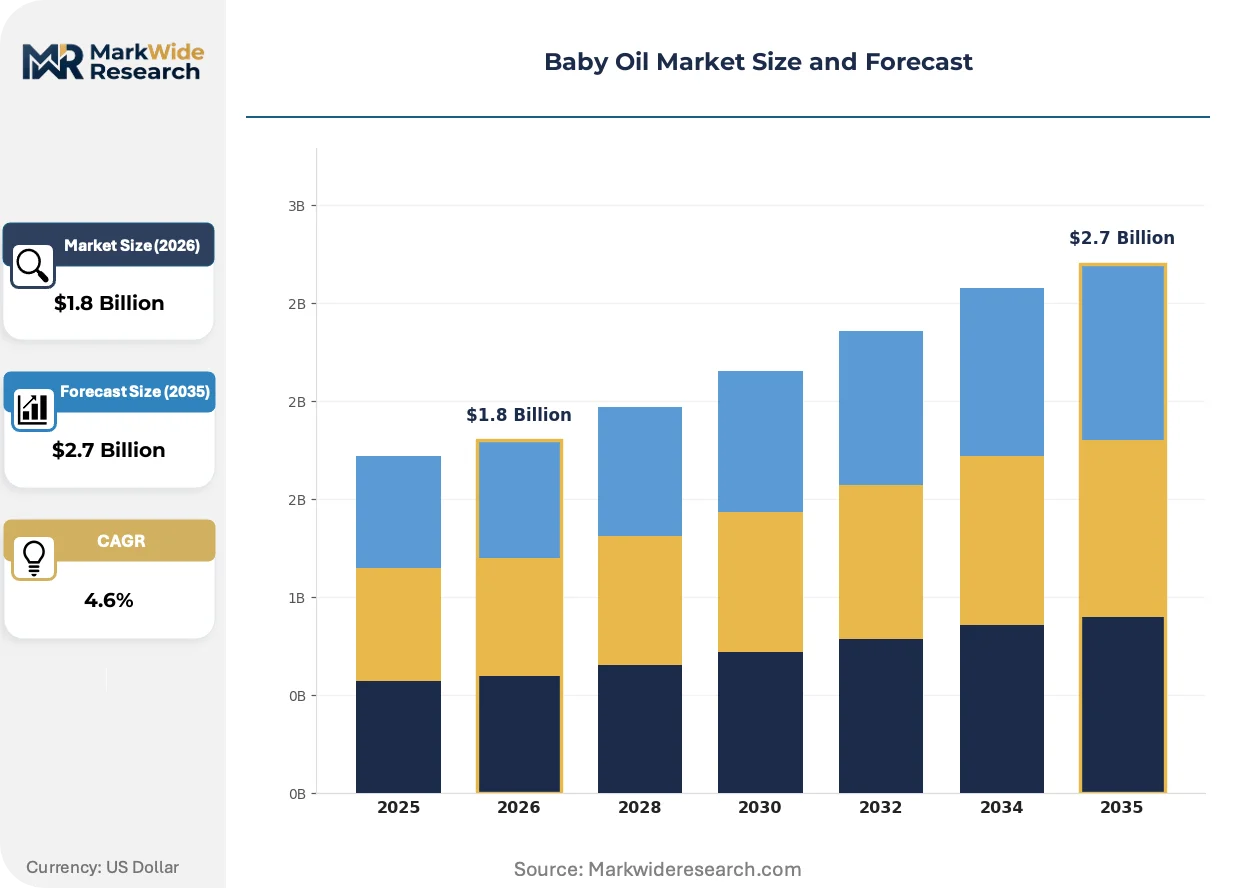
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mineral Oil, Coconut Oil, Almond Oil, Olive Oil Application: Moisturizing, Massage, Hair Care, Skin Care Grade: Organic, Natural, Synthetic, Therapeutic Package Type: Bottle, Tube, Jar, Sachet |
| Companies Covered | Himalaya Wellness Company, Burt's Bees Inc., Johnson & Johnson, Sebapharma GmbH & Co. KG, Farlin-Global, Dabur Ltd., Artsana S.p.A, Laboratoires Expanscience, Pigeon Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baby Oil Market Strategic Shifts
Reformulation activity around mineral oil purity standards is compressing supplier margins while opening certification-driven price tiers. Three distinct trajectories are reshaping competitive positioning.
Super-refining technology for cosmetic-grade mineral oil is consolidating supplier tiers by enabling sub-ppm PAH residue achievement. European pediatric dermatology clinics are adopting these grades for cradle cap management protocols. This capability concentration is compressing market access for mid-tier refiners lacking pharmaceutical-grade certification infrastructure.
ECHA REACH restrictions on polycyclic aromatic hydrocarbon residues are mandating compositional reformulation across European supply chains. Industrial consequence includes supplier disqualification and volume migration toward certified refiners. Baby oil segments in Germany and France are responding with organic-grade product line extensions to preempt regulatory exposure.
Massage therapy application demand is rotating toward Ayurvedic botanical formulations in South Asian markets. Heritage cold-pressed oil suppliers are displacing synthetic-base incumbents through wellness channel positioning. This pattern concentrates in India's tier-two cities where organized retail penetration enables premium product accessibility.
Baby Oil Market Segmentation
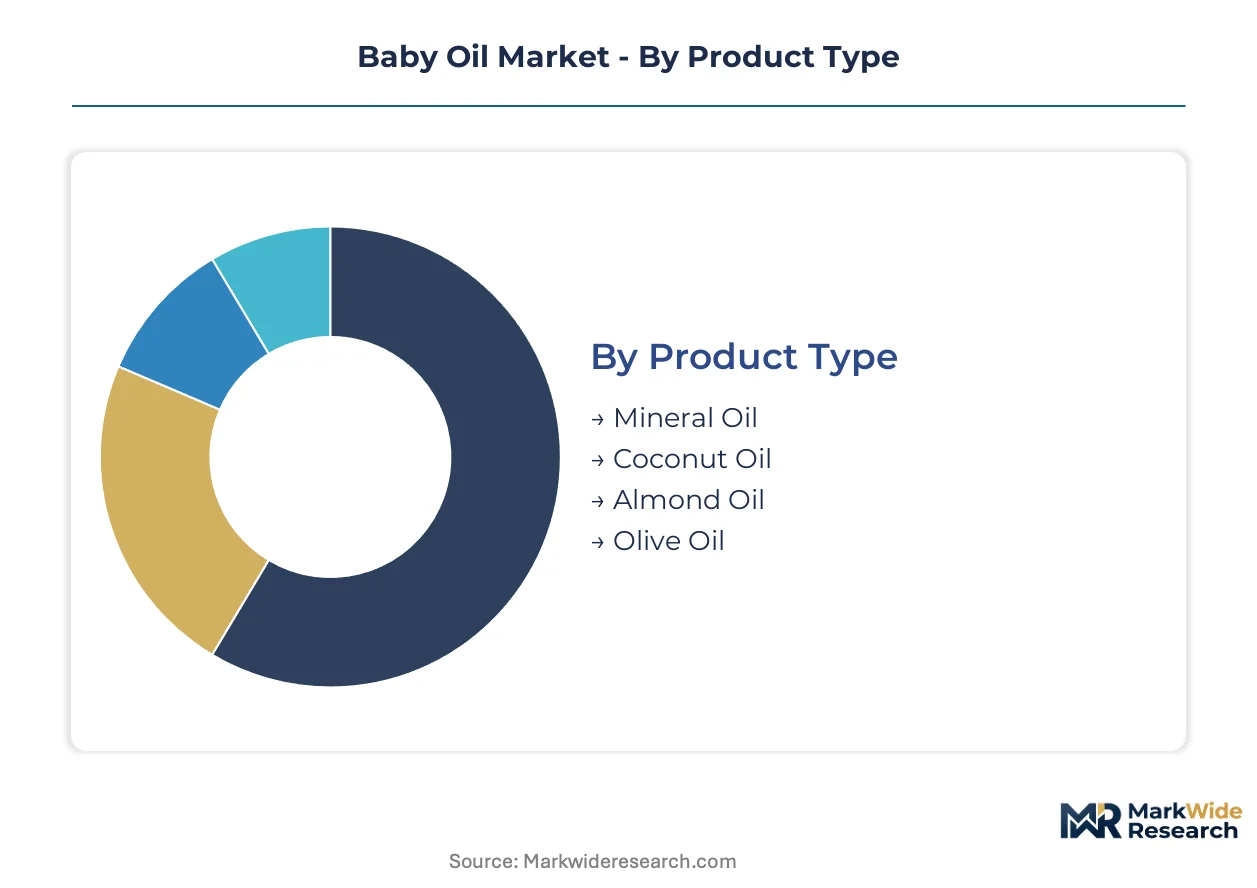
Segmentation in baby oil reveals how formulation chemistry, use context, and purity certification create distinct margin architectures. Each dimension carries divergent regulatory exposure and channel access requirements that reshape supplier portfolios.
Product Type:
Mineral oil segments function as standalone commodities with established pharmacopeia standards, while botanical alternatives embed within wellness positioning systems.
- Mineral Oil:Highly refined white mineral oil meeting pharmaceutical-grade purity thresholds achieves kinematic viscosities between 25 and 80 centistokes at 40°C. Demand concentrates in India's tier-two cities where price-sensitive consumers prioritize cost efficiency over botanical provenance, though ECHA REACH PAH residue limits are compressing supplier margins in Europe.
- Coconut Oil:Cold-pressed virgin coconut oil carries lauric acid content above 45 percent, delivering antimicrobial properties valued in tropical climates. European and North American retail channels command premium shelf positioning for this segment, with Germany's pediatric dermatology clinics integrating it into cradle cap management protocols as mineral oil alternatives face compositional scrutiny.
- Almond Oil:Sweet almond oil formulations leverage oleic acid profiles for epidermal barrier support in post-bath applications.
- Olive Oil:Extra virgin olive oil variants target Mediterranean heritage positioning with squalene-rich emollient properties.
Mineral oil leads volumes today; coconut oil is gaining share fastest.
Application:
Application segments diverge by institutional adoption depth versus household purchase frequency.
- Moisturizing:Post-bath moisture retention protocols in hospital nurseries drive bulk procurement contracts for compliant suppliers. Southeast Asian pediatric dermatology clinics are standardizing mineral-based emollient use in neonatal care, creating institutional demand pull distinct from retail channels.
- Massage:Infant massage therapy demand in South Asia rotates toward Ayurvedic botanical formulations as heritage cold-pressed oil suppliers displace synthetic-base incumbents through wellness channel positioning in India's organized retail expansion zones.
- Hair Care:Cradle cap management applications concentrate in clinical settings with super-refining technology enabling sub-ppm PAH residue achievement for European regulatory compliance.
- Skin Care:General epidermal barrier maintenance spans both institutional formulary inclusion and direct-to-consumer positioning.
Moisturizing commands the largest revenue pool; massage applications show the steepest expansion trajectory.
Grade:
Grade differentiation maps directly onto certification burden and margin capture potential.
- Organic:Certified organic-grade products bypass petroleum inputs entirely, capturing expanding margin pools as ECHA restrictions on synthetic residues create price tier separation. Supply concentrates with vertically integrated refiners and heritage cold-pressed oil processors who control upstream agricultural inputs.
- Natural:Natural-grade formulations occupy mid-tier positioning between certified organic and synthetic alternatives, requiring botanical allergen disclosure compliance that increases packaging costs for heritage blenders.
- Synthetic:Synthetic-grade mineral oil faces REACH-driven reformulation costs and supplier disqualification in European markets.
- Therapeutic:Therapeutic-grade products target clinical channel access with enhanced purity documentation.
Natural grade holds current volume leadership; organic certification is climbing the fastest.
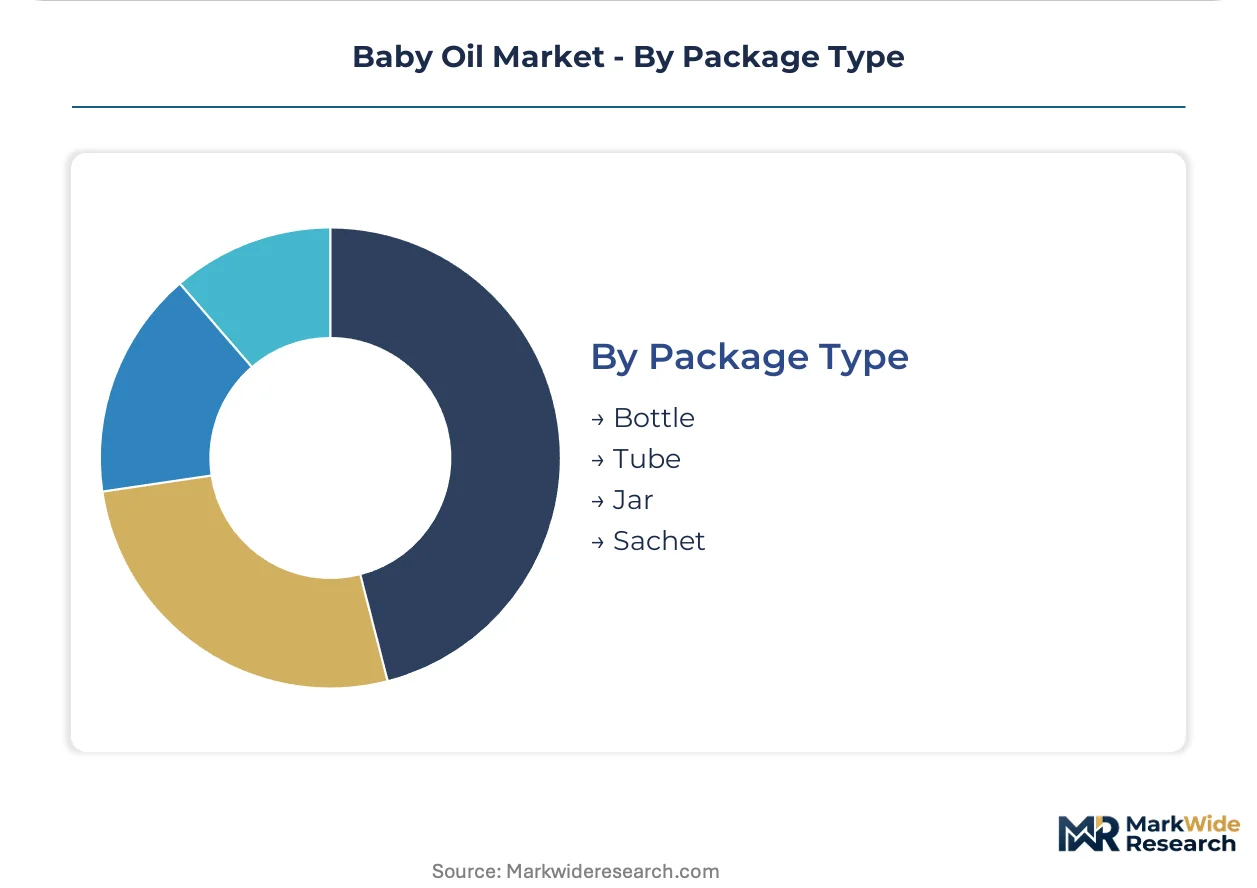
Package Type:
Package economics determine distribution reach and trial conversion efficiency across consumer segments.
- Bottle:Standard pump and flip-cap bottles dominate mother-and-baby retail shelf space in India's deepening organized retail penetration zones, with tier-two city expansion enabling premium product accessibility previously concentrated in metropolitan centers.
- Tube:Squeeze tubes target travel and trial-size positioning with lower per-unit commitment.
- Jar:Wide-mouth jars serve bulk institutional procurement for hospital nursery protocols.
- Sachet:Single-use sachets penetrate price-sensitive rural markets with minimal entry barriers.
Bottle formats anchor current distribution; sachet penetration is expanding most quickly in emerging market access points.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's tier-two cities anchor demand expansion for mother-and-baby products as organized retail penetration deepens across secondary urban centers. Pediatric dermatology protocol adoption in Southeast Asian clinics creates institutional pull for mineral-based emollients. REACH compliance mandates in Europe compress supplier margins while concentrating volume with certified refiners.
India
Tier-two cities including Pune, Jaipur, and Lucknow drive volume growth through expanding modern trade shelf space for infant care products. FSSAI edible-grade oil standards and BIS cosmetic safety certification create dual compliance layers for cross-category suppliers. Heritage cold-pressed oil processors in Gujarat and Rajasthan capture wellness-oriented consumers rejecting petroleum-derived bases.
Germany
Super-refining technology adoption for sub-ppm PAH residue achievement concentrates supply with pharmaceutical-grade certified refiners. ECHA REACH polycyclic aromatic hydrocarbon threshold reductions mandate compositional reformulation across cosmetic supply chains. Pediatric dermatology clinics in Berlin and Munich integrate mineral-based emollients into standardized neonatal skincare protocols.
United States
FDA monograph oversight governs labeling claims and safety substantiation for infant topical products across hospital nursery and retail channels. Post-bath moisture retention protocols in institutional settings drive bulk procurement contracts for compliant suppliers. Manufacturing concentration in New Jersey and Pennsylvania supports captive supply chain integration for pharmaceutical-grade white mineral oil.
Thailand
Pediatric dermatology clinic expansion across Bangkok and Chiang Mai integrates mineral-based emollients into standardized infant skincare regimens. The country's national pharmaceutical regulator enforces cosmetic safety standards aligned with ASEAN harmonization frameworks. Cold-pressed coconut oil processors in southern provinces leverage lauric acid antimicrobial properties for tropical climate positioning.
France
Organic-grade product line extensions preempt regulatory exposure from ECHA synthetic residue restrictions. ANSM cosmetic surveillance mandates allergen disclosure requirements for botanical formulations. Laboratoires Expanscience and heritage oil blenders in the Île-de-France region navigate packaging compliance cost increases from botanical allergen labeling mandates.
Baby Oil Market Competitive Environment
Global majors compete with regional champions across formulation chemistry and certification-grade positioning. The market structures around vertically integrated refiners with pharmaceutical-grade infrastructure, heritage cold-pressed oil processors with Ayurvedic positioning, and mid-tier blenders facing margin compression from input cost volatility. Three archetypes dominate: captive supply chain operators, botanical wellness specialists, and reformulation-pressured commodity blenders. Competitive moves concentrate on backward integration into base oil supply and organic certification acquisition to capture price tier separation.
Within the heritage wellness tier, Himalaya Wellness Company and Dabur Ltd. exemplify Ayurvedic botanical formulation strategies that bypass petroleum-derived inputs entirely. Johnson & Johnson occupies a position representing captive supply chain architecture through pharmaceutical-grade white mineral oil volume security. Sebapharma GmbH & Co. KG anchors the European clinical channel access archetype with enhanced purity documentation for therapeutic-grade positioning.
| Leading Market Players |
|---|
| Himalaya Wellness Company |
| Burt's Bees Inc. |
| Johnson & Johnson |
| Sebapharma GmbH & Co. KG |
| Farlin-Global |
| Dabur Ltd. |
| Artsana S.p.A |
| Laboratoires Expanscience |
| Pigeon Corporation |
| Others |
Value Chain & Pricing Dynamics
Captive supply relationships with pharmaceutical-grade white mineral oil refiners anchor both cost predictability and margin protection for established blenders. Johnson & Johnson's in-house production of cosmetic-grade base stocks insulates its pricing power from ECHA REACH-driven input volatility that compresses non-integrated competitors.
Pricing Analysis
Input-cost pass-through from pharmaceutical-grade white mineral oil concentrates pricing power with vertically integrated refiners in New Jersey and Pennsylvania. Certification-grade differentiation separates organic-certified botanical formulations from synthetic mineral oil tiers, with cold-pressed heritage oils commanding shelf-space premiums in India's organized retail expansion. Cost compression in European synthetic-grade segments intensifies as ECHA PAH threshold tightening accelerates reformulation expenses. Price sensitivity concentrates among India's tier-two city consumers prioritizing cost efficiency over botanical provenance.
Supply Chain Analysis
Base oil supply rests on vertically integrated refiners in the United States, heritage cold-pressed processors in Gujarat and Rajasthan, and super-refining specialists in Germany. Pharmaceutical-grade white mineral oil, cold-pressed sesame and almond oils, and certified organic coconut lipids constitute the critical input trinity. Single-source vulnerability concentrates around REACH-compliant cosmetic-grade mineral oil capacity in Europe. Distribution runs through hospital nursery procurement contracts, modern trade retail in India's tier-two cities, and wellness channel positioning in Southeast Asian pediatric dermatology networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in baby oil tracks the shift from synthetic mineral oil tiers toward certified organic-grade positioning, with ECHA residue restrictions compressing legacy supplier economics while opening premium capture for compliant botanical processors.
For Market Incumbents: To counter botanical substitution threats from Ayurvedic heritage blenders, secure backward integration into cold-pressed oil supply in Gujarat and Rajasthan while accelerating organic certification acquisition to preempt ECHA-driven tier separation. For New Entrants and Emerging Players: Capture institutional procurement contracts for hospital nursery moisture retention protocols in Thailand and Vietnam, where pediatric dermatology clinic expansion creates demand pull distinct from saturated retail channels. For Investors and Strategic Acquirers: Roll-up economics work for heritage cold-pressed oil processors with Ayurvedic positioning because wellness-channel penetration in India's tier-two cities enables premium pricing power unavailable to synthetic-base commodity blenders. Watch ECHA PAH threshold enforcement velocity as the signal determining which supplier portfolios retain European market access.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Supply | Captive sourcing of pharmaceutical-grade white mineral oil insulates margin from ECHA-driven input cost volatility. |
| Organic Certification Acquisition | Certified organic-grade positioning captures price tier separation as REACH synthetic residue restrictions tighten. |
| Hospital Nursery Channel Expansion | Bulk procurement contracts for post-bath moisture protocols in Southeast Asian clinics create institutional demand pull. |
| Ayurvedic Formulation Development | Cold-pressed sesame and almond oil heritage positioning displaces synthetic-base incumbents in wellness-oriented segments. |
| Super-Refining Technology Investment | Sub-ppm PAH residue achievement enables European regulatory compliance and clinical channel access concentration. |
Study Parameters
Multiple input streams — primary interviews with brand managers and category buyers at mother-and-baby retailers, supply planner discussions at heritage oil processors, and regulatory affairs consultations — were reconciled against secondary validation from BIS cosmetic safety filings, FSSAI edible-grade oil standards, ECHA REACH substance dossiers, and organized retail penetration data across India's tier-two cities. Bottom-up volume builds by product grade and application were cross-checked against top-down market sizing approaches.
Data-stream reconciliation anchored the analytical framework across the projection horizon, modeling segmentation dimensions including formulation chemistry, purity certification tier, use context, and regional regulatory cluster. CAGRs were derived from trend extrapolation of pediatric dermatology protocol adoption rates, REACH compliance timeline impacts, and channel shift patterns in organized retail expansion zones.
ECHA PAH threshold enforcement velocity, FSSAI-BIS dual compliance timeline extensions, and botanical allergen disclosure mandate implementation are the dominant revision risks to modeled outputs. A small set of named regulatory triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Grooming Products
Tattoo Accessories Market
Personal Grooming Products
Insect Repellent Wipes Market
Personal Grooming Products
Smart Electric Toothbrush Market
Personal Grooming Products
Global Posture Corrector Market
Personal Grooming Products
Women Face Razor Market
Personal Grooming Products
Europe Hair Styling Tools Market
Personal Grooming Products
Toothpaste Tablet Market
Personal Grooming Products
Disposable Shower Caps Market
Personal Grooming Products
Foot Care Products Market
Personal Grooming Products
Asia Pacific Hair Styling Tools Market
Personal Grooming Products
Global Hairbrush Market
Personal Grooming Products
Disposable Slippers Market
Personal Grooming Products
Hair Styling Tools Market
Personal Grooming Products
Electric Tooth Polisher Market
Personal Grooming Products
Global Canes and Walking Sticks Market
Personal Grooming Products
Charcoal Bristle Toothbrush Market