
 Cotton Buds Market | 2026-2036
Cotton Buds Market Size, Share, and Industry Trends Forecast 2026-2036
Cotton Buds Market Intelligence
ISO 9001 quality management certification is reorganizing competitive access in the cotton buds industry, filtering out smaller producers lacking documented process controls. Johnson & Johnson leverages its pharmaceutical heritage to sustain premium positioning across pharmacy chains. Groupe Lemoine anchors European supply through specialized organic cotton sourcing. Unilever competes on brand recognition and retail shelf dominance in mass-market channels.
Cotton buds consist of tightly wound cotton fiber tips attached to slender stems, historically plastic but increasingly paper or bamboo, designed for precise cleaning and application tasks in hygiene, medical, and craft settings. The product type dimension shows eco-friendly and biodegradable variants capturing fastest growth as regulatory bans on plastic stems proliferate across jurisdictions. Application segmentation reveals personal care maintaining volume leadership while medical use commands premium pricing through sterilization requirements and clinical compliance standards.
FDA oversight governs medical-grade cotton buds marketed for wound care and clinical procedures in the United States, while the EU Single-Use Plastics Directive mandates stem material transitions across member states. REACH chemical compliance and CE marking requirements further shape product formulations and market entry protocols for European manufacturers. Stakeholders must monitor evolving national implementation timelines for plastic bans and certify alternative materials before shelf access restrictions tighten.
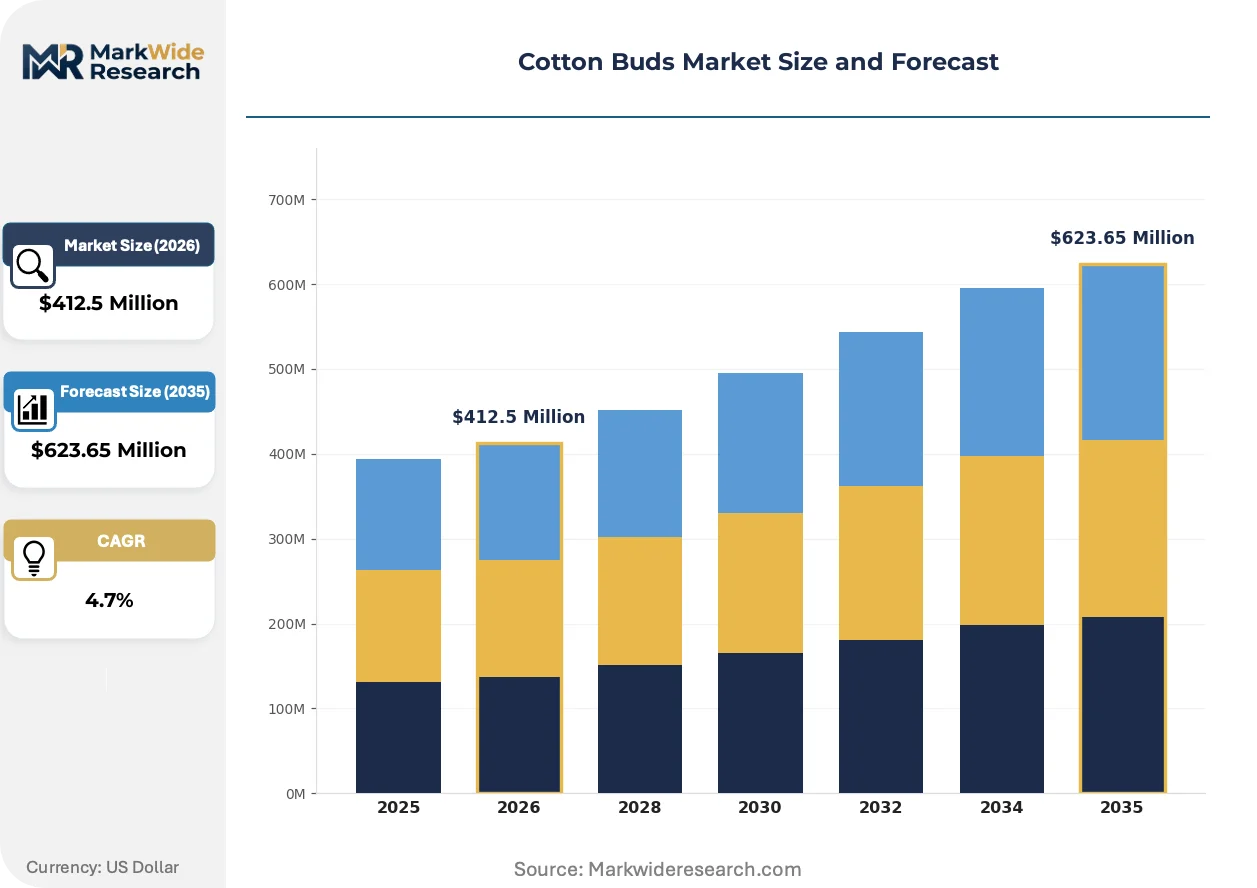
Market Dynamics
The EU Single-Use Plastics Directive is forcing a wholesale material transition across cotton bud manufacturing, with paper and bamboo stems rapidly replacing polypropylene and polystyrene equivalents in European supply chains.
Growth Catalysts
- Biodegradable Material Mandates:The EU Single-Use Plastics Directive bans plastic-stemmed cotton buds across member states, creating immediate substitution demand for certified paper and bamboo alternatives.
- Pharmacy Channel Expansion:Personal care applications drive volume through pharmacy chains where ISO 9001-certified products command preferred shelf placement.
- Organic Cotton Sourcing:Specialized agricultural networks in Egypt and Turkey supply pesticide-free fiber meeting REACH chemical compliance standards for European medical-grade applications.
Market Restraints
- Raw Material Cost Volatility:Bamboo harvests in Guangdong and Fujian provinces face climate-related yield fluctuations that transmit directly to stem pricing.
- Supply Concentration Risk:Three specialized paper mills in Sweden and Finland control the majority of food-grade kraft paper suitable for cotton bud stems.
- Technical Limitation:Bamboo fiber exhibits 15-20% higher moisture absorption than plastic, requiring modified adhesive formulations and extended curing protocols.
Strategic Opportunities
- Medical-Grade Sterilization:CE marking compliance for clinical cotton buds opens premium pricing tiers in German and French hospital procurement systems.
- E-Commerce Direct Channels:Amazon and specialized health platforms bypass traditional retail markups for subscription-based personal care bundles.
- CSRD Reporting Alignment:The EU Corporate Sustainability Reporting Directive incentivizes transparent supply chain documentation that certified organic producers can leverage.
Industry Challenges
- Adhesive Certification Timeline:FDA and EMA biocompatibility testing for new plant-based binding agents extends product launch cycles by 18-24 months.
- Production Line Retrofitting:Legacy plastic extrusion equipment requires capital-intensive modification to handle brittle paper and bamboo feedstocks without fiber splintering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cotton Buds Market |
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $623.65 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Cotton Buds, Eco-friendly Cotton Buds, Plastic-Stem Cotton Buds, Biodegradable Cotton Buds Application: Personal Care, Medical Use, Household Cleaning, Arts & Crafts Packaging Type: Box Packaging, Bag Packaging, Tube Packaging, Bulk Packaging Distribution Channel: Online Retail, Supermarkets, Pharmacy Chains, Specialty Stores |
| Companies Covered | Johnson & Johnson, Unilever, Groupe Lemoine, Jieyang Top-Tip's Daily Use Products, Sanyo Co., Ltd., Dongguan David Health Products, Organyc Italia, Kimberly-Clark Corporation, Essity AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cotton Buds Market Strategic Shifts & Innovations
Bamboo stem technology is displacing conventional materials at the fastest rate in the industry's history, while regulatory frameworks and procurement patterns simultaneously restructure competitive access.
Bamboo stem construction is displacing plastic equivalents through mechanical property improvements that now match polypropylene flexural strength. German pharmacy chains have accelerated adoption timelines, demanding full SKU conversion by 2026. This material shift is compressing margins for legacy petrochemical suppliers while vertically integrated fiber processors capture upstream value.
The EU Single-Use Plastics Directive mandates stem material transitions with enforcement varying by national implementation schedule. French and Italian regulators have imposed earlier compliance deadlines than minimum EU requirements. Medical-grade cotton bud manufacturers face parallel REACH chemical compliance audits that filter out uncertified competitors.
Hospital procurement consortiums in Germany and the United Kingdom now require ISO 9001 documentation as a mandatory bid qualification. Traditional distributors lose share to direct manufacturer contracts with centralized purchasing authorities. This concentration is most visible in NHS supply frameworks where three-year sterilized product agreements displace fragmented spot purchasing.
Cotton Buds Market Segmentation
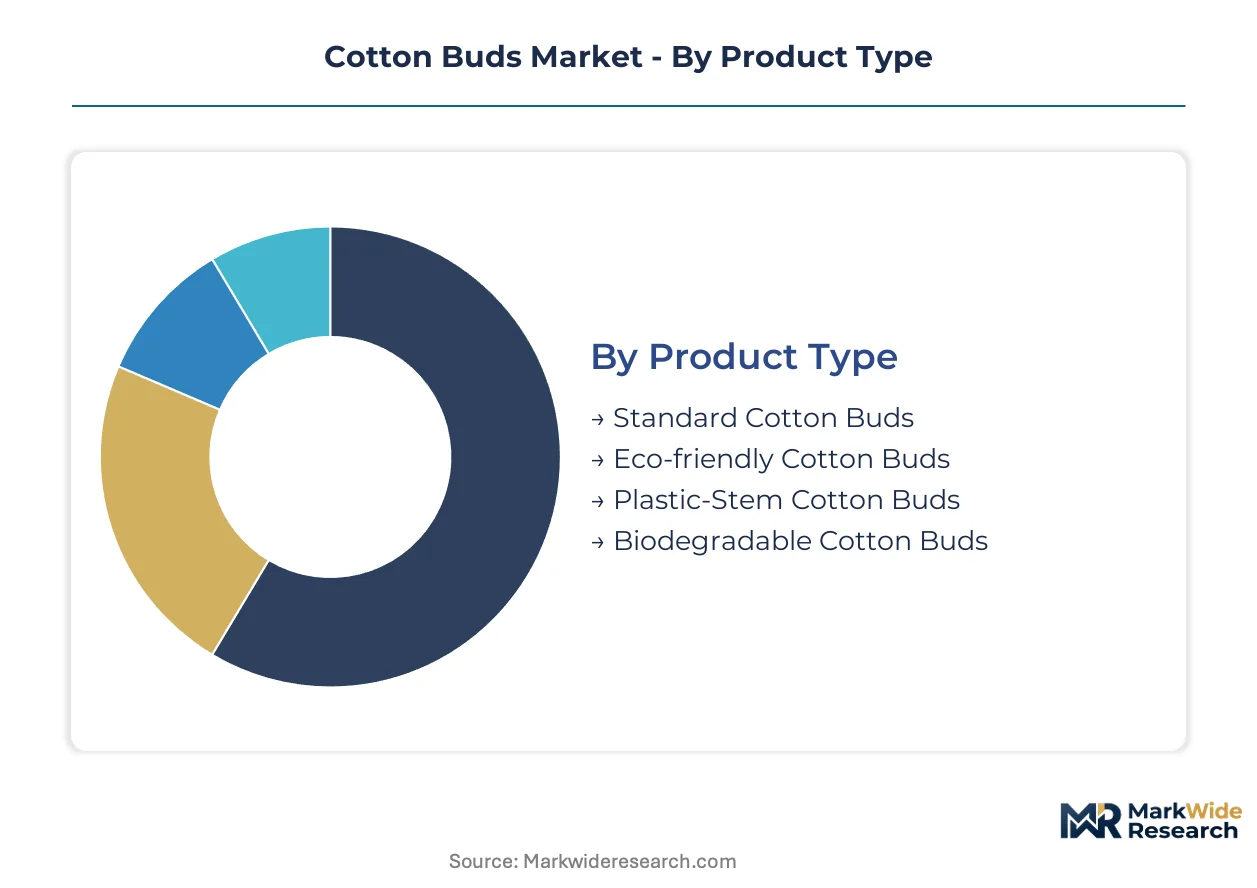
Cotton bud manufacturers face divergent technical requirements across regulatory jurisdictions, with EU plastic bans, FDA medical standards, and REACH chemical compliance each dictating distinct product specifications. Segmentation reveals how material choices and channel strategies align with these compliance boundaries rather than pure consumer preference.
Product Type:
REACH chemical compliance and the EU Single-Use Plastics Directive create tiered certification burdens that segment manufacturers by their testing capabilities and material sourcing relationships.
- Eco-friendly Cotton Buds:Paper and bamboo stems bonded with plant-derived adhesives meet ECHA substance restrictions for European pharmacy placement. German retailers now mandate full SKU conversion to these variants, compressing timelines for legacy producers dependent on petrochemical supply chains.
- Biodegradable Cotton Buds:Certified compostable formulations carry OK Compost or TÜV Austria industrial/home certification, commanding placement premiums in French and Italian chains with earlier national implementation deadlines than baseline EU requirements. Adhesive biocompatibility testing under EMA protocols extends development cycles substantially.
- Standard Cotton Buds:Conventional cotton-wrapped plastic stems retain volume in non-EU markets without single-use plastic prohibitions.
- Plastic-Stem Cotton Buds:Polypropylene and polystyrene constructions face phased withdrawal from EU member state shelves; residual demand concentrates in export markets with less stringent material regulations.
Standard cotton buds handle the majority of throughput; biodegradable variants are expanding most quickly on share.
Application:
End-use specifications separate markets by sterilization requirements, with medical applications demanding documented process controls that filter out uncertified competitors.
- Medical Use:Sterilized cotton buds for wound care and clinical procedures carry FDA 510(k) clearance or CE marking under EU MDR, with ISO 9001 documentation mandatory for NHS and German hospital procurement consortiums. Egyptian and Turkish organic cotton sourcing satisfies pesticide-free fiber requirements for premium pricing tiers.
- Personal Care:Daily hygiene applications drive volume through pharmacy chains where ISO 9001-certified products secure preferred shelf placement against uncertified alternatives. Unilever and Johnson & Johnson leverage pharmaceutical heritage and brand recognition respectively to dominate this channel.
- Household Cleaning:Precision cleaning tasks in electronics and automotive maintenance favor standard plastic-stem durability where regulatory bans do not apply.
- Arts & Crafts:Hobby and educational supply segments prioritize cost efficiency over material certification, sourcing through bulk channels.
Personal care generates the highest unit volumes; medical use captures the steepest margin expansion trajectory.
Packaging Type:
Channel economics and shelf-life requirements determine packaging selection, with pharmacy and supermarket formats imposing distinct structural and labeling standards.
- Box Packaging:Rigid cardboard constructions with tamper-evident seals satisfy pharmacy chain requirements for contamination protection and retail display integrity. Swedish and Finnish kraft paper mills supply food-grade substrates suitable for stem and packaging integration.
- Tube Packaging:Cylindrical dispensers reduce shelf footprint and support premium positioning in personal care aisles, though material transitions from plastic to paperboard tubes lag stem conversion timelines.
- Bag Packaging:Flexible pouches minimize unit shipping costs for high-volume retail replenishment.
- Bulk Packaging:Institutional formats serve medical and industrial procurement with cost-optimized per-unit economics.
Box packaging dominates pharmacy throughput; tube formats are climbing fastest in supermarket personal care sets.
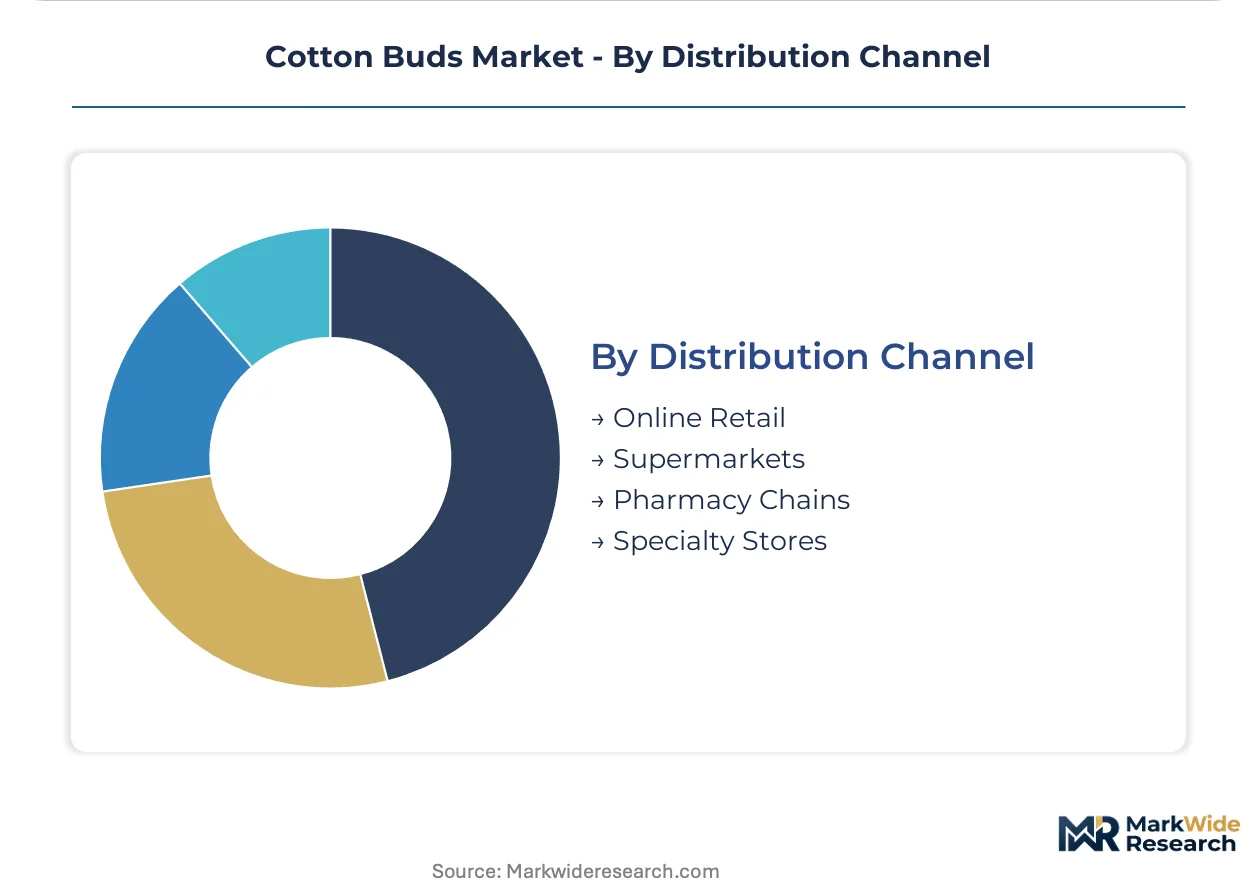
Distribution Channel:
Procurement centralization in healthcare systems and platform consolidation in e-commerce are restructuring traditional wholesale relationships.
- Pharmacy Chains:Centralized purchasing authorities in Germany, France, and the United Kingdom now require ISO 9001 documentation as mandatory bid qualifications, displacing fragmented distributor networks with direct manufacturer contracts. Three-year sterilized product agreements lock in supply relationships.
- Online Retail:Amazon and specialized health platforms enable subscription-based personal care bundles that bypass traditional retail markups, with CSRD-aligned supply chain documentation serving as a differentiation tool for certified organic producers.
- Supermarkets:Mass-market shelf placement rewards brand recognition and volume scale, with Unilever competing on retail dominance.
- Specialty Stores:Niche beauty and craft retailers serve segments prioritizing material provenance or specific technical properties.
Pharmacy chains control the largest share of certified product flow; online retail is gaining share fastest through subscription mechanics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam anchors European supply chain integration for cotton bud manufacturers sourcing bamboo from Guangdong and organic cotton from Egyptian agricultural networks.
Germany
Pharmacy chain consolidation in Berlin and Hamburg drives demand for ISO 9001-certified biodegradable variants. The Bundesamt für Verbraucherschutz und Lebensmittelsicherheit enforces early national implementation of EU Single-Use Plastics Directive deadlines. North Rhine-Westphalia hosts specialized paper mills supplying food-grade kraft substrates for stem production.
France
Hospital procurement consortiums in Paris and Lyon prioritize CE-marked medical-grade cotton buds with REACH-compliant organic cotton sourcing. ANSM mandates stricter biocompatibility documentation than baseline EU requirements. The Île-de-France region concentrates sterilization facilities serving domestic and export markets.
United Kingdom
NHS supply frameworks in London and Manchester require three-year sterilized product agreements with documented process controls. The Environment Agency enforces plastic stem prohibitions ahead of minimum EU timelines. The Midlands cluster houses legacy manufacturers retrofitting production lines for paper and bamboo feedstocks.
United States
FDA 510(k) clearance requirements for wound care applications sustain premium pricing tiers in Boston and New York medical corridors. EPA oversight of adhesive formulations shapes plant-based binding agent development cycles. The Southeast textile belt processes Egyptian and Turkish organic cotton for clinical-grade fiber specifications.
China
Bamboo harvest networks in Guangdong and Fujian provinces supply stem raw materials facing climate-related yield fluctuations. NMPA registration requirements for medical-grade exports filter manufacturer participation in hospital procurement systems. The Pearl River Delta concentrates extrusion equipment retrofitting capabilities for paper and bamboo handling.
Cotton Buds Market Key Industry Players
Listed leaders compete with private specialists across certification tiers and channel access. The vendor base stratifies between pharmaceutical heritage conglomerates, specialized organic cotton processors, and regional bamboo stem fabricators. Three archetypes dominate: ISO-certified pharmacy suppliers, vertically integrated fiber processors, and mass-market brand licensors. Competitive moves concentrate on production line retrofitting for biodegradable materials and direct contracting with centralized hospital procurement authorities.
Among diversified consumer health conglomerates, Johnson & Johnson and Unilever occupy positions spanning pharmacy and mass-market channels. Groupe Lemoine represents the specialized organic sourcing archetype with European agricultural network integration. These three exemplify how certification depth and channel relationships determine shelf access under tightening regulatory timelines.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Unilever |
| Groupe Lemoine |
| Jieyang Top-Tip's Daily Use Products |
| Sanyo Co., Ltd. |
| Dongguan David Health Products |
| Organyc Italia |
| Kimberly-Clark Corporation |
| Essity AB |
| Others |
Cost & Logistics Intelligence
Minimum efficient scale in cotton bud manufacturing sits below 50 million units annually, creating fragmented capacity utilization that compresses price floors and concentrates supply relationships among three Swedish and Finnish paper mills controlling food-grade kraft substrates. This scale dynamic forces smaller producers into spot purchasing while ISO 9001-certified manufacturers lock multi-year contracts with German pharmacy chains, embedding cost advantages that resist price erosion.
Pricing Analysis
Volume-discount tiering structures separate hospital procurement consortiums from pharmacy spot buyers, with three-year sterilized product agreements commanding 15-20% unit cost reductions against fragmented distributor pricing. Certification grade and brand heritage drive differentiation between Johnson & Johnson pharmaceutical positioning and mass-market Unilever shelf dominance. Cost compression in biodegradable variants intensifies as bamboo harvest volatility in Guangdong transmits directly to stem pricing. Arts and craft bulk channels exhibit highest price sensitivity, while NHS frameworks prioritize compliance documentation over unit economics.
Supply Chain Analysis
Strategic stockpiling of Egyptian and Turkish organic cotton dominates medical-grade sourcing, with just-in-time preferences limited to non-certified personal care segments where shelf-life constraints are minimal. Raw material dependencies center on Guangdong bamboo networks, Swedish kraft paper mills, and specialized organic cotton agricultural cooperatives. Single-source vulnerability concentrates in Nordic paper substrate supply, with three mills controlling food-grade certification required for EU pharmacy placement. Distribution runs through Rotterdam port integration for Asian bamboo feedstocks, then fragments across direct manufacturer contracts with German hospital procurement authorities and traditional wholesale relationships in mass-market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Single-Use Plastics Directive has triggered material transition disruption that compounds competitive advantage for certified producers while filtering legacy petrochemical-dependent manufacturers from pharmacy access. This regulatory inflection compresses adaptation windows to 24-36 months for production line retrofitting.
For Market Incumbents: Compound certification depth into channel lock-in by accelerating ISO 9001 documentation for NHS and German hospital procurement frameworks before three-year sterilization agreements solidify. Secure captive supply of food-grade kraft paper from Swedish and Finnish mills through equity stakes or long-term offtake, insulating against single-source vulnerability as bamboo stem adoption accelerates. Threat: Emerging bamboo processors in Guangdong bypassing European adhesive certification timelines through NMPA-registered export pathways. For New Entrants and Emerging Players: Subscription-based personal care bundles on Amazon and specialized health platforms represent the most penetrable service-layer gap, where incumbents under-serve direct-to-consumer documentation transparency demanded by CSRD-aligned buyers. Target Italian and French pharmacy chains with earlier national plastic ban deadlines than baseline EU requirements, where certified biodegradable variants command placement premiums. Go-to-market angle: OK Compost or TÜV Austria certification as subscription bundle anchor, bypassing retail shelf competition entirely. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated fiber processors with Egyptian organic cotton sourcing and in-house bamboo stem fabrication capabilities, where subscription mechanics and hospital procurement contracts stabilize cash flow quality across economic cycles. Long-term viability favors acquisition targets with completed production line retrofitting for paper and bamboo feedstocks, avoiding capital-intensive modification risk. Signal to watch: EMA biocompatibility testing completion timelines for plant-based adhesives, which compress or extend competitive entry windows by 12-18 months.| Strategic Initiative | Industry Significance |
|---|---|
| Production Line Retrofitting | Legacy plastic extrusion equipment modification for bamboo and paper feedstocks determines EU pharmacy shelf access under Single-Use Plastics Directive enforcement. |
| Organic Cotton Sourcing Integration | Backward integration into Egyptian and Turkish agricultural networks secures pesticide-free fiber supply for REACH-compliant medical-grade premium tiers. |
| CE Marking Pathway Investment | EU MDR sterilization documentation opens German and French hospital procurement consortiums to three-year exclusive supply agreements. |
| Direct-to-Consumer Platform Launch | Amazon and health platform subscriptions bypass retail markups while leveraging CSRD-aligned supply chain transparency as differentiation. |
| Adhesive Biocompatibility Certification | EMA and FDA testing completion for plant-based binding agents determines competitive positioning in medical-grade segments. |
Research Approach
Operator-level perspectives from cotton bud manufacturing plant managers, pharmacy chain category buyers, hospital procurement committee members, and organic cotton agricultural cooperative directors anchored the qualitative base. Primary interviews combined with secondary validation from FDA 510(k) filings, EMA medical device registrations, EU customs trade data on bamboo and kraft paper imports, and REACH substance restriction databases. Bottom-up unit economics modeling triangulated against top-down category spend analysis across German, French, and UK pharmacy channels.
Sensitivity analysis tested forecast outputs against alternative scenarios for EU national plastic ban implementation timelines, bamboo yield volatility in Guangdong, and adhesive certification completion rates. Segmentation dimensions modeled included product type tier, application end-use, packaging format, and distribution channel concentration. CAGRs derived from regression analysis of historical volume trajectories adjusted for regulatory inflection points, with forecast inputs incorporating hospital procurement centralization rates and e-commerce subscription penetration curves.
Forecasts assume regulatory continuity in EU Single-Use Plastics Directive enforcement and FDA medical device oversight; material policy shifts would require re-modeling. Revision becomes warranted when bamboo harvest disruptions in Guangdong or kraft paper mill capacity constraints cross thresholds that invalidate supply cost assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Grooming Products
Personal Hygiene Market
Personal Grooming Products
Electric Hair Brush Market
Personal Grooming Products
Military Hydration Products Market
Personal Grooming Products
Smart Water Bottle Market
Personal Grooming Products
Global Organic and Natural Feminine Care Market
Personal Grooming Products
Tattoo Accessories Market
Personal Grooming Products
Electric Tooth Polisher Market
Personal Grooming Products
Smart Bathroom Scale Market
Personal Grooming Products
Biometric Vaporizer Market
Personal Grooming Products
Electric Toothbrush Market
Personal Grooming Products
Epilators Market
Personal Grooming Products
Global Massage Guns Market
Personal Grooming Products
Horsehair Clippers Market
Personal Grooming Products
Global Canes and Walking Sticks Market
Personal Grooming Products
Hair Scissors Market
Personal Grooming Products
Global Aligner Sheet Market