
 Europe Agricultural Robot Market | 2026-2036
Europe Agricultural Robot Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Agricultural Robot Market Intelligence
Autonomous precision tiers is rotating the Europe agricultural robot market toward higher-value deployments. John Deere leverages its embedded sensor networks to anchor large-arable automation across Germany and Poland. Naïo Technologies specializes in compact electric weeding platforms that navigate narrow vineyard rows in France and Italy. Lely sustains its dominance in dairy farm robotics through integrated herd management software that controls milking workflow scheduling.
Europe agricultural robots encompass self-propelled electromechanical systems equipped with GNSS guidance, LiDAR obstacle detection, and variable-rate actuators for field-level crop intervention. These machines execute seeding, spraying, cultivation, and harvest tasks with sub-centimeter positional accuracy to reduce input waste and manual labor dependency. Robotic tractors and weeding robots capture the dominant installed base, while drone sprayers represent the fastest-expanding product category as aerial application bypasses soil compaction constraints. Machine learning and computer vision segments command premium positioning through real-time crop-health classification algorithms that differentiate treatment zones without human intervention.
EMA guidelines on agricultural machinery safety certification, REACH compliance for battery chemistries, and the EU AI Act's risk classification for autonomous decision systems collectively shape product development timelines and market access conditions for equipment suppliers. The EU Green Deal's pesticide reduction mandates directly accelerate demand for mechanical weeding and precision spraying platforms that eliminate blanket chemical application. Stakeholders must monitor how the EU AI Act's evolving enforcement thresholds for autonomous agricultural equipment will reshape R&D allocation between hardware manufacturers and software providers.
Market Dynamics
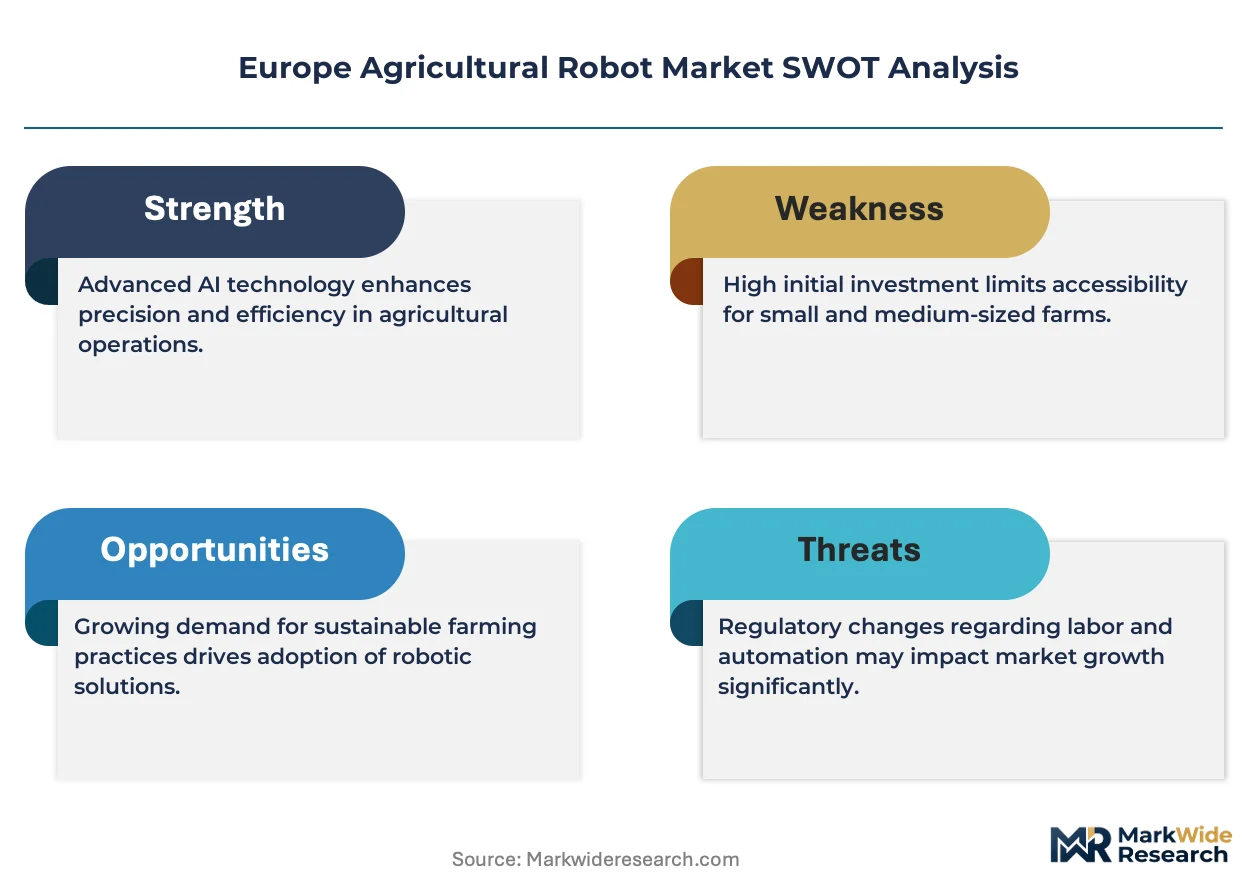
The EU Green Deal's pesticide reduction mandates are compressing deployment timelines for mechanical weeding and precision spraying platforms across European farmland. Vineyard operators in France and Spain now face binding chemical reduction targets that autonomous harvesters and electric weeders can satisfy.
Growth Catalysts
- Farm to Fork pesticide mandates:The EU Green Deal tightens chemical reduction targets, forcing growers toward precision weeding robots that eliminate blanket spraying.
- Seasonal labor shortages:Vineyard and orchard operators across France, Spain, and Italy cannot source sufficient manual harvest labor, accelerating autonomous picker procurement.
- GNSS-RTK accuracy gains:Real-time kinematic positioning now delivers sub-centimeter guidance precision, enabling robotic cultivation in narrow row crops previously deemed too complex.
Market Restraints
- Lithium-ion battery cost volatility:REACH compliance for battery chemistries adds certification overhead and raw material uncertainty to electric platform economics.
- CE marking complexity:EMA machinery safety guidelines and the EU AI Act's risk classification for autonomous systems extend product development timelines by 12-18 months.
- Specialized maintenance infrastructure:Rural repair networks lack technicians trained in LiDAR calibration and hydraulic actuator diagnostics, limiting fleet uptime.
Strategic Opportunities
- Polish arable automation:Large-scale grain operations in Poland remain underpenetrated by robotic tractors, presenting first-mover expansion potential for sensor-integrated platforms.
- Greenhouse robotics convergence:Netherlands-based growers are integrating computer vision with climate control systems, creating demand for multi-function robotic platforms.
- EU AI Act enforcement thresholds:Evolving risk classifications for autonomous agricultural equipment will reshape R&D allocation toward software providers capable of compliance documentation.
Industry Challenges
- Field technician scarcity:Agricultural robotics deployment requires mechatronics specialists who can troubleshoot GNSS drift, sensor fusion errors, and hydraulic failures in remote locations.
- Legacy equipment integration:Mixed fleets of conventional tractors and autonomous units create workflow scheduling conflicts that farm management software must resolve.
- CSRD reporting alignment:Sustainability disclosure requirements demand carbon footprint tracking across robotic equipment lifecycles, complicating procurement decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Agricultural Robot Market |
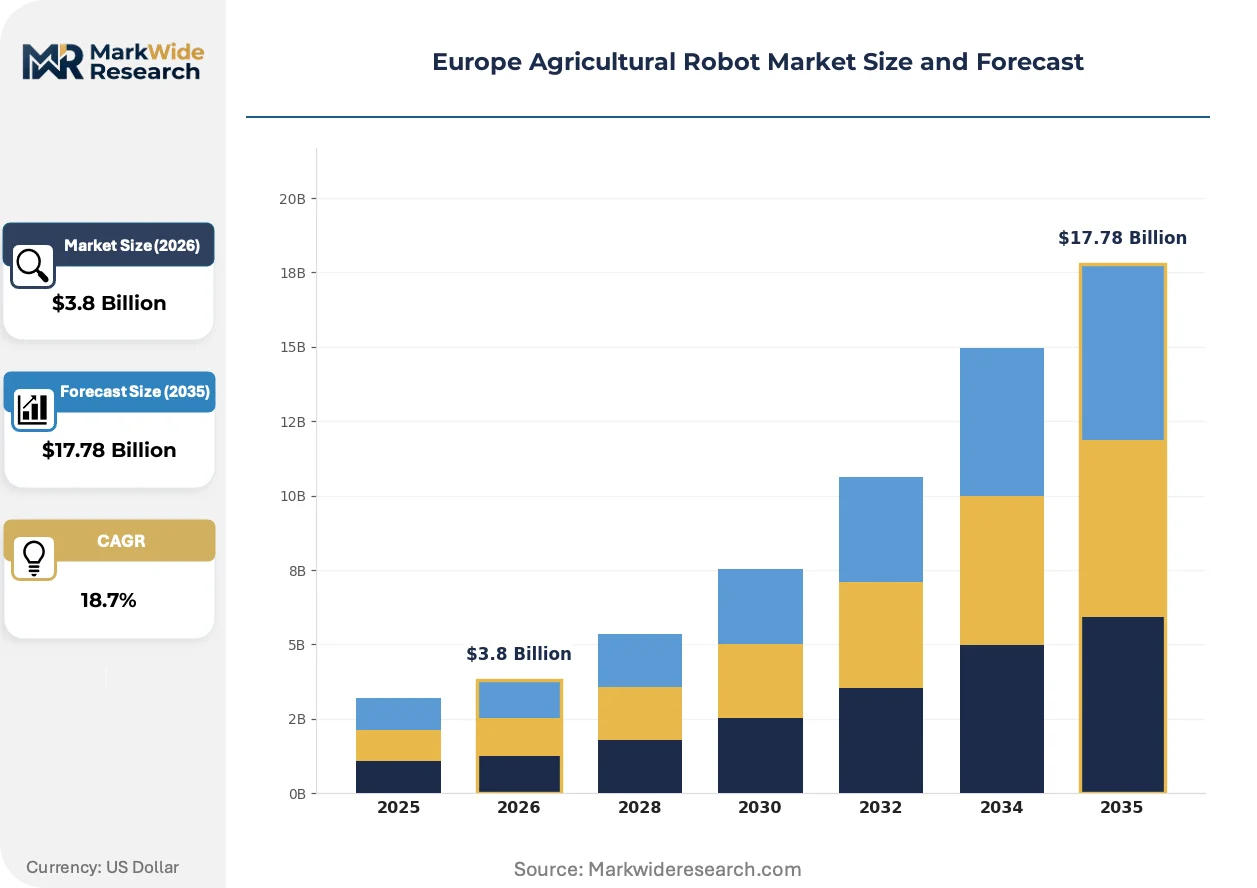
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.78 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Autonomous Navigation, Machine Learning, Computer Vision, IoT Integration Application: Crop Harvesting, Soil Analysis, Irrigation Management, Pest Control End User: Farmers, Agricultural Cooperatives, Research Institutions, Commercial Growers Product Type: Robotic Tractors, Drone Sprayers, Harvesting Robots, Weeding Robots |
| Companies Covered | John Deere, CNH Industrial, AGCO Corporation, Trimble Inc., Lely, DeLaval, CLAAS, GEA Group, Naïo Technologies, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Agricultural Robot Market Strategic Shifts & Innovations
Computer vision and machine learning are compressing decision cycles for crop intervention, enabling real-time differentiation between weeds and cash crops without human verification. Three developments are accelerating this transformation.
Vision-guided mechanical weeding is displacing chemical herbicide programs in row-crop operations. These systems use convolutional neural networks to identify plant species at seedling stage and trigger precision hoeing tools. Dutch vegetable growers and French viticulturists are deploying units at scale during the 2024-2025 growing seasons. The technology is displacing blanket spraying contracts and reshaping input supplier relationships across the value chain.
The EU AI Act's risk-based classification for autonomous decision systems is tightening compliance requirements for agricultural equipment. Machinery exceeding defined autonomy thresholds must undergo conformity assessment procedures that documentation-heavy manufacturers navigate more readily than hardware-focused entrants. Vineyard robotics platforms with real-time path replanning capabilities face the most stringent scrutiny, pushing developers toward Brussels-based regulatory consulting partnerships.
Service-based equipment access is fragmenting traditional ownership models in capital-intensive segments. Dutch greenhouse operators now lease robotic harvesting arms through output-linked contracts rather than purchasing outright. Equipment financiers in Germany and Denmark are structuring per-hectare pricing agreements that transfer operational risk to technology providers. This shift concentrates most visibly in controlled-environment agriculture where yield predictability supports performance guarantees.
Europe Agricultural Robot Market Segmentation
Technology-application-product combinations in European agricultural robotics face divergent compliance pathways under the EU AI Act and EMA machinery directives. Segmentation reveals where regulatory burden concentrates and which configurations unlock subsidy eligibility under Farm to Fork implementation frameworks.
Technology:
EMA safety certification thresholds and EU AI Act risk tiers stratify development timelines across these four technology bases.
- Autonomous Navigation:GNSS-RTK and LiDAR-based path planning systems deliver sub-centimeter field positioning. Vineyard operators in France and Spain deploy these platforms for narrow-row cultivation where manual steering fails. CE marking complexity extends product launches by 12-18 months.
- Machine Learning:Real-time crop-health classification algorithms differentiate treatment zones without human verification. Dutch greenhouse growers integrate these systems with climate control infrastructure. The EU AI Act's high-risk classification for autonomous decision systems imposes documentation burdens that favor established software providers.
- Computer Vision:Convolutional neural networks identify plant species at seedling stage for mechanical weeding.
- IoT Integration:Sensor networks connecting field equipment to farm management software platforms.
Autonomous Navigation handles the majority of throughput; Machine Learning is expanding most quickly on share.
Application:
End-use concentration patterns in France, Spain, and the Netherlands determine which applications command R&D priority.
- Crop Harvesting:Autonomous pickers address seasonal labor shortages in French viticulture and Spanish citrus operations. Binding chemical reduction targets under Farm to Fork accelerate procurement of precision harvesters that minimize crop damage.
- Pest Control:Precision spraying platforms eliminate blanket chemical application through variable-rate actuators. German arable farms deploy these systems to meet EU Green Deal pesticide mandates.
- Soil Analysis:Robotic soil sampling with automated laboratory integration.
- Irrigation Management:Sensor-guided water distribution systems for drought-prone Mediterranean regions.
Crop Harvesting dominates current deployment volumes; Pest Control is gaining share fastest as regulatory pressure intensifies.
End User:
Procurement scale and subsidy access differentiate these four customer categories across European member states.
- Farmers:Individual owner-operators in Poland and Germany purchase compact electric weeding platforms through national agricultural modernization funds. Limited technical support infrastructure in rural areas constrains fleet uptime.
- Agricultural Cooperatives:Shared-equipment models in France and Italy spread capital costs across multiple vineyard holdings. These entities negotiate volume discounts with manufacturers and maintain in-house technician training programs.
- Research Institutions:Universities and agricultural extension services pilot next-generation robotics before commercial release.
- Commercial Growers:Large-scale greenhouse operators in the Netherlands lease robotic systems through output-linked contracts.
Agricultural Cooperatives manage the largest equipment pools; Commercial Growers are climbing the fastest as service-based access models fragment traditional ownership.
Product Type:
Physical platform configurations face distinct REACH compliance requirements for battery chemistries and EMA safety certification protocols.
- Robotic Tractors:Self-propelled electromechanical systems with variable-rate actuators for seeding and cultivation. Polish grain operations remain underpenetrated, presenting first-mover expansion potential for sensor-integrated platforms.
- Drone Sprayers:Aerial application systems bypass soil compaction constraints in fragile vineyard soils. French and Italian regulators are developing specific flight authorization frameworks for autonomous agricultural UAVs.
- Harvesting Robots:Articulated arms with computer vision for selective fruit and vegetable picking.
- Weeding Robots:Compact electric platforms navigating narrow crop rows for mechanical weed control.
Robotic Tractors carry the heaviest installed base; Drone Sprayers show the steepest expansion trajectory as aerial platforms gain regulatory clarity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment manufacturing clusters concentrate in Germany and the Netherlands, while deployment intensity peaks in French viticulture and Dutch greenhouse corridors. Regulatory pressure from the EU Green Deal and Farm to Fork strategy drives adoption patterns unevenly across member states.
Germany
Large-arable grain operations in Lower Saxony and Brandenburg deploy sensor-integrated robotic tractors for precision cultivation. CE marking requirements under EMA machinery safety guidelines extend certification timelines for domestic manufacturers. Munich-based automation firms supply GNSS-RTK guidance systems to Polish and Czech farm operators expanding eastward.
France
Vineyard operators in Bordeaux and Burgundy face binding chemical reduction targets that accelerate procurement of electric weeding robots and autonomous harvesters. ANSM and CNIL guidance on autonomous data collection shapes compliance protocols for field robotics. Naïo Technologies anchors development activity in Toulouse, supplying compact platforms to Italian and Spanish growers.
Netherlands
Greenhouse operators in Westland and North Brabant integrate computer vision systems with climate control infrastructure for robotic harvesting workflows. REACH compliance for battery chemistries dominates supplier qualification processes for electric platform vendors. Wageningen University research partnerships accelerate commercialization of multi-function robotic arms through output-linked leasing contracts.
Spain
Citrus and olive growers in Andalusia and Valencia deploy autonomous pickers to address seasonal labor shortages intensified by demographic shifts. Spanish agricultural modernization funds subsidize precision spraying platforms that satisfy EU Green Deal pesticide mandates. Barcelona-based robotics startups partner with French manufacturers for cross-border technician training programs.
Poland
Large-scale grain operations in Greater Poland and Lower Silesia remain underpenetrated by robotic tractors, presenting expansion opportunity for sensor-integrated platforms. National agricultural modernization funds finance compact electric weeding equipment for diversified farms. Poznań equipment distributors build maintenance networks to address rural technician scarcity constraining fleet uptime.
Europe Agricultural Robot Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the European agricultural robot market. The vendor base stratifies between diversified machinery conglomerates with embedded sensor networks and specialized electric platform developers focused on narrow-row applications. Two strategic archetypes dominate: integrated full-line suppliers controlling milking workflow scheduling and vineyard robotics, and compact equipment specialists navigating regulatory compliance for autonomous weeding. Competitive moves concentrate on strategic partnerships with Brussels-based regulatory consultants and geographic expansion into underpenetrated arable markets.
Among diversified machinery manufacturers, John Deere and CNH Industrial exemplify the integrated full-line archetype with embedded automation capabilities across large-arable segments. Naïo Technologies occupies a specialist position within the compact electric platform tier, representing the vineyard and narrow-row robotics segment where regulatory compliance documentation requirements favor focused developers over hardware-generalists.
| Leading Market Players |
|---|
| John Deere |
| CNH Industrial |
| AGCO Corporation |
| Trimble Inc. |
| Lely |
| DeLaval |
| CLAAS |
| GEA Group |
| Naïo Technologies |
| Others |
Cost & Logistics Intelligence
Output-linked equipment leasing contracts now dominate procurement for Dutch greenhouse operators, locking in multi-year supply access while transferring operational risk to technology providers. This contract structure anchors price visibility across the Europe agricultural robot market, particularly where Farm to Fork subsidy eligibility depends on vendor qualification status.
Pricing Analysis
The EU AI Act dictates the pricing tier structure across autonomous navigation platforms, separating high-risk classification systems requiring extensive documentation from lower-tier equipment. CE marking complexity and REACH battery compliance create premium-mid-economy pricing differentiation based on certification burden. Cost compression in compact electric weeding platforms is intensifying because Naïo Technologies and similar specialists compete on acquisition cost. Agricultural cooperatives exhibit highest price sensitivity due to shared-equipment cost distribution, while commercial greenhouse operators accept premium pricing for output-linked performance guarantees.
Supply Chain Analysis
Inventory cycles for LiDAR sensors and GNSS-RTK modules now stretch 16-20 weeks, constraining assembly schedules for German and Dutch manufacturers. Component sourcing draws from Taiwan for precision optics, South Korea for battery cells, and Germany for hydraulic actuators. Single-source vulnerability concentrates in solid-state LiDAR emitters where automotive demand competes for foundry capacity. Distribution runs through Poznań and Munich equipment distributors serving Polish arable farms and French viticulture cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across EU member states creates niche opportunities for compliance-specialized entrants. Farm to Fork implementation variance between France, Spain, and Poland fragments addressable demand into distinct procurement clusters.
For Market Incumbents: Secure Brussels-based regulatory consulting partnerships to navigate evolving EU AI Act enforcement thresholds for autonomous path replanning capabilities. John Deere and CNH Industrial should anchor large-arable automation in Poland through technician training networks addressing rural maintenance infrastructure gaps. Vertical integration into LiDAR calibration services defends against emerging platform-agnostic service providers. For New Entrants and Emerging Players: Technician training and aftermarket service gaps in rural France and Spain present immediate white-space targets where incumbents under-serve vineyard cooperatives. Polish grain operations remain the most penetrable geography for first-mover robotic tractor deployment. A go-to-market angle anchored in output-linked leasing contracts aligns with Dutch greenhouse procurement patterns spreading southward. For Investors and Strategic Acquirers: Compact electric platform developers with documented EU AI Act compliance pathways represent the highest-conviction acquisition archetype for portfolio exposure to mechanical weeding acceleration. Long-term viability hinges on software-enabled recurring revenue attachment rather than hardware transaction margins. Watch for ANSM guidance clarifications on autonomous data collection protocols as the inflection signal for French market access timing.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Consulting Partnership | Brussels-based compliance documentation accelerates CE marking timelines for vineyard robotics platforms. |
| Technician Training Network Expansion | Poznań and Toulouse service hubs address rural LiDAR calibration scarcity constraining Polish fleet uptime. |
| Output-Linked Leasing Structure | Per-hectare pricing agreements align Dutch greenhouse procurement models with Mediterranean grower risk profiles. |
| Software-Defined Autonomy Investment | Real-time path replanning capabilities trigger EU AI Act high-risk classification requiring conformity assessment. |
| Backward Integration into Sensor Supply | Captive GNSS-RTK module sourcing insulates German manufacturers from Taiwan optics lead-time volatility. |
Research Approach
A spread of perspectives from vineyard operators in Bordeaux, greenhouse managers in Westland, Polish grain cooperative procurement leads, and EMA machinery safety officers converged on the working assumptions governing deployment timelines. Primary interviews with these stakeholders combined with secondary validation from EU Green Deal implementation reports, REACH battery chemistry filings, and national agricultural modernization fund disbursement records. Bottom-up equipment shipment tracking and top-down subsidy allocation analysis triangulated market sizing across the projection horizon.
Segmentation dimensions modeled span technology base, application type, end-user category, and product configuration across the analysis window. CAGRs derive from equipment replacement cycle analysis, subsidy eligibility phase-ins, and regulatory compliance cost trajectories. Industry-specific forecast inputs include Farm to Fork pesticide reduction mandate enforcement schedules and EU AI Act risk classification threshold evolution.
Underlying assumptions cover subsidy continuity, battery chemistry cost trajectories, and GNSS-RTK accuracy gains, with deviation risk concentrated in EU AI Act enforcement timing and rural technician training program scale-up. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Global Wafer Handling Robots Market
Robotics and Automation
Asia-Pacific Logistics Robotics Market
Robotics and Automation
High-Precision Truss Robot Market
Robotics and Automation
Global Medical Robotic Systems Market
Robotics and Automation
North America Automated Guided Vehicle (AGV) Market
Robotics and Automation
Humanoid Robot Market
Robotics and Automation
Underwater Exploration Robots Market
Robotics and Automation
Smart Remote Control Market
Robotics and Automation
Nanorobotics Market
Robotics and Automation
Simultaneous Localization and Mapping (SLAM) Technology Market
Robotics and Automation
Professional Service Robots Market
Robotics and Automation
Social Robots Market
Robotics and Automation
Asia Pacific Warehouse Robotics Market
Robotics and Automation
LAMEA Demolition Robot Market
Robotics and Automation
Tool Tethering Market
Robotics and Automation
Hospitality Robots Market