
 Italy Kitchen Appliances Market | 2026-2036
Italy Kitchen Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Kitchen Appliances Market Foresight
Premium energy-efficiency certification tiers is rotating demand toward A+++ and beyond-rated equipment across Italian households. Whirlpool leverages its Cassinetta manufacturing complex to sustain domestic production scale for built-in refrigeration lines. Smeg Appliance Company anchors its competitive position through design-forward positioning in the premium cooker segment. De'Longhi differentiates via specialization in compact appliance categories where Italian export strength runs deepest.
Italy kitchen appliances encompass electrically powered domestic and semi-commercial equipment designed for food storage, preparation, cooking, and cleaning, typically operating at 220-240V/50Hz with energy efficiency indices measured under EU standardized test cycles. Refrigerators and ovens command the largest installed base, though smart appliance configurations are expanding fastest as connectivity modules become standard in mid-tier pricing bands. Energy efficient technology segments carry disproportionate margin pools due to Italian consumer willingness to pay for operating cost reduction and EU Ecodesign compliance requirements. Distribution through specialty stores retains structural importance for high-consideration purchases, while online retail channels are capturing replacement-cycle volume in established product categories.
Italy's AEEE national compliance scheme for WEEE directives shapes manufacturer obligations for collection and recycling, while EU Ecodesign regulations administered through the Ministry of Enterprise and Made in Italy mandate minimum efficiency thresholds that filter non-compliant imports from Eastern European supply sources. CE marking requirements under EU appliance safety directives create baseline product standards that domestic manufacturers embed earlier in development cycles than some import competitors. Stakeholders must monitor how Italy's transposition of pending EU right-to-repair legislation reshapes spare parts availability obligations and aftermarket service economics.
Market Dynamics
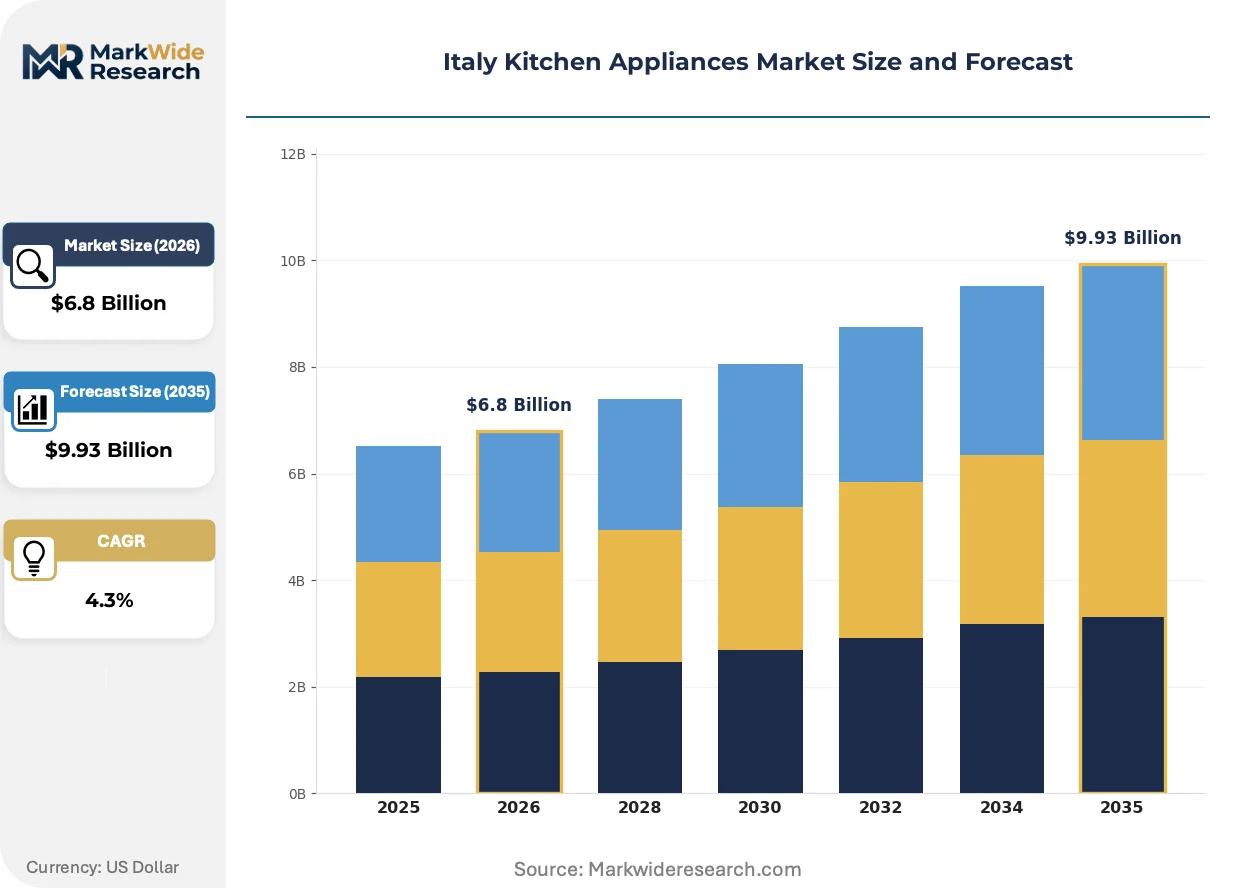
Italy's National Recovery and Resilience Plan disbursements for residential energy efficiency are compressing appliance replacement cycles from ten-year norms toward seven-year intervals, pulling forward demand for A+++ certified equipment.
Growth Catalysts
- EU Ecodesign mandates:Minimum efficiency thresholds under transposed directives are filtering non-compliant imports from Eastern European supply sources, expanding addressable market share for certified domestic manufacturers.
- Smart module integration:Wi-Fi and Bluetooth connectivity hardware is becoming standard in mid-tier refrigerator and oven configurations, enabling remote diagnostics and energy optimization that commands price premiums.
- Milan-Rome renovation corridor:Residential refurbishment activity across these metropolitan clusters is pulling demand toward premium built-in kitchen configurations with integrated appliance suites.
Market Restraints
- Copper and steel input volatility:Raw material cost swings for compressor housings and oven cavities compress margin predictability for manufacturers without long-term supply agreements.
- Component supply concentration:Compressor and control module sourcing clusters in Southeast Asia create vulnerability to logistics disruptions affecting finished goods assembly timelines.
- Technical limitation of legacy housing stock:Pre-1990s Italian residential electrical infrastructure lacks capacity for simultaneous operation of multiple high-draw induction cooking zones.
Strategic Opportunities
- Southern Italy underpenetration:Naples and Palermo metropolitan zones exhibit lower smart appliance penetration rates than northern industrial corridors, presenting white-space expansion potential.
- Right-to-repair regulatory tailwind:Pending EU legislation mandating spare parts availability will reshape aftermarket service economics and create authorized repair network opportunities.
- Channel convergence:Hybrid showroom-digital purchase journeys are emerging where consumers configure appliances in specialty stores then complete transactions through manufacturer-direct portals.
Industry Challenges
- Embedded software certification timelines:Smart appliance connectivity modules require CE marking under EU radio equipment directives, extending product launch cycles by four to six months.
- Skill scarcity in IoT integration:Domestic appliance engineering talent pools lack depth in cloud architecture and cybersecurity protocols required for connected product development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Kitchen Appliances Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $9.93 Billion |
| CAGR (2026 – 2036) | 4.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Ovens, Dishwashers, Microwaves End User: Households, Restaurants, Cafes, Catering Services Technology: Smart Appliances, Energy Efficient, Traditional, Hybrid Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Whirlpool, AEG, Siemens, Samsung Electronics, De'Longhi, Smeg Appliance Company, Electrolux, Signature Kitchen Suites, Bosch, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Kitchen Appliances Market Shifts & Advancements
Connectivity hardware, energy efficiency certification tiers, and distribution channel hybridization are the three forces actively restructuring competitive positioning and margin capture mechanisms across Italian kitchen appliance supply.
Induction cooking technology is displacing gas burner configurations in new residential construction and major renovation projects. Northern Italian households in Turin and Bologna industrial corridors are adopting induction hobs at rates outpacing national averages by substantial margins. This shift is displacing traditional gas infrastructure dependencies and enabling all-electric kitchen suites that align with municipal decarbonization targets.
Italy's transposition of EU Ecodesign regulations through the Ministry of Enterprise and Made in Italy is mandating minimum efficiency thresholds that escalate on preset schedules. Domestic manufacturers are embedding compliance testing earlier in development cycles than import competitors, compressing time-to-certification advantages. Built-in refrigeration lines face the most stringent upcoming threshold escalations, forcing product architecture redesigns.
Specialty retail channels are unbundling after-sales service from product margin capture as online retail captures replacement-cycle volume in established categories. Milan and Rome showroom operators are pivoting toward consultative configuration services while logistics partnerships handle fulfillment. This bifurcation is most visible in cooker and refrigerator segments where consideration cycles remain high but purchase completion migrates to digital interfaces.
Italy Kitchen Appliances Market Segmentation
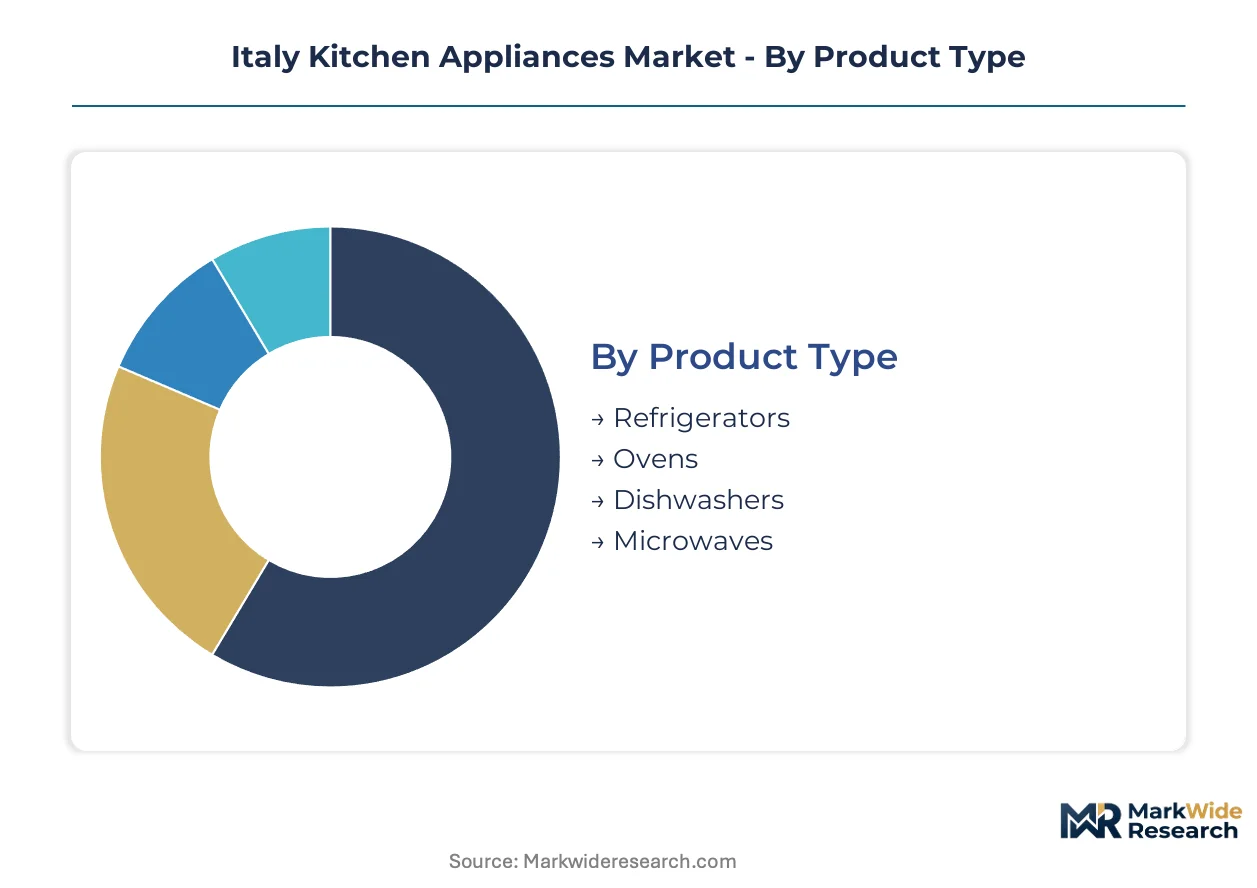
Segmentation in the Italy Kitchen Appliances Market reveals how regulatory pressure, distribution infrastructure, and end-use requirements fragment demand across distinct purchasing behaviors and technical specifications. Understanding these divisions enables manufacturers to align product development with the specific compliance and performance thresholds that govern each segment's growth trajectory.
Product Type:
EU Ecodesign mandates administered through the Ministry of Enterprise and Made in Italy impose divergent efficiency certification requirements across product categories, creating tiered compliance burdens that reshape competitive positioning.
- Refrigerators:Built-in refrigeration lines face the most stringent upcoming threshold escalations under transposed EU directives, forcing product architecture redesigns. Demand concentrates in Milan and Rome renovation corridors where premium integrated configurations dominate replacement cycles.
- Ovens:Induction and convection technologies are displacing gas burner configurations in new residential construction across Turin and Bologna industrial corridors. Northern Italian households adopt all-electric oven suites at rates outpacing national averages, aligning with municipal decarbonization targets.
- Dishwashers:Water consumption indices measured under EU standardized test cycles drive A+++ certification competition among domestic manufacturers.
- Microwaves:Compact appliance categories leverage Italian export strength in design-forward positioning for European markets.
Refrigerators handle the majority of throughput; ovens are expanding most quickly on share.
End User:
Volume concentration varies sharply between replacement-driven residential demand and specification-intensive commercial procurement channels.
- Households:Italy's National Recovery and Resilience Plan disbursements compress appliance replacement cycles from ten-year norms toward seven-year intervals. Residential renovation activity across Milan and Rome pulls demand toward premium built-in configurations with integrated appliance suites.
- Restaurants:Commercial kitchen operators prioritize durability and simultaneous operation capacity under high-draw electrical infrastructure constraints. Northern industrial corridors exhibit faster adoption of induction-based cooking lines than southern metropolitan zones.
- Cafes:Compact footprint requirements drive specification toward multi-functional equipment with reduced energy draw profiles.
- Catering Services:Mobile and event-based operators demand portable configurations with robust transport durability and rapid setup protocols.
Households dominate absolute volume; restaurants show the steepest expansion trajectory in premium equipment procurement.
Technology:
Margin capture potential stratifies across certification tiers and connectivity integration levels, with energy efficiency and smart modules commanding disproportionate pricing power.
- Smart Appliances:Wi-Fi and Bluetooth connectivity hardware is becoming standard in mid-tier refrigerator and oven configurations, enabling remote diagnostics and energy optimization. Penetration concentrates in northern industrial corridors stretching from Turin to Bologna, with Naples and Palermo exhibiting underpenetration presenting white-space expansion potential.
- Energy Efficient:A+++ and beyond-rated equipment carries disproportionate margin pools due to Italian consumer willingness to pay for operating cost reduction and EU Ecodesign compliance requirements. CE marking under EU appliance safety directives creates baseline product standards that domestic manufacturers embed earlier in development cycles.
- Traditional:Legacy configurations retain volume in replacement cycles where electrical infrastructure limitations constrain upgrade paths.
- Hybrid:Dual-mode appliances bridge compatibility gaps between gas and all-electric kitchen suites during transition periods.
Energy Efficient configurations anchor revenue concentration; Smart Appliances are gaining share fastest as connectivity modules become standard in mid-tier pricing bands.
Distribution Channel:
Channel economics bifurcate between high-consideration consultative sales and logistics-efficient replacement volume capture.
- Specialty Stores:Showroom operators in Milan and Rome are pivoting toward consultative configuration services while logistics partnerships handle fulfillment. This channel retains structural importance for high-consideration purchases in cooker and refrigerator segments where consideration cycles remain elevated.
- Online Retail:Digital interfaces capture replacement-cycle volume in established product categories with standardized specifications. Hybrid showroom-digital purchase journeys are emerging where consumers configure appliances in specialty stores then complete transactions through manufacturer-direct portals.
- Supermarkets:Mass retail channels concentrate on compact appliance categories with lower consideration thresholds and impulse purchase characteristics.
- Direct Sales:Manufacturer-direct portals enable configuration-to-order workflows for built-in kitchen suites with extended delivery timelines.
Specialty Stores manage the highest-value transactions; Online Retail is climbing the fastest on transaction volume as replacement cycles migrate to digital completion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian kitchen appliance exports flow predominantly toward Germany and France, with secondary corridors reaching Switzerland and Austria. Northern Italian manufacturing clusters in Lombardy and Piedmont anchor production capacity for premium built-in configurations. The Ministry of Enterprise and Made in Italy administers EU Ecodesign transpositions that filter non-compliant imports from Eastern European supply sources.
Lombardy
Milan's residential renovation corridor pulls demand toward premium integrated appliance suites with A+++ certification tiers. Italy's National Recovery and Resilience Plan disburses incentives for home energy efficiency that compress replacement cycles. The Cassinetta manufacturing complex sustains domestic production scale for built-in refrigeration lines serving northern European export markets.
Piedmont
Turin's industrial corridor exhibits induction cooking adoption rates outpacing national averages by substantial margins. Municipal decarbonization targets in the metropolitan zone accelerate displacement of gas burner configurations. Whirlpool leverages regional manufacturing infrastructure to serve cross-border demand from French and Swiss retail channels.
Emilia-Romagna
Bologna anchors connectivity module integration for smart refrigerator and oven configurations penetrating mid-tier pricing bands. Regional engineering talent pools concentrate IoT development for remote diagnostics and energy optimization features. The Bologna-Turin industrial corridor exhibits the densest smart appliance penetration in the national market.
Lazio
Rome's renovation activity drives specification toward premium built-in kitchen configurations with extended consideration cycles. Specialty retail showroom operators in the metropolitan zone pivot toward consultative configuration services. Online retail channels capture replacement-cycle volume as consumers complete transactions through manufacturer-direct portals.
Campania and Sicily
Naples and Palermo metropolitan zones exhibit smart appliance underpenetration relative to northern benchmarks, presenting white-space expansion potential. Electrical infrastructure limitations in legacy housing stock constrain simultaneous operation of multiple high-draw induction zones. Southern distribution networks remain less developed for hybrid showroom-digital purchase journeys.
Italy Kitchen Appliances Market Competitive Landscape
Listed leaders compete with private specialists across certification-tier positioning and distribution channel control. The vendor base stratifies into three tiers: multinational appliance conglomerates with integrated European manufacturing, mid-scale domestic specialists with design-forward positioning, and compact appliance exporters leveraging Italian brand equity. Strategic moves concentrate on backward integration into compressor and control module sourcing, plus channel convergence investments linking specialty showroom consultation to digital fulfillment.
Within the multinational tier, Whirlpool and Electrolux exemplify scale-driven positioning with captive manufacturing infrastructure. Among domestic specialists, Smeg Appliance Company and De'Longhi occupy positions anchored in design differentiation and compact category focus respectively. Samsung Electronics represents the connectivity-technology archetype, embedding smart modules as standard configurations. Bosch and Siemens exemplify German-engineered positioning competing for premium specification in northern Italian renovation corridors. AEG competes on efficiency-certification leadership within mid-tier pricing bands.
| Leading Market Players |
|---|
| Whirlpool |
| AEG |
| Siemens |
| Samsung Electronics |
| De'Longhi |
| Smeg Appliance Company |
| Electrolux |
| Signature Kitchen Suites |
| Bosch |
| Others |
Supply & Pricing Matrix
EU Ecodesign mandates administered through Italy's Ministry of Enterprise and Made in Italy gate both supply qualification and price differentiation simultaneously, filtering non-compliant imports while creating tiered margin pools around A+++ certification tiers that domestic manufacturers exploit through earlier compliance embedding.
Pricing Analysis
Household renovation buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the Italian kitchen appliances market. Price differentiation rests on certification grade and after-sales service bundling, with A+++ rated equipment commanding substantial premiums over baseline configurations. Cost compression in mid-tier segments is intensifying because raw material volatility for copper compressor housings and steel oven cavities squeezes manufacturer margins. Price-sensitive replacement-cycle purchasers through online retail channels exhibit highest elasticity, while consultative specialty store buyers in Milan and Rome renovation corridors demonstrate lowest sensitivity to premium positioning.
Supply Chain Analysis
China and Southeast Asian manufacturing clusters anchor compressor and control module production for Italian kitchen appliance assembly. Raw material dependencies center on copper for compressor housings, cold-rolled steel for oven cavities, and rare earth elements for induction hob electronics. Single-source vulnerability in Southeast Asian component sourcing creates exposure to logistics disruptions affecting finished goods assembly timelines. Distribution runs through hybrid showroom-digital pathways where specialty retailers in northern industrial corridors handle configuration consultation while manufacturer-direct portals manage fulfillment completion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Italian kitchen appliances market operates as a defensive-moat story where regulatory entrenchment through EU Ecodesign compliance creates durable barriers against import competition and sustains incumbent pricing power.
For Market Incumbents: Fortify captive manufacturing infrastructure through backward integration into compressor sourcing and control module production. Expand certification investment ahead of scheduled EU Ecodesign threshold escalations to compress time-to-market advantages over Eastern European import competitors. Deepen channel control in the Milan-Rome renovation corridor where consultative configuration services lock in premium built-in suite specifications. For New Entrants and Emerging Players: Lead with white-space expansion into Naples and Palermo metropolitan zones where smart appliance underpenetration relative to northern benchmarks creates addressable demand. Target compact appliance categories where Italian design-forward brand equity commands export pricing power across European markets. Pursue manufacturer-direct portal strategies that bypass established specialty retail gatekeepers in replacement-cycle segments. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational conglomerates seeking to divest non-core appliance portfolios amid portfolio rationalization pressures. Long-term viability framing centers on regulatory compliance capabilities and captive manufacturing scale as durable value drivers. Monitor Italy's transposition timeline for EU right-to-repair legislation as an inflection indicator for aftermarket service economics restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compressor Manufacturing | Captive supply of compressor housings insulates Whirlpool's Cassinetta complex from copper price volatility. |
| Smart Module Platform Standardization | Connectivity hardware integration enables remote diagnostics that command price premiums in Bologna-Turin corridors. |
| Specialty Retail Channel Convergence | Hybrid showroom-digital journeys capture high-consideration configuration demand while optimizing fulfillment economics. |
| Southern Italy Distribution Expansion | Naples and Palermo network development addresses smart appliance underpenetration relative to northern benchmarks. |
| Right-to-Repair Network Authorization | Pending EU legislation mandates spare parts availability that reshapes aftermarket service revenue capture. |
Research Methodology
A spread of perspectives from appliance manufacturing executives, specialty retail channel partners, regulatory affairs specialists at the Ministry of Enterprise and Made in Italy, and residential renovation contractors converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation through EU Ecodesign directive filings, AEEE national compliance scheme documentation, and customs trade data on compressor and steel imports. Bottom-up triangulation across product category volume estimates and top-down reconciliation against National Recovery and Resilience Plan disbursement schedules anchored the analytical framework.
Segmentation dimensions modeled span product type, end-user category, technology tier, and distribution channel across the projection horizon. CAGRs were derived through trend extrapolation of replacement cycle compression and smart module penetration trajectories. Forecast inputs incorporated residential renovation activity indices for Milan and Rome metropolitan clusters, plus induction cooking adoption rates across northern industrial corridors.
Forecasts assume regulatory continuity in EU Ecodesign transpositions through Italy's Ministry of Enterprise and Made in Italy; material policy shifts would require re-modeling of compliance cost burdens and import filtration effects. Specific risk factors include raw material price volatility for copper and steel, plus logistics disruption scenarios affecting Southeast Asian component sourcing. Recalibration cycles align with material shifts in EU Ecodesign threshold escalations and right-to-repair legislative implementation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
United States Electric Vegetable Choppers Market
Kitchen Appliances
Asia-Pacific Air Fryers Market
Kitchen Appliances
Self-Heating Butter Knife Market
Kitchen Appliances
Smart Kitchen Faucet Market
Kitchen Appliances
Europe Major Home Appliances Market
Kitchen Appliances
Household Bread Machine Market
Kitchen Appliances
Asia Pacific Induction Hobs Market
Kitchen Appliances
United States Small Kitchen Appliances Market
Kitchen Appliances
Asia Pacific Household Electric Grills Market
Kitchen Appliances
Tabletop Kitchen Products Market
Kitchen Appliances
Temperature Controlled Mug Market
Kitchen Appliances
Bakeware Market
Kitchen Appliances
Garlic Press Market
Kitchen Appliances
Australia Kitchen Appliances Market
Kitchen Appliances
Electric Lunch Box Market
Kitchen Appliances
Global Smart Ovens Market