
 Fox Nuts Market | 2026-2036
Fox Nuts Market Size, Share, and Industry Trends Forecast 2026-2036
Fox Nuts Market Analysis
Organic and premium-grade fox nut certification is redrawing competitive boundaries across the value chain. Shakti Sudha Industries leverages its Bihar-based sourcing network to secure consistent raw material flows. Haldiram Foods International Private Limited dominates branded snack retail through its extensive distribution infrastructure. Farmley differentiates via direct-to-consumer digital channels targeting health-focused urban buyers.
Fox nuts, botanically Euryale ferox seeds, comprise approximately 9-10% protein by dry weight with low fat content and a glycemic index below 55, making them suitable for diabetic-friendly and weight-management food formulations. The seeds undergo sun-drying, popping through heated sand, and subsequent roasting or flavoring to achieve commercial ready-to-eat status. Roasted fox nuts command the largest volume share among product types due to their versatility across savory and sweet applications, while organic fox nuts capture disproportionate margin pools as export buyers in Germany and the United Kingdom enforce stringent residue standards. Pouch packaging for flavored variants is expanding fastest among packaging types, driven by convenience-seeking urban consumers and airline hospitality procurement.
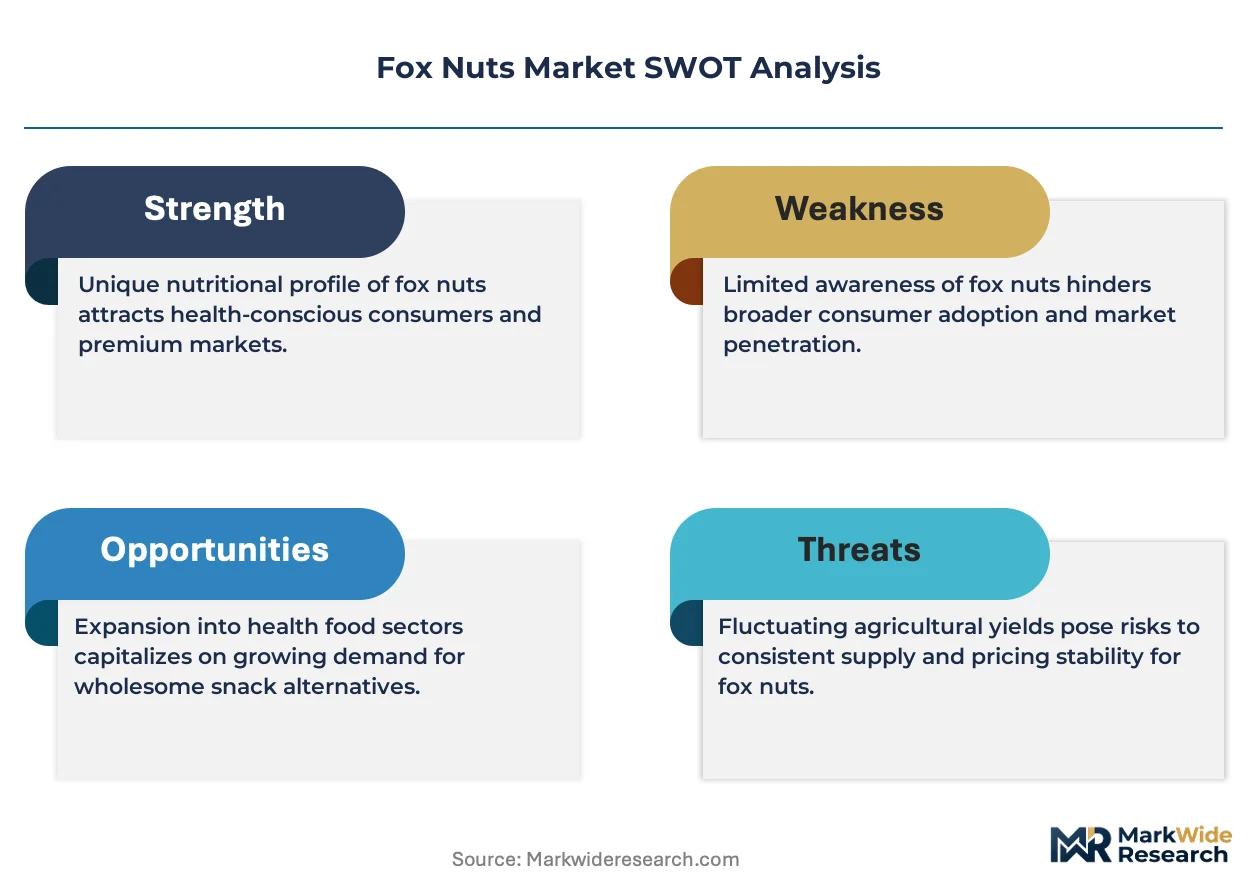
FSSAI standards govern maximum permissible moisture and aflatoxin levels for domestic Indian trade, while the EU's EFSA residue protocols determine market access for European-bound shipments. The USDA's organic certification requirements shape premium pricing structures for North American exports. Stakeholders must monitor evolving phytosanitary barriers and invest in traceability systems to sustain premium positioning as regulatory stringency tightens across destination markets.
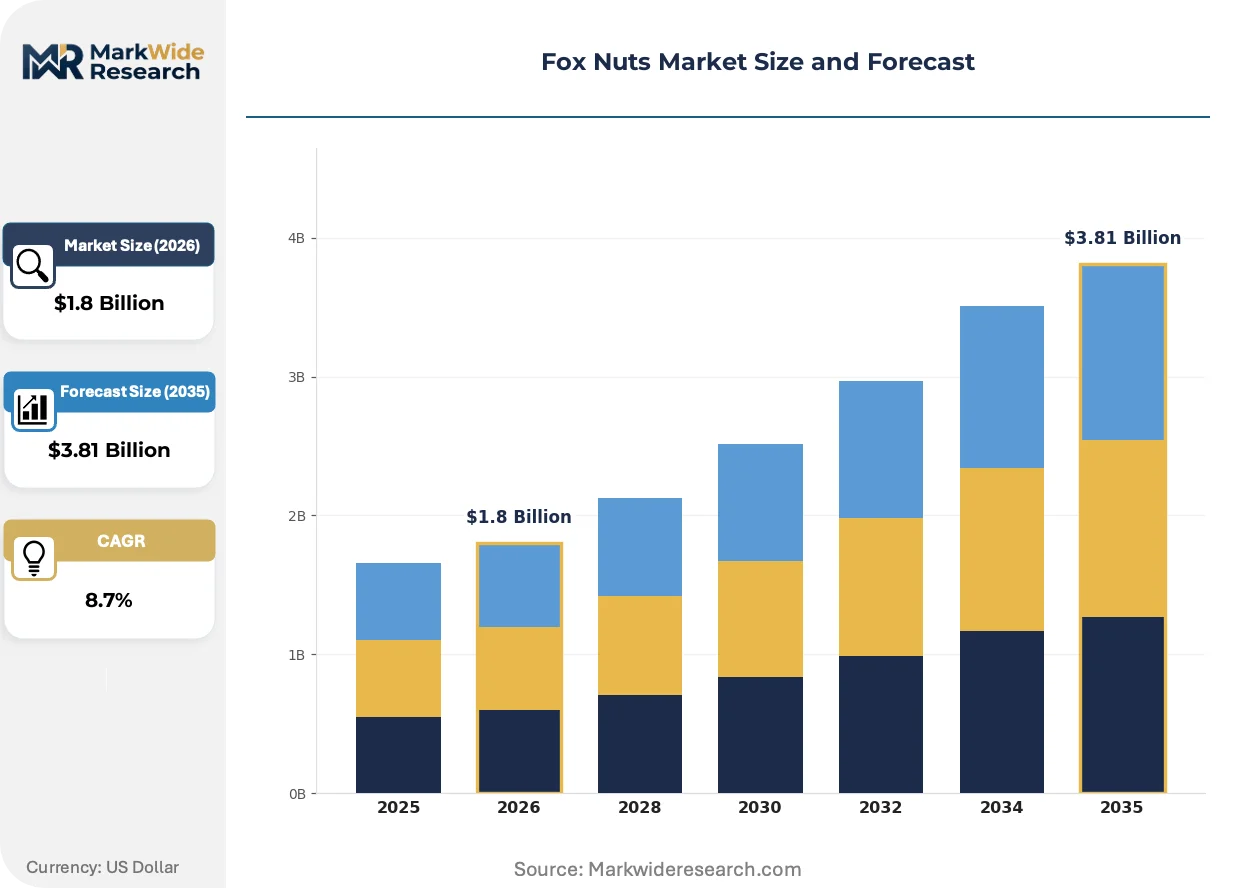
Market Dynamics
Processing capacity concentration in Bihar's Mithila region is redrawing competitive boundaries as export-oriented facilities absorb smaller sun-drying operations unable to meet EFSA residue protocols for European shipments.
Growth Catalysts
- India's PLI scheme for food processing:Capital subsidies are accelerating automated popping and roasting line installations in Bihar and Uttar Pradesh, expanding export-grade output capacity.
- Diabetic-friendly formulation demand:North American functional food manufacturers are incorporating fox nuts into low-glycemic snack bars and meal replacements, pulling premium-grade raw material.
- Airline hospitality procurement:Pouch-packaged flavored variants are displacing conventional nut mixes in in-flight service programs across Germany, the United Kingdom, and the United States.
Market Restraints
- Input cost volatility:Monsoon dependency in Bihar's floodplain cultivation zones creates annual yield swings that compress processor margins during poor harvests.
- Supply concentration risk:Over 70% of global raw material originates from districts within 150 kilometers of Darbhanga, creating single-point vulnerability to climate events.
- Regulatory friction:USDA organic certification timelines stretching 18-24 months block mid-tier processors from accessing North American premium pricing tiers.
Strategic Opportunities
- Underpenetrated United States retail:Direct-to-consumer subscription models for roasted and flavored variants remain nascent outside Indian diaspora corridors.
- Regulatory tailwind:India's FSSAI is harmonizing domestic aflatoxin standards with Codex Alimentarius, reducing dual-compliance burdens for export-oriented processors.
- Technology convergence:Near-infrared spectroscopy for real-time moisture and protein grading is enabling lot-level traceability demanded by German organic buyers.
Industry Challenges
- Skill gap in thermal processing:Artisanal sun-drying expertise does not translate to automated sand-popping line operation, creating operator shortages.
- Certification timeline compression:EU organic equivalence negotiations require parallel documentation streams that strain quality assurance departments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fox Nuts Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw Fox Nuts, Roasted Fox Nuts, Flavored Fox Nuts, Organic Fox Nuts End User: Food Industry, Health Conscious Consumers, Retailers, Snack Manufacturers Packaging Type: Bags, Boxes, Tubs, Pouches Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Wholesale |
| Companies Covered | Shakti Sudha Industries, Bikaji Foods International Limited, K.K. Products, Caryopses Pvt. Ltd., Haldiram Foods International Private Limited, Manju Makhana Enterprises, Maruti Makhana, Farmley, Madhubani Makhana Private Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fox Nuts Market Emerging Trajectories
Processing automation and residue detection technologies are compressing the gap between artisanal harvest practices and export-grade compliance requirements. These shifts are fragmenting traditional value chain roles.
Near-infrared spectroscopy for real-time protein and moisture analysis is fragmenting quality assurance workflows. Mid-scale processors in Muzaffarpur and Samastipur districts are deploying portable units to pre-grade farmer deliveries before formal laboratory testing. This technology is compressing rejection rates at export consolidation points while enabling premium lot segregation earlier in the chain.
REACH candidate list expansion for food contact materials is forcing pouch film reformulation across European-bound shipments. ECHA scrutiny of phthalate alternatives is accelerating migration to bio-based barrier layers. German and Dutch importers are now demanding third-party migration testing certificates that most Indian converters cannot yet provide.
Direct procurement from farmer-producer organizations is displacing mandi-based auction aggregation in premium-grade sourcing. Urban health-focused buyers in London and New York are paying lot premiums for blockchain-traceable origin claims. This pattern concentrates most visibly in organic segments where German retailers enforce farm-level audit requirements.
Fox Nuts Market Segmentation
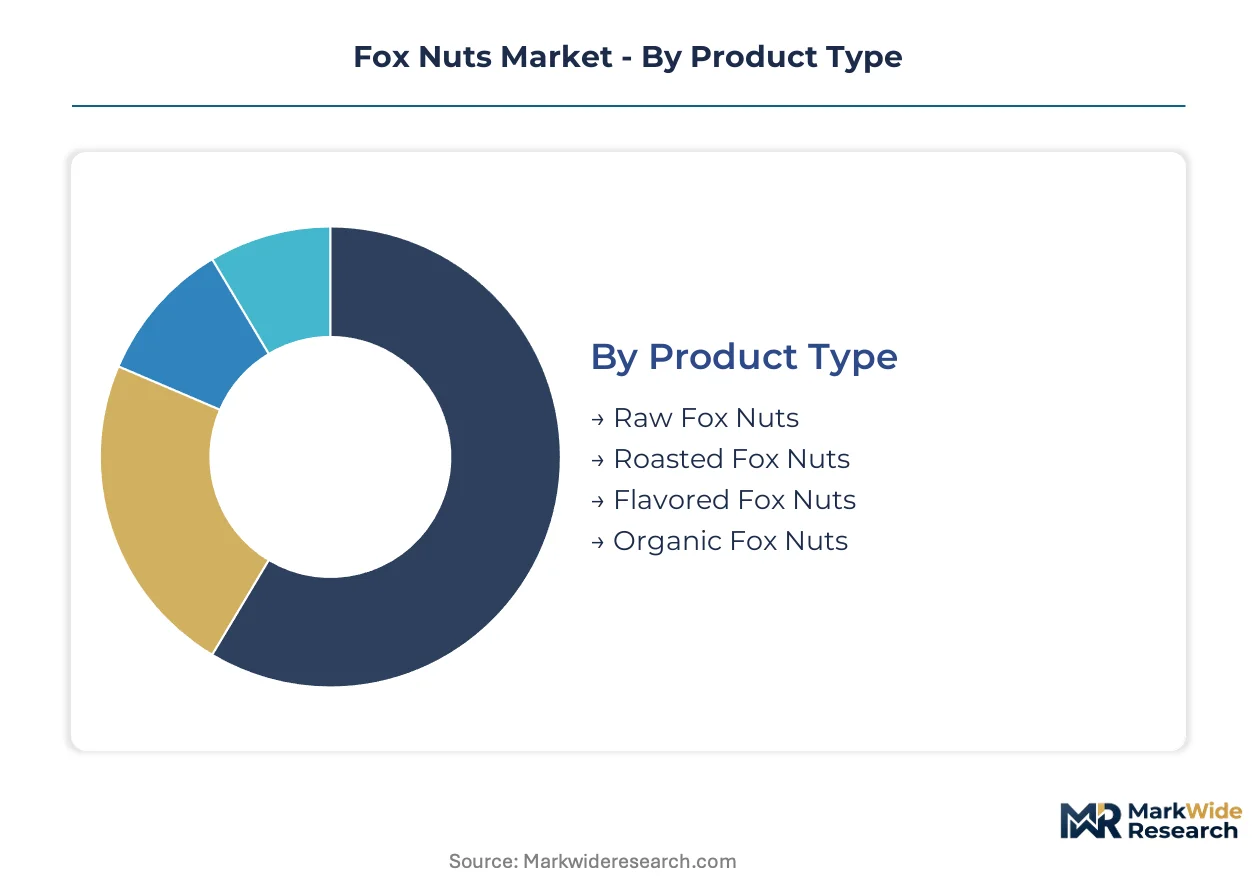
Fox nut value chains fragment across processing intensity, certification tiers, and channel access. Each segmentation dimension reveals distinct margin structures and geographic concentration patterns that determine competitive positioning.
Product Type:
Domestic Indian trade centers on raw and conventionally processed grades, while export demand concentrates in certified organic and precision-roasted segments. European and North American buyers enforce residue protocols that filter out sun-dried artisanal output.
- Raw Fox Nuts:Unpopped seeds retain 12-14% moisture and require further thermal processing. Bihar's mandi auctions supply domestic popping units and small-scale regional traders. Monsoon yield volatility compresses processor margins during deficit harvests.
- Roasted Fox Nuts:Sand-popped seeds achieve 3-4% moisture with expanded texture suitable for savory and sweet coating applications. Airline hospitality programs across Germany, the United Kingdom, and the United States pull volume through this segment. EFSA aflatoxin screening eliminates non-compliant lots at Rotterdam and Hamburg entry points.
- Flavored Fox Nuts:Post-roast seasoning with masala, cheese, or chocolate coatings targets urban convenience channels. Pouch formats dominate this segment.
- Organic Fox Nuts:Farm-level certification under USDA or EU organic equivalence protocols commands premium positioning. German retailers enforce lot-level blockchain traceability.
Roasted fox nuts command the established base. The steepest expansion runs through organic certification tiers.
End User:
Customer archetypes split between ingredient buyers seeking formulation inputs and finished-goods channels targeting direct consumption. Margin capture varies sharply across these procurement modes.
- Food Industry:Ingredient buyers incorporate fox nuts into cereal bars, trail mixes, and baked goods. North American functional food manufacturers specify low-glycemic index certification for diabetic-friendly product lines.
- Health Conscious Consumers:Direct purchasers prioritize protein content and clean-label attributes. Urban Indian metros and diaspora corridors in London and New York drive subscription-model adoption.
- Retailers:Supermarket and specialty store buyers negotiate slotting fees and promotional support. Branded shelf placement requires FSSAI compliance documentation.
- Snack Manufacturers:Contract processors supply private-label roasted and flavored variants. Haldiram and similar integrated players internalize this demand.
Food industry procurement anchors volume. Health-conscious direct buyers are climbing the fastest.
Packaging Type:
Format selection tracks consumption occasion and shelf-life requirements. Export-grade specifications increasingly mandate migration-tested barrier materials.
- Bags:Multi-layer polyethylene structures serve bulk retail and institutional catering. Indian domestic trade favors this economical format.
- Boxes:Rigid paperboard with windowed panels supports gift-oriented positioning during festival seasons. Premium tier retailers in Mumbai and Delhi specify this presentation.
- Tubs:Reclosable rigid containers target pantry stocking and extended consumption cycles. Limited adoption outside Indian urban households.
- Pouches:Flexible laminated films with reseal features dominate airline hospitality and convenience retail. REACH candidate list expansion for phthalate alternatives is forcing bio-based barrier layer adoption.
Bags retain the volume base. Pouch configurations are gaining share fastest.
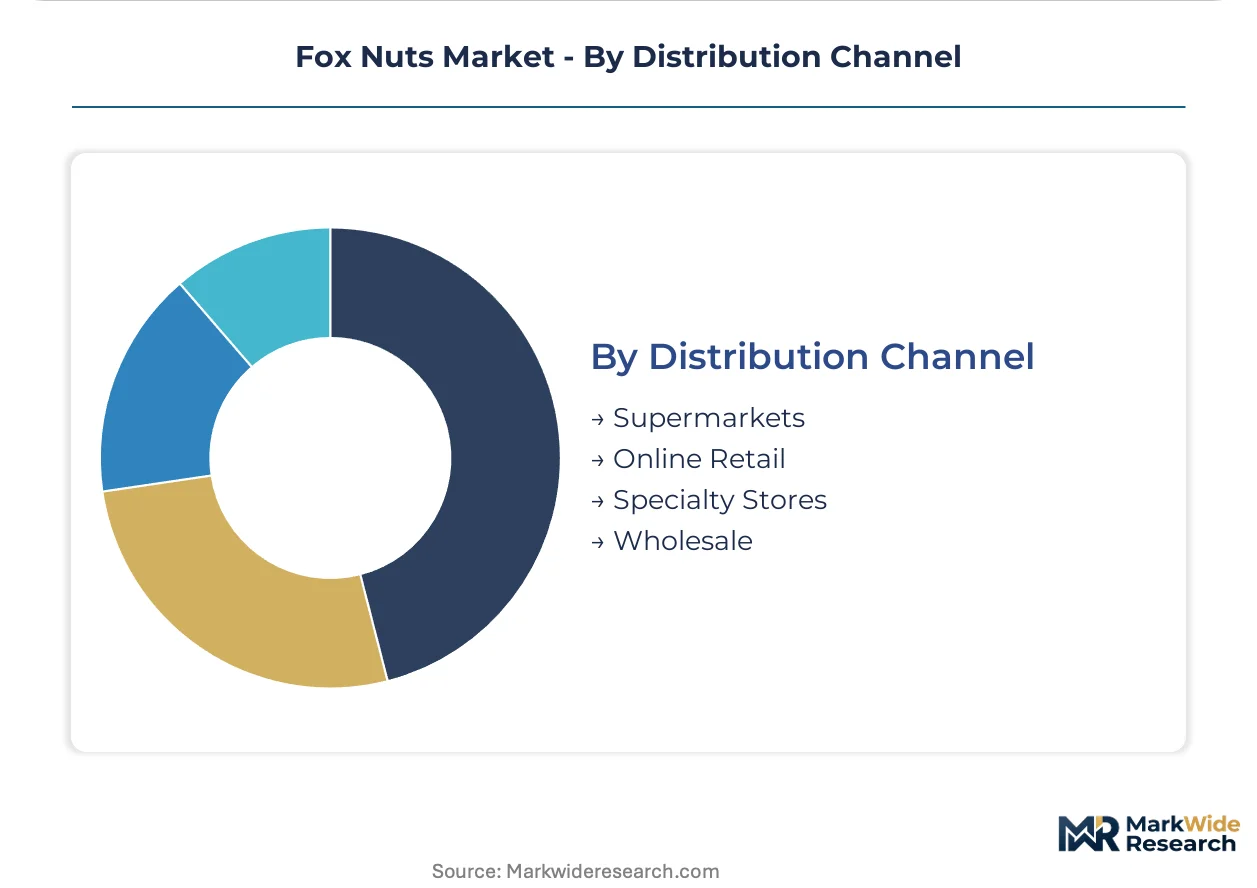
Distribution Channel:
Channel access determines certification burden and working capital intensity. Direct-to-consumer models bypass traditional mandi aggregation but require traceability infrastructure.
- Supermarkets:Modern trade chains in India and ethnic retail in North America enforce barcode traceability and promotional calendar compliance. Shelf placement fees strain smaller processors.
- Online Retail:Direct-to-consumer platforms enable origin storytelling and subscription bundling. Farmley and similar digital-native brands exploit this channel.
- Specialty Stores:Organic and ayurvedic retailers in Germany and the United Kingdom demand third-party audit certificates. Store-level staff training influences repurchase rates.
- Wholesale:Bulk consolidation for export and institutional catering minimizes packaging cost but compresses per-unit margins. Darbhanga-based aggregators dominate this tier.
Supermarket placement secures the established base. Online retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India exports fox nuts to Germany, the United Kingdom, and the United States, with raw material originating from Bihar's Mithila region and processing facilities supplying premium-grade organic and roasted variants to these destination markets.
United States
Diabetic-friendly snack formulations drive demand from North American functional food manufacturers seeking low-glycemic index ingredients. USDA organic certification timelines of 18-24 months create entry barriers for mid-tier processors. Indian diaspora corridors in New York and New Jersey anchor ethnic retail distribution.
Germany
Airline hospitality procurement programs source pouch-packaged flavored variants for in-flight service. EFSA residue protocols and REACH candidate list expansion for food contact materials enforce stringent compliance. Hamburg and Rotterdam serve as primary entry points for EFTA aflatoxin screening.
United Kingdom
Health-conscious urban consumers in London subscribe to direct-to-origin digital channels demanding blockchain-traceable organic certification. EFSA equivalence standards govern import acceptance. Specialty ayurvedic retailers in Greater Manchester and Birmingham enforce third-party audit requirements.
India
FSSAI food safety standards and the PLI scheme for food processing strengthen export-oriented capacity in Bihar and Uttar Pradesh. Darbhanga-based processing clusters absorb smaller sun-drying operations unable to meet European residue protocols. Monsoon dependency in floodplain cultivation zones creates annual yield volatility.
China
Domestic cultivation of Euryale ferox in lake regions supplies local traditional medicine and snack markets. SAMR food safety standards govern domestic trade. Processing technology imports from Indian equipment fabricators support popping and roasting line automation in Hubei and Jiangsu provinces.
Fox Nuts Market Vendor Landscape
Listed leaders compete with private specialists across certification tiers and channel access. The vendor base stratifies between integrated snack conglomerates, regional processors with captive sourcing networks, and digital-native direct-to-consumer brands. Three archetypes dominate: Bihar-based raw material aggregators, national branded snack houses with distribution infrastructure, and technology-enabled origin-story marketers. Competitive moves concentrate on automated processing capacity installation and direct farmer-producer organization procurement relationships.
Within the Bihar-based sourcing tier, Shakti Sudha Industries and Madhubani Makhana Private Limited occupy positions anchored to Mithila region cultivation clusters. Haldiram Foods International Private Limited exemplifies the national branded snack house archetype with integrated processing and retail distribution. Farmley represents the digital-native vector targeting health-focused urban consumers through subscription and direct-to-origin storytelling. These three company patterns illustrate how competitive positioning fragments across raw material control, brand infrastructure, and channel innovation.
| Leading Market Players |
|---|
| Shakti Sudha Industries |
| Bikaji Foods International Limited |
| K.K. Products |
| Caryopses Pvt. Ltd. |
| Haldiram Foods International Private Limited |
| Manju Makhana Enterprises |
| Maruti Makhana |
| Farmley |
| Madhubani Makhana Private Limited |
| Others |
Supply Flow & Price Mechanics
Automated popping line scale economies in Bihar and Uttar Pradesh are compressing unit processing costs while simultaneously elevating price floors for export-grade organic certification. This dual dynamic concentrates margin capture among processors with FSSAI-compliant facilities and USDA-equivalent documentation capacity.
Pricing Analysis
Processing-technology generation gaps separate artisanal sun-drying operations from automated sand-popping lines and near-infrared spectroscopy-enabled grading facilities. Three-tier pricing structure across premium organic, standard export-grade, and domestic commodity levels tracks certification burden and residue testing intensity. Pricing pressure stems from EFSA aflatoxin screening rejections at Rotterdam and Hamburg entry points that compress realized yields. Food industry ingredient buyers exhibit highest price sensitivity due to formulation cost targets, while airline hospitality procurement programs demonstrate lowest sensitivity given service-level specifications.
Supply Chain Analysis
India anchors global raw material supply through Bihar's Mithila region cultivation clusters, with secondary processing capacity expansion in Uttar Pradesh. The chain draws from monsoon-dependent floodplain farming, artisanal sun-drying labor pools, and automated roasting line equipment imports. Single-source vulnerability concentrates in districts within 150 kilometers of Darbhanga where over 70 percent of global Euryale ferox seed originates. Distribution runs through Darbhanga-based aggregators for export consolidation, direct-to-consumer digital platforms for urban health-focused buyers, and ethnic retail corridors for diaspora markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across certification tiers and channel access creates specialist opportunities as health-conscious buyers in Germany, the United Kingdom, and the United States demand blockchain-traceable origin claims.
For Market Incumbents: Compound automated processing capacity advantages by installing near-infrared spectroscopy grading lines in Muzaffarpur and Samastipur districts to pre-grade farmer deliveries. Deepen backward integration into farmer-producer organization procurement relationships to secure premium organic lots before mandi auction exposure. Defend against digital-native entrants by accelerating FSSAI-Codex harmonization documentation for dual-compliance efficiency. For New Entrants and Emerging Players: Lead with direct-to-consumer subscription models targeting underpenetrated United States retail corridors outside Indian diaspora strongholds. Exploit white-space in blockchain-traceable organic segments where German retailers enforce farm-level audit requirements. Deploy pouch-packaged flavored variants with bio-based barrier layers to capture airline hospitality procurement displacement of conventional nut mixes. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors processors with installed automated popping capacity and established EFSA compliance track records. Long-term viability hinges on traceability infrastructure deployment and organic certification pipeline depth. Acquisition target archetypes include Bihar-based regional processors with captive sourcing networks and incomplete certification stacks. The inflection signal to monitor is USDA organic equivalence timeline compression for mid-tier facility access.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Processing Line Installation | Near-infrared spectroscopy deployment in Bihar reduces export rejection rates at EFTA entry points. |
| Farmer-Producer Organization Procurement | Direct sourcing relationships enable premium lot segregation before mandi price volatility exposure. |
| Organic Certification Pipeline Investment | Parallel USDA and EU organic documentation streams unlock North American and German premium pricing tiers. |
| Bio-Based Packaging Reformulation | REACH-compliant barrier layer migration addresses ECHA scrutiny of phthalate alternatives in pouch films. |
| Direct-to-Consumer Channel Launch | Subscription models bypass Darbhanga aggregator margins while capturing urban health-focused buyer premiums. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with fox nut processors, FSSAI compliance officers, and airline hospitality procurement managers; and secondary validation through customs trade records, FSSAI notification databases, and EFSA residue monitoring reports. Bottom-up triangulation across farmer-producer organization delivery patterns and top-down consolidation through export shipment manifests anchored volume estimates.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning product type intensity, certification tier, packaging format migration, and distribution channel access. CAGRs derived from processing capacity installation trajectories under India's PLI scheme and diabetic-friendly formulation adoption curves in North American functional food manufacturing. Forecast inputs incorporated monsoon yield volatility patterns in Bihar's floodplain zones and EFSA aflatoxin screening rejection rates at Rotterdam and Hamburg.
The analysis sits within stated boundaries; outcomes outside sustained PLI scheme capital subsidy availability or accelerated EFSA-EU organic equivalence negotiations would require recalibration. Forecasts reflect documented assumptions regarding processing automation adoption timelines and airline hospitality procurement program expansion. Recalibration cycles align with material shifts in FSSAI harmonization progress, REACH candidate list expansions, and blockchain traceability infrastructure deployment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuts and Seeds
Breadnut Market
Nuts and Seeds
Tree Nut Allergy Market
Nuts and Seeds
Vietnam Cashew Market
Nuts and Seeds
Almond Butter Market
Nuts and Seeds
Carob Market
Nuts and Seeds
Betel Nuts Market
Nuts and Seeds
Packaged Sunflower Seeds Market
Nuts and Seeds
India Processed Cashew Market
Nuts and Seeds
Hickory Nut Market
Nuts and Seeds
Apricot Kernel Powder Market
Nuts and Seeds
India Cashew Market
Nuts and Seeds
Thailand Fox Nuts Market
Nuts and Seeds
Nutmeg Butter Market
Nuts and Seeds
Saudi Arabia Nuts Market
Nuts and Seeds
Flax Seed Meal Market
Nuts and Seeds
Walnut Oil Market