
 Hickory Nut Market | 2026-2036
Hickory Nut Market Size, Share, and Industry Trends Forecast 2026-2036
Hickory Nut Market Insights
Snack production is decoupling from commodity nut sourcing as brands seek differentiated flavor profiles. Campbell Soup Company leverages its procurement scale to secure long-term hickory contracts. Diamond Foods Inc. sustains roasting expertise that anchors premium positioning. Hickory Nut Gap specializes in heritage varietal cultivation, occupying a defensible niche against commodity imports.
Hickory nuts are the edible seeds of Carya species, typically containing 60-70% oil by weight with distinctive sweet-smoky flavor compounds developed through slow roasting at temperatures below 150°C. The nuts serve commercial bakeries and confectioners seeking texture contrast in premium formulations. Raw nuts dominate volume throughput due to ingredient-grade demand from baked goods manufacturers, while processed snacks capture margin concentration through flavor innovation. Single-serve packs are expanding fastest within packaging type as convenience channels absorb portion-controlled formats.
USDA enforces grading standards under the Agricultural Marketing Service that determine processor eligibility for federal procurement contracts. FDA food safety modernization rules require hazard controls at shelling and roasting stages, elevating capital requirements for market entry. APHIS phytosanitary certificates govern interstate movement of in-shell nuts, creating compliance friction for small-scale harvesters. Stakeholders must monitor evolving organic certification thresholds and regional pest quarantine boundaries that could reshape supply zone viability.
Market Dynamics
Clean-label ingredient mandates from major retail chains are forcing snack producers to decouple from commodity nut sourcing and secure traceable hickory supply chains with documented provenance.
Growth Catalysts
- USDA Organic Certification Thresholds:Federal procurement eligibility now requires verified organic handling, pulling processors toward certified orchard networks and away from conventional bulk channels.
- Heritage Varietal Revival:Distinctive Carya cultivars with documented terroir profiles command ingredient-grade premiums from artisan confectioners seeking flavor differentiation.
- Southeastern Orchard Clustering:Native Carya species concentration near shelling infrastructure in North Carolina, Georgia, and Tennessee reduces post-harvest transit damage and preserves oil integrity.
Market Restraints
- Shelling Labor Intensity:Hickory's thick endocarp requires specialized cracking equipment or hand-processing, elevating unit costs versus mechanically harvested pecans or walnuts.
- Biennial Bearing Cycles:Native Carya species exhibit irregular mast years, creating volume unpredictability that complicates contract fulfillment for bulk ingredient buyers.
- APHIS Phytosanitary Friction:Interstate movement certificates for in-shell nuts impose documentation burdens that exclude small-scale foragers from formal supply chains.
Strategic Opportunities
- Direct-to-Consumer Roasting Subscriptions:Specialty retailers bypass wholesale intermediaries by shipping small-batch roasted product through e-commerce channels with harvest-date transparency.
- Carbon Accounting Integration:Native orchard carbon sequestration metrics align with emerging corporate Scope 3 reporting requirements, creating premium positioning for domestic sourcing.
- Functional Ingredient Expansion:High oleic acid content positions hickory oil as a clean-label alternative to synthetic emulsifiers in plant-based dairy formulations.
Industry Challenges
- Mechanical Harvesting Adaptation:Orchard floor topography and nut dispersal patterns resist standard tree-shaker deployment, requiring custom equipment R&D with uncertain payback timelines.
- Organic Transition Periods:Three-year soil certification gaps strand conventional growers without premium pricing during conversion, straining working capital reserves.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hickory Nut Market |
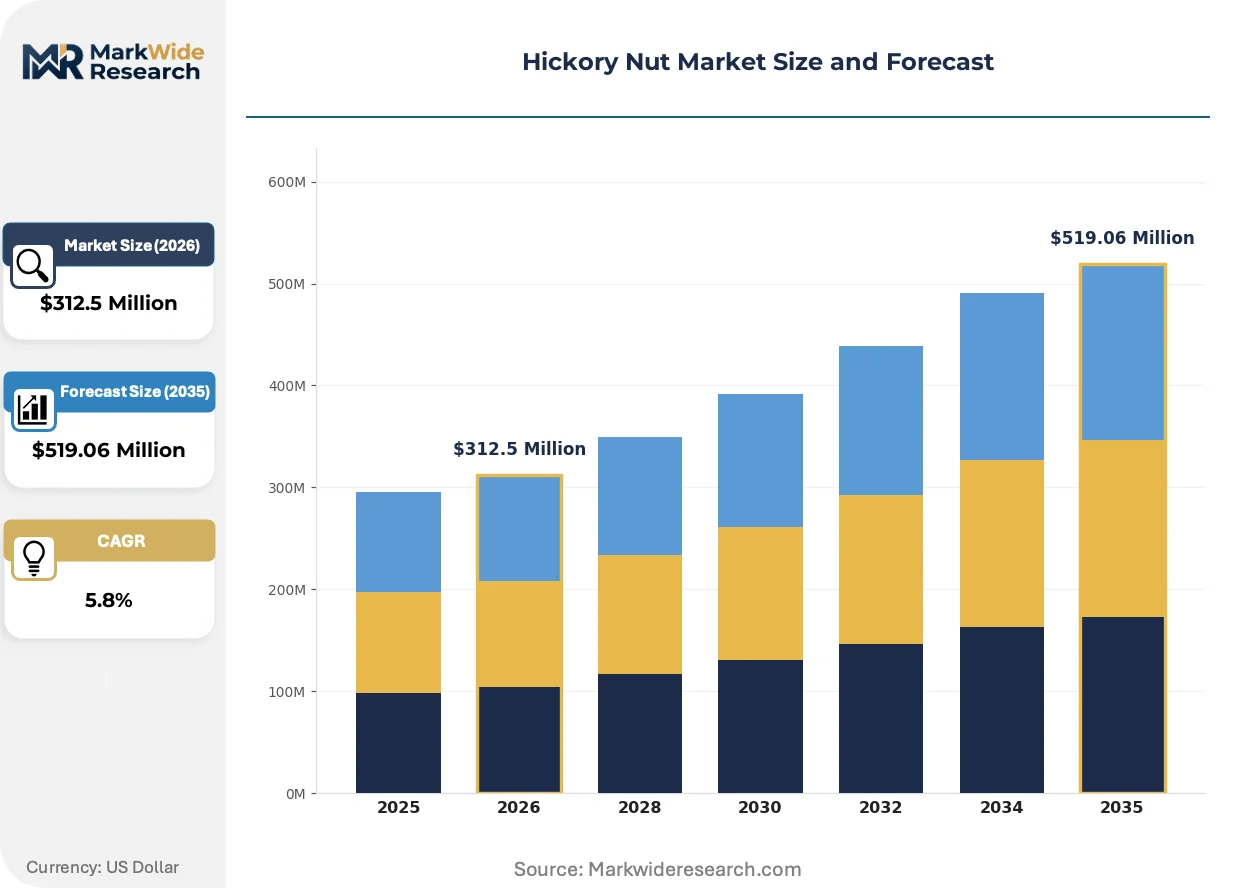
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $519.06 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw Nuts, Roasted Nuts, Processed Snacks, Flavored Nuts End User: Food Industry, Retail Consumers, Baked Goods Manufacturers, Snack Producers Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Food Service Packaging Type: Bags, Tins, Bulk Containers, Single-Serve Packs |
| Companies Covered | Campbell Soup Company, Diamond Foods Inc., Hickory Nut Gap, Kanegrade, Kerry Group, Olam International Limited, Cargill Incorporated, ADM, Hangzhou Yaosheng Food Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hickory Nut Market Trends and Innovations
Flavor compound preservation technologies and portion-format engineering are reshaping how hickory nuts move from orchard through processing into finished goods channels.
Low-temperature convection roasting is modularizing flavor development protocols across mid-scale processing facilities. Regional bakeries and confectioners adopt these systems to replicate heritage smoke profiles without open-flame inconsistency. Equipment standardization is compressing the capital barrier between artisan and commercial production tiers.
USDA Agricultural Marketing Service grading enforcement tightens processor eligibility for federal foodservice contracts. Facilities lacking documented hazard controls at shelling stages face exclusion from institutional procurement pools. Small-scale operators in Arkansas and Missouri are consolidating under shared-use certified facilities to maintain market access.
Single-serve portion packs displace bulk ingredient formats in convenience channel placements. Grab-and-go retail locations and workplace micro-markets absorb individually wrapped SKUs that extend shelf stability through modified atmosphere sealing. Southeastern airport concessions and college campus vending networks exhibit the fastest absorption velocity for these formats.
Hickory Nut Market Segmentation
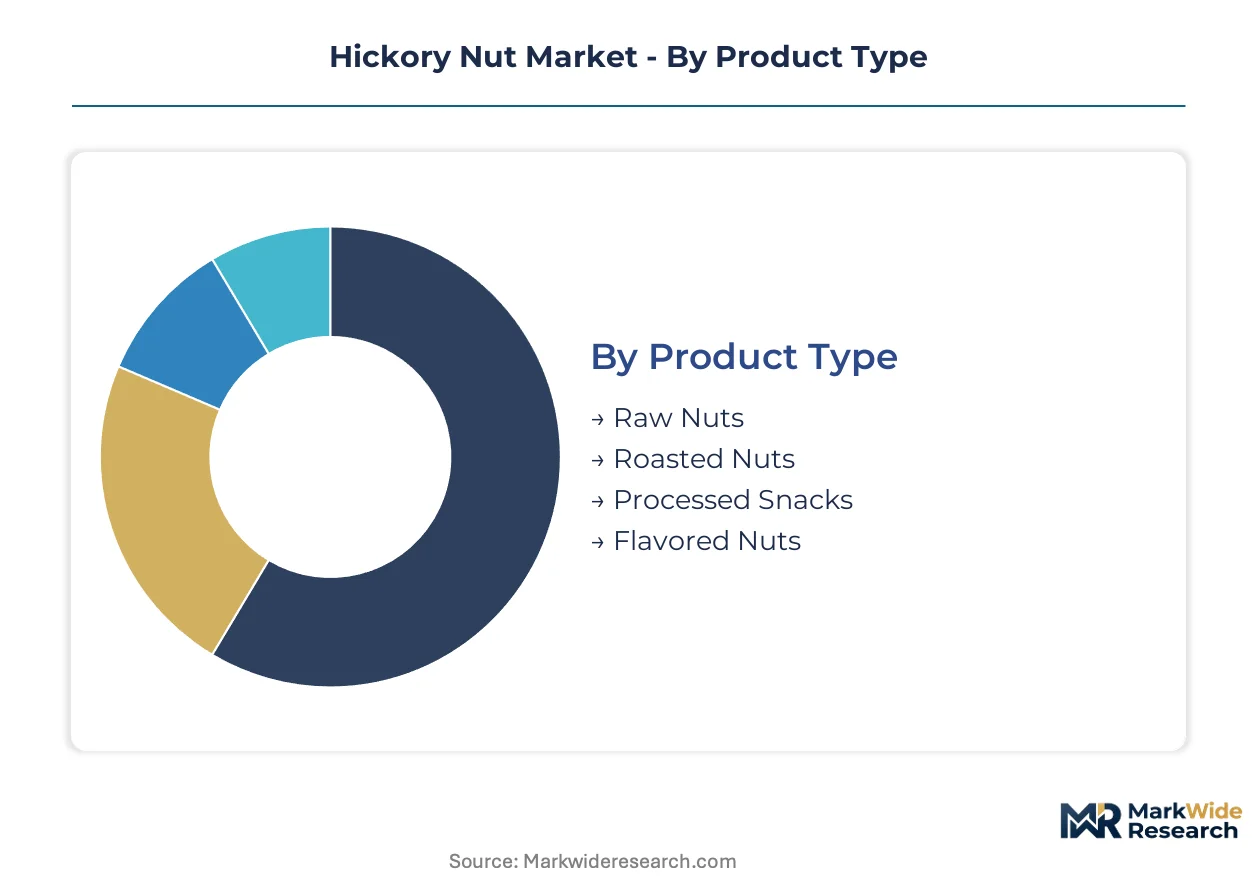
Hickory nut segmentation reveals how supply chain configuration shapes profit pools across the value chain. Product form and packaging decisions determine which processors capture organic premiums versus commodity margins.
Product Type:
Shelling infrastructure concentration in the Southeast pulls product form decisions toward formats that minimize post-harvest handling damage.
- Raw Nuts:Unprocessed in-shell or shelled kernels retain 60-70% oil content for bakery ingredient applications. Baked goods manufacturers in North Carolina and Georgia contract directly for volume throughput to supply clean-label formulations.
- Roasted Nuts:Slow-roasted kernels below 150°C develop signature sweet-smoky flavor compounds that command ingredient-grade premiums. Artisan confectioners in Tennessee source small-batch lots with documented harvest dates for traceability compliance.
- Processed Snacks:Value-added formats including seasoned clusters and brittle confections.
- Flavored Nuts:Smoke-infused or maple-glazed varieties targeting premium snacking occasions.
Raw nuts absorb the bulk of installed capacity; processed snacks are expanding most quickly.
End User:
Customer type determines whether procurement flows through long-term contracts or spot market purchases.
- Food Industry:Broad ingredient procurement spanning confectionery, dairy alternatives, and plant-based emulsifier applications. Snack producers seeking differentiated flavor profiles are decoupling from commodity nut sourcing to secure traceable hickory supply chains.
- Snack Producers:Clean-label mandates from major retail chains force documented provenance requirements. Campbell Soup Company leverages procurement scale for multi-year orchard contracts.
- Baked Goods Manufacturers:Volume buyers prioritizing oil integrity for texture contrast in premium formulations.
- Retail Consumers:Direct purchasers through farmers markets and heritage food subscriptions.
Food industry buyers absorb the bulk of installed capacity; snack producers are expanding most quickly.
Distribution Channel:
Channel selection determines compliance burden intensity for phytosanitary documentation.
- Supermarkets:Conventional retail placement requiring USDA Agricultural Marketing Service grading compliance. Chains with clean-label mandates are forcing processors toward certified organic handling documentation.
- Online Retail:Direct-to-consumer roasting subscriptions with harvest-date transparency. Hickory Nut Gap and similar heritage cultivators bypass wholesale intermediaries through e-commerce channels.
- Specialty Stores:Curated placement emphasizing terroir documentation and single-origin sourcing.
- Food Service:Institutional procurement pools requiring FDA food safety modernization hazard controls at shelling stages.
Supermarkets absorb the bulk of installed capacity; online retail is expanding most quickly.
Packaging Type:
Format engineering determines shelf stability extension and convenience channel penetration.
- Single-Serve Packs:Individually wrapped SKUs with modified atmosphere sealing for grab-and-go retail. Southeastern airport concessions and college campus vending networks exhibit steepest absorption velocity for portion-controlled formats.
- Bags:Flexible retail packaging for conventional grocery placement.
- Tins:Premium gift formats with extended shelf stability for seasonal confectionery.
- Bulk Containers:Foodservice and ingredient-grade shipments to commercial bakeries.
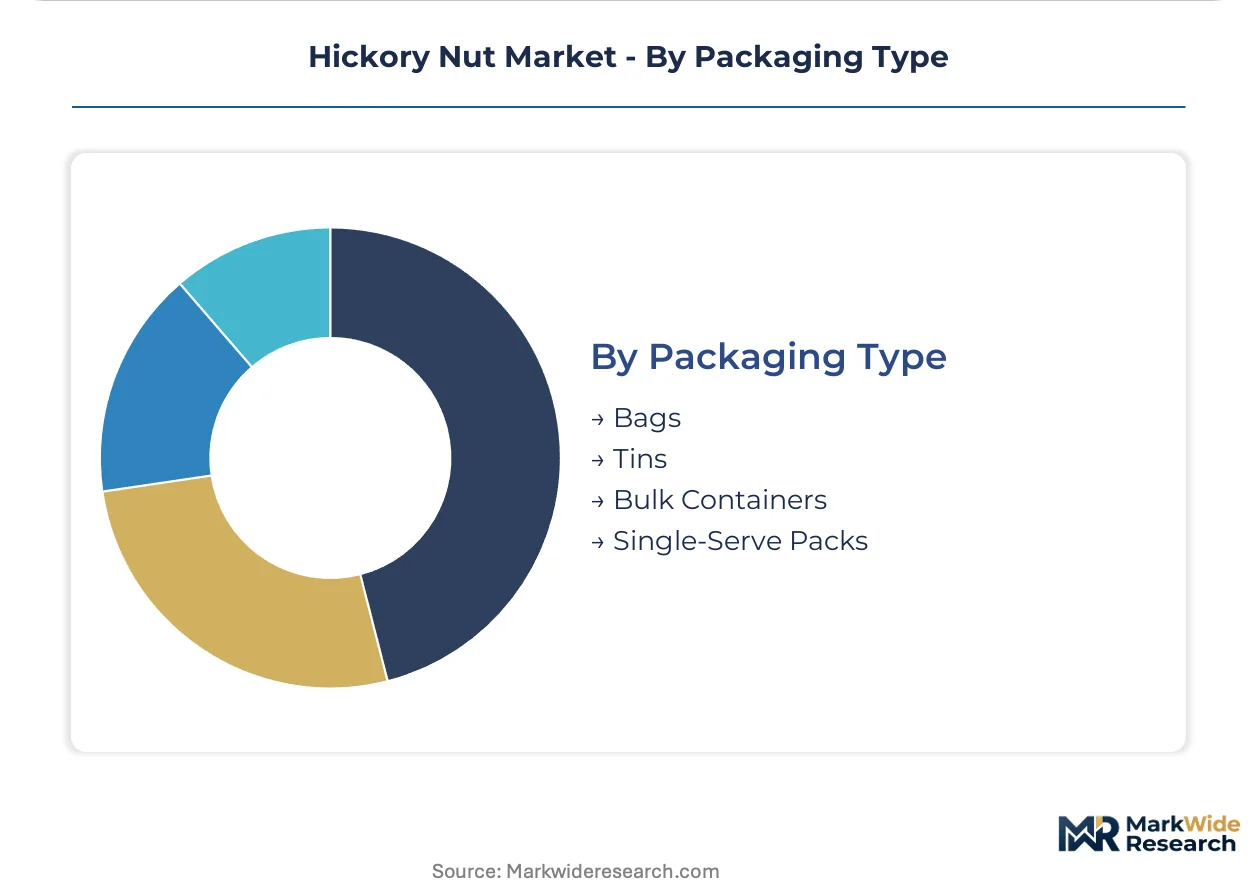
Bags absorb the bulk of installed capacity; single-serve packs are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity zones in North Carolina's western counties attract shelling facility investment through state tax credits tied to agricultural processing infrastructure.
United States
Native Carya orchards cluster in the Appalachian foothills where Campbell Soup Company secures multi-year procurement contracts. USDA Agricultural Marketing Service grading standards determine federal foodservice eligibility. Shelling cooperatives in Asheville, North Carolina consolidate small-holder harvests to meet volume thresholds for institutional buyers.
Canada
Specialty food importers in Ontario and Quebec source hickory kernels for artisan confectionery applications. Canadian Food Inspection Agency phytosanitary requirements govern cross-border nut shipments from US suppliers. Toronto-based distributors maintain cold-chain logistics for oil-integrity preservation in bakery ingredient channels.
China
Domestic Carya cathayensis production in Zhejiang and Anhui provinces supplies regional snack manufacturers. SAMR food safety standards enforce hazard controls at roasting facilities. Hangzhou Yaosheng Food Co. anchors processing capacity in the Yangtze Delta for both domestic distribution and export preparation.
Germany
European confectionery houses import hickory kernels for premium praline formulations and texture contrast applications. EU organic certification requirements under EFSA jurisdiction mandate documented handling chain provenance. Hamburg port logistics clusters facilitate bulk container receipt and redistribution to Central European bakery manufacturers.
Australia
Native macadamia processors in Queensland and New South Wales experiment with hickory roasting protocols for cross-nut flavor innovation. Department of Agriculture biosecurity regulations restrict raw nut imports, favoring processed kernel trade. Sydney specialty retailers source small-batch roasted product through direct US orchard relationships.
Hickory Nut Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with heritage cultivators occupying defensible niches against commodity traders. The vendor base organizes around three archetypes: integrated food conglomerates with procurement scale, regional roasting specialists with flavor expertise, and orchard-origin brands with terroir documentation. Competitive moves concentrate on long-term supply contracts and certified organic handling infrastructure rather than price-based confrontation.
Within the integrated food conglomerate tier, Campbell Soup Company and Cargill Incorporated exemplify procurement-scale archetypes that leverage volume commitments to secure orchard access. Diamond Foods Inc. anchors the roasting-specialist position with heritage smoke-profile capabilities. Hickory Nut Gap occupies the orchard-origin niche, representing terroir-focused cultivation models that bypass wholesale intermediaries through direct channels.
| Leading Market Players |
|---|
| Campbell Soup Company |
| Diamond Foods Inc. |
| Hickory Nut Gap |
| Kanegrade |
| Kerry Group |
| Olam International Limited |
| Cargill Incorporated |
| ADM |
| Hangzhou Yaosheng Food Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Shelling labor costs cascade through hickory nut pricing tiers, with hand-processed heritage varietals commanding ingredient-grade premiums while mechanically cracked commodity lots absorb volume discounts. Biennial bearing cycles in native Carya orchards concentrate supply uncertainty into contract structures that reward long-term procurement commitments from Campbell Soup Company and Cargill Incorporated with price stability clauses.
Pricing Analysis
Short lead-time premiums separate urgent bakery ingredient orders from standard contract fulfillment windows, with North Carolina processors charging differential rates based on harvest-date proximity. Three-tier pricing structure across organic-certified heritage lots, conventional shelled kernels, and bulk in-shell commodity grades reflects USDA Agricultural Marketing Service grading enforcement and APHIS phytosanitary documentation burden. Cost compression in conventional tiers intensifies because pecan and walnut substitution pressures limit hickory's ingredient share. Snack producers with clean-label mandates show least price sensitivity; small-scale foragers excluded from formal supply chains face spot-market vulnerability.
Supply Chain Analysis
Regional distribution centers in Asheville, North Carolina and Atlanta, Georgia anchor hub-and-spoke patterns that consolidate small-holder harvests from Appalachian foothill orchards. Supply concentrates in the United States, with secondary sourcing from China's Zhejiang province and limited European import through Hamburg port logistics. Raw material inputs draw from native Carya species mast cycles, specialized cracking equipment, and modified atmosphere packaging films. Single-source vulnerability around southeastern shelling infrastructure creates concentration risk from pest quarantine boundaries. Distribution runs through institutional procurement pools, e-commerce direct channels, and airport concession micro-markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Low-temperature convection roasting systems are displacing open-flame heritage protocols across mid-scale processing facilities, compressing capital barriers between artisan and commercial production tiers.
For Market Incumbents: Extend certified organic handling infrastructure to secure federal procurement eligibility as USDA Agricultural Marketing Service grading enforcement tightens. Acquire shelling cooperative capacity in North Carolina's western counties to consolidate small-holder harvests and defend against heritage cultivator direct-channel encroachment. For New Entrants and Emerging Players: The price-point gap between premium organic heritage lots and economy-grade conventional kernels offers white-space entry through direct-to-consumer roasting subscriptions with harvest-date transparency. Target southeastern airport concessions and college campus vending networks for single-serve pack placement. Pursue carbon accounting integration as a go-to-market angle for corporate Scope 3 reporting alignment. For Investors and Strategic Acquirers: Multi-year orchard contract announcements from integrated food conglomerates are the leading indicator that procurement-scale consolidation is accelerating. Over the projection horizon, vertically integrated processors with captive shelling capacity and documented terroir provenance represent the preferred acquisition archetype. Monitor APHIS phytosanitary rule expansions as the inflection signal for supply zone viability shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Organic Handling Investment | USDA Agricultural Marketing Service grading compliance secures federal foodservice contract eligibility. |
| Heritage Varietal Cultivation Expansion | Documented terroir profiles command ingredient-grade premiums from artisan Tennessee confectioners. |
| Single-Serve Pack Format Engineering | Modified atmosphere sealing extends shelf stability for grab-and-go retail channel penetration. |
| Direct-to-Consumer Channel Development | E-commerce subscriptions bypass wholesale intermediaries with harvest-date transparency. |
| Carbon Accounting Integration | Native orchard sequestration metrics align with corporate Scope 3 reporting requirements. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across orchard operators, shelling facility managers, bakery procurement leads, and specialty retail buyers. USDA Agricultural Marketing Service grading standards, FDA food safety modernization filings, and APHIS phytosanitary certificate databases supplemented customs import records. Bottom-up orchard yield estimates and top-down snack ingredient demand models were triangulated for volume reconciliation.
Data-stream reconciliation across product form, end-user category, distribution channel, and packaging type dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segmented growth rate modeling. Shelling labor intensity coefficients, biennial bearing cycle adjustments, and organic certification transition timelines fed industry-specific forecast inputs.
Inputs from USDA, FDA, and APHIS regulatory databases were available through the study window; gaps in small-scale forager harvest documentation introduce uncertainty bands around informal supply chain estimates. Forecasts reflect assumptions regarding clean-label mandate persistence and southeastern infrastructure investment continuity. Pest quarantine boundary shifts and mechanical harvesting R&D outcomes represent specific risk factors that could revise projections. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuts and Seeds
Almond Butter Market
Nuts and Seeds
Almond with Shell Snack Market
Nuts and Seeds
Walnut Market
Nuts and Seeds
Nutmeg Market
Nuts and Seeds
Fruit Kernel Products Market
Nuts and Seeds
Apricot Kernel Powder Market
Nuts and Seeds
Almond Oil Market
Nuts and Seeds
Nuts Market
Nuts and Seeds
Organic Almond Oil Market
Nuts and Seeds
North America Hazelnut Market
Nuts and Seeds
Nut Oil Market
Nuts and Seeds
Macadamia Market
Nuts and Seeds
Macadamia Nut Market
Nuts and Seeds
Global Cashew Nutshell Liquid Market
Nuts and Seeds
Germany Cashew Market
Nuts and Seeds
Reduced Fat Peanut Butter Market