
 Home Outdoor Pest Control Devices Market | 2026-2036
Home Outdoor Pest Control Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Home Outdoor Pest Control Devices Market Outlook
Connected sensor integration and IoT-enabled monitoring is reshaping how manufacturers design next-generation outdoor pest control systems. Flowtron leverages its heritage in electronic insect elimination to sustain engineering leadership in UV-LED attractant technologies. Woodstream Corporation anchors its position through dominant retail channel control across North American home improvement stores. Spectrum Brands Holdings differentiates via broad portfolio coverage spanning chemical, electronic, and natural modalities.
Home outdoor pest control devices encompass electromechanical, chemical-dispensing, and biological systems engineered to repel, trap, or eliminate arthropods and vertebrate pests in residential exterior environments, typically operating within 15-30 meter effective ranges and incorporating weatherproof IPX4+ enclosures for sustained outdoor deployment. These systems serve the primary commercial purpose of protecting human activity zones from disease vectors and nuisance species while minimizing ecological disruption. Electronic technology leads unit shipments due to consumer preference for non-chemical perimeter defense, while biological formulations command premium positioning among environmentally conscious homeowners. Ultrasonic repellers represent the fastest-growing product category as semiconductor miniaturization reduces cost curves for frequency-modulation circuits.
The EPA regulates chemical active ingredients through FIFRA registration mandates that govern label claims and application rates for residential outdoor use. The EU REACH framework and RoHS directives constrain substance composition for devices imported into European markets, compelling reformulation of legacy repellent chemistries. California's Department of Pesticide Regulation maintains the nation's most restrictive state-level propositions on neonicotinoid and pyrethroid deployment. Stakeholders must monitor evolving pollinator-protection protocols that threaten to reclassify broad-spectrum outdoor sprays and reshape permissible application windows across multiple jurisdictions.
Market Dynamics
IoT-enabled perimeter monitoring systems are restructuring competitive advantage in outdoor pest control, as semiconductor miniaturization collapses cost barriers for connected sensor deployment while EPA FIFRA registration timelines lengthen for chemical alternatives.
Growth Catalysts
- Warm-climate replacement cycles:Suburban homeowners in Florida, Texas, and Arizona replace seasonal outdoor protection equipment annually, sustaining baseline demand for electromechanical and electronic repellent systems.
- REACH substance restrictions:The EU's evolving chemical framework is accelerating reformulation toward biological active ingredients, opening premium positioning for enzyme-based and pheromone-dispensing device categories.
- UV-LED attractant maturation:Solid-state ultraviolet emitters now achieve wavelength precision matching insect phototaxis peaks, improving trap efficacy while reducing power consumption versus legacy fluorescent tubes.
Market Restraints
- Neonicotinoid regulatory compression:California's Department of Pesticide Regulation and parallel state-level propositions are eliminating broad-spectrum chemistries from residential outdoor formulations, forcing costly active ingredient substitutions.
- Semiconductor supply concentration:Frequency-modulation chips for ultrasonic repellers source primarily from East Asian foundries, exposing manufacturers to geopolitical disruption in microcontroller and MEMS component flows.
- Acoustic efficacy boundaries:Ultrasonic frequency propagation degrades beyond 15 meters in humid conditions, constraining perimeter coverage claims and limiting single-device protection zones for large residential lots.
Strategic Opportunities
- Subscription hardware models:Device-as-a-service platforms incorporating seasonal cartridge replenishment and mobile app monitoring are penetrating high-income suburban zip codes, locking in recurring revenue streams.
- Smart home ecosystem integration:API connectivity with Amazon Alexa and Google Home ecosystems enables voice-activated perimeter activation, differentiating premium electronic repellent lines from standalone competitors.
- Texas and Florida municipal procurement:County vector control agencies are piloting residential-scale trap networks for mosquito-borne disease monitoring, creating institutional demand channels beyond traditional retail.
Industry Challenges
- IPX4+ weatherproofing certification timelines:Extended enclosure testing protocols for sustained outdoor deployment delay product launch windows and inflate pre-market engineering expenditures.
- Firmware cybersecurity compliance:Connected devices face emerging FCC and state-level data privacy mandates for IoT endpoints, requiring ongoing security patch infrastructure that legacy manufacturers lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home Outdoor Pest Control Devices Market |
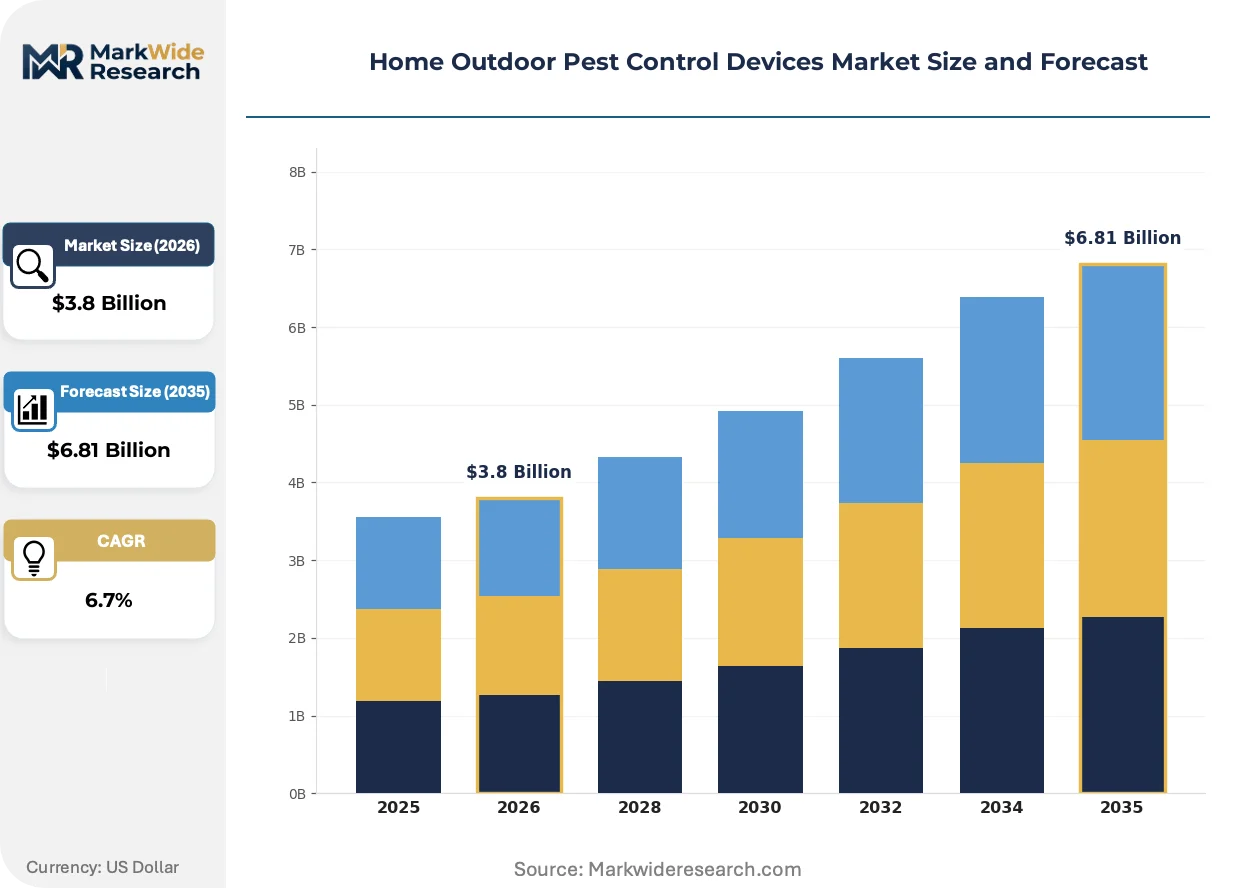
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sprays, Traps, Ultrasonic Repellers, Granules Technology: Chemical, Biological, Electronic, Natural Application: Gardens, Patios, Lawns, Decks End User: Homeowners, Renters, Landscapers, Property Managers |
| Companies Covered | Bird-X, Flowtron, Woodstream Corporation, Aspectek, Nixalite of America, Bell Laboratories, Spectrum Brands Holdings, Rentokil Initial plc, Thermacell, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home Outdoor Pest Control Devices Market Strategic Shifts
Three intersecting developments are compressing product lifecycles and redrawing competitive boundaries: connected hardware architectures, regulatory chemistry constraints, and shifting homeowner procurement preferences toward integrated smart home ecosystems.
Frequency-modulated ultrasonic repellers are migrating from fixed single-frequency emission to adaptive algorithms that cycle through variable wavelengths to prevent pest habituation. Early-adopter households in suburban Atlanta and Phoenix are replacing static units at accelerated intervals. This migration from deterministic to stochastic acoustic output is compressing replacement cycles while raising average selling prices for algorithm-enabled hardware.
EPA's evolving pollinator-protection protocols under FIFRA are reclassifying permissible application windows for pyrethroid-based outdoor sprays. The industrial consequence is a forced pivot toward electromechanical and biological modalities in product development pipelines. Warm-climate states with extended mosquito seasons face the most acute formulation constraints, driving fastest adoption of UV-LED and CO2-baited trap systems as chemical alternatives.
Homeowner buying patterns are fragmenting across direct-to-manufacturer subscription portals and big-box retail, with the former capturing high-engagement customers seeking mobile monitoring capabilities. Amazon and specialized pest control e-commerce platforms are disintermediating traditional home improvement store dominance for replacement cartridge and accessory sales. This channel bifurcation is most pronounced in coastal California and Pacific Northwest metropolitan areas where smart home penetration exceeds national baselines.
Home Outdoor Pest Control Devices Market Segmentation
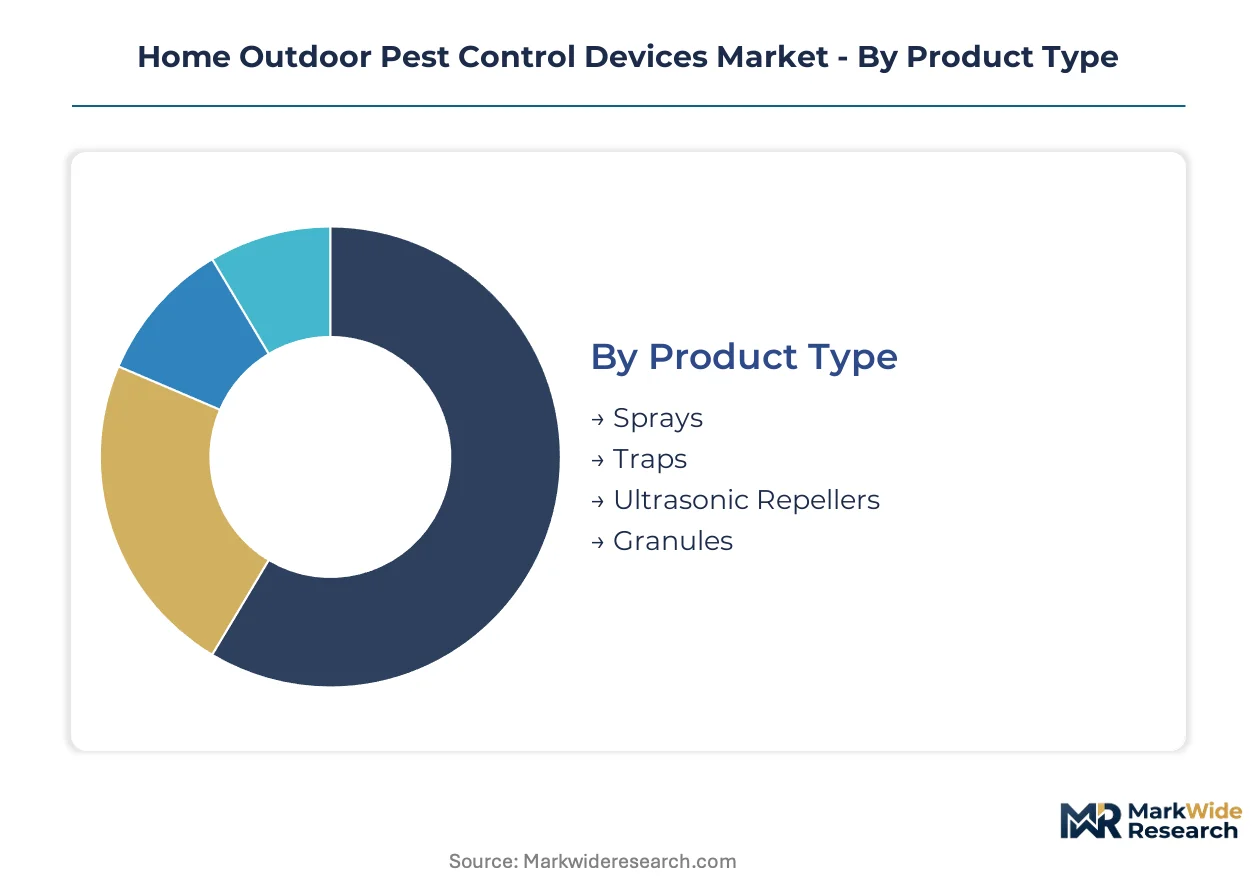
Home outdoor pest control devices fragment across four intersecting dimensions that determine procurement patterns, regulatory exposure, and replacement cycles. Product type and technology choices drive hardware margins, while application context and end-user identity shape distribution channel selection and seasonal demand timing.
Product Type:
Residential exterior environments demand differentiated deployment formats based on pest species, coverage area, and human activity patterns.
- Sprays:Pressurized liquid formulations deliver immediate perimeter knockdown for mosquitoes, ants, and flying insects. Demand concentrates in suburban Texas and Florida households preparing for summer entertaining seasons, constrained by EPA FIFRA registration delays for reformulated pyrethroid alternatives.
- Traps:Electromechanical units combining UV-LED attractants with adhesive or electric capture mechanisms target specific vector species. Adoption accelerates in California coastal communities where municipal vector control agencies subsidize residential trap networks for West Nile surveillance.
- Ultrasonic Repellers:Frequency-modulation devices emit variable-wavelength acoustic barriers against rodents and insects. Compact semiconductor packages now enable sub-$30 retail pricing for entry-tier hardware.
- Granules:Slow-release pellet formulations provide extended soil-barrier protection against lawn-dwelling pests. Landscapers in Phoenix and Atlanta metropolitan areas specify bulk-format procurement for recurring seasonal applications.
Established volume favors Sprays; emerging adoption favors Traps.
Technology:
Active ingredient and energy-source selection determines regulatory pathway, manufacturing location, and premium pricing eligibility.
- Chemical:Synthetic pyrethroid and organophosphate formulations dominate unit economics through concentrated active loading and established supply chains. California Department of Pesticide Regulation restrictions on neonicotinoids are forcing active ingredient substitutions that extend reformulation timelines.
- Electronic:Solid-state electromechanical systems eliminate residue concerns and enable connected monitoring architectures. Smart home integration capabilities in premium lines command 40-60% price premiums over standalone units in Seattle and Portland markets.
- Biological:Enzyme-based and pheromone-dispensing modalities target environmentally conscious homeowners willing to accept slower onset for reduced ecological impact. REACH substance restrictions in European markets accelerate biological pipeline investment.
- Natural:Essential oil and plant-derived repellent formulations leverage consumer perception of safety for pet-accessible outdoor spaces. Retail shelf placement competes directly with chemical alternatives in mass-market channels.
Revenue concentration sits with Chemical; steepest expansion trajectory belongs to Electronic.
Application:
Physical deployment context dictates weatherproofing requirements, coverage specifications, and replacement frequency.
- Gardens:Pollinator-sensitive zones require selective targeting that excludes flowering vegetation. Biological and natural modalities gain preference where bee populations are active.
- Patios:Immediate human proximity demands rapid-acting formats with minimal odor persistence. Ultrasonic and electronic systems dominate this high-visibility entertaining space.
- Lawns:Large-area coverage favors broadcast application formats and perimeter barrier systems. Granule and spray combinations address subsurface pest pressure.
- Decks:Elevated wooden structures attract specialized wood-boring and nesting species. Targeted trap placement addresses confined spatial geometry.
Volume leadership resides in Lawns; premium positioning concentrates in Patios.
End User:
Procurement authority and technical sophistication fragment across residential tenure types and professional service relationships.
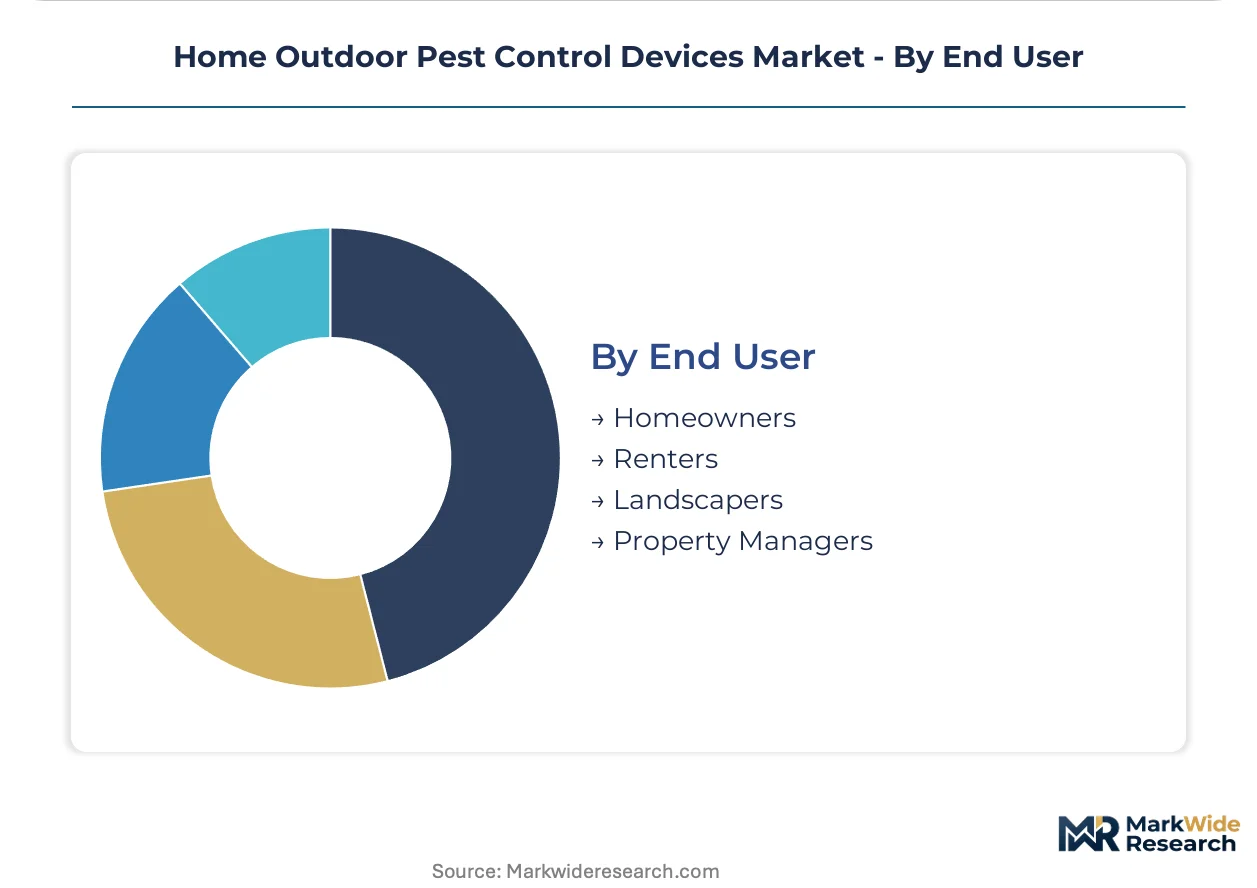
- Homeowners:Permanent residents invest in durable hardware with multi-season depreciation. Smart home ecosystem compatibility influences premium purchase decisions in high-income zip codes.
- Renters:Transient tenure favors portable, non-permanent formats without installation requirements. Subscription cartridge replenishment models reduce upfront capital commitment.
- Landscapers:Commercial maintenance contractors prioritize bulk procurement economics and application efficiency. Professional-grade formulations with extended residual activity reduce service call frequency.
- Property Managers:Multi-unit residential operators balance tenant complaint resolution with liability exposure. Standardized deployment protocols across property portfolios enable volume purchasing leverage.
Transaction volume flows through Homeowners; margin expansion targets Property Managers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in outdoor pest control hardware tilt toward net importing in high-consumption markets, with manufacturing concentration in East Asian electronics clusters supplying North American and European retail channels. Trade flows reflect regulatory divergence on chemical active ingredients, pushing device-format substitution in jurisdictions with stricter residue standards.
United States
Suburban homeowners in Florida, Texas, and Arizona drive replacement cycles for seasonal electromechanical protection systems. EPA FIFRA registration timelines for reformulated pyrethroid alternatives extend product development windows. The Dallas-Fort Worth metroplex anchors distribution infrastructure for bulk-format granule procurement serving professional landscaping contractors.
Germany
REACH substance restrictions accelerate demand for biological and electronic modalities over residual chemical sprays. ECHA evaluations of neonicotinoid alternatives force active ingredient substitutions in cross-border formulations. The Rhine-Ruhr industrial corridor concentrates precision electronics manufacturing for frequency-modulation components used in ultrasonic repeller assembly.
China
Domestic manufacturing capacity for UV-LED emitters and microcontroller assemblies supplies global OEM procurement for connected trap systems. MIIT standards for IoT device cybersecurity impose firmware certification requirements on export-bound hardware. The Pearl River Delta cluster dominates semiconductor packaging for MEMS-based acoustic sensor modules.
United Kingdom
Smart home ecosystem penetration in Greater London and Southeast England drives premium positioning for API-integrated electronic repellent lines. HSE regulations on amateur-use pesticide formulations constrain retail spray availability. The Midlands manufacturing belt hosts enclosure fabrication for IPX4+ weatherproofing certification required in North American export markets.
Australia
Extended mosquito seasons in Queensland and New South Wales sustain elevated demand for CO2-baited trap networks. APVMA registration requirements for biological active ingredients lag European timelines, delaying product launch windows. Sydney and Melbourne metropolitan areas concentrate direct-to-consumer subscription platform adoption for cartridge-replenishment service models.
Home Outdoor Pest Control Devices Market Competitive Environment
On the supply side, the industry is moderately consolidated around diversified consumer goods conglomerates with parallel household product portfolios, while specialized electromechanical manufacturers occupy defended niches in electronic attractant technologies. Three strategic archetypes dominate: heritage electronics specialists with UV-LED engineering depth, diversified chemical-device hybrids with retail channel control, and subscription-platform insurgents capturing recurring revenue through connected hardware. Competitive moves center on M&A absorption of biological formulation startups and strategic partnerships with smart home ecosystem providers for API integration.
Among heritage electronics specialists, Flowtron and Aspectek exemplify engineering-led positioning in solid-state attractant systems, while Woodstream Corporation and Spectrum Brands Holdings anchor the diversified conglomerate tier with cross-format portfolio coverage spanning chemical, electronic, and natural modalities. Rentokil Initial plc occupies a distinct position bridging commercial pest control service networks with residential device distribution, leveraging institutional vector control relationships to penetrate municipal procurement channels in warm-climate states.
| Leading Market Players |
|---|
| Bird-X |
| Flowtron |
| Woodstream Corporation |
| Aspectek |
| Nixalite of America |
| Bell Laboratories |
| Spectrum Brands Holdings |
| Rentokil Initial plc |
| Thermacell |
| Others |
Value Chain & Pricing Dynamics
Semiconductor supply concentration in East Asian foundries exposes manufacturers to tariff volatility that widens pricing spreads between premium connected units and entry-tier standalone hardware while compressing margins across mid-tier offerings. This dependency simultaneously shapes inventory positioning strategies and tiered product architectures as vendors buffer against component flow disruption.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Premium electronic systems with smart home API integration command substantial markups over standalone ultrasonic units, while certification tier—specifically FCC Part 15 compliance for IoT endpoints—separates price bands. Cost compression in entry-tier hardware is intensifying because microcontroller price volatility feeds directly into bill-of-materials pressure. Property managers demonstrate lowest price sensitivity due to portfolio-standardization requirements, whereas renters exhibit highest sensitivity favoring subscription models with minimal upfront capital.
Supply Chain Analysis
Export control restrictions on frequency-modulation chip architectures constrain component sourcing for ultrasonic repeller manufacturers. Manufacturing concentrates in China, Taiwan, and South Korea for UV-LED emitters, MEMS acoustic sensors, and microcontroller assemblies. Raw material dependencies span gallium nitride substrates, rare-earth phosphors, and weatherproof polymer resins. Single-source vulnerability in East Asian semiconductor packaging creates exposure to geopolitical disruption. Distribution runs through big-box retail channels for hardware and direct-to-manufacturer portals for subscription replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from seasonal cartridge replenishment and mobile app monitoring is expanding faster than hardware unit sales, repositioning vendor economics toward recurring relationship models. This shift elevates software infrastructure and logistics integration as competitive differentiators alongside physical product engineering.
For Market Incumbents: Pre-empt subscription-platform insurgents by acquiring biological formulation startups with EPA FIFRA registration pipelines already in progress. Lock in exclusive API integration partnerships with Amazon Alexa and Google Home ecosystems before smart home penetration saturates in coastal metropolitan markets. Vertical integration into UV-LED emitter manufacturing mitigates East Asian supply concentration risk. For New Entrants and Emerging Players: Build out direct-to-consumer subscription platforms targeting high-income suburban zip codes in Texas and Florida where replacement cycles are annual and smart home adoption exceeds national baselines. The most penetrable white space sits in municipal vector control procurement channels, where county agencies pilot residential-scale trap networks for disease surveillance. A go-to-market angle emphasizing firmware cybersecurity compliance differentiates against legacy manufacturers lacking patch infrastructure. For Investors and Strategic Acquirers: EPA pollinator-protection protocol evolution reshapes the acquisition landscape toward electromechanical and biological modality specialists with reformulated active ingredient pipelines. Long-term viability favors targets with diversified technology portfolios spanning chemical, electronic, and natural formats rather than pure-play chemical formulators exposed to regulatory compression. The specific signal to watch is California Department of Pesticide Regulation neonicotinoid restriction expansion into pyrethroid reclassification.| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Platform Launch | Captures recurring revenue through seasonal cartridge replenishment and mobile monitoring in high-income suburban markets. |
| Smart Home API Integration | Enables voice-activated perimeter control via Amazon Alexa and Google Home ecosystems, differentiating premium electronic lines. |
| Biological Formulation Acquisition | Accelerates EPA FIFRA registration timelines for enzyme-based alternatives as pyrethroid restrictions tighten. |
| UV-LED Manufacturing Scale-Up | Reduces dependency on East Asian foundries for solid-state attractant components critical to next-generation trap systems. |
| Municipal Procurement Partnership | Opens institutional demand channels through county vector control agency pilot programs for residential-scale disease surveillance networks. |
Study Parameters
The analysis maps electronic, chemical, biological, and natural modality sub-sectors, each validated through product managers at diversified consumer goods conglomerates, electromechanical engineering leads at heritage electronics specialists, regulatory affairs directors navigating EPA FIFRA timelines, and procurement officers at big-box retail chains. Primary interview insights triangulate against secondary sources including EPA registration databases, ECHA REACH substance restriction updates, SEC 10-K disclosures from listed parent companies, and customs trade flow records for UV-LED and microcontroller import volumes. Bottom-up unit shipment estimates and top-down market value reconstructions converge through iterative stakeholder validation.
Assumptions regarding EPA FIFRA registration timeline stability, East Asian semiconductor supply continuity, and smart home ecosystem penetration rates were held fixed across the modeling period, while warm-climate replacement cycle intensity and municipal procurement pilot expansion were varied as sensitivity parameters. Segmentation dimensions include product type, technology modality, application context, and end-user identity, with CAGRs derived from regression analysis against historical shipment correlations with housing starts and seasonal temperature indices. Forecast inputs incorporate pollinator-protection protocol evolution trajectories and REACH substance restriction phased implementation schedules.
Stress conditions across semiconductor supply disruption severity, pyrethroid reclassification acceleration, and connected device cybersecurity mandate timing were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory pathway stability and component sourcing geography. Material shifts in EPA pollinator-protection protocol scope or East Asian export control expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective Gear
Flavored Condoms Market
Protective Gear
Mobile Phone Protective Cover Market
Protective Gear
Personal Flotation Devices Market
Protective Gear
Pet Control Devices Market
Protective Gear
Earplugs Market
Protective Gear
Diving Suits Market
Protective Gear
Mobile Protective Cases Market
Protective Gear
UK Mobility Devices Market
Protective Gear
Work Shoes Market
Protective Gear
Disposable Hygiene Footwear Market
Protective Gear
Safety Shoes Market
Protective Gear
Europe Protective Footwear Market
Protective Gear
Waterproof Cases Market
Protective Gear
Battery Heated Gloves Market
Protective Gear
Europe Lanyards Market
Protective Gear
Food Processing Uniforms Market