
 Retail Point of Sale (POS) Market | 2026-2036
Retail Point of Sale (POS) Market Size, Share, and Industry Trends Forecast 2026-2036
Retail Point of Sale (POS) Market Analytics
The EU Green Deal's digital transition requirements is shifting procurement priorities toward energy-efficient POS terminals across European retail chains. Shopify leverages its commerce platform integration to anchor cloud-based POS adoption among mid-market merchants. Square competes through its integrated hardware-software ecosystem that spans payment processing and business analytics. Epos Now specializes in sector-specific configurations for hospitality and retail verticals, sustaining differentiated positioning against horizontal rivals.
Retail Point of Sale (POS) systems encompass hardware terminals, software applications, and payment processing infrastructure that record transactions, manage inventory, and capture customer data at the point of purchase, typically operating with EMV chip compatibility, NFC contactless readers, and cloud synchronization protocols to enable real-time sales analytics and unified commerce operations. Mobile POS terminals lead volume growth as merchants prioritize line-busting flexibility and pop-up retail deployment, while cloud-based POS captures expanding margin pools through recurring software subscriptions and integrated payment monetization. Traditional POS retains dominance in large-format grocery and department store environments where fixed-lane infrastructure and complex peripheral integration remain essential.
FDA guidelines on consumer data protection intersect with PCI DSS standards and FCC equipment authorization requirements to mandate encrypted transaction processing and secure hardware certification for POS devices deployed in US retail environments. The EU AI Act and GDPR frameworks impose algorithmic transparency and data minimization obligations on POS systems that deploy personalized pricing or loyalty analytics across European markets. Stakeholders must monitor evolving biometric payment authentication standards and central bank digital currency pilot programs that could recalibrate terminal hardware specifications and processor certification pathways.
Market Dynamics
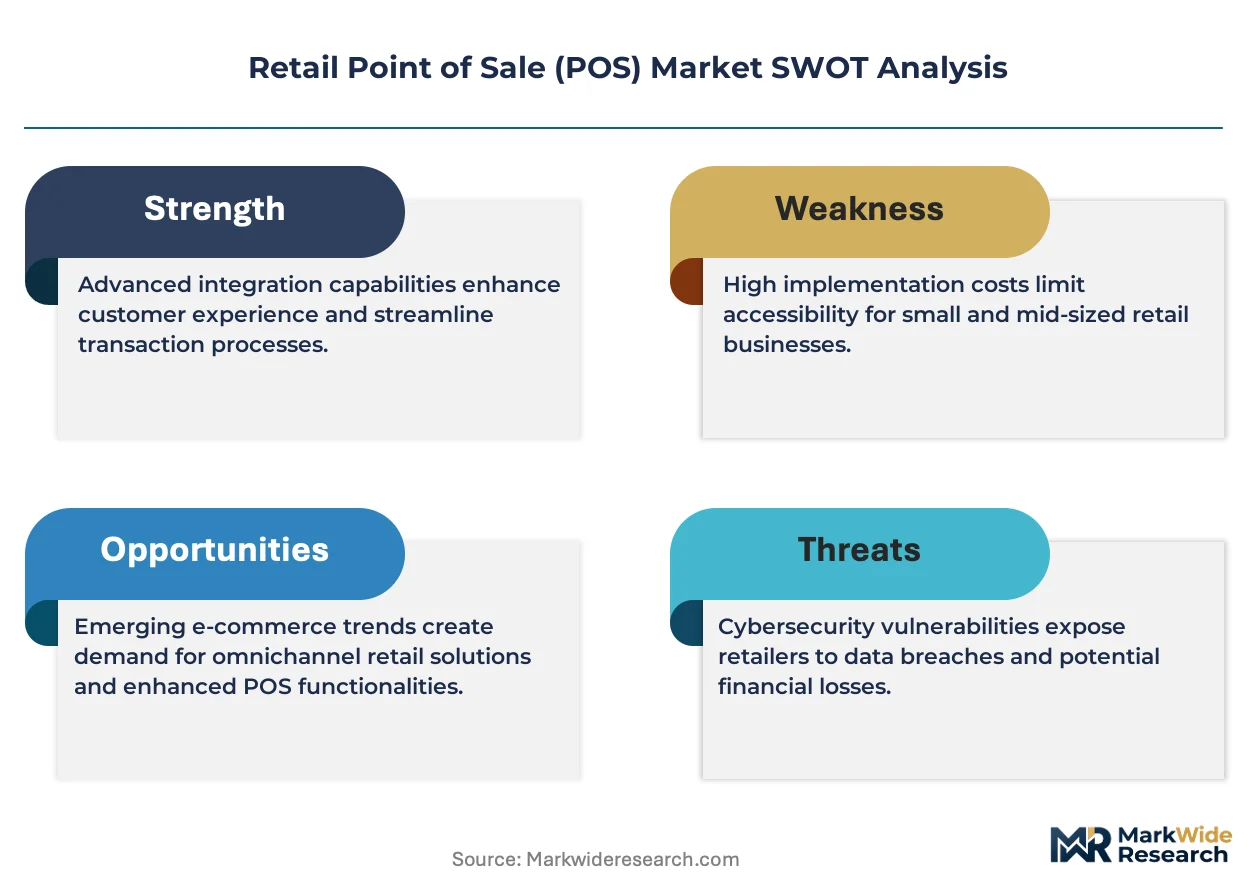
The migration from on-premise to cloud-native POS architectures is compressing replacement cycles and redistributing vendor margins toward software subscriptions, forcing hardware manufacturers to anchor recurring revenue streams.
Growth Catalysts
- Contactless payment mandates:PCI DSS compliance deadlines in the United States and EMV liability shifts are accelerating terminal refresh programs among mid-tier retailers.
- Quick-service restaurant digitization:Mobile POS adoption is reducing checkout friction across drive-thru and curbside formats, expanding addressable hardware volume.
- EU Green Deal procurement rules:Energy-efficiency criteria are redirecting European retail chain capital toward low-power terminal portfolios.
Market Restraints
- Semiconductor supply concentration:Taiwan and South Korea dominate NFC chip fabrication, exposing terminal manufacturers to allocation volatility.
- Legacy system integration costs:Custom middleware development for ERP connectivity consumes 15-25% of deployment budgets in grocery and department store segments.
- Biometric authentication uncertainty:Pending ISO/IEC 30107-3 certification timelines are freezing fingerprint and facial recognition feature rollouts.
Strategic Opportunities
- Central bank digital currency pilots:China's e-CNY and India's digital rupee programs are recalibrating processor certification pathways for CBDC-compatible terminals.
- Hospitality vertical specialization:Tableside ordering and split-check functionality represent underpenetrated configuration demand across independent restaurants.
- Unified commerce convergence:Integration of inventory, loyalty, and payment data across online and physical channels is creating white space for API-first platform vendors.
Industry Challenges
- Embedded software talent scarcity:Firmware engineers with EMV kernel and PCI PTS expertise command premium compensation, constraining R&D scaling.
- Multi-jurisdiction certification complexity:Separate FCC, CE marking, and BIS approval processes extend hardware launch timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Retail Point of Sale (POS) Market |
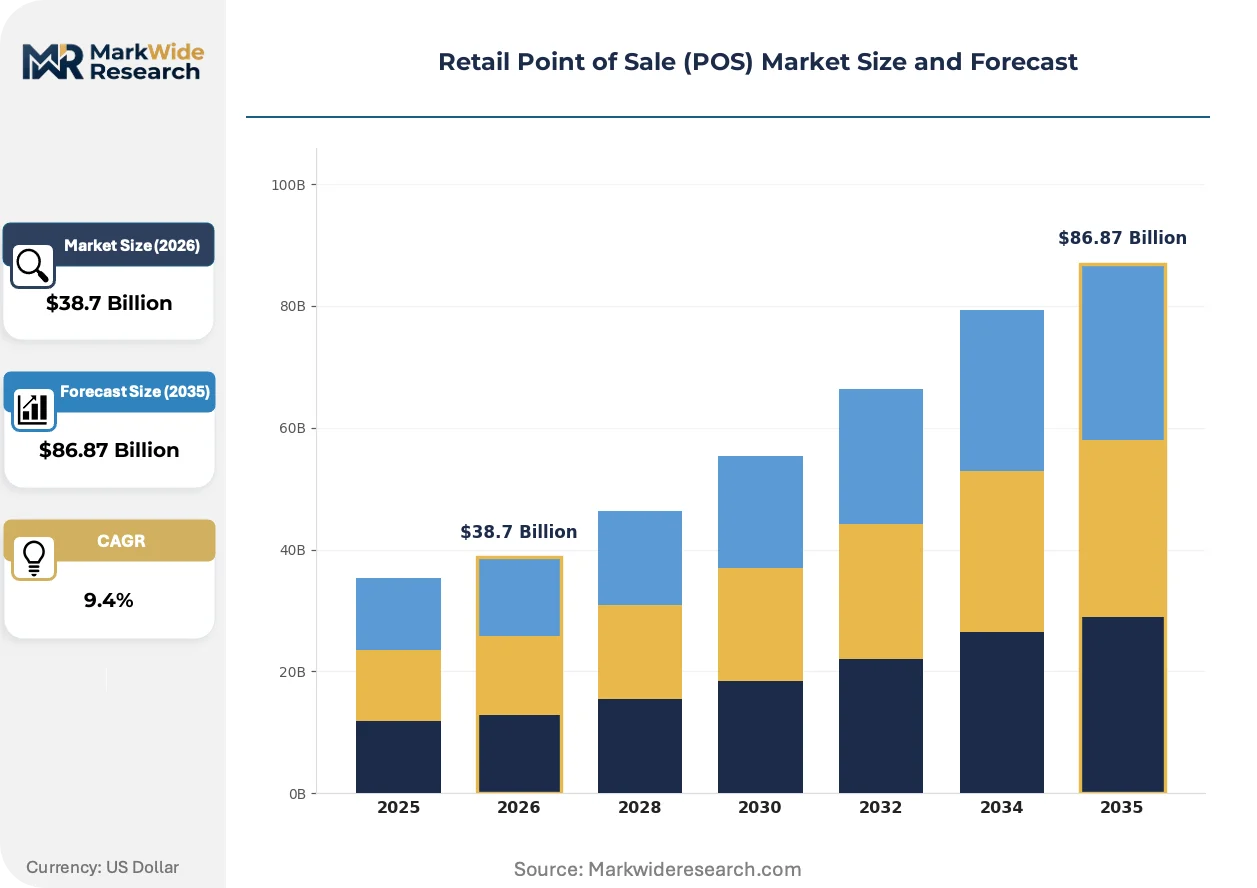
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $86.87 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Traditional POS, Mobile POS, Cloud-based POS, Self-service Kiosks End User: Retail Stores, Restaurants, Hotels, E-commerce Payment Method: Credit Card, Debit Card, Mobile Payments, Gift Cards Deployment Model: On-premise, Cloud-hosted, Hybrid, Managed Services |
| Companies Covered | GoDaddy, Epos Now, Shopify, AirPOS, Helcim, Square, Clover, SumUp, Lightspeed, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Retail Point of Sale (POS) Market Evolving Landscape
Payment terminal architecture is converging with retail software platforms, compressing the distinction between transaction hardware and commerce operating systems. Three developments are restructuring competitive positioning.
Android-based open-platform terminals are consolidating merchant preference by enabling third-party application deployment alongside payment processing. Mid-market retailers in the United States and Germany are adopting these devices at twice the rate of proprietary closed systems. This consolidation is eroding hardware margins while expanding software monetization opportunities for platform orchestrators.
The EU AI Act's risk classification framework is imposing algorithmic transparency obligations on POS systems deploying dynamic pricing or loyalty analytics. European retailers must now maintain audit trails for automated decision-making affecting consumer transactions. Hospitality chains in France and Spain are responding by simplifying recommendation engines to reduce compliance surface area.
Merchant acquisition models are fragmentating as independent software vendors bypass traditional ISO channels to embed payment processing directly. Shopify and Square's direct-to-merchant approaches are compressing reseller margins and forcing incumbent acquirers to unbundle hardware from processing contracts. This disintermediation is most pronounced among e-commerce-native brands expanding into physical retail in the United Kingdom and Australia.
Retail Point of Sale (POS) Market Segmentation
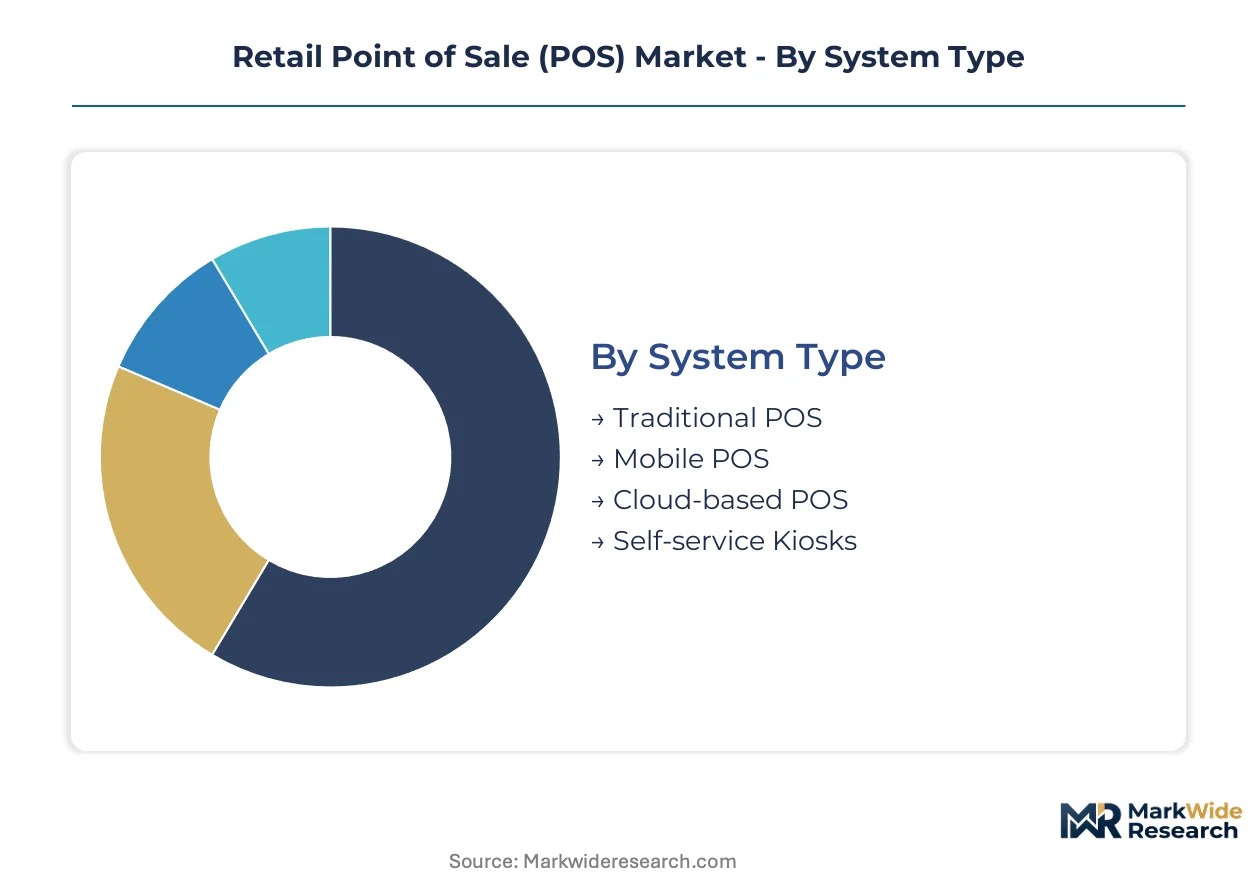
POS segmentation reveals how hardware-software integration depth varies dramatically across merchant tiers. Understanding these divides exposes where cloud-native platforms displace legacy infrastructure versus where fixed-lane systems retain structural advantages.
System Type:
Standalone terminals dominate high-volume grocery environments while embedded tablet-based systems penetrate hospitality and pop-up retail.
- Traditional POS:Fixed-lane terminals with integrated peripherals—receipt printers, barcode scanners, cash drawers—process transactions through on-premise servers. Grocery chains and department stores in the United States deploy these for checkout lane throughput requirements and complex peripheral orchestration.
- Mobile POS:Tablet or smartphone-based terminals with Bluetooth-connected card readers enable line-busting and curbside payment capture. Quick-service restaurants across the United States and Germany adopt these to reduce drive-thru friction and support pop-up retail formats.
- Cloud-based POS:Browser-native applications running on generic tablets route transactions through remote servers, minimizing local infrastructure. Mid-market merchants in the United Kingdom and Australia favor these for real-time inventory synchronization across multiple locations.
- Self-service Kiosks:Freestanding touchscreen terminals with integrated payment acceptance enable customer-directed ordering and checkout. Fast-casual restaurant chains deploy these for labor cost reduction and order accuracy improvement.
Traditional POS leads volumes today; mobile POS is gaining share fastest.
End User:
Integration complexity scales with transaction volume and peripheral count, separating high-throughput fixed installations from flexible mobile deployments.
- Retail Stores:Grocery, apparel, and specialty merchants require inventory management integration, loyalty program connectivity, and high-volume payment processing. Large-format retailers in the United States maintain substantial traditional POS infrastructure while adding mobile terminals for seasonal peak capacity.
- Restaurants:Tableside ordering, kitchen display integration, and split-check functionality define hospitality-specific configurations. Independent restaurants in France and Spain prioritize mobile POS for table-turn efficiency and tip distribution automation.
- Hotels:Property management system integration, folio charging, and multi-outlet reconciliation distinguish lodging deployments. Boutique properties favor cloud-based systems for front-desk mobility and spa or restaurant outlet unification.
- E-commerce:Omnichannel merchants require unified inventory visibility across warehouse and physical locations, with buy-online-pickup-in-store transaction reconciliation. Direct-to-consumer brands expanding into physical retail in the United Kingdom drive hybrid deployment demand.
Retail stores anchor installed base; restaurants show steepest expansion trajectory.
Payment Method:
Terminal hardware specifications diverge based on authentication technology and network routing requirements.
- Credit Card:EMV chip contact and contactless acceptance with PCI PTS-certified encryption modules remains the baseline hardware requirement. United States liability shift deadlines continue driving terminal refresh cycles among mid-tier merchants.
- Debit Card:PIN entry device certification and regional network routing—Interlink, Plus, Cirrus—require additional hardware compliance layers. European markets mandate strong customer authentication through PIN or biometric verification.
- Mobile Payments:NFC antenna configuration and tokenization protocol support enable Apple Pay, Google Pay, and Samsung Pay acceptance. Urban markets in Germany and the United Kingdom show highest tap-to-pay penetration.
- Gift Cards:Closed-loop and open-loop stored value processing demands loyalty platform integration and real-time balance inquiry capability. Hospitality chains deploy these for breakage revenue capture and customer retention programs.
Credit card acceptance remains universal; mobile payments climb the fastest.
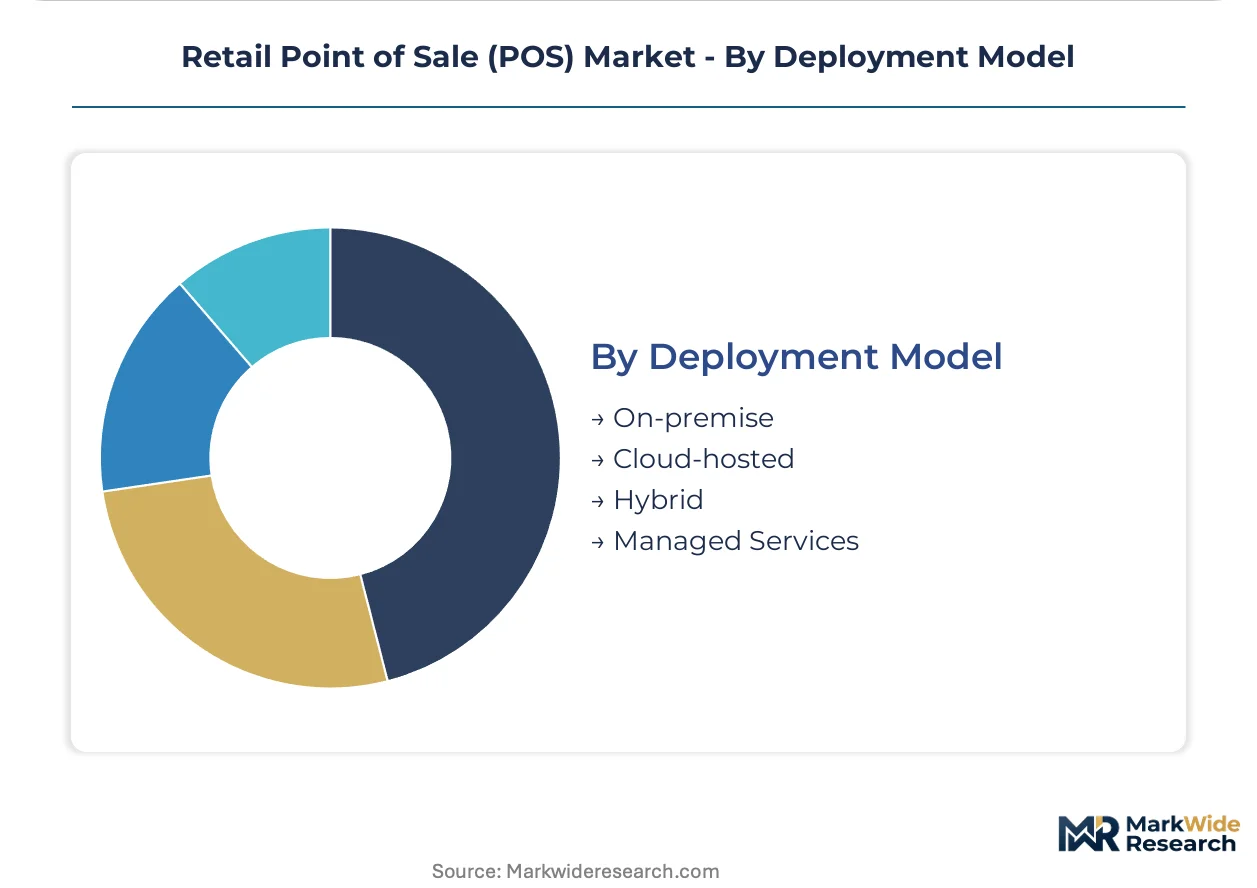
Deployment Model:
Control over data residency and upgrade cadence separates merchant preferences across risk tolerance and IT staffing levels.
- On-premise:Local server installation with dedicated network infrastructure provides maximum transaction control and customization depth. Large grocery chains maintain these for sub-second response times and disaster recovery autonomy.
- Cloud-hosted:Vendor-managed infrastructure with automatic software updates and elastic capacity scaling reduces internal IT burden. Mid-market retailers across Australia and the United Kingdom migrate here to eliminate server maintenance costs.
- Hybrid:Core transaction processing on-premise with analytics and reporting in cloud environments balances latency requirements with remote access convenience. Multi-location hospitality groups favor this for centralized menu management with local payment continuity.
- Managed Services:Outsourced terminal provisioning, help desk support, and compliance monitoring bundled into per-transaction fees. Small independent merchants accept margin compression for operational simplicity.
On-premise retains largest installed base; cloud-hosted expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
POS engineering talent clusters in the United States, Germany, and India anchor regional development velocity. Terminal manufacturers concentrate firmware expertise in Bangalore and Shenzhen. Cloud-native platform architects dominate London and San Francisco hiring markets.
United States
Quick-service restaurant chains drive mobile POS refresh cycles across 50,000+ locations. FCC equipment authorization mandates and PCI DSS compliance deadlines accelerate terminal replacement through 2026. Dallas-Fort Worth hosts major payment processor headquarters where hardware-software integration teams expand.
Germany
Retail chains prioritize energy-efficient terminal portfolios under EU Green Deal procurement rules. Strong customer authentication requirements through the national banking regulator shape PIN entry device specifications. Berlin's fintech corridor attracts cloud POS engineering talent from London and Amsterdam.
United Kingdom
Mid-market merchants adopt cloud-based systems for omnichannel inventory synchronization. GDPR frameworks impose audit trail requirements on loyalty analytics engines. Manchester hosts independent software vendors embedding payment processing directly into retail platforms.
India
The digital rupee pilot program recalibrates processor certification pathways for CBDC-compatible terminals. BIS approval processes extend hardware launch timelines for international manufacturers. Bangalore concentrates embedded firmware engineers with EMV kernel expertise.
Australia
Small independent merchants favor managed services models bundling terminal provisioning and compliance monitoring. The national payments network mandates contactless acceptance standards. Sydney hosts Asia-Pacific headquarters for cloud POS platform expansion.
Retail Point of Sale (POS) Market Competitive Landscape
Capital-heavy terminal manufacturers compete with asset-light software platforms for merchant relationships. The vendor base fragments across four distinct tiers: integrated commerce platforms, payment-focused hardware specialists, sector-specific configurators, and managed service aggregators. Dominant competitive moves include API-first platform unification and direct-to-merchant acquisition channel bypassing traditional ISO networks.
Within the integrated commerce tier, Shopify and Square exemplify platform orchestration strategies that compress hardware margins while expanding software monetization. Epos Now occupies a position among sector-specific configurators targeting hospitality and retail verticals with differentiated positioning against horizontal rivals. SumUp represents the mobile-first hardware specialist archetype emphasizing line-busting flexibility for pop-up retail formats.
| Leading Market Players |
|---|
| GoDaddy |
| Epos Now |
| Shopify |
| AirPOS |
| Helcim |
| Square |
| Clover |
| SumUp |
| Lightspeed |
| Others |
Value Network & Pricing Analysis
EU Green Deal procurement mandates for energy-efficient terminals are forcing manufacturers to redesign power architectures and absorb certification costs, compressing margins on standard-tier hardware while opening premium pricing for compliant portfolios. This demand-side specification shift redistributes pricing power toward vendors with pre-certified low-power designs.
Pricing Analysis
Bundled hardware-software subscription models dominate mid-market cloud POS, while unbundled terminal sales persist in large-format grocery where legacy integration demands custom middleware. Price differentiation rests on PCI PTS certification tier and after-sales service bundling, with certified encryption modules commanding sustained premiums. Cost compression in entry-level mobile readers is intensifying because independent software vendors embed payment processing directly, bypassing traditional reseller markups. Small independent merchants exhibit highest price sensitivity, accepting managed service bundles for operational simplicity, while enterprise retailers prioritize total cost of ownership over upfront hardware expenditure.
Supply Chain Analysis
NFC chip fabrication rests on Taiwanese and South Korean foundries, with EMV kernel development concentrated in Bangalore and Shenzhen engineering centers. Terminal assembly draws from Chinese component ecosystems for displays and batteries, while firmware talent clusters in India and Germany. Single-source vulnerability in advanced semiconductor allocation exposes manufacturers to foundry capacity constraints during demand spikes. Distribution runs through independent sales organizations in North America, direct-to-merchant platforms in the United Kingdom, and managed service aggregators in Australia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Retail POS market reads as a late-cycle quality story where terminal refresh cycles favor vendors with pre-integrated compliance and energy-efficient architectures. Merchant procurement is shifting toward premium specifications that bundle sustainability credentials with security certification.
For Market Incumbents: Anchor recurring revenue streams through cloud-native platform migration, expanding software monetization as hardware margins compress. Deepen backward integration into EMV kernel development to reduce firmware talent dependency and accelerate certification timelines. Defend against independent software vendor disintermediation by unbundling hardware from processing contracts and embedding loyalty analytics directly. For New Entrants and Emerging Players: Capture white space in hospitality vertical specialization, particularly tableside ordering configurations for independent restaurants in France and Spain. Penetrate the managed services tier serving small merchants in Australia and the United Kingdom through per-transaction fee structures that eliminate upfront capital barriers. Lead with API-first platform positioning that enables rapid third-party application deployment on Android-based open terminals. For Investors and Strategic Acquirers: Asymmetric upside sits with sector-specific configurators possessing hospitality and retail vertical expertise that horizontal platforms struggle to replicate. Long-term viability favors vendors with unified commerce data orchestration capabilities spanning inventory, loyalty, and payment channels. Watch central bank digital currency pilot expansions in India and China as inflection indicators requiring processor certification pathway recalibration.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | Compresses hardware margins while expanding recurring software subscription pools across mid-market merchants. |
| Energy-Efficient Terminal Certification | Unlocks EU Green Deal procurement eligibility and commands premium positioning in German retail chains. |
| Vertical Hospitality Specialization | Captures underpenetrated demand for tableside ordering and split-check functionality in independent restaurants. |
| Direct-to-Merchant Acquisition Channel | Bypasses traditional ISO networks and compresses reseller margins in United Kingdom and Australian markets. |
| CBDC-Compatible Processor Development | Positions terminals for India's digital rupee and China's e-CNY pilot program expansion requirements. |
Research Methodology
Coverage spans the United States, Germany, the United Kingdom, India, and Australia, with primary inputs from each market. The analysis combines structured interviews with payment processor executives, POS platform engineers, retail procurement directors, and hospitality operations managers with secondary validation from FCC equipment authorization filings, PCI DSS compliance documentation, EU Green Deal procurement guidelines, and BIS regulatory notices. Bottom-up terminal shipment estimates and top-down payment volume analytics were triangulated to calibrate market sizing.
Rate-of-change decomposition across the projection horizon isolates volume drivers from value migration effects. The analytical framework models segmentation across system type, end-user vertical, payment method, and deployment model, with regional adoption patterns and merchant tier behavior as cross-cutting dimensions. CAGRs were derived from installed base replacement cycles, cloud migration velocity, and contactless payment penetration trajectories. Industry-specific inputs include EMV liability deadline impacts, semiconductor allocation volatility, and biometric authentication certification timelines.
Semiconductor supply disruption, regulatory certification delays, and central bank digital currency program acceleration are the dominant revision risks to terminal demand forecasts. Forecasts reflect assumptions about merchant refresh cadence and cloud adoption velocity that could shift with macroeconomic conditions. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Subscription Billing Management Market
Payments
Asia Pacific Real Time Payment Market
Payments
Mobile Money Market
Payments
Mpos Terminals Market
Payments
Spain POS Terminals Market
Payments
Netherlands Mobile Payments Market
Payments
Canada Gift Card and Incentive Card Market
Payments
India Payment Gateway Market
Payments
Japan Retail Cash Management Market
Payments
Malaysia Payments Market
Payments
Slovenia Point of Sale (POS) Terminal Market
Payments
3D Secure Payment Authentication Market
Payments
Argentina Mobile Wallet Market
Payments
Vietnam Payments Market
Payments
Cryptocurrency Payment Apps Market
Payments
Mexico Real Time Payments Market