
 Plastic Bathtub Market | 2026-2036
Plastic Bathtub Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Bathtub Market Analytics
Chinese acrylic sheet producers is broadening output capacity for thermoformed bathtub shells. TOTO LTD. leverages vertical integration across sanitary ware ceramics and resin-based fixtures to sustain cost discipline. Villeroy & Boch anchors premium positioning through controlled distribution in European design channels. HSIL Limited competes on manufacturing scale across South Asian retail and project segments.
Plastic bathtubs are molded fixtures fabricated from acrylic, fiberglass-reinforced polyester, PVC, or polypropylene, typically vacuum-formed or hand-laid into seamless shells with integral structural ribs and gel-coat finishes. These units serve residential and commercial wet spaces where corrosion resistance, thermal retention, and lower installed weight differentiate them from cast iron or enamel-steel alternatives. Freestanding designs command margin pools in renovation-driven premium segments, while alcove configurations dominate new construction volume through standardized dimensional compatibility. Acrylic material grades lead value contribution due to surface repairability and color stability, though fiberglass-reinforced options occupy contractor channels on price positioning.
EPA standards govern volatile organic compound emissions from gel-coat and resin curing operations in United States manufacturing facilities. REACH restrictions on styrene and phthalate plasticizers constrain formulation choices for European market access, while China's GB standards set baseline mechanical performance and surface quality thresholds for domestic sale. Stakeholders must monitor regulatory divergence between jurisdictions to align product certification investments with prioritized market entry sequencing.
Market Dynamics
Residential renovation cycles in single-family housing developments are compressing replacement timelines for bathroom fixtures, while REACH and EPA emissions protocols force simultaneous reformulation of gel-coat resins and curing processes across manufacturing footprints.
Growth Catalysts
- REACH phthalate restrictions:European formulators are accelerating bio-based plasticizer adoption, creating first-mover certification advantages for compliant bathtub exporters.
- Thermoformed acrylic shells:Vacuum-forming process improvements reduce material waste rates and enable deeper draw ratios for freestanding designs.
- China's domestic production clusters:Concentrated acrylic sheet manufacturing in Zhejiang and Guangdong provinces shortens supply lines for both local consumption and export assembly.
Market Restraints
- Styrene monomer volatility:Unsaturated polyester resin feedstock costs fluctuate with crude oil derivatives, compressing margins on fiberglass-reinforced bathtub lines.
- Cast iron substitution resilience:Premium renovation segments retain preference for enamel-steel thermal mass and acoustic dampening in heritage property restorations.
- Single-source gel-coat supply:Specialty resin formulations for UV-stable surface finishes concentrate among limited European and Japanese chemical suppliers.
Strategic Opportunities
- India's PLI scheme for building materials:Domestic manufacturing incentives reduce import dependency for acrylic sheet and resin compound inputs.
- Smart bathroom integration:Convergence of thermostatic valve controls and embedded sensor arrays creates premium positioning for connected bathtub systems.
- Direct-to-contractor digital platforms:B2B procurement channels bypass traditional distributor markups in North American renovation markets.
Industry Challenges
- Low-VOC curing technician training:EPA-compliant spray booth operations require certified applicators with scarce gel-coat experience.
- Cross-jurisdiction certification timelines:Parallel GB standard testing in China and CE marking in Europe extend product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Bathtub Market |
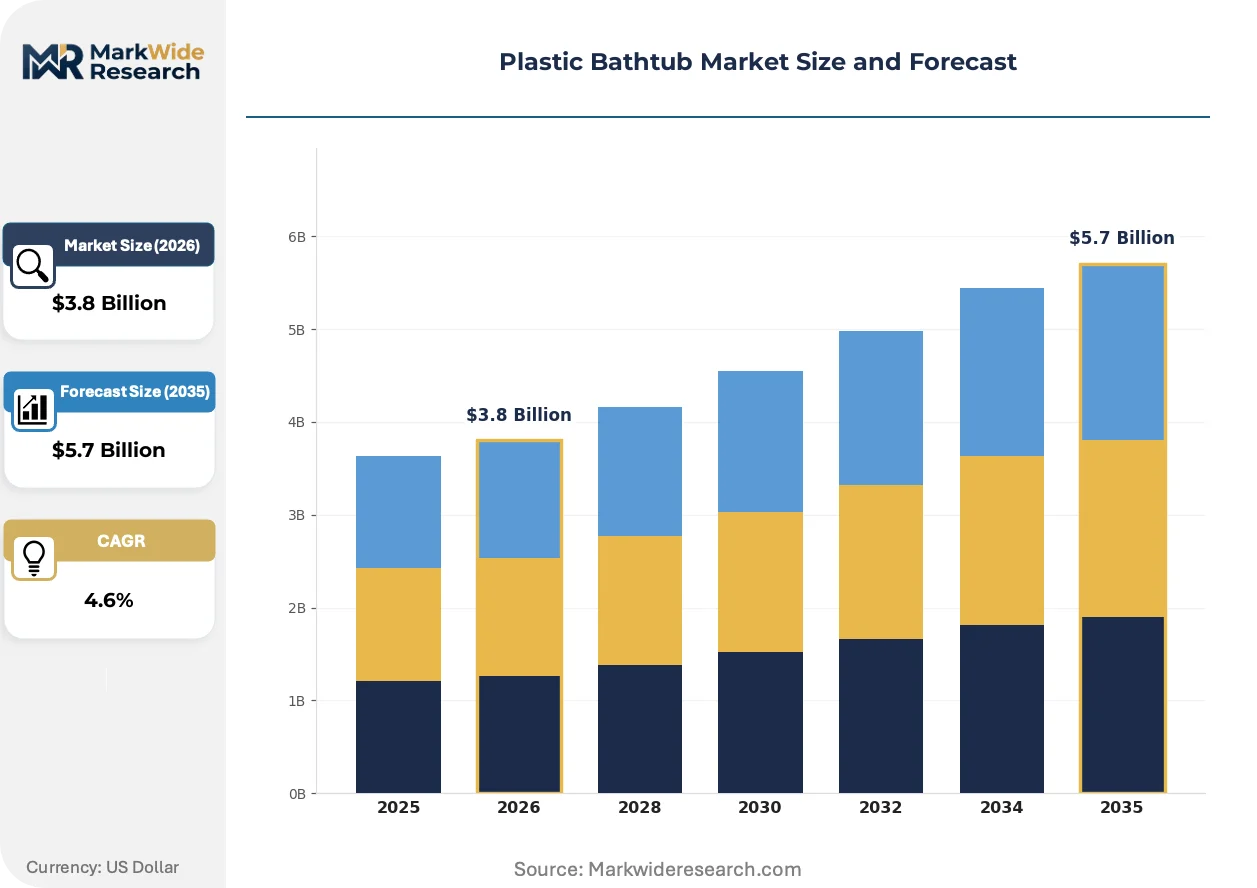
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Freestanding, Alcove, Corner, Drop-in Material: Acrylic, Fiberglass, PVC, Polypropylene Feature: Whirlpool, Walk-in, Soaking, Air Bath Installation: Above Ground, In-ground, Wall-mounted, Integrated |
| Companies Covered | TOTO LTD., Villeroy & Boch, Roca Sanitario, HSIL Limited, OVE Decors, Homefilos, KOBIA Bathtub Manufacturer, Korra Bath Ware Co., Ltd., Asia Billion Innovation Technology Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Bathtub Market Evolving Landscape
Material science advances and regulatory tightening are converging to reshape manufacturing processes, surface performance specifications, and channel economics across plastic bathtub supply chains.
Acrylic-capped ABS composite sheet is absorbing surface repair demand from pure acrylic alternatives, enabling thinner-wall construction with equivalent scratch resistance. Multi-family housing developers in the United States specify these laminates for standardized alcove installations where replacement frequency exceeds repair intent. The technology is absorbing volume from cast polymer segments by matching thermal retention at 40% lower installed weight.
EPA volatile organic compound standards for gel-coat and resin curing operations are tightening permissible emissions thresholds in United States manufacturing facilities. Batch production scheduling now requires extended booth purge cycles or catalytic oxidation investments. Small-to-mid-scale fabricators in Ohio and Tennessee face disproportionate compliance costs versus integrated coastal producers with captive chemical processing.
Certification-driven specification is displacing price-first procurement in European commercial renovation channels. Architects and facilities managers prioritize REACH-compliant surface finishes with documented 10-year color stability warranties. Germany and France exhibit the strongest preference shift, where public housing authorities mandate EPD-certified products for carbon accounting compliance.
Plastic Bathtub Market Segmentation
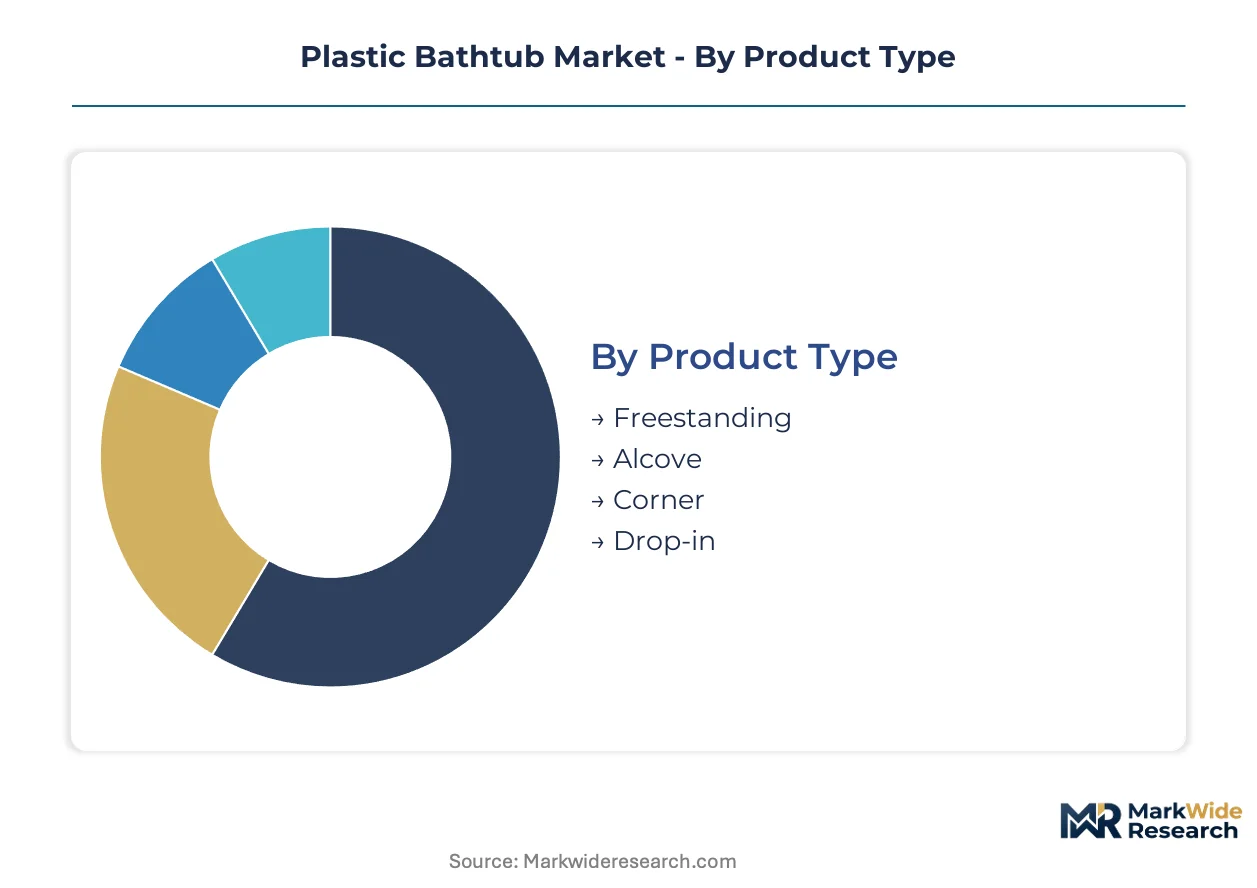
Plastic bathtub procurement splits across four independent decision axes: spatial configuration, material chemistry, functional feature set, and mounting architecture. Each axis carries distinct margin profiles, certification requirements, and channel access patterns that shape manufacturer portfolio strategy.
Product Type:
Architectural footprint and bathroom layout constraints drive specification, with renovation versus new construction creating divergent demand patterns.
- Freestanding:Sculptural monolithic shells in acrylic or cast polymer command premium positioning in master bathroom renovations. Demand concentrates in North American and European single-family housing where spatial flexibility permits center-floor placement; margin pools expand with designer collaboration and showroom specification.
- Alcove:Three-wall recessed configurations dominate new construction volume through standardized dimensional compatibility with rough plumbing. Multi-family developers in the United States and China specify these units for cost discipline and rapid installation sequencing.
- Corner:Angular footprint designs maximize floor space in compact bathrooms common in Japanese apartments and European urban housing. Triangular or pentagonal shells require specialized thermoforming tooling that limits supplier base.
- Drop-in:Rim-supported basins integrate with custom surround materials, serving hospitality and high-end residential projects where tile or stone decking defines aesthetic. Specification flows through interior design channels rather than plumbing wholesalers.
Volume sits with Alcove; growth tilts toward Freestanding.
Material:
Surface performance, thermal retention, and repairability create tiered cost positions that align with project budget bands and warranty expectations.
- Acrylic:Cross-linked polymethyl methacrylate sheet vacuum-formed over fiberglass reinforcement delivers superior surface repairability and color stability. REACH-compliant grades from European and Chinese sheet producers now dominate specification in Germany, France, and coastal United States markets.
- Fiberglass:Chopped-strand or woven-glass mat impregnated with unsaturated polyester resin occupies contractor channels on price positioning. Styrene monomer volatility in resin feedstock compresses margins and drives geographic production shifts toward integrated chemical clusters.
- PVC:Extruded or rotational-molded polyvinyl chloride shells serve budget renovation segments and temporary installations. Phthalate plasticizer restrictions under REACH constrain formulation flexibility for European market access.
- Polypropylene:Injection-molded copolymer grades offer chemical resistance and lower unit costs for institutional and commercial wet spaces. Limited surface gloss retention restricts penetration in residential premium segments.
Volume sits with Fiberglass; expansion climbs fastest for Acrylic.
Feature:
Functional augmentation transforms commodity fixtures into wellness appliances, with electrical integration and accessibility compliance creating distinct regulatory pathways.
- Whirlpool:Recirculating pump systems with hydrotherapy jets require UL or CE electrical certification and dedicated circuit installation. Aging-in-place demand in Japan and Germany sustains specification despite higher maintenance liability.
- Walk-in:Threshold-reduced or door-sealed designs serve accessibility mandates in public housing and senior living facilities. ADA compliance in the United States and equivalent standards in France and the United Kingdom drive specification.
- Soaking:Deep-walled non-jetted basins emphasize thermal mass and ergonomic recline, gaining share in wellness-oriented residential renovations. Japanese ofuro influence shapes North American and European premium positioning.
- Air Bath:Blower-driven bubble systems offer gentler massage than hydrotherapy jets with reduced bacterial colonization risk. Specification concentrates in hospitality and healthcare segments where sanitation protocols prioritize.
Volume sits with Soaking; growth tilts toward Walk-in.
Installation:
Structural integration method determines supply chain touchpoints, with contractor skill requirements and rough-in timing creating distinct procurement patterns.
- Above Ground:Self-supporting pedestal or clawfoot designs bypass subfloor reinforcement requirements, accelerating renovation timelines. Freestanding product lines default to this architecture.
- In-ground:Subfloor-recessed basins require concrete deck preparation and waterproofing membranes, common in custom residential and luxury hospitality. Installation sequencing demands coordination with general contractors.
- Wall-mounted:Cantilevered or concealed-carrier systems maximize floor clearance and simplify cleaning protocols. Specification concentrates in commercial and healthcare segments where hygiene access is paramount.
- Integrated:Factory-bonded tub-shower combinations or modular wet-room units reduce field assembly complexity for multi-family developers. Chinese producers dominate export supply for this configuration.
Volume sits with Above Ground; expansion climbs fastest for Integrated.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Acrylic sheet production clusters in Zhejiang and Guangdong provinces anchor Chinese supply for thermoformed bathtub shells. This feedstock concentration shapes procurement patterns across export markets and domestic renovation channels.
United States
Single-family housing starts in Texas and Florida drive alcove bathtub specification for new construction. EPA volatile organic compound standards for gel-coat curing operations force manufacturing investments in catalytic oxidation systems. Ohio and Tennessee host mid-scale fabricators facing disproportionate compliance costs versus coastal integrated producers.
Germany
Public housing authorities in Berlin and Hamburg mandate EPD-certified fixtures for carbon accounting compliance. REACH phthalate restrictions accelerate bio-based plasticizer adoption among bathtub formulators. Bavaria-based sanitary ware distributors prioritize REACH-compliant surface finishes with documented color stability warranties.
China
Urban renovation waves in Shanghai and Shenzhen compress replacement timelines for bathroom fixtures. GB standards set baseline mechanical performance thresholds for domestic bathtub sales. Zhejiang and Guangdong acrylic sheet manufacturing clusters shorten supply lines for export assembly operations.
India
Multi-family residential construction in Maharashtra and Karnataka expands demand for standardized alcove configurations. The PLI scheme for building materials reduces import dependency for acrylic sheet inputs. Gujarat chemical processing hubs supply resin compounds to domestic bathtub fabricators.
Japan
Aging-in-place renovation demand in Tokyo and Osaka sustains walk-in bathtub specification despite higher maintenance liability. METI energy efficiency guidelines influence thermal retention requirements for residential fixtures. Nagoya-area manufacturers integrate thermostatic controls into premium soaking basin designs.
Plastic Bathtub Market Competitive Landscape
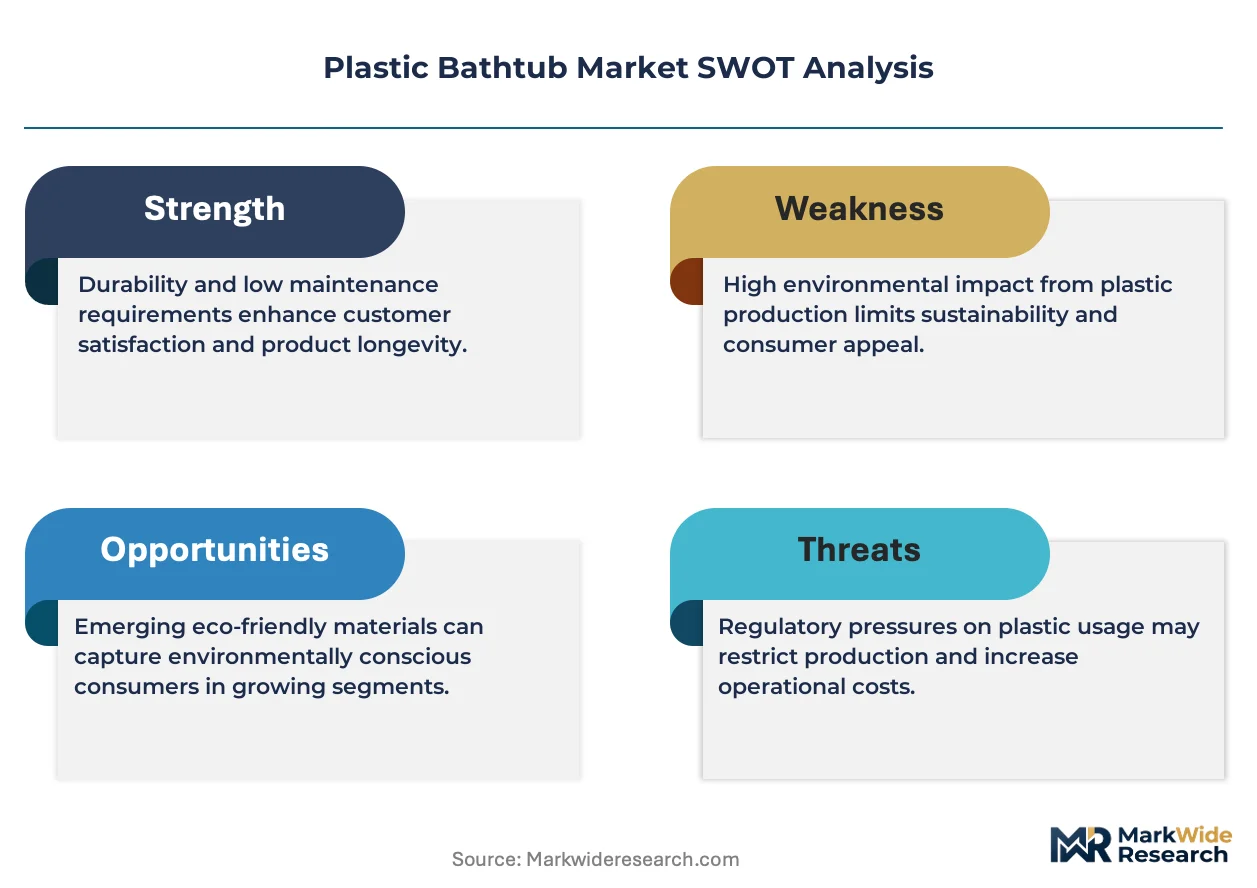
Established producers occupy the standard tier; emerging entrants pursue smart bathroom integration and direct-to-contractor digital channels. The vendor base spans integrated sanitary ware conglomerates, specialized acrylic fabricators, and regional resin compounders. Two strategic archetypes dominate: vertically integrated players controlling sheet production through captive chemical processing, and design-focused specialists leveraging showroom specification. Capacity expansion and certification-driven portfolio diversification represent the primary competitive moves.
Among Asia-Pacific fabricators, TOTO LTD. and Korra Bath Ware Co., Ltd. exemplify divergent scale positions within regional supply chains. European design channels anchor premium positioning for Villeroy & Boch. HSIL Limited occupies a manufacturing-scale archetype across South Asian retail and project segments. These three companies represent distinct geographic and tier specializations without overlapping strategic footprints.
| Leading Market Players |
|---|
| TOTO LTD. |
| Villeroy & Boch |
| Roca Sanitario |
| HSIL Limited |
| OVE Decors |
| Homefilos |
| KOBIA Bathtub Manufacturer |
| Korra Bath Ware Co., Ltd. |
| Asia Billion Innovation Technology Limited |
| Others |
Value Network & Pricing Analysis
Certified gel-coat applicator scarcity in Ohio and Tennessee manufacturing corridors widens labor-cost spreads between coastal integrated producers and inland mid-scale fabricators, compressing margins on REACH-compliant acrylic lines while premium freestanding units absorb technician premiums through warranty bundling.
Pricing Analysis
Warranty and service-bundling separates premium freestanding acrylic lines from unbundled contractor-grade fiberglass alternatives. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and color-stability warranty duration. Cost compression in fiberglass-reinforced segments intensifies because styrene monomer feedstock volatility feeds through resin compound costs. Multi-family developers in the United States exhibit highest price sensitivity; heritage renovation architects in Germany show lowest.
Supply Chain Analysis
Skilled thermoforming technician availability constrains output expansion in Zhejiang and Guangdong acrylic sheet clusters. Supply concentrates in China, Germany, and the United States for thermoformed shells and gel-coat resin compounds. Raw material flows draw from Saudi styrene monomer, South Korean specialty chemical additives, and domestic acrylic sheet stock. Single-source vulnerability sits with Japanese and European UV-stable gel-coat suppliers. Distribution runs through plumbing wholesalers in North America and sanitary ware distributors in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialty resin formulation capacity bottlenecks prop pricing across premium surface finish tiers, constraining volume response even as renovation demand accelerates in single-family housing developments.
For Market Incumbents: Deepen backward integration into acrylic sheet production to capture margin compression from Chinese feedstock suppliers. Expand certified gel-coat applicator training programs in Tennessee and Ohio to deflect EPA compliance cost disadvantages versus coastal competitors. Prioritize REACH-compliant grade certification for European public housing authority specification. For New Entrants and Emerging Players: Capture direct-to-contractor digital procurement channels in North American renovation markets where traditional distributor markups create arbitrage space. India's PLI scheme for building materials offers the most penetrable geography for domestic manufacturing scale without import duty exposure. Lead with integrated tub-shower modular units targeting multi-family developers seeking rapid installation sequencing. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated sheet-to-fabrication players given REACH phthalate restriction enforcement tightening formulation compliance requirements. Long-term viability favors producers controlling captive acrylic supply and certified low-VOC curing capacity. Watch cross-jurisdiction certification timeline divergence as inflection indicator for portfolio geographic concentration risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Sheet Production | Captures margin from Zhejiang and Guangdong feedstock suppliers while securing REACH-compliant grade access. |
| Low-VOC Curing Certification Investment | EPA-compliant spray booth operations unlock United States manufacturing viability against coastal integrated competitors. |
| Direct-to-Contractor Digital Platform Launch | Bypasses traditional plumbing wholesaler markups in North American renovation procurement channels. |
| EPD Certification Program | Germany and France public housing mandates require documented carbon accounting for specification eligibility. |
| Smart Bathroom Integration Partnership | Thermostatic valve and embedded sensor convergence creates premium positioning in Japanese aging-in-place segments. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with thermoforming plant managers, sanitary ware procurement leads at multi-family developers, plumbing wholesaler category buyers, and gel-coat R&D directors. EPA enforcement documentation, REACH restriction updates, and GB standard mechanical performance thresholds provided regulatory boundary conditions. Bottom-up volume modeling triangulated against top-down construction spend projections.
Granularity-level modeling tracked spatial configuration, material chemistry, functional feature set, and mounting architecture as independent demand axes. CAGRs derived from segment-level volume trajectories cross-referenced against acrylic sheet production capacity expansion announcements and resin compound supply forecasts. Analysis window spans from baseline market sizing through projection horizon endpoint. Styrene monomer price volatility and certification timeline divergence served as scenario sensitivity inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EPA emissions threshold tightening, REACH phthalate restriction enforcement acceleration, and Chinese domestic consumption absorption versus export channel prioritization. Forecasts reflect documented assumptions on housing start trajectories and renovation cycle compression rates. Material deviation in named regulatory triggers or feedstock cost shocks warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Car Air Freshener Market
Household Items
North America Tankless Water Heater Market
Household Items
Fine Mist Sprayer Market
Household Items
Heated Mattress Pads Market
Household Items
Aquarium Heaters and Chillers Market
Household Items
Stainless Steel Toilet Paper Dispenser Market
Household Items
Pet Safe Cleaners Market
Household Items
Global Paper Towels Market
Household Items
Command Hooks Market
Household Items
UK Digital Showers Market
Household Items
Electric Blankets Market
Household Items
Knife Set Market
Household Items
Paper Towel Dispenser Market
Household Items
Integrated Smart Toilet Market
Household Items
Electric Tealight Candles Market
Household Items
Smart Faucets Market