
 Shower Caddies Market | 2026-2036
Shower Caddies Market Size, Share, and Industry Trends Forecast 2026-2036
Shower Caddies Market Insights
Capital-intensity divergence between stainless steel fabricators and plastic molders is bifurcating competitive dynamics in shower caddies. iDesign leverages global sourcing networks to sustain cost-competitive positioning across mass retail channels. simplehuman anchors premium positioning through precision-engineered tension-mount systems and extended warranties. OXO Good Grips differentiates via ergonomic design patents and controlled distribution through specialty home goods retailers.
A shower caddy is a portable or fixed storage unit, typically constructed from coated steel, polypropylene, teak, or laminated bamboo, designed to organize toiletries within wet environments; units range from single-shelf hanging designs to multi-tier freestanding towers with integrated drainage. The primary commercial purpose centers on moisture-resistant organization that prolongs product lifespan while maximizing spatial efficiency in compact bathing areas. Metal hanging caddies dominate volume in residential replacement cycles, while bamboo corner units represent the fastest-growing material-format intersection as sustainability preferences harden. Plastic over-the-showerhead designs occupy the economy tier with thin margin pools, whereas large-format freestanding metal caddies concentrate value in hospitality specification channels.
REACH restrictions on hexavalent chromium plating and EPA guidelines for volatile organic compound emissions from powder-coating operations are elevating compliance costs for metal finishers. The EU Green Deal's circular economy requirements are accelerating recycled-content mandates for polypropylene caddies sold in European member states. California's Proposition 65 enforcement on phthalate content continues to reshape plastic formulation standards for products entering US distribution. Stakeholders must monitor evolving chemical disclosure regimes and material certification thresholds as procurement criteria tighten across both consumer and commercial specification channels.
Market Dynamics
REACH restrictions on hexavalent chromium plating are forcing metal finishers toward PVD coatings and powder-coating alternatives, bifurcating supply economics between legacy chrome-plated steel and compliant surface technologies.
Growth Catalysts
- EU Green Deal circular economy mandates:Recycled-content thresholds for polypropylene caddies are accelerating demand for post-consumer resin formulations in European retail channels.
- Hospitality renovation cycles:Premium hotel operators in Germany and France are specifying corrosion-resistant stainless steel corner units for guest bathroom retrofits.
- Bamboo material substitution:Laminated bamboo caddies are capturing sustainability-driven consumers seeking alternatives to petroleum-based plastics in North American specialty retail.
Market Restraints
- Input cost volatility:Nickel and chromium price swings are compressing margins for stainless steel fabricators serving the mid-tier residential segment.
- Supply concentration risk:Powder-coating capacity clusters in China's Guangdong province, exposing brands to tariff and logistics disruptions.
- Technical limitation:Bamboo's dimensional instability under prolonged moisture exposure restricts application to well-ventilated bathroom configurations.
Strategic Opportunities
- Underpenetrated hospitality specification:Boutique hotel chains in Portugal and Spain are accelerating procurement of tension-mount systems for compact ensuite renovations.
- Regulatory tailwind:California Proposition 65 enforcement on phthalate content is creating first-mover advantage for compliant polypropylene formulations in US mass retail.
- Technology convergence:Integration of antimicrobial copper-ion additives with powder-coated steel is opening premium positioning in healthcare-adjacent lodging segments.
Industry Challenges
- Certification timeline compression:Dual certification requirements for REACH and EPA VOC compliance are extending new product introduction cycles by 8-14 months.
- Skill gap in PVD coating:Qualified technicians for physical vapor deposition finishing remain scarce in Eastern European manufacturing zones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shower Caddies Market |
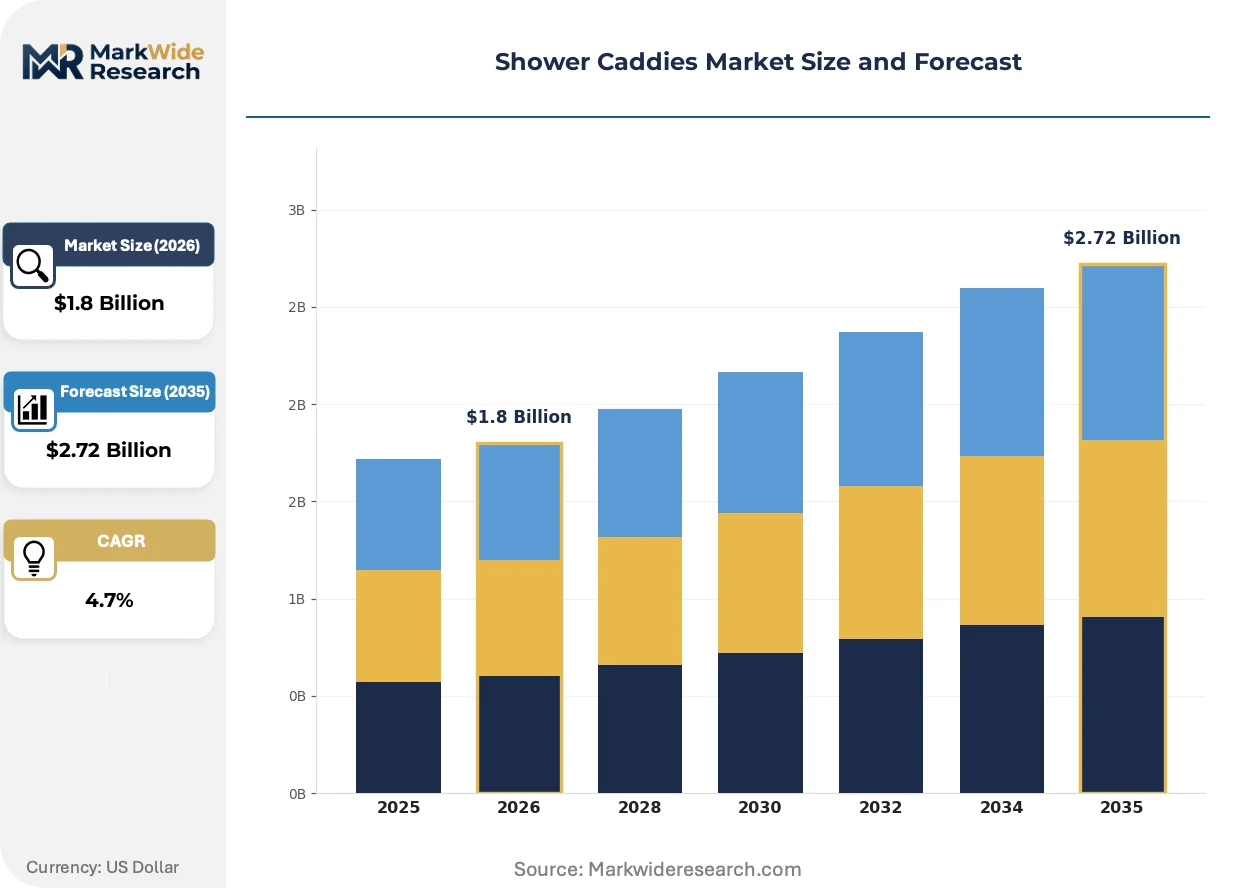
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hanging Caddies, Corner Caddies, Over-the-Showerhead Caddies, Freestanding Caddies Material: Plastic, Metal, Bamboo, Fabric Size: Small, Medium, Large, Extra Large End User: Residential, Commercial, Hospitality, Retail |
| Companies Covered | iDesign, Vidan Home Solutions, simplehuman, DecoBros, AquaTeak, OXO Good Grips, Nieifi, ALLZONE, Zenna Home, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shower Caddies Market Trends and Innovations
Material science advances and regulatory chemistry restrictions are converging to reshape product architecture and surface finishing protocols across all price tiers.
Tension-mount engineering is supplanting traditional suction-cup and adhesive mounting systems in premium residential and hospitality specification channels. Marriott and Hilton procurement teams are mandating drill-free installation for renovated properties to preserve tile warranties. This shift is compressing demand for legacy over-the-showerhead plastic designs while elevating mechanical engineering capabilities among tier-one suppliers.
REACH Annex XVII restrictions on hexavalent chromium compounds are redirecting metal finishing investment toward trivalent chrome and ceramic-coating alternatives. German fabricators Kesseböhmer and Emco are converting production lines to PVD titanium-nitride finishes at 15-20% cost premiums. Hospitality specification buyers are absorbing these premiums to maintain EU market access, while mass retail channels are retreating toward powder-coated steel at lower price points.
Buyer concentration among hospitality procurement consortia is consolidating vendor selection criteria around extended warranty terms and corrosion-performance guarantees. InterContinental Hotels Group and Accor are unbundling after-sales service from product cost, creating recurring revenue streams for certified installation and maintenance providers. This restructuring is most visible in German-speaking markets where facility management outsourcing penetrates deeper than in Southern Europe.
Shower Caddies Market Segmentation
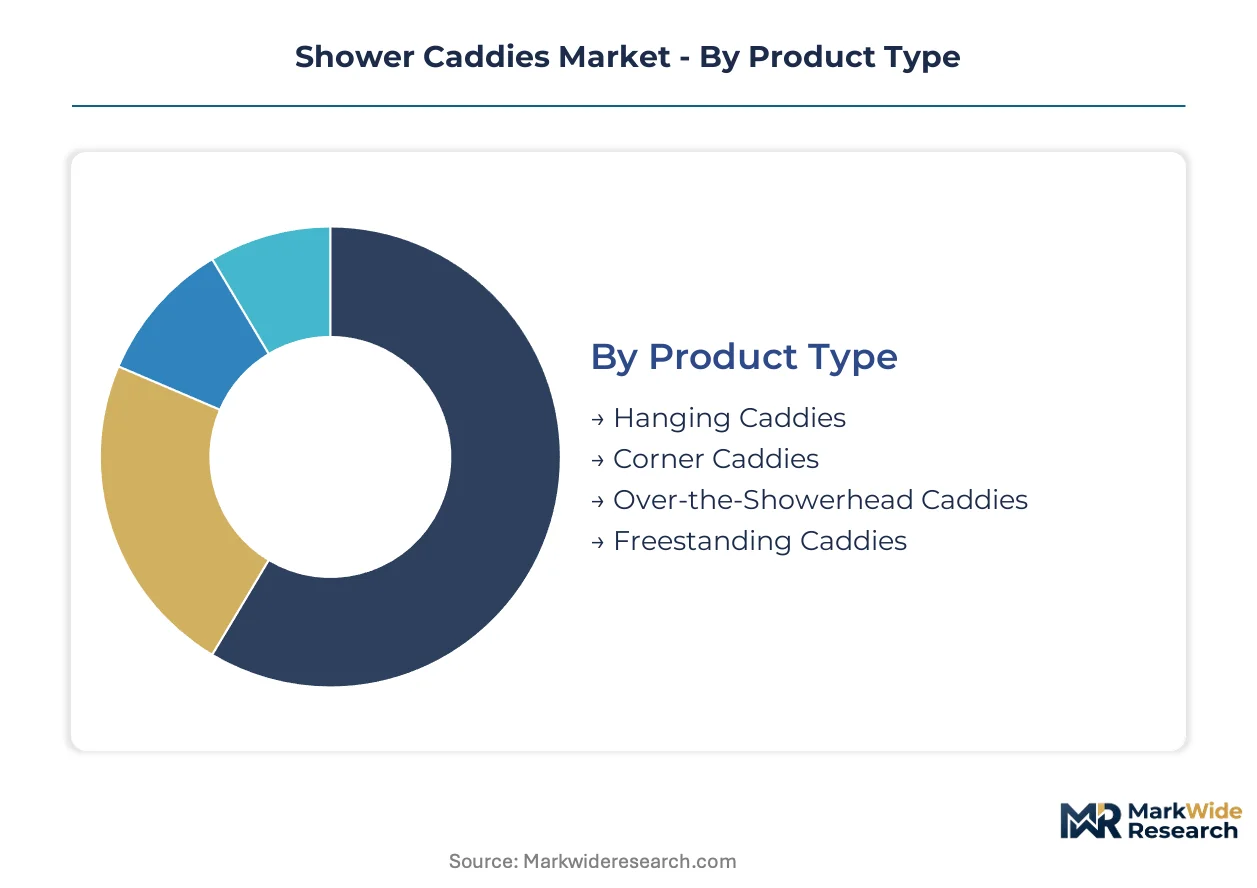
Shower caddy procurement patterns diverge sharply across mounting configurations and material substrates, with regulatory chemistry restrictions and hospitality specification standards reshaping vendor prioritization. Understanding these segment boundaries clarifies where margin pools concentrate versus where price competition erodes returns.
Product Type:
Corner caddies face the most acute substitution pressure as tension-mount engineering displaces traditional adhesive and suction-cup installation methods across premium residential and hospitality channels.
- Hanging Caddies:Suspended units with coated steel or polypropylene baskets designed for showerhead or curtain-rod mounting dominate residential replacement cycles in North American mass retail. Demand concentrates in big-box channels where price elasticity remains high and corrosion warranties are minimal.
- Corner Caddies:Triangular shelving systems engineered for 90-degree wall junctions command premium positioning in German and French hospitality retrofits; InterContinental Hotels Group procurement mandates specify stainless steel construction with PVD titanium-nitride finishes to satisfy REACH Annex XVII compliance.
- Over-the-Showerhead Caddies:Hook-mounted plastic units occupy the economy tier with thin margin pools; California Proposition 65 enforcement on phthalate content is forcing formulation changes that compress already-weak returns.
- Freestanding Caddies:Multi-tier tower designs with weighted bases and integrated drainage target spa-adjacent residential bathrooms and boutique hotel configurations where drill-free installation preserves tile warranties.
Hanging caddies anchor the volume base while corner caddies gain share at the steepest rate.
Material:
Cost tier stratification runs deepest here, with raw material volatility and regulatory compliance burdens creating divergent margin structures across substrate categories.
- Plastic:Polypropylene and ABS formulations dominate economy-channel volume; EU Green Deal circular economy mandates are accelerating post-consumer resin integration that adds 8-12% to input costs for European-bound production.
- Metal:Stainless steel and powder-coated carbon steel command hospitality specification premiums; REACH hexavalent chromium restrictions have elevated PVD coating adoption at 15-20% cost premiums absorbed by German fabricators Kesseböhmer and Emco.
- Bamboo:Laminated timber alternatives capture sustainability-driven consumers in North American specialty retail; dimensional instability under prolonged moisture exposure restricts application to well-ventilated bathroom configurations.
- Fabric:Mesh and quick-dry textile organizers occupy travel and temporary-use niches with minimal fixed investment requirements and low barriers to entry.
Metal construction commands the pricing ceiling while bamboo climbs fastest among sustainability-positioned segments.
Size:
Application context determines dimensional requirements, with hospitality procurement concentrating in standardized formats that simplify inventory and installation logistics.
- Small:Compact single-shelf units target apartment bathrooms and cruise ship cabins where spatial constraints are acute; Accor procurement specifications standardize on 25cm width maximum for European boutique properties.
- Medium:Two-tier configurations balance storage capacity with visual footprint, representing the default specification for mid-tier hotel renovation cycles.
- Large:Three-to-four tier systems serve family residential segments and extended-stay hospitality formats where toiletry volume justifies expanded footprint.
- Extra Large:Floor-standing tower configurations with 120cm+ height target luxury residential and spa-adjacent commercial installations; antimicrobial copper-ion additive integration opens healthcare-adjacent positioning.
Medium formats dominate hospitality procurement volume while extra-large units expand most quickly in premium residential specification.
End User:
Customer type segmentation reveals divergent procurement modalities, with hospitality consortia consolidating vendor selection around extended warranty terms that reshape supplier economics.
- Residential:Individual consumers purchasing through mass retail, specialty home goods, and e-commerce channels drive replacement-cycle volume with price-sensitive behavior and minimal brand loyalty.
- Commercial:Corporate procurement for employee facilities and multi-unit housing operates on standardized specifications with multi-year contract structures that favor established metal fabricators.
- Hospitality:Marriott, Hilton, and IHG procurement teams mandate corrosion-performance guarantees and drill-free installation protocols; German-speaking markets unbundle after-sales service from product cost to create recurring revenue streams for certified maintenance providers.
- Retail:Private-label sourcing for house brands and promotional merchandise occupies volatile volume with compressed margins and rapid supplier switching.
Residential channels anchor absolute volume while hospitality procurement expands most aggressively in Southern European renovation cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between hospitality-driven European specification and price-elastic North American replacement cycles, while Asian manufacturing clusters dominate coated-steel fabrication for export markets.
United States
Mass retail channels drive polypropylene volume through big-box distributors, with California Proposition 65 enforcement reshaping phthalate-free formulation standards. EPA guidelines on powder-coating VOC emissions elevate compliance burdens for metal finishers serving the residential replacement segment. Manufacturing concentration clusters in Ohio and Pennsylvania for coated-steel shower caddies bound for hospitality specification channels.
Germany
Premium bathroom fixture retailing concentrates demand for PVD-finished stainless steel corner units in renovated hotel properties. REACH Annex XVII restrictions on hexavalent chromium compounds redirect fabricator investment toward trivalent chrome and ceramic-coating alternatives. Industrial metalworking capabilities in North Rhine-Westphalia support Kesseböhmer and Emco production lines converting to compliant surface technologies.
China
Guangdong province hosts concentrated powder-coating capacity serving export-oriented brands, exposing supply chains to tariff and logistics disruption risks. The country's national environmental regulator enforces tightening VOC emission standards on coating operations that elevate production costs for mid-tier fabricators. Shenzhen and Dongguan manufacturing zones specialize in tension-mount engineering components for hospitality specification exports.
France
Boutique hotel renovation cycles in Paris and Lyon accelerate procurement of drill-free installation systems that preserve tile warranties. EU Green Deal circular economy mandates drive post-consumer resin integration requirements for polypropylene caddies entering French distribution. Hospitality procurement consortia unbundle after-sales service from product cost, creating recurring revenue structures for certified maintenance providers.
United Kingdom
Specialty home goods retailers anchor demand for ergonomic design patents in premium residential segments. The country's product safety regulator enforces chemical disclosure thresholds that extend new product introduction timelines. London and Southeast England distribution hubs concentrate import logistics for bamboo-based alternatives targeting sustainability-positioned consumers.
Shower Caddies Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with stainless steel fabricators and plastic molders diverging on capital intensity. Market structure bifurcates between corrosion-resistant metal finishers serving hospitality specification and economy-tier polypropylene suppliers competing on unit cost. Three archetypes dominate: precision-engineered tension-mount specialists, global sourcing networks sustaining mass retail positioning, and sustainability-focused bamboo laminators. Competitive moves concentrate on geographic expansion into underpenetrated Southern European hospitality markets and backward integration into captive powder-coating capacity.
Among US-based design houses, iDesign exemplifies global sourcing network archetypes while simplehuman anchors premium-tier positioning through precision-engineered systems. OXO Good Grips represents ergonomic specialization within controlled distribution channels. These three entities illustrate how competitive positioning stratifies across mass retail, specialty home goods, and hospitality specification vectors without overlapping segment focus.
| Leading Market Players |
|---|
| iDesign |
| Vidan Home Solutions |
| simplehuman |
| DecoBros |
| AquaTeak |
| OXO Good Grips |
| Nieifi |
| ALLZONE |
| Zenna Home |
| Others |
Pricing and Supply Chain Analysis
PVD titanium-nitride coating substitution for legacy hexavalent chromium plating simultaneously shifts production geography toward German metalworking clusters and widens cost spreads between REACH-compliant premium tiers and powder-coated economy alternatives. Hospitality procurement teams absorb 15-20% finish premiums to maintain EU market access while mass retail channels retreat to lower-specification steel products.
Pricing Analysis
Long-term offtake contracts with hospitality procurement consortia anchor premium-tier pricing stability, contrasting with spot-market volatility in polypropylene resin formulations bound by EU Green Deal recycled-content mandates. Price differentiation separates PVD-finished stainless steel specifications from powder-coated alternatives, with corrosion-performance guarantees and extended warranty terms commanding substantial premiums. Cost compression in plastic economy tiers intensifies because California Proposition 65 phthalate compliance forces formulation changes that erode already-thin margins. Residential mass retail buyers exhibit highest price sensitivity, while hospitality specification channels prioritize performance guarantees over unit cost.
Supply Chain Analysis
Inventory lead times for tension-mount engineering components extend when sourcing from Shenzhen and Dongguan manufacturing zones, reflecting concentration risk in Guangdong province powder-coating capacity. Raw material flows draw from Indonesian nickel ore, Australian chromium, and Saudi petrochemical feedstocks for polypropylene resin synthesis. Single-source vulnerability concentrates in China's coating operations, exposing brands to tariff and logistics disruptions. Distribution runs through big-box retail channels for residential replacement cycles and direct specification relationships with hospitality procurement teams for premium metal fabrications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospitality renovation cycles position this market in early recovery phase, with German and French hotel retrofit demand providing cyclical lift through specification-grade stainless steel procurement.
For Market Incumbents: Secure captive PVD coating capacity in North Rhine-Westphalia to defend against emerging Asian tension-mount specialists. Backward integration into certified installation and maintenance services captures recurring revenue streams that hospitality consortia increasingly unbundle from product cost. REACH Annex XVII compliance timelines and scarce qualified technician pools create defendable moats for early movers. For New Entrants and Emerging Players: Anchor in Portuguese and Spanish boutique hotel chains where tension-mount specification penetration remains underdeveloped relative to German-speaking markets. Sustainability-positioned bamboo laminators find white-space in North American specialty retail channels seeking alternatives to petroleum-based plastics. Direct-to-architect specification relationships bypass entrenched distributor relationships that lock up hospitality procurement. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors precision-engineered metal fabricators with captive compliance capabilities over commodity plastic molders. Long-term viability across the next decade rests on regulatory chemistry expertise and hospitality specification relationships rather than scale economies in mass retail. Monitor REACH enforcement intensity and nickel price volatility as inflection indicators for margin compression versus expansion cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Captive PVD Coating Investment | REACH Annex XVII compliance secures hospitality specification access against powder-coated competitors. |
| Certified Installation Service Launch | InterContinental Hotels Group and Accor procurement unbundling creates recurring revenue from maintenance contracts. |
| Bamboo Material Line Extension | Sustainability-driven North American specialty retail positioning captures premium from petroleum-plastic substitution. |
| Tension-Mount Engineering Patent Filing | Marriott and Hilton drill-free mandates protect tile warranties and differentiate from adhesive-mounted alternatives. |
| Post-Consumer Resin Integration | EU Green Deal circular economy mandates preempt regulatory exclusion from European polypropylene distribution. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with hospitality procurement directors, metal fabrication plant managers, and specialty retail category buyers; and secondary validation through customs trade records, EPA VOC emission filings, and ECHA REACH registration databases. Bottom-up demand modeling triangulated against top-down market sizing from production capacity assessments and channel shipment data.
Across the projection horizon, the analytical framework segmented volume and value by mounting configuration, material substrate, end-user procurement modality, and regional regulatory cluster. CAGRs derived from trend extrapolation of hospitality renovation cycles, residential replacement rates, and material substitution elasticities. Forecast inputs incorporated nickel price volatility indices, REACH enforcement trajectory, and EU Green Deal recycled-content threshold implementation.
Material uncertainties — tariff escalation on Chinese powder-coated components, nickel supply disruption from Indonesian mining policy shifts, REACH Annex XVII expansion to additional chromium compounds — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory timeline adherence and hospitality capital expenditure continuity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Barbeque Grill Market
Household Items
North America Tankless Water Heater Market
Household Items
Memory Foam Market
Household Items
Portable Showers Market
Household Items
Car Air Freshener Market
Household Items
Commercial Locker Market
Household Items
Waterless Aroma Diffuser Market
Household Items
Toilet Brush Market
Household Items
Asia-Pacific Handheld Vacuum Cleaner Market
Household Items
Domestic Sauna Heaters Market
Household Items
Global Buddhist Supplies Market
Household Items
Qatar Gas Hobs Market
Household Items
Global Rimless Toilets Market
Household Items
United States Barbeque Grill Market
Household Items
Permanent Marker Market
Household Items
Robot Mops Market