
 Global Residential Robotic Vacuum Cleaner Market | 2026-2036
Global Residential Robotic Vacuum Cleaner Market Size, Share, and Industry Trends Forecast 2026-2036
Global Residential Robotic Vacuum Cleaner Market Intelligence
A shift from outsourced sensor procurement to in-house chipset design is repositioning competitive dynamics across the supply base. iRobot Corporation anchors its Massachusetts engineering footprint through captive lidar development. Ecovacs Robotics leverages Suzhou-based manufacturing scale to control cost structures in wet-mopping variants. Samsung Electronics differentiates through Seoul-integrated IoT ecosystems that bind vacuums to broader smart home platforms.
Residential robotic vacuum cleaners are autonomous floor-cleaning devices equipped with suction motors, debris bins, and navigation arrays typically operating at 50-70 decibels for household noise compliance; their primary purpose is unsupervised particulate removal from hard surfaces and low-pile carpeting. Lidar-enabled units command premium positioning due to real-time room mapping accuracy, while camera-based systems compete on object recognition for pet care and allergen reduction applications. Wet-mopping configurations represent a fast-growing segment as consumers seek consolidated floor maintenance, though standard suction models still occupy the largest volume tier among apartments and rental properties.
The EU Ecodesign Directive and RoHS compliance frameworks constrain motor efficiency thresholds and hazardous substance thresholds for units sold across Europe, while the FCC in the United States governs wireless connectivity standards for cloud-linked navigation updates. China's GB standards and NMPA-equivalent consumer safety protocols mandate battery thermal stability testing for lithium-ion power packs. Stakeholders must monitor how diverging energy efficiency certifications across Brussels, Washington, and Beijing reshape product architecture and regional launch sequencing.
Market Dynamics
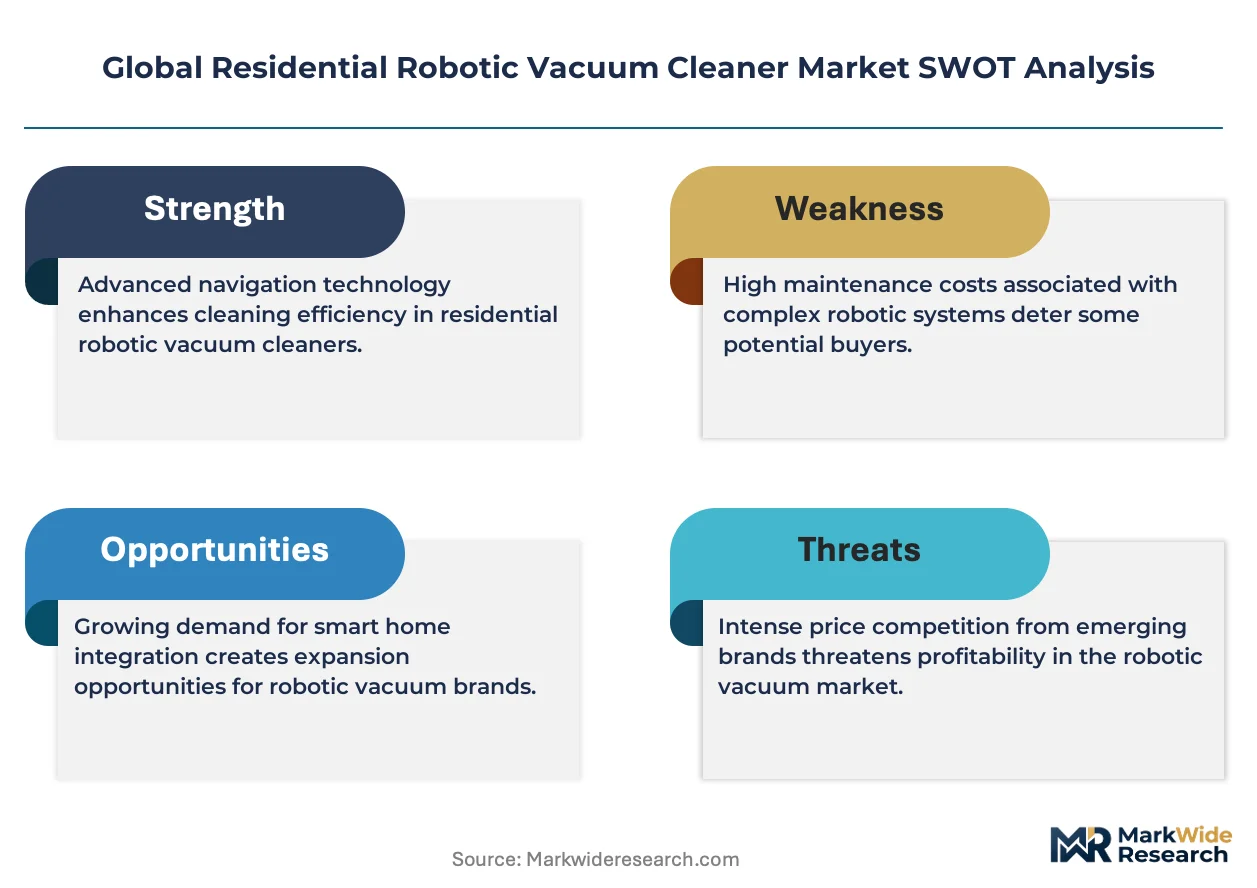
Navigation chipset design is consolidating into captive engineering centers as manufacturers abandon outsourced lidar procurement, compressing supplier margins while accelerating mapping precision wars among autonomous cleaning systems.
Growth Catalysts
- EU Ecodesign Directive motor efficiency mandates:Tiered energy thresholds force motor upgrades that extend replacement cycles and position compliant manufacturers for premium channel placement across Germany, France, and Italy.
- Dual-income household time scarcity:Unsupervised floor maintenance demand concentrates in urban apartment clusters of China, the United States, and Germany where smart home penetration exceeds residential robotics adoption.
- Lithium-ion battery thermal stability protocols:China's GB standards and NMPA-equivalent testing regimes validate product safety for cross-border e-commerce distribution into Southeast Asian markets.
Market Restraints
- Precision sensor input cost volatility:Lidar module pricing fluctuates with semiconductor foundry capacity allocation, squeezing gross margins on mid-tier camera-competing units.
- Suzhou manufacturing cluster concentration:Wet-mopping variant production gravity creates single-point vulnerability for brands without secondary assembly footprints.
- RoHS hazardous substance thresholds:European compliance adds 8-12 week certification lead times that delay regional launch sequencing against faster FCC-cleared competitors.
Strategic Opportunities
- India urban apartment density:Sub-50 decibel noise compliance and compact form factors address untapped demand in Mumbai and Bangalore high-rise developments.
- IoT ecosystem convergence:Seamless binding between autonomous vacuums and Seoul-integrated smart home platforms creates switching costs that defend installed base.
- US Inflation Reduction Act residential efficiency incentives:Energy-certified autonomous cleaning systems qualify for indirect consumer purchasing power expansion through broader home electrification subsidies.
Industry Challenges
- Multi-sensor fusion algorithm talent scarcity:Simultaneous localization and mapping expertise concentrates in Massachusetts and Suzhou engineering clusters, inflating compensation for specialized robotics software architects.
- FCC wireless connectivity certification timelines:Cloud-linked navigation update capabilities face 14-18 week approval queues that compress competitive response windows.
- Legacy hard flooring compatibility:Variable surface detection calibration demands extensive field testing across terrazzo, engineered wood, and ceramic tile sub-segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Residential Robotic Vacuum Cleaner Market |
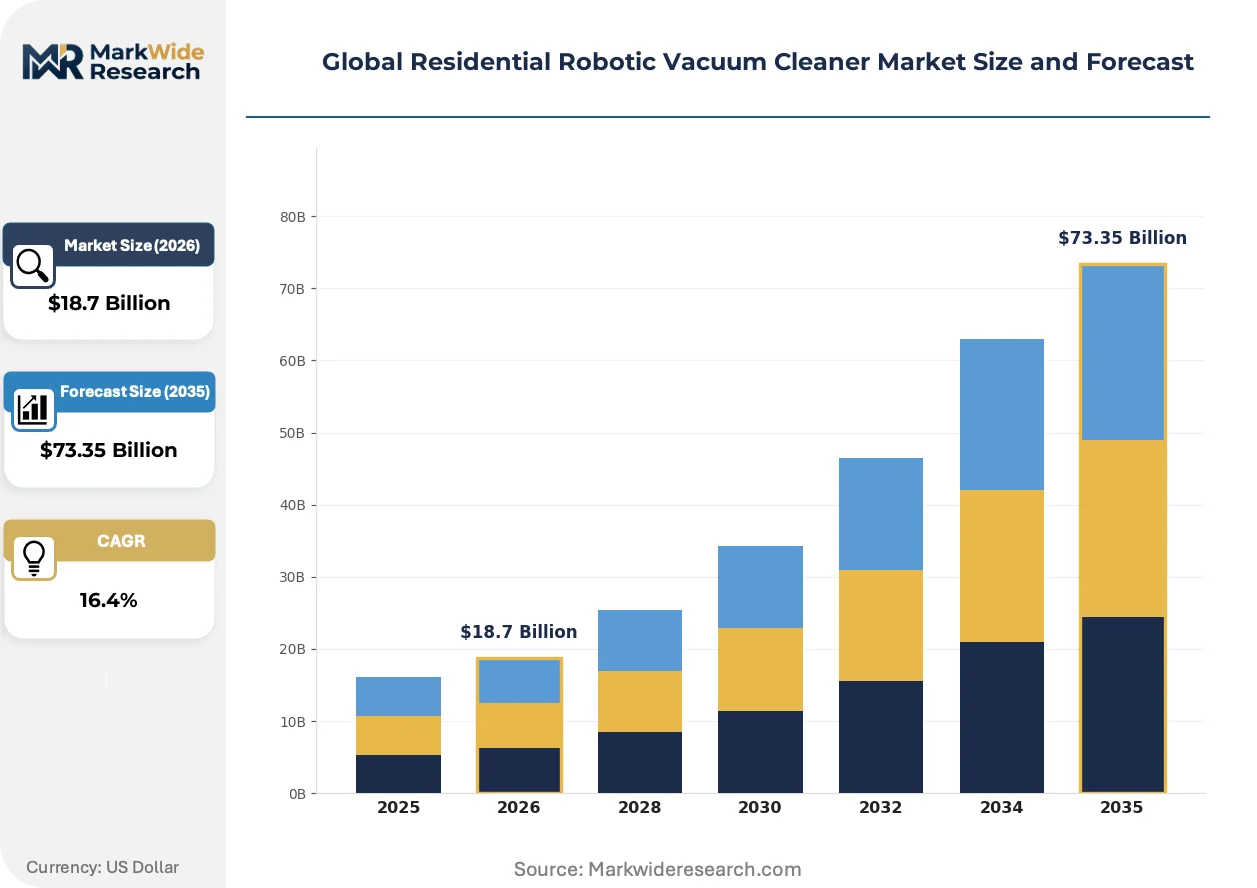
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard, Wet Mopping, UV Sterilizing, Pet Hair, Advanced Navigation Technology: Lidar, Infrared Sensor, Camera-Based, Gyroscope, Ultrasonic Application: Home Cleaning, Floor Polishing, Dust Control, Allergen Reduction, Pet Care End User: Households, Apartments, Condominium Owners, Rental Properties, Smart Homes |
| Companies Covered | iRobot Corporation, Ecovacs Robotics, Roborock Technology, Samsung Electronics, Xiaomi Corporation, SharkNinja Operating LLC, LG Electronics, Dyson, Panasonic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Residential Robotic Vacuum Cleaner Market Strategic Shifts & Innovations
Real-time spatial computing is compressing the performance gap between premium and standard navigation tiers, while regulatory energy frameworks and direct-to-consumer channel expansion simultaneously reshape competitive positioning.
Lidar-enabled simultaneous localization and mapping is consolidating market structure around real-time room geometry reconstruction. Dual-income households in dense German and Chinese urban centers prioritize centimeter-level accuracy for furniture-dense layouts. This precision standard is consolidating price-performance expectations and marginalizing gyroscope-only units to rental-property volume tiers.
REACH substance restrictions and EU Ecodesign Directive motor efficiency thresholds are tightening component sourcing requirements for European market entry. Manufacturers must reformulate lubricants and redesign winding architectures to meet standby power limits. Wet-mopping configurations face the steepest compliance recalibration due to integrated pump motor energy profiles.
Direct-to-consumer channel expansion is fragmenting traditional electronics retail dependence. Chinese manufacturers now bypass distributor markups through flagship storefronts on domestic e-commerce platforms, capturing first-party data on usage patterns. This disintermediation is most visible in Southeast Asian markets where mobile-first purchasing dominates urban household appliance acquisition.
Global Residential Robotic Vacuum Cleaner Market Segmentation
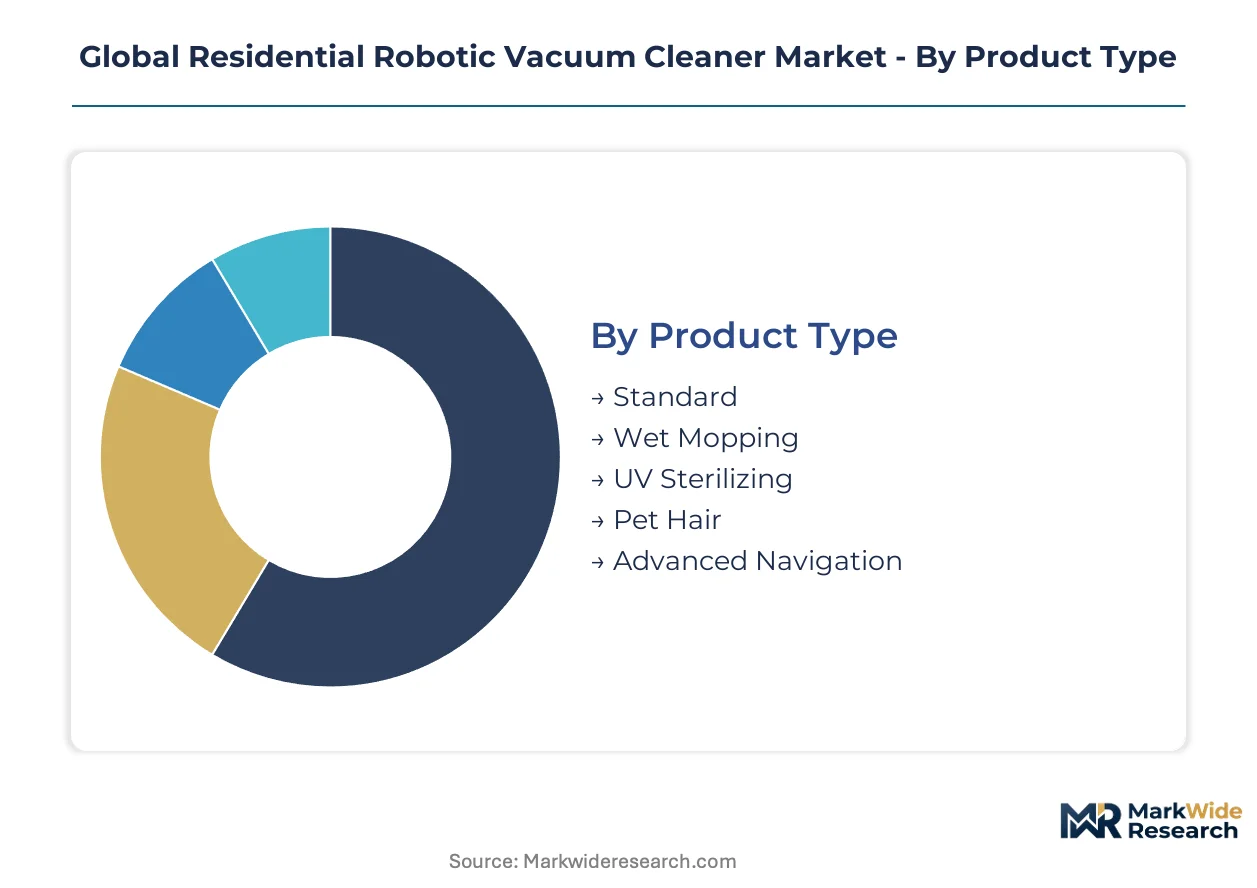
Segmentation in residential robotic vacuum cleaners reveals how navigation precision, surface specialization, and dwelling type reshape procurement patterns across dual-income households. Manufacturers align R&D roadmaps to these divides, prioritizing sensor fusion for premium tiers while cost-optimizing gyroscope units for rental-property volume.
Product Type:
Supply concentration in Suzhou manufacturing clusters favors wet-mopping variant production, while Massachusetts and Seoul engineering centers anchor advanced navigation development through captive lidar programs.
- Wet Mopping:Integrated pump motors and dual-tank systems enable simultaneous suction and liquid dispersion across hard flooring. Demand concentrates in Chinese urban apartments where consolidated floor maintenance reduces chore frequency for time-scarce professionals. REACH substance restrictions and EU Ecodesign Directive motor efficiency thresholds force lubricant reformulation and winding architecture redesigns that extend certification timelines for European market entry.
- Advanced Navigation:Real-time simultaneous localization and mapping reconstructs room geometry through lidar or camera fusion, enabling centimeter-level obstacle avoidance. German and US households in furniture-dense layouts prioritize this precision, displacing simpler units from premium channel placement. FCC wireless connectivity certification for cloud-linked updates requires 14-18 week approval queues that compress competitive response windows against faster CE-marked rivals.
- Standard:Suction-only configurations with gyroscope navigation serve rental-property volume tiers through sub-200 decibel operation and disposable price points.
- UV Sterilizing:Integrated ultraviolet-C emitters target pathogen reduction on hard surfaces, appealing to allergen-sensitive households in Japan and South Korea.
- Pet Hair:Tangle-resistant brush rolls and enhanced suction motors address shedding volumes in North American homes with companion animals.
Today's leader: Advanced Navigation. Tomorrow's challenger: Wet Mopping.
Technology:
Cost tiers stratify sharply around sensor input expenses, with lidar modules commanding semiconductor foundry premiums that squeeze mid-tier camera-competing gross margins.
- Lidar:Rotating laser arrays generate 360-degree spatial maps at 10Hz refresh rates, enabling dynamic path recalculation. Chinese and German manufacturers prioritize this specification for smart home integration, where room-specific cleaning schedules bind vacuums to broader IoT ecosystems. GB standards and NMPA-equivalent battery thermal stability protocols validate cross-border e-commerce distribution into Southeast Asian markets.
- Camera-Based:Visual simultaneous localization and mapping leverages neural networks for object recognition, differentiating pet waste and charging cables from cleanable debris. US households with mixed flooring and companion animals drive adoption, though algorithm training demands extensive field data collection across terrazzo and engineered wood sub-segments.
- Infrared Sensor:Proximity detection arrays prevent cliff falls and furniture collisions in budget-tier units with limited mapping retention.
- Gyroscope:Inertial measurement units estimate position through dead reckoning, occupying rental-property price bands where navigation precision is secondary to acquisition cost.
- Ultrasonic:High-frequency emitters detect transparent obstacles like glass barriers, supplementing primary navigation arrays in hybrid sensor configurations.
Volume concentrates in Lidar. Margin expansion sits with Camera-Based.
Application:
Customer type determines performance thresholds, with allergen-sensitive households and pet owners demanding specialized filtration and brush architectures that standard home cleaning configurations cannot satisfy.
- Allergen Reduction:HEPA-sealed suction paths and high-efficiency particulate arrestation target dust mite and pollen removal for respiratory-sensitive occupants. German and Japanese households with diagnosed allergies prioritize this specification, driving premium positioning through clinical validation requirements. EU Ecodesign Directive standby power limits constrain motor controller design, forcing firmware optimizations that extend development cycles.
- Pet Care:Tangle-free extractors and acoustic dampening address companion animal maintenance in US and Australian homes with indoor pets. Object recognition algorithms identify pet waste to avoid smearing incidents, requiring extensive training datasets that concentrate machine learning talent in Massachusetts and Suzhou engineering clusters.
- Home Cleaning:General particulate removal across hard surfaces and low-pile carpeting represents the baseline functional tier for first-time adopters.
- Floor Polishing:Integrated microfiber pads and mild abrasive compounds restore luster to sealed hardwood and engineered stone surfaces.
- Dust Control:Scheduled operation modes maintain baseline cleanliness in secondary residences and vacation properties with intermittent occupancy.
Allergen Reduction commands price premiums. Pet Care is gaining share fastest.
End User:
Dwelling density and ownership structure reshape noise compliance and form factor requirements, with Mumbai and Bangalore high-rise developments demanding sub-50 decibel operation that legacy architectures cannot deliver.
- Smart Homes:IoT-native vacuums with Matter or proprietary protocol support integrate with lighting, climate, and security systems for unified automation. Seoul-integrated platforms from Samsung Electronics create switching costs that defend installed base through ecosystem binding. FCC and CE marking divergence for wireless interoperability standards complicates multi-region launch sequencing.
- Apartments:Compact docking stations and slim profiles accommodate space constraints in Chinese and Indian urban high-rises where square footage commands premium valuations. India's BIS certification for electronic goods adds regulatory friction that delays market entry against pre-cleared competitors.
- Households:Single-family residences with mixed flooring drive demand for variable surface detection and extended runtime configurations.
- Condominium Owners:Shared-wall noise sensitivity in North American multi-unit buildings prioritizes acoustic engineering and scheduled operation during permitted hours.
- Rental Properties:Landlord-provisioned units emphasize durability and tenant-proof simplicity over feature depth, concentrating procurement in standard gyroscope tiers.
Smart Homes extract margin through ecosystem lock-in. Apartments represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Suzhou manufacturing clusters anchor global wet-mopping variant production, while Massachusetts and Seoul engineering centers concentrate lidar and IoT ecosystem development. Dual-income household density in Chinese and German urban centers drives premium navigation adoption, with regulatory divergence across Brussels, Washington, and Beijing reshaping regional launch sequencing.
China
Urban apartment density in Shanghai and Shenzhen accelerates demand for compact docking stations and sub-55 decibel operation. GB standards and NMPA-equivalent battery thermal stability protocols validate cross-border e-commerce distribution into Southeast Asian markets. Suzhou-based manufacturing scale controls cost structures for wet-mopping configurations targeting time-scarce professionals.
United States
Mixed flooring and companion animal ownership in suburban households drive tangle-resistant brush roll specifications. FCC wireless connectivity certification governs cloud-linked navigation updates with 14-18 week approval queues. Massachusetts engineering clusters concentrate simultaneous localization and mapping talent for lidar-enabled premium tiers.
Germany
Furniture-dense layouts in Berlin and Munich apartments prioritize centimeter-level mapping precision for autonomous path planning. EU Ecodesign Directive motor efficiency mandates and RoHS hazardous substance thresholds extend certification lead times by 8-12 weeks. REACH lubricant reformulation requirements force winding architecture redesigns for wet-mopping pump motors.
India
Mumbai and Bangalore high-rise developments generate untapped demand for sub-50 decibel noise compliance and slim form factors. BIS certification for electronic goods adds regulatory friction that delays market entry against pre-cleared competitors. Compact docking stations accommodate square footage premiums in dense urban residential towers.
South Korea
Seoul-integrated IoT ecosystems create switching costs that defend installed base through ecosystem binding with lighting and climate systems. MFDS-equivalent consumer safety protocols align with regional smart home penetration rates exceeding residential robotics adoption. Allergen-sensitive households in metropolitan areas prioritize HEPA-sealed suction paths for respiratory health.
Global Residential Robotic Vacuum Cleaner Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue wet-mopping specialization and IoT ecosystem convergence. Market structure consolidates around three archetypes: Massachusetts-based navigation chipset developers, Suzhou-scaled manufacturing specialists, and Seoul-integrated platform builders. Competitive moves center on captive lidar development and direct-to-consumer channel expansion that fragments traditional electronics retail dependence.
Within the navigation-tier, iRobot Corporation and Ecovacs Robotics exemplify divergent geographic anchoring strategies, while Samsung Electronics occupies a position in ecosystem-integrated platform development. Roborock Technology represents scale-driven specialization in simultaneous localization and mapping hardware. These three entities collectively illustrate how engineering footprint location—Massachusetts, Suzhou, and Seoul—shapes competitive positioning across premium and standard tiers.
| Leading Market Players |
|---|
| iRobot Corporation |
| Ecovacs Robotics |
| Roborock Technology |
| Samsung Electronics |
| Xiaomi Corporation |
| SharkNinja Operating LLC |
| LG Electronics |
| Dyson |
| Panasonic Corporation |
| Others |
Cost & Logistics Intelligence
Dual-income urban households in China and Germany concentrate procurement power in premium navigation tiers, anchoring a three-tier pricing structure across premium, standard, and economy levels that rewards lidar-enabled precision while compressing margins on gyroscope-only rental-property units.
Pricing Analysis
Semiconductor foundry capacity allocation for lidar modules passes through to end-user pricing, with camera-based systems competing on object recognition capabilities at mid-tier positioning. Price differentiation separates CE-marked European units from FCC-cleared US variants through certification-driven cost adders. Pricing pressure stems from Suzhou manufacturing scale advantages in wet-mopping configurations that force margin compression elsewhere. Rental-property buyers exhibit highest price sensitivity; smart home ecosystem integrators show lowest.
Supply Chain Analysis
CE marking and FCC wireless certification gates create 8-18 week lead time divergences that reshape regional launch sequencing. Component sourcing concentrates in China, South Korea, and Germany, with lidar arrays and lithium-ion battery packs as critical inputs. Single-source vulnerability sits with Suzhou wet-mopping pump motor production. Distribution runs through direct-to-consumer flagship storefronts on domestic e-commerce platforms that disintermediate traditional electronics retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The 8-12 week RoHS certification lag in Europe against 14-18 week FCC queues in the United States creates arbitrage windows for manufacturers with dual-approval capabilities to capture first-mover positioning in overlapping launch cycles.
For Market Incumbents: Extend captive lidar development in Massachusetts and Suzhou engineering clusters to defend mapping precision leadership against emerging camera-fusion entrants. Accelerate GB standards and NMPA-equivalent battery thermal stability pre-certification to capture Southeast Asian cross-border e-commerce distribution before rivals clear compliance queues. Channel control through IoT ecosystem binding with Seoul-integrated platforms creates switching costs that protect installed base erosion. For New Entrants and Emerging Players: Capture sub-50 decibel compact form factor demand in Mumbai and Bangalore high-rise developments where BIS certification friction has delayed incumbent entry. Target wet-mopping specialization for Chinese urban apartments as the most penetrable white-space segment. Deploy direct-to-consumer flagship storefronts on mobile-first e-commerce platforms as the dominant go-to-market angle to bypass distributor markups and capture first-party usage data. For Investors and Strategic Acquirers: Consumer electronics conglomerates with existing IoT platform assets are the most active acquirer in this space, seeking navigation chipset capabilities to complete smart home ecosystem coverage. The five-to-ten year viability window favors targets with simultaneous localization and mapping software architectures and established Suzhou manufacturing partnerships. Acquisition target archetype: mid-scale lidar developers with captive sensor fusion algorithms and secondary assembly footprints outside single-cluster concentration. Monitor divergence between EU Ecodesign Directive motor efficiency mandates and FCC wireless certification timelines as the signal to watch for regional winner-take-all dynamics.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Lidar Development | iRobot Corporation's Massachusetts engineering footprint reduces outsourced sensor dependency and accelerates mapping precision iteration cycles. |
| Wet-Mopping Variant Scale-Up | Ecovacs Robotics leverages Suzhou manufacturing gravity to control cost structures in integrated pump motor configurations. |
| IoT Ecosystem Integration | Samsung Electronics binds autonomous vacuums to Seoul-integrated lighting and climate systems through Matter protocol support. |
| Direct-to-Consumer Channel Expansion | Chinese manufacturers bypass distributor markups through flagship storefronts on domestic e-commerce platforms capturing usage pattern data. |
| Dual-Certification Pre-Approval | Parallel CE marking and FCC wireless connectivity investment compresses competitive response windows in overlapping regional launches. |
Research Approach
Direct dialogue with robotics engineering directors, smart home platform architects, contract manufacturing procurement leads, and Southeast Asian e-commerce category managers grounded qualitative insights in operational reality. Secondary validation drew from FCC equipment authorization databases, EU Ecodesign Directive compliance filings, Chinese customs export records for robotic vacuum HS codes, and SEC 10-K disclosures from listed appliance manufacturers. Bottom-up unit shipment modeling and top-down addressable household penetration estimates were triangulated against sensor foundry capacity utilization reports.
Bottom-up volume construction aggregated lidar module shipments, battery pack procurement volumes, and docking station production across Suzhou, Massachusetts, and Seoul manufacturing clusters. Segmentation dimensions spanned navigation technology tier, surface specialization configuration, dwelling type density, and regional regulatory framework. CAGRs were derived from fitted adoption curves against dual-income household growth and smart home penetration benchmarks. Forecast inputs included semiconductor foundry capex cycles for navigation chipsets and lithium-ion cell thermal stability protocol evolution.
Semiconductor foundry capacity reallocation, regulatory timeline divergence between Brussels and Washington, and battery chemistry safety standard revisions are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions on household formation rates and smart home interoperability protocol adoption. A model refresh is warranted upon material change in EU Ecodesign Directive motor efficiency threshold enforcement or FCC wireless certification queue duration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Dryer Sheets Market
Household Items
Pocket Tissues Market
Household Items
Stainless Steel Vacuum Flask Market
Household Items
Germany Induction Hobs Market
Household Items
Netherlands Cookware Market
Household Items
Aromatherapy Diffuser Market
Household Items
Electric Hedge Trimmer Market
Household Items
Smart Memory Foam Market
Household Items
Electric Soap Dispenser Market
Household Items
Germany Digital Showers Market
Household Items
Pet Fur Remover Market
Household Items
Gas Hobs Market
Household Items
China Digital Showers Market
Household Items
Disposable Cutlery Market
Household Items
Smart Bath Heater Market
Household Items
Toilet Brush Market