
 Dry Cleaning and Laundry Market | 2026-2036
Dry Cleaning and Laundry Market Size, Share, and Industry Trends Forecast 2026-2036
Dry Cleaning and Laundry Market Insights
The EU Green Deal is repositioning European dry cleaning operations toward perchloroethylene-free solvent systems. Alliance Laundry Systems LLC leverages its manufacturing scale to dominate commercial equipment supply across Western Europe. Cintas Corporation anchors its position through captive uniform rental networks that integrate on-premise laundering. Elis SA competes via geographic density in France and Benelux, where hospital linen contracts require ISO 14001-certified processing.
Dry cleaning and laundry encompasses the professional cleaning, finishing, and restoration of textiles using solvent-based or aqueous processes operating at temperatures between 20°C and 85°C depending on fiber composition and soiling level. The primary purpose spans garment care for consumers, institutional linen hygiene for healthcare facilities, and brand presentation for corporate uniform programs. Automated technology leads capital deployment as operators replace batch washers with continuous batch washers and tunnel finisher systems that cut labor hours and water consumption per kilogram. The commercial client segment sustains the deepest margin pools through multi-year hospitality and healthcare contracts with predictable volume commitments. Eco-friendly service lines are growing fastest where municipal authorities restrict perc emissions and buyers mandate Scope 3 reporting.
REACH regulation governs solvent chemistry across Europe, while the EPA enforces National Emission Standards for Hazardous Air Pollutants at US perc facilities, and ISO 14001 certification shapes tender eligibility for institutional buyers in multiple jurisdictions. These frameworks elevate compliance costs for small independents while creating barriers that favor capitalized operators with environmental management systems. Stakeholders must monitor solvent substitution timelines and municipal water pricing reforms that could accelerate consolidation among fragmented neighborhood operators.
Market Dynamics
The EU Ecodesign for Sustainable Products Regulation is forcing solvent substitution across European facilities, compressing the installed base of perchloroethylene systems while accelerating capital redeployment toward wet-cleaning and liquid CO2 infrastructure.
Growth Catalysts
- Hospitality Outsourcing:Hotel chains in Germany and France are consolidating linen management under multi-year commercial contracts with volume guarantees.
- REACH Solvent Restrictions:ECHA classification of perc as a substance of very high concern is closing legacy dry cleaning operations and transferring volume to certified industrial laundries.
- Continuous Batch Washers:Tunnel washer systems cut water consumption per kilogram by half compared to conventional batch equipment, satisfying municipal discharge limits in water-stressed regions.
Market Restraints
- Capital Intensity:Tunnel finisher installations require seven-figure euro outlays that exclude independent neighborhood operators from equipment upgrades.
- Input Cost Volatility:Natural gas and electricity price spikes in Germany and Italy have compressed margins at heat-intensive finishing operations.
- Technical Limitation:Wet-cleaning remains unsuitable for structured wool garments and certain fused interlinings, preserving a residual perc-dependent niche.
Strategic Opportunities
- Scope 3 Reporting Mandates:Corporate uniform programs now require ISO 14001-certified processing, creating tender eligibility barriers that favor consolidated operators with environmental management systems.
- Healthcare Linen Density:Hospital networks in Belgium and the Netherlands are awarding decade-long hygiene contracts to regional processors with HACCP accreditation.
- CO2 Recovery Systems:Closed-loop liquid CO2 technology converges with heat pump drying to eliminate thermal energy from the cleaning cycle entirely.
Industry Challenges
- Specialized Technician Scarcity:Maintenance of continuous batch washers and tunnel finishers requires mechatronics skills that vocational programs have not scaled to match equipment deployment.
- Legacy Integration Friction:Operators retrofitting wet-cleaning lines into perc-era facilities face space constraints and wastewater plumbing reconfiguration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dry Cleaning and Laundry Market |
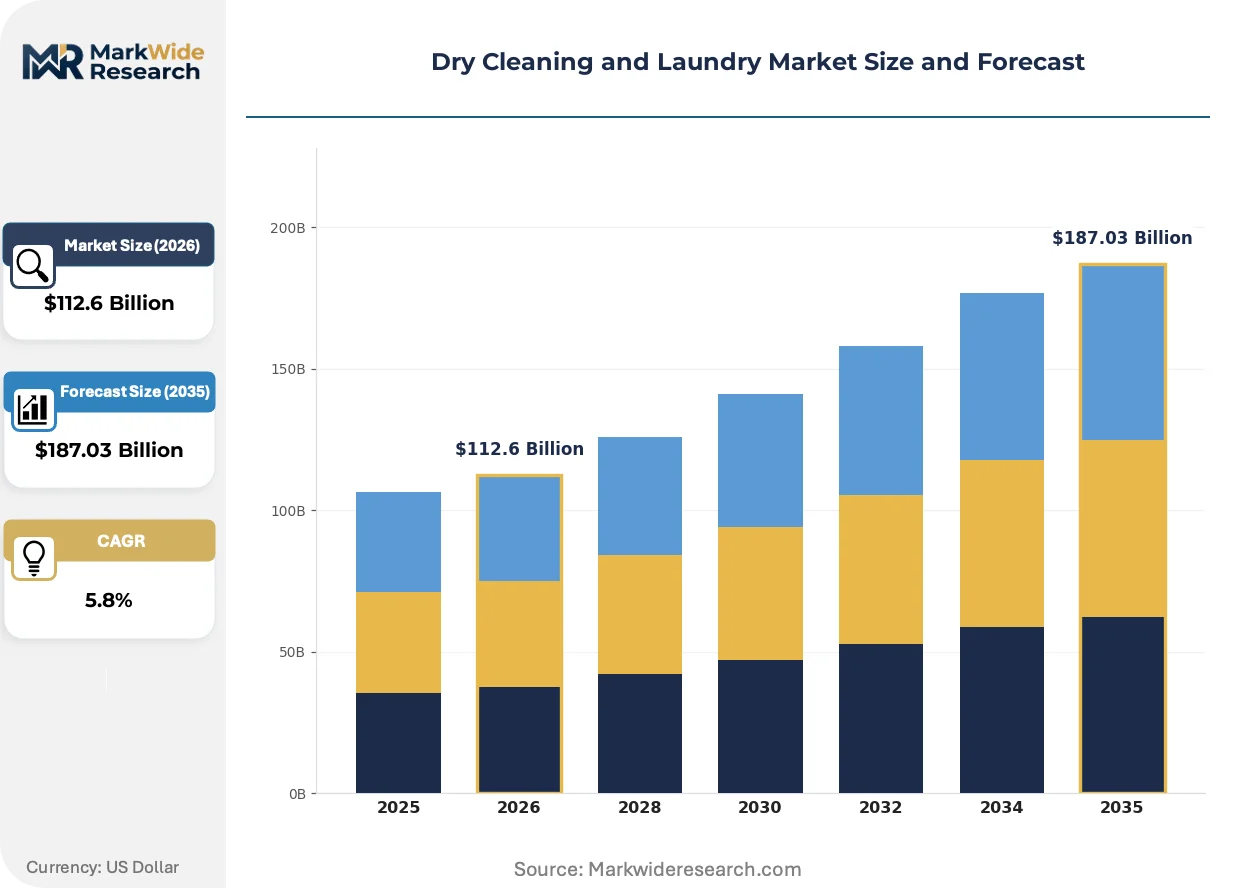
| Market Size in 2026 | $112.6 Billion |
| Market Size in 2035 | $187.03 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Dry Cleaning, Laundry, Ironing, Alterations Client Type: Residential, Commercial, Hospitality, Corporate Technology: Traditional, Automated, Eco-Friendly, Manual Delivery Model: In-Store, Pickup and Delivery, Self-Service, Subscription |
| Companies Covered | Aramark, Cintas Corporation, Alliance Laundry Systems LLC, ZIPS Dry Cleaners, Tide Cleaners, Rinse, Inc., Cleanly, Elis SA, The Huntington Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dry Cleaning and Laundry Market Trends and Innovations
Equipment automation and solvent chemistry are converging to restructure competitive economics, compressing labor hours while elevating environmental compliance thresholds that fragment the vendor base.
Closed-loop liquid CO2 cleaning is decentralizing production geography by eliminating the thermal energy dependency that historically concentrated operations near utility infrastructure. Boutique hotel operators in Copenhagen and Amsterdam are piloting compact CO2 units for on-premise garment care. This distributed model compresses logistics costs and turnaround time for high-value guest services.
REACH authorization requirements for perc are forcing solvent substitution timelines across France, Italy, and Spain. ECHA sunset dates are triggering equipment write-downs at independent dry cleaners. Hospital linen tenders in Germany now specify perc-free processing as a mandatory technical criterion.
Corporate buyers are unbundling after-sales service from equipment procurement, demanding performance-based maintenance contracts with uptime guarantees. Hospitality groups in Portugal and Greece are shifting from capital purchase to operational lease structures for tunnel washer systems. This financing rotation concentrates vendor risk with manufacturers while transferring balance sheet burden away from hotel operators.
Dry Cleaning and Laundry Market Segmentation
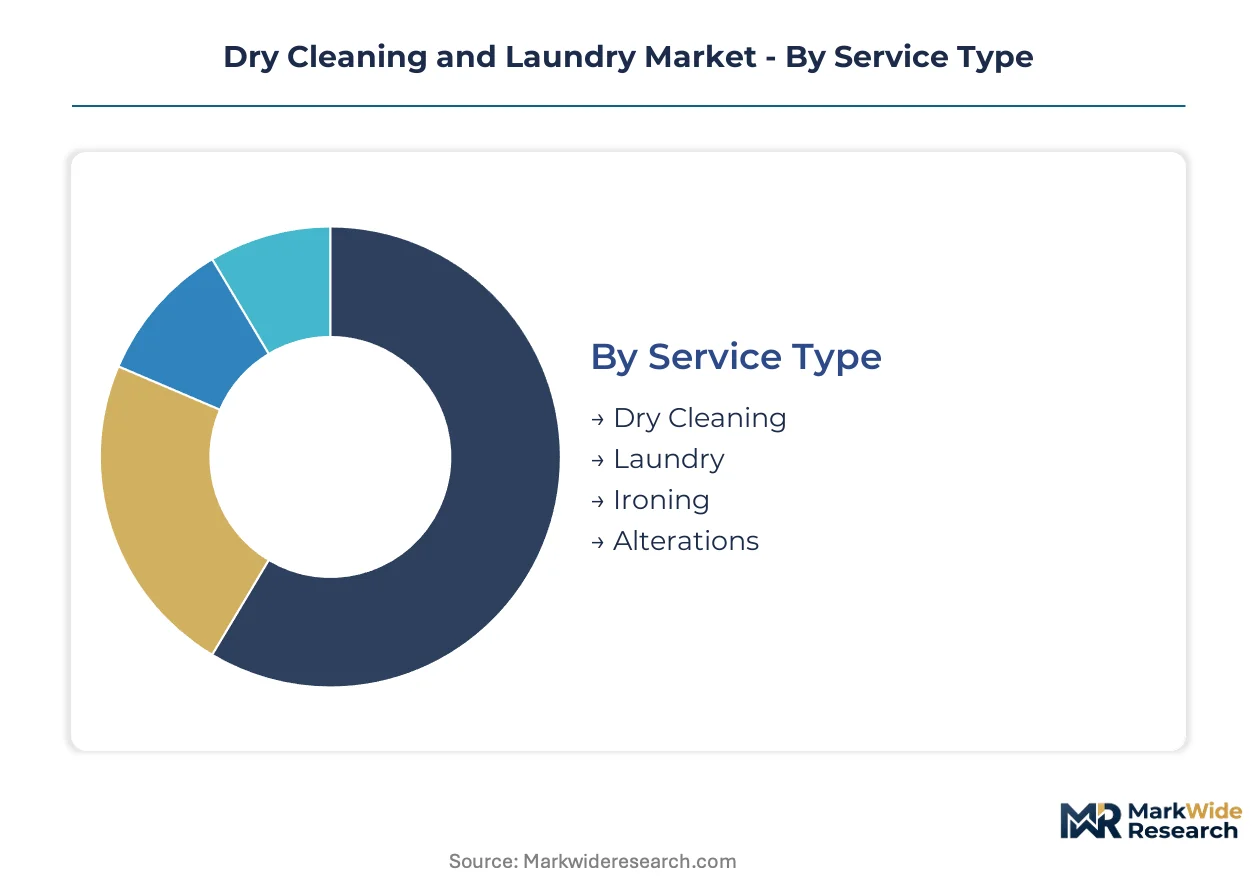
Segmentation in dry cleaning and laundry services reveals distinct operational economics across service intensities and client reliability profiles. Each dimension carries implications for capital deployment, labor scheduling, and compliance exposure that reshape competitive positioning.
Service Type:
Standalone garment care services operate at lower integration depth than bundled offerings that combine cleaning with finishing and restoration.
- Dry Cleaning:Solvent-based processing using perchloroethylene, hydrocarbon, or liquid CO2 systems operating at controlled temperatures for delicate fibers. Demand concentrates in affluent urban districts where professional attire maintenance commands premium pricing; REACH solvent restrictions in France and Germany are compressing perc-dependent operations while elevating certified industrial alternatives.
- Laundry:Aqueous washing processes for bulk textile processing at temperatures between 40°C and 85°C depending on fiber composition and hygiene requirements. Hospital networks in Belgium and the Netherlands are consolidating volume under decade-long contracts with HACCP-accredited regional processors that guarantee predictable throughput.
- Ironing:Thermal finishing using steam or hot-air systems to restore garment structure and appearance.
- Alterations:Tailoring and repair services extending garment lifecycle through structural modification.
Volume placements concentrate in Laundry; the faster expansion belongs to Dry Cleaning as solvent substitution timelines accelerate equipment turnover.
Client Type:
Cost tier stratification separates price-sensitive transactional demand from contracted volume commitments with multi-year visibility.
- Residential:Individual consumers purchasing garment care on an episodic basis with high sensitivity to convenience and turnaround time.
- Commercial:Small businesses and professional service firms requiring uniform maintenance and linen services without dedicated facilities.
- Hospitality:Hotel and restaurant operators outsourcing linen management under volume-guaranteed contracts; German and French chains are consolidating programs with commercial laundries that offer ISO 14001-certified processing to satisfy corporate sustainability mandates.
- Corporate:Large enterprises with captive uniform programs and Scope 3 reporting requirements that specify environmental management system certification as a mandatory tender criterion.
Contracted volume anchors in Hospitality; Corporate is climbing the fastest as ESG procurement standards harden.
Technology:
Maturity gradients separate legacy equipment bases from capital-intensive automation deployments that compress labor hours per kilogram.
- Traditional:Conventional batch washers and solvent-based dry cleaning systems with established maintenance protocols and technician availability.
- Automated:Continuous batch washers and tunnel finisher systems that halve water consumption per kilogram compared to conventional equipment; seven-figure euro capital requirements exclude independent operators from this tier.
- Eco-Friendly:Wet-cleaning and liquid CO2 infrastructure eliminating perc dependency; the EU Ecodesign for Sustainable Products Regulation is forcing adoption timelines across Italian and Spanish facilities facing ECHA sunset dates.
- Manual:Labor-intensive processing for specialized restoration or delicate items unsuited to mechanical handling.
Installed base dominance rests with Traditional; Eco-Friendly is gaining share fastest as municipal emission restrictions tighten.
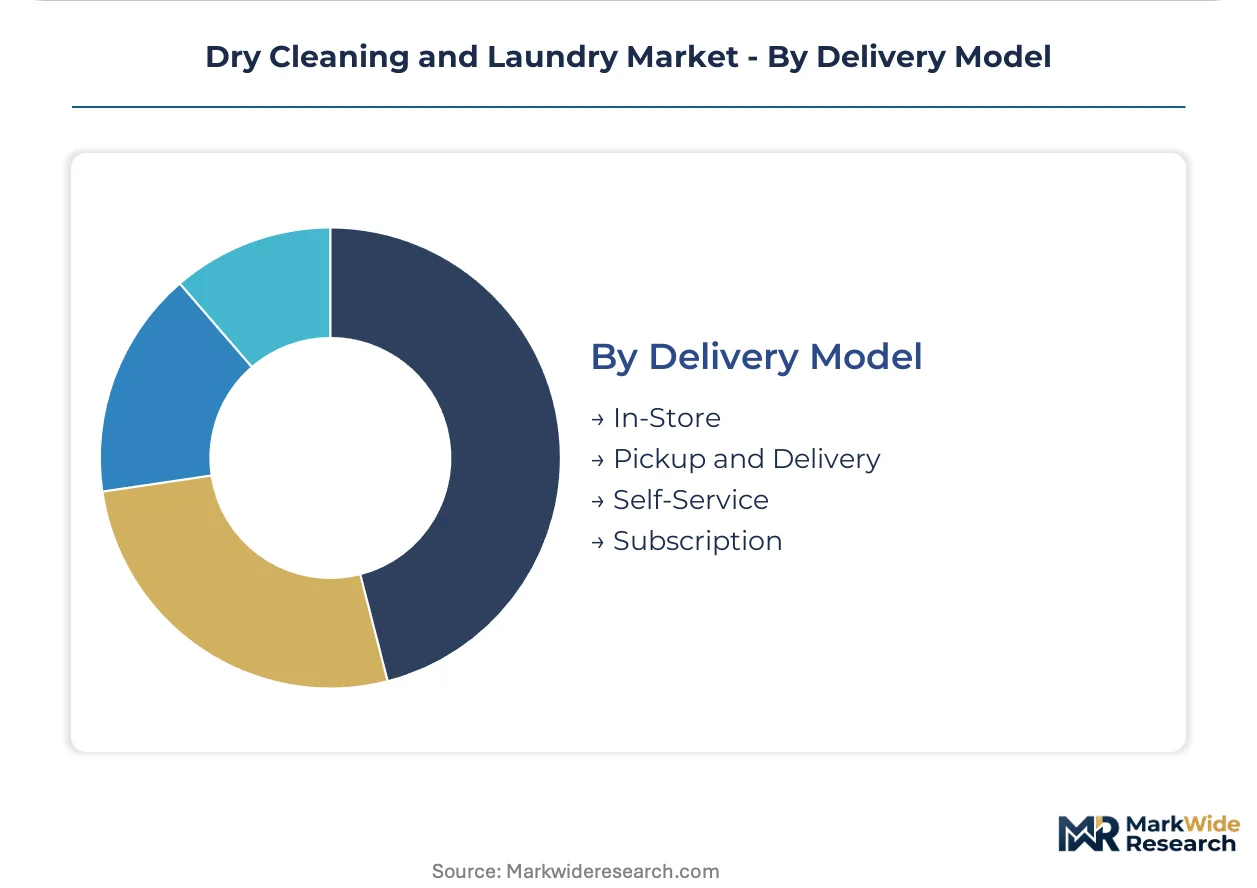
Delivery Model:
Customer access patterns differentiate between fixed-location service and logistics-intensive models with distinct working capital profiles.
- In-Store:Fixed-location processing with customer drop-off and collection; neighborhood operators in dense European urban centers maintain this structure despite rising real estate costs.
- Pickup and Delivery:Scheduled collection and return logistics adding transportation costs but capturing time-sensitive residential and commercial demand.
- Self-Service:Coin-operated or card-activated machines in laundromat format with minimal labor content; prevalent in student districts and transient-worker neighborhoods.
- Subscription:Recurring revenue models with predictable volume commitments; boutique hotel operators in Copenhagen and Amsterdam are piloting compact CO2 units for on-premise garment care under operational lease structures.
Transaction density peaks in In-Store; Subscription shows the steepest expansion trajectory as hospitality groups shift from capital purchase to performance-based equipment arrangements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Düsseldorf anchors the densest concentration of commercial linen processors in Europe, where hospital networks and hospitality chains drive contract consolidation.
Germany
Hospital linen contracts in North Rhine-Westphalia and Bavaria demand ISO 14001-certified processing with perc-free solvent systems. REACH authorization timelines enforced by ECHA are accelerating equipment turnover at independent operators. Frankfurt's commercial laundries are deploying continuous batch washers to meet municipal discharge limits.
France
Elis SA maintains geographic density in hospital linen management across Île-de-France and Benelux border zones. The EU Green Deal is repositioning Parisian dry cleaning operations toward wet-cleaning infrastructure. Lyon and Marseille processors are consolidating under multi-year hospitality contracts with volume guarantees.
United States
EPA National Emission Standards for Hazardous Air Pollutants enforce perc facility compliance across metropolitan markets. Cintas Corporation anchors captive uniform rental networks integrating on-premise laundering. Chicago and New York commercial laundries are replacing batch washers with tunnel finisher systems.
Netherlands
Amsterdam boutique hotel operators pilot compact liquid CO2 units for on-premise garment care under operational lease structures. Hospital networks in Rotterdam and Utrecht award decade-long hygiene contracts requiring HACCP accreditation. Municipal water pricing reforms are compressing margins at heat-intensive finishing operations.
Italy
ECHA sunset dates for perc are triggering equipment write-downs at independent dry cleaners in Milan and Rome. REACH solvent restrictions are transferring volume to certified industrial laundries with environmental management systems. Tuscany hospitality groups are outsourcing linen management under multi-year commercial contracts.
Dry Cleaning and Laundry Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification tiers and contract duration. The vendor base separates into capitalized operators with ISO 14001 systems and fragmented neighborhood independents facing compliance cost escalation. Three archetypes dominate: integrated uniform rental networks, geographic-density linen specialists, and equipment-scale manufacturers. Consolidation is accelerating through multi-year hospitality contract capture and tunnel washer system deployment.
Within the integrated service tier, Cintas Corporation and Elis SA exemplify divergent geographic strategies. Cintas anchors North American uniform rental density through captive processing networks. Elis SA occupies a position in European hospital linen consolidation across France and Benelux. Alliance Laundry Systems LLC represents the equipment-scale archetype, manufacturing commercial washers and tunnel systems that define processing economics for contract operators.
| Leading Market Players |
|---|
| Aramark |
| Cintas Corporation |
| Alliance Laundry Systems LLC |
| ZIPS Dry Cleaners |
| Tide Cleaners |
| Rinse, Inc. |
| Cleanly |
| Elis SA |
| The Huntington Company |
| Others |
Pricing and Supply Chain Analysis
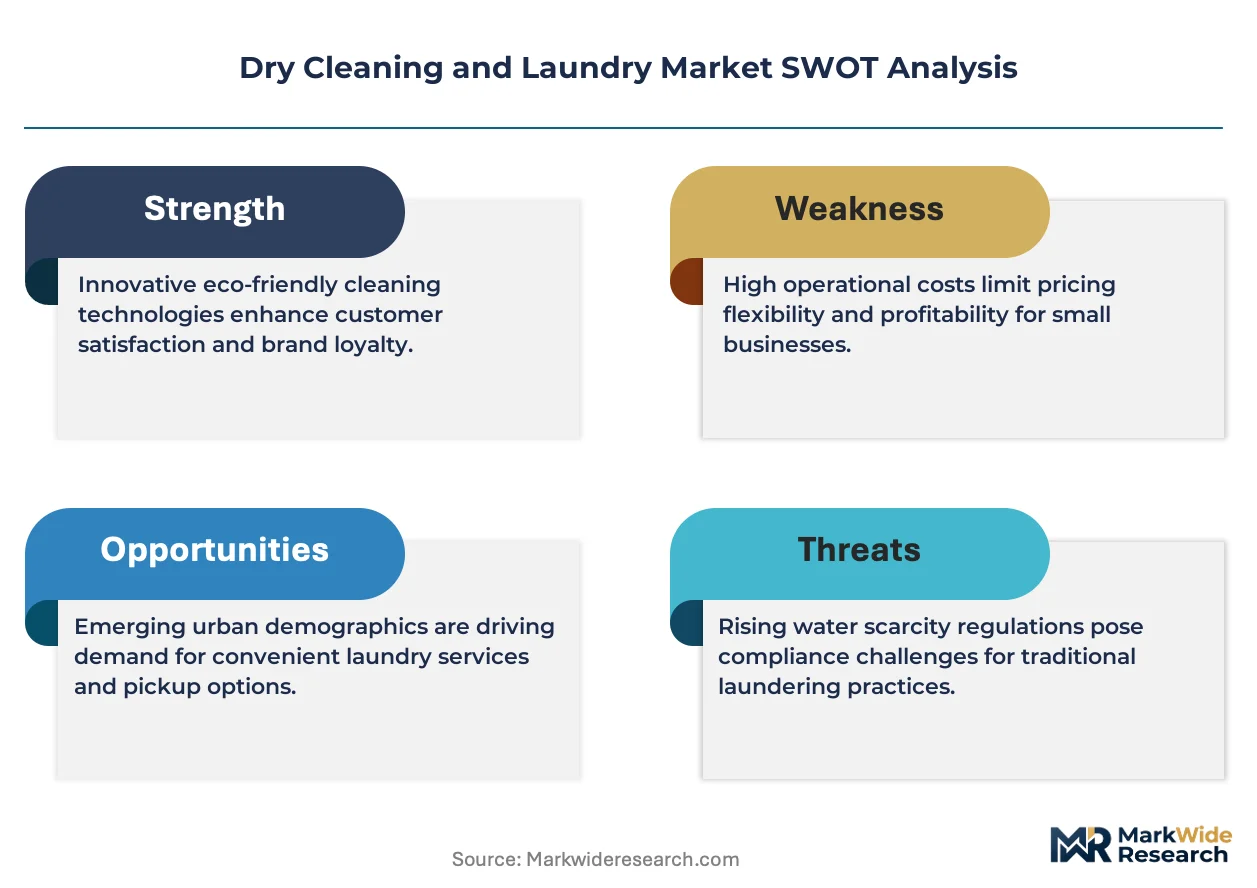
Natural gas and electricity tariffs in Germany and Italy cascade through tunnel finisher operating costs to compress margins at heat-intensive finishing operations, forcing operators toward subscription-based equipment leases that transfer balance sheet burden to manufacturers while preserving pricing power for capitalized players with environmental management systems.
Pricing Analysis
Uptime-guaranteed performance contracts anchor value-based pricing for tunnel washer systems, with three-tier pricing structure across premium, standard, and economy levels separating ISO 14001-certified processors from HACCP-accredited regional players and uncertified independents. Cost compression in the economy tier is intensifying because REACH solvent restrictions are triggering equipment write-downs at perc-dependent operators. Corporate uniform programs with Scope 3 mandates show least price sensitivity; residential consumers exhibit highest sensitivity to turnaround time premiums.
Supply Chain Analysis
Dual-sourcing requirements for liquid CO2 and hydrocarbon solvents mandate multi-supplier qualification across German, Italian, and Spanish chemical distributors to mitigate single-source vulnerability from ECHA authorization timelines. Equipment manufacturing draws from German precision engineering clusters, Chinese steel fabrication, and Italian control systems integration. Distribution runs through manufacturer-direct channels for tunnel systems and regional distributor networks for consumables and spare parts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment technician scarcity props pricing for maintenance contracts, creating supply-constrained conditions that favor operators with captive training pipelines over fragmented independents facing labor cost escalation.
For Market Incumbents: Deploy backward integration into solvent recycling infrastructure to capture margin from REACH-driven substitution timelines. Consolidate market position through multi-year hospitality contract capture in France and Benelux, where hospital linen density rewards geographic concentration. Counter wet-cleaning technical limitations by investing in liquid CO2 pilot programs that eliminate thermal energy dependency entirely.
For New Entrants and Emerging Players: App-based subscription routing offers the most penetrable channel for residential demand in dense European urban centers where convenience premiums outweigh price sensitivity. Target boutique hotel operators in Copenhagen and Amsterdam piloting on-premise CO2 units under operational lease structures. White-space exists in HACCP-accredited regional processing for Dutch and Belgian hospital networks awarding decade-long hygiene contracts.
For Investors and Strategic Acquirers: ECHA sunset date announcements for perchloroethylene are the leading indicator that certified industrial laundries will absorb volume from decommissioned independents. Long-term viability favors capitalized operators with ISO 14001 systems and tunnel washer deployment capability. Acquisition focus should center on regional processors with existing hospital linen density and municipal discharge compliance infrastructure.
| Strategic Initiative | Industry Significance |
|---|---|
| Wet-Cleaning Infrastructure Deployment | REACH solvent restrictions in France and Germany mandate perc-free processing timelines. |
| Continuous Batch Washer Installation | Tunnel systems halve water consumption per kilogram for municipal discharge compliance. |
| Operational Lease Structuring | Hospitality groups shift capital burden to manufacturers while securing uptime guarantees. |
| ISO 14001 Certification Investment | Corporate Scope 3 reporting mandates elevate tender eligibility barriers for institutional contracts. |
| Liquid CO2 Recovery Systems | Closed-loop technology eliminates thermal energy dependency from the cleaning cycle. |
Research Methodology
Trade association filings, ECHA regulatory databases, and municipal water pricing records formed the secondary backbone, supplemented by primary interviews with commercial laundry operations directors, hospital procurement managers, hospitality linen program heads, and equipment manufacturer sales engineers. Bottom-up volume modeling across service type, client segment, technology tier, and delivery mode was triangulated against top-down market sizing from customs data and industry association membership records.
Top-down macroeconomic indicators were reconciled with bottom-up operator capacity utilization rates across the analysis window. Segmentation dimensions modeled include service intensity, contract duration, certification tier, and regional regulatory cluster. CAGRs were derived from equipment deployment trajectories and solvent substitution timelines rather than extrapolated trend lines. Forecast inputs incorporated REACH authorization schedules and municipal discharge limit enforcement patterns.
Inputs from commercial operators and institutional buyers were available through the study window; gaps in independent neighborhood operator financial disclosure introduce uncertainty bands around fragmentation estimates. Deviation in ECHA sunset date enforcement or natural gas tariff trajectories would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Insulated Tumblers Market
Household Items
Snow Blower Market
Household Items
Smart Shower Market
Household Items
Tiki Torch Market
Household Items
Sleeping Pillow Market
Household Items
Sanitary Napkin Receptacles Market
Household Items
Mosquito Lamps Market
Household Items
Smart Pool Skimmer Market
Household Items
Electric Shoe Polisher Market
Household Items
Compressed Tablet Towel Market
Household Items
Barbeque Grill Market
Household Items
Wipes Market
Household Items
Party Balloon Market
Household Items
Dosage Spoon Market
Household Items
Asia-Pacific Air Purifier Market
Household Items
US Air Fresheners Market