
 Saudi Arabia Pet Food Market | 2026-2036
Saudi Arabia Pet Food Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Pet Food Market Intelligence
Aftermarket service revenue is tilting toward veterinary-linked nutritional counseling and subscription replenishment programs. Mars Petcare leverages its therapeutic diet portfolio to anchor clinic-channel relationships across the Kingdom. Royal Canin specializes in breed-specific formulations that dominate the premium shelf space in Jeddah and Riyadh pet stores. Nestlé Purina PetCare competes through localized packaging and Arabic-label compliance that sustains supermarket penetration.
Pet food comprises formulated nutritional products manufactured through extrusion, canning, or fresh preparation processes, with protein content, moisture ratios, and micronutrient profiles calibrated to species-specific metabolic requirements. Dry food occupies the largest volume share due to shelf stability and lower logistics costs across Saudi Arabia's dispersed retail network. Wet food commands the fastest value growth as cat owners in urban centers prioritize hydration-linked formulations. Treats represent a concentrated margin pool where premium positioning and gift-oriented packaging drive per-unit profitability.
SFDA halal certification requirements and the Saudi Food and Drug Authority's ingredient traceability mandates shape import clearance timelines and domestic manufacturing investment decisions. The Saudi Standards, Metrology and Quality Organization (SASO) technical regulations for animal feed safety create compliance barriers that favor established multinationals with dedicated regulatory affairs teams. Stakeholders must monitor evolving pet humanization trends and veterinary clinic consolidation patterns to anticipate channel power shifts and formulation premiumization trajectories.
Market Dynamics
SFDA halal certification mandates and SASO feed safety technical regulations are compressing import timelines and forcing domestic manufacturing investment decisions among multinational suppliers serving Saudi Arabia's urban pet-owning households.
Growth Catalysts
- Urban Pet Humanization:Riyadh and Jeddah households treat companion animals as family members, creating demand for veterinary-grade nutrition and breed-specific formulations that mirror human food quality expectations.
- SFDA Regulatory Clarity:The Saudi Food and Drug Authority's standardized halal certification pathways reduce import uncertainty, enabling faster product registration and shelf placement for compliant manufacturers.
- Veterinary Channel Expansion:Clinic consolidation across the Eastern Province creates concentrated prescription diet distribution points, locking in therapeutic nutrition contracts with premium suppliers.
Market Restraints
- Protein Input Volatility:Global poultry and fish meal price fluctuations compress formulation margins, forcing Saudi importers to absorb cost swings or pass through to price-sensitive standard-tier buyers.
- Import Dependency Concentration:European and North American suppliers dominate premium dry food manufacturing, exposing distributors to shipping lane disruptions and extended replenishment cycles.
- Halal Supply Chain Complexity:SFDA traceability mandates require segregated production lines and ingredient sourcing documentation that disqualifies non-compliant international facilities from market access.
Strategic Opportunities
- Eastern Province Underpenetration:Dammam and Al-Khobar residential districts show lower premium pet food saturation than Riyadh, creating whitespace for localized veterinary partnerships and Arabic-language marketing.
- Subscription Replenishment Models:Direct-to-consumer auto-ship programs bypass supermarket slotting fees and build recurring revenue streams among high-income cat-owning households in gated communities.
- SASO Domestic Manufacturing Incentives:Saudi Standards, Metrology and Quality Organization technical regulations favor in-country production, rewarding capital investment in Riyadh-based extrusion and canning facilities.
Industry Challenges
- Regulatory Affairs Talent Scarcity:SFDA registration specialists and halal compliance officers command premium salaries, constraining mid-size importers' ability to navigate multi-month product approval timelines.
- Cold Chain Capex Requirements:Wet food distribution demands refrigerated warehousing and last-mile delivery infrastructure that exceeds the capabilities of traditional dry goods distributors in Jeddah's ambient storage networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Pet Food Market |
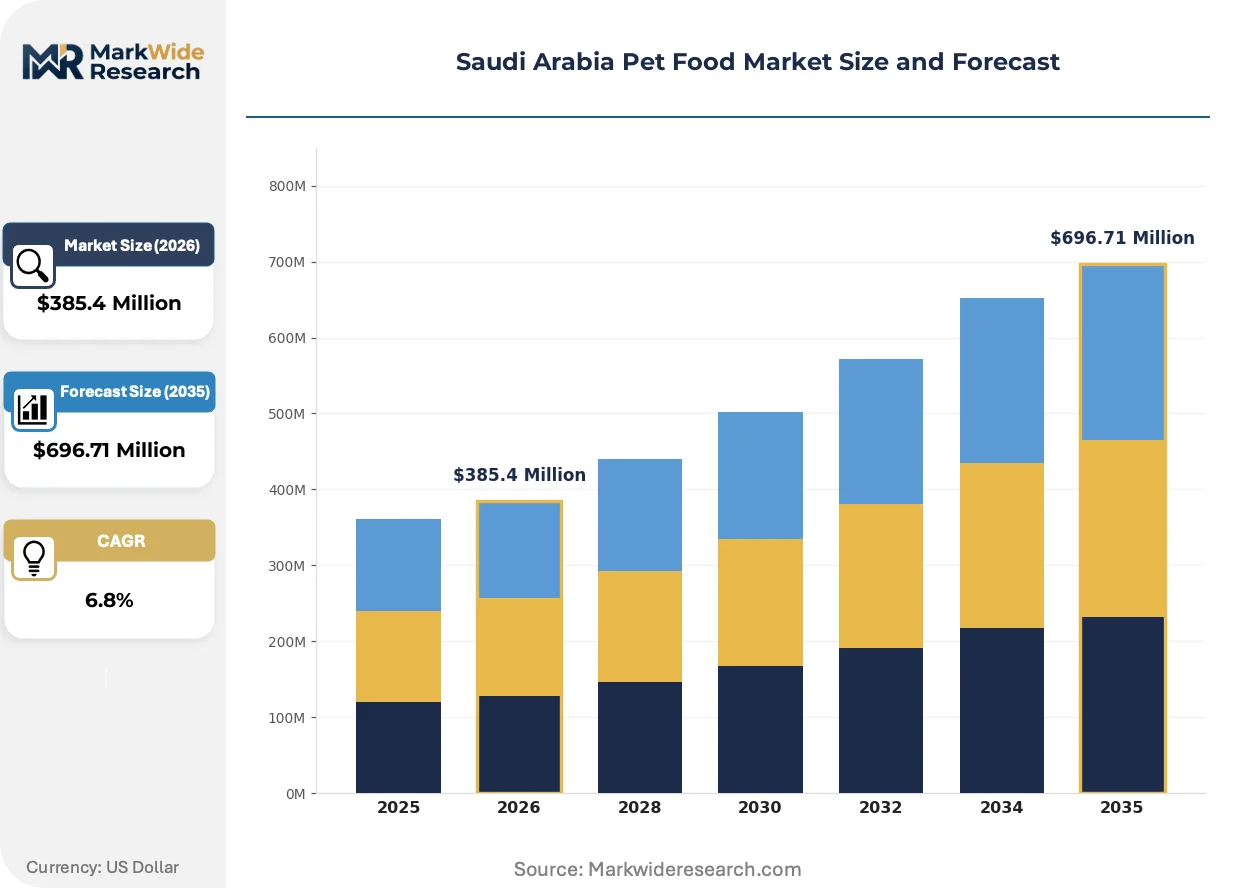
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $696.71 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Fresh Food Animal Type: Dogs, Cats, Birds, Small Mammals Distribution Channel: Online Retailers, Pet Stores, Supermarkets, Veterinary Clinics Price Tier: Premium, Mid-Range, Economy, Budget |
| Companies Covered | Royal Canin, Colgate-Palmolive, Mars Petcare, Blue Buffalo Pet Products, Del Monte Foods, Nestlé Purina PetCare, Delicious Food Factory, Spectrum Brands (United Pet Group), Hill's Pet Nutrition, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Pet Food Market Strategic Shifts & Innovations
Digital platforms and precision nutrition technologies are compressing traditional retail intermediation while elevating formulation science beyond commodity extrusion. Three developments merit particular attention.
Artificial intelligence-driven dietary recommendation engines are virtualizing the traditional veterinary consultation pathway. Saudi pet owners in Riyadh's high-income districts input breed, age, and health parameters into mobile applications that generate customized feeding protocols. Mars Petcare and Royal Canin leverage these tools to capture first-party consumer data and bypass supermarket shelf competition.
SFDA's 2023 ingredient traceability mandates require blockchain-enabled supply chain documentation from import through retail. The regulation forces European suppliers to retrofit legacy batch tracking systems, while domestic manufacturers gain compliance advantages through shorter chain-of-custody records. Wet food importers face the steepest adaptation costs due to perishable ingredient complexity.
Cat owners in Jeddah and Riyadh are consolidating purchases through veterinary clinic subscription programs that bundle nutritional counseling with auto-replenishment. Traditional pet store traffic is fragmenting as these locked-in relationships reduce brand-switching frequency. The shift concentrates channel power with clinic networks and erodes supermarket margin pools for standard-tier dry food.
Saudi Arabia Pet Food Market Segmentation
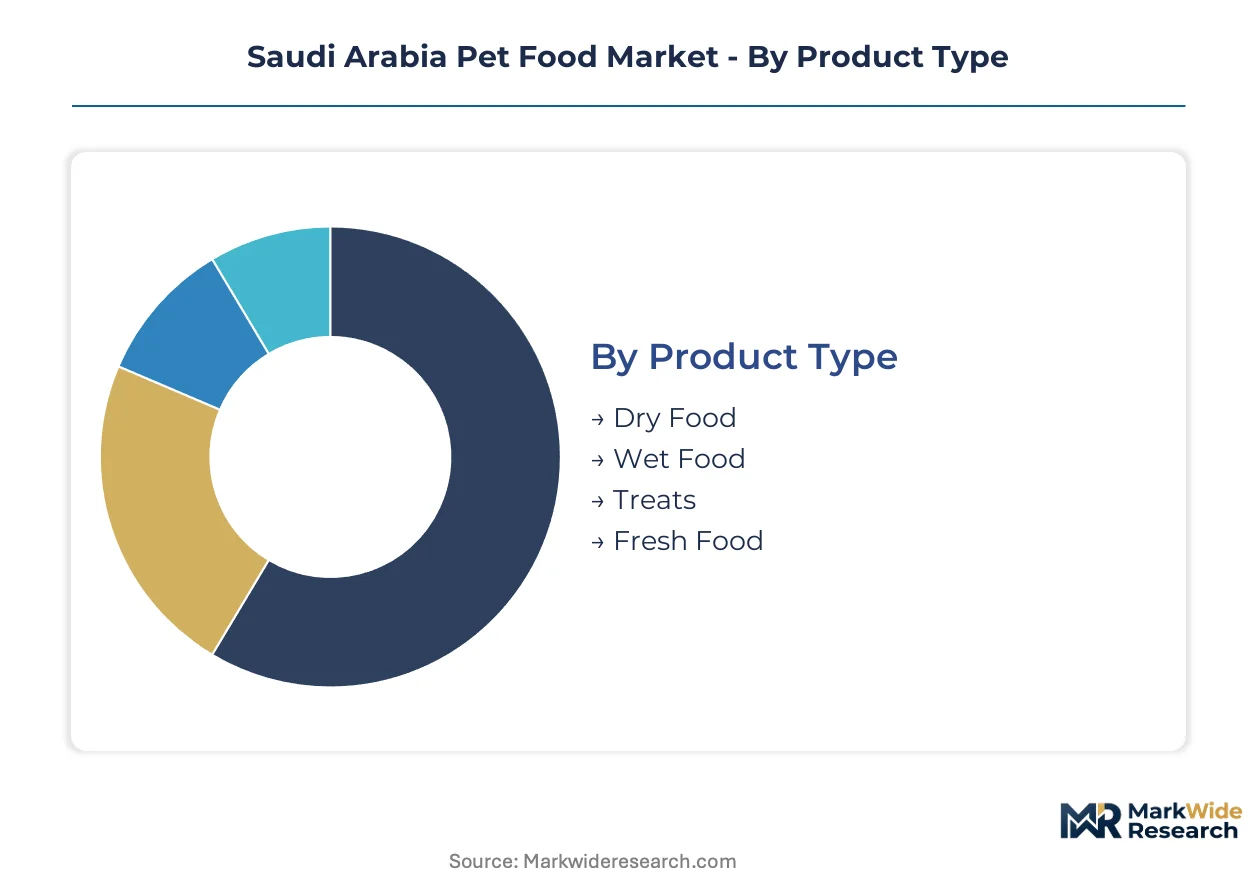
Segmentation in the Saudi Arabia pet food market reveals how urban household preferences and SFDA regulatory pathways fragment demand across formulation types and channel access tiers. Manufacturers calibrate portfolio depth against the veterinary clinic consolidation in Riyadh and Jeddah versus supermarket penetration in secondary cities.
Product Type:
Mature extrusion technology dominates dry food manufacturing, while emerging fresh preparation methods attract capital investment from domestic entrants seeking SASO compliance advantages.
- Dry Food:Extruded kibble formulations achieve moisture content below 10% through high-pressure thermal processing, enabling ambient storage across Saudi Arabia's dispersed retail network. Demand concentrates in Riyadh's standard-tier supermarket channels where bulk purchasing and shelf stability reduce household replenishment frequency. SFDA halal certification mandates favor established suppliers with segregated production lines.
- Wet Food:Canned or pouch formats maintain 75-85% moisture content through retort sterilization, addressing hydration concerns among urban cat owners. Growth concentrates in Jeddah's high-income districts where veterinary clinic subscription programs bundle therapeutic wet formulations with nutritional counseling. Cold chain infrastructure gaps in the Eastern Province constrain distribution reach.
- Treats:Functional and reward-oriented formulations occupy premium shelf positioning in pet specialty stores across gated Riyadh communities.
- Fresh Food:Refrigerated minimally processed meals gain traction through direct-to-consumer platforms serving Jeddah's expatriate-heavy districts.
Dry Food retains volume leadership; Wet Food holds the steepest expansion curve.
Animal Type:
Customer type segmentation separates established companion species from emerging niche ownership patterns across Saudi Arabia's urban household landscape.
- Cats:Obligate carnivores drive protein-rich formulation demand, with Saudi households prioritizing taurine-fortified diets. Concentration in Riyadh and Jeddah's high-income residential towers supports premium wet food subscription models. Breed-specific nutritional counseling through veterinary clinics locks in therapeutic diet loyalty.
- Dogs:Large-breed and working dog formulations serve security-conscious Eastern Province households and rural estates. Regulatory restrictions on public dog ownership in urban centers suppress mass-market growth relative to feline segments.
- Birds:Seed and pellet blends address avian ownership in Jeddah's traditional souk retail channels.
- Small Mammals:Rabbit and rodent nutrition remains underdeveloped, served primarily through online specialist importers.
Cats dominate value concentration; Dogs face regulatory headwinds in urban expansion.
Distribution Channel:
Margin structure varies sharply between high-touch veterinary consultation models and efficiency-driven supermarket replenishment across the Kingdom's retail hierarchy.
- Veterinary Clinics:Prescription diet distribution locks in therapeutic nutrition contracts through Eastern Province clinic consolidation. Mars Petcare and Royal Canin anchor relationships with breed-specific and condition-targeted formulations. First-party data capture through clinic management systems enables personalized replenishment scheduling.
- Online Retailers:Auto-ship subscription platforms bypass slotting fees and build recurring revenue among Riyadh's time-constrained professionals. Arabic-language interface compliance and SFDA traceability documentation determine platform eligibility.
- Pet Stores:Premium positioning and gift-oriented packaging drive per-unit profitability in Jeddah's mall-based specialty retailers.
- Supermarkets:Standard-tier dry food occupies high-velocity shelf space with localized Arabic labeling compliance.
Veterinary Clinics command the highest margin per transaction; Online Retailers gain share fastest among urban millennials.
Price Tier:
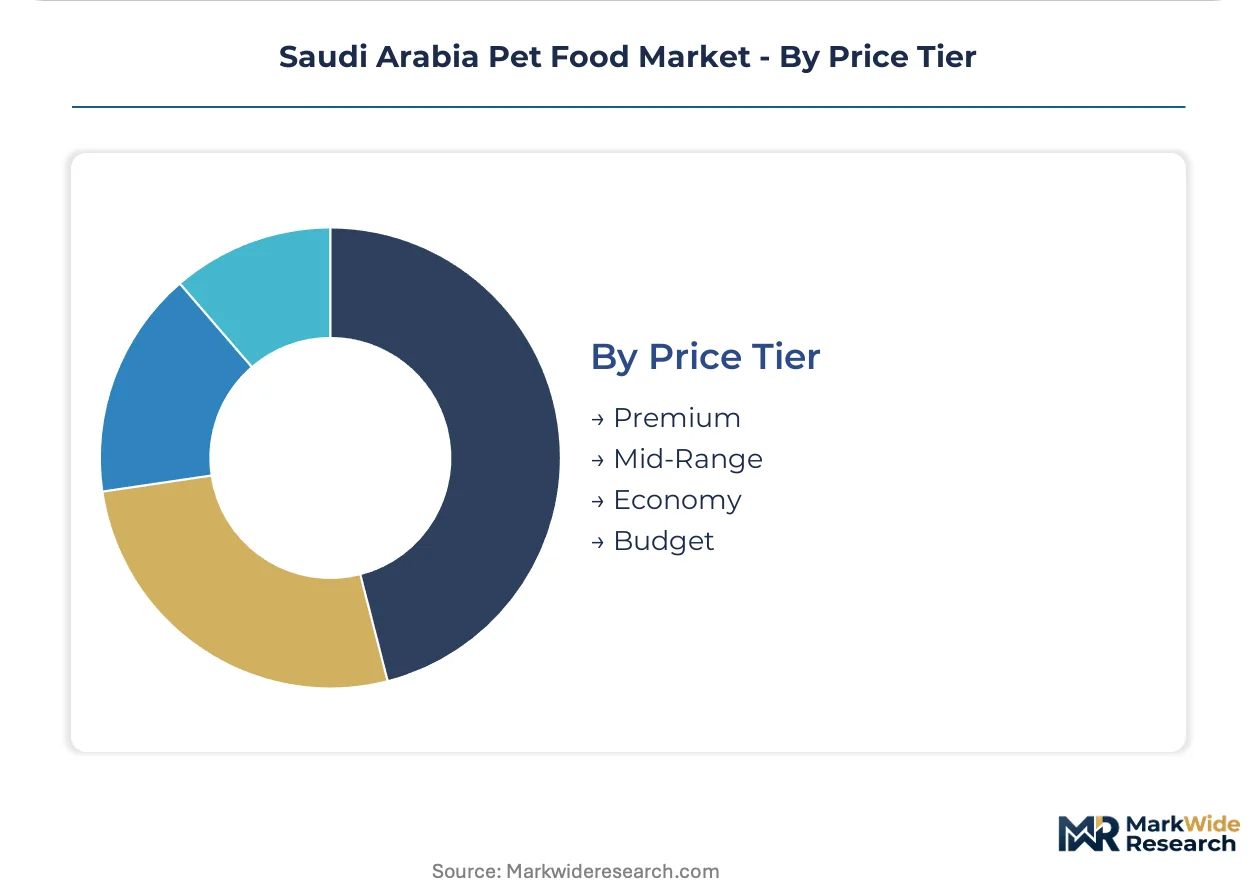
Cost tier segmentation reflects the divergence between veterinary-grade nutritional investment and commodity extrusion accessible to price-sensitive households.
- Premium:Human-grade ingredient sourcing and breed-specific formulation justify 3-4x standard-tier pricing in Riyadh's gated communities. Halal certification at ingredient level and blockchain traceability documentation satisfy SFDA mandates. Royal Canin dominates breed-specific shelf positioning.
- Mid-Range:Balanced nutrition positioning captures Jeddah's emerging middle-class pet owners transitioning from standard to enhanced formulations.
- Economy:Mass-market extruded products serve multi-pet households in secondary cities with basic nutritional adequacy claims.
- Budget:Unbranded or private-label offerings concentrate in traditional trade channels with minimal regulatory documentation.
Premium tier captures value concentration; Mid-Range expands most quickly through trade-up behavior.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban households in Riyadh prioritize premium wet food subscriptions, while Eastern Province buyers favor bulk dry food procurement through veterinary channels, creating a consumption-mix differential that shapes distribution infrastructure investment across the Kingdom.
Riyadh
High-income residential towers in the capital drive demand for breed-specific formulations and AI-driven dietary recommendation platforms. SFDA halal certification mandates accelerate product registration timelines for compliant suppliers. The Riyadh-based clinic consolidation trend locks in therapeutic nutrition contracts with premium pet food manufacturers.
Eastern Province
Dammam and Al-Khobar districts show lower premium pet food saturation, creating whitespace for localized veterinary partnerships. SASO technical regulations for animal feed safety favor domestic manufacturing investment in the region's industrial zones. Cold chain infrastructure gaps constrain wet food distribution reach compared to Riyadh's logistics networks.
Jeddah
Expatriate-heavy districts and mall-based specialty retailers anchor premium treat and gift-oriented packaging demand. Arabic-label compliance requirements sustain supermarket penetration for multinational suppliers. The Western Region's pet store traffic fragments as veterinary clinic subscription programs capture recurring revenue from cat-owning households.
NEOM Northwest
Emerging residential developments in the giga-project zone attract early-stage pet humanization trends among international resident populations. Domestic manufacturing incentives under Vision 2030 industrial policy reward capital investment in extrusion and canning facilities. Supply chain documentation requirements for SFDA traceability mandates favor shorter chain-of-custody records from nearby production sites.
Saudi Arabia Pet Food Market Key Industry Players
Capability concentration sits with multinational nutrition science specialists; scale advantage sits with diversified consumer goods conglomerates with existing Saudi distribution infrastructure. The market structure tilts toward tiered consolidation where therapeutic diet portfolios anchor high-margin veterinary channel relationships, while standard-tier dry food competes on supermarket shelf velocity and Arabic-label compliance. Three archetypes dominate: science-driven prescription diet specialists, mass-market extrusion scale players, and emerging domestic halal-certified manufacturers. Competitive moves concentrate on clinic-channel partnership lock-ins and SASO-compliant domestic production capacity expansion.
Within the science-driven prescription tier, Royal Canin and Hill's Pet Nutrition exemplify breed-specific and condition-targeted formulation expertise that dominates premium shelf positioning. Mars Petcare occupies a scale-driven position leveraging diversified pet nutrition portfolios across multiple price tiers and channel access points. Among diversified consumer goods conglomerates, Nestlé Purina PetCare and Colgate-Palmolive anchor mass-market penetration through localized packaging compliance and existing Saudi retail relationships.
| Leading Market Players |
|---|
| Royal Canin |
| Colgate-Palmolive |
| Mars Petcare |
| Blue Buffalo Pet Products |
| Del Monte Foods |
| Nestlé Purina PetCare |
| Delicious Food Factory |
| Spectrum Brands (United Pet Group) |
| Hill's Pet Nutrition |
| Others |
Cost & Logistics Intelligence
Riyadh-based extrusion and canning facilities anchor domestic production capacity, with SFDA halal certification compliance granting local manufacturers pricing leverage over European importers facing extended clearance timelines and segregated production line investments.
Pricing Analysis
Long-term subscription contracts dominate premium tier transactions, while spot purchasing persists in standard-tier supermarket channels. Price differentiation rests on halal certification grade and veterinary consultation bundling, with clinic-linked auto-replenishment commanding 3-4x economy tier levels. Cost compression in mid-range dry food is intensifying because poultry meal input volatility forces margin absorption or trade-down risk. Budget-tier buyers in secondary cities exhibit highest price sensitivity; gated community households in Riyadh show lowest.
Supply Chain Analysis
European contract manufacturers and Thai halal-certified processors hold dominant import capacity serving Saudi distributors. Raw material sourcing draws from Brazilian poultry meal, Peruvian fish meal, and Australian lamb by-products. Single-source vulnerability concentrates in European premium dry food production, exposing replenishment cycles to shipping lane disruptions. Distribution runs through veterinary clinic networks for therapeutic tiers and supermarket ambient storage for standard extruded products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Veterinary nutritional counseling and subscription replenishment programs represent the fastest-expanding revenue layer, outpacing hardware-equivalent product sales as service-attach deepens household lifetime value.
For Market Incumbents: Pre-empt domestic manufacturing scale-up by securing SASO-compliant extrusion capacity in Riyadh industrial zones before import dependency penalties tighten. Lock in Eastern Province veterinary clinic networks through exclusive therapeutic diet distribution contracts to forestall emerging halal-certified local challengers.
For New Entrants and Emerging Players: Eastern Province premium wet food underpenetration represents the most penetrable entry point, with Dammam and Al-Khobar residential districts showing lower saturation than Riyadh. Direct-to-consumer Arabic-language auto-ship platforms bypass supermarket slotting barriers and capture recurring revenue from time-constrained professionals.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors domestic halal-certified manufacturers with SFDA regulatory affairs capabilities and shortened supply chain documentation. Acquisition targets should demonstrate clinic-channel relationship density and blockchain-enabled traceability infrastructure. Watch SFDA domestic manufacturing incentive expansion as inflection signal for capital deployment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Manufacturing Scale-Up | Riyadh-based extrusion capacity captures SASO compliance advantages and reduces import clearance exposure. |
| Veterinary Clinic Network Partnership | Exclusive therapeutic diet distribution locks in recurring revenue through Eastern Province consolidation. |
| Subscription Replenishment Platform Launch | Auto-ship programs bypass supermarket slotting fees and build first-party data among urban millennials. |
| Halal Certification Infrastructure Investment | Segregated production lines satisfy SFDA traceability mandates and qualify for faster product registration. |
| Cold Chain Distribution Expansion | Refrigerated warehousing addresses wet food growth constraints in Jeddah and Eastern Province logistics gaps. |
Research Approach
Operator-level perspectives from veterinary clinic directors, pet specialty retail buyers, SFDA regulatory affairs specialists, and multinational supply chain managers anchored the qualitative base. Secondary validation drew from SASO technical regulation filings, SFDA product registration databases, Saudi customs import records, and veterinary industry association membership data. Bottom-up household penetration modeling and top-down manufacturer shipment triangulation produced volume and value estimates.
Scenario-bracketing around protein input cost volatility and regulatory enforcement intensity framed the analytical approach across the projection horizon. Segmentation dimensions modeled include product formulation type, animal species, distribution channel tier, and price positioning band. CAGRs were derived from trend-line extrapolation against urban household pet ownership growth curves and veterinary clinic expansion trajectories.
Practitioners should monitor SFDA halal certification timeline extensions and poultry meal commodity price swings for early signals of forecast revision. Quarterly review of veterinary clinic consolidation rates and domestic manufacturing permit approvals is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
China Pet Clothing Market
Pet Care Products
Automatic and Smart Pet Feeder Market
Pet Care Products
South Africa Pet Training Services Market
Pet Care Products
Smart Pet Leash Market
Pet Care Products
Cat Diets Market
Pet Care Products
Pet Transport Cage Market
Pet Care Products
Plant-Based Dog Food Market
Pet Care Products
Tofu Cat Litter Market
Pet Care Products
US Pet Treats Market
Pet Care Products
Aquarium Market
Pet Care Products
India Pet Clothing Market
Pet Care Products
UTI Cat Food Market
Pet Care Products
China Pet Food Market
Pet Care Products
Pet Tech Market
Pet Care Products
Pet Relaxants Market
Pet Care Products
Pet Jerky Treat Market