
 Mexico Pet Food Market | 2026-2036
Mexico Pet Food Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Pet Food Market Outlook
Domestic pet food manufacturing capacity in Jalisco and Querétaro is decoupling from import dependency as local extrusion and canning lines scale output. Mars, Incorporated leverages its Puebla production complex to anchor national distribution for dry and wet portfolios. Nestlé Purina competes through veterinary channel partnerships that sustain prescription diet revenues. Grupo Sesajal differentiates via grain-free formulations using regionally sourced proteins.
Pet food comprises nutritionally complete and complementary feeds formulated from animal proteins, cereals, fats, vitamins, and minerals, processed through extrusion, baking, or retorting to meet species-specific dietary requirements. Dry Food dominates volume throughput due to shelf stability and lower logistics costs, while Treats capture expanding margin pools as humanization trends elevate discretionary spending. Wet Food retains structural importance in veterinary-prescribed therapeutic diets where moisture content and palatability drive compliance.
COFEPRIS enforces NOM-012-ZOO-1993 standards for pet food labeling and ingredient safety, while SENASICA monitors import sanitary certificates for animal-origin inputs. SAGARPA rural development programs indirectly shape raw material availability through livestock and grain subsidies. Stakeholders must monitor evolving NOM revisions and e-commerce compliance obligations as direct-to-consumer channels bypass traditional retail gatekeepers.
Market Dynamics
Domestic manufacturing capacity expansion in Jalisco and Querétaro is severing Mexico's historical reliance on U.S. and Canadian imports, while SENASICA's tightening sanitary certificate requirements for animal-origin inputs force reformulation strategies across the value chain.
Growth Catalysts
- COFEPRIS NOM-012-ZOO-1993 enforcement:Stricter labeling and ingredient safety standards elevate compliance costs for informal producers, accelerating formal channel consolidation and quality-tier premiumization.
- Urban millennial pet ownership:Metropolitan concentration in Mexico City, Guadalajara, and Monterrey generates sustained demand for veterinary-prescribed therapeutic diets and grain-free formulations.
- Extrusion technology localization:Domestic canning and dry food production lines in central Mexico reduce logistics costs and import duty exposure for national distribution networks.
Market Restraints
- Animal protein input volatility:SENASICA-monitored import certificates for poultry meal and fish derivatives expose formulators to supply interruptions and price swings.
- Metropolitan demand concentration:Overreliance on three urban corridors concentrates volume risk and intensifies retail slotting fee competition.
- Wet food logistics costs:Higher moisture content elevates transport weight and refrigeration requirements, compressing margins outside premium therapeutic segments.
Strategic Opportunities
- Direct-to-consumer channel expansion:E-commerce platforms bypass traditional retail gatekeepers, enabling subscription models and personalized nutrition portfolios.
- SAGARPA rural development alignment:Livestock and grain subsidy programs offer raw material cost advantages for producers integrating with domestic agricultural supply chains.
- Veterinary channel deepening:Prescription diet partnerships with clinics and hospitals capture recurring revenue streams and build switching costs.
Industry Challenges
- NOM revision tracking:Evolving COFEPRIS standards require continuous reformulation and label redesign, extending product development cycles.
- E-commerce compliance complexity:Direct-to-consumer fulfillment obligations span multiple state-level tax and sanitary registrations, fragmenting operational overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Pet Food Market |
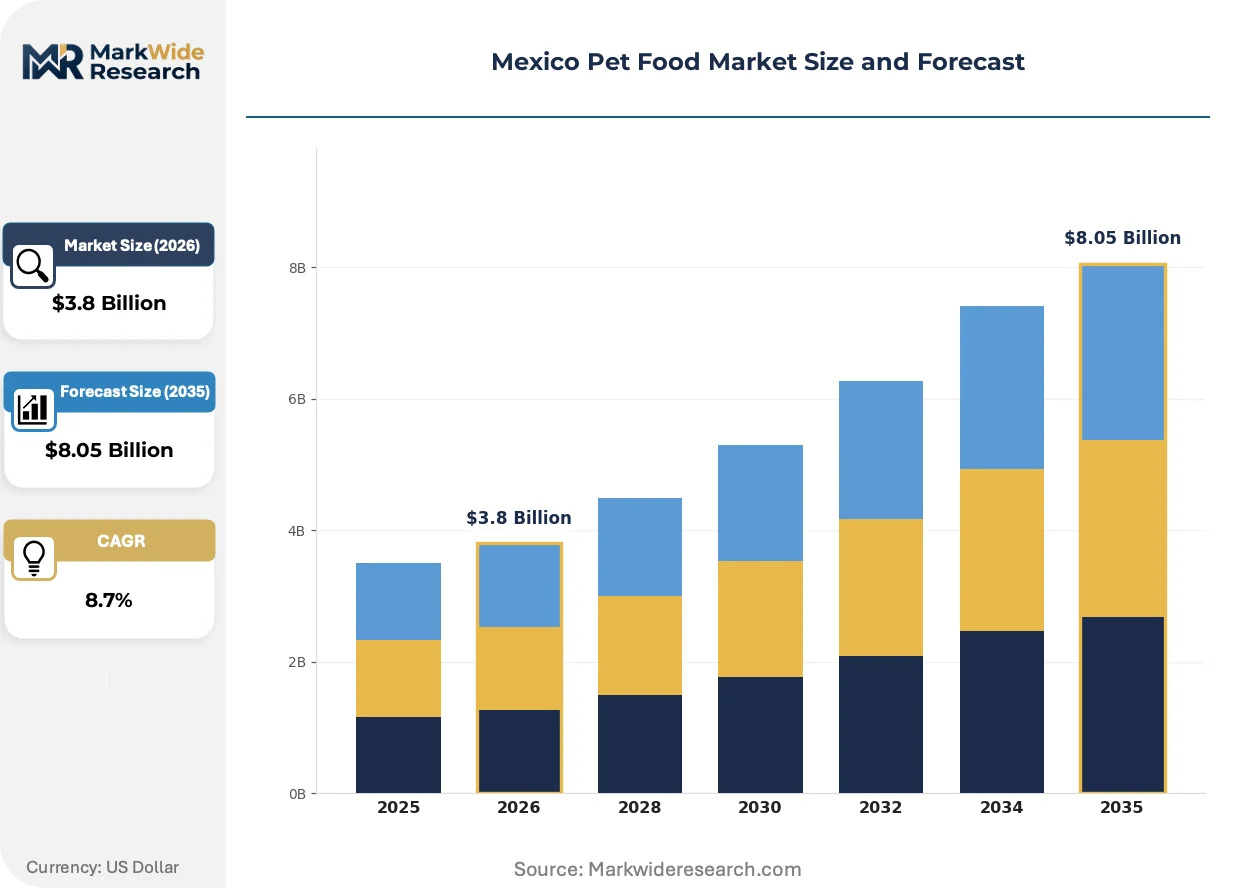
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Supplements Animal Type: Dogs, Cats, Birds, Fish Distribution Channel: Retail Stores, E-commerce, Veterinary Clinics, Pet Shops Price Tier: Premium, Mid-range, Economy, Value |
| Companies Covered | Colgate-Palmolive Company (Hill's Pet Nutrition), General Mills, Mars, Incorporated, Affinity Petcare SA, Grupo Sesajal, Nestlé Purina, Schell & Kampeter, Inc. (Diamond Pet Foods), Dechra Pharmaceuticals PLC, ADM, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Pet Food Market Strategic Shifts
Humanization of pet relationships is compressing the innovation cycle from human food to pet food, forcing manufacturers to replicate clean-label, functional ingredient, and sustainability credentials at accelerated pace.
Cold-pressed extrusion technology is rewriting protein bioavailability benchmarks in dry food manufacturing. Premium and super-premium brands in Mexico City and Guadalajara are adopting these lower-temperature processes to preserve amino acid integrity and market differentiated nutritional claims. The technology is compressing the quality gap between imported European formulations and domestically produced alternatives.
COFEPRIS is tightening traceability mandates for animal-origin inputs under revised NOM-012 protocols. Manufacturers must now document supply chain provenance for meat meals and rendered proteins, elevating documentation costs and disqualifying informal suppliers. Wet food and treat segments with complex multi-protein formulations face the steepest compliance recalibration.
Veterinary clinics are displacing mass retail as the primary education and trial channel for therapeutic and preventive nutrition. Pet owners in Monterrey's affluent districts increasingly purchase initial diets through prescription and maintain replenishment via clinic-affiliated e-commerce portals. This channel rotation compresses price transparency and builds durable manufacturer-veterinarian revenue shares.
Mexico Pet Food Market Segmentation
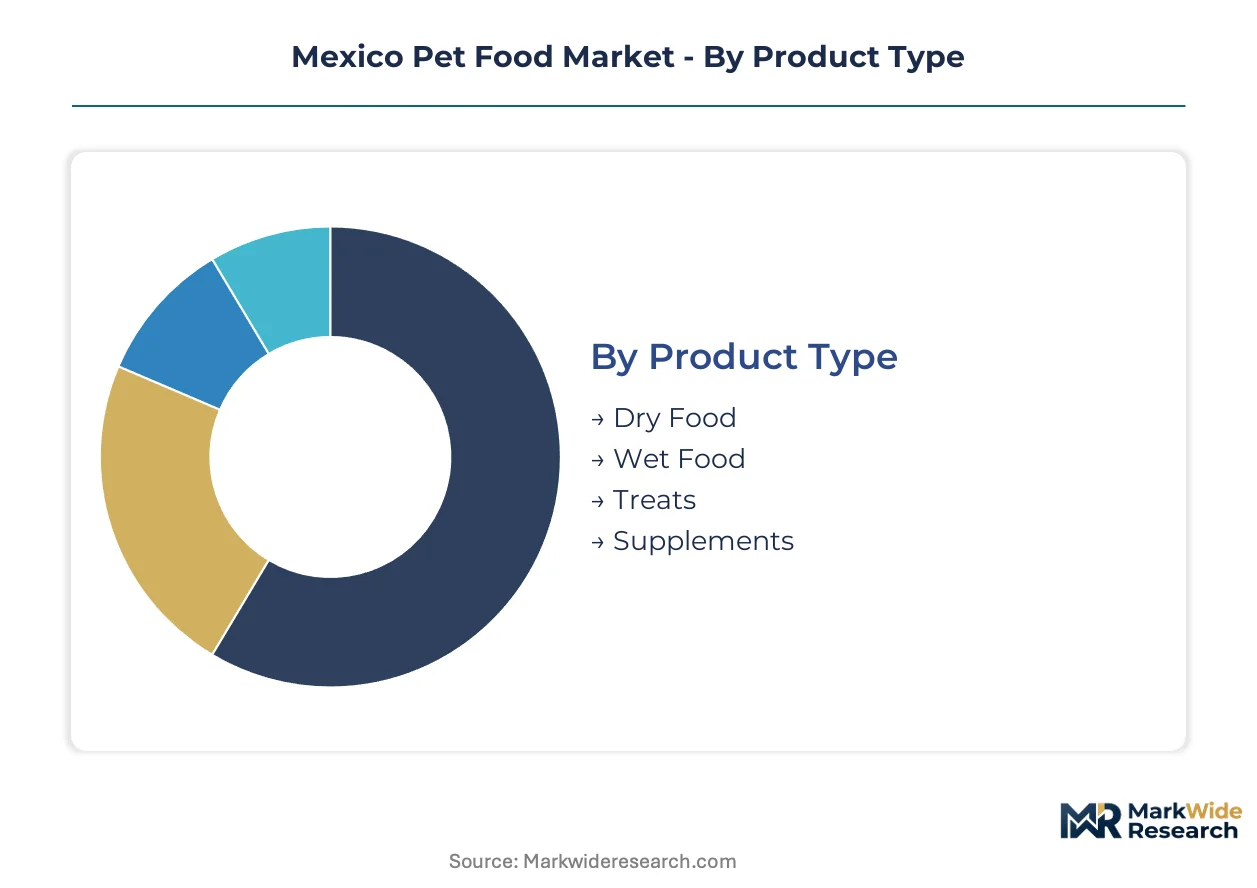
Segmentation in the Mexico pet food market reveals how supply-side capabilities, regulatory compliance burdens, and channel economics allocate margin across distinct product tiers. Understanding these divides exposes where manufacturing investments and distribution partnerships concentrate competitive advantage.
Product Type:
Extrusion and canning line investments in Jalisco and Querétaro have reconfigured output capacity across physical form factors, with moisture content and shelf stability determining logistics economics and margin capture.
- Dry Food:Extruded kibble formulations achieve shelf stability through low moisture content, enabling ambient storage and bulk distribution. Mexico City, Guadalajara, and Monterrey metropolitan corridors absorb the majority of tonnage, driven by lower per-kilogram logistics costs and extended retail shelf life.
- Wet Food:Retorted cans and pouches deliver higher palatability and moisture content, processed through SENASICA-monitored canning lines. Veterinary-prescribed therapeutic diets in Monterrey's affluent districts sustain premium positioning despite elevated transport weight and refrigeration requirements.
- Treats:Baked and freeze-dried formats command discretionary spending premiums as humanization trends elevate snacking occasions.
- Supplements:Functional additives targeting joint, digestive, and coat health occupy niche positioning requiring COFEPRIS NOM-012 compliance for label claims.
Dry Food absorbs the bulk of installed capacity; Treats are expanding most quickly as margin pools shift toward discretionary consumption.
Animal Type:
Species-specific nutritional requirements and ownership demographics partition demand concentration, with companion animal protein needs driving formulation complexity and raw material sourcing strategies.
- Dogs:Omnivorous formulations span grain-inclusive and grain-free positioning, with large-breed and life-stage variants requiring distinct calcium-phosphorus ratios. Urban millennial ownership in Mexico City sustains premiumization across all price tiers.
- Cats:Obligate carnivore biology mandates higher animal protein inclusion and taurine fortification, elevating input costs and SENASICA certificate dependency for poultry meal and fish derivatives.
- Birds:Seed and pellet blends serve avian nutritional requirements with lower regulatory scrutiny than mammalian formulations.
- Fish:Aquatic species feeds occupy specialized distribution through pet shops and hobbyist channels with distinct shelf-life constraints.
Dog nutrition commands the deepest manufacturing investment; cat food formulations are climbing the fastest as protein quality premiums expand.
Distribution Channel:
Channel economics determine customer acquisition costs and switching dynamics, with regulatory compliance obligations fragmenting across traditional retail, professional veterinary, and direct-to-consumer pathways.
- Retail Stores:Mass-market supermarkets and hypermarkets provide volume throughput for economy and mid-range tiers, with slotting fee competition intensifying in concentrated metropolitan markets.
- E-commerce:Direct-to-consumer platforms bypass traditional gatekeepers, enabling subscription models and personalized nutrition portfolios while multiplying state-level tax and sanitary registration burdens.
- Veterinary Clinics:Prescription diet partnerships capture recurring revenue streams and build switching costs through professional recommendation authority.
- Pet Shops:Specialty retailers serve enthusiast segments with premium positioning and species-specific expertise.
Retail Stores retain volume dominance; E-commerce channels are gaining share fastest as fulfillment infrastructure matures.
Price Tier:
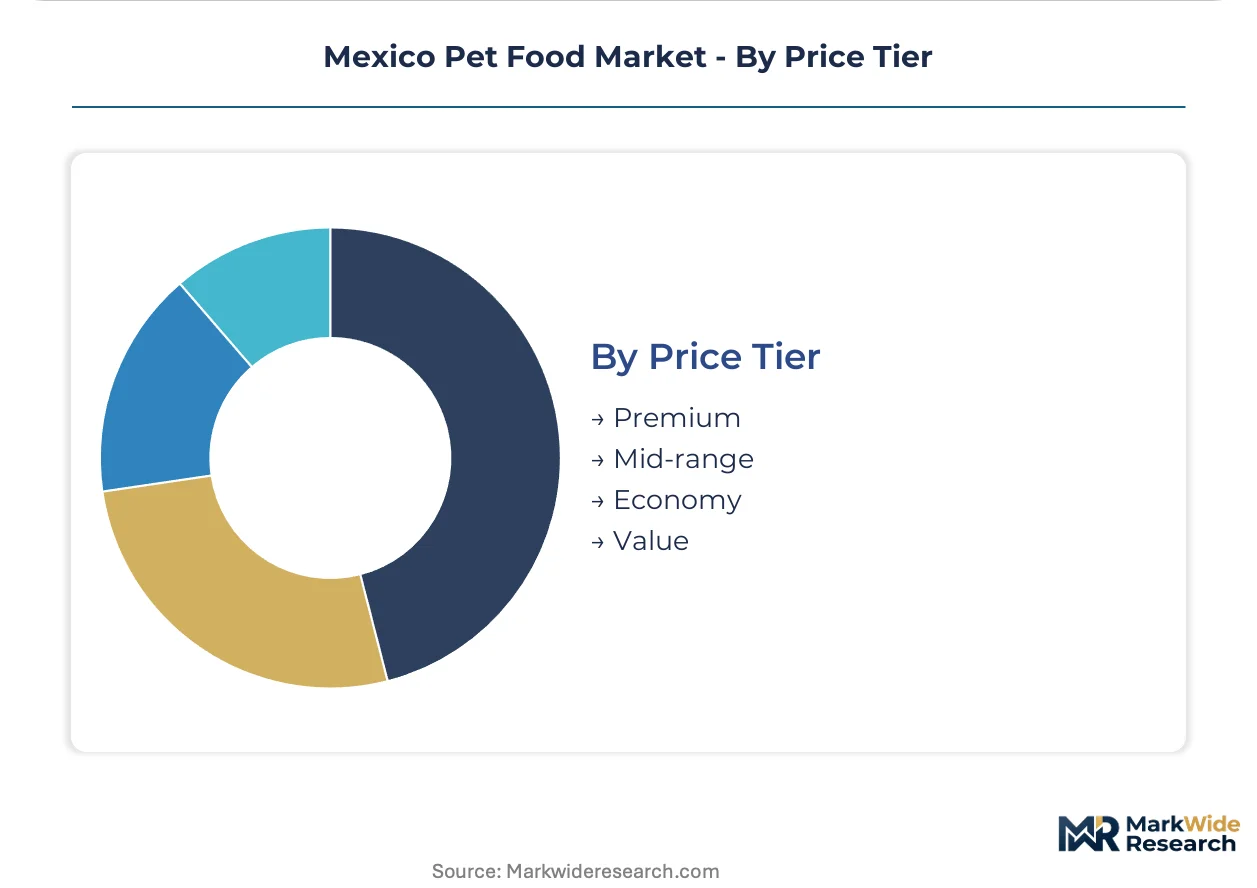
Raw material provenance, manufacturing process sophistication, and certification status stratify pricing architecture across four distinct quality-positioned bands.
- Premium:Cold-pressed extrusion, human-grade ingredient claims, and COFEPRIS traceability documentation support elevated positioning in Mexico City and Guadalajara.
- Mid-range:Standard extrusion with regionally sourced proteins balances quality perception and accessibility for metropolitan middle-income households.
- Economy:Commodity grain and rendered protein formulations serve price-sensitive volume demand through traditional retail.
- Value:Entry-positioned offerings compete on absolute price point with minimal formulation differentiation.
Economy tier absorbs mass-market volume; Premium positioning shows the steepest expansion trajectory as urban millennial spending power concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jalisco's grain belt and Querétaro's livestock corridors anchor Mexico's pet food manufacturing geography, supplying the maize, sorghum, and rendered proteins that feed extrusion lines across the central highlands.
Mexico City Metropolitan Area
Urban millennial pet ownership concentrates demand for veterinary-prescribed therapeutic diets and grain-free formulations. COFEPRIS NOM-012-ZOO-1993 enforcement elevates compliance costs for informal producers, accelerating formal channel consolidation. Veterinary clinics in Polanco and Santa Fe displace mass retail as the primary education channel for premium nutrition.
Nuevo León
Monterrey's affluent districts sustain premium wet food positioning despite elevated logistics costs from higher moisture content. SAGARPA rural development programs channel livestock subsidies into regional poultry meal supply chains. San Pedro Garza García hosts the densest cluster of prescription diet fulfillment through clinic-affiliated e-commerce portals.
Jalisco
Domestic extrusion and canning capacity expansion severs historical import dependency for dry food production. SENASICA-monitored sanitary certificates for animal-origin inputs force reformulation strategies among local processors. Guadalajara's manufacturing corridor absorbs the majority of new production line investments from multinational and domestic producers.
Bajío Region
Querétaro's central location reduces logistics costs for national distribution networks serving secondary metropolitan markets. Grain subsidy programs through SAGARPA lower raw material acquisition costs for mid-range formulation tiers. Industrial parks in El Marqués host co-manufacturing facilities serving private label and regional brand portfolios.
Northern Border States
Cross-border supply chain integration exposes formulators to SENASICA import certificate volatility for U.S.-sourced poultry meal and fish derivatives. Chihuahua and Nuevo León distribution hubs face heightened price competition from informal gray-market imports. Cold-pressed extrusion adoption lags national averages due to capital constraints among smaller regional players.
Mexico Pet Food Market Competitive Environment
Global majors compete with regional champions across manufacturing scale and veterinary channel access, producing a tiered structure where multinational portfolios dominate premium positioning while domestic specialists capture mid-range volume. Three archetypes define competitive positioning: integrated multinationals with captive production complexes, regional grain processors leveraging agricultural supply chain proximity, and veterinary-focused specialists building prescription diet recurring revenue. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with producers securing SENASICA-compliant raw material sourcing and clinic distribution networks.
Within the integrated multinational tier, Mars, Incorporated and Nestlé Purina exemplify scale-driven positioning through production complex ownership and veterinary channel partnerships. Grupo Sesajal occupies the regional specialist archetype, leveraging Jalisco agricultural supply chain integration for grain-free formulation differentiation. Colgate-Palmolive Company (Hill's Pet Nutrition) represents the veterinary-prescribed segment through clinic-centric distribution and therapeutic diet specialization.
| Leading Market Players |
|---|
| Colgate-Palmolive Company (Hill's Pet Nutrition) |
| General Mills |
| Mars, Incorporated |
| Affinity Petcare SA |
| Grupo Sesajal |
| Nestlé Purina |
| Schell & Kampeter, Inc. (Diamond Pet Foods) |
| Dechra Pharmaceuticals PLC |
| ADM |
| Others |
Value Chain & Pricing Dynamics
COFEPRIS traceability mandates under revised NOM-012 protocols gate both qualified supply and premium-tier pricing access, disqualifying informal protein suppliers while elevating documentation costs that manufacturers recover through cold-pressed extrusion and human-grade ingredient premiums.
Pricing Analysis
Veterinary consultation fees bundled with prescription diet fulfillment compress price transparency while unbundled e-commerce replenishment exposes sticker shock. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and moisture content, with cold-pressed dry formats commanding the widest spreads. Cost compression in economy tiers is intensifying because metropolitan retail slotting fee competition absorbs margin. Price-sensitive volume buyers in traditional retail contrast with clinic-channel subscribers who accept recurring premium outlays for therapeutic compliance.
Supply Chain Analysis
Direct-to-veterinary channels handle prescription diet demand while mass retail and e-commerce platforms split replenishment volume. Jalisco grain belts and Querétaro livestock corridors anchor domestic production, with SENASICA-monitored poultry meal and fish derivatives drawing from U.S. and Canadian rendering facilities. Single-source vulnerability concentrates in imported animal protein certificates subject to sanitary hold disruptions. Distribution runs through captive production complexes in Puebla and co-manufacturing parks in El Marqués.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Domestic extrusion capacity expansion lags demand acceleration, propping pricing power for SENASICA-compliant producers who secured canning line investments ahead of NOM revision enforcement.
For Market Incumbents: Lock in veterinary channel exclusivity through clinic-affiliated e-commerce portal integration before subscription models mature. Deepen backward integration into Jalisco grain supply chains to buffer SAGARPA subsidy volatility and deny cost advantages to emerging competitors. For New Entrants and Emerging Players: Capture white-space in freeze-dried treat segments where humanization trends outpace incumbent R&D cycles. Target secondary metropolitan corridors beyond Mexico City-Guadalajara-Monterrey concentration where slotting fee barriers moderate and local pet shop relationships yield faster trial conversion. For Investors and Strategic Acquirers: SENASICA certificate backlogs clearing for regional processors is the leading indicator that mid-tier consolidation will accelerate. Five-to-ten year viability favors veterinary-focused specialists with recurring revenue streams over commodity extrusion plays exposed to grain price swings. Watch for COFEPRIS enforcement intensity in informal retail channels as the signal for formal channel premiumization velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Pressed Extrusion Scale-Up | Preserves amino acid integrity for premium positioning against European imports. |
| Veterinary Channel Partnership | Builds switching costs through prescription diet recurring revenue shares. |
| Grain-Free Formulation Development | Differentiates via regionally sourced proteins in Jalisco supply corridors. |
| Direct-to-Consumer Platform Launch | Bypasses retail slotting fees while multiplying state-level registration burdens. |
| SENASICA-Compliant Sourcing Integration | Secures sanitary certificate continuity for animal-origin protein inputs. |
Study Parameters
Document review covered SENASICA sanitary certificate databases, COFEPRIS NOM-012 regulatory filings, and SAGARPA rural development program disclosures, complemented by interviews with pet food plant managers, veterinary clinic procurement leads, retail category buyers, and grain cooperative supply planners. Secondary validation drew from customs import records, extrusion equipment manufacturer order backlogs, and Nielsen retail audit data. Bottom-up capacity installation tracking and top-down metropolitan demand modeling were triangulated against channel shipment estimates.
Segmented outputs across product type, animal species, distribution channel, and price tier were generated over the projection horizon. CAGRs were derived from installed capacity expansion schedules, urban household pet ownership surveys, and veterinary clinic density mapping. Modeled inputs included SENASICA certificate approval velocity, cold-pressed extrusion adoption curves, and e-commerce fulfillment infrastructure buildout.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to NOM revision timing, grain subsidy allocation shifts, and import certificate disruption frequency. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Cat Window Perches and Wall Shelves Market
Pet Care Products
Pet Toys Market
Pet Care Products
Dog Pad Market
Pet Care Products
Dog Perfume Market
Pet Care Products
Pet Noise Anxiety Market
Pet Care Products
Small Breed Dog Food Market
Pet Care Products
Pet Food Market
Pet Care Products
South America Pet Diet Market
Pet Care Products
United Kingdom Pet Food Market
Pet Care Products
Pet Tick and Flea Prevention Market
Pet Care Products
Pet Bathing Supplies Market
Pet Care Products
Pet Pee Pads Market
Pet Care Products
North America Pet Treats Market
Pet Care Products
Pet Grooming Products Market
Pet Care Products
Dog Clippers Market
Pet Care Products
Pet Shampoo Market