
 Natural Pet Food Market | 2026-2036
Natural Pet Food Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Pet Food Market Outlook
Single-serve pouch configurations are realigning how owners portion fresh meals at home. Mars Petcare leverages its refrigerated supply chain to dominate this format across North American retail. WellPet LLC anchors its competitive position through specialized grain-free and limited-ingredient recipes. Diamond Pet Foods sustains manufacturing scale advantages in dry kibble production for private-label and branded channels.
Natural pet food comprises formulations free from artificial preservatives, colors, and flavors, typically manufactured through extrusion, retorting, or cold-pressing methods to preserve nutrient bioavailability. The primary commercial purpose centers on delivering species-appropriate nutrition that mirrors ancestral feeding patterns while meeting AAFCO nutrient profiles. Dry food occupies the largest volume share due to shelf stability and cost efficiency, though raw and refrigerated wet formats command premium margin pools. Grain-free positioning under ingredient source segmentation continues to attract allergy-conscious buyers despite ongoing FDA investigation into dilated cardiomyopathy correlations.
USDA National Organic Program standards govern organic claims, while FDA Center for Veterinary Medicine oversees ingredient safety and facility inspections across domestic production. State-level feed control officials in California, Texas, and New York enforce additional labeling requirements that create compliance complexity for interstate distribution. Stakeholders must monitor evolving regulatory positions on novel proteins and cultivated meat ingredients as these technologies mature toward commercial scale.
Market Dynamics
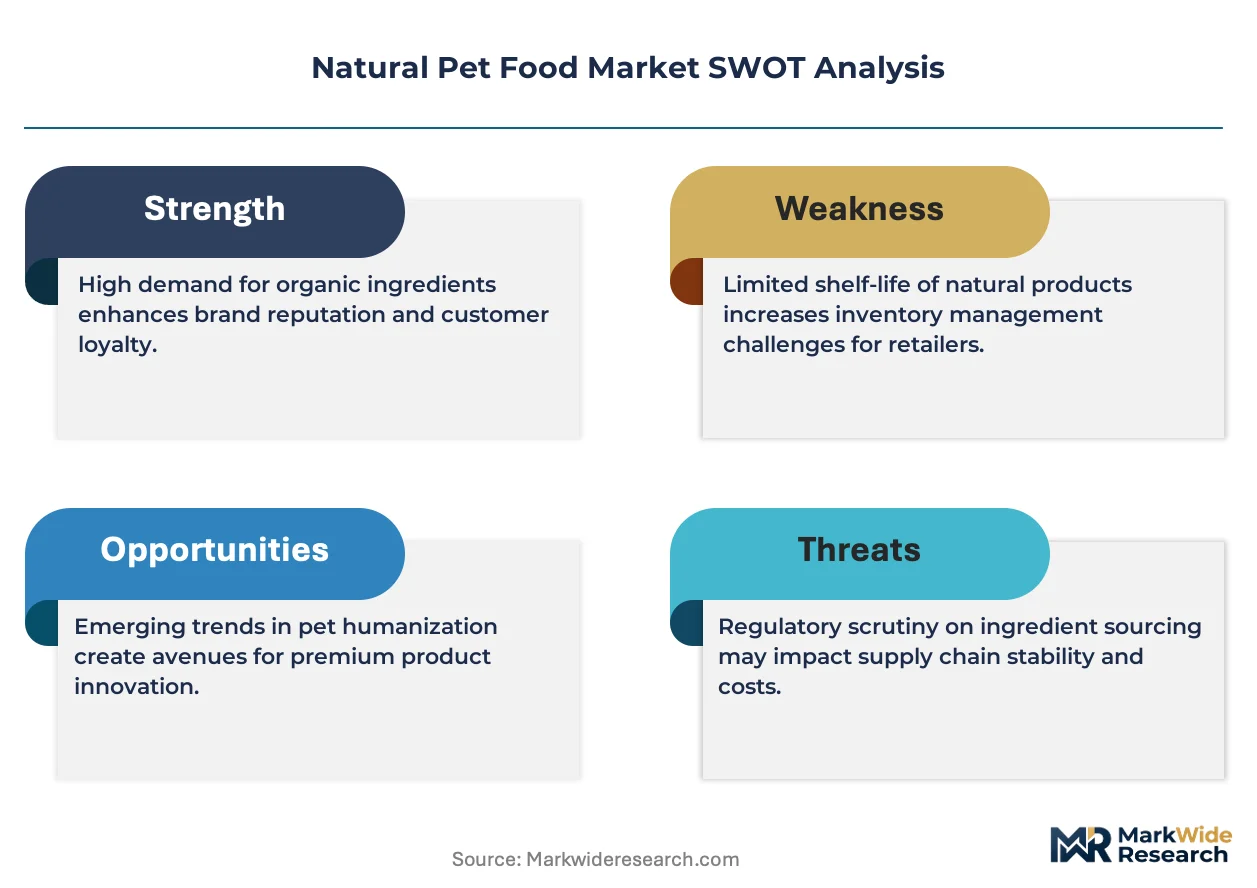
Clean-label ingredient transparency requirements are compressing formulation timelines and forcing manufacturers to revalidate supplier networks against evolving certification standards.
Growth Catalysts
- USDA Organic Certification:Federal standards for organic pet food claims create definitional clarity that reduces consumer confusion and supports premium pricing architecture.
- Gen Z Pet Ownership Patterns:Younger cohorts treat companion animals as family members, translating human dietary preferences directly into pet food purchasing criteria.
- Cold-Pressed Processing:Low-temperature manufacturing preserves enzyme activity and nutrient density, enabling brands to substantiate bioavailability claims with measurable metrics.
Market Restraints
- Novel Protein Input Volatility:Insect and cultivated meat ingredient supplies remain constrained by limited commercial-scale production facilities and inconsistent cold-chain infrastructure.
- State-Level Labeling Fragmentation:California, Texas, and New York maintain divergent feed control regulations that multiply compliance costs for interstate distribution.
- Grain-Free Formulation Scrutiny:Ongoing FDA investigation into dilated cardiomyopathy correlations has chilled retailer willingness to expand shelf space for legume-heavy recipes.
Strategic Opportunities
- Japanese Premium Channel Expansion:Urban pet density in Tokyo and Osaka supports subscription-based fresh meal delivery models with household penetration rates below comparable US metros.
- Veterinary Prescription Integration:Therapeutic natural formulations positioned through clinic channels capture recurring revenue streams with higher switching costs than retail.
- Retort Pouch Technology Convergence:Combining barrier film advances with high-pressure processing extends ambient-stable wet food shelf life without synthetic preservatives.
Industry Challenges
- AAFCO Nutrient Profile Compliance:Balancing ancestral feeding narrative claims against standardized nutritional adequacy testing creates formulation iteration cycles that extend product development timelines.
- Refrigerated Last-Mile Infrastructure:Fresh and raw format expansion requires temperature-controlled logistics investments that strain capital allocation for mid-scale manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Pet Food Market |
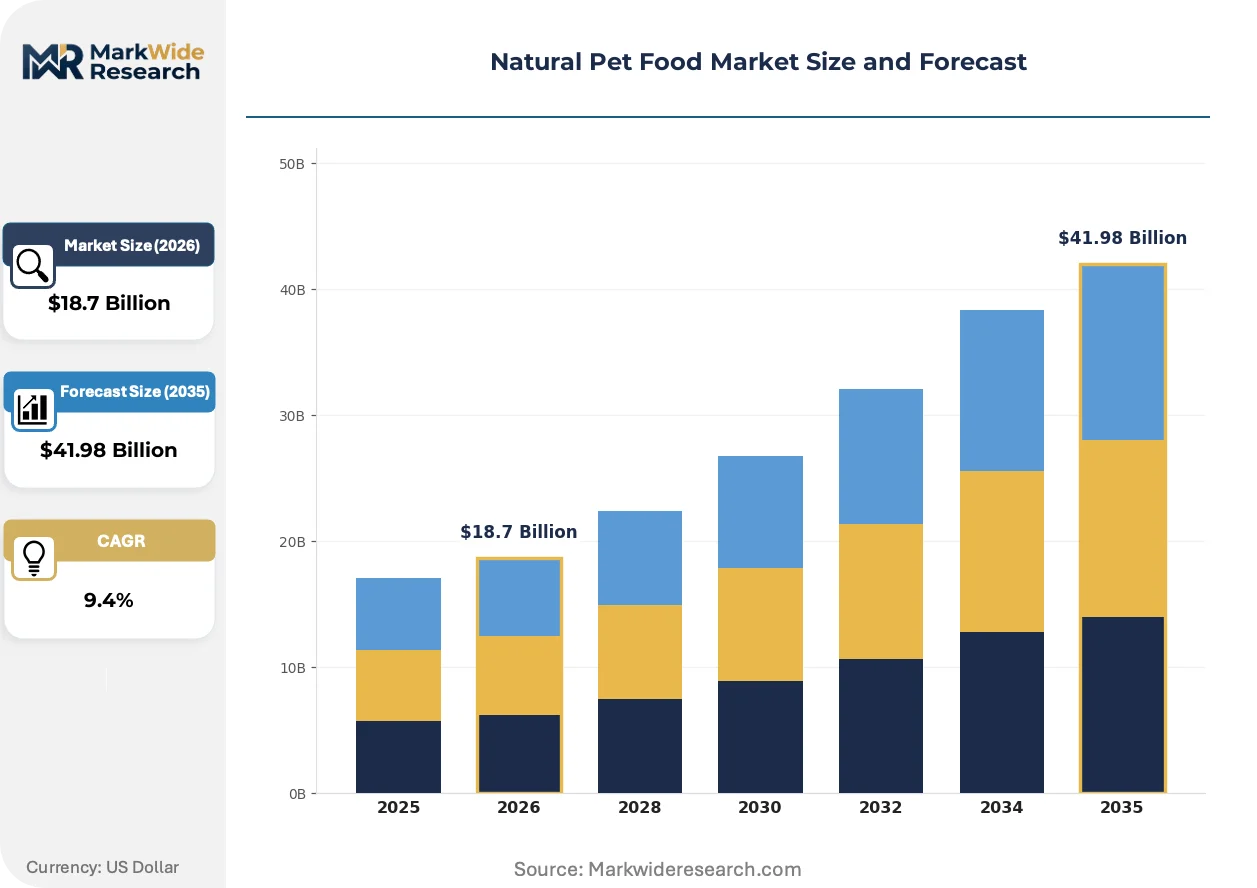
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Supplements Ingredient Source: Organic, Grain-Free, Raw, Non-GMO Pet Type: Dogs, Cats, Birds, Small Animals Packaging Type: Bags, Cans, Pouches, Tubs |
| Companies Covered | Blue Buffalo, WellPet LLC, Diamond Pet Foods, Nestlé Purina PetCare, Mars Petcare, General Mills, J.M. Smucker, Hill's Pet Nutrition, Nutro Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Pet Food Market Strategic Shifts
Processing technology advances and regulatory clarity initiatives are simultaneously expanding format possibilities while compressing the window for unsubstantiated marketing claims.
High-pressure processing (HPP) is automating pathogen reduction in raw pet food manufacturing without thermal degradation of heat-sensitive vitamins and enzymes. Premium raw brands in the United States and Germany are adopting HPP lines at accelerating rates to satisfy retailer food safety requirements. This automation is compressing the competitive advantage window between validated-safe raw products and conventional retorted wet formats.
The FDA Center for Veterinary Medicine's evolving position on novel protein safety substantiation is forcing ingredient suppliers to generate species-specific digestibility data prior to commercial launch. This regulatory trajectory elevates capital requirements for new entrant protein sources while advantaging established suppliers with existing toxicology dossiers. Wet food and treat categories containing unconventional proteins face the steepest compliance trajectory.
Subscription direct-to-consumer replenishment is displacing periodic bulk purchasing among urban millennial pet owners. Specialty e-commerce platforms capture recurring revenue with customized portion algorithms that reduce household food waste. This behavioral shift concentrates most visibly in dense metropolitan areas of the United States and Germany where delivery logistics economics favor frequent small-batch shipments.
Natural Pet Food Market Segmentation
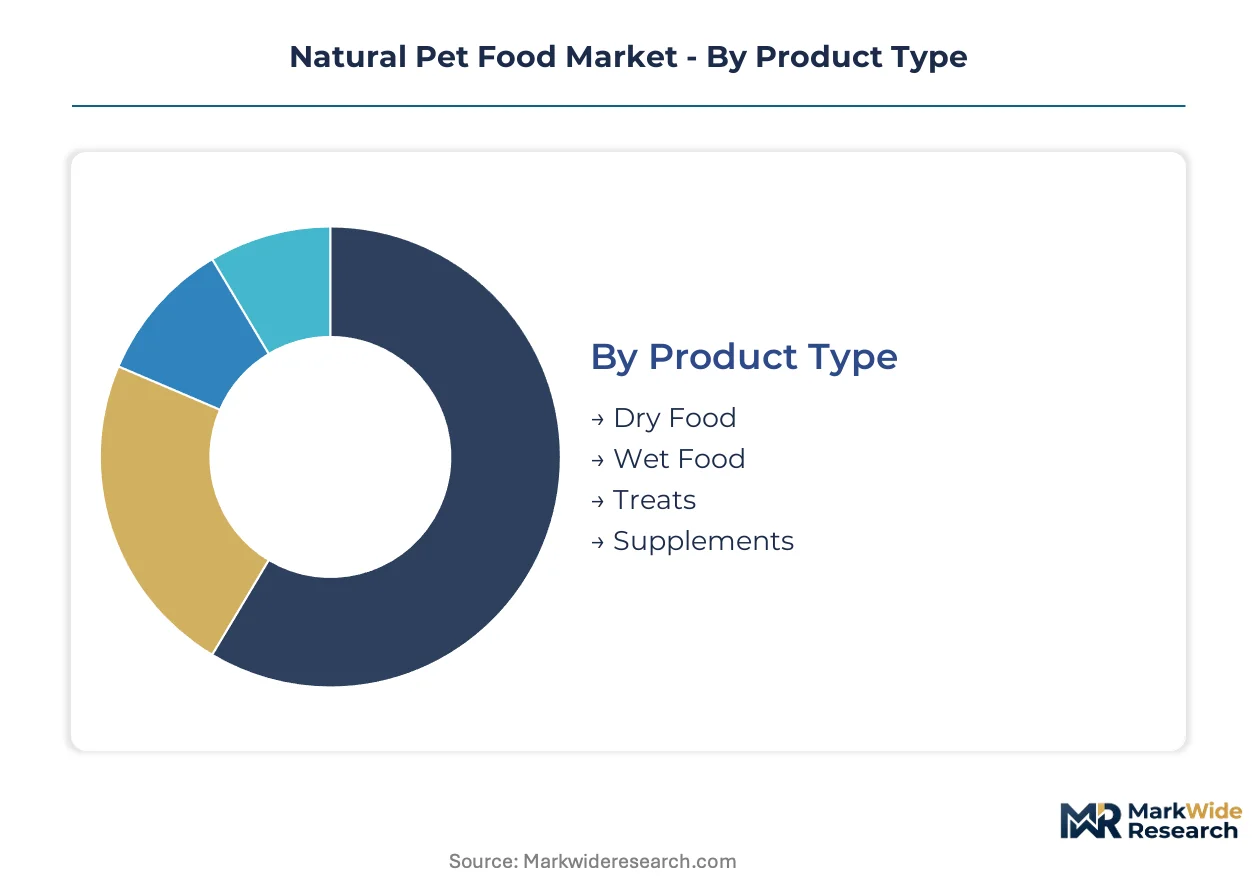
Segmentation in natural pet food reveals how processing technology, ingredient sourcing, and species-specific nutrition create distinct margin pools. Manufacturers configure supply chains differently across these dimensions, with refrigerated formats demanding entirely different distribution infrastructure than shelf-stable alternatives.
Product Type:
The customization-vs-standardization spectrum runs from mass-produced dry extrusion to small-batch raw formulations requiring HPP validation.
- Dry Food:Extruded kibble dominates manufacturing scale with shelf-stable convenience and cost efficiency. Demand concentrates in suburban United States households prioritizing bulk purchasing and extended storage. Cold-pressed variants command 40-60% price premiums by preserving enzyme activity through sub-45°C processing.
- Wet Food:Retorted cans and ambient-stable pouches deliver higher moisture content aligned with ancestral feeding patterns. Growth clusters in urban Germany and Japan where apartment-dwelling pet owners favor portion-controlled freshness. High-pressure processing lines are automating pathogen reduction without thermal vitamin degradation.
- Treats:Functional reward formats with limited-ingredient positioning address allergy-sensitive companion animals.
- Supplements:Targeted nutrient add-ons support joint, digestive, and coat health in aging pet populations.
Leading the category by volume: Dry Food. Growing fastest: Wet Food.
Ingredient Source:
Cost tier stratification separates certified organic supply chains from conventional natural positioning.
- Organic:USDA National Organic Program certification requires 95% organic ingredients and restricts synthetic additives. Demand concentrates in affluent coastal United States markets where consumers extend personal clean-label preferences to companion animal nutrition. Premium pricing architecture supports 25-35% retail markups over conventional natural.
- Grain-Free:Legume and pulse-based formulations target allergy-conscious buyers despite FDA dilated cardiomyopathy investigations. Retailer shelf space expansion has chilled pending regulatory clarity, with volume concentrating in veterinary-channel therapeutic positioning.
- Raw:Unprocessed muscle meat, organ, and bone formulations require frozen or refrigerated distribution.
- Non-GMO:Identity-preserved ingredient sourcing appeals to buyers seeking transparency without full organic certification cost.
Expanding most quickly: Organic. Maintaining volume leadership: Grain-Free.
Pet Type:
Application-specific formulation requirements drive species-appropriate nutrient density and palatability engineering.
- Dogs:Omnivore-adapted formulations span kibble, wet, and raw formats with breed-size portion customization. Demand concentrates in United States single-family households where humanization trends translate to fresh meal subscription services. Therapeutic weight management and senior formulations capture recurring veterinary-channel revenue.
- Cats:Obligate carnivore nutrition demands higher protein and taurine minimums with minimal carbohydrate tolerance. Growth concentrates in Japanese urban apartments where feline ownership exceeds canine due to space constraints. Wet and raw formats align with moisture requirements for urinary tract health.
- Birds:Species-specific seed, pellet, and fresh food combinations address psittacine nutritional complexity.
- Small Animals:Rabbit, guinea pig, and hamster formulations emphasize hay-based fiber and controlled calorie density.
Highest volume concentration: Dogs. Steepest expansion trajectory: Cats.
Packaging Type:
Supply concentration in barrier film technology and metal can manufacturing shapes regional competitive dynamics.
- Bags:Multi-layer flexible packaging dominates dry food with oxygen and moisture barrier properties. United States Midwest production clusters leverage resin supply proximity for cost-efficient extrusion.
- Cans:Steel and aluminum retort containers preserve wet food sterility through thermal processing. Manufacturing concentrates in legacy food canning regions with established coating and seaming expertise.
- Pouches:Retortable and refrigerated barrier films enable single-serve convenience and portion precision. Tokyo and Osaka subscription services drive premium adoption for fresh meal delivery.
- Tubs:Refrigerated polyethylene containers support raw and fresh formats requiring cold-chain integrity.
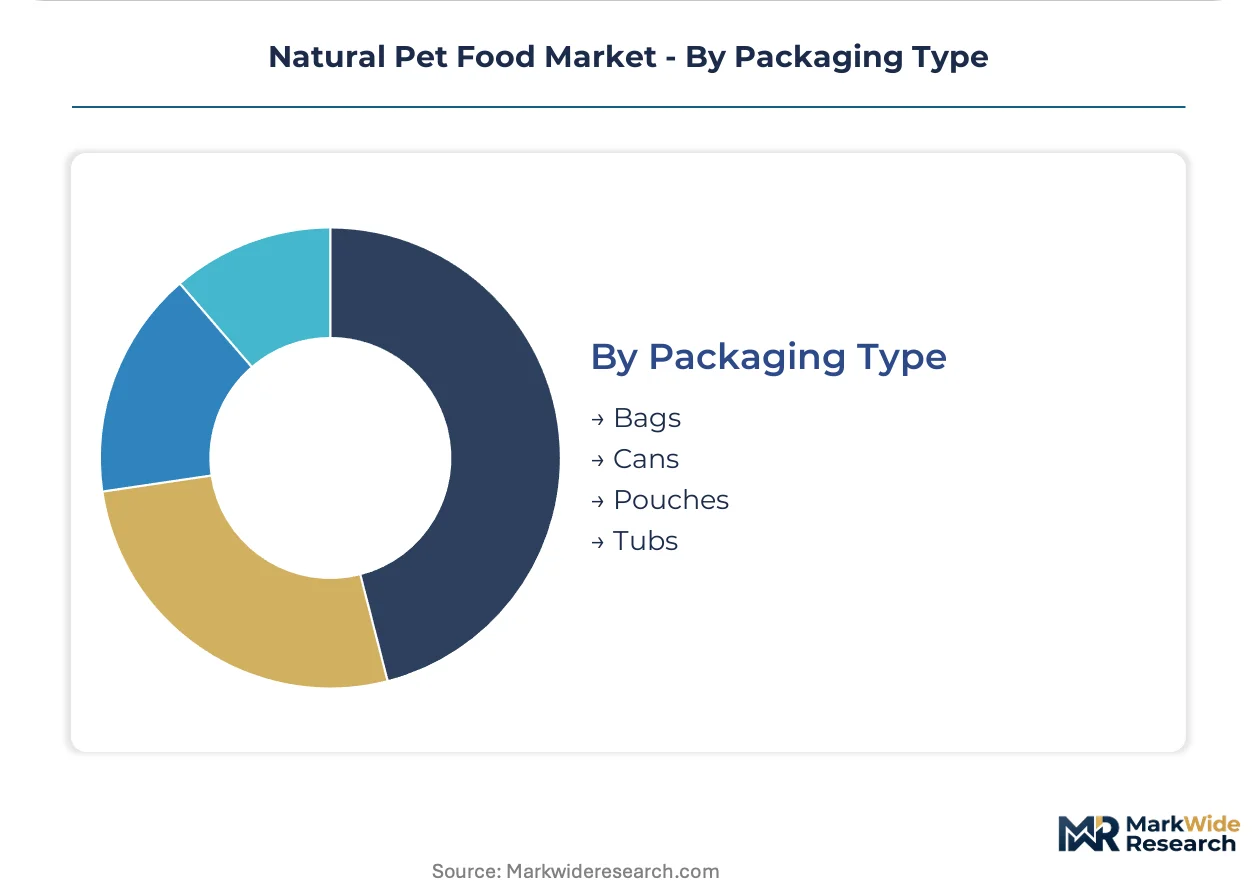
Volume leadership: Bags. Fastest-growing format: Pouches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing scale concentrates in the United States while consumption patterns fragment across mature pet-owning economies with divergent regulatory postures toward ingredient transparency and novel protein authorization.
United States
Millennial and Gen Z pet owners in coastal metropolitan areas drive subscription-based fresh meal adoption. The FDA Center for Veterinary Medicine enforces ingredient safety standards and facility inspections across domestic production. Mars Petcare leverages refrigerated supply chain infrastructure in the Midwest to dominate single-serve pouch distribution through North American retail channels.
Germany
Urban apartment dwellers in Berlin and Munich favor portion-controlled wet food formats aligned with ancestral feeding narratives. EFSA guidelines on novel protein safety substantiation shape ingredient approval timelines for insect and cultivated meat suppliers. Cold-pressed processing equipment manufacturers cluster in Bavaria, supplying brands across the European premium segment with sub-45°C nutrient preservation technology.
Japan
Feline ownership exceeds canine in Tokyo and Osaka due to space constraints, concentrating demand for moisture-rich wet and raw formats. METI standards govern functional pet food claims and substantiation requirements for therapeutic positioning. Subscription fresh meal delivery services in the Kanto region report household penetration rates below comparable US metros, indicating expansion runway.
United Kingdom
Allergy-conscious buyers in London and Southeast England sustain demand for limited-ingredient and grain-free formulations despite ongoing regulatory scrutiny. FSA feed hygiene regulations enforce cold-chain integrity requirements for raw and refrigerated distribution. Specialist retailers in the Midlands source cold-pressed dry variants from regional manufacturers serving the premium natural segment.
Canada
Health Canada and the Canadian Food Inspection Agency coordinate oversight of imported natural pet food ingredients and labeling compliance. Toronto and Vancouver metropolitan areas mirror US coastal demand patterns for organic-certified and subscription-delivered fresh formats. Quebec-based manufacturers supply private-label natural positioning to retailers across North American border markets.
Natural Pet Food Market Competitive Environment
The competitive structure tilts toward diversified consumer packaged goods conglomerates with captive pet care divisions. Tiered concentration separates multinational scale players from mid-cap specialists and regional private-label suppliers. Two archetypes dominate: refrigerated supply chain integrators and formulation specialists with veterinary-channel access. Capacity expansion in high-pressure processing lines and strategic partnerships with novel protein suppliers constitute the primary competitive moves reshaping positioning.
Within the diversified conglomerate tier, Mars Petcare and Nestlé Purina PetCare occupy positions defined by scale advantages in manufacturing and distribution infrastructure. WellPet LLC exemplifies the mid-cap specialist archetype, anchoring competitive positioning through focused recipe development in grain-free and limited-ingredient categories. Blue Buffalo represents the premium-tier independent brand that diversified food companies have targeted for portfolio expansion into natural positioning.
| Leading Market Players |
|---|
| Blue Buffalo |
| WellPet LLC |
| Diamond Pet Foods |
| Nestlé Purina PetCare |
| Mars Petcare |
| General Mills |
| J.M. Smucker |
| Hill's Pet Nutrition |
| Nutro Products |
| Others |
Value Chain & Pricing Dynamics
Captive refrigerated distribution networks anchor both supply positioning and pricing power for premium-format manufacturers. Mars Petcare's Midwest cold-chain infrastructure enables single-serve pouch dominance while insulating margin pools from commodity kibble volatility.
Pricing Analysis
Margin tightening in cold-pressed and raw tiers reflects certification validation costs and HPP equipment amortization. Three-tier pricing structure across premium, standard, and economy levels separates USDA organic-certified formulations from conventional natural and private-label positioning. Price differentiation hinges on cold-chain integrity guarantees and AAFCO therapeutic claim substantiation. Urban millennial subscribers show lowest price sensitivity; suburban bulk dry-food buyers concentrate price elasticity.
Supply Chain Analysis
Regional distribution centers in the United States Midwest, Germany's Bavaria corridor, and Japan's Kanto region form hub-and-spoke patterns for temperature-controlled fulfillment. Raw material flows draw from North American organic protein suppliers, European cold-pressed equipment manufacturers, and Asian barrier-film producers. Single-source vulnerability concentrates in novel protein cultivation facilities with limited commercial-scale capacity. Distribution runs through veterinary clinics, specialty e-commerce platforms, and mass retail refrigerated sections.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
High-pressure processing automation is displacing legacy retort sterilization across wet-format manufacturing, compressing pathogen-reduction timelines while preserving nutrient bioavailability claims.
For Market Incumbents: Hedge against novel protein supply volatility through backward integration into insect cultivation or cultivated meat partnerships. Lock in refrigerated last-mile capacity additions in Tokyo and Osaka before subscription-service density saturates. Defensive patent positioning around HPP protocol optimization creates moats against mid-scale raw-format entrants.
For New Entrants and Emerging Players: Cold-pressed dry equipment retrofits offer a technology-first wedge into German and UK premium channels underserved by multinational scale players. Target Japanese feline wet-format subscriptions where household penetration trails US metros. Veterinary prescription integration captures recurring revenue with higher switching costs than retail shelf competition.
For Investors and Strategic Acquirers: Exit pathways concentrate in conglomerate portfolio absorption for mid-cap specialists with captive novel protein supply or HPP-validated safety dossiers. Five-to-ten-year viability favors brands bridging ancestral feeding narratives with AAFCO compliance automation. Watch FDA novel protein safety substantiation timelines as inflection indicator for ingredient supplier valuation resets.
| Strategic Initiative | Industry Significance |
|---|---|
| HPP Line Installation | Automates pathogen reduction without thermal vitamin degradation for raw-format safety validation. |
| Novel Protein Supply Agreement | Secures insect or cultivated meat volumes ahead of FDA species-specific digestibility requirements. |
| Veterinary Channel Partnership | Positions therapeutic natural formulations through clinic dispensing with recurring prescription capture. |
| Subscription Platform Launch | Customizes portion algorithms for urban millennial households reducing food waste and churn. |
| USDA Organic Certification Investment | Supports 25-35% retail markup architecture in affluent coastal United States markets. |
Study Parameters
SEC 10-K filings, FDA Center for Veterinary Medicine enforcement correspondence, and Nielsen retail audit data formed the secondary backbone for volume and pricing calibration. Primary interviews with pet food formulation scientists, veterinary clinic procurement managers, cold-chain logistics directors, and specialty e-commerce platform operators validated demand assumptions. Bottom-up and top-down triangulation reconciled SKU-level velocity data against manufacturer-reported capacity utilization.
Bottom-up modeling aggregated segment-level growth across product type, ingredient source, pet species, and packaging format dimensions. Top-down validation cross-referenced macro pet ownership trends, disposable income elasticity coefficients, and regulatory enforcement intensity indices. CAGRs derived from normalized historical growth rates applied across the projection horizon with adjustment for HPP adoption curves and novel protein commercialization timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA novel protein approval delays or dilated cardiomyopathy regulatory action. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
US Pet Boarding Market
Pet Care Products
Dog Pillow Market
Pet Care Products
Pet Tag Market
Pet Care Products
Canada Pet Training Services Market
Pet Care Products
North America Pet Treats Market
Pet Care Products
Europe Dog Food Market
Pet Care Products
Saudi Arabia Dog Food Market
Pet Care Products
Europe Pet Smart Tracker Market
Pet Care Products
Small Breed Dog Food Market
Pet Care Products
US Pet Daycare Market
Pet Care Products
Pet Oral Care Products Market
Pet Care Products
Cat Mat Market
Pet Care Products
Hair Dryer for Pets Market
Pet Care Products
Netherlands Pet Boarding Market
Pet Care Products
Smart Pet Supply Market
Pet Care Products
Organic Pet Food Market