
 US Pet Boarding Market | 2026-2036
US Pet Boarding Market Size, Share, and Industry Trends Forecast 2026-2036
US Pet Boarding Market Insights
Pet Care Services Certification from the National Association of Professional Pet Sitters is reorganizing competitive access across the US pet boarding landscape. Camp Bow Wow leverages its franchise network to sustain national coverage with standardized facility protocols. Dogtopia Enterprises anchors its position through daycare-centric real estate in suburban retail corridors. PetSmart LLC competes via co-location with retail veterinary clinics inside big-box footprints.
US pet boarding encompasses supervised temporary housing and care for companion animals, typically delivered through climate-controlled kennel runs, group play enclosures, and monitored feeding schedules with documented health observations. The primary commercial purpose is to substitute owner-provided care during travel, illness, or work absences while ensuring animal welfare compliance. Overnight boarding and daycare together capture the dominant share of revenue, though grooming services and training programs attached to extended stays yield the highest margin per animal-day. Standalone kennels and pet hotels lead facility type revenue, while mobile boarding units represent the fastest-expanding format serving rural and exurban markets.
USDA Animal Welfare Act licensing, state-level Department of Agriculture kennel inspections, and local zoning boards collectively govern facility approval, staffing ratios, and sanitation mandates across US jurisdictions. OSHA workplace safety standards and state veterinary practice acts further constrain who may administer medications or perform health assessments on boarded animals. Stakeholders must monitor evolving municipal short-term rental ordinances that increasingly classify residential pet sitting as commercial activity subject to permitting, taxation, and neighbor-notification requirements.
Market Dynamics
Dual-income household density in metropolitan corridors is compressing booking windows and forcing capacity reconfiguration across US pet boarding networks. Operators now face real-time yield management pressure previously unseen in animal care services.
Growth Catalysts
- USDA Animal Welfare Act licensing:Federal inspection standards elevate facility credibility and reduce consumer vetting burden. Premium operators leverage compliance as a market access tool.
- Climate-controlled kennel infrastructure:Temperature and humidity monitoring systems extend serviceable pet demographics to brachycephalic breeds previously excluded from traditional boarding.
- Los Angeles-Dallas-Miami corridor:Concentrated dual-income household formation generates sustained demand for both overnight boarding and daycare slots with limited seasonal fluctuation.
Market Restraints
- Veterinary technician wage inflation:Licensed staffing requirements under state veterinary practice acts compress operating margins in California and Texas markets.
- Commercial real estate concentration:Suburban retail corridor dependence exposes operators to landlord rent escalation and co-tenancy clause restrictions.
- Residential pet sitting substitution:Unlicensed home-based caregivers operating through digital platforms capture price-sensitive demand in exurban zones.
Strategic Opportunities
- Rural and exurban mobile boarding:Veterinary trailer units and converted transport vehicles address geographic service gaps outside metropolitan statistical areas.
- OSHA workplace safety standard integration:Proactive compliance with federal injury prevention mandates reduces insurance premiums and supports staff retention.
- Training program attachment:Behavior modification services bundled with extended stays capture margin expansion unavailable in basic overnight housing.
Industry Challenges
- Pet Care Services Certification timeline:National Association of Professional Pet Sitters credentialing requirements extend staff onboarding periods and constrain rapid facility scaling.
- Kennel run sanitation capex:Epoxy flooring, drainage systems, and HVAC filtration upgrades demand substantial capital deployment for state Department of Agriculture inspection compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Pet Boarding Market |
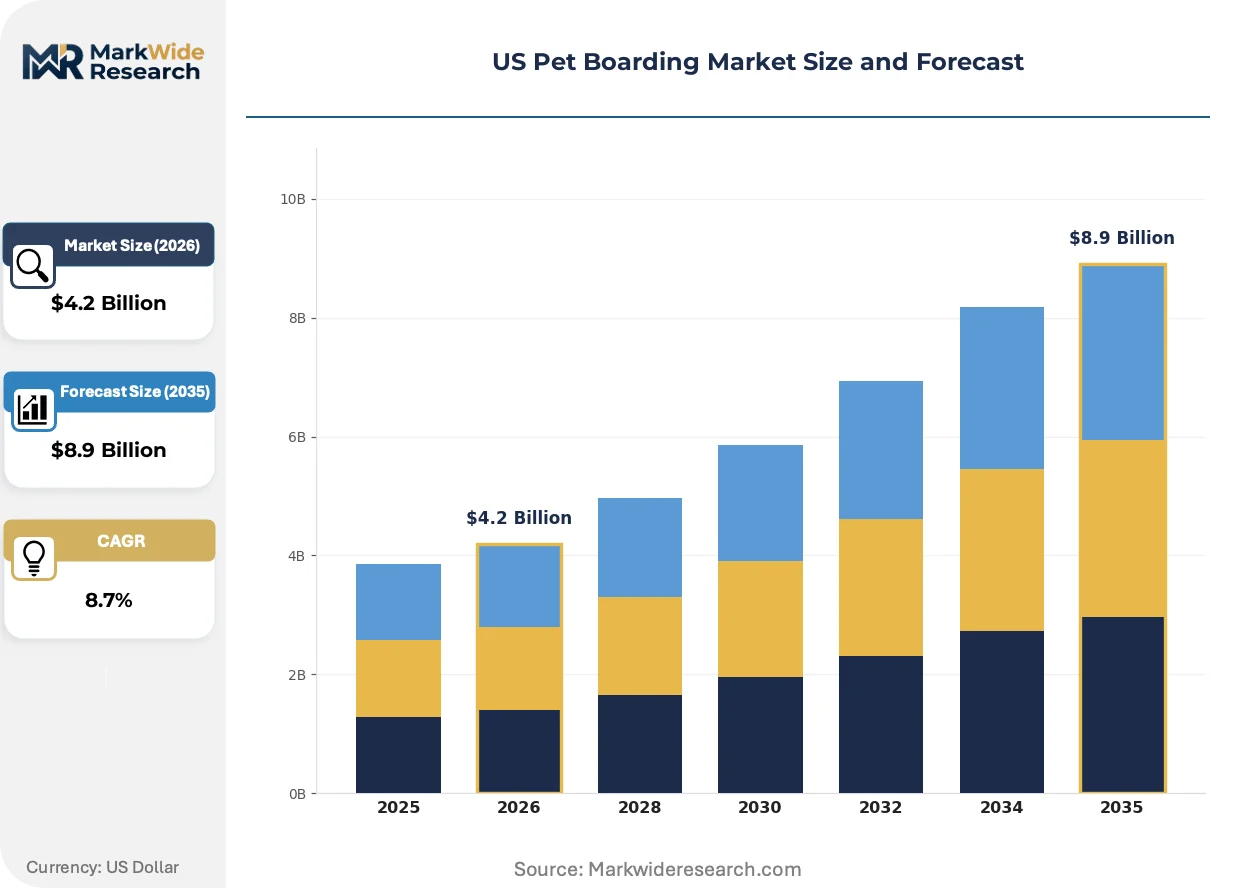
| Market Size in 2026 | $4.2 Billion |
| Market Size in 2035 | $8.9 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Overnight Boarding, Daycare, Grooming Services, Training Programs, Veterinary Care Animal Type: Dogs, Cats, Birds, Small Mammals, Reptiles Facility Type: Standalone Kennels, Veterinary Clinics, Pet Hotels, Mobile Boarding Units, Residential Sitters Customer Type: Individual Pet Owners, Professional Breeders, Animal Shelters, Pet Trainers, Rescue Organizations |
| Companies Covered | Camp Bow Wow, Dogtopia Enterprises, A Place for Rover, Inc., PetSmart LLC, Petco, Best Friends Pet Care, Paradise 4 Paws, LLC, Pet Paradise, The Dog Stop, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Pet Boarding Market Trends and Innovations
Facility automation and real-time pet monitoring systems are compressing labor intensity while elevating owner communication expectations. These shifts reshape competitive positioning around transparency rather than physical amenity scale.
Live-streaming camera networks and wearable activity trackers are miniaturizing owner oversight into continuous digital access. Millennial and Gen-Z pet owners now demand smartphone-based visibility into feeding, play, and rest intervals. This transparency expectation is compressing differentiation between premium and standard service tiers.
California state-level kennel licensing requirements are tightening staffing ratio mandates and sanitation documentation protocols. Facilities must maintain daily health observation logs and veterinary contact protocols. Suburban retail corridor operators face the steepest compliance cost escalation.
Subscription-based daycare memberships are displacing per-visit booking for routine weekday care. Urban dual-income households prefer fixed monthly billing with guaranteed slot availability. This pattern concentrates revenue predictability in metropolitan Texas and Florida markets.
US Pet Boarding Market Segmentation
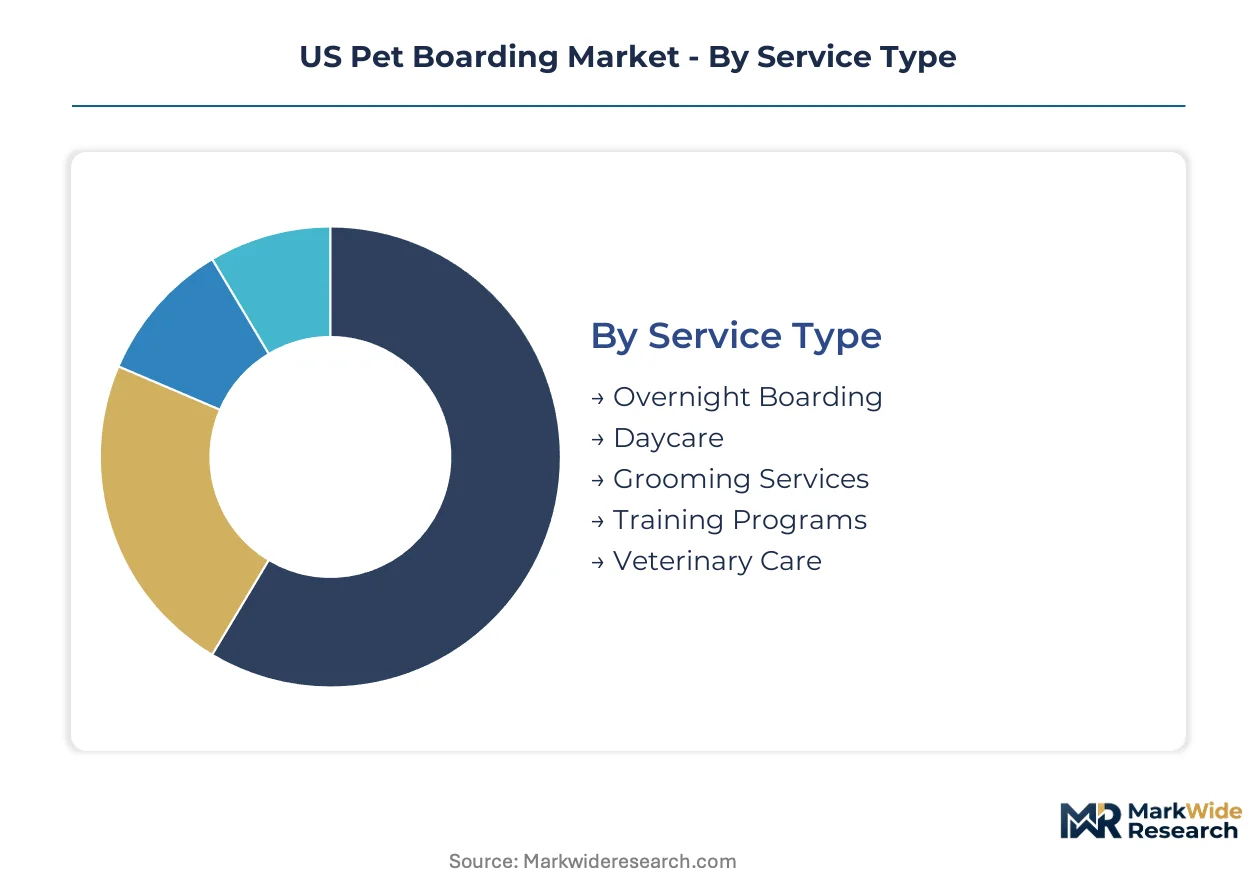
Segmentation in the US pet boarding market reveals how service configuration, animal demographics, and facility economics fragment revenue capture across distinct operational models. Understanding these divides clarifies where capital deployment and compliance investment yield differential returns.
Service Type:
Domestic demand concentrates in overnight and daycare services serving metropolitan dual-income households, while grooming and training attachments expand margin per animal-day across all geographies.
- Overnight Boarding:Climate-controlled kennel runs with documented health observation logs constitute the core revenue foundation. Los Angeles and Dallas-Fort Worth corridors generate sustained demand from travel-dependent professionals seeking USDA Animal Welfare Act-compliant facilities.
- Daycare:Supervised group play enclosures with real-time camera access address compressed booking windows from suburban retail corridor workers. Subscription memberships are displacing per-visit billing in Texas and Florida metropolitan zones.
- Grooming Services:Coat maintenance and hygiene procedures bundled with extended stays yield premium pricing.
- Training Programs:Behavior modification protocols attached to boarding durations capture margin expansion unavailable in basic housing.
- Veterinary Care:Medication administration and health assessments performed under state veterinary practice act supervision.
Overnight boarding commands the established base. The steepest expansion runs through daycare subscription models.
Animal Type:
Cost tier stratification separates high-touch canine services from lower-labor small mammal and reptile accommodations, with brachycephalic breeds now serviceable through climate-controlled infrastructure upgrades.
- Dogs:Group play protocols and individualized exercise schedules dominate facility design and staffing ratios. California kennel licensing mandates tighten health documentation requirements for canine populations.
- Cats:Separate feline housing with vertical enrichment and reduced noise exposure addresses stress-sensitive demographics. Miami corridor facilities report expanding cattery investments.
- Birds:Specialized aviary environments with humidity control and social grouping for psittacine species.
- Small Mammals:Compact housing units for rabbits, guinea pigs, and ferrets with species-specific dietary protocols.
- Reptiles:Temperature-gradient enclosures with UV lighting and humidity management for herpetological collections.
Canine services anchor revenue concentration. Feline accommodations are gaining share fastest in coastal metropolitan markets.
Facility Type:
Volume throughput varies dramatically: standalone kennels and pet hotels maximize animal-days per square foot, while mobile units address geographic coverage gaps without real estate concentration risk.
- Standalone Kennels:Purpose-built structures with epoxy flooring, drainage systems, and HVAC filtration meeting state Department of Agriculture inspection standards. Suburban retail corridor locations face rent escalation pressure.
- Veterinary Clinics:Co-located boarding with immediate medical escalation capability and licensed technician staffing. PetSmart LLC leverages this format inside big-box footprints.
- Pet Hotels:Premium amenity configurations with private suites and expanded play services.
- Mobile Boarding Units:Veterinary trailer and converted transport vehicle formats serving rural and exurban markets outside metropolitan statistical areas.
- Residential Sitters:Home-based care subject to municipal short-term rental ordinances classifying pet sitting as commercial activity.
Standalone kennels retain the volume base. Mobile boarding units are climbing the fastest as rural coverage gaps attract capital.
Customer Type:
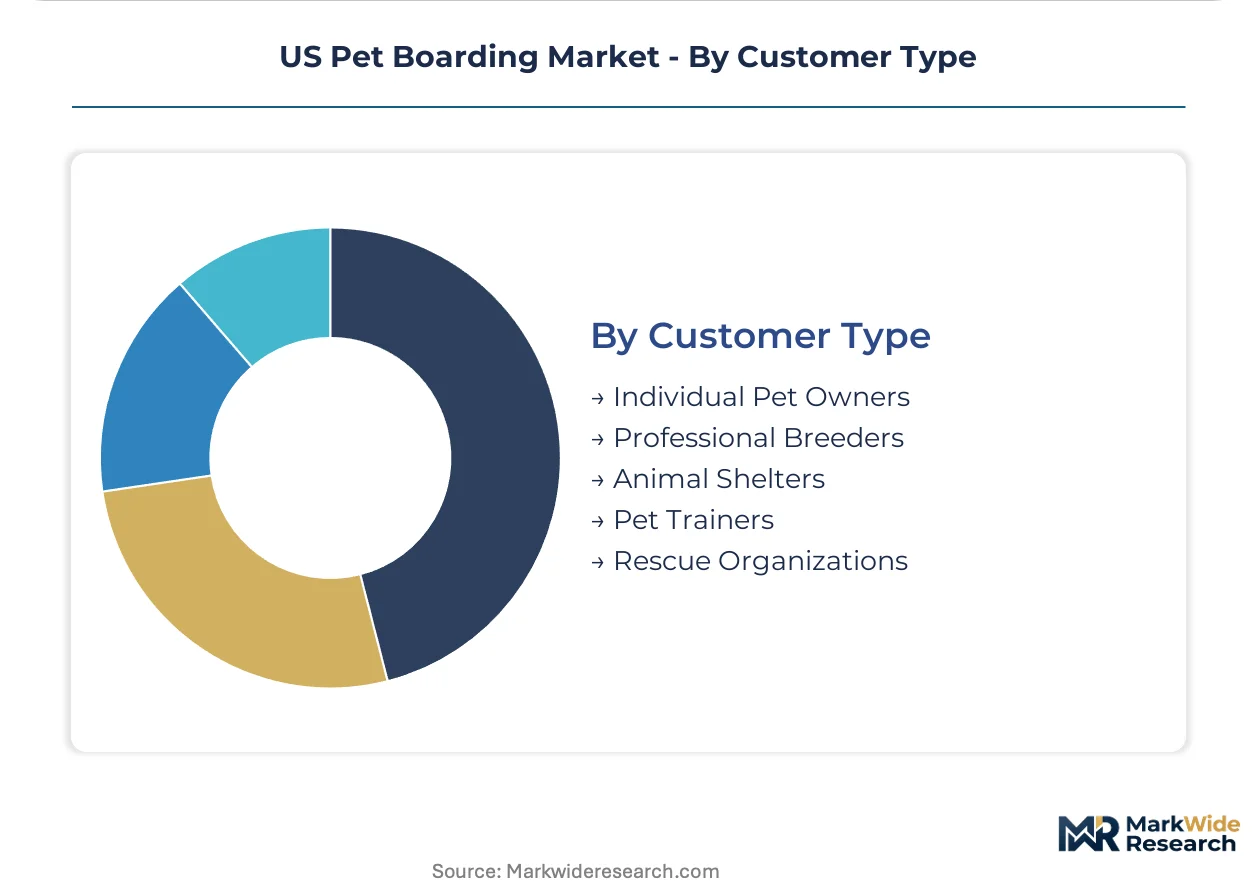
Customer maturity separates routine individual demand from institutional volume contracts, with rescue organizations and shelters presenting counter-cyclical booking patterns during economic stress.
- Individual Pet Owners:Millennial and Gen-Z demographics treating animals as family members drive premium service tier demand. Smartphone-based visibility into feeding and play intervals is now baseline expectation.
- Professional Breeders:Volume boarding during whelping and show circuits with specialized neonatal care requirements.
- Animal Shelters:Temporary overflow housing and quarantine protocols for municipal facilities.
- Pet Trainers:Extended-stay behavior modification programs with dedicated training space access.
- Rescue Organizations:Emergency placement and transport staging for nonprofit animal welfare operations.
Individual owners dominate revenue contribution. Rescue organizations are expanding most quickly as municipal shelter capacity constraints deepen.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Interstate 95 corridor and transcontinental rail links anchor pet boarding density along coastal population centers, while regional airport hubs concentrate premium pet hotel development in major metropolitan zones.
California
Los Angeles and San Francisco metropolitan corridors generate sustained demand from entertainment industry professionals with irregular travel schedules. State Department of Agriculture kennel licensing mandates tighten staffing ratios and sanitation documentation protocols. San Diego facilities report expanding climate-controlled infrastructure investments to accommodate brachycephalic breeds previously excluded from traditional boarding.
Texas
Dallas-Fort Worth and Houston dual-income household formation drives subscription-based daycare membership adoption over per-visit billing. State veterinary practice acts constrain medication administration authority to licensed technicians. Austin corridor operators face veterinary technician wage inflation compressing operating margins.
Florida
Miami and Tampa metropolitan zones concentrate demand from seasonal residents and cruise-dependent travelers seeking reliable pet care. Local zoning boards enforce commercial activity classification for residential pet sitting operations. Orlando facilities report expanding cattery investments addressing stress-sensitive feline demographics.
New York Metro
Manhattan and Brooklyn pet owners drive premium pet hotel development with private suite configurations. Municipal short-term rental ordinances increasingly subject residential pet sitting to permitting and taxation requirements. Long Island operators face real estate concentration risk from suburban retail corridor landlord rent escalation.
Illinois
Chicago metropolitan demand concentrates in daycare services for downtown commuter households. State-level animal welfare ordinances govern facility approval and health observation documentation. Suburban collar county operators report mobile boarding unit deployment addressing exurban geographic coverage gaps.
US Pet Boarding Market Competitive Landscape
Listed leaders compete with private specialists across facility format and geographic coverage dimensions. The vendor base fragments across standalone kennels, veterinary clinic co-locations, franchise networks, and mobile units with no single archetype commanding dominant share. Three strategic archetypes define competitive positioning: scale-driven franchise operators with standardized protocols, premium pet hotel developers with amenity differentiation, and mobile specialists addressing rural coverage gaps. M&A activity concentrates on suburban retail corridor real estate acquisition, while technology licensing partnerships accelerate live-streaming camera network deployment.
Within the franchise network tier, Camp Bow Wow and Dogtopia Enterprises exemplify scale-driven expansion models. PetSmart LLC anchors the veterinary co-location archetype through big-box footprint integration. These three operators represent distinct strategic bets on facility format, geographic density, and service bundling approaches.
| Leading Market Players |
|---|
| Camp Bow Wow |
| Dogtopia Enterprises |
| A Place for Rover, Inc. |
| PetSmart LLC |
| Petco |
| Best Friends Pet Care |
| Paradise 4 Paws, LLC |
| Pet Paradise |
| The Dog Stop |
| Others |
Pricing and Supply Chain Analysis
Fourteen-day advance booking windows for premium kennel slots compress inventory turnover and concentrate pricing power with facilities holding USDA Animal Welfare Act certification. This lead-time structure rewards operators with climate-controlled infrastructure and licensed veterinary technician staffing, while penalizing last-minute capacity additions.
Pricing Analysis
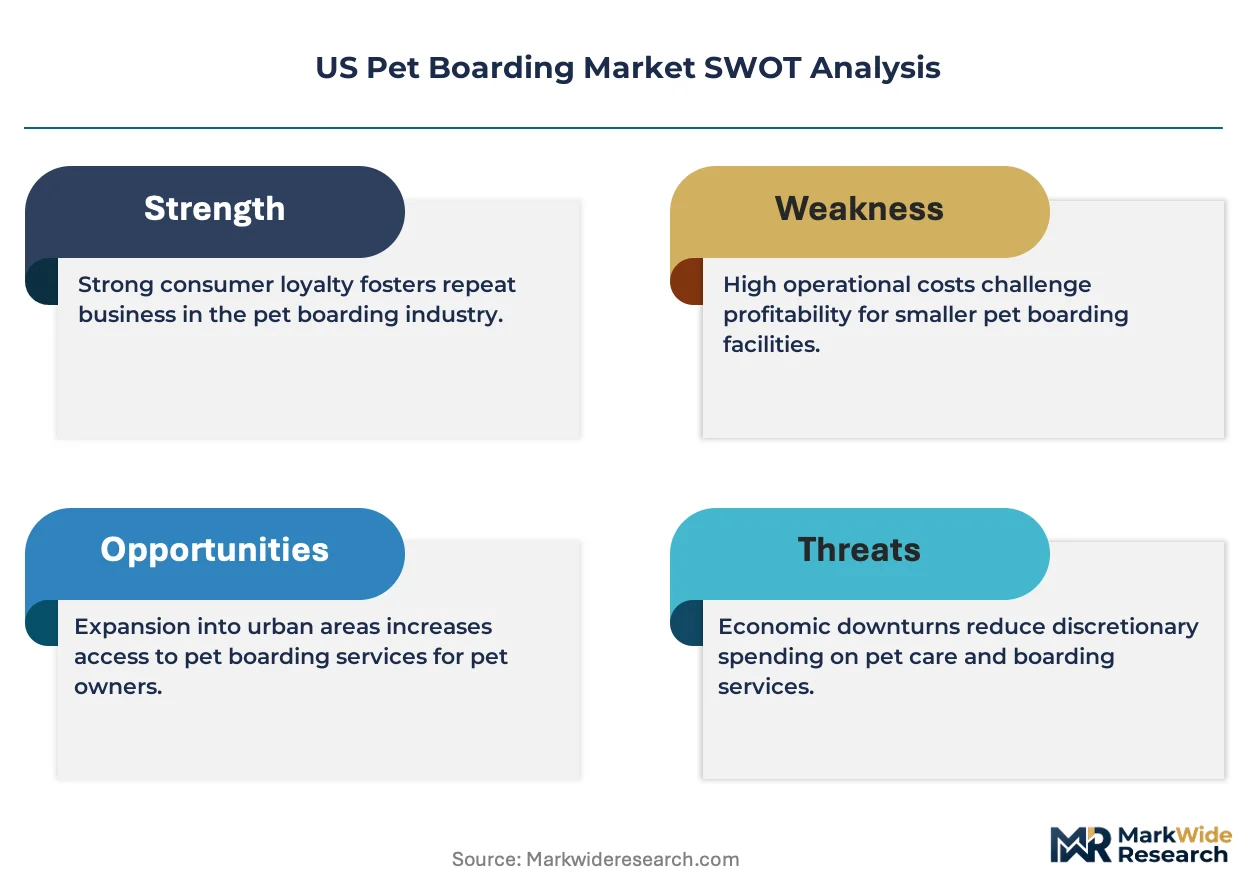
Three-tier pricing structure across premium, standard, and economy levels separates climate-controlled private suites from basic kennel runs and mobile trailer units. Certification grade under state Department of Agriculture inspection standards and geographic delivery cost to suburban retail corridors drive differentiation. Cost compression in standard-tier overnight boarding intensifies because residential pet sitting platforms capture price-sensitive exurban demand. Individual pet owners seeking smartphone-based visibility show least price sensitivity, while rescue organizations and municipal shelters operate under strict budget constraints.
Supply Chain Analysis
Strategic stockpiling of veterinary pharmaceuticals and specialty pet food inventories dominates over just-in-time approaches due to animal health regulatory requirements. Domestic manufacturing of epoxy flooring systems and HVAC filtration equipment draws from Ohio, Pennsylvania, and Texas production hubs. Supply chain risk centers on single-source vulnerability for climate-control components imported from Mexico and China. Distribution runs through veterinary supply cooperatives and direct manufacturer relationships to standalone kennels and veterinary clinic co-locations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US pet boarding market functions as a service-attach opportunity where training program and grooming service revenue layers expand faster than basic overnight housing. Recurring subscription daycare memberships now anchor predictable cash flows ahead of transactional boarding.
For Market Incumbents: Compound defensive positioning through backward integration into veterinary technician training pipelines and captive supply of climate-control equipment. State-level kennel licensing mandates in California and Texas threaten rapid facility scaling. Certification investment and channel control through exclusive suburban retail corridor real estate leases provide durable moats against mobile boarding entrants.
For New Entrants and Emerging Players: Differentiate on transparency technology by deploying live-streaming camera networks and wearable activity trackers as baseline offerings rather than premium upgrades. Rural and exurban mobile boarding units present the most penetrable white space, with veterinary trailer formats addressing geographic coverage gaps outside Dallas-Fort Worth and Miami metropolitan statistical areas. Direct-to-consumer digital booking platforms bypass incumbent franchise network dependencies.
For Investors and Strategic Acquirers: Carve-out targets emerge from multi-location veterinary clinic groups with underutilized boarding capacity and compliant infrastructure. Long-term viability over the next decade hinges on subscription revenue predictability and regulatory compliance automation. Watch municipal short-term rental ordinance enforcement intensity as the inflection signal separating licensed commercial operators from residential pet sitting substitution.
| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Membership Expansion | Fixed monthly billing with guaranteed slot availability locks in revenue predictability across Texas and Florida metropolitan zones. |
| Climate-Control Infrastructure Upgrade | Temperature and humidity monitoring systems extend serviceable demographics to brachycephalic breeds previously excluded from traditional boarding. |
| Mobile Boarding Unit Deployment | Veterinary trailer formats address geographic coverage gaps outside metropolitan statistical areas without real estate concentration risk. |
| Training Program Attachment | Behavior modification services bundled with extended stays capture margin expansion unavailable in basic overnight housing. |
| OSHA Compliance Integration | Proactive federal injury prevention mandate adherence reduces insurance premiums and supports veterinary technician retention. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of state Department of Agriculture inspection records, municipal zoning board filings, and veterinary practice act documentation. Facility operators, veterinary clinic owners, and franchise development executives provided operational data. State licensing databases, USDA Animal Welfare Act inspection reports, and suburban retail corridor lease transaction records supplied bottom-up validation. Top-down triangulation against household formation statistics and travel demand indices anchored market sizing.
Segmentation dimensions modeled include service type, animal type, facility format, and customer maturity across the projection horizon. Overnight boarding, daycare, grooming, and training attachments formed service-level splits. Canine, feline, and exotic animal categories structured animal-type segmentation. Standalone kennels, veterinary co-locations, pet hotels, and mobile units defined facility archetypes. CAGRs derived from capacity utilization trends, subscription membership adoption curves, and regulatory compliance cost trajectories.
Material uncertainties — veterinary technician wage inflation, commercial real estate rent escalation, and municipal short-term rental ordinance enforcement — sit outside the modeled envelope. Forecasts reflect assumptions about dual-income household formation and travel demand recovery. Revision becomes warranted when residential pet sitting platform penetration crosses thresholds that materially compress commercial facility booking windows.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Pet Relaxants Market
Pet Care Products
Organic and Natural Dog Foods Market
Pet Care Products
Cat Furniture and Scratchers Market
Pet Care Products
Pet Care E-Commerce Market
Pet Care Products
Pet Perfume Market
Pet Care Products
South Korea Organic and Natural Pet Food Market
Pet Care Products
South America Pet Food Market
Pet Care Products
Dog Box Market
Pet Care Products
Germany Pet Food Market
Pet Care Products
Dog Crate Furniture Market
Pet Care Products
Smart Dog Collar Market
Pet Care Products
Smart Pet Leash Market
Pet Care Products
Brazil Cat Litter Market
Pet Care Products
Pet Pens Market
Pet Care Products
India Pet Food Market
Pet Care Products
Pet Supplement Market