
 Dog Clippers Market | 2026-2036
Dog Clippers Market Size, Share, and Industry Trends Forecast 2026-2036
Dog Clippers Market Analytics
Clipper kit bundling with blade guards, cleaning brushes, and lubricating oil is pivoting buyer choice toward all-in-one solutions over standalone devices. Andis leverages its century-old blade manufacturing heritage to sustain loyalty among professional groomers. Wahl anchors North American distribution through salon-supply channel control. Oster competes on price-performance positioning in the entry-level cordless segment.
Dog clippers are motorized shearing devices with oscillating or rotary blade assemblies, typically operating at 2,000–5,000 strokes per minute, designed to trim canine coats without skin abrasion. Professional groomers and veterinary clinics constitute the primary commercial end users, while pet owners represent a growing amateur segment. Cordless units powered by rechargeable lithium-ion batteries capture the fastest expansion as mobility constraints fade. Ceramic blade materials command premium positioning due to cooler running temperatures and extended edge retention. Clipper kits concentrate margin pools through attachment sales and consumable replenishment cycles.
The U.S. Consumer Product Safety Commission monitors electrical safety standards for pet grooming appliances, while the EU's CE marking and REACH frameworks govern material composition and electromagnetic compatibility for imported clippers. Japan's Ministry of Economy, Trade and Industry (METI) enforces appliance efficiency benchmarks that shape motor selection for brands targeting East Asian markets. Stakeholders must monitor evolving right-to-repair legislation across multiple geographies, as blade cartridge standardization and motor accessibility become decisive purchase criteria.
Market Dynamics
The EU's Ecodesign Directive is compressing motor architecture choices across the supply base, forcing manufacturers to redesign for repairability and energy efficiency while maintaining blade speed performance. This regulatory pressure intersects with lithium-ion battery maturation to reshape product roadmaps.
Growth Catalysts
- REACH material compliance:European chemical safety frameworks are accelerating ceramic blade adoption as manufacturers eliminate heavy-metal coatings from traditional steel alloys.
- Veterinary clinic electrification:Small-animal practices in Germany's Bavaria region are replacing pneumatic grooming stations with cordless units to reduce noise trauma in surgical recovery wards.
- Right-to-repair legislation:France's repairability index mandates are extending clipper replacement cycles and creating aftermarket blade cartridge demand.
Market Restraints
- Neodymium magnet supply concentration:Brushless motor production depends on rare-earth processing capacity concentrated in China's Inner Mongolia region.
- Ceramic sintering yield rates:Zirconia blade manufacturing achieves only 60-70% first-pass quality, compressing margin structures for premium positioning.
- CE marking electromagnetic compatibility:Stricter emission thresholds for cordless appliances are extending product validation timelines by 4-6 months.
Strategic Opportunities
- Mobile grooming van proliferation:Battery-powered clipper demand is accelerating in the US Pacific Northwest where urban density restrictions favor door-to-door service models.
- AI-assisted coat analysis:Smartphone-integrated blade selection tools are converging with e-commerce platforms to reduce return rates on attachment purchases.
- Subscription blade replenishment:Direct-to-consumer consumable programs are capturing recurring revenue from amateur groomers bypassing salon-supply intermediaries.
Industry Challenges
- Certified pet groomer shortages:The National Dog Groomers Association of America reports 15,000 unfilled positions, constraining professional-grade equipment turnover.
- Legacy blade inventory stranding:Proprietary cartridge designs from the 2010s are becoming incompatible with new motor mounts, creating customer migration friction.
- Cross-border warranty fulfillment:Repair network density varies sharply between metropolitan and rural service territories, elevating customer acquisition costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dog Clippers Market |
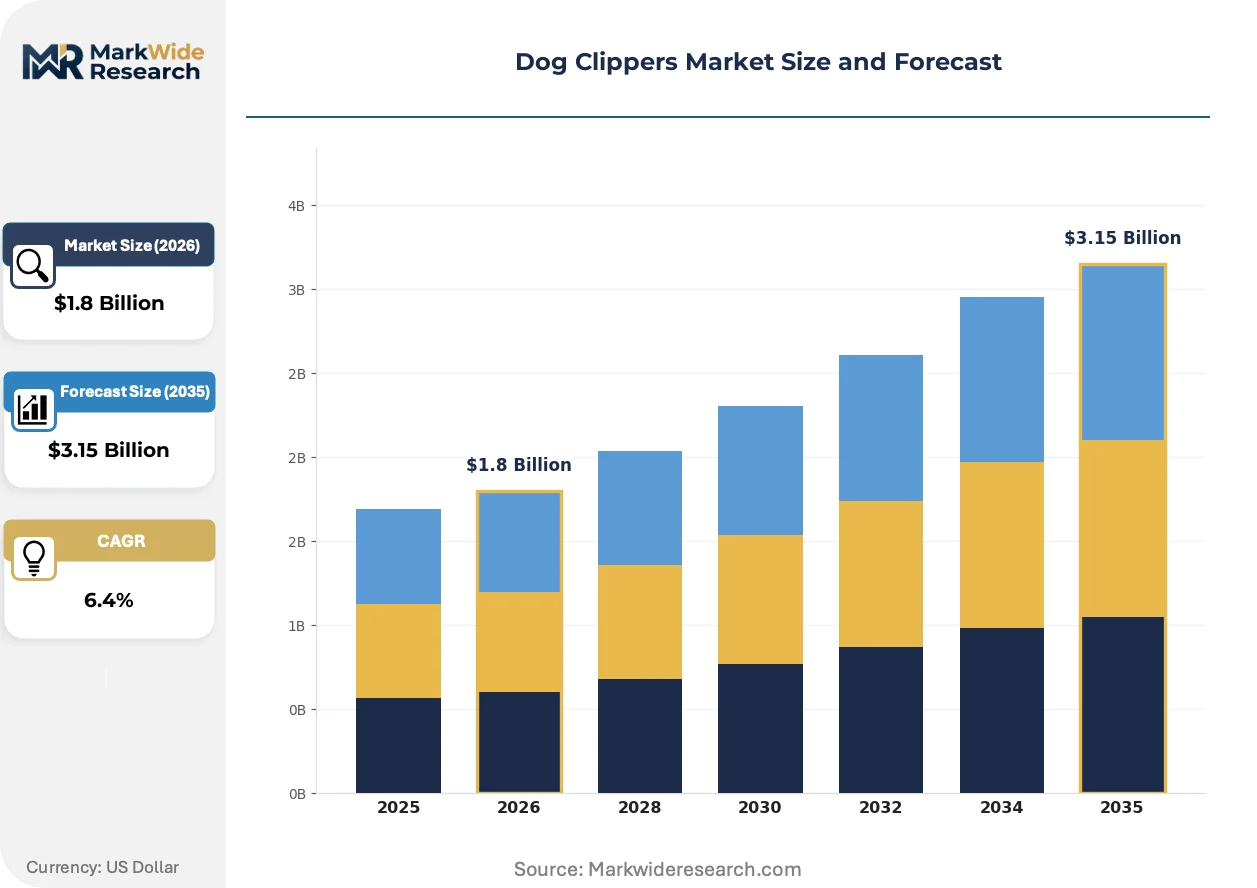
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corded, Cordless, Clipper Kits, Trimming Accessories End User: Professional Groomers, Pet Owners, Animal Hospitals, Veterinary Clinics Power Source: Electric, Rechargeable Battery, Manual, Hybrid Blade Material: Stainless Steel, Ceramic, Titanium, Carbon Steel |
| Companies Covered | Andis, Wahl, Oster, Ruri, Sminiker, PetTech, Oneisall, Boosic, GerryMade, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dog Clippers Market Evolving Landscape
Cordless lithium-ion architectures are displacing corded designs across every price tier, while ceramic materials and smart diagnostics reshape buyer expectations. These shifts are compressing replacement cycles in professional segments and elevating kit bundling as a margin strategy.
Brushless DC motor technology is converging with precision-machined ceramic blade assemblies to eliminate heat buildup during extended grooming sessions. Professional groomers in high-throughput salons are adopting these configurations to reduce coat damage and extend continuous operation time. The convergence is compressing demand for traditional brushed-motor units with steel blades in premium segments.
France's repairability index scoring system now mandates disassembly instructions and spare parts availability for electrical grooming appliances sold domestically. Manufacturers must publish technical documentation and maintain blade cartridge inventories for ten years post-discontinuation. The policy is accelerating standardization of motor mounting interfaces and blade attachment mechanisms across European product lines.
Amateur groomers are shifting from episodic replacement purchases toward integrated kit solutions that include blade guards, cleaning brushes, and lubricating oil. E-commerce platforms are capturing this behavioral change through subscription bundling that locks in consumable replenishment cycles. This pattern is most visible in Germany and the United Kingdom where dense pet ownership supports direct-to-consumer logistics economics.
Dog Clippers Market Segmentation
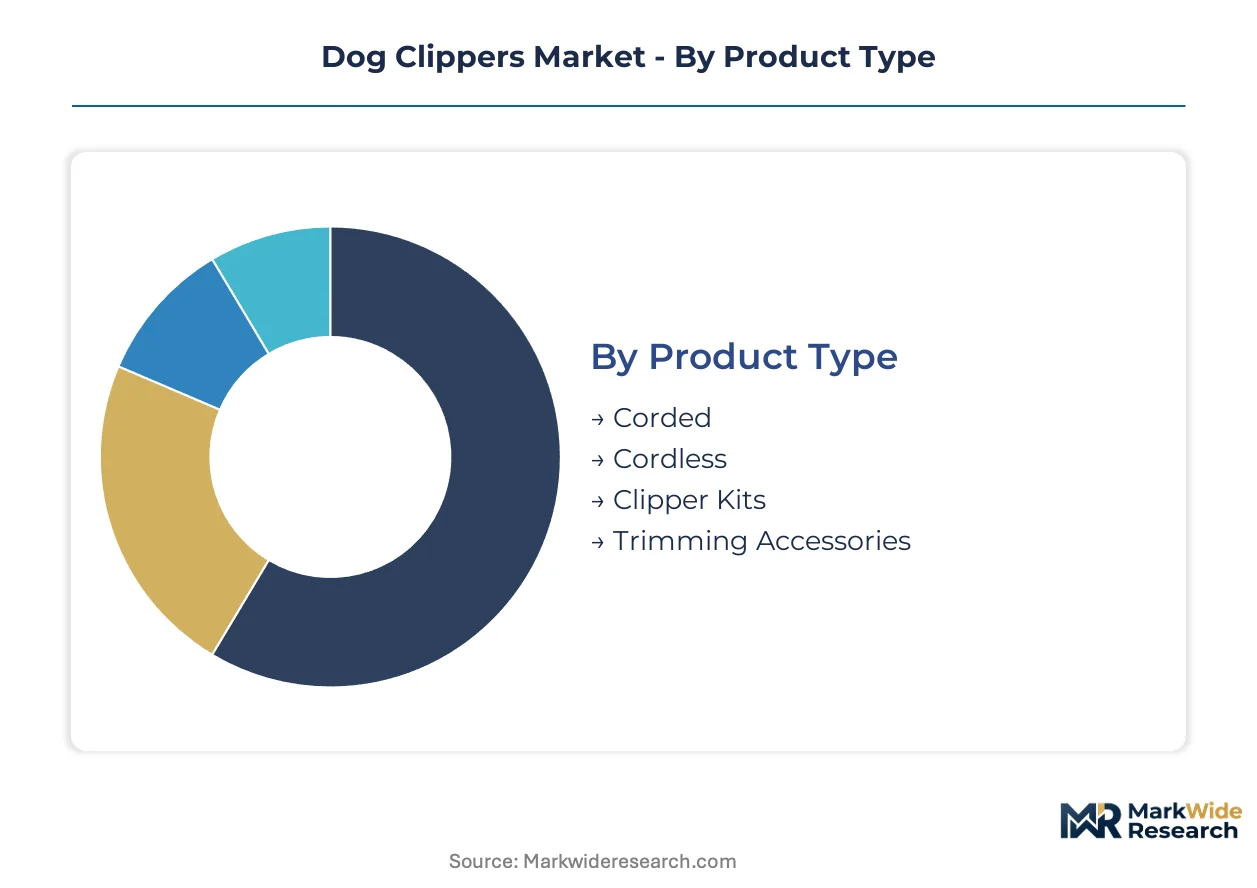
Upgrade cycles in dog clippers vary sharply by user sophistication and regulatory environment. Segmentation reveals where lithium-ion displacement, ceramic blade adoption, and kit bundling concentrate margin capture across distinct buyer profiles.
Product Type:
Replacement intervals diverge dramatically between corded legacy installations and cordless field units, with kit bundling now compressing standalone device turnover.
- Corded:AC-powered units deliver sustained 3,000-5,000 SPM output without thermal fade, anchoring fixed-position grooming stations in Germany's Bavaria salon clusters where electrical infrastructure reliability reduces mobility premiums.
- Cordless:Lithium-ion architectures operating 2,000-4,500 SPM dominate mobile grooming van deployments across the US Pacific Northwest, where urban density restrictions and noise ordinances favor battery-powered flexibility over tethered operation.
- Clipper Kits:Bundled solutions with blade guards, cleaning brushes, and lubricating oil capture amateur groomers in the United Kingdom through subscription replenishment economics.
- Trimming Accessories:Replacement blades, attachment combs, and maintenance consumables sustain recurring revenue from installed bases in professional and veterinary settings.
Volume placements concentrate in Corded configurations; the faster expansion belongs to Cordless architectures.
End User:
Procurement authority and technical specification knowledge separate commercial buyers from amateur segments, with regulatory compliance requirements widening the gap.
- Professional Groomers:High-throughput operators prioritize ceramic blade compatibility and brushless motor thermal management, with Germany's dense salon networks driving premium equipment replacement every 18-24 months.
- Pet Owners:Amateur groomers in the United Kingdom and Germany exhibit kit-purchasing behavior through e-commerce platforms, with AI-assisted coat analysis tools reducing attachment return rates.
- Animal Hospitals:Surgical recovery wards in Bavaria region clinics demand sub-50 dB operation to minimize noise trauma, accelerating cordless lithium-ion adoption over pneumatic legacy systems.
- Veterinary Clinics:Small-animal practices balance cost constraints against CE marking compliance, with France's repairability index mandates extending equipment replacement cycles and shifting spend toward blade cartridges.
Professional Groomers generate the highest absolute unit demand; Pet Owners are expanding most quickly as direct-to-consumer channels mature.
Power Source:
Energy efficiency regulations and battery chemistry maturation are reconfiguring the cost-performance frontier across all price tiers.
- Electric:Mains-powered units retain dominance in fixed commercial installations where continuous operation demands exceed lithium-ion duty cycles.
- Rechargeable Battery:Lithium-ion cells with 2-4 hour runtime now standard in professional cordless units, with EU Ecodesign Directive pressure accelerating brushless motor pairing for energy efficiency compliance.
- Manual:Spring-loaded or squeeze-action clippers persist in emergency backup roles and regulatory environments with unreliable electrical infrastructure.
- Hybrid:Dual-power architectures allowing AC/battery switching address mobile groomers needing field flexibility without sacrificing station throughput.
Electric configurations retain volume leadership; Rechargeable Battery systems are gaining share fastest as salon electrification and mobile service models converge.
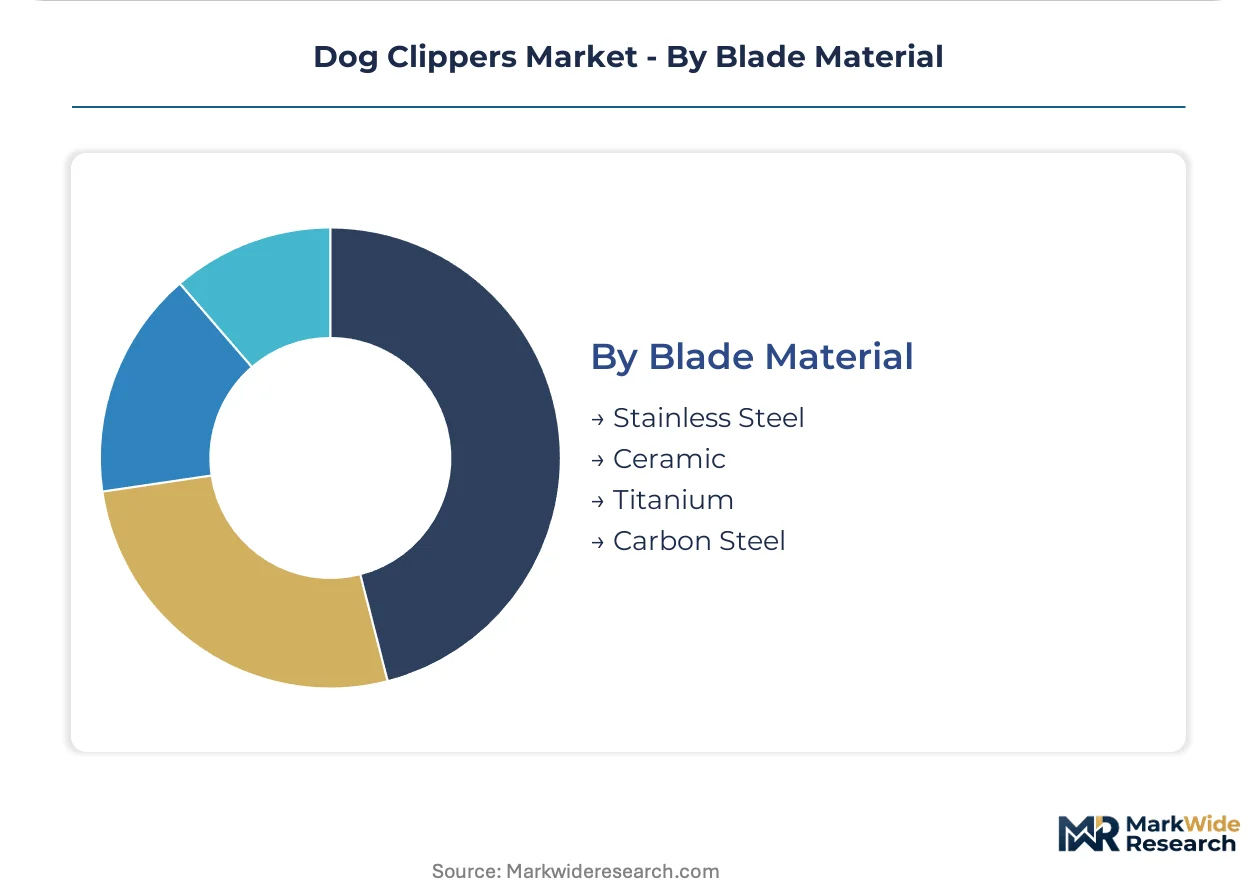
Blade Material:
Heat dissipation characteristics and coating chemistry regulations are reshaping blade replacement economics and manufacturing yield structures.
- Stainless Steel:Chromium-nickel alloys with chrome plating dominate mid-market positioning, though REACH compliance costs are compressing margins as heavy-metal elimination mandates accelerate.
- Ceramic:Zirconia sintered blades run 30-50% cooler than steel equivalents, commanding premium positioning in high-throughput German salons where continuous operation demands thermal stability despite 60-70% first-pass manufacturing yields.
- Titanium:Nitride-coated steel substrates offer enhanced edge retention for professional segments prioritizing durability over ceramic thermal performance.
- Carbon Steel:High-carbon alloys with oil-dependent maintenance requirements retain price-sensitive entry-level positioning where coating compliance costs are prohibitive.
Stainless Steel maintains the largest installed base; Ceramic materials are climbing the fastest as REACH frameworks eliminate traditional coating chemistries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Bavaria region concentrates premium grooming salon density, with tax incentives for veterinary equipment modernization accelerating cordless clipper procurement cycles.
United States
Mobile grooming van proliferation in the Pacific Northwest drives lithium-ion battery demand, as Seattle and Portland noise ordinances restrict pneumatic equipment. The Consumer Product Safety Commission enforces electrical safety standards for pet grooming appliances. California's dense pet ownership supports subscription blade replenishment programs through direct-to-consumer logistics.
Germany
Bavaria's professional salon clusters replace equipment every 18-24 months, prioritizing ceramic blade thermal stability for high-throughput operations. The EU Ecodesign Directive mandates repairable motor architectures and energy efficiency benchmarks. North Rhine-Westphalia's veterinary clinic networks are converting surgical recovery wards to sub-50 dB cordless units.
United Kingdom
Amateur groomers exhibit kit-purchasing behavior through e-commerce platforms, with AI-assisted coat analysis reducing attachment return rates. REACH frameworks eliminate heavy-metal coatings from traditional steel alloys. Greater London's dense urban pet ownership supports subscription bundling economics for consumable replenishment.
France
Repairability index mandates extend clipper replacement cycles and shift spend toward blade cartridges. ANSM and CNIL frameworks govern product safety and data handling for smart diagnostics. The Île-de-France region's grooming salons standardize motor mounting interfaces to comply with ten-year spare parts availability requirements.
Japan
METI appliance efficiency benchmarks shape brushless motor selection for brands targeting East Asian markets. Veterinary clinics in Tokyo and Osaka prioritize electromagnetic compatibility compliance for imported cordless units. Kanto region distributors stock hybrid AC/battery architectures for mobile groomers requiring field flexibility.
Dog Clippers Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered price-performance segments. The market exhibits moderate consolidation, with century-old blade manufacturers anchoring professional loyalty against emerging direct-to-consumer entrants. Strategic archetypes include heritage toolmakers with captive blade production, electronics specialists leveraging battery chemistry advantages, and platform-native brands capturing amateur segments through subscription economics. Competitive moves concentrate on salon-supply channel control and consumable lock-in through proprietary cartridge designs.
Within the heritage manufacturing tier, Andis and Wahl exemplify divergent geographic anchoring strategies. Andis represents century-old blade manufacturing lineage sustaining professional groomer loyalty through thermal management expertise. Wahl occupies a position as North American distribution anchor, leveraging salon-supply intermediaries for channel control. Oster sits within price-performance positioning, capturing entry-level cordless demand through cost-optimized motor architectures.
| Leading Market Players |
|---|
| Andis |
| Wahl |
| Oster |
| Ruri |
| Sminiker |
| PetTech |
| Oneisall |
| Boosic |
| GerryMade |
| Others |
Value Network & Pricing Analysis
Captive blade manufacturing anchors both supply position and pricing power for heritage toolmakers, while outsourced motor sourcing creates tiered cost structures across cordless architectures. EU Ecodesign Directive compliance costs feed into premium positioning for repairable designs, compressing margins for brands lacking in-house ceramic sintering capabilities.
Pricing Analysis
Short lead-time premiums concentrate in ceramic blade procurement, where 60-70% first-pass yield rates compress spot inventory availability and elevate pricing for immediate fulfillment. Pricing stratifies across premium ceramic-thermal tiers, standard stainless-REACH tiers, and economy carbon-steel entry points. Cost compression in mid-market steel blades is intensifying because heavy-metal coating elimination mandates raise compliance spend. Amateur groomers through UK e-commerce channels exhibit highest price sensitivity, while Bavaria salon clusters prioritize thermal performance over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with China's Inner Mongolia region for neodymium magnet processing, which feeds brushless motor production across all cordless tiers. Manufacturing draws from China for lithium-ion cell assembly, Germany for precision motor winding, and Vietnam for plastic housing injection. Tariff exposure on rare-earth processed materials elevates landed cost volatility for brands without captive magnet sourcing. Distribution runs through salon-supply intermediaries in North America and direct-to-consumer platforms in European urban corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
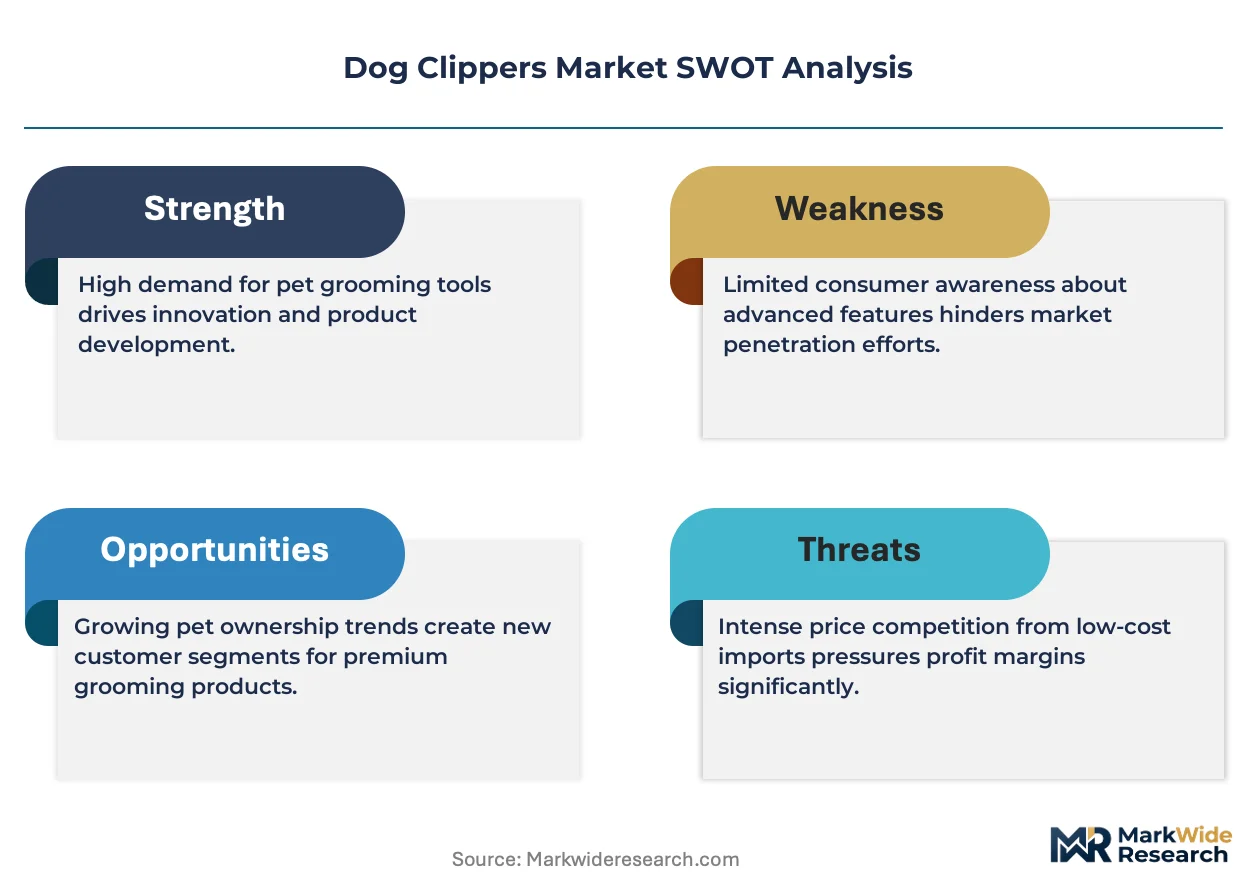
The dog clippers market sits in a technology-transition phase, with brushless DC motor architectures displacing legacy brushed designs and ceramic blade assemblies eliminating heat-damaged coat risk.
For Market Incumbents: Hedge ceramic sintering yield volatility through backward integration into zirconia powder sourcing or long-term offtake agreements with Japanese material suppliers. Defend salon-supply channel control against direct-to-consumer entrants by embedding subscription blade replenishment into professional equipment warranties, locking in consumable recurring revenue. For New Entrants and Emerging Players: Enter via AI-assisted coat analysis tools that reduce amateur groomer attachment return rates, capturing UK and German e-commerce white space. Target mobile grooming van operators in the US Pacific Northwest with hybrid AC/battery architectures that address noise ordinance constraints. Deploy platform-native subscription bundling to bypass established salon-supply intermediaries. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified toolmaking conglomerates seeking grooming vertical penetration. Long-term viability favors brands with captive blade production and repairability index compliance infrastructure already embedded. Watch France's repairability index mandate adoption rates across neighboring EU member states as the inflection signal for standardization-driven consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Blade Manufacturing Scale-Up | In-house zirconia sintering captures margin lost to 60-70% yield rates at third-party suppliers. |
| Repairability Index Compliance Program | France's ten-year spare parts mandate requires motor mount standardization across European product lines. |
| Subscription Consumable Platform Launch | Direct-to-consumer blade replenishment locks in amateur groomer lifetime value beyond initial kit purchase. |
| Brushless Motor R&D Partnership | Collaboration with Chinese rare-earth processors hedges neodymium magnet supply concentration risk. |
| Mobile Groomer Channel Expansion | Pacific Northwest van operator relationships capture lithium-ion demand from noise-restricted urban service models. |
Research Methodology
Trade association filings, EU regulatory databases, and veterinary equipment procurement records formed the secondary backbone, cross-referenced against primary interviews with professional groomers, salon supply distributors, ceramic blade manufacturers, and veterinary clinic procurement managers. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions from customs trade data and channel inventory audits.
Historical replacement cycle analysis across corded, cordless, and kit product categories informed penetration curve modeling over the projection horizon. Segmentation dimensions included power source architecture, blade material chemistry, end-user sophistication tier, and regional regulatory cluster. CAGRs derived from logistic adoption curve fitting against lithium-ion battery cost decline trajectories and REACH compliance timeline enforcement.
Forecast precision tightens around the base case; tail outcomes carry wider variance under rare-earth export restriction scenarios or accelerated right-to-repair legislative adoption. Forecasts embed assumptions regarding ceramic sintering yield improvement rates and brushless motor cost parity achievement. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Spain Pet Boarding Market
Pet Care Products
Pet Hotels Market
Pet Care Products
Inflatable Pet Collars Market
Pet Care Products
Pet Food Nutraceutical Market
Pet Care Products
Canada Pet Training Services Market
Pet Care Products
Dog Box Market
Pet Care Products
Dog Clothes Market
Pet Care Products
GPS Dog Collar Market
Pet Care Products
Saudi Arabia Pet Boarding Market
Pet Care Products
Smart Connected Pet Collar Market
Pet Care Products
Vegan Pet Food Market
Pet Care Products
North America Pet Food Nutraceuticals Market
Pet Care Products
Weight Management Dog Food Market
Pet Care Products
US Pet Treats Market
Pet Care Products
Large Breed Dog Food Market
Pet Care Products
Dog Vitamins Market