
 Canada Pet Training Services Market | 2026-2036
Canada Pet Training Services Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Pet Training Services Market Insights
Aftermarket service revenue from behavioral modification programs is tilting toward subscription-based follow-up models. Dog Training Elite leverages proprietary curriculum standardization to sustain margins across franchise locations. Bark Busters Home Dog Training anchors its competitive position through in-home delivery formats that dominate suburban markets. Camp Bow Wow differentiates via integrated daycare-training bundles that occupy the premium tier of commercial pet services.
Canada pet training services encompass structured behavioral instruction delivered by certified professionals using evidence-based protocols, typically involving operant conditioning techniques, session durations of thirty to sixty minutes, and progressive skill ladders designed to modify animal conduct for domestic coexistence. Private sessions command premium pricing due to customized pacing and address-specific aggression or anxiety cases, while group classes represent the volume foundation driven by puppy socialization demand and municipal licensing requirements. Online courses capture growing interest from rural pet owners and breeders seeking asynchronous access to foundational obedience modules.
Health Canada enforces animal transport and welfare protocols under the Health of Animals Act, while provincial societies for the prevention of cruelty to animals administer certification standards that shape trainer credentialing and facility accreditation. The Canadian Veterinary Medical Association publishes guidelines linking behavioral health to veterinary outcomes, indirectly steering clinic referrals toward accredited training providers. Stakeholders must monitor evolving municipal leash laws and breed-specific legislation that could redirect demand toward behavioral modification specialists.
Market Dynamics
Subscription-based follow-up models for behavioral modification programs are restructuring revenue stability across Canadian pet training services, replacing one-time session fees with recurring income streams that deepen client retention and lifetime value.
Growth Catalysts
- Municipal Licensing Mandates:Cities across Ontario and British Columbia now require obedience certification for dog licensing, routing first-time pet owners toward accredited training providers.
- Veterinary Referral Networks:The Canadian Veterinary Medical Association's behavioral health guidelines steer clinic referrals toward certified trainers, creating institutional demand channels.
- Urban Millennial Household Formation:Toronto and Vancouver apartment-dwelling millennials prioritize professional training to manage breed restrictions and noise complaints in dense housing.
Market Restraints
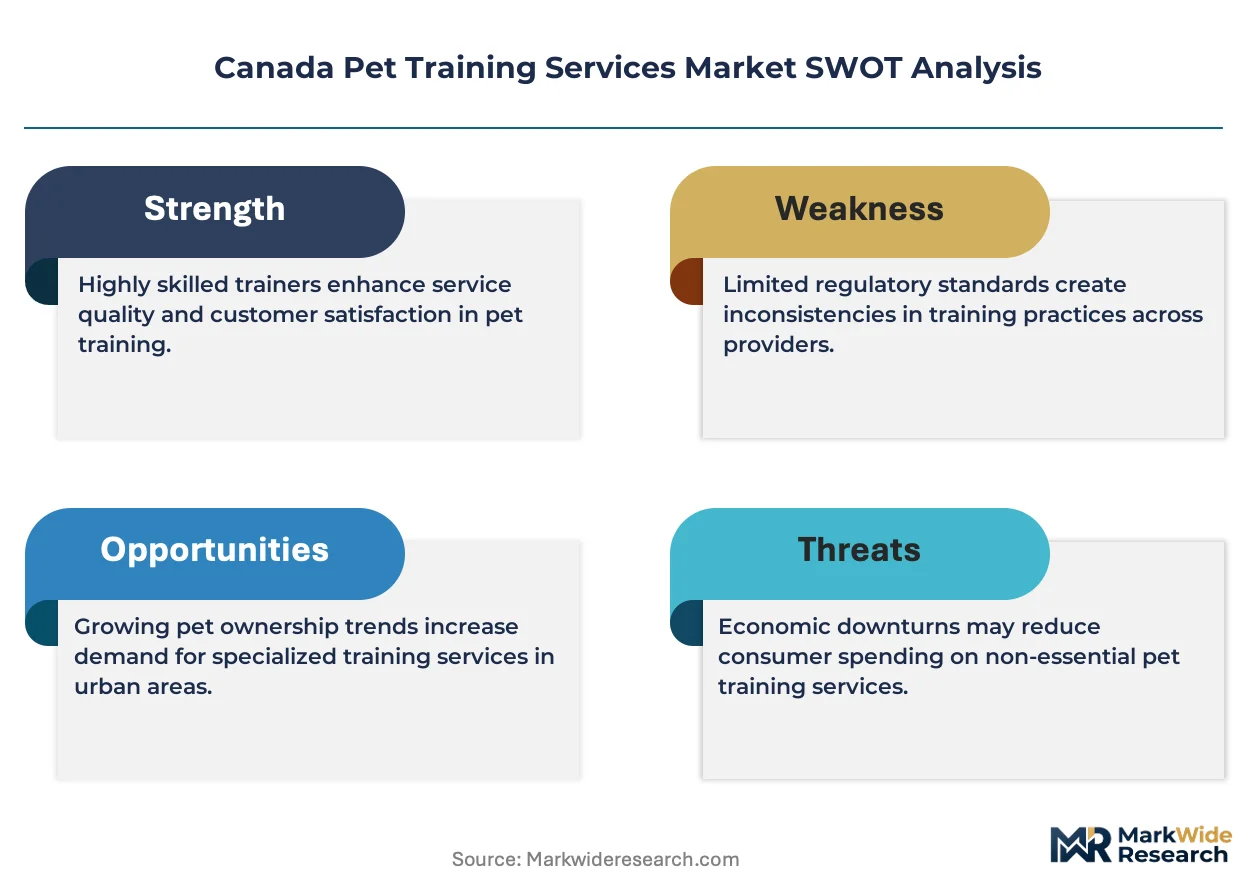
- Certification Fragmentation:Provincial societies for the prevention of cruelty to animals administer non-uniform credentialing standards, creating interprovincial mobility barriers for trainers.
- Rural Service Gaps:Prairie provinces and northern territories lack sufficient accredited facility density, forcing pet owners toward unregulated informal providers.
- Input Cost Pressure:Facility lease rates in Vancouver and Toronto consume disproportionate revenue share, compressing operating margins for independent operators.
Strategic Opportunities
- Atlantic Canada Expansion:Halifax and Moncton exhibit rising pet ownership without proportional training service penetration, presenting first-mover advantages.
- Telehealth Integration:Remote video coaching platforms enable asynchronous rural access, capturing underserved breeders and farm dog owners.
- Daycare-Training Bundles:Integrated service packages occupy premium positioning while reducing customer acquisition costs through shared facility utilization.
Industry Challenges
- Trainer Talent Pipeline:Evidence-based operant conditioning expertise remains scarce relative to demand, extending recruitment cycles for quality hires.
- Breed-Specific Legislation Complexity:Evolving municipal restrictions on pit bulls and similar breeds require continuous curriculum adaptation and liability protocol updates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Pet Training Services Market |
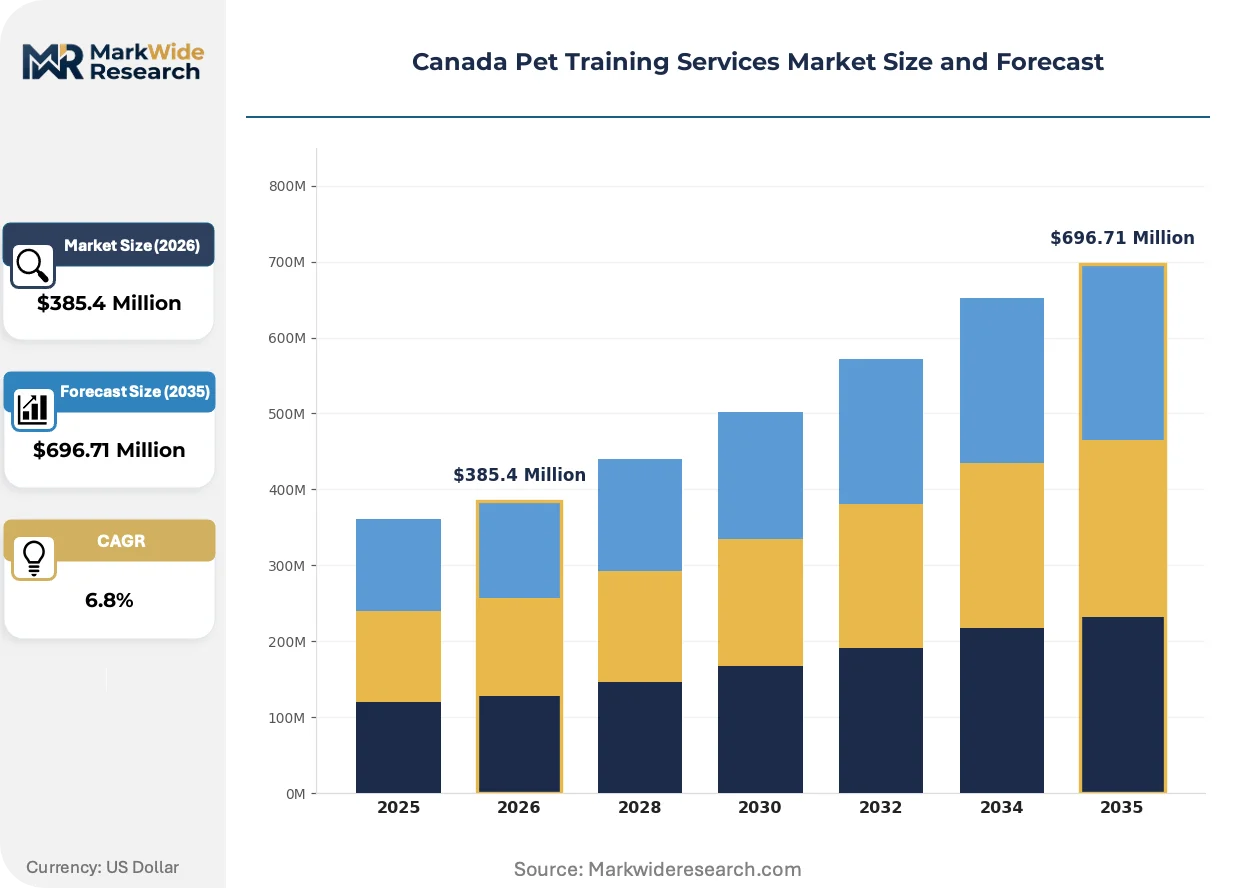
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $696.71 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Group Classes, Private Sessions, Online Courses, Behavioral Modification Animal Type: Dogs, Cats, Birds, Small Mammals Training Method: Positive Reinforcement, Clicker Training, Obedience Training, Socialization Client Type: Pet Owners, Breeders, Shelters, Veterinary Clinics |
| Companies Covered | Dogtopia, Shake a Paw Dog Training, Camp Bow Wow, Pawsome Concierge, ProPet Software Inc., Bark Busters Home Dog Training, Best Friends Pet Care, The Dog Child, Dog Training Elite, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Pet Training Services Market Trends and Innovations
Digital delivery formats are converging with traditional in-person instruction, creating blended service architectures that expand geographic reach while preserving the hands-on elements essential for aggression and anxiety cases.
Artificial intelligence-driven behavioral assessment tools are hybridizing diagnostic capabilities with trainer expertise. Urban millennials in Toronto increasingly demand data-driven progress tracking alongside conventional session formats. This convergence is compressing the gap between standardized curriculum delivery and hyper-customized intervention planning.
Health Canada's enforcement posture under the Health of Animals Act is elevating facility accreditation requirements nationwide. Trainers now face documented welfare protocol obligations that previously applied only to transport and veterinary contexts. Ontario-based providers are responding fastest, using compliance investments as competitive differentiation against unaccredited competitors.
Pet owner purchasing patterns are gravitating toward subscription-based follow-up support rather than discrete session packages. Group class providers in British Columbia are unbundling core instruction from ongoing behavioral maintenance, creating separate revenue streams. This shift is most visible among suburban Vancouver households managing multi-dog dynamics.
Canada Pet Training Services Market Segmentation
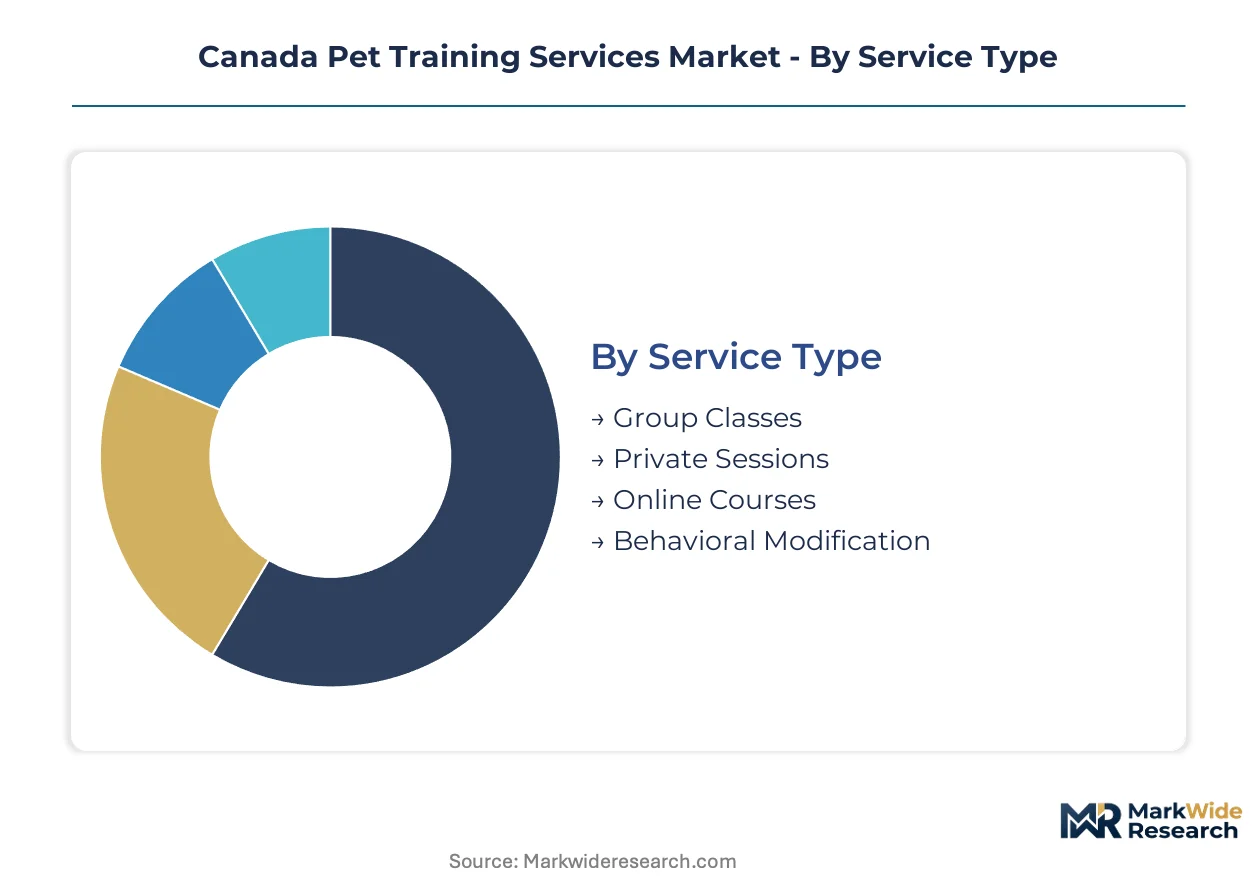
Training service segmentation reveals divergent margin profiles and client lifetime value patterns across delivery formats. Understanding these structural differences enables providers to optimize capacity allocation between high-touch private instruction and scalable digital offerings.
Service Type:
After-sales service intensity varies dramatically across delivery formats, with behavioral modification programs requiring sustained follow-up contact while group classes operate on transactional completion models.
- Private Sessions:One-on-one instruction customized to specific aggression, anxiety, or obedience challenges. Toronto and Vancouver apartment-dwelling millennials drive premium bookings as municipal licensing mandates in these cities require documented training credentials.
- Behavioral Modification:Intensive intervention protocols addressing severe conduct disorders through operant conditioning techniques. Subscription-based follow-up models are restructuring revenue stability here, replacing discrete session fees with recurring income streams.
- Group Classes:Standardized curriculum delivered to multiple animals simultaneously, typically organized around puppy socialization or basic obedience. Volume foundation for the industry.
- Online Courses:Asynchronous modules accessible to rural pet owners and breeders in Prairie provinces lacking accredited facility density.
By volume, Group Classes leads. By growth pace, Online Courses is expanding most quickly.
Animal Type:
Cost tier stratification separates species with established training infrastructures from emerging service categories commanding premium pricing due to specialized expertise scarcity.
- Dogs:Dominant species segment supported by municipal licensing requirements, breed-specific legislation compliance needs, and veterinary referral networks under Canadian Veterinary Medical Association guidelines.
- Cats:Litter box issues and aggression management drive demand among urban millennials in dense housing where noise and odor complaints create urgency.
- Birds:Behavioral feather plucking and screaming interventions require avian-specific conditioning expertise concentrated in Ontario and British Columbia.
- Small Mammals:Litter training and handling desensitization for rabbits, ferrets, and rodents represents niche demand from specialty pet retailers.
By revenue concentration, Dogs dominates. By margin expansion potential, Cats is gaining share fastest.
Training Method:
Application context determines method selection, with veterinary-referred cases demanding evidence-based protocols while owner-initiated training accepts broader technique variation.
- Positive Reinforcement:Reward-based conditioning aligned with Health Canada animal welfare standards under the Health of Animals Act. Preferred protocol for accredited providers seeking differentiation.
- Obedience Training:Structured command-response drilling for licensing compliance and household integration. Core curriculum for municipal certification programs.
- Clicker Training:Marker signal precision for timing-sensitive skill acquisition. Popular among competitive obedience enthusiasts and service dog preparatory programs.
- Socialization:Controlled exposure protocols for puppy developmental windows. Group class providers in British Columbia unbundle this from ongoing maintenance instruction.
By facility utilization, Obedience Training leads. By accreditation alignment, Positive Reinforcement shows the steepest expansion trajectory.
Client Type:
Customer type shapes procurement patterns, with institutional buyers demanding standardized reporting while individual owners prioritize convenience and emotional outcomes.
- Pet Owners:Individual households seeking behavioral solutions for domestic coexistence. Suburban Vancouver multi-dog households increasingly purchase subscription-based follow-up support.
- Veterinary Clinics:Referral sources channeling behavioral health cases per Canadian Veterinary Medical Association guidelines. Create institutional demand for certified providers.
- Breeders:Early socialization and foundation obedience for puppies before sale. Rural Prairie operators leverage asynchronous online access.
- Shelters:Pre-adoption behavioral assessment and post-surrender rehabilitation. Budget-constrained procurement favoring group formats.
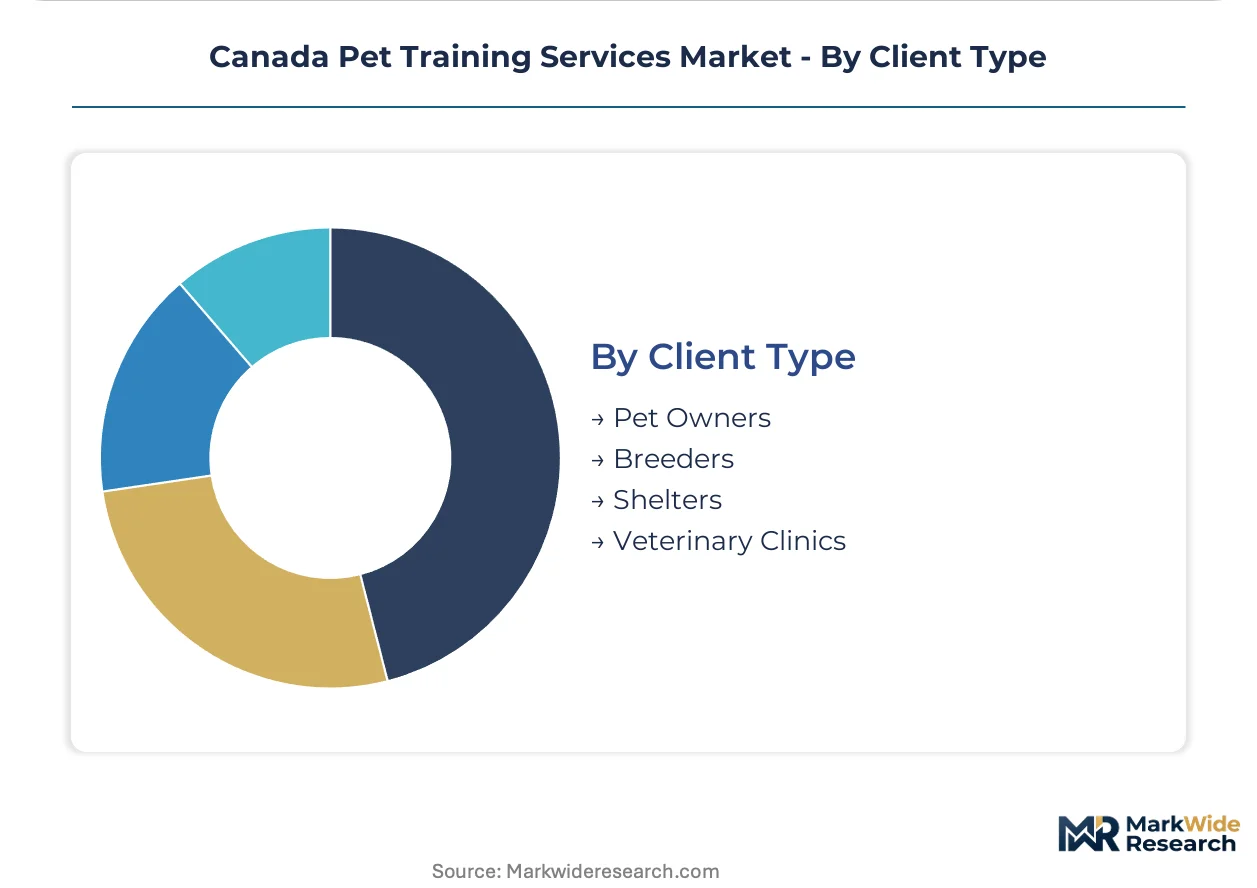
By session volume, Pet Owners leads. By contract value stability, Veterinary Clinics is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban millennial households in Vancouver and Toronto absorb premium pricing with minimal elasticity, while Prairie province pet owners exhibit acute price sensitivity that channels demand toward asynchronous digital formats and informal providers.
Ontario
Toronto's apartment-dwelling millennials drive concentrated demand for private behavioral sessions addressing breed restrictions and noise complaints. Health Canada's Health of Animals Act enforcement elevates facility accreditation requirements province-wide, filtering unaccredited competitors from municipal licensing channels. The Kitchener-Waterloo corridor hosts emerging franchise operations targeting suburban multi-dog households with subscription-based follow-up models.
British Columbia
Vancouver's dense housing stock generates urgent demand for anxiety and aggression management among restricted breeds. Provincial societies for the prevention of cruelty to animals administer certification standards that shape trainer credentialing and facility accreditation across the Lower Mainland. Victoria and Kelowna exhibit service penetration gaps where telehealth-integrated platforms capture rural and island-based pet owners.
Alberta
Calgary and Edmonton's suburban sprawl favors in-home delivery formats over facility-based instruction, with commute distances compressing group class viability. Municipal leash law variations across the province create compliance-driven demand for documented obedience certification. The Calgary metropolitan area anchors franchise expansion from British Columbia-based operators seeking Alberta market entry.
Quebec
Montreal's linguistic duality fragments trainer supply, with French-language certification pathways operating parallel to anglophone credentialing systems. The province's distinct animal welfare regulatory framework under the Quebec Animal Welfare and Safety Act imposes facility standards that diverge from Health Canada protocols. Laval and Quebec City concentrate independent operators serving breed-specific legislation compliance needs.
Atlantic Canada
Halifax and Moncton exhibit rising pet ownership without proportional training service penetration, presenting first-mover advantages for accredited providers. The region's veterinary referral networks remain underdeveloped relative to Ontario and British Columbia, limiting institutional demand channels. St. John's and Charlottetown rely heavily on unregulated informal providers due to accredited facility scarcity.
Canada Pet Training Services Market Competitive Landscape
Capability concentration sits with boutique operators possessing certified operant conditioning expertise; scale advantage sits with franchise networks deploying standardized curricula across multiple provinces. The market exhibits moderate fragmentation with three discernible tiers: premium private-session boutiques, mid-market franchise chains, and volume-oriented group class providers. Two strategic archetypes dominate competitive positioning: in-home delivery specialists leveraging suburban accessibility, and integrated daycare-training bundlers capturing premium positioning through shared facility utilization. Geographic expansion through franchise licensing and curriculum standardization represent the dominant competitive moves.
Within the franchise tier, Dog Training Elite and Bark Busters Home Dog Training occupy positions exemplifying divergent delivery format strategies, while Camp Bow Wow anchors the integrated service bundling archetype. Dogtopia represents the scale-driven facility network model. These entities collectively illustrate how proprietary curriculum control, in-home accessibility, and daycare-training integration serve as the primary vectors for competitive differentiation across Canadian provincial markets.
| Leading Market Players |
|---|
| Dogtopia |
| Shake a Paw Dog Training |
| Camp Bow Wow |
| Pawsome Concierge |
| ProPet Software Inc. |
| Bark Busters Home Dog Training |
| Best Friends Pet Care |
| The Dog Child |
| Dog Training Elite |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in accredited trainer supply across Atlantic Canada and the Prairie provinces compresses pricing power for independent operators while elevating premiums for certified providers in Toronto and Vancouver. Facility lease rate disparities between these markets directly shape margin structures and service format choices.
Pricing Analysis
Subscription-based contracts dominate behavioral modification programs, displacing discrete session fees with recurring revenue streams. Price differentiation rests on certification tier under provincial SPCA standards and facility accreditation status under Health Canada protocols. Cost compression in group classes intensifies as unregulated informal providers capture rural price-sensitive demand. Urban millennials in Vancouver exhibit minimal elasticity for private sessions, while Prairie province pet owners gravitate toward asynchronous digital formats.
Supply Chain Analysis
Extended payment terms from franchise networks strain independent operator cash flow, particularly for curriculum licensing and facility fit-out costs. Trainer talent concentrates in Ontario and British Columbia, where credentialing infrastructure under provincial SPCA societies anchors supply. Raw material dependencies include proprietary training equipment, digital platform licensing, and facility lease commitments. Single-source vulnerability runs through curriculum standardization controlled by franchise headquarters. Distribution runs through direct-to-consumer booking platforms and veterinary clinic referral channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from unregulated informal providers and DIY digital training platforms that erode the bottom of the market. Defense requires structural moves that professionalize service delivery and deepen client retention.
For Market Incumbents: Entrench competitive position through proprietary curriculum standardization and Health Canada accreditation investments that filter unqualified competitors. Pursue backward integration into trainer education pipelines to secure operant conditioning expertise scarce relative to demand. Subscription-based follow-up models deepen client lifetime value against one-time session alternatives.
For New Entrants and Emerging Players: Atlantic Canada presents first-mover terrain with rising pet ownership and underdeveloped accredited facility density. Halifax and Moncton offer white-space entry with lower lease cost structures than Toronto or Vancouver. Telehealth-integrated platforms capture rural Prairie and island-based demand excluded from in-person service radii.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across digital-first training platforms as asynchronous delivery reduces facility dependency. Long-term viability favors scalable models with recurring revenue architecture over transactional session businesses. Acquisition targets should demonstrate curriculum IP control and veterinary referral network integration. Watch municipal licensing mandate expansion as inflection signal for institutional demand channel growth.
| Strategic Initiative | Industry Significance |
|---|---|
| Curriculum Standardization Investment | Proprietary IP under Dog Training Elite's model enables margin preservation across franchise locations. |
| Telehealth Platform Integration | Remote video coaching captures rural Prairie breeders excluded from accredited facility catchment areas. |
| Daycare-Training Bundle Development | Camp Bow Wow's integrated model reduces customer acquisition costs through shared facility utilization. |
| Veterinary Referral Network Expansion | Canadian Veterinary Medical Association guidelines create institutional demand channels for certified providers. |
| Atlantic Canada Geographic Expansion | Halifax and Moncton exhibit rising pet ownership without proportional training service penetration. |
Research Methodology
A spread of perspectives from certified trainers, franchise operations directors, veterinary clinic managers, and provincial SPCA certification officers converged on the working assumptions shaping this analysis. Primary interviews with facility operators in Toronto, Vancouver, and Calgary supplied ground-level capacity and pricing intelligence. Secondary validation drew from Health Canada regulatory filings, provincial animal welfare enforcement records, municipal licensing databases, and Canadian Veterinary Medical Association guideline publications. Bottom-up service provider counts and top-down pet ownership demographic modeling were triangulated to establish market sizing.
Demand-supply balance across private sessions, group classes, and digital formats anchored the forecast framework throughout the projection horizon. Segmentation dimensions modeled include service delivery format, animal species, training methodology, and client type. CAGRs were derived from capacity expansion trajectories, municipal licensing mandate adoption curves, and veterinary referral network penetration rates. Urban millennial household formation in dense housing and subscription model adoption velocity served as key forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending patterns or commercial real estate lease rates would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement posture and certification standard harmonization across provinces. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
UK Pet Training Services Market
Pet Care Products
Animal-Based Pet Protein Market
Pet Care Products
Natural Cat Litter Products Market
Pet Care Products
UK Pet Boarding Market
Pet Care Products
Vegan Dog Food Market
Pet Care Products
UAE Pet Food Market
Pet Care Products
Indonesia Pet Food Market
Pet Care Products
Dog Crate Furniture Market
Pet Care Products
Indestructible Dog Toys Market
Pet Care Products
Asia Pacific Dog Food Market
Pet Care Products
Pet Water Fountain Market
Pet Care Products
GCC Cat Food Market
Pet Care Products
Europe Dog Food Market
Pet Care Products
Cat Backpacks Market
Pet Care Products
Taiwan Pet Food Market
Pet Care Products
Japan Pet Food Market