
 US Pet Treats Market | 2026-2036
US Pet Treats Market Size, Share, and Industry Trends Forecast 2026-2036
US Pet Treats Market Insights
Subscription-based auto-delivery services for recurring treat replenishment is realigning how manufacturers monetize pet owner relationships beyond single-transaction retail. Mars Incorporated leverages its direct-to-consumer infrastructure to capture recurring revenue streams. Nestlé Purina PetCare anchors shelf presence through veterinary channel partnerships that bundle treats with wellness protocols. General Mills competes via specialty retail exclusivity that limits price transparency.
US pet treats comprise formulated edible products designed for intermittent feeding to companion animals, typically containing protein meals, starches, and functional additives processed through extrusion or dehydration to achieve specified moisture content below twenty percent. Their commercial purpose centers on training reinforcement, dental hygiene support, and emotional bonding between owners and pets. Natural ingredient formulations now command premium positioning as meat-based segments face margin compression from volatile protein input costs. Jerky formats sustain growth in grain-free positioning while biscuit categories occupy mature volume channels with thinner returns.
FDA Center for Veterinary Medicine oversight shapes safety protocols and adverse event reporting requirements that elevate compliance costs for domestic producers. USDA labeling standards intersect with state-level feed control regulations administered by entities like the California Department of Food and Agriculture to create fragmented compliance terrain. AAFCO nutrient profiles further constrain formulation flexibility. Stakeholders must monitor pending federal traceability mandates that could reshape supplier qualification and lot-tracking investments.
Market Dynamics
Millennial pet owners in coastal urban centers are accelerating premiumization through subscription auto-delivery models that transform single-transaction retail into recurring revenue relationships, forcing manufacturers to restructure distribution strategies around direct-to-consumer infrastructure.
Growth Catalysts
- FDA Labeling Evolution:The FDA Center for Veterinary Medicine's tightening adverse event reporting requirements are elevating safety investment as a competitive differentiator for compliant domestic producers.
- Protein Input Volatility:Meat-based segment margin compression is redirecting R&D investment toward plant-based and insect protein formulations that stabilize cost structures.
- California Coastal Clusters:Specialty retail penetration in Los Angeles and San Francisco corridors is creating concentrated demand nodes that reward premium positioning and localized supply chain configuration.
Market Restraints
- Fragmented Compliance Terrain:Overlapping FDA, USDA, and California Department of Food and Agriculture regulations create redundant testing burdens that disproportionately impact mid-scale producers without dedicated regulatory affairs functions.
- Grain-Free Substitution Threat:FDA investigations linking certain grain-free formulations to canine dilated cardiomyopathy have triggered veterinarian channel withdrawal from jerky and rawhide categories.
- Protein Meal Concentration:Domestic rendering capacity constraints in the Midwest force reliance on imported poultry meal, exposing margins to freight rate volatility and foreign supplier qualification delays.
Strategic Opportunities
- Northeast Corridor Expansion:Underpenetrated independent pet specialty doors in Boston and Philadelphia metro areas offer white space for veterinary-exclusive treat protocols bundled with wellness services.
- Functional Additive Convergence:Probiotic and dental enzyme technologies are converging with extrusion processes to create dual-claim products that command shelf space in both treat and supplement aisles.
- State-Level Traceability Mandates:Pending California lot-tracking requirements will favor early-adopter manufacturers with existing serialization infrastructure, creating regulatory moats against laggard competitors.
Industry Challenges
- Extrusion Technician Scarcity:Specialized knowledge in low-moisture thermal processing is concentrating among aging workforce cohorts, forcing manufacturers to automate or absorb wage premiums.
- AAFCO Nutrient Profile Lag:Delayed updates to official feeding guidelines for novel proteins create formulation uncertainty and extended product development cycles.
- Legacy ERP Integration:Lot-tracking investments required by evolving FDA mandates face friction with decades-old manufacturing execution systems common among regional producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Pet Treats Market |
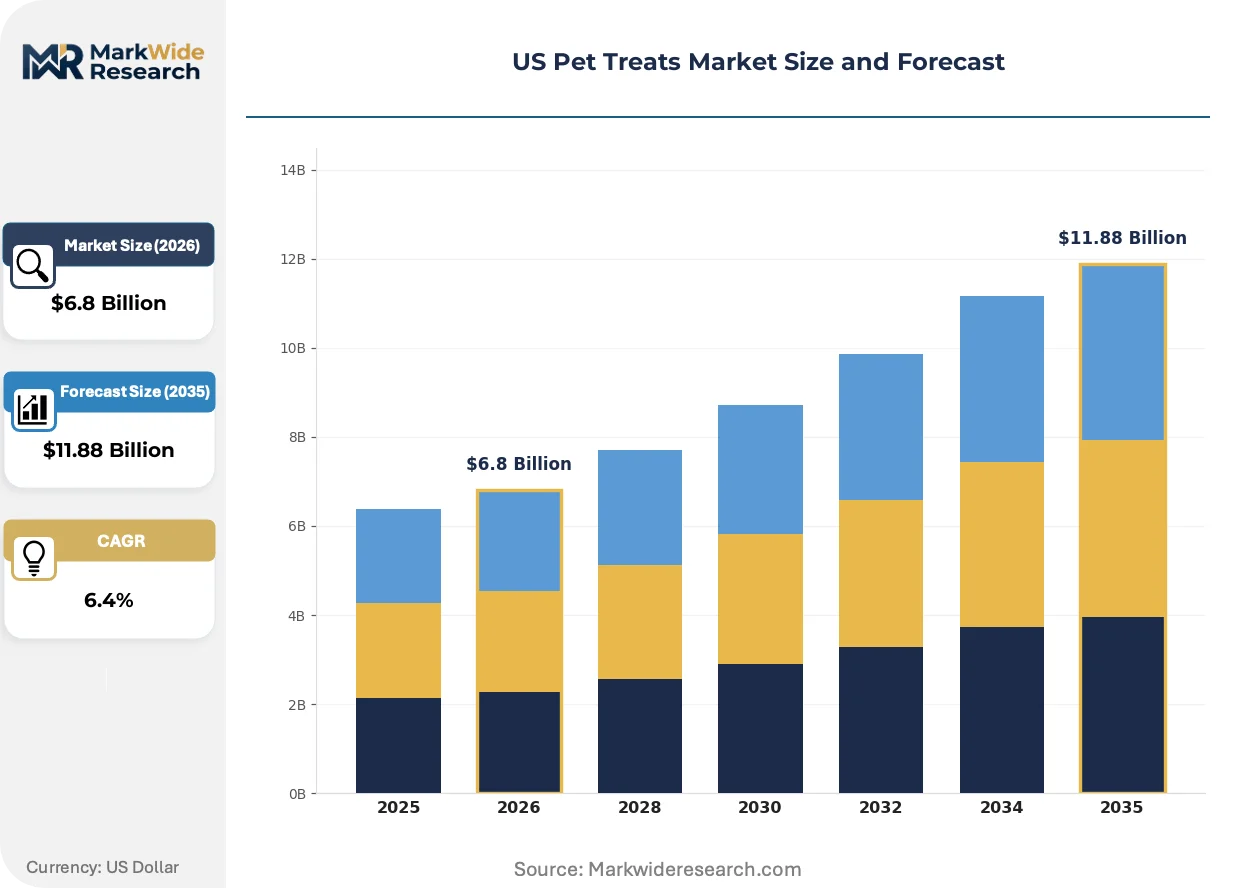
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biscuit, Jerky, Chews, Natural Ingredient Type: Meat-Based, Grain-Free, Organic, Byproducts Packaging Type: Bags, Tubs, Pouches, Boxes End User: Pet Owners, Retailers, Veterinarians, Distributors |
| Companies Covered | Colgate-Palmolive Company, Spectrum Brands Holdings, Mars Incorporated, Diamond Pet Foods, Central Garden & Pet, Nestlé Purina PetCare, General Mills, Wellness Pet Company, The J.M. Smucker Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Pet Treats Market Trends and Innovations
Reformulation investments are accelerating across the US pet treats landscape as manufacturers respond to simultaneous pressures from input cost volatility, evolving safety protocols, and shifting owner preferences toward functional positioning.
Cold-pressed dehydration technology is modularizing production economics for mid-scale manufacturers by enabling smaller batch sizes without the capital intensity of traditional extrusion lines. Regional specialty brands in the Pacific Northwest are adopting these systems to launch limited-ingredient SKUs with six-week development cycles. The technology is modularizing how formulation teams prototype, compressing time-to-shelf from quarters to weeks and eroding the scale advantages historically held by national brands.
The FDA's evolving adverse event reporting framework is reshaping supplier qualification protocols by mandating documented lot traceability from protein meal source through finished goods distribution. Domestic producers are responding by consolidating vendor panels and investing in blockchain-anchored documentation systems. Veterinary channel partners are now requiring this documentation as a condition of shelf placement, particularly for dental chew categories where safety incidents carry reputational risk.
Subscription auto-delivery is displacing periodic retail replenishment among urban millennial owners who prioritize convenience and portion control. Mars Incorporated's direct-to-consumer infrastructure captures this behavior through personalized replenishment algorithms, while specialty retailers counter with exclusive SKU strategies that limit price transparency. This channel rotation is most visible in California and New York metro areas where same-day delivery density supports recurring shipment economics.
US Pet Treats Market Segmentation
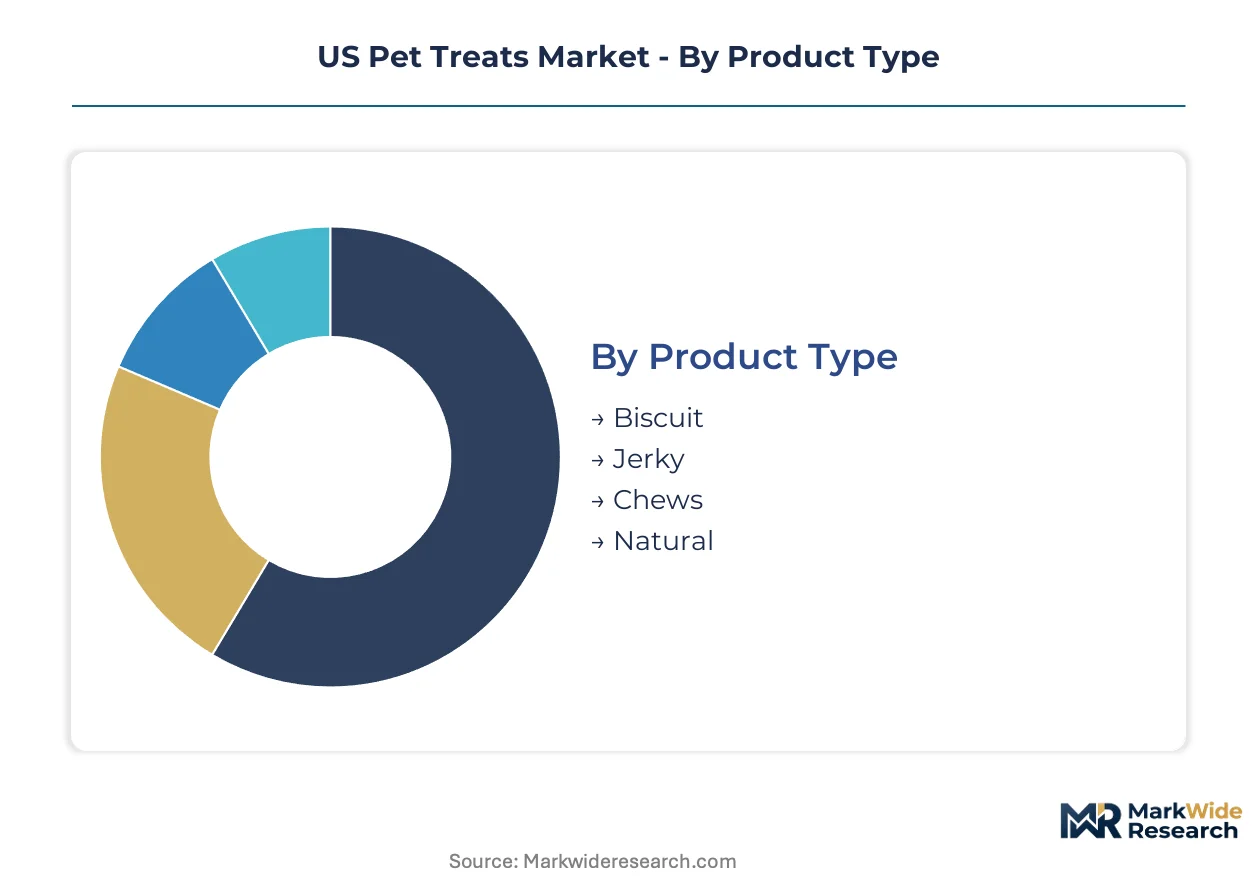
US pet treat manufacturers align capital deployment with segment-specific margin profiles and channel access requirements. Product format and ingredient positioning dictate extrusion equipment specifications, packaging automation needs, and cold-chain investments that fragment competitive economics across the value chain.
Product Type:
Extrusion line configurations vary dramatically across formats, with thermal processing intensity and dehydration cycle duration driving fixed asset requirements.
- Jerky:Low-moisture dehydration demands extended thermal cycles and precise humidity control systems that extend production runs. California coastal clusters concentrate demand for grain-free jerky SKUs where premium positioning offsets protein input volatility.
- Chews:Dental hygiene formulations require dual-stage extrusion with enzymatic additive integration at controlled temperature thresholds. Veterinary channel partnerships in the Northeast corridor bundle chews with wellness protocols, creating recurring prescription-driven demand.
- Biscuit:Mature volume channels with standardized equipment footprints and thinner margin profiles.
- Natural:Limited-ingredient positioning with shorter production runs and higher per-unit overhead absorption.
Most installed capacity flows through Biscuit. Expansion is steepest in Jerky.
Ingredient Type:
Raw material qualification protocols and supplier consolidation requirements reshape procurement economics differently across protein sourcing strategies.
- Meat-Based:Poultry meal concentration in Midwest rendering capacity forces coastal manufacturers to absorb freight rate volatility and foreign supplier qualification delays. FDA adverse event reporting mandates now require documented lot traceability from protein source through finished goods.
- Grain-Free:FDA investigations linking certain formulations to canine dilated cardiomyopathy triggered veterinarian channel withdrawal, compressing shelf presence in specialty retail. Reformulation investments now redirect toward legume-free positioning.
- Organic:USDA certification compliance adds audit layers that extend supplier onboarding timelines.
- Byproducts:Rendering economics favor regional sourcing within 200-mile radii of production facilities.
Procurement is shifting most aggressively in Grain-Free. Margin stability concentrates in Meat-Based.
Packaging Type:
Automation compatibility and shelf-life extension properties determine capital allocation across primary packaging formats.
- Pouches:Flexible film structures with reseal features dominate subscription auto-delivery channels where portion control and freshness signaling matter. Mars Incorporated's direct-to-consumer infrastructure leverages pouch formats for personalized replenishment algorithms.
- Bags:High-speed form-fill-seal lines achieve lowest per-unit labor content in biscuit and bulk treat categories. Northeast corridor specialty retailers favor bag formats for shelf-stable inventory turns.
- Tubs:Rigid container automation requires higher capital intensity with limited format flexibility.
- Boxes:Secondary packaging for premium gift assortments with manual assembly dependencies.
Equipment utilization peaks in Bags. Format innovation concentrates in Pouches.
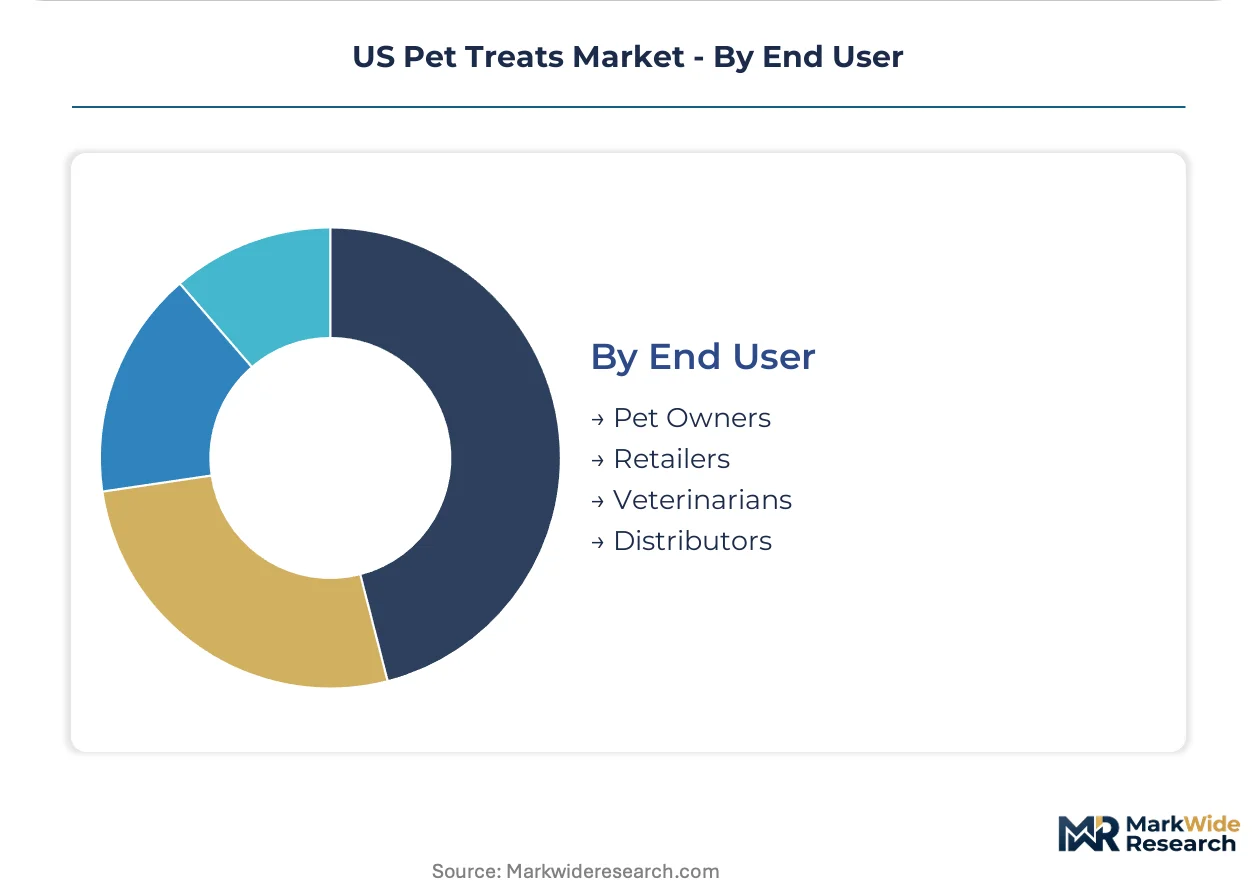
End User:
Channel-specific service requirements and order pattern predictability segment working capital needs and customer acquisition economics.
- Pet Owners:Direct-to-consumer subscription models transform single-transaction relationships into recurring revenue with predictable demand forecasting. California and New York metro areas support same-day delivery density that enables auto-replenishment economics.
- Veterinarians:Wellness protocol bundling creates prescription-driven treat recommendations with professional endorsement value. Nestlé Purina PetCare anchors shelf presence through exclusive veterinary channel partnerships that limit competitive access.
- Retailers:Slotting fee structures and promotional calendar coordination absorb manufacturer trade spending.
- Distributors:Consolidated freight and warehousing services with inventory ownership transfer at delivery.
Customer lifetime value concentrates in Veterinarians. Acquisition cost efficiency favors Pet Owners.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migration patterns within the US track regulatory cost differentials between state feed control programs, with California's stringent California Department of Food and Agriculture enforcement pushing mid-scale manufacturers toward more permissive jurisdictions while coastal demand clusters retain premium pricing power.
California
Los Angeles and San Francisco metro areas concentrate subscription auto-delivery demand among millennial pet owners. California Department of Food and Agriculture labeling requirements exceed federal baselines, forcing reformulation investments. San Diego County hosts specialty retail distribution hubs serving Pacific Coast premium positioning.
Northeast Corridor
Boston and Philadelphia independent pet specialty doors show underpenetrated white space for veterinary-exclusive protocols. FDA Center for Veterinary Medicine adverse event reporting mandates elevate compliance investment. New York Metro same-day delivery density enables recurring shipment economics for direct-to-consumer channels.
Pacific Northwest
Seattle and Portland urban clusters favor limited-ingredient SKUs with shorter production cycles. State-level feed control regulations in Washington and Oregon create moderate compliance terrain. Regional specialty brands adopt cold-pressed dehydration systems for rapid prototyping.
Midwest
Illinois and Ohio rendering capacity constraints force coastal manufacturers to absorb freight volatility. USDA labeling standards intersect with state feed regulations. Chicago distribution hubs consolidate poultry meal supply chains for national biscuit production.
Southeast
Florida and Georgia growth corridors show expanding veterinary channel partnerships. State feed control programs maintain lighter enforcement profiles than coastal jurisdictions. Atlanta distribution nodes serve expanding specialty retail penetration in Sun Belt metros.
US Pet Treats Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with consolidated multinational portfolios dominating veterinary and mass retail channels while regional specialists capture premium positioning in independent pet specialty. Three archetypes define competitive structure: diversified consumer goods conglomerates with captive pet divisions, pure-play pet food specialists with veterinary channel anchoring, and emerging direct-to-consumer brands with subscription infrastructure. M&A activity concentrates on veterinary clinic network acquisitions and cold-pressed dehydration technology licensing.
Within the conglomerate tier, Mars Incorporated and Nestlé Purina PetCare exemplify scale-driven positioning through direct-to-consumer infrastructure and veterinary channel bundling respectively. General Mills occupies specialty retail exclusivity archetypes. Among pure-play specialists, Diamond Pet Foods and Wellness Pet Company represent regional manufacturing concentration and natural ingredient positioning. Colgate-Palmolive Company and Spectrum Brands Holdings anchor diversified consumer goods portfolios with pet care divisions.
| Leading Market Players |
|---|
| Colgate-Palmolive Company |
| Spectrum Brands Holdings |
| Mars Incorporated |
| Diamond Pet Foods |
| Central Garden & Pet |
| Nestlé Purina PetCare |
| General Mills |
| Wellness Pet Company |
| The J.M. Smucker Company |
| Others |
Pricing and Supply Chain Analysis
Subscription-to-retail bifurcation separates premium direct-to-consumer pricing from mass-market transactional economics, with Mars Incorporated's auto-replenishment algorithms commanding margin premiums while biscuit producers absorb slotting fee compression in conventional retail. California's lot-tracking mandates and FDA adverse event reporting requirements reshape supplier qualification costs differently across these tiers, forcing mid-scale manufacturers toward either premium positioning or contract manufacturing exits.
Pricing Analysis
Direct-to-consumer subscription discounts bypass distributor margin layers entirely, while veterinary channel bundling supports premium markups through Nestlé Purina PetCare's wellness protocol anchoring. Three-tier pricing structure across premium, standard, and economy levels stratifies by ingredient certification grade and channel exclusivity. Pricing pressure stems from protein input volatility compressing meat-based segment returns. Mass retail buyers exhibit highest price sensitivity; veterinary-exclusive purchasers show lowest.
Supply Chain Analysis
Domestic-content rules under California Department of Food and Agriculture labeling requirements and FDA traceability mandates are consolidating vendor panels toward qualified domestic renderers. Supply concentration centers on Illinois and Ohio poultry meal rendering, with coastal manufacturers absorbing freight volatility from Midwest sources. Raw material dependencies include poultry meal, starches, and functional additives. Single-source vulnerability runs through concentrated rendering capacity. Distribution runs through San Diego and Chicago hub consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in cold-pressed dehydration technology licensing and veterinary channel bundling, as protein input volatility forces cost structure differentiation between premium subscription and commodity retail tiers.
For Market Incumbents: Acquire cold-pressed dehydration technology licensing to modularize production economics against emerging Pacific Northwest regional specialists. Consolidate vendor panels to meet FDA lot-tracking mandates before California serialization requirements take effect. Backward integration into Midwest rendering capacity mitigates poultry meal freight exposure. For New Entrants and Emerging Players: FDA Center for Veterinary Medicine adverse event reporting evolution opens a window for blockchain-anchored documentation specialists serving veterinary channel compliance demands. Target underpenetrated Boston and Philadelphia independent pet specialty doors with limited-ingredient SKUs. Launch through subscription auto-delivery infrastructure to bypass slotting fee barriers. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-scale producers lack dedicated regulatory affairs functions to absorb overlapping FDA, USDA, and state feed control compliance burdens. Long-term viability favors manufacturers with existing serialization infrastructure and veterinary channel anchoring. Watch California lot-tracking mandate enforcement timing as inflection indicator for competitive moat formation.| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Channel Partnership | Nestlé Purina PetCare's wellness protocol bundling creates prescription-driven recurring demand with professional endorsement value. |
| Cold-Pressed Dehydration Licensing | Pacific Northwest regional brands compress development cycles from quarters to weeks using modular production systems. |
| Direct-to-Consumer Infrastructure | Mars Incorporated's personalized replenishment algorithms capture subscription economics in California and New York metro areas. |
| Blockchain Traceability Investment | FDA mandates and veterinary channel requirements now condition shelf placement on documented lot documentation systems. |
| Specialty Retail Exclusivity | General Mills limits price transparency through exclusive SKU strategies in independent pet specialty doors. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with pet food manufacturing executives, veterinary channel procurement managers, specialty retail category buyers, and extrusion equipment specialists with secondary validation against FDA Center for Veterinary Medicine filings, USDA labeling standards, AAFCO nutrient profile databases, and customs trade records. Bottom-up segment modeling and top-down demand triangulation anchored value estimates.
Segment-weighting across product format, ingredient positioning, packaging automation compatibility, and end-user channel requirements shaped volume and value outputs across the analysis window. CAGRs derived from trend extrapolation of subscription penetration rates, protein input cost trajectories, and regulatory compliance investment cycles. Modeled inputs included millennial pet owner urban clustering patterns and cold-pressed dehydration technology adoption curves.
Revisions become necessary when FDA traceability mandate enforcement timelines shift, California Department of Food and Agriculture labeling requirements expand, or protein rendering capacity constraints trigger supply reallocations. Forecasts reflect documented assumptions about subscription auto-delivery penetration and veterinary channel bundling sustainability. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Japan Pet Boarding Market
Pet Care Products
Pet GPS Tracker Market
Pet Care Products
Canada Pet Boarding Market
Pet Care Products
Europe Organic Pet Food for Cats and Dogs Market
Pet Care Products
Pet Smart Tracker Market
Pet Care Products
Bird Cages and Accessories Market
Pet Care Products
Smart Pet Leash Market
Pet Care Products
Cat Litter Boxes Market
Pet Care Products
Pet Shampoo Market
Pet Care Products
Dog Hoodies Market
Pet Care Products
Weight Management Dog Food Market
Pet Care Products
Philippines Pet Food Market
Pet Care Products
Pet Meal Kit Delivery Services Market
Pet Care Products
Outdoor Dog Bed Market
Pet Care Products
Pet Hair Care Market
Pet Care Products
UAE Dog Food Market