
 China Catalog Market | 2026-2036
China Catalog Market Size, Share, and Industry Trends Forecast 2026-2036
China Catalog Market Insights
Manufacturing procurement is decoupling from traditional print-based sourcing as industrial buyers migrate to digital channels. JD.com anchors its position through captive logistics infrastructure serving enterprise catalog fulfillment. Taobao leverages merchant density to dominate small-business catalog discovery. Pinduoduo competes on agricultural and industrial supply aggregation, extending its catalog reach into lower-tier cities.
A catalog is a structured product listing system, historically print-based but now predominantly digital, containing standardized item descriptions, pricing matrices, SKU identifiers, and procurement terms for commercial ordering. Digital catalogs incorporate searchable databases, real-time inventory APIs, and multimedia specifications to streamline B2B and B2C transactions. Print catalog formats retain niche demand in trade show and direct mail channels where tactile engagement supports high-consideration purchases. E-commerce platform distribution channels capture the dominant transaction flow, while interactive catalog formats with embedded configurators command premium positioning among business customer segments.
China's MIIT sets data handling and cloud service standards that constrain foreign-hosted catalog platforms, while SAMR enforces anti-monopoly provisions affecting platform catalog aggregation practices. The country's GB standards framework mandates product information accuracy in commercial listings, creating compliance costs for cross-border catalog operators. Stakeholders must monitor evolving data localization rules and platform interoperability requirements that will determine catalog technology architecture decisions.
Market Dynamics
China's MIIT cloud computing standards are forcing catalog platform operators to re-architect data infrastructure, while manufacturing procurement migrates from print to searchable digital databases with real-time inventory APIs.
Growth Catalysts
- MIIT Data Localization Mandates:Domestic hosting requirements for commercial transaction data are accelerating platform migration to state-certified cloud providers, creating captive demand for compliant catalog infrastructure.
- Yangtze River Delta Manufacturing Density:Industrial clusters in Jiangsu and Zhejiang provinces generate concentrated B2B catalog volume as procurement digitizes across automotive and electronics supply chains.
- Small-Medium Enterprise Procurement Expansion:SMBs are adopting digital catalogs for indirect materials sourcing, with Taobao's merchant density enabling discovery at scale previously reserved for large enterprises.
Market Restraints
- GB Standards Compliance Costs:Mandatory product information accuracy requirements in commercial listings impose documentation burdens on cross-border catalog operators unfamiliar with China's technical specifications framework.
- Platform Concentration Risk:JD.com's captive logistics infrastructure and Taobao's merchant lock-in create switching friction for enterprise buyers seeking multi-source catalog access.
- Print-to-Digital Transition Friction:High-consideration industrial purchases in heavy machinery segments retain tactile catalog dependency for specification validation, slowing full digitization.
Strategic Opportunities
- Lower-Tier City Industrial Supply:Pinduoduo's agricultural and industrial supply aggregation model extends catalog reach into manufacturing hubs beyond coastal provinces, accessing underpenetrated procurement demand.
- Interactive Configurator Integration:Embedded product configurators in digital catalogs command premium positioning among business customer segments requiring specification customization before order commitment.
- SAMR Anti-Monopoly Enforcement:Platform catalog aggregation practices face regulatory scrutiny, creating openings for specialized vertical catalog operators to compete against horizontal platform dominance.
Industry Challenges
- API Integration Complexity:Legacy ERP systems in state-owned manufacturing enterprises resist real-time inventory API connectivity, forcing catalog platforms to maintain hybrid digital-print fulfillment workflows.
- Data Sovereignty Architecture:Dual carbon goals and evolving MIIT cloud service standards require continuous platform re-engineering, consuming technical resources that could advance catalog feature development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Catalog Market |
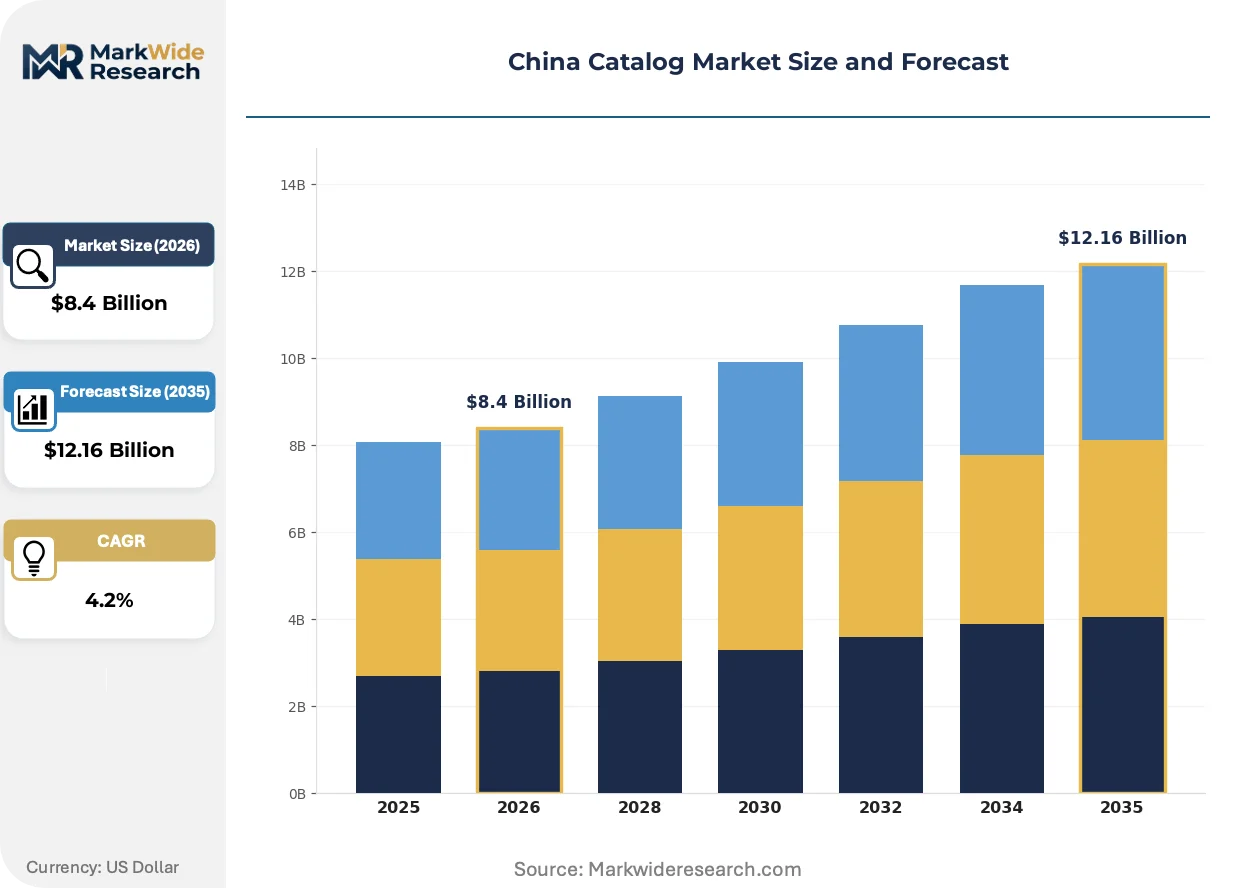
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $12.16 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Print Catalog, Digital Catalog, Interactive Catalog, Online Brochure Distribution Channel: Retail Stores, E-commerce Platforms, Direct Mail, Trade Shows Customer Type: Consumers, Businesses, Educational Institutions, Government Agencies Catalog Format: PDF, HTML, Mobile App, Video Catalog |
| Companies Covered | Taobao, Tmall, JD.com, Pinduoduo, Suning.com, Dangdang, YHD.com, Douyin, Yiwu International Trade City, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Catalog Market Trends and Innovations
Catalog technology is absorbing artificial intelligence for specification matching, while regulatory pressure on data handling reshapes platform architecture and buyer behavior fragments across procurement channels.
AI-powered specification search is absorbing natural language processing to convert unstructured buyer queries into structured SKU identification. Industrial procurement teams in automotive and electronics verticals are adopting these tools to compress supplier discovery cycles. The technology is absorbing manual catalog navigation workflows, compressing the role of traditional sales intermediaries in initial supplier qualification.
MIIT's cloud computing standards are tightening data handling requirements for commercial transaction platforms. Foreign-hosted catalog operators must migrate to domestic infrastructure or exit the market, creating structural advantage for locally-architected competitors. Manufacturing procurement departments are prioritizing platforms with state-certified data localization to ensure supply chain continuity under enforcement.
Buyer behavior is fragmenting across direct platform procurement and embedded catalog discovery within enterprise software workflows. Industrial purchasers increasingly initiate sourcing through ERP-integrated catalog APIs rather than standalone platform visits. This pattern concentrates in Yangtze River Delta manufacturing clusters where digital infrastructure maturity supports system-to-system procurement automation.
China Catalog Market Segmentation
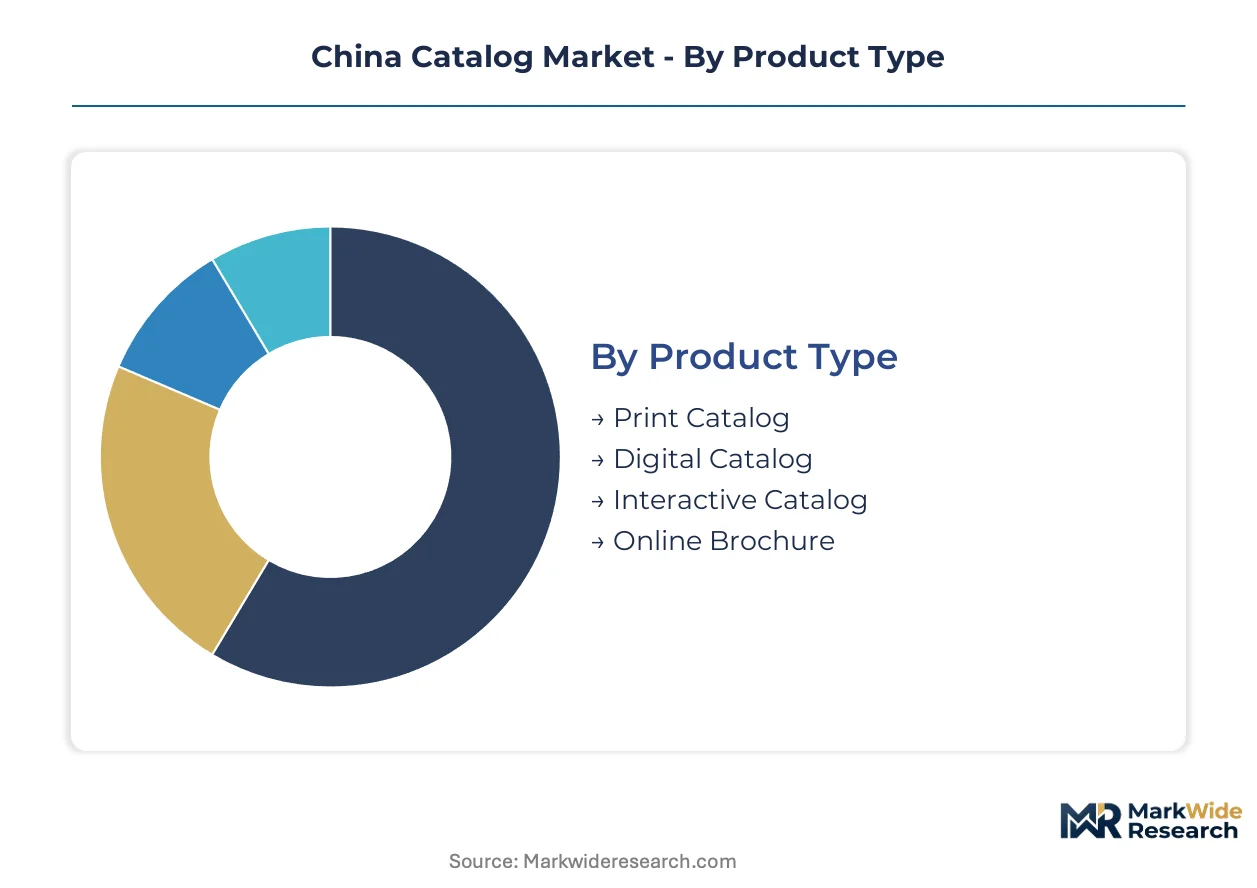
Catalog segmentation in China reflects divergent compliance obligations across product formats and distribution channels. MIIT data localization rules and GB standards accuracy requirements create tiered certification burdens that reshape platform architecture decisions for each segment.
Product Type:
Digital catalog formats trigger MIIT cloud computing certification requirements, while print catalogs face lighter documentation under GB product information standards.
- Print Catalog:Physical product listings with standardized item descriptions and pricing matrices retain niche demand in heavy machinery procurement. Yangtze River Delta manufacturing clusters sustain tactile catalog dependency for specification validation where high-consideration purchases resist full digitization.
- Digital Catalog:Searchable databases with real-time inventory APIs dominate B2B transaction flow. Small and medium enterprises in Jiangsu and Zhejiang provinces drive volume as procurement digitizes across automotive and electronics supply chains.
- Interactive Catalog:Embedded product configurators command premium positioning among business customer segments requiring specification customization before order commitment.
- Online Brochure:Lightweight digital formats serve consumer discovery and lower-consideration procurement with reduced API integration requirements.
Digital Catalog sits at the top of the volume ranking, with Interactive Catalog climbing the fastest.
Distribution Channel:
Channel selection determines data sovereignty architecture costs, with e-commerce platforms absorbing the heaviest MIIT compliance investments.
- E-commerce Platforms:JD.com's captive logistics infrastructure and Taobao's merchant density anchor enterprise catalog fulfillment. Platform concentration creates switching friction for buyers seeking multi-source access.
- Direct Mail:Print-to-digital transition friction concentrates in trade show and direct mail channels where tactile engagement supports high-consideration purchases.
- Retail Stores:Physical distribution points serve consumer segments with limited digital infrastructure access in lower-tier cities.
- Trade Shows:Tactile catalog formats retain procurement workflow significance for industrial machinery specification validation.
E-commerce Platforms capture the dominant transaction share, with Direct Mail contracting most sharply.
Customer Type:
Procurement digitization maturity varies sharply across customer categories, fragmenting catalog feature requirements.
- Businesses:ERP-integrated catalog APIs concentrate in Yangtze River Delta manufacturing clusters where system-to-system automation compresses supplier discovery cycles. Industrial procurement teams prioritize platforms with state-certified data localization.
- Consumers:Discovery-driven catalog usage dominates on Taobao's merchant-dense platform, with mobile-first formats capturing transaction flow.
- Educational Institutions:Standardized procurement workflows favor PDF and HTML catalog formats with simplified compliance requirements.
- Government Agencies:State-owned enterprise legacy ERP systems resist real-time inventory API connectivity, forcing hybrid digital-print fulfillment workflows.
Businesses generate the highest catalog transaction volume, with Government Agencies expanding most slowly due to integration complexity.
Catalog Format:
Format selection dictates technical architecture investment and API compatibility requirements across procurement workflows.
- Mobile App:Pinduoduo's agricultural and industrial supply aggregation extends catalog reach into lower-tier city manufacturing hubs beyond coastal provinces.
- HTML:Browser-based catalogs enable embedded configurators and real-time inventory display without native application deployment.
- PDF:Static formats persist in educational and government procurement where system integration requirements remain limited.
- Video Catalog:Multimedia specifications streamline complex product visualization for high-consideration industrial purchases.
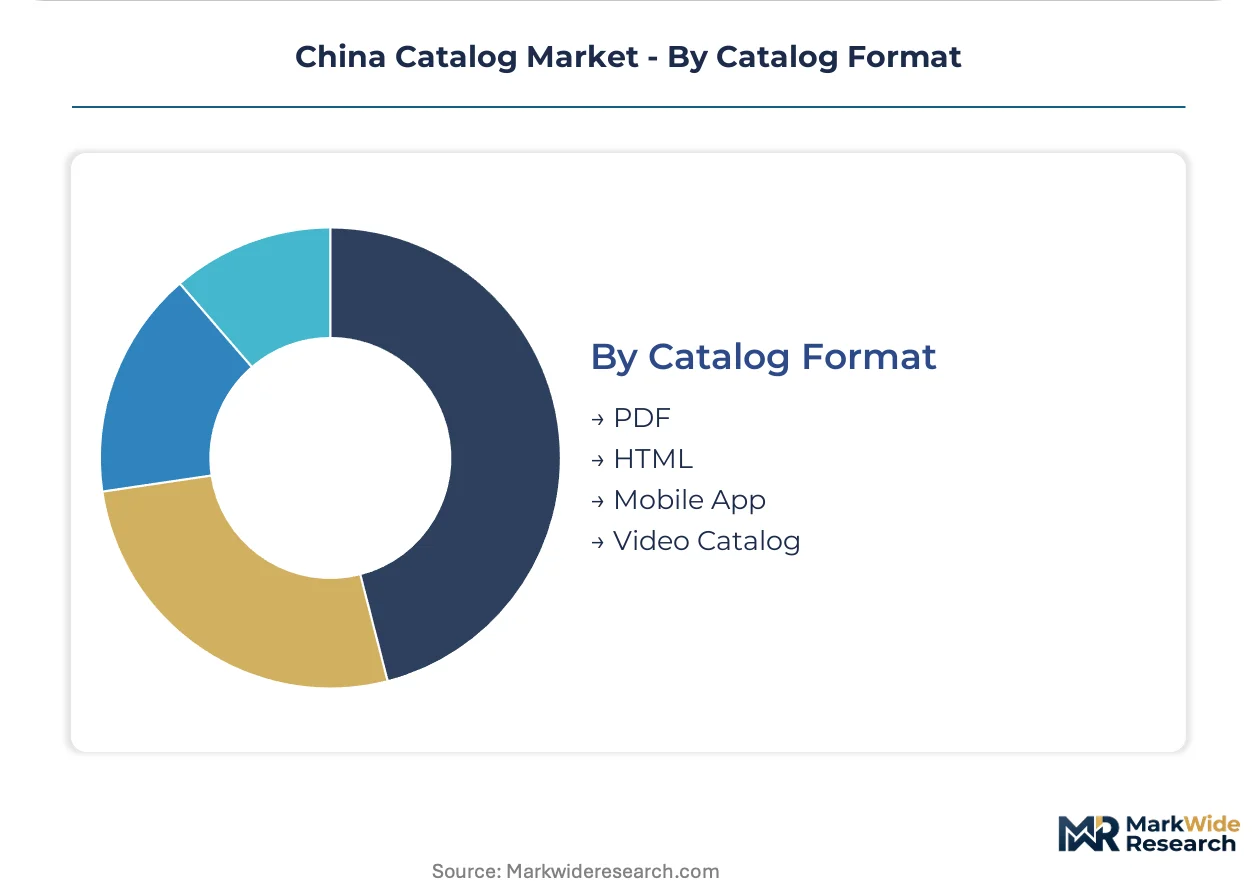
HTML formats hold the broadest deployment base, with Mobile App gaining share fastest in lower-tier city penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping catalog platform architecture as data localization mandates force infrastructure migration toward state-certified cloud providers, compressing cost-of-compliance gaps between domestic and foreign-hosted operators.
Yangtze River Delta
Jiangsu and Zhejiang provinces generate concentrated B2B catalog volume through automotive and electronics supply chain digitization. MIIT cloud computing standards require state-certified data infrastructure for platforms serving manufacturing procurement clusters. Suzhou and Hangzhou anchor industrial catalog demand as ERP-integrated APIs compress supplier discovery cycles across dense supplier networks.
Pearl River Delta
Guangdong's export-oriented manufacturing base drives cross-border catalog transaction flow through integrated logistics corridors. SAMR anti-monopoly enforcement scrutinizes platform catalog aggregation practices affecting merchant access. Shenzhen and Dongguan concentrate small-medium enterprise procurement digitization, with mobile-first catalog formats capturing lower-tier city penetration.
Beijing-Tianjin-Hebei
State-owned enterprise procurement modernization creates hybrid digital-print fulfillment demand due to legacy ERP integration complexity. GB standards mandate product information accuracy in commercial listings, imposing documentation burdens on catalog operators. Beijing's technology policy concentration shapes national catalog compliance architecture through MIIT standards development.
Sichuan-Chongqing
Western China manufacturing relocation absorbs catalog platform expansion beyond coastal infrastructure concentration. Dual carbon goals and evolving data sovereignty rules require continuous platform re-engineering for regional operators. Chengdu anchors industrial supply aggregation as Pinduoduo extends agricultural and industrial catalog reach into interior procurement markets.
Shandong Peninsula
Heavy machinery procurement retains tactile catalog dependency for specification validation, resisting full digitization in high-consideration purchase segments. Provincial industrial clusters sustain print-to-digital transition friction. Qingdao and Jinan concentrate trade show and direct mail catalog distribution where physical specification review supports complex equipment sourcing.
China Catalog Market Competitive Landscape
Platform infrastructure investment dominates the current landscape as operators re-architect data systems for MIIT compliance. The market exhibits tiered concentration around captive logistics networks and merchant density advantages. Three strategic archetypes anchor competitive positioning: horizontal marketplace aggregators, vertical supply chain integrators, and social commerce discovery engines. M&A activity and state-certified cloud migration represent the dominant competitive moves as operators secure compliant infrastructure.
Among horizontal marketplace aggregators, Taobao and JD.com exemplify the merchant-density and logistics-captive archetypes respectively, while Pinduoduo occupies a position representing lower-tier city and agricultural-industrial supply aggregation. These three platforms collectively anchor the competitive structure, with each representing distinct procurement channel specialization within the broader catalog ecosystem.
| Leading Market Players |
|---|
| Taobao |
| Tmall |
| JD.com |
| Pinduoduo |
| Suning.com |
| Dangdang |
| YHD.com |
| Douyin |
| Yiwu International Trade City |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between MIIT-compliant state-certified cloud hosting and uncertified foreign infrastructure manifests in both pricing premiums and supply chain re-architecture decisions for catalog platform operators. Platform operators absorbing domestic cloud migration costs pass compliance premiums to enterprise buyers, while SMB-facing channels compress margins through merchant-density advantages.
Pricing Analysis
Platform-retailer markup layers dominate catalog distribution economics, with JD.com's captive logistics infrastructure commanding fulfillment premiums against Taobao's merchant-density-driven compression. Three-tier pricing structure across premium configurators, standard searchable databases, and economy-grade online brochures reflects integration depth and API sophistication. Pricing pressure stems from Pinduoduo's agricultural-industrial aggregation model extending into manufacturing procurement. Government agencies exhibit lowest price sensitivity due to legacy ERP lock-in, while SMBs drive aggressive discounting through multi-platform comparison.
Supply Chain Analysis
Regional distribution center placement tracks Yangtze River Delta manufacturing density, with Suzhou and Hangzhou anchoring hub-and-spoke fulfillment networks serving automotive and electronics supply chains. Cloud infrastructure provisioning draws from domestic state-certified providers including Alibaba Cloud, Huawei Cloud, and Tencent Cloud under MIIT mandates. Raw material dependencies center on server hardware components, data center construction materials, and logistics fleet assets. Single-source vulnerability concentrates in state-certified cloud certification pathways. Distribution runs through e-commerce platform APIs integrated with enterprise ERP systems, supplemented by hybrid print-digital workflows for state-owned enterprise procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in China's catalog market rests on compliance-cost recovery through premium-tier platform positioning and operational leverage from merchant-density scale. Platform operators capturing MIIT-certified infrastructure advantages command pricing power against foreign-hosted competitors facing exit pressure.
For Market Incumbents: Lock in enterprise buyer relationships through ERP-integrated catalog APIs that increase switching costs. Deepen captive logistics infrastructure in Yangtze River Delta clusters to defend against Pinduoduo's lower-tier city expansion. Prioritize state-certified cloud certification investment to maintain supply chain continuity under tightening MIIT enforcement. Counter emerging vertical catalog operators exploiting SAMR anti-monopoly scrutiny through exclusive supplier contracts.
For New Entrants and Emerging Players: AI-powered specification search technology offers entry wedge against incumbent platform search limitations. Target heavy machinery procurement segments retaining tactile catalog dependency, where embedded product configurators command premium positioning. White-space opportunity concentrates in Shandong Peninsula industrial equipment sourcing and Sichuan-Chongqing manufacturing relocation corridors. Go-to-market angle should emphasize ERP integration simplicity for state-owned enterprises resisting legacy system replacement.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized vertical catalog operators possessing MIIT-compliant infrastructure and deep automotive or electronics vertical expertise. Long-term viability favors platforms with merchant-density network effects and captive logistics assets. Acquisition target archetype: mid-scale operators with state-certified cloud architecture serving underpenetrated lower-tier city manufacturing hubs. Signal to watch: SAMR enforcement actions creating structural openings for non-horizontal competitors.
| Strategic Initiative | Industry Significance |
|---|---|
| State-Certified Cloud Migration | MIIT compliance secures supply chain continuity for enterprise catalog transactions under tightening data localization enforcement. |
| ERP-Integrated API Development | System-to-system procurement automation captures Yangtze River Delta manufacturing cluster volume from standalone platform visits. |
| Interactive Configurator Deployment | Embedded customization tools command premium positioning among business customers requiring specification validation before commitment. |
| Lower-Tier City Logistics Expansion | Pinduoduo's agricultural-industrial aggregation model extends catalog reach into interior manufacturing hubs beyond coastal infrastructure concentration. |
| Vertical Catalog Specialization | SAMR anti-monopoly scrutiny of horizontal platform aggregation creates structural openings for focused automotive and electronics operators. |
Research Methodology
Bottom-up enterprise procurement modeling reconciled against top-down platform transaction tracking forms the analytical core of this study. Primary interviews with catalog platform product managers, MIIT compliance officers, manufacturing procurement directors, cloud infrastructure architects, and SAMR policy specialists informed demand-side assumptions. Secondary validation drew from MIIT cloud service standard filings, SAMR anti-monopoly enforcement announcements, GB standards technical documentation, and provincial manufacturing cluster economic reports. Cross-referencing bottom-up segment builds against top-down platform disclosed metrics ensured triangulation integrity.
Historical trendline analysis across digital catalog adoption curves, print-to-digital transition rates, and platform infrastructure investment cycles established baseline growth patterns. The analytical framework models volume and value across product type, distribution channel, customer segment, and catalog format dimensions throughout the projection horizon. CAGRs derive from regression analysis of procurement digitization penetration rates and SMB adoption acceleration. Industry-specific forecast inputs include MIIT certification timeline assumptions and SAMR enforcement intensity scenarios affecting platform concentration dynamics.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to MIIT data localization rule evolution and dual carbon goal implementation pace. Assumptions reflect current regulatory trajectory and platform infrastructure commitment visibility. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Publishing
Ebook Publishing Platform Market
Digital Publishing
Digital Publishing Platforms Market
Digital Publishing
Global E-Book Market
Digital Publishing
Digital Music Publishing Market
Digital Publishing
Children Illustration Book Market
Digital Publishing
Book Publishers Market
Digital Publishing
Africa Catalog Market
Digital Publishing
US Newspaper Market
Digital Publishing
Middle East Catalog Market
Digital Publishing
France Catalog Market
Digital Publishing
Magazine Subscription Service Market
Digital Publishing
Japan Catalog Market
Digital Publishing
Comic Book Market
Digital Publishing
Adaptive Content Publishing Market
Digital Publishing
Europe E-Book Market
Digital Publishing
Books Market