
 Book Publishers Market | 2026-2036
Book Publishers Market Size, Share, and Industry Trends Forecast 2026-2036
Book Publishers Market Analysis
The EU Green Deal is consolidating sustainability expectations across European publishing supply chains, forcing printers and paper mills to certify carbon footprints. Penguin Random House LLC leverages its global distribution network to source FSC-certified paper at scale. Hachette Livre S.A. anchors its competitive position through deep relationships with French literary estates and institutional buyers. Scholastic Corporation dominates the North American school channel with curriculum-aligned publishing programs.
Book publishers acquire, edit, design, manufacture, and distribute bound or digital textual content for consumer, educational, and professional markets. Offset and digital printing remain standard production methods, with web-to-print workflows reducing inventory risk for mid-list titles. Fiction and non-fiction trade categories command the largest revenue pools, though audiobook format expansion is accelerating fastest as streaming platforms reshape consumer habits. Online retailers now capture the dominant share of volume, while brick-and-mortar stores concentrate margin in gift-oriented and children's segments.
EMA, ECHA, and the EU Green Deal framework collectively shape European market access through chemical safety rules for inks and binding adhesives, plus mandatory carbon disclosure for large publishers. The US EPA regulates volatile organic compound emissions from printing facilities, affecting domestic production economics. Stakeholders must monitor how platform-driven audiobook licensing terms and state-level curriculum standards in Texas and California reshape content investment priorities.
Market Dynamics
The EU Green Deal is compressing print production economics across European supply chains, forcing publishers to absorb carbon certification costs while maintaining price parity with digital alternatives. This regulatory pressure is accelerating format diversification and reshaping capital allocation toward lower-emission production technologies.
Growth Catalysts
- Audiobook platform licensing:Streaming services are expanding exclusive content deals with publishers, creating recurring revenue streams that offset physical print volatility. Educational institutions in India are scaling English-language digital procurement.
- REACH chemical compliance:ECHA mandates for ink and adhesive safety are standardizing European supply chains, eliminating non-compliant competitors and consolidating market access for certified publishers.
- Web-to-print workflows:On-demand manufacturing is reducing inventory risk for mid-list titles, enabling publishers to maintain backlist depth without warehousing exposure.
Market Restraints
- Pulp cost volatility:Scandinavian paper mills face energy price swings that transmit directly to print production margins, compressing profitability for offset-dependent publishers.
- Platform dependency:Amazon and Apple capture dominant ebook and audiobook distribution share, extracting terms that limit publisher pricing autonomy and customer data access.
- Textbook substitution:Open educational resources and institutional repository models are displacing traditional academic textbook adoptions in North American higher education.
Strategic Opportunities
- Indian English-language expansion:Rising disposable incomes and competitive examination culture are driving trade and academic publishing demand in Mumbai, Delhi, and Bangalore.
- FSC-certified premium positioning:EU Green Deal carbon disclosure requirements are creating differentiation value for publishers with verified sustainable sourcing credentials.
- Direct-to-consumer subscription models:Publishers are bypassing retail intermediaries through membership programs that bundle print, digital, and audio formats.
Industry Challenges
- Audiobook production talent scarcity:Narrator and studio engineer pipelines are constraining publisher capacity to meet platform-exclusive content commitments.
- Legacy ERP integration:Publishers with decades-old inventory and rights management systems face friction migrating to cloud-based analytics platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Book Publishers Market |
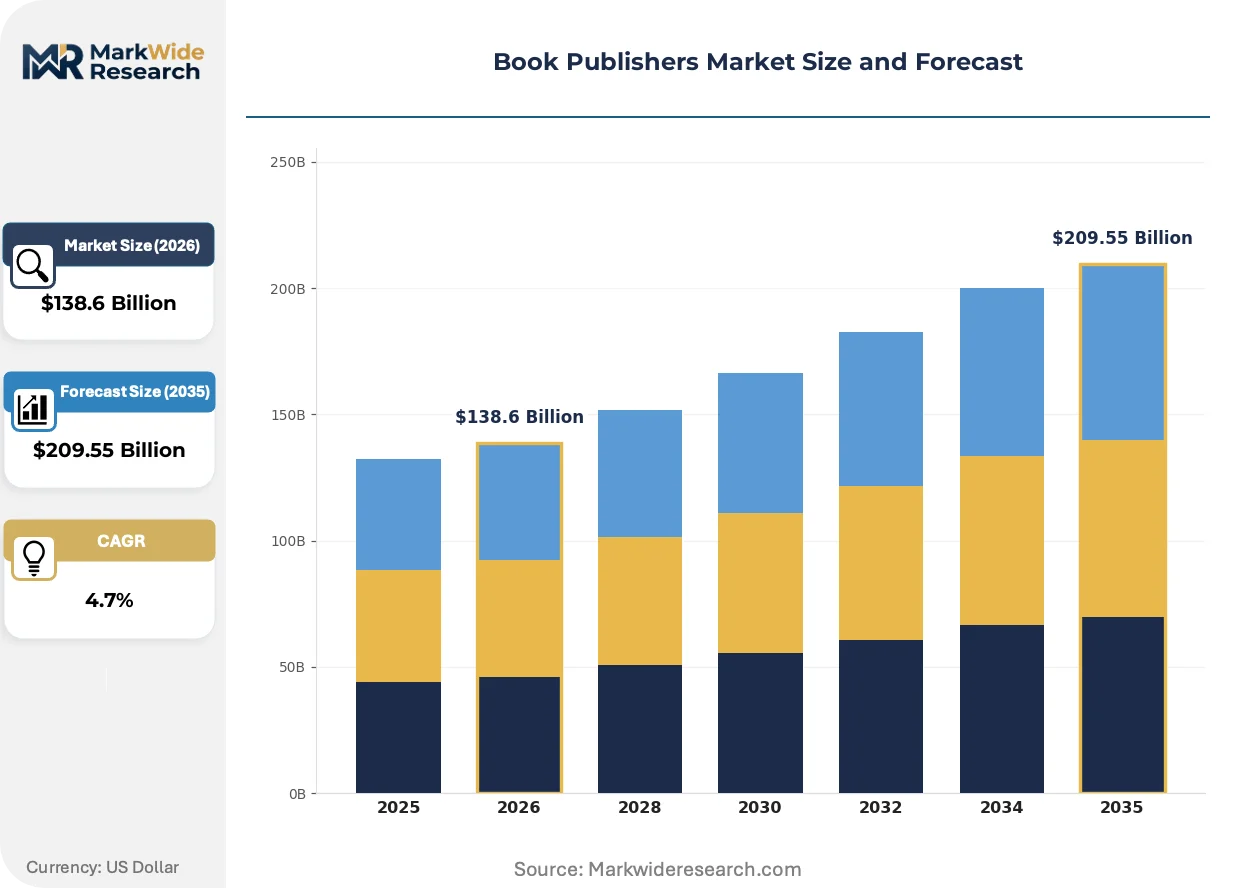
| Market Size in 2026 | $138.6 Billion |
| Market Size in 2035 | $209.55 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Publication Type: Fiction, Non-Fiction, Textbooks, Reference Distribution Channel: Online Retailers, Brick-and-Mortar Stores, Libraries, Direct Sales Format: Print, eBook, Audiobook, Digital Target Audience: Adults, Young Adults, Children, Academic Institutions |
| Companies Covered | Penguin Random House LLC, Hachette Livre S.A., HarperCollins Publishers LLC, Simon & Schuster, Macmillan Publishers Limited, Bertelsmann SE & Co. KGaA, Scholastic Corporation, Oxford University Press, John Wiley & Sons Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Book Publishers Market Emerging Trajectories
Artificial intelligence is compressing editorial and production timelines across trade publishing, while regulatory carbon accounting and shifting consumption patterns are forcing structural reinvention of content monetization models.
Generative AI tools for manuscript assessment and copyediting are electrifying pre-publication workflows. Mid-sized publishers are adopting these systems to reduce editorial overhead on genre fiction slates. The technology is enabling faster title throughput and compressing the traditional acquisition-to-publication cycle.
The EU Green Deal's mandatory carbon disclosure framework is reshaping European print economics. Large publishers must now certify supply chain emissions or face market access restrictions. German and French houses are responding by consolidating printing partnerships with FSC-certified mills and investing in domestic digital-first imprints.
Subscription bundling is displacing single-title purchasing among heavy readers. Audible and Spotify are capturing listener budgets that previously supported discrete audiobook sales. This shift is most visible in the US and UK, where platform penetration has reached saturation among commuting professionals and fitness-oriented consumers.
Book Publishers Market Segmentation
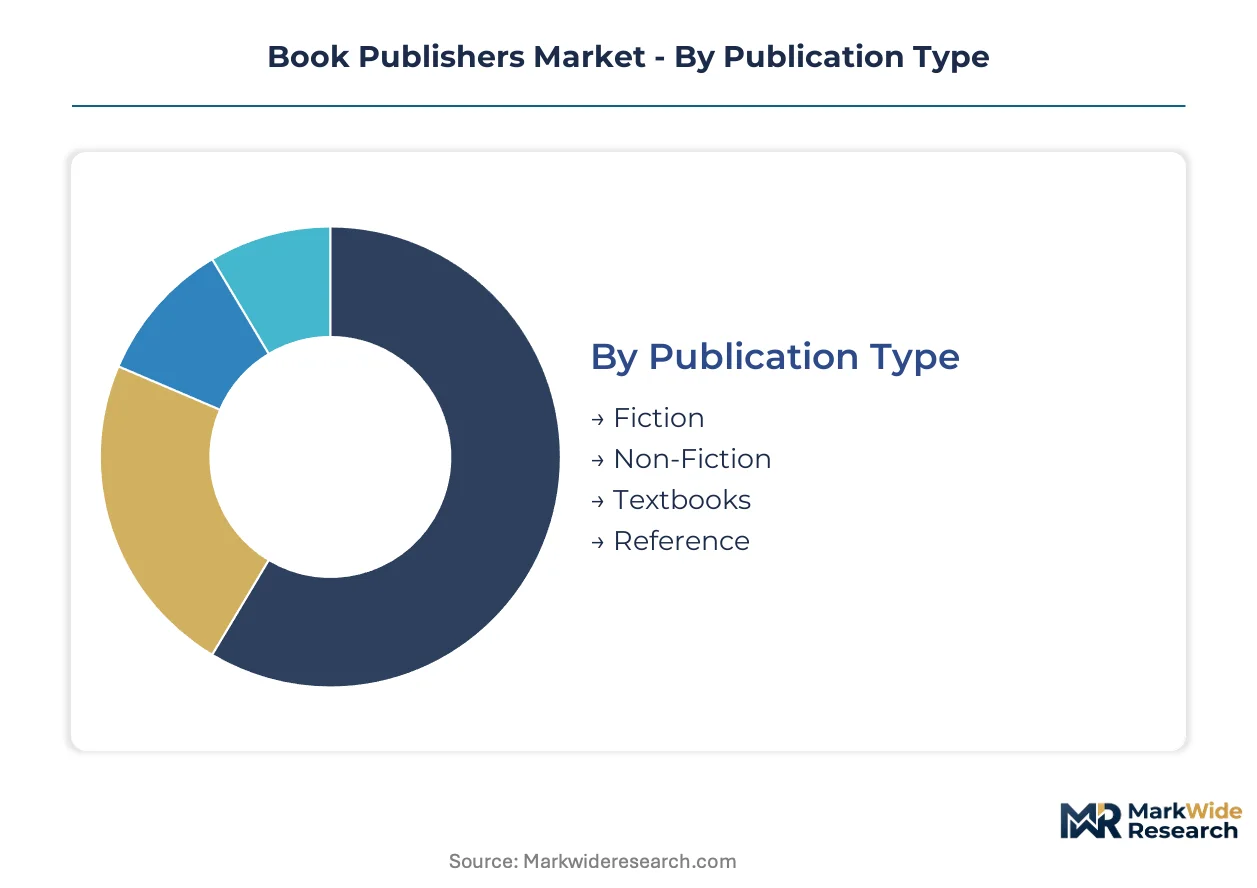
Book publishers structure their operations across four intersecting dimensions that determine content investment, production economics, and channel strategy. Each segmentation layer carries distinct margin profiles and regulatory exposure, forcing publishers to optimize portfolio mix rather than compete uniformly across all categories.
Publication Type:
Standalone categories operate as independent profit centers with dedicated editorial teams, while embedded formats like reference works integrate into institutional procurement systems with multi-year contract cycles.
- Fiction:Trade narratives spanning genre and literary categories command the largest consumer revenue pools. Demand clusters in English-language markets with established reading cultures, where streaming platform adaptations are accelerating backlist monetization through licensing surges.
- Non-Fiction:Biography, history, and popular science titles carry higher per-unit pricing and longer sales tails. The segment is gaining share fastest in India, where competitive examination culture and professional upskilling are driving English-language acquisition.
- Textbooks:Curriculum-aligned content bound to state and national standards, facing displacement pressure from open educational resources in North American higher education.
- Reference:Encyclopedic and professional reference works distributed through institutional licenses and library consortia, with digital subscriptions displacing print editions in academic and legal markets.
Volume placements concentrate in Fiction; the faster expansion belongs to Non-Fiction.
Distribution Channel:
Cost tier stratification separates high-touch physical retail from algorithm-driven digital discovery, with margin structures inverting between premium in-store experience and volume-driven online efficiency.
- Online Retailers:Algorithmic discovery platforms capture dominant volume share through personalized recommendation engines. Amazon and Apple extract terms that compress publisher pricing autonomy while limiting direct customer data access.
- Brick-and-Mortar Stores:Curated physical environments concentrate margin in gift-oriented segments and children's categories, where browse-driven impulse purchasing sustains premium pricing.
- Libraries:Institutional procurement through consortia and single-system acquisitions, with ebook lending terms under active renegotiation between publishers and platform intermediaries.
- Direct Sales:Publisher-controlled channels including subscription memberships and author event commerce, enabling first-party data capture and format bundling.
Revenue concentration sits with Online Retailers; Direct Sales is climbing the fastest as publishers bypass retail intermediaries.
Format:
Maturity gradients separate legacy print infrastructure from emerging digital-native production workflows, with capital allocation shifting toward lower-emission and higher-margin formats.
- Print:Offset and digital printing remain standard for frontlist trade titles, with web-to-print workflows reducing inventory risk. EU Green Deal carbon disclosure requirements are forcing FSC-certified sourcing investments.
- eBook:Reflowable and fixed-layout digital editions distributed through proprietary platforms and open standards, with pricing pressure from subscription bundling and platform exclusivity terms.
- Audiobook:Professional narration and audio production for streaming platform licensing. Narrator and studio engineer scarcity is constraining publisher capacity to meet exclusive content commitments.
- Digital:Interactive and enhanced digital content including educational platforms and professional databases, requiring continuous technical investment and cloud infrastructure.
Print still dominates volume placements; Audiobook is expanding most quickly as streaming platforms reshape consumption habits.
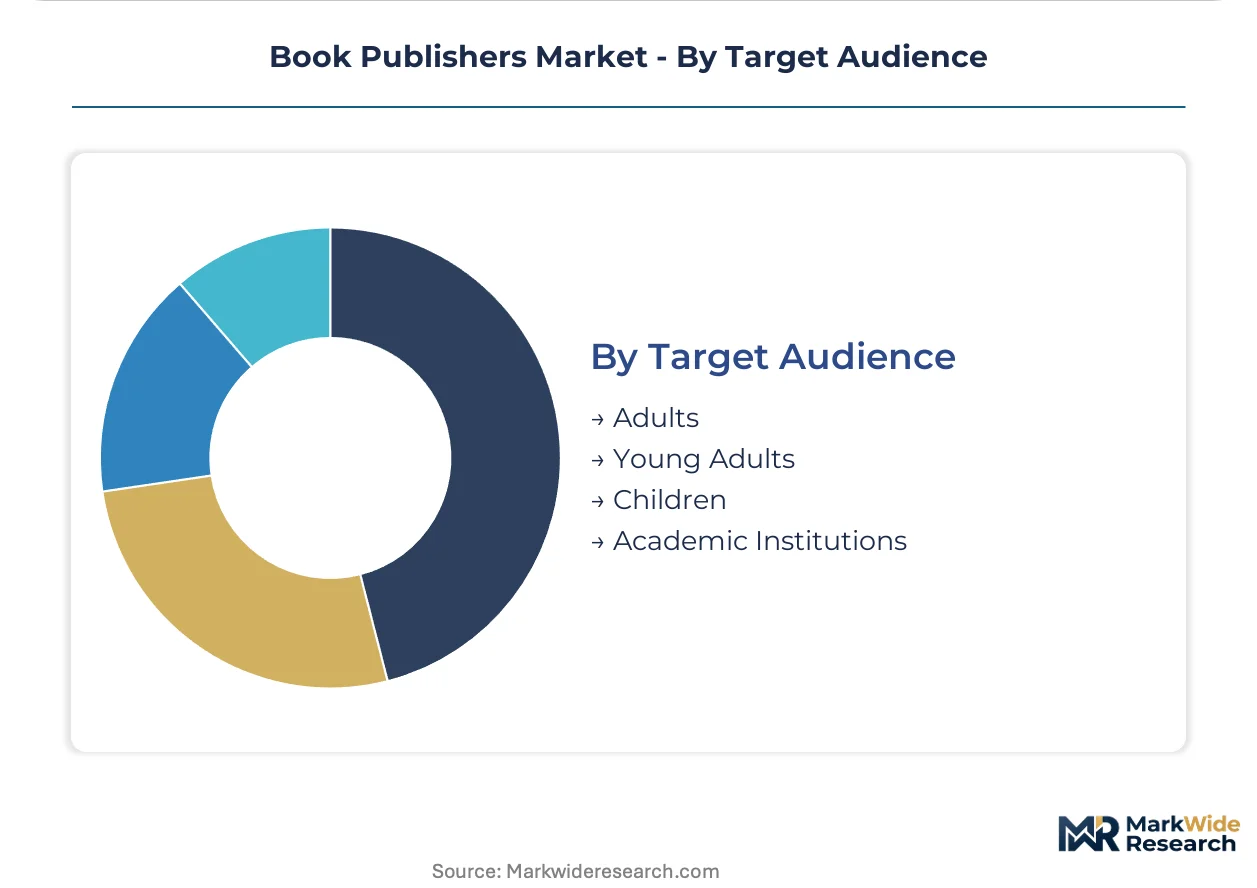
Target Audience:
Customer type determines content development cycles, with institutional buyers demanding curriculum alignment and compliance certification versus individual consumers driving discretionary purchasing.
- Adults:The largest addressable market spanning trade fiction, non-fiction, and professional development, with format preferences diverging by commuting patterns and device ownership.
- Young Adults:Crossover fiction and educational content positioned between children's and adult categories, with strong social media discovery dynamics and series-driven purchasing.
- Children:Illustrated formats and early reader programs with gift-purchase economics, concentrated in brick-and-mortar retail and school book fair channels.
- Academic Institutions:K-12 and higher education procurement governed by state-level standards in Texas and California, with digital adoption accelerating in Indian competitive examination markets.
Adults anchor volume placements; Academic Institutions show the steepest expansion trajectory in emerging markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mumbai anchors the fastest-growing English-language publishing corridor outside North America and Western Europe, with Delhi and Bangalore forming secondary concentration nodes. Regulatory frameworks and consumption patterns diverge sharply across major national markets.
United States
Texas and California state curriculum standards govern K-12 textbook procurement cycles, driving publisher investment in aligned content development. EPA volatile organic compound regulations constrain domestic printing facility economics. New York Metro houses the headquarters clusters of trade publishing majors and audiobook production studios.
United Kingdom
London's literary agency ecosystem feeds manuscript pipelines into global trade publishing operations. GDPR compliance requirements shape digital rights management and consumer data handling protocols. The Southeast England corridor concentrates audiobook narrator talent pools and post-production facilities.
Germany
REACH chemical safety mandates standardize ink and adhesive specifications across European supply chains. EU Green Deal carbon disclosure requirements force FSC-certified paper sourcing investments. Frankfurt anchors continental rights trading and the world's largest book fair infrastructure.
India
Competitive examination culture in Mumbai, Delhi, and Bangalore drives English-language academic and test-prep publishing demand. BIS quality certification requirements apply to imported educational materials. Noida and Chennai host expanding digital content production facilities serving institutional procurement.
France
Deep literary estate relationships sustain premium trade publishing economics in Paris. ANSM and CNIL frameworks govern consumer protection and data privacy in direct-to-consumer channels. The Île-de-France region concentrates editorial talent and illustrated book production expertise.
Book Publishers Market Vendor Landscape
The competitive structure tilts toward diversified media conglomerates with integrated print-digital-audio capabilities. Market access concentrates among houses with established distribution infrastructure and institutional procurement relationships. Three archetypes dominate: transnational trade publishers with global imprint portfolios; education specialists with curriculum-aligned content pipelines; and academic houses with subscription database models. Competitive moves center on audiobook platform exclusivity negotiations and direct-to-consumer subscription program launches.
Among transnational trade publishers, Penguin Random House LLC and Hachette Livre S.A. occupy positions reflecting scale-driven consolidation trajectories, while Scholastic Corporation exemplifies the education-specialist archetype with concentrated North American school channel penetration. These entities represent the structural tension between diversified conglomerate models and focused vertical strategies.
| Leading Market Players |
|---|
| Penguin Random House LLC |
| Hachette Livre S.A. |
| HarperCollins Publishers LLC |
| Simon & Schuster |
| Macmillan Publishers Limited |
| Bertelsmann SE & Co. KGaA |
| Scholastic Corporation |
| Oxford University Press |
| John Wiley & Sons Inc. |
| Others |
Supply Flow & Price Mechanics
Platform-dependent retailers anchor pricing power in the book publishers market, compressing publisher margins through algorithmic discounting while forcing trade houses toward subscription bundling to escape transactional commoditization.
Pricing Analysis
Per-title consumer willingness-to-pay sets the value-based pricing anchor for trade publishing, with streaming platform subscriptions displacing discrete unit economics. Three-tier pricing structure across premium hardcover, standard paperback, and economy mass-market levels stratifies by format durability and gift-purchase occasion. Pricing pressure stems from Amazon and Apple extracting favorable terms that limit publisher pricing autonomy. Academic institutions exhibit highest price sensitivity as open educational resources displace traditional textbook adoptions.
Supply Chain Analysis
Narrator and studio engineer scarcity in Southeast England and New York Metro constrains audiobook production capacity, forcing publishers toward exclusive platform licensing to secure talent commitments. Paper manufacturing draws from Scandinavian mills and Chinese producers, with FSC-certified sourcing becoming mandatory for EU market access. Single-source vulnerability concentrates in carbon-intensive offset printing partnerships facing EU Green Deal disclosure requirements. Distribution runs through Amazon's fulfillment network for volume efficiency, while brick-and-mortar retail concentrates margin in children's and gift segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The book publishers market functions as a vertical-integration race, with houses pursuing backward integration into direct-to-consumer subscription channels to escape platform dependency and reclaim customer data ownership.
For Market Incumbents: Deepen exclusive audiobook platform relationships to lock in narrator talent pipelines against production capacity constraints. Consolidate printing partnerships with FSC-certified mills in Germany and France to preempt EU Green Deal carbon disclosure enforcement. Anchor competitive position through curriculum-aligned content development for Texas and California state standards. For New Entrants and Emerging Players: Begin with English-language test-prep and competitive examination publishing in Mumbai, Delhi, and Bangalore, where institutional procurement is scaling fastest. Target direct-to-consumer subscription models bundling print, digital, and audio formats to bypass Amazon's algorithmic gatekeeping. Leverage web-to-print workflows to minimize inventory risk against established houses with legacy warehousing infrastructure. For Investors and Strategic Acquirers: The window for entry favors education-specialist publishers with curriculum-aligned content pipelines and established school channel relationships. Long-term viability hinges on format diversification capabilities spanning print-digital-audio integration. Monitor state-level curriculum standard revisions in Texas and California as inflection indicators for textbook procurement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Audiobook Platform Exclusivity Negotiation | Streaming services like Audible and Spotify are capturing listener budgets previously supporting discrete sales. |
| FSC-Certified Supply Chain Consolidation | EU Green Deal carbon disclosure requirements force verified sustainable sourcing investments for market access. |
| Direct-to-Consumer Subscription Launch | Publisher-controlled membership programs enable first-party data capture and format bundling beyond retail intermediaries. |
| Indian English-Language Expansion | Competitive examination culture in Mumbai, Delhi, and Bangalore drives academic and trade publishing demand. |
| Web-to-Print Workflow Adoption | On-demand manufacturing reduces inventory risk for mid-list titles without warehousing exposure. |
Methodological Framework
Multi-period observation of audiobook licensing terms, platform distribution share shifts, and curriculum procurement cycles anchored the trend analysis, supplemented by interviews with editorial directors, audiobook production studio heads, educational procurement officers, and literary rights agents. Secondary validation drew from SEC 10-K filings of trade publishing conglomerates, EU ECHA chemical safety registrations, BIS quality certification databases for Indian educational imports, and customs records tracking paper mill sourcing patterns. Bottom-up title-level revenue modeling and top-down market sizing triangulated volume and value estimates.
Segment-weighting across publication type, distribution channel, format, and target audience dimensions structured the analytical framework throughout the projection horizon. CAGRs were derived from trend extrapolation of format adoption curves, regulatory compliance cost trajectories, and institutional procurement scaling patterns. Indian English-language expansion rates and EU Green Deal carbon certification adoption curves served as industry-specific forecast inputs.
Underlying measurement precision varies by segment; audiobook streaming revenue and online retail volume carry tighter precision than emerging direct-to-consumer subscription contributions. Forecasts reflect documented assumptions regarding platform licensing term stability, pulp cost volatility, and state-level curriculum standard continuity. Material deviation in EU carbon disclosure enforcement timing, Amazon pricing algorithm adjustments, or Indian competitive examination policy shifts warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Publishing
Magazine Subscription Service Market
Digital Publishing
Online Comic Market
Digital Publishing
China Catalog Market
Digital Publishing
Global E-Book Market
Digital Publishing
Africa Catalog Market
Digital Publishing
Adaptive Content Publishing Market
Digital Publishing
Editor App Market
Digital Publishing
Digital Comics Platform Market
Digital Publishing
Middle East Catalog Market
Digital Publishing
Egypt Book Services Market
Digital Publishing
Comic Book Market
Digital Publishing
Europe E-Book Market
Digital Publishing
US Newspaper Market
Digital Publishing
France Catalog Market
Digital Publishing
Digital Newspapers and Magazines Market
Digital Publishing
Digital Publishing Platforms Market