
 Cloud-Based Dental Practice Management Software Market | 2026-2036
Cloud-Based Dental Practice Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud-Based Dental Practice Management Software Market Intelligence
Practice software procurement is shifting from perpetual-license on-premises installations toward subscription-based cloud deployments. Henry Schein One leverages its integrated supply chain and software ecosystem to dominate the mid-market dental segment. Curve Dental competes through a browser-native architecture that eliminates local server dependencies. Planet DDS anchors its position in the dental support organization channel with multi-location workflow tools.
Cloud-based dental practice management software encompasses scheduling, billing, patient records, imaging integration, and treatment planning modules delivered through remote servers with web or mobile client access. The architecture relies on encrypted data transmission, role-based access controls, and API connectivity with digital imaging hardware and electronic claims clearinghouses to centralize clinical and administrative workflows for dental practices. Patient management software leads in revenue contribution due to recurring per-provider licensing and mandatory EHR interoperability requirements. Hybrid cloud deployment represents the fastest-expanding segment as practices balance HIPAA-mandated data sovereignty with the scalability of public infrastructure. Technical support services command durable margin pools because cloud migration complexity generates sustained demand for implementation assistance and ongoing system optimization.
FDA oversight of software-as-a-medical-device intersects with HIPAA security rule enforcement by the Office for Civil Rights to shape product development priorities and liability exposure for vendors. State dental boards in California, Texas, and New York impose supplementary record retention and telehealth consent requirements that fragment compliance obligations across jurisdictions. Stakeholders must monitor evolving FDA guidance on clinical decision support algorithms and state-level teledentistry reimbursement rules to anticipate platform capability requirements and geographic expansion constraints.
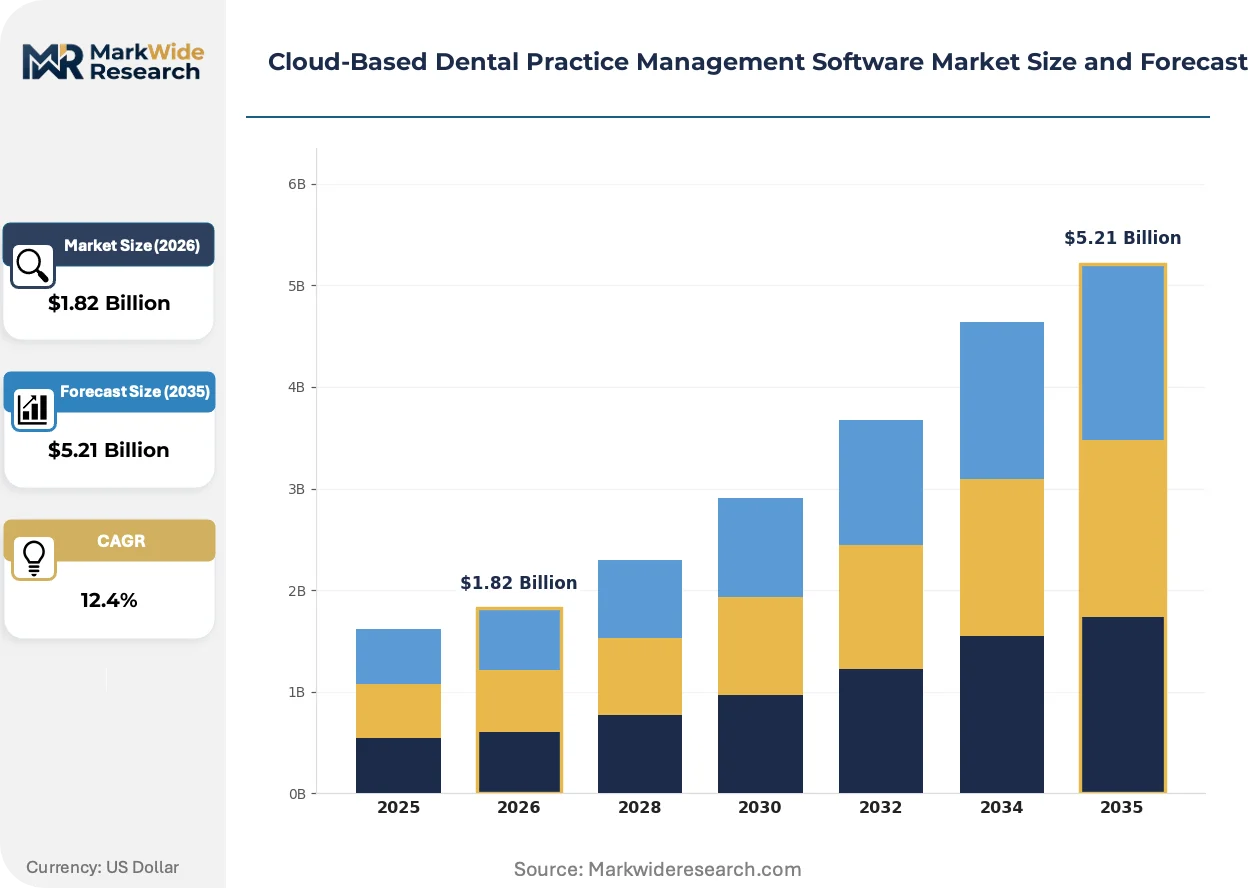
Market Dynamics
HIPAA security rule enforcement and state-level data privacy mandates are compelling dental practices to decommission legacy on-premises servers in favor of cloud-native architectures with encrypted transmission protocols and role-based access controls.
Growth Catalysts
- HIPAA Omnibus Rule:The Office for Civil Rights intensified audit protocols for dental practices, mandating encrypted data transmission and audit logging that cloud platforms deliver natively.
- Dental support organization consolidation:Multi-location DSOs standardize infrastructure across affiliated practices, creating volume procurement pull for centralized cloud deployments.
- API-first architecture:Open integration frameworks enable seamless connectivity with digital imaging hardware and electronic claims clearinghouses, reducing workflow friction.
Market Restraints
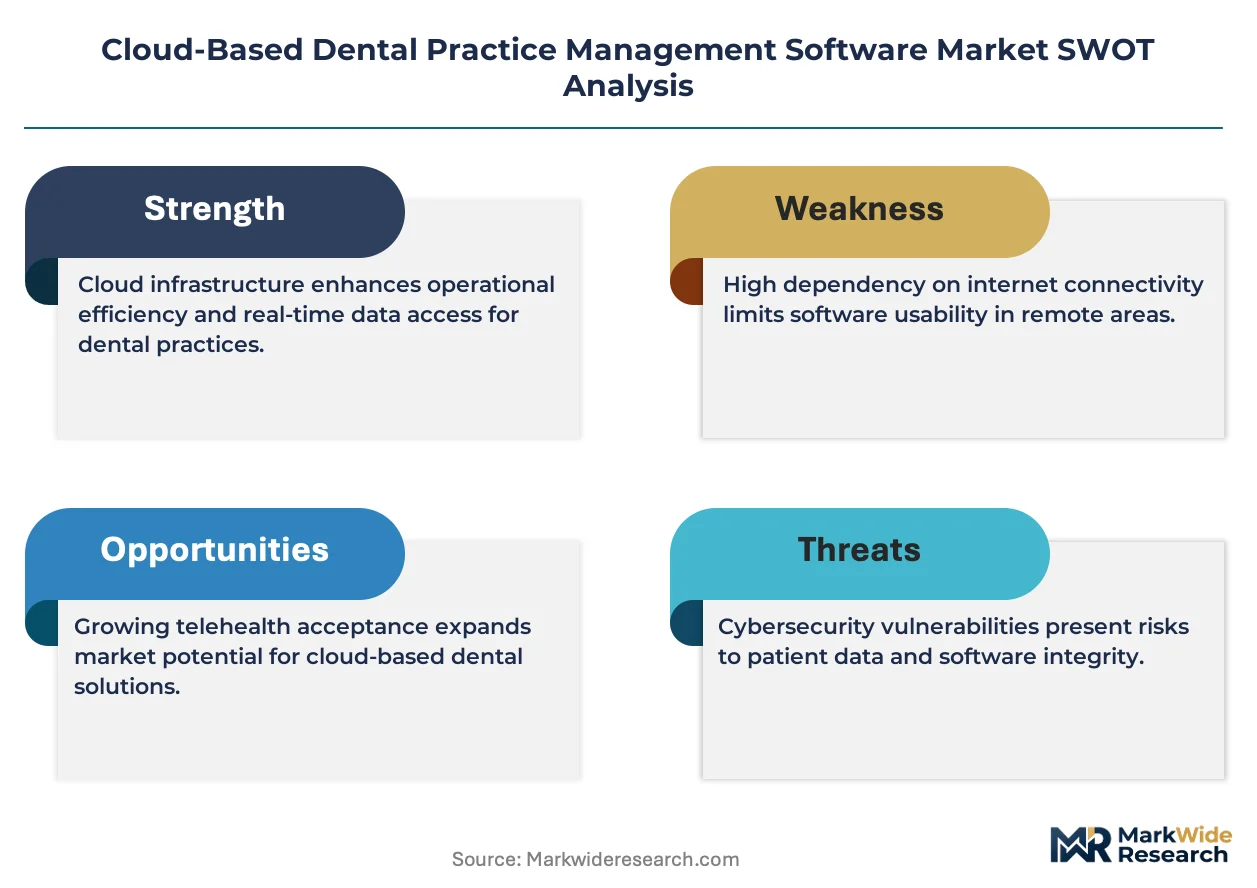
- Internet dependency:Rural practices in broadband-underserved counties face operational vulnerability from connectivity outages that disrupt real-time patient scheduling and billing.
- Data sovereignty fragmentation:California, Texas, and New York impose supplementary record retention and telehealth consent requirements that multiply compliance engineering costs for vendors.
- Legacy system lock-in:Decades of patient records trapped in proprietary on-premises databases create migration friction and switching costs that delay cloud adoption timelines.
Strategic Opportunities
- Teledentistry reimbursement expansion:State Medicaid programs in Texas and New York are adding remote consultation codes, creating platform capability requirements for asynchronous video and digital impression workflows.
- AI-powered clinical decision support:Convergence of machine learning algorithms with radiographic analysis is opening FDA software-as-a-medical-device pathways for diagnostic assistance modules.
- Mobile-native patient engagement:Smartphone-first appointment scheduling and payment portals address younger demographics' channel preferences while reducing front-desk labor intensity.
Industry Challenges
- Cybersecurity workforce scarcity:Dental practices lack in-house expertise to configure zero-trust network architectures and respond to OCR audit findings.
- FDA 510(k) pathway complexity:Clinical decision support algorithms with diagnostic intent face multi-month regulatory review timelines that compress product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud-Based Dental Practice Management Software Market |
| Market Size in 2026 | $1.82 Billion |
| Market Size in 2035 | $5.21 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Scheduling Software, Billing Software, Patient Management Software, Treatment Planning Software End User: General Dentists, Orthodontists, Oral Surgeons, Pediatric Dentists Deployment: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises Service Type: Technical Support, Training Services, Consulting Services, Implementation Services |
| Companies Covered | Henry Schein One, Curve Dental, Planet DDS, Carestream Dental, CareStack, Dentrix Ascend, Denticon, Tab32, Dentiflow, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud-Based Dental Practice Management Software Market Strategic Shifts & Innovations
Browser-native software architectures are eliminating local server dependencies while regulatory pressure on data security accelerates vendor investment in compliance automation tooling.
Artificial intelligence for radiographic interpretation is absorbing diagnostic workload from general practitioners, reducing specialist referral bottlenecks. Solo and small-group practices in metropolitan markets are piloting these tools to preserve chair time for high-margin procedures. The technology is absorbing functions previously requiring human specialist review, compressing the economics of traditional referral networks.
The FDA's evolving guidance on software-as-a-medical-device intersects with OCR HIPAA enforcement to reshape product development priorities. Vendors must now engineer dual compliance pathways for clinical algorithms and data security frameworks. Dental support organizations with multi-state footprints face the steepest adaptation burden as they harmonize platform capabilities across fragmented state requirements.
Subscription pricing for per-provider licensing is displacing perpetual software ownership across mid-market dental practices. Henry Schein One and Planet DDS anchor this shift with recurring-revenue models that bundle implementation support. The United States concentrates this behavioral change where DSO procurement standardization creates volume leverage for SaaS contract terms.
Cloud-Based Dental Practice Management Software Market Segmentation
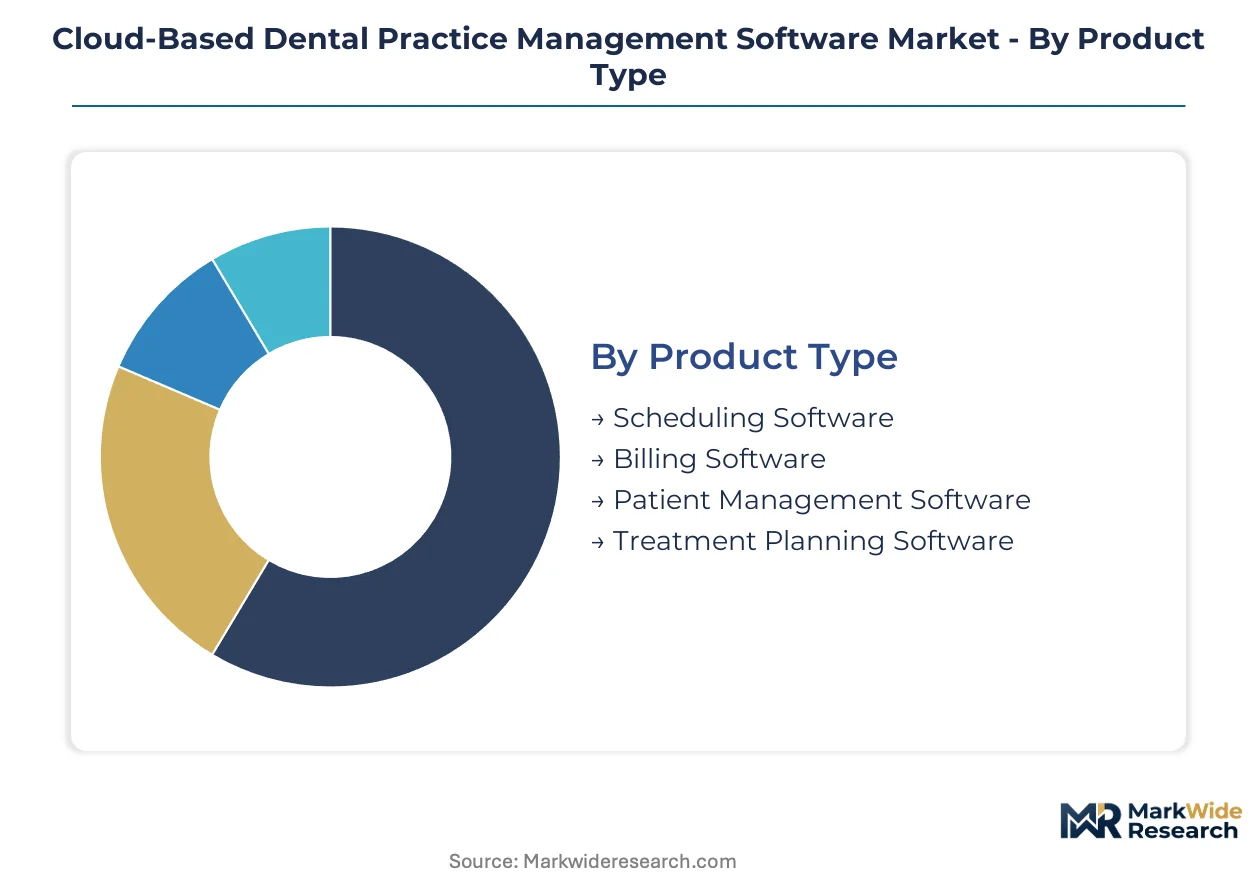
Dental practices select software modules based on regulatory exposure and interoperability mandates. Segmentation reveals how HIPAA compliance costs and DSO procurement patterns concentrate demand across specific product categories and deployment architectures.
Product Type:
FDA 510(k) pathways and HIPAA security rule enforcement impose distinct certification burdens across functional modules, with clinical algorithms facing steeper regulatory review than administrative tools.
- Patient Management Software:Core electronic health record modules with encrypted data transmission and role-based access controls. Demand concentrates in multi-location dental service organizations standardizing HIPAA-compliant infrastructure across hundreds of affiliated practices, driven by OCR audit intensity and mandatory interoperability requirements.
- Scheduling Software:Browser-native appointment coordination with real-time synchronization across devices. General dentistry practices in metropolitan United States markets prioritize these tools to reduce front-desk labor intensity and capture younger demographics through mobile-first interfaces.
- Billing Software:Electronic claims clearinghouse integration with automated coding verification.
- Treatment Planning Software:Visual case presentation tools with 3D imaging integration.
Patient Management Software sits at the top of the volume ranking, with Scheduling Software climbing the fastest.
End User:
Specialty-specific workflows and reimbursement complexity create divergent procurement patterns across dental disciplines, with surgical specialists requiring heavier imaging integration than general practitioners.
- General Dentists:Solo and small-group practices seeking consolidated administrative and clinical platforms. These operators in United States suburban markets drive standardization toward subscription-based cloud deployments as they replace legacy on-premises servers under HIPAA pressure.
- Orthodontists:Treatment planning-intensive workflows demanding 3D imaging integration and digital impression management. Clear aligner therapy expansion in Texas and California orthodontic practices fuels demand for API-first architectures connecting intraoral scanners to cloud-based case management.
- Oral Surgeons:Hospital-affiliated and ambulatory surgical centers requiring anesthesia documentation and medical billing crossover.
- Pediatric Dentists:Medicaid-heavy practices with distinct consent and guardian authorization workflows.
General Dentists command the largest addressable base, while Orthodontists show the steepest expansion trajectory.
Deployment:
Data sovereignty requirements and broadband infrastructure quality shape architecture selection, with hybrid models gaining traction among practices balancing control with scalability.
- Hybrid Cloud:Split architectures retaining sensitive patient records on private infrastructure while leveraging public cloud for non-clinical workloads. Dental support organizations with multi-state footprints in California, Texas, and New York adopt this model to satisfy fragmented state retention mandates without sacrificing operational flexibility.
- Public Cloud:Fully hosted SaaS delivery eliminating local server capital expenditure. Rural practices in broadband-underserved United States counties face operational vulnerability from connectivity outages despite lower upfront costs.
- Private Cloud:Dedicated single-tenant environments for enterprise DSO deployments.
- On-Premises:Legacy server installations facing accelerated decommissioning under OCR enforcement pressure.
Hybrid Cloud leads procurement discussions among multi-location operators, with Public Cloud gaining share fastest among de novo practice formations.
Service Type:
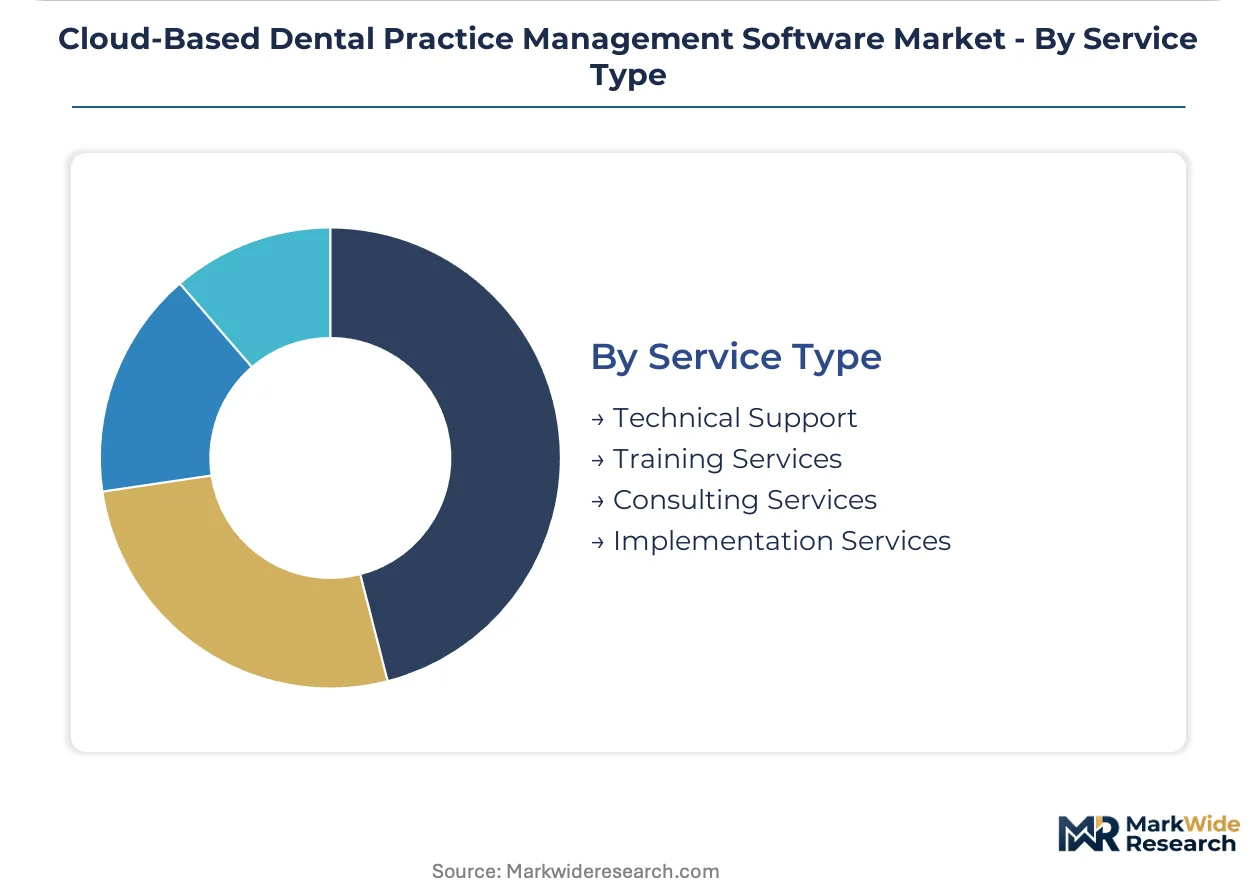
Cloud migration complexity and persistent cybersecurity workforce scarcity sustain durable margin pools in implementation and ongoing technical support.
- Technical Support:Continuous system optimization, security patch management, and OCR audit response assistance. Dental practices lack in-house expertise to configure zero-trust architectures, creating sustained demand for vendor-delivered support services across United States markets.
- Implementation Services:Data migration from proprietary on-premises databases, workflow reconfiguration, and staff training. Decades of legacy patient records generate switching costs that compress product launch windows and extend deployment timelines.
- Training Services:Role-based onboarding for clinical and administrative staff on cloud-native interfaces.
- Consulting Services:Regulatory compliance advisory and multi-state teledentistry workflow design.
Technical Support generates the most recurring revenue, with Implementation Services expanding most quickly as legacy system decommissioning accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates cloud-based dental practice management software demand through its dense network of dental service organizations and stringent HIPAA enforcement corridors.
United States
Multi-location dental service organizations in Texas, California, and New York drive standardization mandates across hundreds of affiliated practices. HIPAA Omnibus Rule enforcement by the Office for Civil Rights compels encrypted data transmission and audit logging that cloud platforms deliver natively. Dallas-Fort Worth anchors DSO procurement centralization where Planet DDS and Henry Schein One compete for enterprise contracts.
Germany
GDPR compliance requirements and the EU Medical Device Regulation shape vendor engineering priorities for dental software entering European markets. The country's national data protection authority enforces strict patient consent protocols for cloud-stored health records. Munich and Berlin host emerging dental technology clusters where practices pilot hybrid cloud architectures balancing data sovereignty with scalability.
United Kingdom
NHS England's digital transformation programs accelerate cloud adoption among contract dental practices seeking interoperability with national health record systems. The Information Commissioner's Office enforces UK GDPR standards that exceed baseline EU requirements for health data processing. London's Harley Street dental district concentrates premium practice demand for integrated imaging and practice management platforms.
Canada
Provincial dental regulatory authorities in Ontario and British Columbia impose supplementary record retention requirements that fragment compliance engineering for vendors. Health Canada oversees software-as-a-medical-device classifications for diagnostic modules integrated into practice management systems. Toronto's dental technology corridor sees concentrated pilot deployments of AI-powered radiographic interpretation tools.
Australia
The Therapeutic Goods Administration regulates clinical decision support algorithms while state dental boards impose varying telehealth consent requirements across jurisdictions. The Australian Digital Health Agency promotes interoperability standards that cloud vendors must satisfy for practice accreditation. Sydney and Melbourne concentrate private dental group demand for multi-location workflow standardization.
Cloud-Based Dental Practice Management Software Market Key Industry Players
Global majors compete with regional champions across compliance engineering and dental support organization channel access, producing a tiered structure where scale advantages concentrate in the United States market. Three strategic archetypes dominate: integrated supply chain platforms bundling software with consumables procurement, browser-native specialists eliminating local infrastructure, and DSO-channel anchors optimizing multi-location workflows. Competitive moves center on API-first architecture investments and state-level compliance certification expansion.
Within the integrated supply chain tier, Henry Schein One leverages its distribution network to bundle software with practice consumables. Curve Dental exemplifies the browser-native architecture archetype through server-eliminating deployment models. Planet DDS anchors the DSO-channel specialist position with multi-location workflow tools. These three occupy positions spanning procurement integration, technical architecture specialization, and vertical channel depth.
| Leading Market Players |
|---|
| Henry Schein One |
| Curve Dental |
| Planet DDS |
| Carestream Dental |
| CareStack |
| Dentrix Ascend |
| Denticon |
| Tab32 |
| Dentiflow |
| Others |
Cost & Logistics Intelligence
Dental support organization procurement consolidation across Texas, California, and New York is forcing vendors to engineer multi-state compliance architectures that inflate engineering costs and compress margin structures at the mid-market tier.
Pricing Analysis
Input-cost pass-through from HIPAA compliance engineering and state-level data sovereignty mandates is intensifying margin pressure across subscription tiers. Per-provider SaaS licensing dominates revenue models, with price differentiation anchored in certification grade—FDA 510(k) cleared modules command premiums over administrative tools—and volume scale through enterprise DSO contracts. Pricing pressure stems from broadband infrastructure gaps in rural United States counties that limit addressable market expansion. Solo practitioners in metropolitan markets exhibit highest price sensitivity, while multi-location DSOs leverage procurement centralization for favorable terms.
Supply Chain Analysis
Reverse-logistics flows for legacy on-premises server decommissioning and data migration services are creating secondary revenue streams for implementation partners. Software development concentrates in the United States, India, and Ireland, with cloud infrastructure provisioning resting on hyperscaler data centers in Virginia, Oregon, and Frankfurt. Raw material dependencies span encryption protocol licensing, API framework development, and cybersecurity tooling. Single-source vulnerability in clearinghouse integrations for electronic claims processing poses structural risk. Distribution runs through direct vendor sales to DSO procurement committees and value-added resellers serving independent practices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where HIPAA Omnibus Rule enforcement by the Office for Civil Rights generates irreversible demand for encrypted, audit-logged cloud architectures.
For Market Incumbents: Anticipate margin compression from browser-native entrants by hardening API-first integration moats with digital imaging hardware manufacturers. Consolidate position through acquisition of teledentistry workflow specialists before state Medicaid reimbursement codes proliferate. Channel control through exclusive DSO partnership structures offers defensive leverage against Henry Schein One's supply chain bundling.
For New Entrants and Emerging Players: HIPAA state-level enforcement variations in California, Texas, and New York open a window for compliance-native point solutions addressing fragmented telehealth consent requirements. Target orthodontic practices in Texas and California piloting clear aligner therapy for lowest competitive density. Go-to-market through specialty dental association channel partnerships bypasses incumbent DSO procurement lock-in.
For Investors and Strategic Acquirers: Asymmetric upside sits with hybrid-cloud infrastructure vendors serving multi-state DSOs navigating data sovereignty fragmentation. Five-to-ten year viability favors platforms with embedded AI radiographic modules progressing through FDA software-as-a-medical-device pathways. Monitor FDA guidance publication velocity on clinical decision support algorithms as inflection indicator for diagnostic module valuation step-ups.
| Strategic Initiative | Industry Significance |
|---|---|
| API-First Architecture Investment | Enables seamless intraoral scanner integration for orthodontic workflows in Texas and California. |
| Multi-State Compliance Certification | Addresses fragmented HIPAA, California Consumer Privacy Act, and Texas telehealth consent mandates. |
| AI Diagnostic Module Development | Positions for FDA software-as-a-medical-device clearance in radiographic interpretation. |
| DSO Channel Partnership Expansion | Captures procurement centralization in Dallas-Fort Worth and New York metropolitan clusters. |
| Mobile-Native Patient Engagement Launch | Reduces front-desk labor intensity for general dentistry practices targeting younger demographics. |
Research Approach
Multiple input streams — structured interviews with dental practice administrators, DSO procurement executives, and cybersecurity compliance officers, plus secondary validation against FDA 510(k) filings, OCR audit enforcement records, and state dental board regulatory updates — were reconciled through bottom-up practice-level sizing and top-down vendor revenue triangulation.
Cross-referencing historical adoption velocity against expert panel assessments shaped the analytical framework across deployment model, practice size, specialty vertical, and regional regulatory cluster dimensions. CAGRs were derived from segmented growth rate reconciliation with macro healthcare IT expenditure trends and dental workforce expansion patterns.
Forecast precision tightens around the base case; tail outcomes carry wider variance under broadband infrastructure deployment delays or accelerated FDA diagnostic algorithm enforcement. Practitioners should monitor OCR audit announcement frequency and state Medicaid teledentistry code expansions for early demand signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Customer Success Software Market
Software & Services
Advanced Product Quality Planning (APQP) Software Market
Software & Services
Human Capital Management (HCM) Saas Market
Software & Services
Global Meeting Room Booking System Software Market
Software & Services
Global Fixed Asset Management Software Market
Software & Services
Eclinical Solutions and Software Market
Software & Services
Cloud Backup and Recovery Software Market
Software & Services
Europe Drone Software Market
Software & Services
Software Market
Software & Services
Category Management Software Market
Software & Services
Hackathon Management Software Market
Software & Services
Canada HR Payroll Software Market
Software & Services
Enterprise Search Software Market
Software & Services
Sports Production Software Market
Software & Services
Middle East and Africa Digital Signage Software Market
Software & Services
Global Building Information Modeling (BIM) Software Market