
 Middle East and Africa Automotive Software Market | 2026-2036
Middle East and Africa Automotive Software Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Automotive Software Market Foresight
Software-defined vehicle architecture is fragmenting traditional tiered supply relationships across the Middle East and Africa. Continental AG anchors its regional position through embedded software integration with European OEM production lines serving African export markets. NVIDIA Corporation differentiates via AI-based solutions for autonomous driving development centers in the UAE and Saudi Arabia. Robert Bosch GmbH dominates aftermarket diagnostics and middleware solutions through its established service networks in Egypt and Morocco.
Automotive software encompasses the programmable instructions, operating systems, and middleware that control vehicle electronic control units, infotainment systems, and connected services, typically executing on processors with ISO 26262 safety integrity levels up to ASIL-D. This technology stack enables real-time powertrain optimization, over-the-air updates, and vehicle-to-everything communication essential for modern mobility platforms. Embedded software retains the largest revenue share due to its ubiquity across engine management and braking systems, while cloud-based software represents the fastest-expanding segment as regional OEMs adopt subscription revenue models for connected services. AI-based solutions command premium pricing in the technology dimension, though deployment remains concentrated among luxury vehicle platforms in Gulf Cooperation Council markets.
South Africa's National Regulator for Compulsory Specifications and the UAE's Telecommunications and Digital Government Regulatory Authority shape product certification requirements for connected vehicle systems entering their respective markets. Compliance with these frameworks determines market access timelines and forces software vendors to maintain localized testing capabilities. Stakeholders must monitor how Saudi Arabia's Saudi Data and Artificial Intelligence Authority develops automotive data governance rules, as cross-border data flow restrictions could reshape cloud deployment strategies for connected car platforms.
Market Dynamics
Fleet operators across commercial transport and logistics are accelerating procurement of telematics and predictive maintenance platforms, compressing traditional OEM sales cycles and forcing software vendors to restructure channel partnerships around operational technology buyers.
Growth Catalysts
- Dubai's smart city infrastructure:Autonomous vehicle trials and connected traffic management systems generate concentrated demand for ADAS and V2X platforms among municipal and commercial fleet buyers.
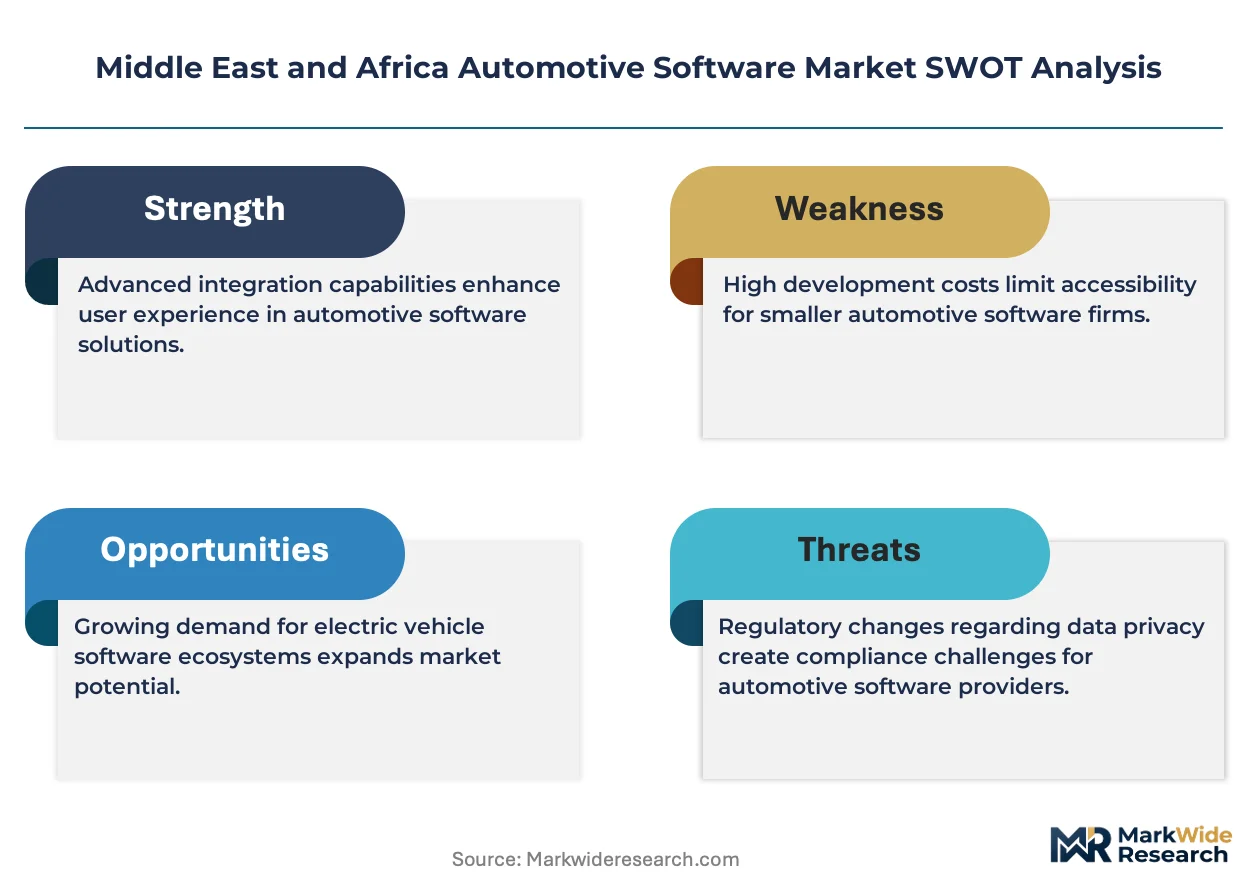
- South Africa's NRCS cybersecurity benchmarks:Compulsory certification requirements for connected vehicle systems accelerate compliance spending by local OEMs and create captive demand for security-validated software stacks.
- Predictive maintenance algorithms:Machine learning models applied to engine telemetry data reduce unplanned downtime for long-haul trucking operators, driving subscription revenue for cloud-based analytics platforms.
Market Restraints
- Semiconductor input volatility:Automotive-grade processor shortages and geopolitical trade restrictions on advanced node chips constrain ECU production volumes across Egyptian and Moroccan assembly plants.
- Cross-border data friction:Saudi Arabia's SDIA data governance framework and pending restrictions on automotive data flows complicate cloud deployment architectures for connected car services.
- Skilled embedded systems labor scarcity:ISO 26262-certified software engineers remain concentrated in South Africa and UAE urban centers, limiting development capacity in secondary African markets.
Strategic Opportunities
- Underpenetrated East African logistics corridors:Kenya and Ethiopia's expanding commercial trucking fleets lack telematics penetration, creating first-mover advantage for subscription-based fleet management platforms.
- ADAS mandate convergence:Egypt's transport ministry is evaluating European NCAP-aligned safety standards, which would mandate automatic emergency braking and lane-keeping software in new vehicle registrations.
- Over-the-air update infrastructure:5G network rollouts in Riyadh and Jeddah enable real-time software deployment models that bypass traditional dealership service dependencies.
Industry Challenges
- Legacy powertrain integration complexity:Software-defined vehicle architectures must coexist with decades-old engine management protocols in African markets where vehicle fleet age averages 12-15 years.
- ASIL-D certification timeline compression:Functional safety validation for autonomous driving software extends development cycles, delaying revenue recognition for AI-based perception stack vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Automotive Software Market |
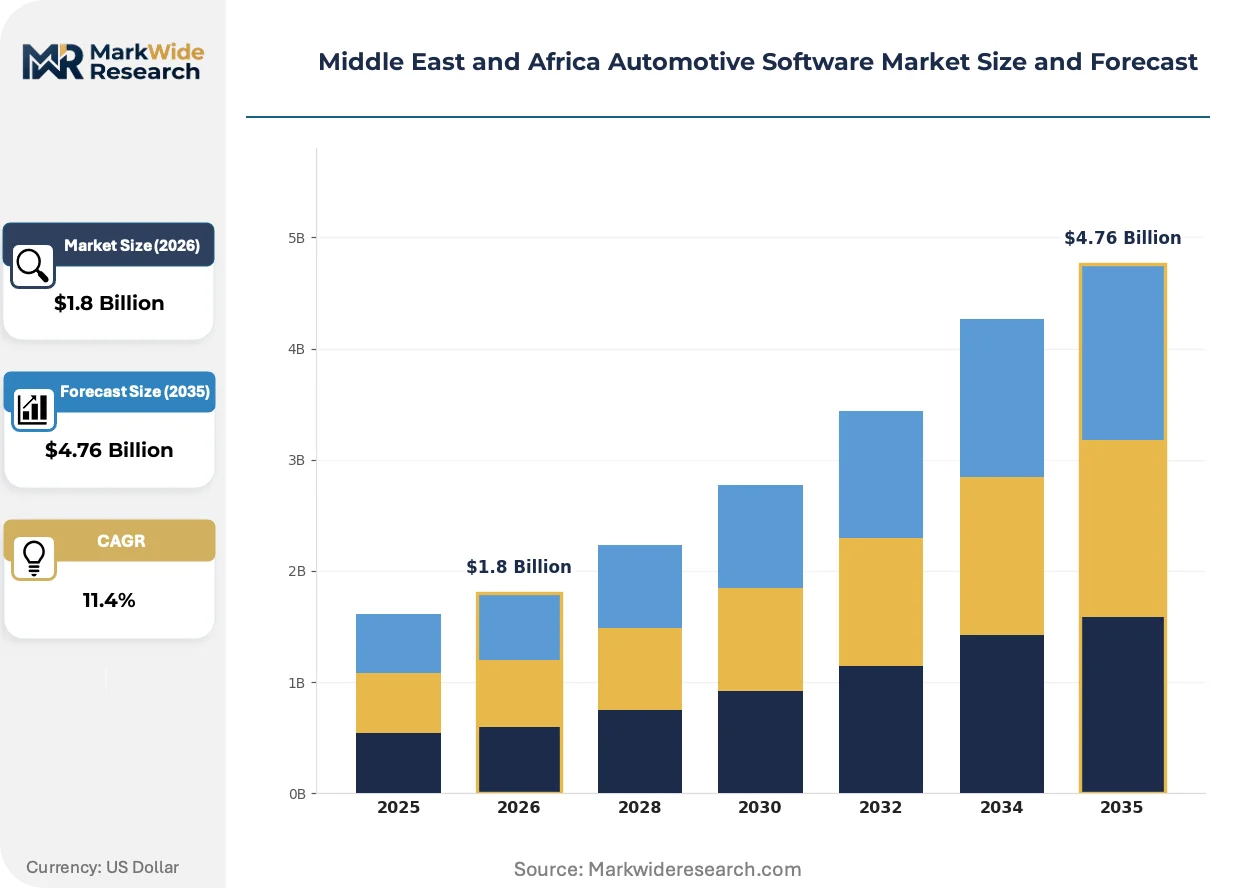
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Embedded Software, Application Software, Middleware Solutions, Cloud-Based Software End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Technology: AI-Based Solutions, IoT Platforms, Blockchain Technology, Advanced Driver Assistance Systems Deployment: On-Premises, Hybrid Solutions, Public Cloud, Private Cloud |
| Companies Covered | Robert Bosch GmbH, Continental AG, NVIDIA Corporation, Aptiv, NXP Semiconductors, BlackBerry Limited, Vector Informatik GmbH, Siemens, Harman International, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Automotive Software Market Shifts & Advancements
Software-defined vehicle architectures are fragmenting traditional tiered supply relationships across the Middle East and Africa, as OEMs bypass conventional middleware vendors to contract directly with specialized AI and cloud infrastructure providers.
Edge computing nodes deployed within vehicle gateways are collapsing the latency constraints that previously forced critical safety functions onto dedicated hardware controllers. Logistics operators in the UAE and Saudi Arabia are adopting these consolidated compute platforms to support real-time cargo monitoring and driver behavior analytics. The structural consequence is collapsing the historical separation between infotainment and powertrain software development silos.
South Africa's National Regulator for Compulsory Specifications is expanding cybersecurity certification requirements from connected passenger vehicles to commercial truck and bus platforms. This regulatory extension forces software vendors to maintain localized penetration testing facilities in Johannesburg and Cape Town. Heavy-duty vehicle OEMs serving mining and agricultural sectors now face 18-24 month compliance timelines that reshape product launch sequencing.
Fleet procurement departments are consolidating vendor relationships around integrated platform providers rather than assembling point solutions from multiple specialists. Large transport operators in Nigeria and Ghana now demand bundled telematics, predictive maintenance, and route optimization from single contracted suppliers. This concentration is most visible among petroleum and cement haulers operating fixed corridor networks between Lagos and Abuja.
Middle East and Africa Automotive Software Market Segmentation
Software procurement patterns across the Middle East and Africa diverge sharply by buyer sophistication and vehicle lifecycle stage. Fleet operators prioritize subscription-based cloud platforms while legacy vehicle assemblers in North Africa remain anchored to embedded systems with minimal connectivity.
Product Type:
After-sales service intensity varies dramatically across software product categories, with cloud-based platforms generating recurring diagnostic engagements versus embedded systems requiring minimal post-deployment intervention.
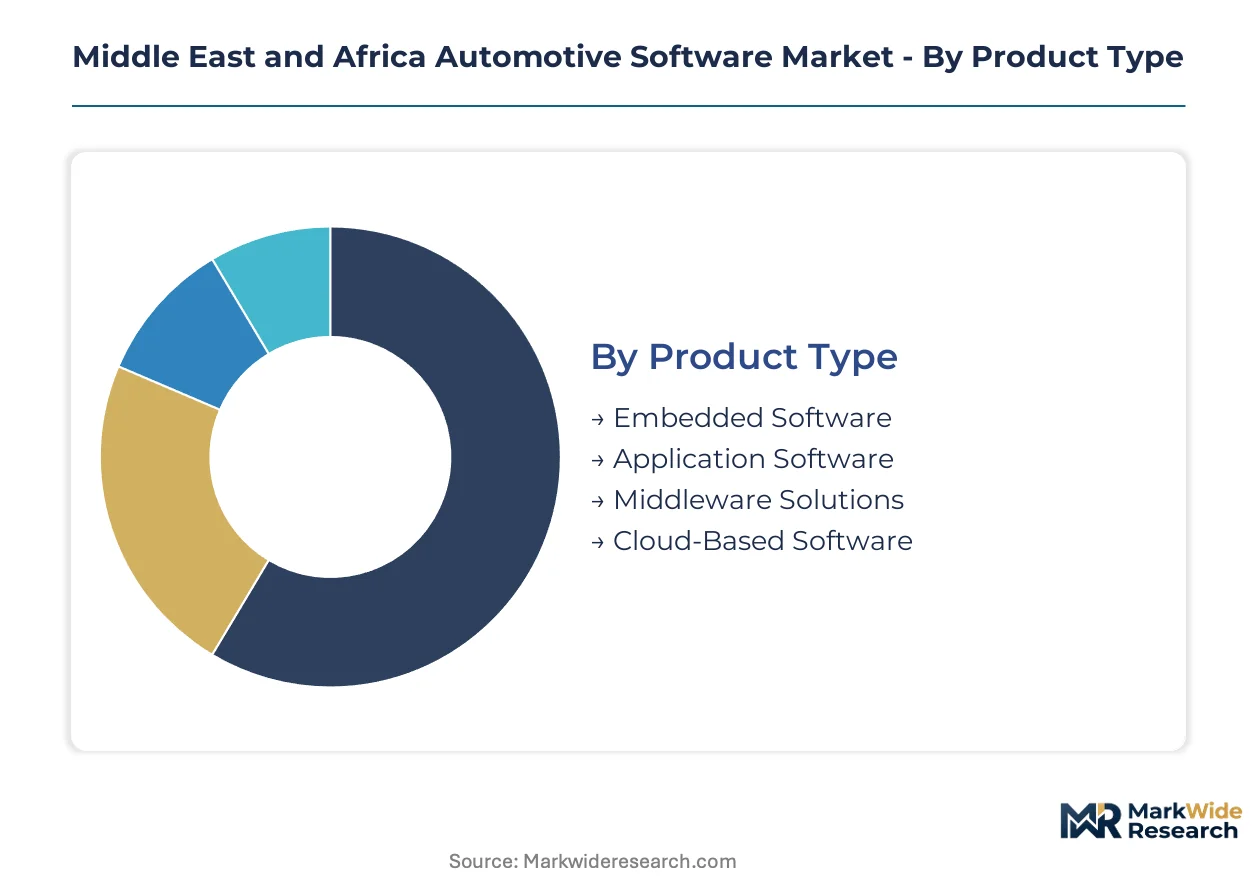
- Embedded Software:Resides directly on electronic control units with ISO 26262 safety integrity certification up to ASIL-D. Demand concentrates among Egyptian and Moroccan vehicle assemblers serving price-sensitive domestic markets where hardware-software integration minimizes unit costs.
- Cloud-Based Software:Delivers over-the-air functionality updates and telemetry analytics via centralized server infrastructure. UAE-based luxury fleet operators and Dubai's autonomous vehicle trials drive procurement, with subscription revenue models displacing perpetual licenses among municipal transport buyers.
- Application Software:Encompasses infotainment interfaces and mobile companion apps executing on consumer-grade processors.
- Middleware Solutions:Provides abstraction layers enabling interoperability between legacy powertrain controllers and modern connectivity stacks.
By volume, Embedded Software leads. By growth pace, Cloud-Based Software is ahead.
End User:
Customer type determines pricing leverage and contract structure, with Tier-1 suppliers capturing bundled procurement from European OEM export platforms while aftermarket providers serve fragmented owner-operated fleets.
- OEMs:Original equipment manufacturers specify software architectures at vehicle design inception, locking suppliers into multi-year development partnerships. South Africa's National Regulator for Compulsory Specifications cybersecurity mandates accelerate compliance spending by BMW and Volkswagen regional assembly operations.
- Aftermarket Providers:Retrofit telematics and diagnostic platforms to existing vehicle fleets through independent service networks. Nigeria's petroleum haulers and Ghana's cement transporters procure route optimization and driver monitoring from these channels, bypassing traditional dealership dependencies.
- Tier-1 Suppliers:Integrate software modules into hardware subsystems delivered to OEM final assembly.
- Vehicle Assemblers:Execute knock-down kit production with localized software calibration for domestic regulatory compliance.
Aftermarket Providers command the steepest expansion trajectory as fleet digitization outpaces new vehicle sales.
Technology:
Technology selection tracks buyer sophistication tier, with AI-based solutions commanding premium pricing in Gulf Cooperation Council luxury segments while IoT platforms penetrate commercial logistics at scale.
- AI-Based Solutions:Encompass machine learning perception stacks for autonomous driving and predictive maintenance algorithms. NVIDIA development centers in the UAE and Saudi Arabia concentrate demand, though ASIL-D certification timelines extend revenue recognition for vendors.
- IoT Platforms:Connect vehicle sensors to fleet management dashboards via cellular networks. Kenyan and Ethiopian logistics corridors drive first-mover deployment as underpenetrated East African markets adopt subscription telematics for cargo monitoring.
- Blockchain Technology:Secures vehicle identity and supply chain provenance through distributed ledger architectures.
- Advanced Driver Assistance Systems:Combines sensor fusion software for automatic emergency braking and lane-keeping functionality.
IoT Platforms dominate current procurement volumes. AI-Based Solutions are gaining share fastest.
Deployment:
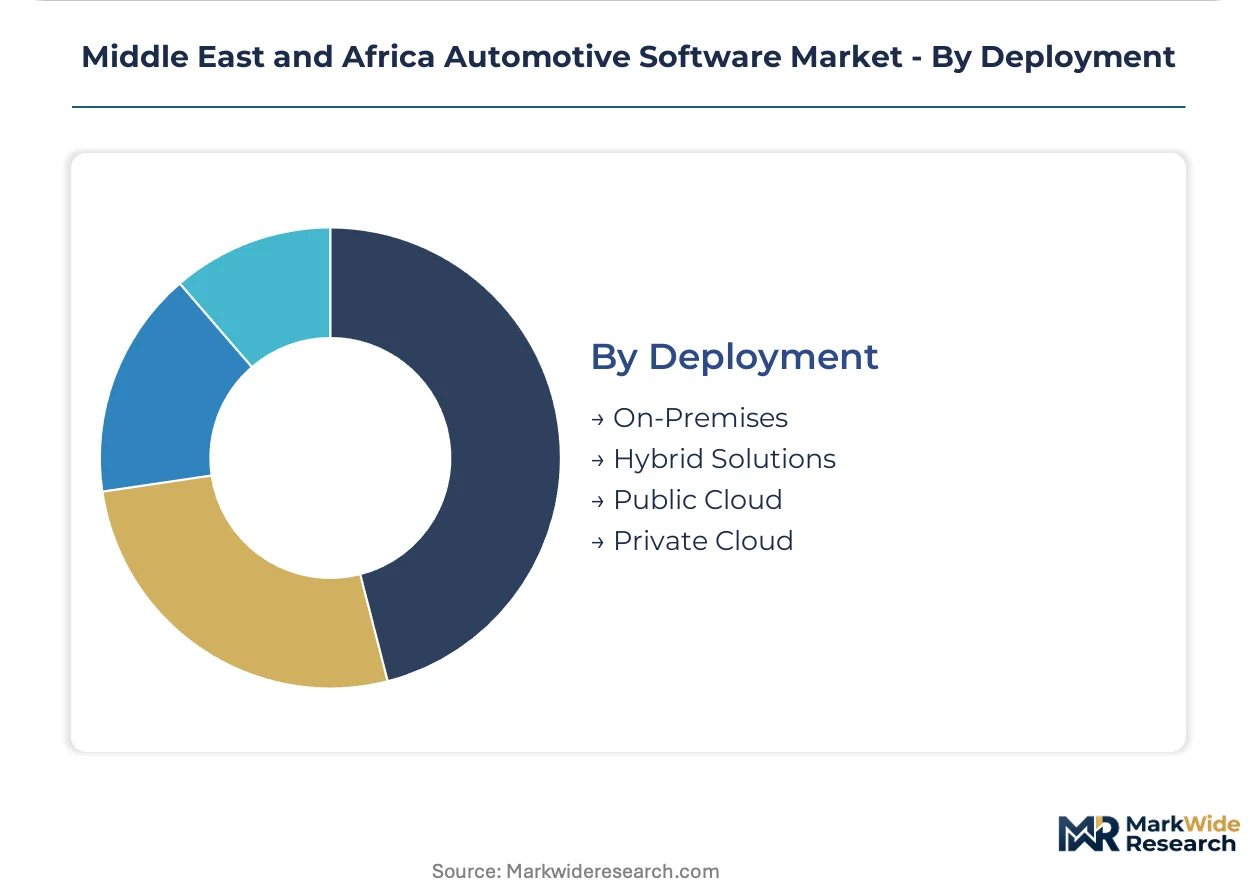
Infrastructure maturity dictates deployment architecture, with 5G availability in Riyadh and Jeddah enabling real-time public cloud services while data sovereignty concerns in Saudi Arabia preserve hybrid demand.
- Public Cloud:Hosts connected vehicle services on shared infrastructure with elastic scaling. Dubai's smart city traffic management platforms and UAE municipal fleet operators drive concentration, leveraging sub-20 millisecond latency from localized edge nodes.
- Hybrid Solutions:Distributes critical safety functions to on-vehicle compute while offloading analytics to centralized servers. Saudi Arabia's SDIA data governance framework and pending cross-border flow restrictions compel this architecture among connected car service providers.
- On-Premises:Maintains complete software stack within buyer-controlled data centers.
- Private Cloud:Delivers dedicated infrastructure with single-tenant isolation for defense and government vehicle fleets.
Hybrid Solutions anchor current spending. Public Cloud is climbing the fastest as 5G coverage expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet operators and smart city initiatives concentrate procurement power across the Middle East and Africa, with commercial transport buyers and municipal authorities driving divergent software requirements.
United Arab Emirates
Dubai's autonomous vehicle trials and connected traffic management systems generate concentrated demand for ADAS and V2X platforms. The Telecommunications and Digital Government Regulatory Authority shapes certification requirements for connected vehicle systems entering the market. Dubai's smart city infrastructure anchors regional procurement, with municipal and commercial fleet buyers compressing traditional OEM sales cycles.
Saudi Arabia
The Saudi Data and Artificial Intelligence Authority is developing automotive data governance rules that reshape cloud deployment strategies. 5G network rollouts in Riyadh and Jeddah enable real-time software deployment models. The Eastern Province hosts logistics corridors where petroleum and cement haulers demand bundled telematics and predictive maintenance platforms.
South Africa
The National Regulator for Compulsory Specifications enforces automotive cybersecurity benchmarks that accelerate compliance spending by local OEMs. BMW and Volkswagen regional assembly operations face 18-24 month certification timelines. Johannesburg and Cape Town concentrate ISO 26262-certified software engineering capacity, limiting development scale in secondary markets.
Egypt
The transport ministry is evaluating European NCAP-aligned safety standards that would mandate automatic emergency braking software. Vehicle assemblers serving price-sensitive domestic markets prioritize embedded systems with minimal connectivity. Cairo-based production facilities execute knock-down kit production with localized software calibration for regulatory compliance.
Kenya
Expanding commercial trucking fleets lack telematics penetration, creating first-mover advantage for subscription-based fleet management platforms. Underpenetrated East African logistics corridors drive IoT platform deployment for cargo monitoring. Nairobi anchors regional adoption as logistics operators digitize fixed corridor networks.
Middle East and Africa Automotive Software Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented supply relationships. The market structure features European OEM-aligned integrators, AI development specialists, and aftermarket service networks as three strategic archetypes. M&A activity concentrates around middleware capabilities, while geographic expansion targets underpenetrated East African logistics corridors.
Among Germany-based diversified technology groups, Robert Bosch GmbH and Continental AG exemplify channel-controlling archetypes with established regional footprints. NVIDIA Corporation represents the product-specialist tier, anchoring AI-based solution development for autonomous driving centers. These three companies illustrate how software-defined vehicle architectures are fragmenting traditional tiered supply relationships across the region.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| NVIDIA Corporation |
| Aptiv |
| NXP Semiconductors |
| BlackBerry Limited |
| Vector Informatik GmbH |
| Siemens |
| Harman International |
| Others |
Supply & Pricing Matrix
Automotive-grade processor concentration in Taiwan and South Korea feeds directly into margin capture by Tier 1 suppliers serving Gulf Cooperation Council OEMs, while Egyptian and Moroccan assemblers absorb cost volatility through fixed-price embedded software contracts.
Pricing Analysis
Cost-plus contracts with semiconductor price indexation dominate procurement between Tier 1 suppliers and North African vehicle assemblers. Three-tier pricing structure across premium, standard, and economy levels tracks ISO 26262 certification grade and after-sales service bundling. Pricing pressure stems from automotive-grade chip shortages constraining ECU production volumes. Fleet operators in Kenya and Ethiopia exhibit highest price sensitivity, while UAE luxury platforms accept premium AI-based solution pricing.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from European OEMs sustain Tier 2 middleware vendors through 18-24 month ASIL-D certification cycles. Geographic supply concentration centers on Germany, Taiwan, and South Korea for processor and toolchain inputs. Raw material dependencies span silicon wafers, automotive-grade memory modules, and specialized compiler software. Single-source vulnerability in advanced node chip fabrication compounds procurement risk. Distribution runs through OEM captive channels and aftermarket service networks anchored in Johannesburg and Dubai.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-defined vehicle architectures threaten embedded software incumbents with disintermediation as OEMs contract directly with cloud infrastructure and AI specialists.
For Market Incumbents: Insulate middleware revenue streams by deepening certification capabilities in Johannesburg and Cape Town to capture South Africa's NRCS cybersecurity mandate spending. Secure exclusive service contracts with Nigerian petroleum haulers and Ghanaian cement transporters before fleet procurement consolidates around integrated platform providers. For New Entrants and Emerging Players: Pursue underpenetrated East African logistics corridors in Kenya and Ethiopia with subscription telematics offerings priced below incumbent per-unit hardware models. Anchor go-to-market through Nairobi-based logistics operators digitizing fixed corridor networks between Mombasa and Kampala. For Investors and Strategic Acquirers: Capital is best deployed toward middleware specialists with ASIL-D validation capabilities and established penetration testing facilities in South Africa. Long-term viability hinges on regulatory compliance service revenue rather than perpetual license models. Watch for Saudi Arabia's SDIA data governance framework finalization as inflection indicator for hybrid cloud deployment demand.| Strategic Initiative | Industry Significance |
|---|---|
| ASIL-D Certification Investment | Captures South Africa NRCS cybersecurity mandate compliance spending by BMW and Volkswagen regional assembly. |
| Geographic Expansion to East Africa | Secures first-mover position in Kenyan and Ethiopian logistics corridors lacking telematics penetration. |
| Platform Integration Partnership | Bundles telematics, predictive maintenance, and route optimization for Nigerian petroleum haulers. |
| Acquisition of Specialist Firm | Absorbs ISO 26262-certified engineering capacity concentrated in Johannesburg and Cape Town. |
| Strategic Partnership with Cloud Provider | Addresses Saudi Arabia SDIA data sovereignty requirements through hybrid deployment architecture. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of vehicle production databases, IHS Markit registration data, SEC filings from listed automotive suppliers, and regulatory filings with South Africa's NRCS and UAE's TDRA. Primary interviews engaged Tier 1 supplier procurement leads, OEM platform engineers, aftermarket distributors, fleet operations managers, and embedded systems developers. Bottom-up segment sizing triangulates against top-down market value reconstruction.
Forecast inputs include vehicle production volumes by propulsion architecture, content-per-vehicle trajectories for ADAS and connectivity modules, and regional OEM tier penetration rates across the projection horizon. Segmentation dimensions span product type, deployment model, end-user category, and technology tier. CAGRs derive from logistic curve fitting against adoption rate benchmarks and regulatory mandate timelines.
Sensitivities concentrate around semiconductor supply volatility, Saudi data governance finalization, and East African logistics digitization pace. Forecasts reflect documented assumptions regarding 5G rollout speed and cybersecurity certification timeline compression. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Retail Inventory Management Software Market
Software & Services
Global Journal App Market
Software & Services
Global Virtualization Software Market
Software & Services
Device Tracking Software Market
Software & Services
Automotive Customization Software Market
Software & Services
Advanced Process Control Software Market
Software & Services
Credit Management Software Market
Software & Services
Global Political Campaign Software Market
Software & Services
Global Knowledge Management Software Market
Software & Services
Model Based Testing Tools Market
Software & Services
B2B Gateway Software Market
Software & Services
Skills Management Software Market
Software & Services
Talent Management Software Market
Software & Services
Software Repository Market
Software & Services
Global Customer Experience Software Market
Software & Services
Stock Media Software Market