
 Data Diode Solution Market | 2026-2036
Data Diode Solution Market Size, Share, and Industry Trends Forecast 2026-2036
Data Diode Solution Market Analysis
NIS2 is realigning the cost-of-entry calculus for data diode vendors serving European critical infrastructure. Owl Cyber Defense leverages its hardware specialization to anchor unidirectional security contracts with US federal agencies. BAE Systems plc sustains dual-market positioning across defense and industrial segments through captive certification pipelines. Advenica AB competes on Nordic manufacturing scale, while Waterfall Security Solutions Ltd. dominates Israel-linked industrial cybersecurity deployments.
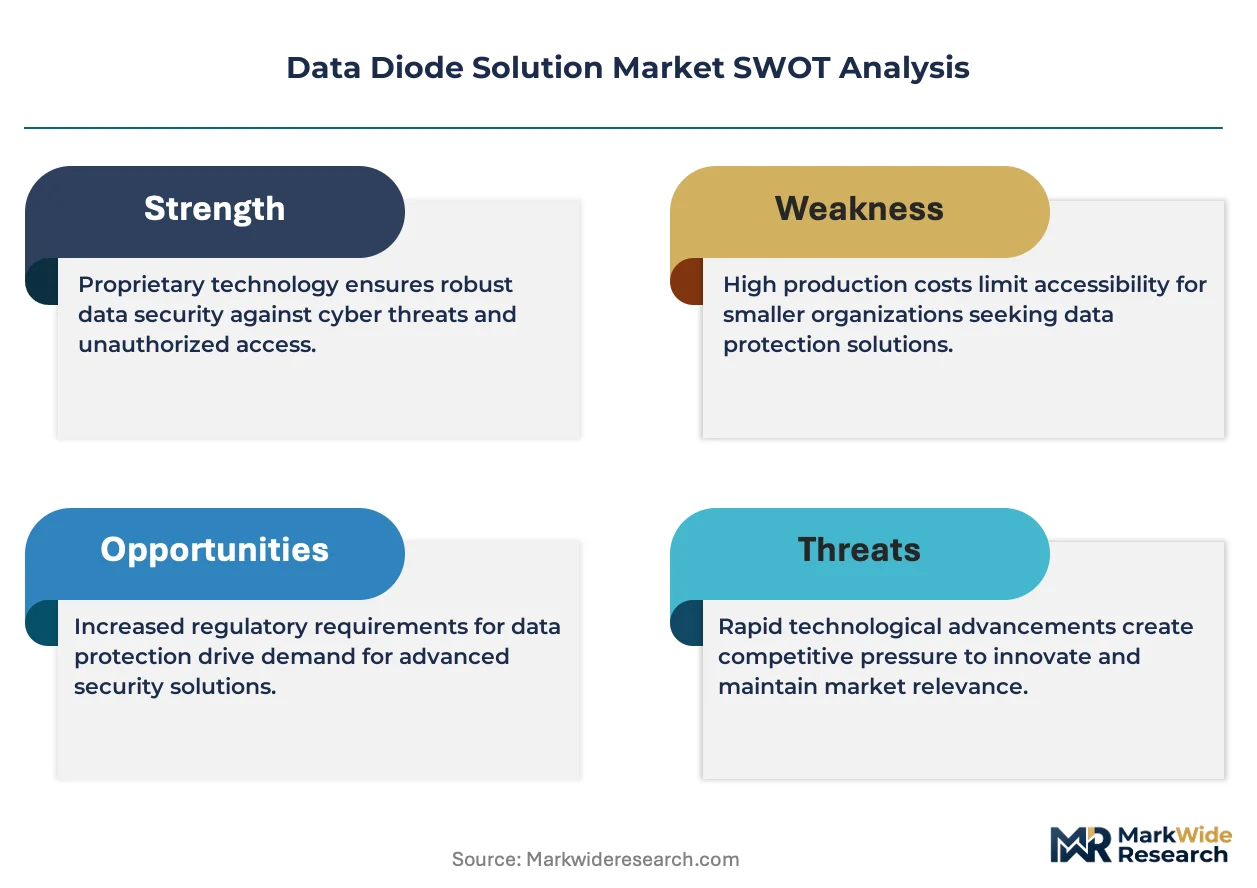
A data diode is a unidirectional network communication device that permits data transmission in only one direction through physical layer isolation, typically employing fiber optic or electrical one-way paths with no return channel. It enforces deterministic information flow control for air-gapped or high-assurance networks where software-defined security cannot guarantee impermeability. Hardware diodes command the dominant product share due to tamper-evident physical architectures that firmware and software layers cannot replicate. Defense and critical infrastructure applications absorb the majority of value, with financial services emerging as the fastest-growing segment as post-SWIFT incident remediation drives unidirectional replication mandates. Government end users retain the deepest procurement budgets, though energy sector deployment is accelerating behind NERC CIP-aligned retrofit timelines.
EU NIS2 and the US NERC CIP framework collectively reshape product standards by mandating deterministic boundary protection for operational technology networks. Germany's BSI and France's ANSSI publish country-specific technical profiles that vendors must satisfy for national critical infrastructure eligibility. The US FAA and FDA maintain sector-specific data diode guidance for aviation and medical device manufacturing environments. Stakeholders must monitor divergence between national certification regimes as fragmentation risks complicate multi-jurisdiction product strategies.
Market Dynamics
Defense procurement cycles and critical infrastructure retrofit mandates are compressing vendor qualification timelines while fragmenting certification requirements across NATO member states and EU national security agencies.
Growth Catalysts
- EU NIS2 Directive:Mandatory deterministic boundary protection for operational technology networks is expanding addressable market for hardware-based unidirectional gateways across energy, transport, and healthcare infrastructure operators.
- Fiber optic physical layer isolation:Tamper-evident architectures that firmware cannot replicate are displacing software-defined alternatives in classified network segmentation applications.
- German industrial control system retrofits:Accelerating BSI-mandated upgrades in manufacturing and chemical processing facilities are driving unidirectional gateway deployment at scale.
Market Restraints
- High-assurance component sourcing:Specialized optical transceivers and hardened chassis manufacturing concentrates in Nordic and Israeli supplier bases, creating single-source vulnerability.
- Cross-border certification friction:Divergent technical profiles between Germany's BSI, France's ANSSI, and US NERC CIP multiply compliance costs for multi-jurisdiction vendors.
- Optical bypass switches:Lower-cost alternatives for non-classified environments threaten price positioning at the mid-market tier.
Strategic Opportunities
- Financial services replication mandates:Post-SWIFT incident remediation protocols are creating unidirectional data replication requirements across transaction processing and settlement infrastructure.
- Medical device manufacturing:FDA guidance for deterministic boundary protection in connected production environments opens new end-use vertical beyond traditional defense and energy.
- Aviation sector deployment:FAA technical specifications for air-gapped maintenance and operations networks are establishing certification pathways for aerospace-qualified diode architectures.
Industry Challenges
- Embedded systems firmware expertise:Scarce talent pools for hardware-software co-design in unidirectional communication stacks constrain product development velocity.
- Multi-agency certification timelines:Parallel validation processes across defense, civilian critical infrastructure, and sector-specific regulators extend revenue recognition cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Diode Solution Market |
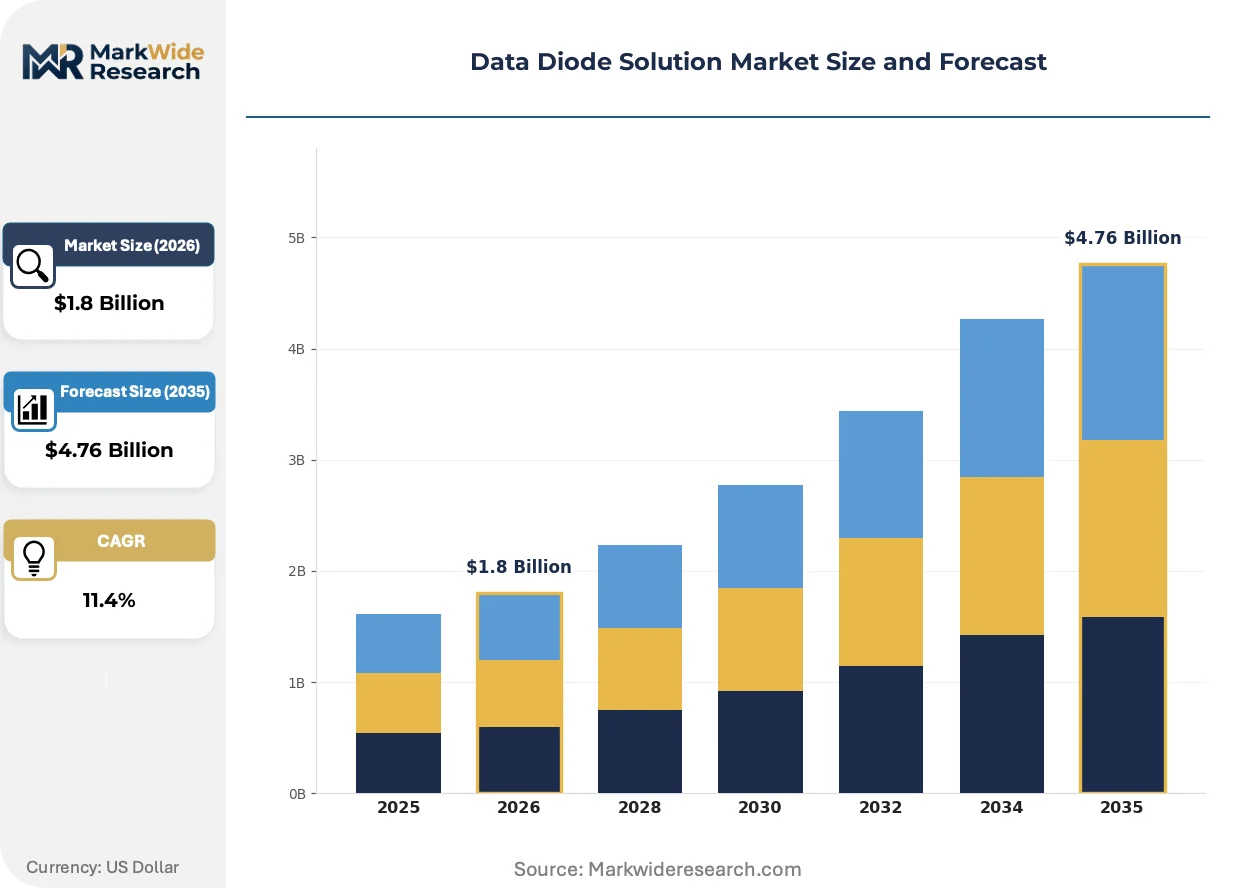
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware, Software, Service, Firmware Application: Critical Infrastructure, Defense, Financial Services, Industrial Control Systems End User: Government, Healthcare, Energy, Transportation Deployment: On-Premises, Cloud-Based, Hybrid, Managed Services |
| Companies Covered | ST Engineering, Owl Cyber Defense, BAE Systems plc, Advenica AB, Everfox, Belden Inc., Fibersystem AB, Waterfall Security Solutions Ltd., Siemens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Diode Solution Market Emerging Trajectories
Physical-layer security architectures are diverging from software-centric cybersecurity approaches, creating distinct product categories with incompatible procurement channels and certification regimes.
Optical data diode miniaturization is decentralizing deployment economics for distributed industrial sensor networks. Water utilities and pipeline operators are adopting compact fiber-based unidirectional modules for remote telemetry aggregation. This footprint reduction is decentralizing what previously required centralized gateway architectures.
EU NIS2 transposition into national law is mandating deterministic boundary protection for operational technology networks. Member states are imposing country-specific technical profiles that vendors must satisfy for critical infrastructure eligibility. Energy sector operators in Germany and France are accelerating procurement to meet compliance deadlines.
Specification-driven procurement is displacing relationship-based vendor selection in defense and critical infrastructure segments. Buyers now require pre-certified hardware architectures with documented tamper-evident properties. This shift is most pronounced in NATO member state defense agencies and EU energy transmission operators.
Data Diode Solution Market Segmentation
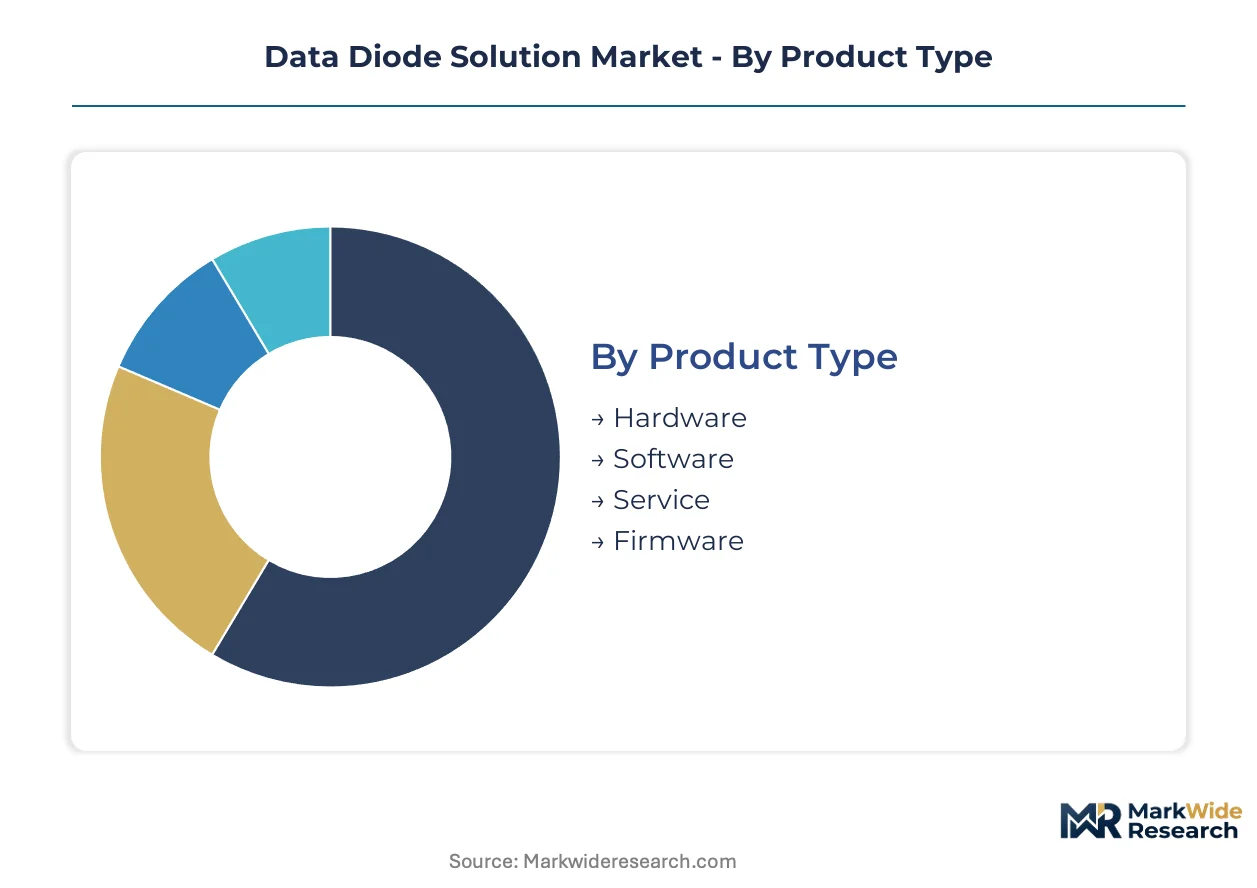
Data diode procurement patterns diverge sharply across product architectures and deployment contexts. Buyers in defense and critical infrastructure prioritize deterministic physical isolation over software flexibility, while emerging financial services adopters balance cost efficiency with compliance mandates.
Product Type:
Hardware diodes command premium positioning through tamper-evident optical architectures that firmware cannot replicate.
- Hardware:Fiber optic and electrical one-way paths with no return channel enforce deterministic information flow control. NATO defense agencies and German BSI-mandated industrial operators drive procurement of hardened chassis with documented physical layer isolation.
- Software:Virtualized unidirectional gateways deploy within existing compute infrastructure for non-classified environments. Cost-sensitive mid-market buyers in commercial manufacturing adopt these where regulatory mandates permit software-defined alternatives.
- Service:Installation, certification support, and managed maintenance contracts accompany hardware deployments. Energy sector operators in France and Germany contract specialized integrators for NIS2-aligned boundary protection implementations.
- Firmware:Embedded control logic for optical transceiver timing and protocol translation resides in specialized hardware modules. Nordic and Israeli component suppliers concentrate expertise in this layer.
Hardware leads volumes today; services are gaining share fastest as retrofit timelines compress vendor qualification cycles.
Application:
Mission-criticality determines whether buyers require hardware-based deterministic isolation or accept software-mediated alternatives.
- Critical Infrastructure:EU NIS2 Directive mandates deterministic boundary protection for energy, transport, and healthcare networks. German transmission operators and French water utilities accelerate procurement to meet national transposition deadlines.
- Defense:Classified network segmentation across NATO member states requires tamper-evident physical architectures with no exploitable return path. Hardware diodes with documented supply chain provenance dominate procurement specifications.
- Financial Services:Post-SWIFT incident remediation protocols mandate unidirectional data replication for transaction processing infrastructure. Settlement networks and clearing houses deploy optical diodes for deterministic audit trail protection.
- Industrial Control Systems:Manufacturing and chemical processing facilities retrofit legacy networks with unidirectional gateways. BSI-mandated upgrades in German industrial clusters drive concentrated demand for compact fiber-based modules.
Defense anchors revenue concentration; financial services climbs the fastest as replication mandates proliferate.
End User:
Budget depth and regulatory exposure shape procurement velocity across institutional buyer categories.
- Government:Defense agencies and civilian security services operate the deepest procurement budgets for high-assurance network segmentation. Multi-year hardware refresh cycles concentrate spending in classified and sensitive-but-unclassified environments.
- Healthcare:EU NIS2 transposition brings medical device manufacturing and hospital networks under mandatory operational technology security standards. FDA guidance for deterministic boundary protection in connected production environments opens additional procurement channels.
- Energy:NERC CIP-aligned retrofit timelines in North America and NIS2 deadlines in Europe compress vendor qualification schedules. Transmission operators and pipeline companies deploy unidirectional gateways for SCADA network isolation.
- Transportation:FAA technical specifications for air-gapped aviation maintenance networks establish certification pathways for aerospace-qualified architectures. Rail signaling and port automation systems adopt compact optical modules for telemetry aggregation.
Government retains the steepest spending trajectory; healthcare shows the sharpest acceleration behind sector-specific regulatory guidance.
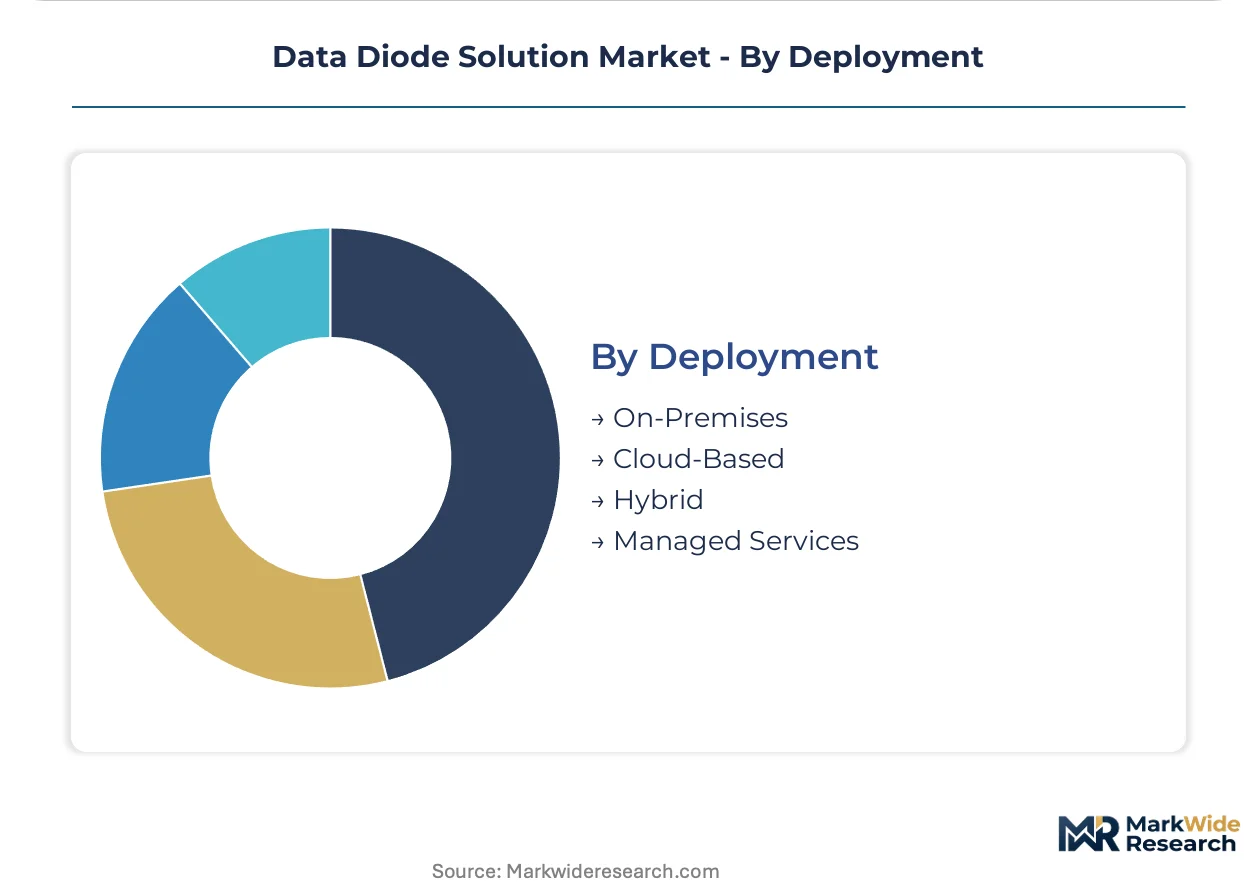
Deployment:
Control requirements and capital constraints determine whether buyers own infrastructure or outsource operational responsibility.
- On-Premises:Physically isolated hardware installations in air-gapped or high-assurance facilities meet the most stringent certification requirements. Defense and classified civilian agencies mandate direct operational control over boundary protection assets.
- Cloud-Based:Virtualized unidirectional gateways deploy within sovereign or commercial cloud environments for non-classified workloads. Financial services firms adopt these for cost-efficient disaster recovery replication between cloud regions.
- Hybrid:Combinations of on-premises hardware for critical boundaries and cloud-based services for administrative functions balance security assurance with operational flexibility. Energy sector operators favor this architecture for geographically distributed infrastructure.
- Managed Services:Third-party operation of unidirectional gateway infrastructure transfers compliance liability to specialized security providers. Mid-market industrial buyers lacking embedded systems expertise contract managed diode services for NIS2 adherence.
On-premises deployment dominates certified environments; managed services expand most quickly among compliance-constrained mid-market buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Embedded systems firmware specialists cluster in Nordic and Israeli supplier bases, anchoring hardware diode manufacturing expertise. Defense procurement cycles and NIS2 transposition deadlines compress vendor qualification timelines across NATO member states. Critical infrastructure retrofit mandates fragment certification requirements between national security agencies.
United States
Defense agencies operate the deepest procurement budgets for high-assurance network segmentation. The FAA maintains technical specifications for air-gapped aviation maintenance networks. Washington DC and Virginia defense corridors concentrate classified network upgrade programs.
Germany
BSI-mandated industrial control system retrofits accelerate unidirectional gateway deployment. The EU NIS2 Directive transposition imposes deterministic boundary protection standards. The Ruhr industrial cluster and Bavarian manufacturing belt drive concentrated demand for compact fiber-based modules.
France
ANSSI publishes country-specific technical profiles for critical infrastructure eligibility. Energy sector operators accelerate procurement to meet NIS2 compliance deadlines. The Île-de-France region hosts transmission operators deploying SCADA network isolation architectures.
United Kingdom
Classified network segmentation requirements across defense and civilian security services sustain hardware diode demand. The UK National Cyber Security Centre aligns procurement with NATO interoperability standards. London and Southeast England concentrate financial services replication mandates for settlement infrastructure.
Israel
Industrial cybersecurity deployments concentrate expertise in optical transceiver timing and protocol translation. The national cyber directorate influences deterministic boundary protection standards for critical infrastructure. Tel Aviv and Haifa anchor aerospace-qualified diode architecture development.
Data Diode Solution Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across defense and industrial segments. The vendor base organizes around three strategic archetypes: defense contractors with captive certification pipelines, Nordic hardware specialists leveraging manufacturing scale, and industrial automation incumbents extending into operational technology security. Competitive moves center on multi-agency certification acquisition and optical component supply chain control.
Within the defense contractor tier, BAE Systems plc and ST Engineering exemplify diversified conglomerates spanning classified and industrial market segments. Owl Cyber Defense represents the pure-play specialist archetype anchored in federal agency relationships. Waterfall Security Solutions Ltd. occupies a position exemplifying geographic concentration in industrial cybersecurity expertise. Siemens and Belden Inc. sit within the industrial automation extension archetype, leveraging existing operational technology channel relationships.
| Leading Market Players |
|---|
| ST Engineering |
| Owl Cyber Defense |
| BAE Systems plc |
| Advenica AB |
| Everfox |
| Belden Inc. |
| Fibersystem AB |
| Waterfall Security Solutions Ltd. |
| Siemens |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between NATO-qualified hardware and commercial software alternatives manifests in both procurement premiums and component sourcing strategies. Defense agencies absorb cost premiums for tamper-evident optical architectures while mid-market industrial buyers face compressed margins from optical bypass switch substitutes.
Pricing Analysis
Bundled certification support and managed maintenance contracts dominate hardware diode transactions, while unbundled software licenses serve cost-constrained manufacturing segments. Price differentiation rests on BSI and ANSSI certification tiers plus after-sales service depth. Cost compression in the commercial tier intensifies because optical bypass switches offer partial functionality at lower price points. Government end users exhibit the least price sensitivity; mid-market industrial buyers in commercial manufacturing show the highest.
Supply Chain Analysis
Domestic-content mandates in German BSI procurement and US federal agency specifications are reshaping sourcing toward qualified local integrators. Optical transceiver manufacturing concentrates in Israel and Nordic supplier bases, while hardened chassis fabrication draws from German and US defense industrial channels. Supply chains rest on specialized fiber optic components, radiation-hardened semiconductors, and precision-machined enclosures. Single-source vulnerability in Israeli optical timing modules creates concentration risk. Distribution runs through defense contractors, specialized cybersecurity integrators, and industrial automation channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Data Diode Solution Market operates as a stable compounder anchored by regulatory retrofit mandates that generate predictable procurement cycles across defense and critical infrastructure verticals.
For Market Incumbents: Hedge against optical bypass switch encroachment by deepening certification moats across ANSSI, BSI, and NERC CIP frameworks simultaneously. Acquire captive optical component supply from Nordic and Israeli specialists to defend margin position against supply chain disruption. For New Entrants and Emerging Players: Begin with financial services settlement infrastructure, where post-SWIFT replication mandates create unmet demand without classified clearance barriers. Pursue managed services packaging for NIS2-constrained mid-market industrial buyers lacking embedded systems expertise. For Investors and Strategic Acquirers: Consolidation pressure builds where multi-agency certification timelines exceed product development cycles. Position for acquisitions of pure-play hardware specialists with existing BSI or FAA technical qualifications. Watch German transmission operator procurement velocity as an inflection indicator for European retrofit momentum.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Agency Certification Acquisition | BSI-ANSSI-NERC CIP parallel qualification opens NATO and EU critical infrastructure procurement channels simultaneously. |
| Optical Component Supply Control | Captive sourcing of Israeli and Nordic transceiver modules insulates against single-source vulnerability and tariff exposure. |
| Managed Services Capability Buildout | Third-party operation contracts transfer NIS2 compliance liability from resource-constrained mid-market industrial operators. |
| Financial Services Vertical Expansion | Post-SWIFT settlement infrastructure mandates create replication-grade demand outside traditional defense procurement cycles. |
| Miniaturized Module Development | Compact fiber-based architectures decentralize deployment economics for water utility and pipeline telemetry aggregation. |
Methodological Framework
Direct dialogue with defense procurement officers, critical infrastructure security directors, industrial control system integrators, and optical component suppliers grounded qualitative findings. Secondary validation drew from NATO procurement databases, BSI technical profiles, ANSSI certification registries, NERC CIP compliance filings, and FAA technical specifications. Bottom-up segment sizing triangulated against top-down defense budget allocation analysis.
Bottom-up modeling of hardware, software, and service revenue streams across defense, energy, financial services, and industrial end users anchored the analytical framework throughout the projection horizon. Segmentation by product architecture, application mission-criticality, deployment model, and national regulatory cluster shaped volume and value outputs. CAGRs derived from procurement cycle analysis and retrofit deadline compression across EU NIS2 transposition timelines. Forecast inputs included defense agency refresh schedules, German industrial control system upgrade mandates, and financial services replication protocol adoption curves.
Several conditions sit outside the modeled scope, including classified program spending opacity, supply chain disruption scenarios beyond tariff exposure, and emergent quantum communication technologies. Forecasts reflect documented assumptions about regulatory deadline adherence and certification timeline stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
Latin America Cybersecurity Market
Cybersecurity
DNS Firewall Market
Cybersecurity
Italy Cybersecurity Market
Cybersecurity
Corporate Web Security Market
Cybersecurity
Application Security Market
Cybersecurity
Vietnam Cybersecurity Market
Cybersecurity
Romania Cybersecurity Market
Cybersecurity
Global Patch Management Market
Cybersecurity
Enterprise Mobility Security Market
Cybersecurity
India Ransomware Protection Market
Cybersecurity
Global Network Forensics Market
Cybersecurity
Managed SIEM Service Market
Cybersecurity
Cyber Security in Energy Market
Cybersecurity
Home Wi-Fi Security Solutions Market
Cybersecurity
Penetration Testing Market
Cybersecurity
North America Cyber Security Market