
 Cycling Wear Market | 2026-2036
Cycling Wear Market Size, Share, and Industry Trends Forecast 2026-2036
Cycling Wear Market Intelligence
The substitution of virgin polyester with recycled equivalents derived from post-consumer plastics is consolidating its position as a key material trend in cycling apparel. This shift responds directly to consumer and regulatory pressure for sustainability. Rapha Racing Limited leverages its strong brand identity to command premium pricing in this space. Castelli Cycling specializes in high-performance gear for competitive cyclists, focusing on aerodynamic advantages.
Cycling wear comprises garments engineered for aerodynamic efficiency, moisture management, and comfort during cycling. These products often incorporate multi-panel construction and materials with high spandex content, typically 15-20%, for muscle compression and freedom of movement. Jerseys and shorts represent the core product types, while the professional athletes segment drives fabric innovation. Growth is most pronounced among recreational cyclists, with online retail emerging as the dominant distribution channel.
Product composition and safety are governed by regulations such as the EU's REACH directive, which restricts hazardous chemicals in textiles. In the United States, the FTC enforces labeling rules for fiber content and care instructions, ensuring consumer transparency. Additionally, ISO standards for textile performance provide a baseline for quality assurance across different markets. Navigating this landscape of international chemical regulations and sustainability certifications is critical for maintaining market access.
Market Dynamics
The convergence of sustainability mandates and high-performance material science is the central force shaping the cycling wear market. Consumer and regulatory demands for circularity, particularly the use of recycled polyester, are now as critical to product design as aerodynamics and moisture management.
Growth Catalysts
- Sustainability Policy:The EU Green Deal and related initiatives are accelerating the industry's transition to recycled fabrics, creating a strong pull for innovation in post-consumer plastic reprocessing for textiles.
- Recreational Segment Expansion:A rising number of health-conscious consumers in North America and Europe are adopting cycling for fitness and commuting, increasing the addressable market for technically advanced, comfortable apparel.
- Fabric Technology:Advances in ultrasonic welding and seamless bonding technologies are enabling garments with fewer stitches, which reduces friction and improves aerodynamic profiles for competitive and enthusiast cyclists.
Market Restraints
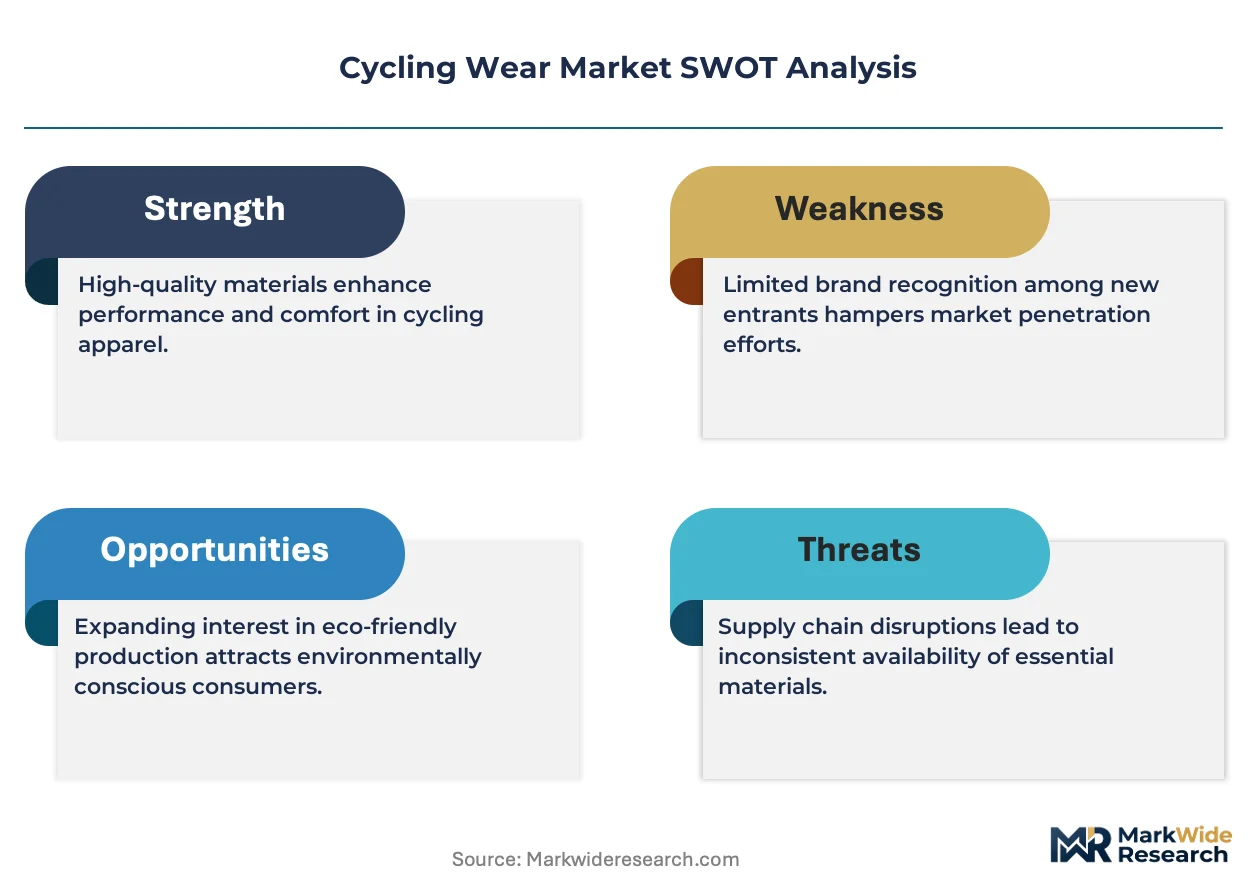
- Input Cost Volatility:Fluctuations in the price of petroleum-derived spandex and specialized recycled polyester feedstocks create margin pressure and complicate long-term production planning for manufacturers.
- Performance Parity:Certain recycled fabrics still exhibit trade-offs in long-term durability, color vibrancy, and UV resistance compared to their virgin material counterparts, limiting adoption in some professional applications.
- Regulatory Compliance Burden:Adhering to a complex web of chemical restrictions, such as the EU's REACH directive for textiles, across a global supply chain adds significant administrative and testing costs.
Strategic Opportunities
- Smart Apparel Integration:The development of cycling wear with embedded biometric sensors for heart rate, muscle oxygenation, and power output tracking presents a major opportunity at the intersection of apparel and fitness technology.
- Geographic Expansion:Targeting nascent but growing cycling cultures in major urban centers across Asia-Pacific and Latin America offers significant white space for market entry and brand building.
- Channel Innovation:Direct-to-consumer (DTC) e-commerce platforms enable niche brands to cultivate a loyal following, bypass traditional retail gatekeepers, and launch products with greater agility.
Industry Challenges
- Certification Delays:The extensive time and cost required to achieve sustainability certifications like Bluesign or Oeko-Tex for new materials can slow down the market introduction of innovative, eco-friendly products.
- Supply Chain Transformation:Shifting procurement from established virgin polyester suppliers to a fragmented and evolving network of qualified recycled material vendors requires significant investment in vetting and quality control.
- Intellectual Property Protection:Safeguarding proprietary aerodynamic panel designs and unique fabric compositions from counterfeiting in a globalized online marketplace remains a persistent operational challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cycling Wear Market |
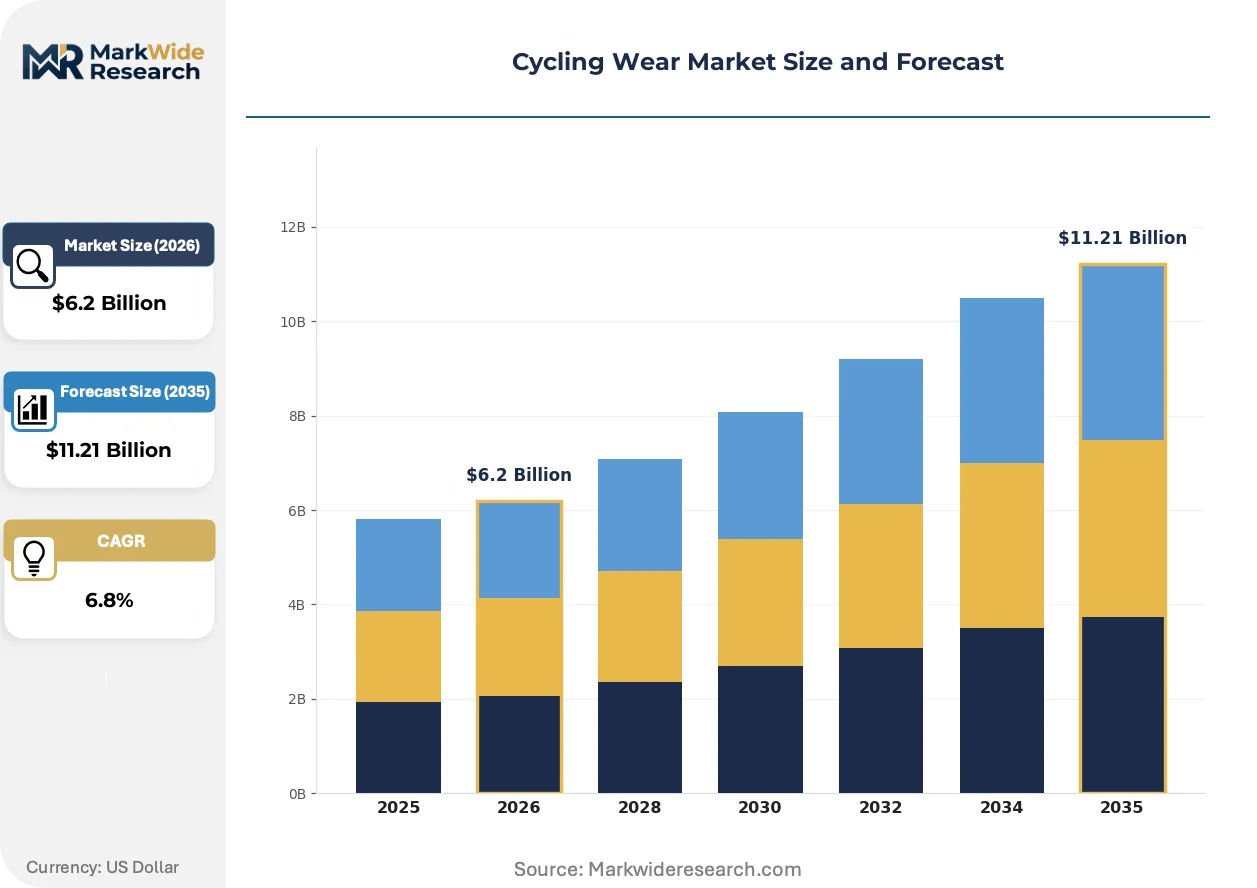
| Market Size in 2026 | $6.2 Billion |
| Market Size in 2035 | $11.21 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shorts, Jerseys, Jackets, Gloves End User: Professional Athletes, Recreational Cyclists, Casual Riders, Women Fabric Type: Polyester, Nylon, Spandex, Merino Wool Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Castelli Cycling, Rapha Racing Limited, ASSOS of Switzerland GmbH, Endura Limited, Pearl Izumi, GIRO SPORT DESIGN, LUMIERE CYCLING, Santini, Isadore Apparel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cycling Wear Market Strategic Shifts & Innovations
Material science advancements and digital connectivity are fundamentally redefining product value in cycling apparel. The focus is shifting from pure performance metrics to a holistic combination of speed, comfort, sustainability, and data integration, creating new avenues for product differentiation.
Bio-based elastomers and advanced recycled nylons derived from fishing nets are emerging as viable alternatives to conventional synthetics. These materials provide the critical stretch and compression properties required for performance wear but with a significantly lower environmental footprint. The premium and eco-conscious consumer segments are driving their adoption, demanding transparency in material sourcing. This movement toward circular and bio-derived inputs is overtaking the market's historical reliance on virgin fossil-fuel-based fabrics.
The EU's proposed Ecodesign for Sustainable Products Regulation (ESPR) is a pivotal policy shift impacting the industry. This directive will mandate digital product passports, requiring manufacturers to disclose detailed information on material composition, recyclability, and environmental impact throughout a garment's lifecycle. The professional and premium apparel categories are most affected, prompting investment in supply chain traceability software and QR-code-based consumer information systems to ensure compliance.
A significant behavioral change is the rise of community-driven purchasing, which bypasses traditional retail calendars. Brands are fostering direct engagement through sponsored cycling clubs and digital platforms, using limited-edition "kit drops" tied to specific events or community milestones. This direct-to-community model is disrupting legacy wholesale channels and is most pronounced in major cycling hubs across Germany, the United States, and Australia.
Cycling Wear Market Segmentation
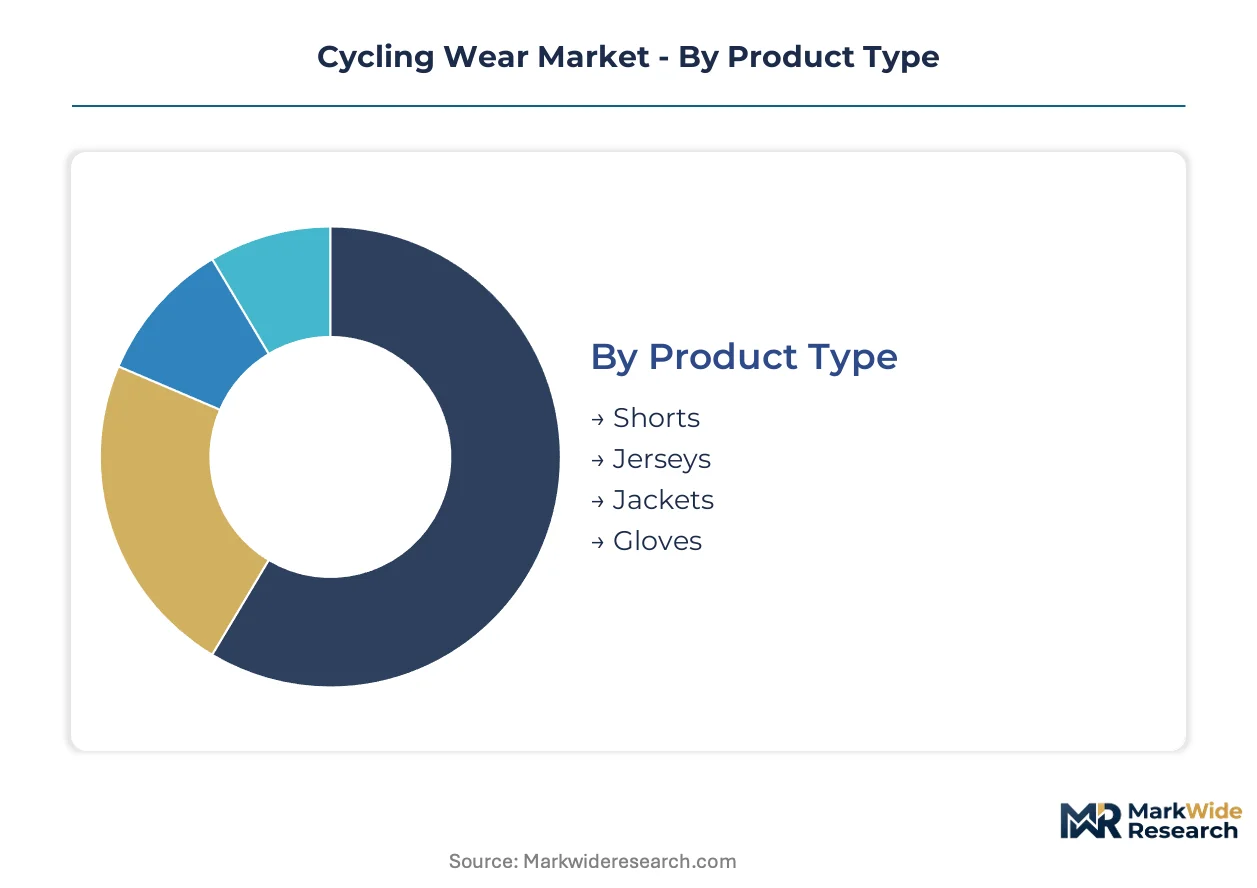
Segmentation provides critical insights into the diverse needs and purchasing behaviors shaping the cycling wear market. Understanding these distinct segments allows manufacturers to tailor product development, marketing strategies, and distribution efforts effectively. This granular view clarifies where specific performance attributes or material innovations will yield the greatest commercial impact.
Product Type:
Product type segmentation in cycling wear reveals varying regulatory compliance needs, with certain garments requiring specific safety certifications for high-performance use.
- Jerseys:These garments prioritize moisture-wicking and aerodynamic performance, often incorporating multi-panel construction for an ergonomic fit. Demand concentrates among professional and recreational cyclists in Europe, driven by performance enhancement and comfort during long rides.
- Shorts:Cycling shorts, including bib shorts, feature padded inserts for comfort and high spandex content for muscle compression. Their demand is high among recreational cyclists and competitive athletes in North America, focusing on endurance and injury prevention.
- Jackets:Designed for weather protection, these often feature windproof and water-resistant fabrics for diverse riding conditions.
- Gloves:Offering grip, comfort, and vibration dampening, gloves are essential accessories for both road and mountain biking.
Jerseys sit at the top of the volume ranking, with Shorts climbing the fastest.
End User:
End user segmentation highlights distinct purchasing motivations and performance expectations across different cyclist groups.
- Recreational Cyclists:This large segment seeks comfort, durability, and aesthetic appeal for fitness, commuting, and leisure rides. Their demand is expanding across Germany and the Netherlands, influenced by health awareness and cycling infrastructure improvements.
- Professional Athletes:These users require apparel engineered for peak aerodynamic efficiency, minimal weight, and advanced moisture management. Demand stems from competitive circuits in Belgium and Italy, where marginal gains in performance are critical.
- Casual Riders:This segment favors comfortable, versatile, and stylish wear suitable for short rides and urban environments.
- Women:Apparel tailored for female anatomy and aesthetic preferences represents a rapidly expanding segment.
Recreational Cyclists dominate the market, while the Women segment is expanding its share.
Fabric Type:
Fabric type segmentation reflects a strategic tension between material cost, performance attributes, and environmental impact.
- Polyester:Valued for its moisture-wicking properties, durability, and cost-effectiveness, recycled polyester is gaining traction. Its adoption is widespread in mass-market and performance apparel across the US, driven by sustainability mandates and consumer preference.
- Spandex:Incorporated for stretch and compression, spandex is crucial for muscle support and freedom of movement. High spandex content is essential for performance wear in European markets, where ergonomic fit and compression are prioritized.
- Nylon:Known for its strength and abrasion resistance, nylon offers good durability for outer layers and reinforcement areas.
- Merino Wool:This natural fiber provides excellent temperature regulation and odor resistance, catering to premium and eco-conscious consumers.
Polyester remains the volume leader, with Merino Wool carving out a premium positioning.
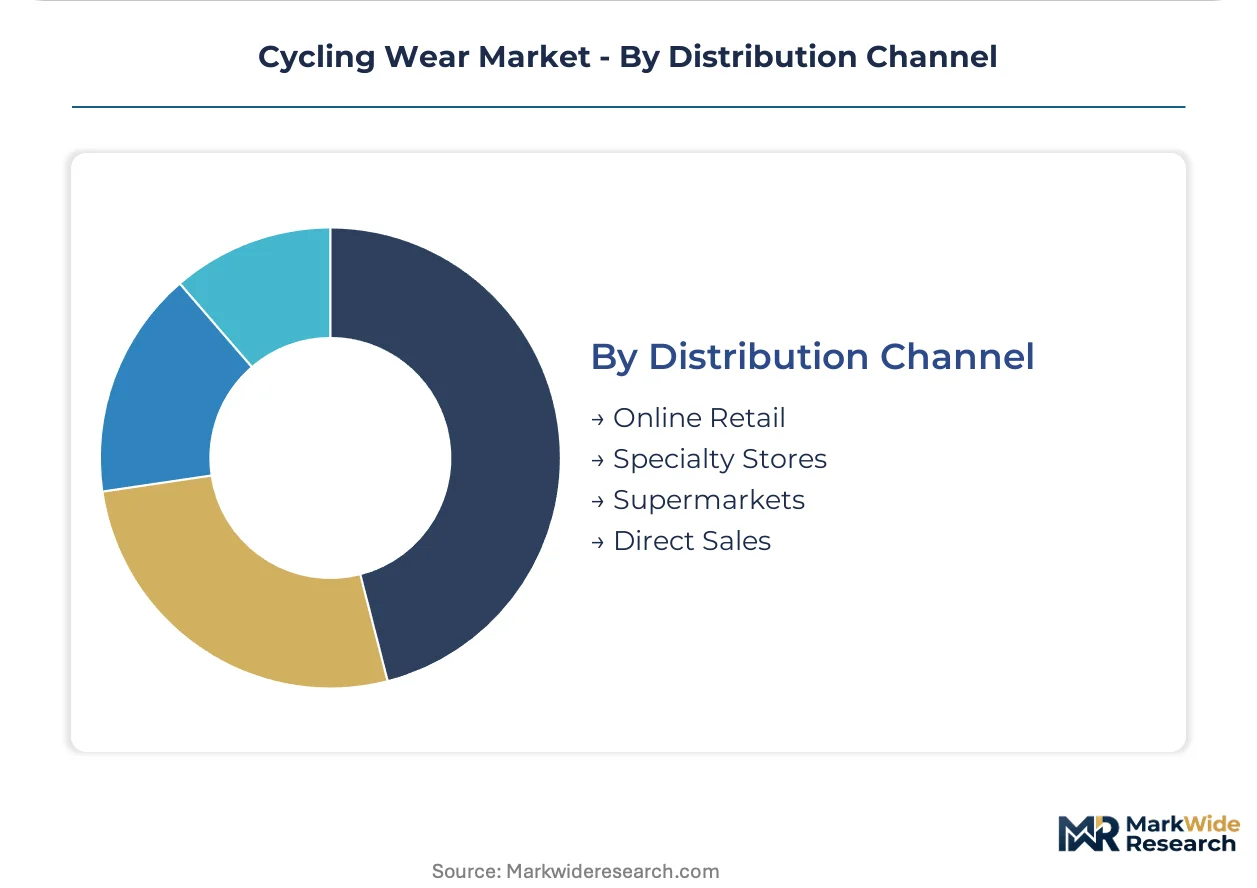
Distribution Channel:
Distribution channel segmentation reveals evolving strategies for customer access and brand engagement.
- Online Retail:This channel offers extensive product ranges, competitive pricing, and global reach, becoming the dominant platform. Its growth is pronounced in North America and Asia-Pacific, fueled by digital native consumers and direct-to-consumer models.
- Specialty Stores:These brick-and-mortar outlets provide expert advice, fitting services, and a curated product selection. They maintain strong presence in cycling-centric regions like the Netherlands, serving enthusiasts seeking personalized guidance and immediate product availability.
- Supermarkets:Primarily offering entry-level or casual cycling apparel, this channel emphasizes convenience and affordability.
- Direct Sales:Brands leverage e-commerce and community engagement to sell directly to consumers, bypassing traditional intermediaries.
Online Retail functions as the dominant channel, while Direct Sales represents a niche but growing approach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European cycling hubs, including Germany, the Netherlands, and Belgium, drive significant demand for cycling wear. These regions combine strong recreational cyclist populations with robust cycling infrastructure. This fosters a market for high-performance and sustainable apparel, aligning with evolving consumer preferences.
Germany
German recreational cyclists prioritize comfort and technical features for fitness and commuting activities. The EU Green Deal influences product development, accelerating recycled fabric adoption across the market. Cities like Munich and Berlin see concentrated demand for innovative, sustainable cycling apparel.
Netherlands
The Netherlands exhibits high demand for durable and weather-resistant cycling wear, supported by extensive cycling infrastructure. The EU's Ecodesign for Sustainable Products Regulation mandates detailed material disclosure for manufacturers. Urban centers within the Randstad region, including Amsterdam, demonstrate strong demand for performance-oriented cycling gear.
United States
United States consumers, particularly recreational cyclists, seek technically advanced apparel for endurance and injury prevention. The FTC enforces strict labeling rules for fiber content and care instructions. California's cycling communities, especially around Los Angeles and San Francisco, represent a major hub for specialized cycling wear.
Australia
Australian cyclists drive demand for performance apparel suitable for diverse climates and outdoor activities. ISO standards for textile performance provide a quality baseline for imported and domestically produced cycling garments. Major cycling hubs like Melbourne and Sydney foster community-driven purchasing and new product trends.
Belgium
Belgium's strong competitive cycling culture generates demand for aerodynamic and high-performance gear. The EU's REACH directive restricts hazardous chemicals in textiles, impacting material selection for apparel components. The Flanders region, a heartland of professional cycling, sees concentrated innovation in specialized athletic wear.
Cycling Wear Market Key Industry Players
Direct-to-consumer expansion dominates the current landscape, allowing specialized brands to bypass traditional retail channels. The market structure exhibits fragmentation, with a mix of established performance-oriented brands and agile sustainable innovators. Strategic archetypes include premium performance specialists, eco-conscious material pioneers, and mass-market comfort providers. Beyond DTC, competitive moves center on strategic partnerships with cycling communities and continuous product differentiation through advanced fabric technology.
Specialists in premium performance apparel include Rapha Racing Limited, which represents brands leveraging strong identity for premium pricing and community engagement. Castelli Cycling exemplifies high-performance gear for competitive cyclists, focusing on aerodynamic advantages and advanced material integration. ASSOS of Switzerland GmbH, a Swiss-based entity, occupies a position emphasizing precision engineering, comfort, and durability for discerning cyclists. These companies collectively anchor the high-end segment, driving innovation in fabric technology, ergonomic design, and sustainable material adoption for enthusiast and professional riders.
| Leading Market Players |
|---|
| Castelli Cycling |
| Rapha Racing Limited |
| ASSOS of Switzerland GmbH |
| Endura Limited |
| Pearl Izumi |
| GIRO SPORT DESIGN |
| LUMIERE CYCLING |
| Santini |
| Isadore Apparel |
Cost & Logistics Intelligence
Consumer and regulatory demands for circularity, particularly the use of recycled polyester, necessitate supply chain reconfiguration, influencing material sourcing costs and final product pricing across the cycling wear market.
Pricing Analysis
Input cost volatility from petroleum-derived spandex and specialized recycled polyester feedstocks directly impacts cycling apparel pricing. The market primarily utilizes a tiered premium-mid-economy pricing differentiation, reflecting brand identity and performance attributes. Price differentiation stems from sustainability certifications like Bluesign and advanced material integration for aerodynamic efficiency. Pricing pressure in the premium segment arises from the high cost of innovative eco-materials, while recreational cyclists exhibit the most price sensitivity for basic comfort wear.
Supply Chain Analysis
Single-source vulnerability sits with the evolving network of qualified recycled material vendors, which remains fragmented. The cycling wear supply chain draws heavily from textile manufacturing hubs in Asia for base polyester and nylon. Raw material dependencies include recycled polyester, spandex, and emerging bio-based elastomers. Supply chain risk primarily stems from certification delays. Distribution runs through a dominant online retail channel and specialty stores.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cycling wear market presents a geographic-arbitrage play, leveraging lower production costs in Asian manufacturing hubs against premium pricing opportunities driven by sustainability mandates in European markets.
For Market Incumbents: Lock in long-term supply agreements for specialized recycled polyester and bio-based elastomers to mitigate input cost volatility. Invest in proprietary fabric technologies, such as advanced seamless bonding, to enhance performance differentiation and maintain premium pricing. This defends against emerging entrants leveraging lower-cost, generic recycled fabrics. Certification investment in Oeko-Tex or Bluesign standards also reinforces brand trust.
For New Entrants and Emerging Players: Capture white space in nascent cycling cultures across Asia-Pacific and Latin American urban centers. Target recreational cyclists with comfortable, aesthetically appealing, and sustainably sourced apparel as the most penetrable segment. A direct-to-consumer e-commerce model, combined with community-driven purchasing initiatives, offers a cost-effective go-to-market angle. Prioritize transparency in material sourcing to build early brand loyalty.
For Investors and Strategic Acquirers: Asymmetric upside sits with eco-conscious material pioneers specializing in bio-based elastomers or advanced recycled nylons. Long-term viability in cycling wear depends on companies with robust supply chain traceability and sustainability certifications. Acquisition targets include firms developing smart apparel integration technologies, offering significant differentiation. The expansion of cycling infrastructure in major urban centers across Asia-Pacific serves as a critical signal to watch for market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrate Bio-based Elastomers | Reduces reliance on petroleum-derived spandex, aligning with EU Green Deal sustainability objectives. |
| Launch Smart Apparel Line | Addresses growing consumer demand for biometric data integration in cycling communities. |
| Expand Direct-to-Consumer Channels | Bypasses traditional retail gatekeepers, fostering direct engagement with recreational cyclists. |
| Form Strategic Material Partnerships | Secures access to innovative recycled fabrics and advanced ultrasonic welding technologies. |
| Obtain Sustainability Certifications | Ensures compliance with EU's Ecodesign Regulation and builds trust among eco-conscious consumers. |
Research Approach
Bottom-up end-user segment modeling reconciled against top-down market volume tracking forms the analytical core. This approach combines primary interviews with product developers, material scientists, brand managers, and retail buyers. Secondary validation draws from EU Green Deal reports, FTC regulations, ISO standards, and textile industry association publications. This triangulation ensures a robust understanding of market dynamics.
The input-output matrix framing delineates market projections across the modeling period. Segmentation dimensions modeled include product type, end user, fabric type, distribution channel, and regional adoption patterns. Compound Annual Growth Rates were derived through regression analysis and market share projections for each segment. Cycling infrastructure investment and consumer health trend data serve as key industry-specific forecast inputs.
Raw material price volatility, evolving sustainability regulations, and shifts in consumer leisure activities are the dominant revision risks. Forecasts reflect assumptions documented through extensive primary and secondary research. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sportswear
Global Women Active Wear Market
Sportswear
Cycling Apparel Market
Sportswear
Bicycle Apparels Market
Sportswear
Workout Clothes Market
Sportswear
Casual Sportswear Market
Sportswear
Activewear Market
Sportswear
Athleisure Market
Sportswear
Cricket Bowling Machine Market
Sportswear
Sports Socks for Children Market
Sportswear
Europe Dancewear Market
Sportswear
Athleisure Wear Market
Sportswear
Skateboard Grip Tapes Market
Sportswear
Billiards and Snooker Equipment Market
Sportswear
North America Dancewear Market