
 Activewear Market | 2026-2036
Activewear Market Size, Share, and Industry Trends Forecast 2026-2036
Activewear Market Intelligence
The shift in consumer spending from single-purpose athletic apparel to versatile lifestyle activewear is reshaping competitive positioning. Nike leverages its iconic brand to dominate both performance and fashion-forward segments. Lululemon Athletica sustains its premium market standing through community-centric strategies and material innovation. Meanwhile, adidas competes effectively by integrating high-fashion collaborations with its established sports heritage.
Activewear comprises garments engineered for physical activity, featuring properties like moisture-wicking and four-way stretch. These fabrics, often blends of polyester and spandex, are designed to enhance performance and comfort during exercise. Leggings and sports bras represent high-volume product types, particularly popular among fitness enthusiasts. While online retailers are the fastest-growing distribution channel, specialty stores maintain a strong presence for high-end products.
Regulations like the EU's REACH directive control chemical use in textiles, affecting dyes and finishes. In the United States, the FTC's Green Guides scrutinize sustainability claims, influencing marketing. China's GB standards impose strict quality and safety requirements on all apparel sold. Navigating this complex web of international material and labeling rules is critical for market access and brand credibility.
Market Dynamics
The activewear market's core dynamic is the accelerating convergence of performance material science with stringent sustainability mandates. This creates a structural tension where demand for features like four-way stretch and moisture-wicking must be reconciled with regulatory and consumer pressure for circularity and reduced chemical footprints.
Growth Catalysts
- Urban Health Consciousness:Rising disposable incomes and a focus on wellness in major metropolitan areas, particularly within cities like Shanghai, are expanding the base of consumers investing in specialized fitness apparel.
- Recycled Material Innovation:Advances in converting PET bottles and other post-consumer waste into high-quality recycled polyester fibers provide a scalable input that helps brands meet sustainability targets and appeal to eco-conscious buyers.
- EU Sustainability Directives:Regulations such as the Corporate Sustainability Reporting Directive (CSRD) are compelling large apparel companies to improve supply chain transparency and adopt more sustainable materials, stimulating demand for compliant textiles.
Market Restraints
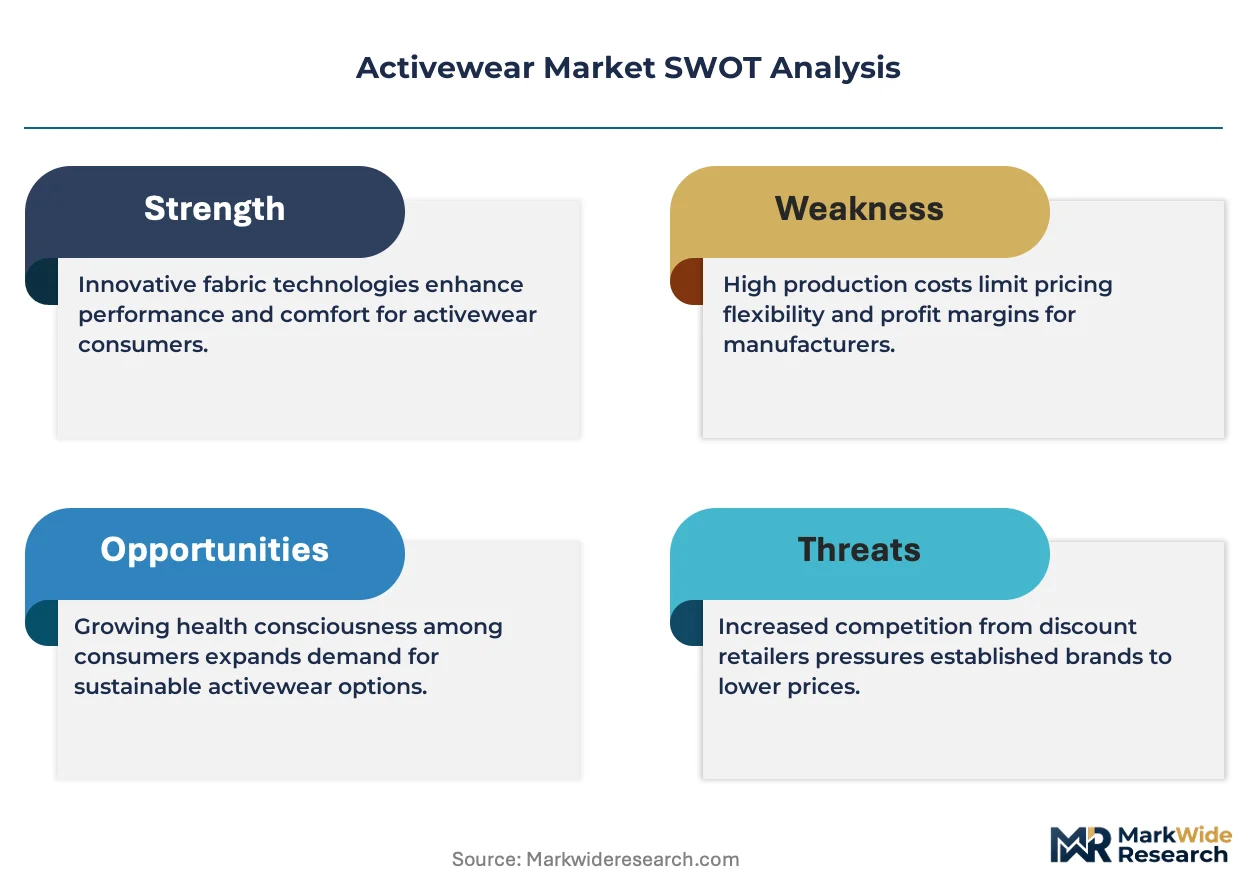
- Input Cost Volatility:The prices of key synthetic inputs like polyester and spandex are directly linked to petroleum markets, exposing manufacturers to significant cost fluctuations that can compress margins.
- Fragmented Regulatory Landscape:Brands face a complex web of differing material and labeling rules, such as the EU's REACH directive, China's GB standards, and the FTC's Green Guides, which increases compliance costs and market entry barriers.
- Textile Production Concentration:Heavy reliance on a few countries in Asia for textile manufacturing and garment assembly creates supply chain vulnerabilities, exposing the market to geopolitical risks and logistical disruptions.
Strategic Opportunities
- Adaptive Activewear:Designing apparel for individuals with disabilities or specific medical needs represents a significant, underserved market segment, offering opportunities for product innovation and brand differentiation.
- Smart Textile Integration:Embedding biometric sensors and conductive fibers into garments opens a new frontier for performance monitoring, connecting activewear to the digital health ecosystem and creating new data-driven services.
- Geographic Expansion:Markets in South America and Southeast Asia with growing middle-class populations and increasing participation in fitness activities present untapped geographic expansion opportunities for established and new brands.
Industry Challenges
- Reverse Logistics Complexity:The high volume of returns from online apparel sales creates significant operational and financial challenges, requiring sophisticated reverse logistics systems to manage inspection, reprocessing, and restocking.
- Sustainability Claim Verification:Authenticating the source and composition of recycled or organic materials across multi-tiered global supply chains is a major challenge, risking brand credibility amid growing consumer and regulatory scrutiny.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Activewear Market |
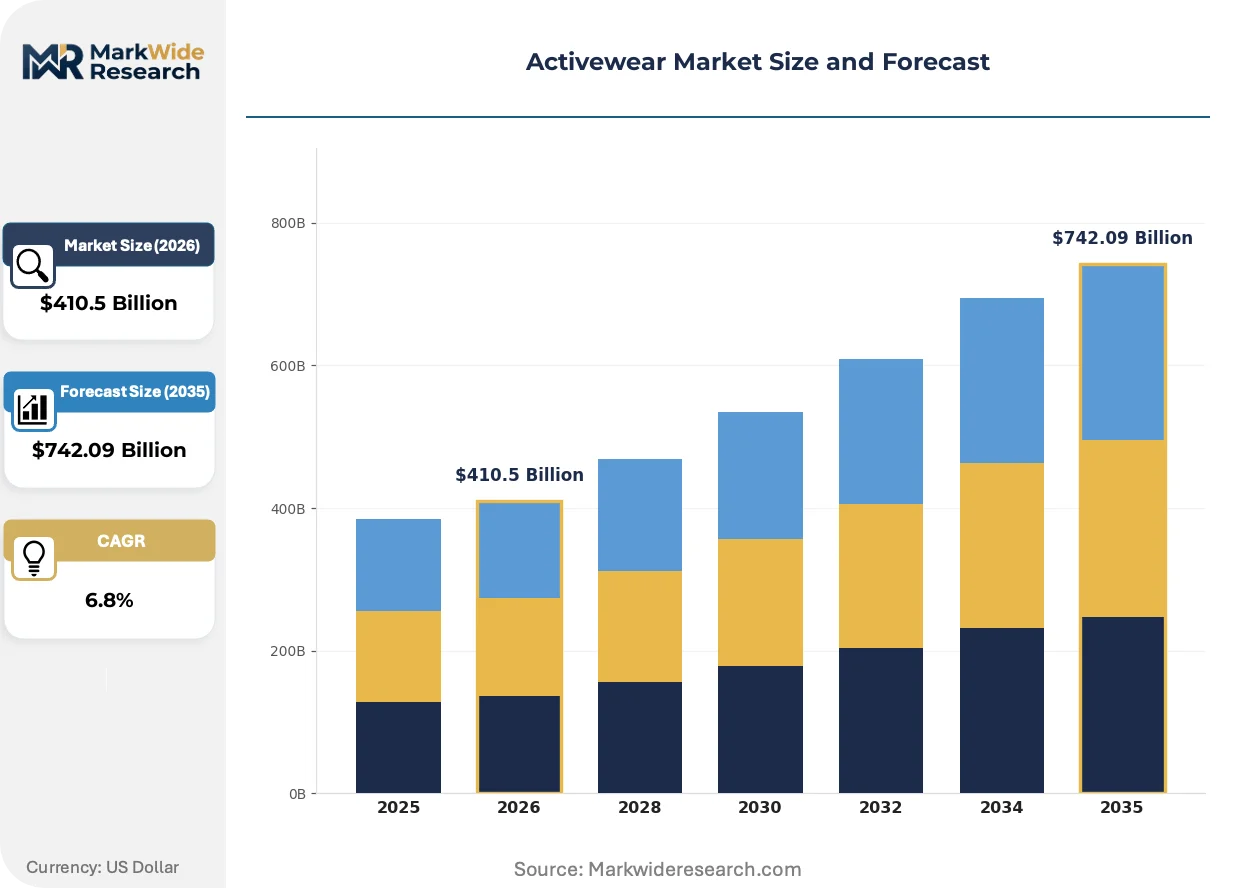
| Market Size in 2026 | $410.5 Billion |
| Market Size in 2035 | $742.09 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Leggings, Sports Bras, T-Shirts, Jackets End User: Athletes, Fitness Enthusiasts, Casual Users, Outdoor Adventurers Distribution Channel: Online Retailers, Specialty Stores, Department Stores, Direct Sales Material: Polyester, Nylon, Cotton, Spandex |
| Companies Covered | ANTA Sports, Under Armour, Nike, Skechers, ASICS, adidas, PUMA, Columbia Sportswear, Lululemon Athletica, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Activewear Market Strategic Shifts & Innovations
The market is defined by a fundamental shift toward multifunctional apparel, where the lines between athletic performance, casual comfort, and fashion aesthetics blur. This evolution is driven by material science, changing consumer lifestyles, and a new wave of digital integration that redefines the purpose of a garment.
Smart fabrics incorporating micro-encapsulation technology are a key product evolution. These textiles are engineered to release substances like moisturizers or anti-inflammatory agents during physical activity. Adoption is currently focused within premium and niche wellness segments seeking recovery and skin-care benefits. This technology is hybridizing activewear with topical cosmetics, creating a new "wearable wellness" category that moves beyond simple performance metrics.
China's "dual carbon" policy goals are influencing material sourcing and production processes for apparel manufacturers globally. The policy incentivizes lower-emission manufacturing and the use of sustainable materials, impacting the cost structure for factories operating within the country. Activewear brands that rely heavily on Chinese manufacturing are now re-evaluating their supplier base and investing in cleaner production technologies to align with these national targets.
Direct-to-consumer sales models are evolving beyond simple brand websites toward community-based digital platforms. Instead of just transacting, brands are building ecosystems that include workout apps, live-streamed fitness classes, and member-exclusive events. This channel shift, most visible in the North American and European markets, transforms a one-time purchase into a recurring subscription-like relationship, enhancing customer loyalty and lifetime value.
Activewear Market Segmentation
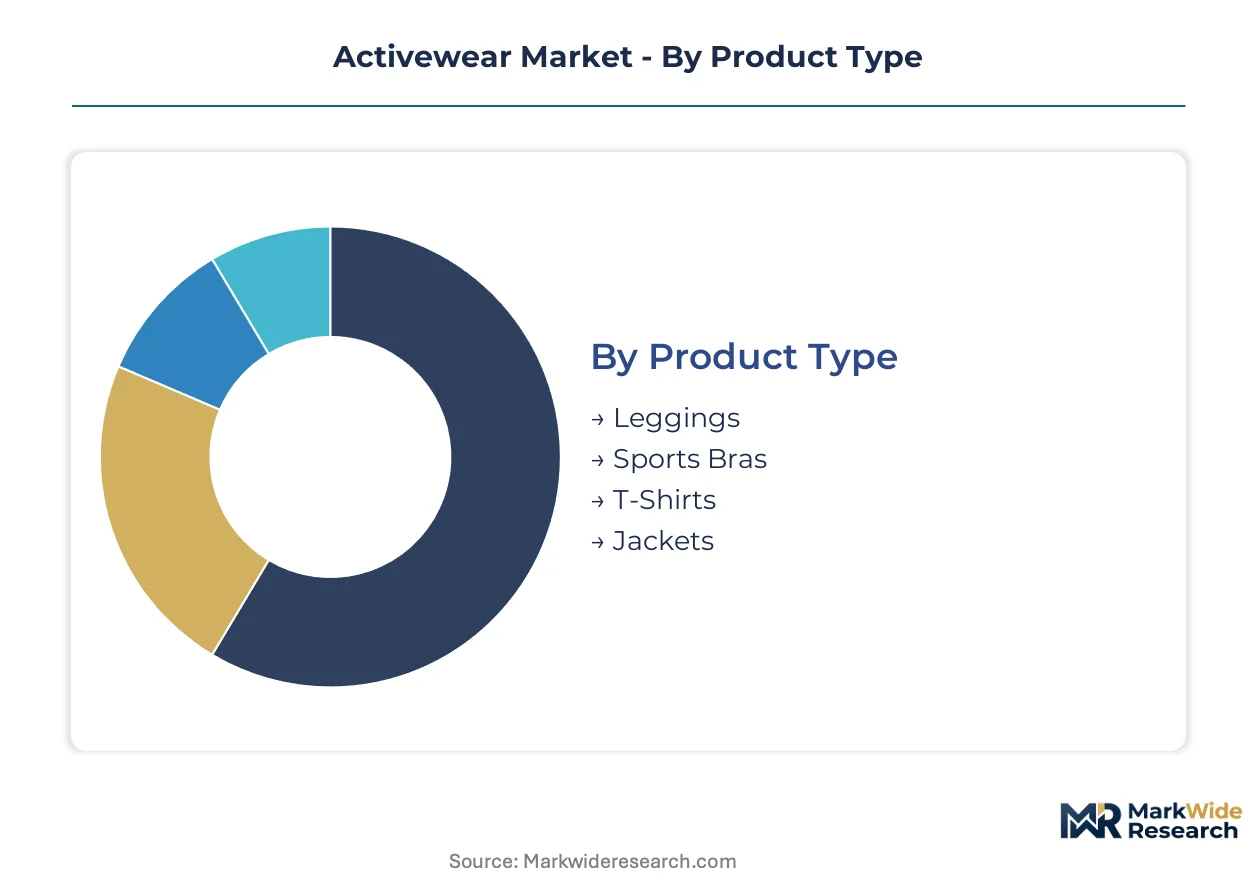
Understanding the distinct segments within the activewear market is critical for brands to tailor product development, marketing strategies, and distribution efforts. This segmentation allows companies to address specific consumer needs and regulatory requirements across diverse product types, end-users, distribution channels, and material compositions.
Product Type:
The turnover rate of activewear products varies significantly across categories, with some items experiencing faster replacement cycles due to wear, fashion trends, or seasonal utility.
- Leggings:These form-fitting garments, typically made from polyester and spandex blends, offer flexibility and moisture-wicking properties essential for diverse physical activities. Demand for leggings is strong among fitness enthusiasts across Europe and North America, driven by their versatility for both exercise and casual wear.
- Sports Bras:Engineered to provide support and minimize movement during physical activity, sports bras utilize specialized fabrics and construction for comfort and performance. Their adoption is high among female athletes and fitness participants globally, with innovation focusing on impact level and material breathability.
- T-Shirts:Activewear t-shirts incorporate lightweight, breathable fabrics designed for comfort and sweat management during workouts.
- Jackets:These outer layers provide warmth, wind resistance, and water repellency, catering to outdoor activities and cooler climates.
Leggings and sports bras dominate the installed base due to their fundamental role in active lifestyles. Jackets are where expansion concentrates, particularly with integration of smart textile technologies.
End User:
The price sensitivity and demand for specialized features differ considerably among various end-user groups, influencing product design and material choices.
- Fitness Enthusiasts:Individuals regularly engaging in gym workouts, running, and studio classes prioritize comfort, flexibility, and moisture-wicking properties in their apparel. This segment drives significant volume in major urban centers like Shanghai, where health consciousness is rising.
- Casual Users:Consumers adopting activewear for everyday comfort and fashion, rather than solely for exercise, seek versatile designs and soft, durable fabrics. This demographic represents a substantial portion of the market, particularly in North America, favoring lifestyle-oriented activewear.
- Athletes:Professional and amateur athletes demand high-performance apparel optimized for specific sports, focusing on advanced technical fabrics and ergonomic designs.
- Outdoor Adventurers:This group requires durable, weather-resistant activewear suitable for hiking, climbing, and other outdoor pursuits, often incorporating features like UV protection and thermal regulation.
Fitness Enthusiasts drive the largest volume across the market. Casual Users are exhibiting the strongest growth trajectory.
Distribution Channel:
Each distribution channel offers distinct advantages in terms of reach, customer experience, and operational efficiency, shaping how activewear reaches consumers.
- Online Retailers:E-commerce platforms provide extensive product selections, competitive pricing, and convenience, appealing to a broad global customer base. This channel is expanding most quickly in North American and European markets, driven by changing consumer purchasing habits.
- Specialty Stores:These dedicated activewear outlets offer curated product assortments, expert advice, and a personalized shopping experience, attracting consumers seeking premium brands and specialized gear. Specialty stores maintain a strong presence for high-end products in key metropolitan areas.
- Department Stores:Large retail establishments offer a diverse range of activewear brands alongside other apparel categories, providing convenience for general shoppers.
- Direct Sales:Brands selling directly to consumers through their own stores or websites allow for greater brand control and direct customer engagement.
Online Retailers offer unparalleled market access. Specialty Stores build brand loyalty through curated experiences.
Material:
The selection of materials is increasingly influenced by both performance requirements and sustainability mandates, creating varying supply chain complexities and cost structures.
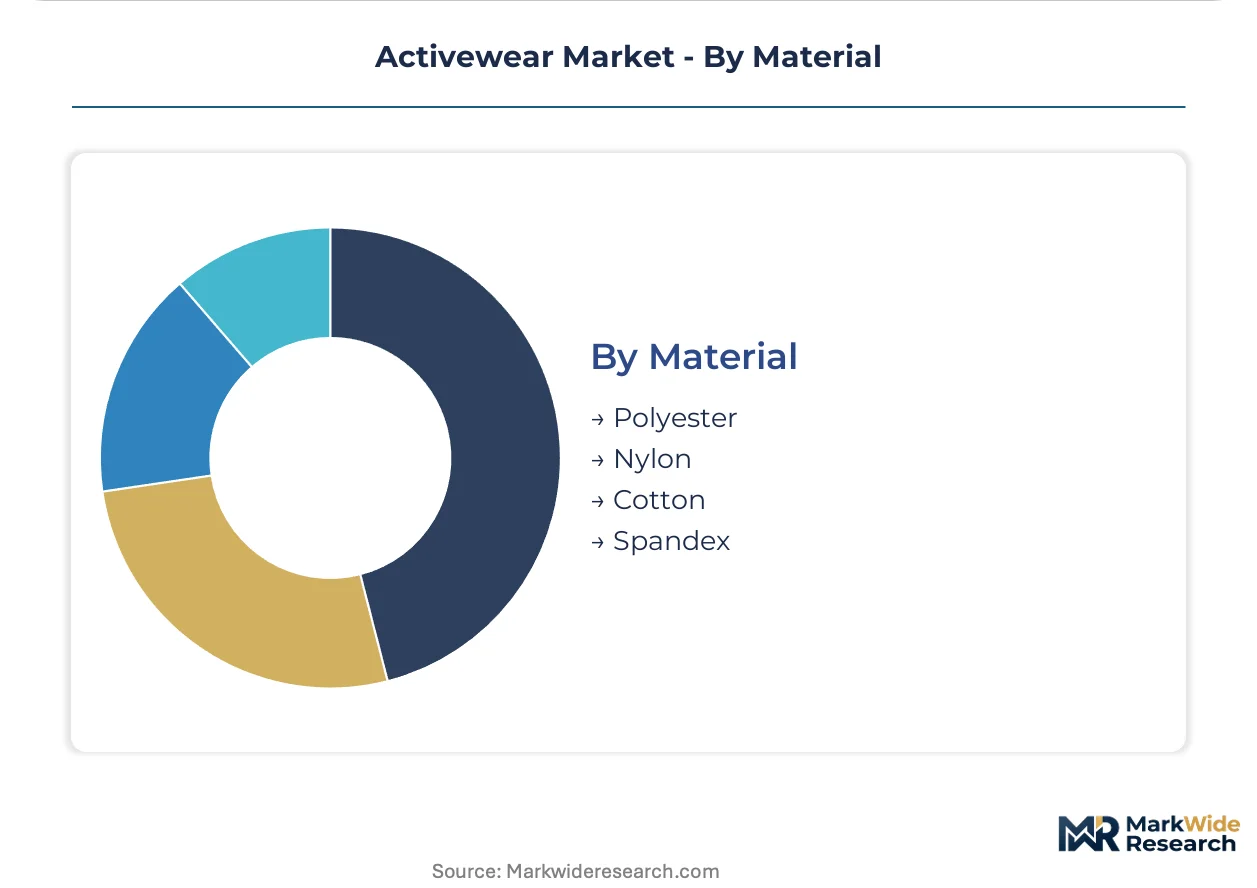
- Polyester:A synthetic fiber widely used for its durability, wrinkle resistance, and moisture-wicking capabilities, polyester is a staple in activewear production. The adoption of recycled polyester responds to stricter environmental regulations, such as the EU's Corporate Sustainability Reporting Directive (CSRD), particularly in Europe.
- Spandex:Known for its exceptional elasticity and stretch recovery, spandex (also known as elastane or Lycra) is blended with other fibers to provide freedom of movement and shape retention. Its integration is critical for garments requiring four-way stretch, driving innovation in comfort and fit.
- Nylon:This synthetic polymer offers strength, abrasion resistance, and a smooth feel, making it suitable for various activewear applications.
- Cotton:A natural fiber prized for its softness and breathability, cotton is often used in activewear for casual comfort, though it lacks the moisture-wicking properties of synthetics.
Polyester is central to material innovation, particularly with recycled variants. Cotton retains a strong traditional use case for comfort-focused activewear.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for activewear varies across global markets, with consumers in developed economies often prioritizing premium features and sustainability, exhibiting lower price sensitivity. Conversely, emerging markets frequently focus on versatile, value-driven apparel, demonstrating higher price elasticity. This distinction shapes product strategies and distribution models across different regions.
United States
Casual users and fitness enthusiasts drive significant activewear demand, valuing comfort, versatility, and brand reputation. The FTC's Green Guides influence marketing claims, compelling brands to verify sustainability attributes. Los Angeles serves as a major hub for lifestyle activewear design and trendsetting, shaping consumer preferences nationwide.
Germany
German consumers prioritize product durability, technical performance, and sustainable sourcing in their activewear purchases. The EU's Corporate Sustainability Reporting Directive (CSRD) mandates increased transparency for large apparel companies operating in the market. Munich and its surrounding region lead in outdoor and technical textile innovation, catering to demanding consumers.
China
Urban health consciousness and rising disposable incomes fuel a strong demand for specialized fitness apparel, particularly in metropolitan areas. China's dual carbon policy goals are influencing material sourcing and manufacturing processes for brands with local operations. Shanghai is a critical hub for activewear consumption and a key center for aligning production with national sustainability targets.
India
The expanding middle class and increasing participation in fitness activities generate substantial demand for affordable yet functional activewear. The Bureau of Indian Standards (BIS) sets quality and safety benchmarks for textile products sold domestically. Bengaluru's youthful population and tech workforce drive demand for practical, everyday activewear suitable for diverse activities.
Brazil
Growing interest in outdoor sports and wellness, coupled with a developing middle class, contributes to the market's expansion. ANVISA regulations impact textile chemical use, ensuring product safety for consumers in the country. São Paulo's vibrant fitness culture and fashion-forward approach stimulate demand for colorful and performance-oriented activewear designs.
Activewear Market Key Industry Players
Capability concentration sits with one tier of activewear companies focused on material science and design innovation; scale advantage sits with another tier leveraging extensive global manufacturing and distribution networks. The market structure exhibits a tiered consolidation, with a few dominant players alongside a multitude of niche and specialized brands. Strategic archetypes include performance-driven specialists, lifestyle-focused brands, and value-oriented mass-market providers. Companies primarily engage in material innovation and direct-to-consumer expansion to secure market share.
Within the performance-driven segment, Nike and adidas exemplify global reach and continuous product innovation across diverse sports categories. Both companies integrate high-fashion collaborations with their established sports heritage, appealing to a broad consumer base. Lululemon Athletica occupies a distinct position on the premium-tier vector, maintaining its market standing through community-centric strategies and advanced material science, particularly for yoga and lifestyle apparel.
| Leading Market Players |
|---|
| ANTA Sports |
| Under Armour |
| Nike |
| Skechers |
| ASICS |
| adidas |
| PUMA |
| Columbia Sportswear |
| Lululemon Athletica |
| Others |
Cost & Logistics Intelligence
Input cost volatility, tied directly to petroleum markets, determines activewear pricing tier spreads and shapes supply chain resilience. This dependency forces brands to balance raw material procurement against consumer price sensitivity.
Pricing Analysis
Brand loyalty programs, often bundled with community access and exclusive content, drive significant lifetime value for activewear brands. Pricing stratifies across premium, mid-range, and value tiers, differentiated by brand premium and material innovation. Pricing pressure stems from intense competition, particularly in the mid-range segment. Casual users exhibit the highest price sensitivity, while professional athletes prioritize performance over cost.
Supply Chain Analysis
Trade tariffs, particularly those between major economic blocs, limit the free flow of finished activewear goods and raw materials. Activewear production concentrates in China, Vietnam, and Bangladesh, drawing heavily from polyester, spandex, and specialized dyes. This reliance creates supply chain vulnerabilities to geopolitical risks and logistical disruptions. Distribution runs through a dual model, leveraging extensive online retailers for reach and specialty stores for curated experiences.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The activewear market is experiencing a buyer-power shift, driven by fragmented consumer preferences for sustainable products and personalized wellness solutions. This shift compels brands to adapt offerings to specific ethical and lifestyle demands.
For Market Incumbents: Insulate core market share through continuous material science R&D, focusing on sustainable and performance-enhancing fabrics. Deepen vertical integration into recycled polyester production to mitigate input cost volatility and meet EU CSRD mandates. Enhance direct-to-consumer channel control to counter emerging niche brand threats and capture higher margins. Invest in robust third-party certifications to validate sustainability claims, building brand credibility against FTC Green Guides scrutiny. For New Entrants and Emerging Players: Establish a beachhead in underserved segments like adaptive activewear for individuals with disabilities, offering specialized designs and inclusive marketing. Target smart textile integration by embedding biometric sensors for performance monitoring, connecting garments to digital health ecosystems. Focus on geographic expansion into South America, leveraging growing middle-class populations and fitness participation. Employ community-based digital platforms to foster loyalty and create subscription-like relationships. For Investors and Strategic Acquirers: The market sits at a growth phase that favors niche innovators with strong intellectual property in sustainable materials or smart textile integration. Long-term viability hinges on companies that can reconcile performance demands with stringent sustainability mandates over the next decade. Target acquisition profiles include agile brands with established community-centric digital platforms or proprietary adaptive activewear designs. The signal to watch is the sustained growth in consumer engagement with wearable wellness technologies.| Strategic Initiative | Industry Significance |
|---|---|
| Material Science R&D Investment | Drives innovation in sustainable and performance-enhancing fabrics, crucial for meeting consumer and regulatory demands. |
| Direct-to-Consumer Channel Expansion | Enhances brand control and customer loyalty, bypassing traditional retail intermediaries for improved margins. |
| Adaptive Activewear Product Launch | Addresses a significant, underserved market segment, fostering inclusivity and brand differentiation. |
| Smart Textile Technology Integration | Opens new revenue streams by connecting garments to the digital health ecosystem for performance monitoring. |
| Sustainability Certification Program | Verifies eco-friendly claims, building brand trust and ensuring compliance with directives like the EU CSRD. |
Research Approach
A standing panel of activewear brand managers, textile engineers, retail buyers, and sustainability officers provided ongoing calibration and insights. This involved combining primary interviews with industry stakeholders and secondary validation from sources like EU CSRD reports and China GB standards. The analysis employed both bottom-up and top-down triangulation to ensure data accuracy. This dual approach captured granular market dynamics and broader industry trends.
Scenario-bracketing provided a robust framework for projecting market trajectories across the analysis window, considering various growth and restraint factors. Segmentation dimensions modeled included product type, end-user, distribution channel, material composition, and regional regulatory clusters. Compound Annual Growth Rates were derived through regression analysis of historical data and projected market drivers. Key forecast inputs included recycled polyester adoption rates and urban health consciousness indices.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending or global trade policies would shift the trajectory. Forecasts reflect assumptions documented from the current market environment and regulatory landscape. Material shifts in textile recycling technology or significant new sustainability directives would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sportswear
North America Dancewear Market
Sportswear
Bicycle Apparels Market
Sportswear
Workout Clothes Market
Sportswear
Billiards and Snooker Equipment Market
Sportswear
Cricket Bowling Machine Market
Sportswear
Skateboard Grip Tapes Market
Sportswear
Sports Socks for Children Market
Sportswear
Athleisure Market
Sportswear
Global Women Active Wear Market
Sportswear
Cycling Wear Market
Sportswear
Casual Sportswear Market
Sportswear
Cycling Apparel Market
Sportswear
Athleisure Wear Market
Sportswear
Europe Dancewear Market