
 Cycling Apparel Market | 2026-2036
Cycling Apparel Market Size, Share, and Industry Trends Forecast 2026-2036
Cycling Apparel Market Intelligence
Market Context
Italian manufacturing is consolidating around high-performance cycling apparel production, with Lombardy and Veneto maintaining dense supplier networks for premium kit. Pearl Izumi leverages its North American distribution infrastructure to serve specialty retailers and direct-to-consumer channels simultaneously. Rapha differentiates through membership-driven community programming that sustains pricing power independent of seasonal product cycles. Castelli anchors its competitive position in European pro-team sponsorships that reinforce brand credibility among serious amateurs.
Technical Definition and Segment Structure
Cycling apparel encompasses form-fitting garments engineered with aerodynamic paneling, moisture-wicking synthetic or natural fiber blends, and compressive structures designed to reduce muscle fatigue and improve thermoregulation during sustained exertion. Polyester dominates material inputs for its durability and sublimation-print compatibility, though merino wool is gaining share in touring and commuter segments where odor resistance and temperature modulation outweigh pure aerodynamic optimization. Professional cyclists drive premium pricing and technical innovation, while casual riders represent the largest volume pool as urban mobility trends normalize bicycle commuting across developed cities. E-commerce channels are displacing specialty shop foot traffic for replenishment purchases, though fit-dependent categories like bib shorts and performance jackets retain higher in-store conversion rates.
Regulatory Framework and Outlook
REACH in the European Union and OEKO-TEX Standard 100 constrain chemical inputs across dyeing and finishing processes, compelling reformulation of water-repellent coatings and antimicrobial treatments. The US Consumer Product Safety Commission governs flammability and labeling standards for children's cycling apparel, while California's Proposition 65 creates disclosure obligations for brands distributing in that state. Stakeholders must monitor evolving extended producer responsibility frameworks in France and Germany that will impose end-of-life collection obligations on textile brands serving those markets.
Market Dynamics
REACH compliance deadlines are forcing rapid reformulation of fluorinated water repellents and synthetic dyes across European supply chains, compressing margins for brands dependent on legacy finishing processes while advantaging early movers with certified alternatives.
Growth Catalysts
- Gran fondo participation:Amateur endurance events in Italy, France, and Belgium are expanding the addressable base for technical bib shorts and aerodynamic jerseys with pro-grade specifications.
- REACH chemical disclosure:ECHA's tightening requirements on per- and polyfluoroalkyl substances are accelerating adoption of bio-based water repellents among premium manufacturers seeking compliance headroom.
- Merino wool blends:Odor-resistant natural fiber innovations are capturing touring and commuter segments where temperature modulation outweighs pure aerodynamic optimization.
Market Restraints
- Petrochemical input volatility:Polyester price swings tied to crude oil markets destabilize margin planning for volume-dependent mid-tier producers.
- Chinese manufacturing concentration:Contract manufacturer consolidation in Guangdong and Zhejiang provinces creates bottleneck risk for brands without diversified sourcing.
- Sub-threshold performance gains:Diminishing aerodynamic returns on paneling refinements above $200 price points limit justification for further premiumization.
Strategic Opportunities
- Urban mobility normalization:Bicycle commuting infrastructure expansion in Copenhagen, Amsterdam, and Paris is creating demand for transitional apparel bridging performance and workplace appropriateness.
- Extended producer responsibility:France's AGEC law and Germany's Textile Strategy EPR frameworks will impose end-of-life collection obligations, rewarding brands with established circular infrastructure.
- Digital fit technologies:3D body scanning and AI-powered size recommendation tools are reducing return rates for direct-to-consumer channels in fit-critical categories like bib shorts.
Industry Challenges
- Pattern engineering talent scarcity:Specialized knowledge in aerodynamic paneling and compressive structure design concentrates among aging technicians in Lombardy and Veneto.
- Dual certification timelines:Simultaneous OEKO-TEX Standard 100 and bluesign approval processes extend product development cycles by 4-8 months for reformulated collections.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cycling Apparel Market |
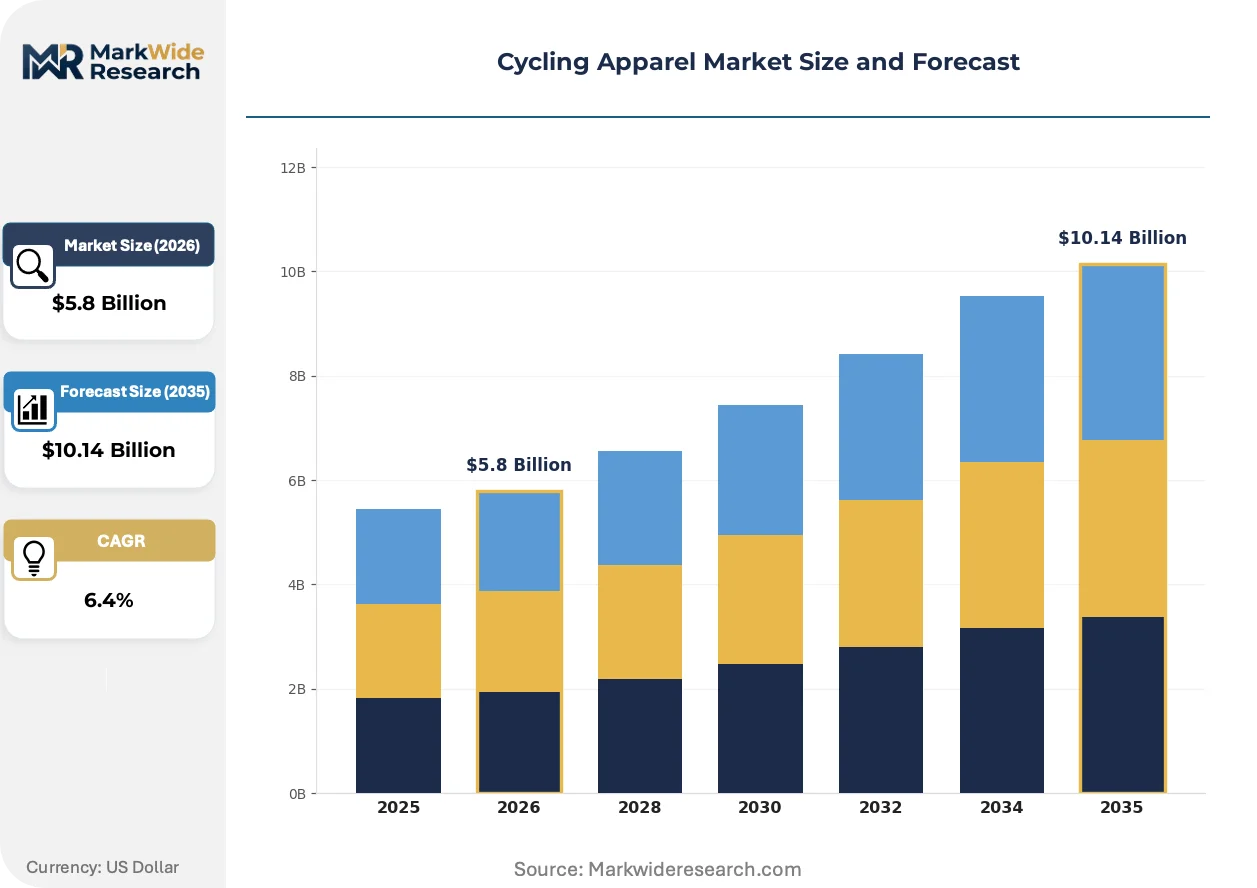
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.14 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shorts, Jerseys, Jackets, Gloves End User: Professional Cyclists, Casual Riders, Recreational Users, Mountain Bikers Material: Polyester, Nylon, Merino Wool, Spandex Distribution Channel: E-commerce, Retail Stores, Specialty Shops, Events |
| Companies Covered | Pearl Izumi, Adidas, Rapha, Santini, Endura, Assos, Nike, Giordana, Castelli, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cycling Apparel Market Strategic Shifts & Innovations
Biomechanical sensor integration and sustainable material science are converging to redefine performance benchmarks, while regulatory pressure on chemical inputs is accelerating substitution timelines across finishing processes.
Seamless knitting technology is rewriting production economics for base layer categories. Single-piece construction eliminates traditional cut-and-sew labor, compressing unit costs by 30-40% while enabling gradient compression mapping previously achievable only through multi-panel assembly. European pro-team suppliers are adopting these systems fastest, forcing tier-two manufacturers to retool or retreat to commodity jersey production.
ECHA's 2023 restriction proposal on PFAS in textiles is compelling wholesale reformulation of durable water repellent coatings. Brands with approved fluorine-free alternatives from Schoeller or Bionic Finish Eco are securing shelf space ahead of enforcement deadlines. The premium outerwear segment faces the steepest compliance curve, as mountain and all-weather jackets historically relied most heavily on C6 and C8 chemistries.
Subscription-based kit replacement programs are displacing seasonal purchase cycles among dedicated amateurs. Rapha's membership model and Pearl Izumi's loyalty tiers normalize continuous garment refresh rather than event-driven buying. This behavioral shift concentrates most visibly in North American and British markets where credit-based consumption patterns already dominate apparel purchasing.
Cycling Apparel Market Segmentation
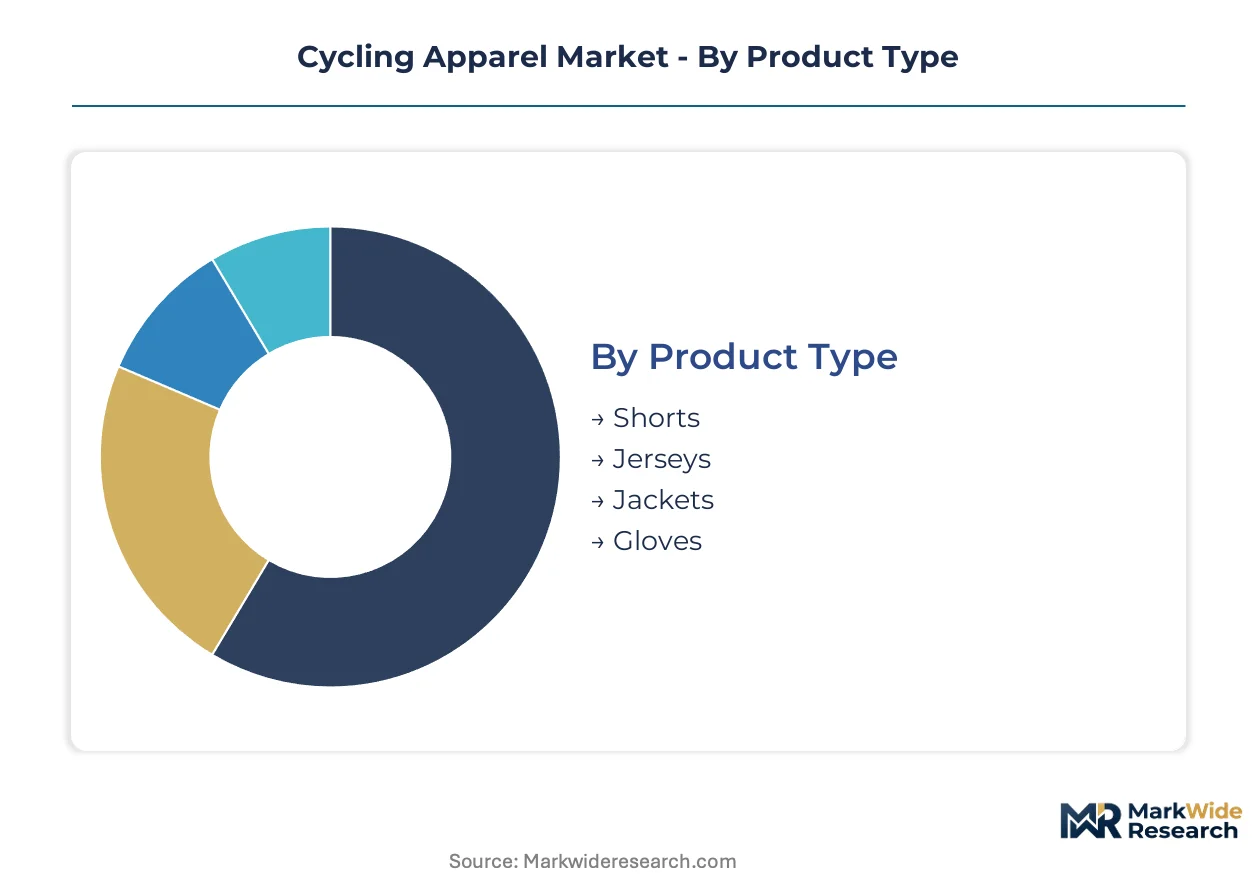
Technical performance requirements and fit precision create divergent investment profiles across cycling apparel segments. Material science capabilities and distribution infrastructure requirements further stratify capital deployment priorities for manufacturers and retailers.
Product Type:
Capital intensity peaks in categories requiring multi-panel pattern engineering and compressive structure development.
- Shorts:Bib construction demands proprietary chamois molding and leg gripper integration. Demand concentrates in Italian gran fondo events where amateur racers seek pro-grade specifications. Dual-density foam formulations and thermoformed padding represent the primary technical moat.
- Jerseys:Aerodynamic paneling and sublimation-print compatibility drive polyester specification. Three-pocket rear construction with radio/energy gel access dominates European pro-team sponsorship requirements. Sleeve length variations and collar geometries differentiate racing from training applications.
- Jackets:Waterproof-breathable membranes and PFAS-free DWR coatings require reformulation investment under REACH timelines.
- Gloves:Gel padding placement and touchscreen-compatible fingertips address commuter utility alongside racing protection.
Most installed capacity flows through Jerseys. Expansion is steepest in Shorts.
End User:
Volume distribution inverts against price realization, with premium concentration in technically demanding user categories.
- Professional Cyclists:UCI WorldTour team sponsorships mandate aerodynamic optimization and thermoregulation precision. Custom fit protocols and race-day garment allocation systems require dedicated account management infrastructure. Sponsorship contracts in Belgium and Italy anchor brand credibility for adjacent amateur segments.
- Casual Riders:Urban commuting normalization in Copenhagen and Amsterdam creates demand for workplace-appropriate transitional designs. Odor-resistant merino blends and reflective visibility elements outweigh pure aerodynamic gains. Volume concentration here supports manufacturing scale economics.
- Recreational Users:Weekend club riders balance technical credibility with value accessibility.
- Mountain Bikers:Abrasion-resistant fabrics and loose-fit silhouettes diverge from road-racing specifications.
Professional Cyclists command the highest price realization per unit. Casual Riders are expanding most quickly.
Material:
Raw material sourcing geography and processing complexity determine working capital intensity and margin stability.
- Polyester:Petrochemical feedstock dependency ties margin planning to crude oil volatility. Sublimation dye compatibility and durability under UV exposure sustain dominance in racing applications. Chinese manufacturers in Zhejiang province control substantial filament spinning capacity.
- Merino Wool:Temperature modulation and odor resistance capture touring and commuter demand. Australian and New Zealand sourcing contracts require longer lead times than synthetic alternatives. Blending ratios with synthetic fibers optimize durability against pure wool performance.
- Nylon:Abrasion resistance prioritizes mountain bike and outerwear applications.
- Spandex:Compressive structure requirements in bib shorts and base layers specify elastane content typically at 15-25% blend ratios.
Polyester retains the greatest installed spinning capacity. Merino Wool is gaining share fastest.
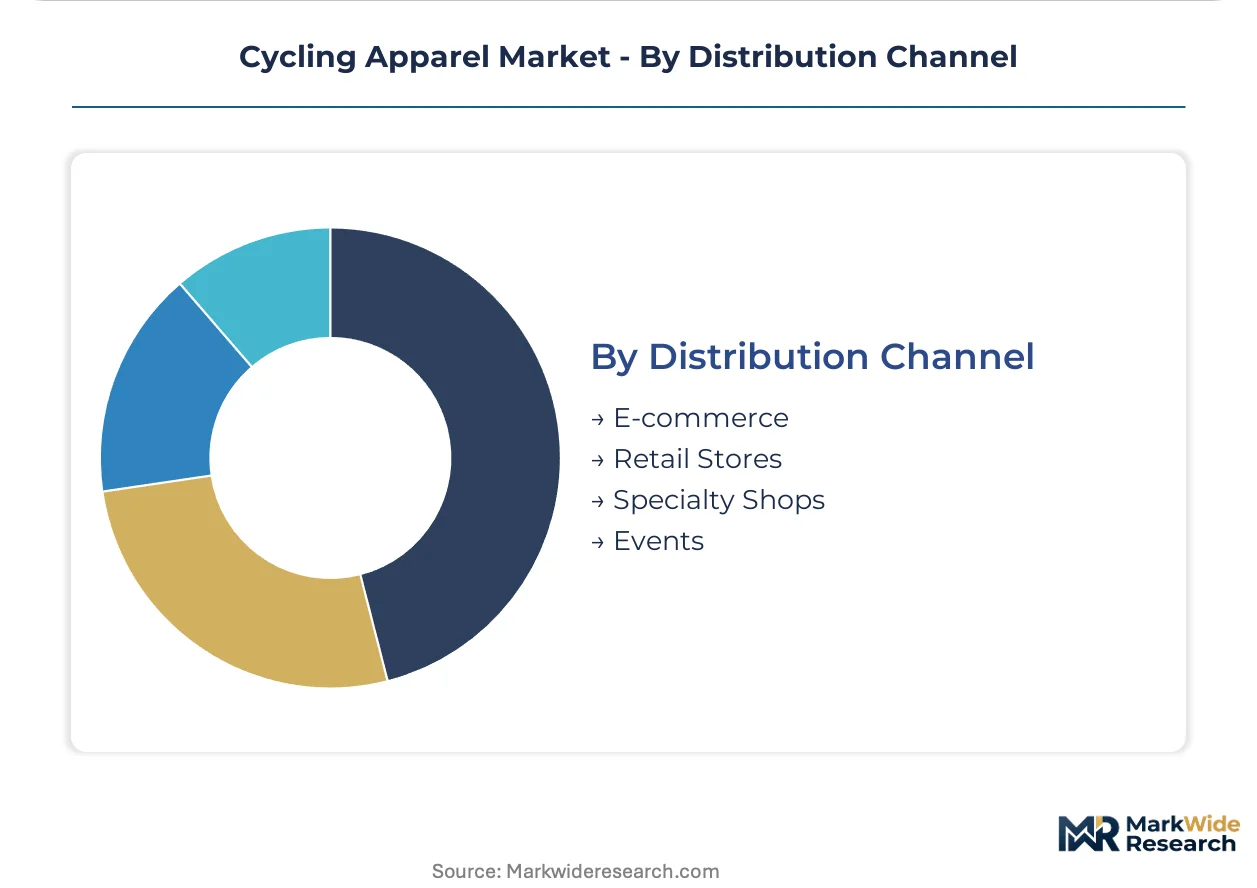
Distribution Channel:
Channel economics diverge sharply on return rates, customer acquisition costs, and inventory carrying requirements.
- E-commerce:Direct-to-consumer platforms reduce wholesale margin sacrifice but elevate fit-related return rates. AI-powered size recommendation tools and 3D body scanning are compressing return incidence in bib short categories. Pearl Izumi and Rapha have invested heavily in proprietary digital infrastructure.
- Specialty Shops:Professional bike fitters and garment technicians provide conversion advantages for fit-critical categories. In-store chamois testing and aerodynamic position consultation justify premium pricing. Lombardy and Veneto maintain dense specialty retail networks.
- Retail Stores:Mass sporting goods chains prioritize inventory turns over technical depth.
- Events:Gran fondo expos and race-day vending capture impulse replenishment purchases.
Specialty Shops retain the highest conversion rates for premium units. E-commerce shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as ECHA's REACH deadlines compress margins for European finishers while Chinese manufacturers absorb compliance costs through scale. Brands now route premium orders to Italian technical clusters and volume production to Zhejiang contract networks.
Italy
Gran fondo culture in Lombardy and Veneto sustains demand for pro-grade bib shorts and aerodynamic jerseys. The EU Green Deal's textile sustainability requirements are accelerating adoption of bluesign-certified dye houses around Milan. Castelli and Santini anchor dense supplier networks in the Lake Como region, where pattern engineering talent concentrates among multi-generational ateliers.
China
Domestic cycling community expansion in Shanghai and Chengdu is absorbing capacity previously dedicated to export markets. MIIT's dual carbon goals are pressuring Zhejiang filament spinners to decarbonize energy-intensive polyester production. Contract manufacturers in Guangdong province are vertically integrating into seamless knitting systems to capture base layer margins from European brands.
United States
Subscription-based kit replacement programs in Colorado and California are normalizing continuous garment refresh among dedicated amateurs. California's Proposition 65 creates disclosure obligations for brands distributing fluorinated water repellents. Pearl Izumi leverages North American distribution infrastructure to serve specialty retailers in the Pacific Northwest and direct-to-consumer channels nationwide.
Germany
Urban commuting normalization in Berlin and Hamburg creates demand for workplace-appropriate transitional apparel. Germany's Textile Strategy EPR framework will impose end-of-life collection obligations on brands serving the market. Assos maintains technical development operations in the Lake Constance region, where proximity to Swiss textile engineering supports membrane innovation.
France
Parisian cycling infrastructure expansion is bridging performance and fashion apparel categories for commuter segments. France's AGEC law mandates repairability labeling and extended producer responsibility for textile waste. Rapha's membership-driven community programming concentrates marketing investment in London and Paris, sustaining pricing power through experiential retail.
Cycling Apparel Market Key Industry Players
Italian producers anchor the premium tier through pro-team sponsorships and dense technical supplier networks; Chinese contract manufacturers hold volume capacity through integrated filament-to-garment operations. The vendor base stratifies across three archetypes: heritage European houses with sponsorship assets, North American direct-to-consumer platforms with digital infrastructure, and Asian contract manufacturers scaling certified sustainable production. Consolidation pressures concentrate among mid-tier European brands lacking proprietary chamois technology or membership programming. Strategic moves center on seamless knitting retooling and PFAS-free coating reformulation ahead of enforcement deadlines.
Within the heritage European tier, Castelli and Assos exemplify pro-team sponsorship strategies that reinforce credibility among serious amateurs. Santini occupies a position bridging Italian manufacturing heritage with gran fondo event partnerships. Pearl Izumi and Rapha represent North American and British direct-to-consumer archetypes respectively, each leveraging proprietary digital infrastructure to reduce fit-related return rates. These five names illustrate the geographic and strategic bifurcation defining competitive positioning: European technical credibility against Anglo-American channel innovation.
| Leading Market Players |
|---|
| Pearl Izumi |
| Adidas |
| Rapha |
| Santini |
| Endura |
| Assos |
| Nike |
| Giordana |
| Castelli |
| Others |
Cost & Logistics Intelligence
Family-owned technical ateliers in Lombardy and Veneto anchor premium tier pricing through multi-generational pattern engineering expertise, while private-equity-rolled mid-tier brands sacrifice margin to compete on channel access. This ownership bifurcation concentrates pricing power among heritage manufacturers with proprietary chamois technology and compresses returns for volume-dependent players exposed to polyester feedstock volatility.
Pricing Analysis
Distributor margin layers in European specialty retail absorb 35-45 points before end-consumer price realization. Three-tier pricing structure across premium, standard, and economy levels separates pro-team specification kit from gran fondo amateur lines and commuter basics. Cost compression in mid-tier polyester jerseys is intensifying because Chinese contract manufacturers are absorbing REACH compliance investments to maintain volume share. Casual riders exhibit highest price sensitivity, while UCI WorldTour team sponsorship contracts anchor premium tier pricing discipline.
Supply Chain Analysis
Polyester filament supply rests on Zhejiang province spinners with captive access to petrochemical feedstocks from Sinopec refining complexes. Merino wool sourcing draws from Australian and New Zealand pastoral contracts with 18-24 month procurement horizons. Spandex elastane hinges on Korean and German specialty chemical producers with limited secondary sourcing. Single-source vulnerability concentrates in seamless knitting machinery where Italian and Japanese OEMs control installed base. Distribution runs through specialty bike fitters in Lombardy and Veneto for premium conversion, with direct-to-consumer platforms capturing replenishment volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cycling apparel functions as a stable compounder anchored by gran fondo participation growth and urban commuting infrastructure normalization across European and North American cities.
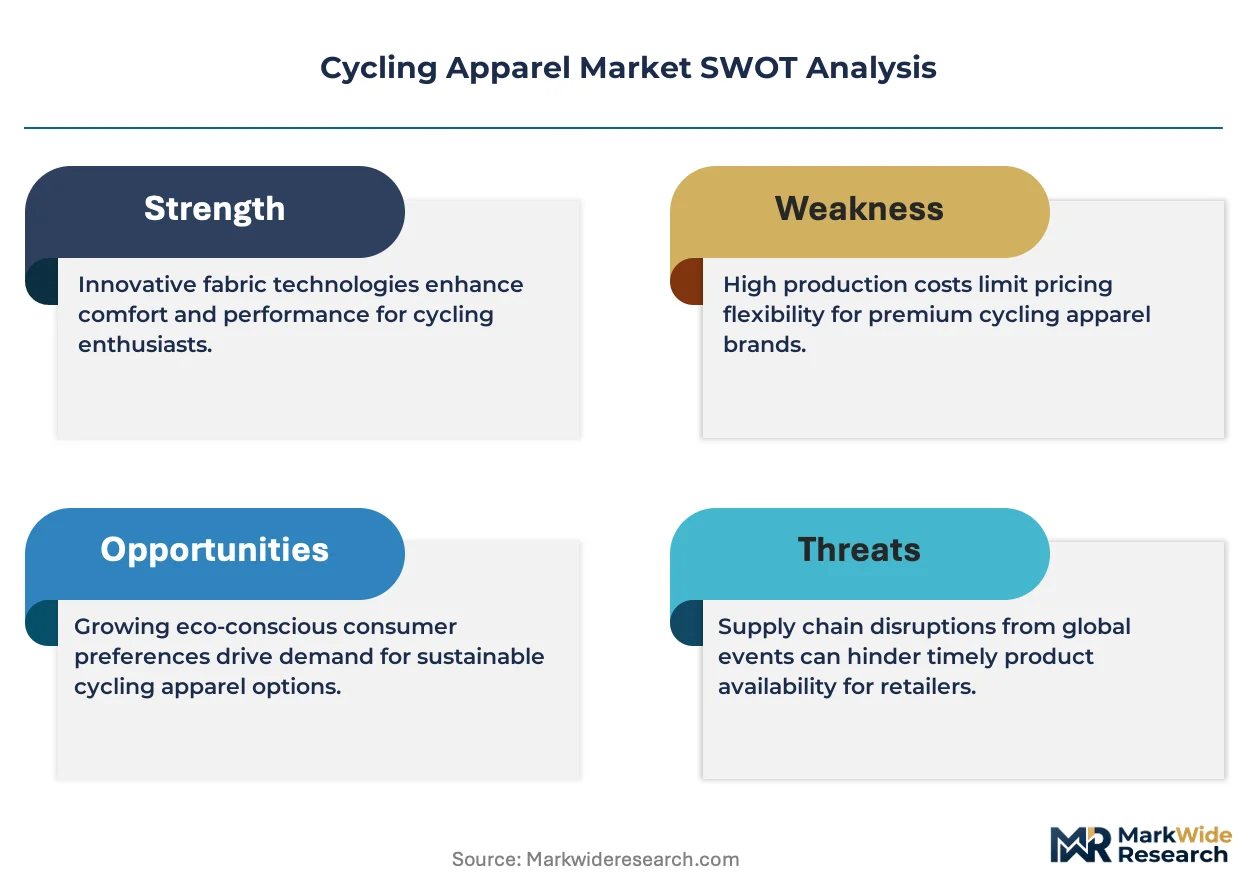
For Market Incumbents: Acquire proprietary chamois molding operations to defend margin position against private-label entrants from Guangdong contract networks. Secure bluesign-certified dye house capacity ahead of ECHA enforcement deadlines. Consolidate pattern engineering talent in Lombardy through apprenticeship pipeline investments to offset aging technician demographics. For New Entrants and Emerging Players: REACH in the European Union opens a window for fluorine-free DWR coating specialists to capture premium outerwear share from legacy brands with reformulation lag. Target commuter segments in Copenhagen and Amsterdam where workplace-appropriate transitional designs remain underdeveloped. Deploy AI-powered fit recommendation tools to reduce return rates in direct-to-consumer bib short categories. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier European brands lacking membership programming or proprietary digital infrastructure. Five-to-ten year viability favors assets with circular collection infrastructure ahead of France AGEC and Germany Textile Strategy EPR obligations. Monitor ECHA PFAS restriction enforcement timelines as inflection indicator for premium outerwear margin reset.| Strategic Initiative | Industry Significance |
|---|---|
| Seamless Knitting Retooling | Single-piece construction eliminates cut-and-sew labor, compressing base layer unit costs by 30-40% for European pro-team suppliers. |
| PFAS-Free Coating Reformulation | Schoeller and Bionic Finish Eco alternatives secure shelf space ahead of ECHA textile restrictions in premium outerwear. |
| Membership Programming Launch | Rapha's community-driven model sustains pricing power independent of seasonal product cycles in British and North American markets. |
| Circular Infrastructure Investment | France AGEC and Germany Textile Strategy EPR frameworks reward brands with established end-of-life collection systems. |
| Digital Fit Technology Deployment | Pearl Izumi's AI-powered size recommendation reduces return rates for direct-to-consumer bib short purchases. |
Research Approach
Multiple input streams — primary interviews with brand product directors, specialty retail buyers, and contract manufacturing executives; secondary validation through customs trade records, EU ECHA regulatory filings, and SEC apparel company disclosures; plus gran fondo event participation databases — were reconciled through bottom-up and top-down triangulation. Primary fieldwork captured pattern engineering capacity constraints in Lombardy-Veneto technical clusters and Zhejiang-Guangdong manufacturing scale economics.
Data-stream reconciliation across product type, material specification, end-user segment, and distribution channel dimensions informed value and volume modeling across the projection horizon. CAGRs were derived from segment-level growth rate synthesis calibrated to EPR regulatory phase-in timelines and urban cycling infrastructure investment pipelines. Forecast inputs incorporated polyester feedstock price elasticity, REACH compliance cost absorption rates, and digital channel penetration curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden petrochemical price spikes or accelerated ECHA restriction enforcement. Material deviation in PFAS regulatory timelines, Chinese dual carbon policy stringency, or gran fondo participation growth rates warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sportswear
North America Dancewear Market
Sportswear
Europe Dancewear Market
Sportswear
Billiards and Snooker Equipment Market
Sportswear
Cricket Bowling Machine Market
Sportswear
Athleisure Wear Market
Sportswear
Cycling Wear Market
Sportswear
Workout Clothes Market
Sportswear
Global Women Active Wear Market
Sportswear
Casual Sportswear Market
Sportswear
Athleisure Market
Sportswear
Skateboard Grip Tapes Market
Sportswear
Bicycle Apparels Market
Sportswear
Sports Socks for Children Market
Sportswear
Activewear Market