
 Athleisure Market | 2026-2036
Athleisure Market Size, Share, and Industry Trends Forecast 2026-2036
Athleisure Market Intelligence
The EU Green Deal is repositioning material sourcing across the athleisure supply chain by mandating recycled content thresholds and carbon disclosure for textile imports. Nike leverages its proprietary Flyknit manufacturing to reduce waste in upper production, while Lululemon Athletica anchors its premium positioning through vertical control over fabric innovation and community-driven retail formats. Adidas competes via its partnership network with ocean plastic recyclers, converting marine waste into performance yarns at commercial scale.
Athleisure denotes apparel engineered with stretch recovery, moisture-wicking fiber architectures, and seamless construction techniques to bridge gym functionality with streetwear aesthetics. Primary commercial purpose centers on serving consumers who transition between exercise, work, and social contexts without changing garments. Leggings dominate women's product type revenue due to elastic waistband engineering and compression grading that supports extended wear duration. Polyester leads material volume through its dimensional stability and dye sublimation compatibility, though spandex blends command margin premiums in performance-tier pricing. Online distribution channels are displacing retail stores in customer acquisition efficiency, particularly for direct-to-consumer specialists with size-optimization algorithms.
The EU's ECHA enforces REACH compliance on textile chemical inputs, restricting azo dyes and perfluorinated treatments that historically delivered water repellency. The US EPA coordinates with OSHA to regulate finishing facility emissions, elevating compliance costs for domestic cut-and-sew operations. China's SAMR monitors GB standard adherence for domestic label claims on fiber content and functional performance. Stakeholders must track how diverging chemical restriction timelines across Brussels, Washington, and Beijing fragment product platform strategies and force regional SKU proliferation.
Market Dynamics
Workplace dress code relaxation across North America and Europe is pulling corporate professionals into structured joggers and performance leggings, while the EU Green Deal's recycled polyester mandates force rapid reformulation of fabric blends across the supply chain.
Growth Catalysts
- REACH chemical compliance:ECHA enforcement on textile inputs is accelerating phase-out of azo dyes and perfluorinated treatments, creating first-mover advantage for brands with certified clean supply chains.
- Urban default wear adoption:Consumers in Shanghai and Beijing treat athleisure as daily standard apparel, expanding addressable market beyond fitness into professional and social contexts.
- Seamless knitting technology:Advanced circular knitting systems reduce cut-and-sew labor while enabling compression grading that supports extended wear duration for women's leggings.
Market Restraints
- Spandex blend cost volatility:Margin premiums on performance-tier pricing compress when elastane feedstock prices spike, forcing trade-offs between stretch recovery and material cost.
- China concentration risk:GB standard enforcement by SAMR and domestic label claim monitoring create compliance friction for foreign brands dependent on Chinese manufacturing.
- Technical limitation in dye sublimation:Polyester's dimensional stability enables vibrant printing but traps heat during high-intensity activity, limiting performance-tier positioning.
Strategic Opportunities
- EU Green Deal tailwind:Recycled content thresholds and carbon disclosure mandates for textile imports reward brands with ocean plastic partnerships and closed-loop material flows.
- Direct-to-consumer channel innovation:Size-optimization algorithms and virtual fitting tools displace retail store dependency for customer acquisition in premium women's leggings.
- Moisture-wicking fiber convergence:Integration of bio-based cellulosic fibers with synthetic architectures opens positioning in sustainability-conscious professional segments.
Industry Challenges
- REACH certification timeline compression:Diverging chemical restriction schedules across Brussels, Washington, and Beijing force regional SKU proliferation and fragment product platform strategies.
- Legacy cut-and-sew capex stranded:Domestic finishing facilities face elevated EPA and OSHA compliance costs while seamless knitting automation renders traditional equipment obsolete.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Athleisure Market |
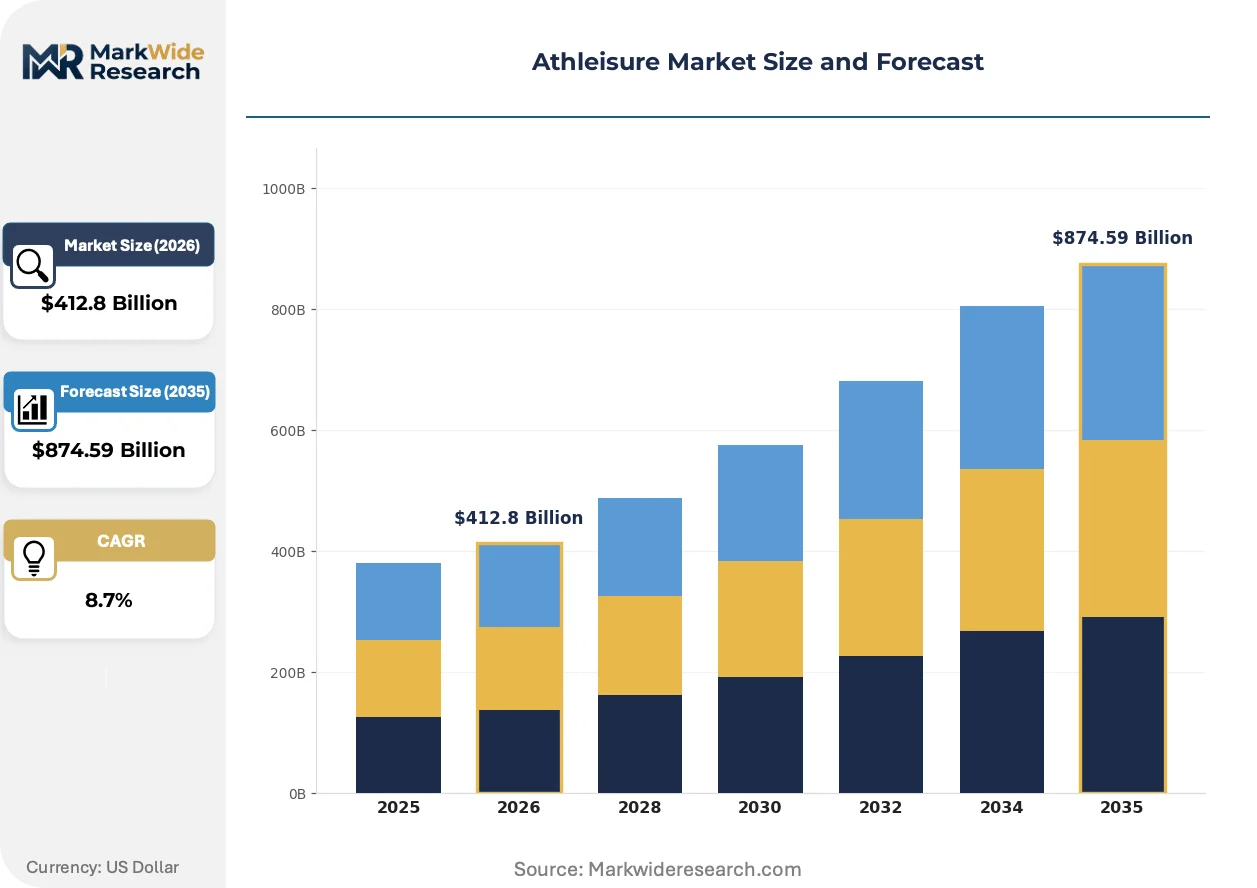
| Market Size in 2026 | $412.8 Billion |
| Market Size in 2035 | $874.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Leggings, Sports Bras, Hoodies, T-Shirts Material: Polyester, Nylon, Cotton, Spandex End User: Men, Women, Children, Athletes Distribution Channel: Online, Retail Stores, Boutiques, Wholesalers |
| Companies Covered | Nike, Adidas, Lululemon Athletica, Puma, Under Armour, Vuori, On, Hanesbrands, Gymshark, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Athleisure Market Strategic Shifts & Innovations
Material science breakthroughs and regulatory chemistry restrictions are simultaneously reshaping how performance apparel is engineered, sourced, and sold across channels.
Seamless construction is consolidating manufacturing footprints by eliminating cut-and-sew stages through 3D knitting of complete garments. Performance brands adopt this at scale for compression leggings and base layers. The technology is consolidating supplier bases around capital-intensive circular knitting equipment while compressing lead times from design to shelf.
REACH restrictions on perfluorinated compounds are eliminating water-repellency treatments that historically differentiated outdoor-oriented athleisure. ECHA enforcement forces reformulation toward silicone-based or bio-derived alternatives. European imports face the strictest compliance windows, accelerating R&D investment in fluorine-free finishing chemistry.
Size-optimization algorithms are displacing traditional retail fitting rooms as primary purchase confidence drivers. Direct-to-consumer specialists deploy body-scan data and machine learning to reduce return rates in women's leggings. This shift concentrates customer acquisition spend in digital channels across North American and European urban markets.
Athleisure Market Segmentation
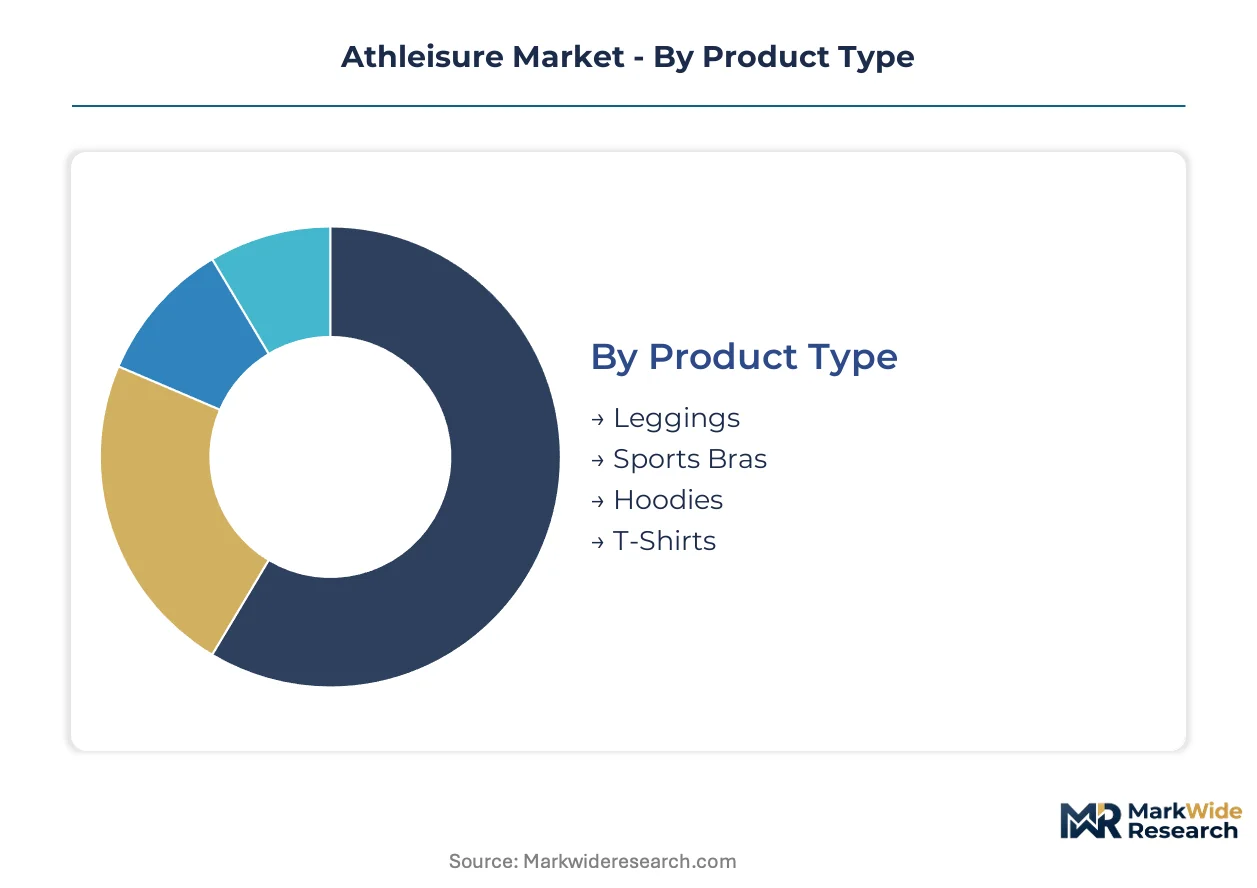
Athleisure segmentation reveals how fabric engineering, channel economics, and user occasion overlap to determine margin capture. Manufacturers configure SKU portfolios around stretch recovery specifications and distribution cost structures rather than traditional demographic brackets.
Product Type:
Standardization dominates basic tops while compression engineering creates customization premiums in lower-body categories.
- Leggings:Elastic waistband architecture with compression grading supports extended wear duration across professional and social contexts. Demand concentrates in women's segments across Shanghai and Beijing where urban consumers treat athleisure as default daily apparel, driven by seamless knitting technology reducing cut-and-sew labor.
- Sports Bras:Moisture-wicking fiber architectures with seamless construction enable high-impact support without hardware migration. Concentration is strongest among studio fitness practitioners in North American metropolitan markets, constrained by size-optimization algorithm adoption in direct-to-consumer channels.
- Hoodies:Cotton-polyester blends with brushed fleece interiors balance thermal retention against streetwear aesthetics.
- T-Shirts:Basic stretch-knit constructions compete primarily on dye sublimation compatibility and unit economics.
Most installed capacity flows through Leggings. Expansion is steepest in Sports Bras.
Material:
Cost tier stratification separates commodity synthetics from performance blends commanding margin premiums.
- Polyester:Dimensional stability and dye sublimation compatibility drive volume leadership in graphic-intensive applications. Demand clusters in mass-market online channels where price elasticity is highest, constrained by heat-trapping limitations during high-intensity activity.
- Spandex:Elastane feedstock integration delivers stretch recovery essential for compression grading in performance-tier pricing. Concentration is strongest in premium women's leggings across European markets, pressured by elastane cost volatility forcing trade-offs against material expense.
- Nylon:Abrasion resistance and smooth hand-feel support outerwear and performance sock applications.
- Cotton:Natural fiber positioning appeals to sustainability-conscious segments despite moisture-management limitations.
Polyester carries the heaviest throughput volume. Spandex is gaining share fastest in premium positioning.
End User:
Application occasion—not demographics—determines technical specification requirements across user segments.
- Women:Multi-context transition requirements between exercise, work, and social settings drive the broadest SKU complexity. Demand concentrates in professional segments across North America and Europe where workplace dress codes relax into structured joggers and performance leggings.
- Athletes:Performance-tier certification requirements for moisture-wicking and compression metrics command the highest unit margins. Concentration is strongest in competitive training contexts, constrained by technical limitations in dye sublimation heat management during peak output.
- Men:Simpler occasion boundaries reduce SKU variety but expand average transaction values through outerweight purchases.
- Children:Growth-contingent sizing and rapid replacement cycles prioritize cost efficiency over technical performance.
Women's segments anchor current revenue concentration. Athletes show the steepest margin expansion trajectory.
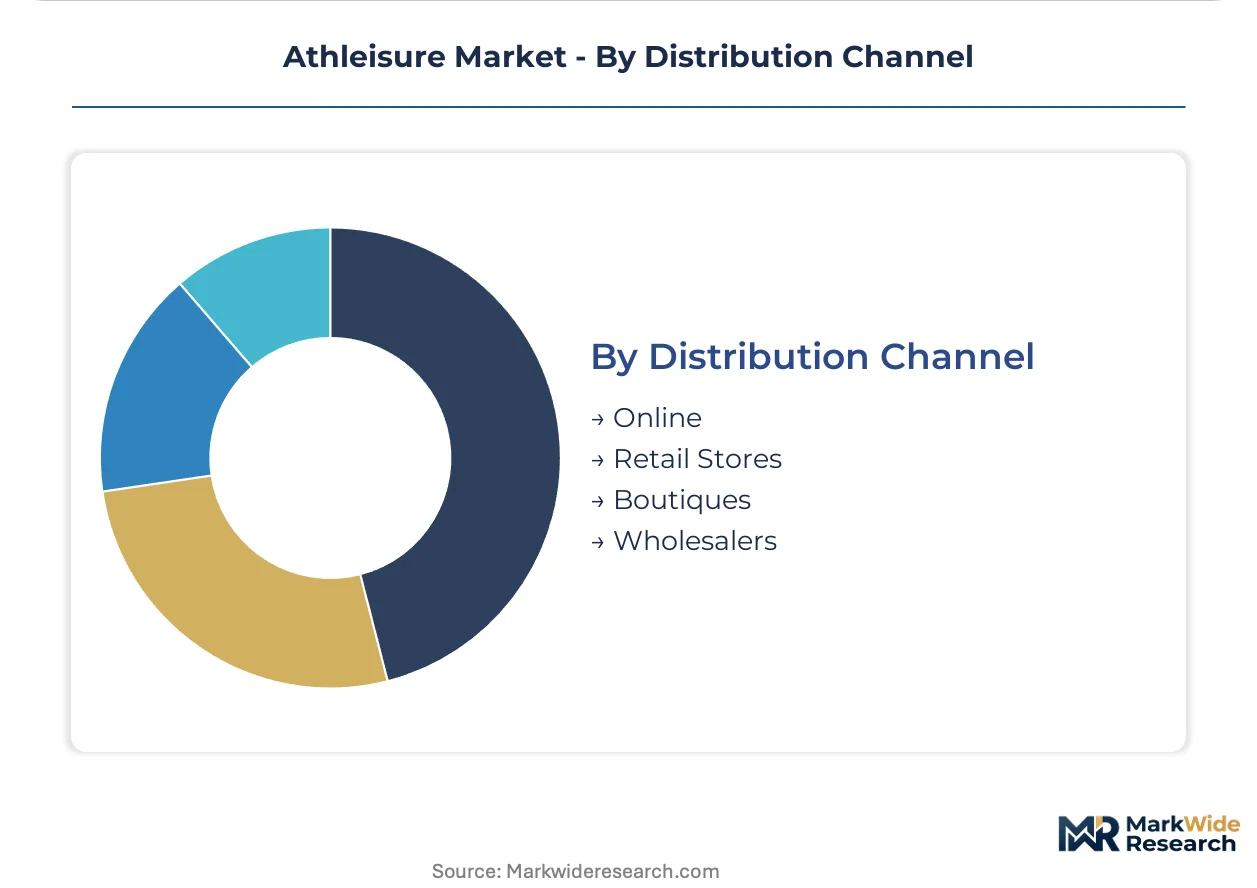
Distribution Channel:
Customer acquisition efficiency separates digital-native specialists from legacy retail infrastructure.
- Online:Size-optimization algorithms and virtual fitting tools displace physical fitting rooms as primary purchase confidence drivers. Demand concentrates in direct-to-consumer specialists across North American and European urban markets, enabled by machine learning reducing return rates in women's leggings.
- Retail Stores:Community-driven formats with in-house fabric innovation demonstrations anchor premium brand positioning. Concentration persists in Lululemon-style experiential formats, pressured by customer acquisition cost advantages in digital channels.
- Boutiques:Curated assortments serve localized taste clusters with higher service premiums.
- Wholesalers:Volume aggregation for mass-market retail partnerships prioritizes unit economics over brand control.
Online channels capture the majority of new customer acquisition investment. Retail Stores retain the highest loyalty-repeat metrics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Workforce concentrations in technical textile engineering and apparel design talent anchor geographic demand formation. Urban professionals in Shanghai and Beijing treat athleisure as default daily wear. EU regulatory enforcement is accelerating material reformulation timelines.
United States
Corporate professionals in New York and Los Angeles drive structured joggers and performance leggings adoption as workplace dress codes relax. EPA coordination with OSHA elevates compliance costs for domestic cut-and-sew finishing facilities. The Pacific Northwest cluster around Portland anchors sustainable material innovation partnerships.
Germany
Technical textile engineers in Bavaria and North Rhine-Westphalia concentrate performance fabric R&D capacity. ECHA REACH enforcement restricts azo dyes and perfluorinated treatments, forcing reformulation toward fluorine-free finishing chemistry. The Stuttgart industrial corridor hosts seamless knitting equipment suppliers serving premium compression wear producers.
China
Urban consumers in Shanghai and Beijing treat athleisure as standard daily apparel across professional and social contexts. SAMR monitors GB standard adherence for domestic label claims on fiber content and functional performance. The Yangtze River Delta manufacturing belt concentrates polyester weaving and dye sublimation capacity.
United Kingdom
Studio fitness practitioners in London drive sports bra and high-impact support garment demand. EU Green Deal recycled content thresholds apply to textile imports via post-Brexit trade alignment. The Manchester textile heritage cluster is repurposing toward technical knitwear and circular material flows.
Japan
METI industrial policy supports moisture-wicking fiber convergence with bio-based cellulosic integration. JIS standards govern functional performance claims on stretch recovery and compression metrics. The Nagoya industrial corridor concentrates circular knitting machinery production for seamless garment manufacturing.
Athleisure Market Key Industry Players
Capital-heavy producers compete with asset-light designers across material innovation and channel control. The vendor base stratifies into three tiers: integrated specialists with captive fabric mills, direct-to-consumer digital natives with algorithmic fitting tools, and wholesale-dependent mass-market aggregators. Dominant competitive moves include strategic partnerships with ocean plastic recyclers and vertical integration into seamless knitting automation.
Within the integrated specialist tier, Nike and Lululemon Athletica exemplify divergent paths to margin capture. Nike leverages proprietary manufacturing processes to reduce waste in upper production. Lululemon Athletica anchors premium positioning through vertical control over fabric innovation and community-driven retail formats. Adidas occupies a position between these archetypes, competing via partnership networks with marine waste recyclers to convert ocean plastic into performance yarns at commercial scale.
| Leading Market Players |
|---|
| Nike |
| Adidas |
| Lululemon Athletica |
| Puma |
| Under Armour |
| Vuori |
| On |
| Hanesbrands |
| Gymshark |
| Others |
Cost & Logistics Intelligence
Elastane feedstock costs cascade from petrochemical complexes through performance-tier leggings pricing, compressing margins when spandex blend premiums cannot absorb raw material spikes. Polyester volume leadership in mass-market channels anchors economy pricing, while seamless knitting automation shifts labor cost structures away from traditional cut-and-sew geographies.
Pricing Analysis
Unbundled fabric innovation commands standalone premiums, whereas bundled community-retail experiences sustain Lululemon-style loyalty pricing. Three-tier pricing structure across premium, standard, and economy levels separates compression-graded performance wear from basic stretch-knit commodities. Pricing pressure stems from spandex cost volatility forcing trade-offs between stretch recovery and material expense. Mass-market online channels exhibit highest price sensitivity; premium women's leggings in European markets show lowest elasticity due to fit-technology differentiation.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Los Angeles orchestrate hub-and-spoke patterns for finished goods, while raw material flows concentrate in China's Yangtze River Delta polyester weaving belt and Germany's Stuttgart seamless knitting equipment corridor. Spandex feedstock draws from South Korean and Japanese petrochemical producers; recycled ocean plastic yarns hinge on Southeast Asian marine waste collection networks. Single-source vulnerability concentrates in circular knitting machinery, where Japanese and German OEMs dominate capital equipment supply. Distribution runs through direct-to-consumer digital channels displacing traditional wholesale apparel brokers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The athleisure market functions as a stable compounder, with workplace dress code relaxation across North America and Europe generating durable demand expansion beyond traditional fitness occasions.
For Market Incumbents: Lock in seamless knitting automation capacity before equipment lead times extend, defending against emerging digital-native entrants with algorithmic fit tools. Prioritize REACH-certified clean supply chains to capture first-mover advantage as ECHA enforcement tightens azo dye and perfluorinated compound restrictions. Backward integration into recycled polyester feedstock secures EU Green Deal compliance margin. For New Entrants and Emerging Players: Corporate professionals in secondary European cities represent an underserved buyer archetype with relaxed dress codes but limited premium retail access. White-space targets include moisture-wicking professional segments seeking bio-based cellulosic fiber alternatives, and size-optimization algorithm deployment for men's structured joggers where virtual fitting lags women's leggings. Go-to-market angle: direct-to-consumer digital acquisition with machine learning return-rate reduction. For Investors and Strategic Acquirers: Consolidation pressure builds where brands lack captive fabric mills and depend on outsourced dye sublimation capacity in China's Yangtze River Delta. Long-term viability favors vertically integrated specialists with community-retail formats and proprietary stretch-recovery R&D. Acquisition target archetype: seamless knitting automation specialists with European regulatory certification. Signal to watch: REACH restriction timeline compression forcing regional SKU proliferation beyond manageable portfolio complexity.| Strategic Initiative | Industry Significance |
|---|---|
| Seamless Knitting Automation | Eliminates cut-and-sew labor while enabling compression grading for extended wear duration in women's leggings. |
| Recycled Polyester Partnership | Converts ocean plastic into performance yarns at commercial scale, satisfying EU Green Deal content thresholds. |
| Direct-to-Consumer Algorithm Launch | Deploys body-scan data and machine learning to reduce return rates in premium women's leggings categories. |
| REACH Certification Investment | Accelerates phase-out of azo dyes and perfluorinated treatments ahead of ECHA enforcement windows. |
| Community-Retail Format Expansion | Anchors premium positioning through in-house fabric innovation demonstrations and experiential loyalty building. |
Research Approach
Direct dialogue with brand sourcing directors, textile mill operations managers, retail category buyers, and seamless knitting equipment engineers grounded qualitative findings, cross-referenced with customs trade data, EU ECHA regulatory filings, SEC apparel company disclosures, and Yangtze River Delta production statistics. Secondary validation drew from GB standard documentation via China's SAMR and polyester feedstock price benchmarks. Bottom-up and top-down triangulation reconciled channel shipment data with end-user demand segmentation.
Bottom-up modeling aggregated product-type volumes across leggings, sports bras, and hoodies, while top-down analysis calibrated total addressable market expansion against urban professional workforce growth in Shanghai, Beijing, New York, and Los Angeles. Segmentation dimensions included material tier, distribution channel economics, and end-user occasion requirements across fitness, professional, and social contexts. CAGRs derived from elasticity-adjusted price trajectories and substitution patterns between synthetic and bio-based fiber architectures.
Underlying measurement precision varies by segment; online channel data carries tighter precision than boutique wholesale estimates due to direct transaction visibility. Forecasts reflect documented assumptions on dress code relaxation velocity and recycled content mandate implementation timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sportswear
Cycling Apparel Market
Sportswear
Athleisure Wear Market
Sportswear
Skateboard Grip Tapes Market
Sportswear
Billiards and Snooker Equipment Market
Sportswear
North America Dancewear Market
Sportswear
Casual Sportswear Market
Sportswear
Bicycle Apparels Market
Sportswear
Workout Clothes Market
Sportswear
Sports Socks for Children Market
Sportswear
Cricket Bowling Machine Market
Sportswear
Global Women Active Wear Market
Sportswear
Cycling Wear Market
Sportswear
Europe Dancewear Market
Sportswear
Activewear Market