
 Billiards and Snooker Equipment Market | 2026-2036
Billiards and Snooker Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Billiards and Snooker Equipment Market Analysis
Multi-source component procurement is consolidating toward vertically integrated in-house manufacturing among premium table builders. Brunswick Corporation leverages captive slate quarries and domestic wood curing facilities to control material quality from raw input through finished assembly. Diamond Billiard Products sustains its tournament-specification reputation through precision-machined rail systems engineered in the United States. Predator Group differentiates via carbon-fiber shaft technology that displaces traditional maple in competitive cue segments.
Billiards and snooker equipment encompasses precision-engineered tables with slate bed substrates, tapered hardwood or composite cues, phenolic resin balls, and ancillary rack systems designed to exacting dimensional tolerances for consistent ball roll and rebound behavior. The primary commercial purpose centers on enabling standardized competitive play across professional circuits, commercial entertainment venues, and residential recreation spaces. Tables command the dominant margin pool due to slate sourcing complexity and freight-intensive assembly logistics, while cues represent the fastest-growing value segment as carbon-fiber composite shafts penetrate professional and enthusiast tiers. The material dimension shows fiber-based alternatives displacing conventional wood in high-wear components, with leather tip demand holding steady among purist professional players.
The EPA regulates volatile organic compound emissions from wood finishes and adhesives used in domestic table manufacturing, while the EU F-Gas Regulation constrains climate-controlled venue infrastructure that protects equipment in humid climates. REACH compliance adds testing burden for phenolic resin formulations in ball production exported to European markets. Stakeholders must monitor evolving chemical disclosure requirements across multiple jurisdictions while calibrating material substitution timelines against performance certification standards.
Market Dynamics
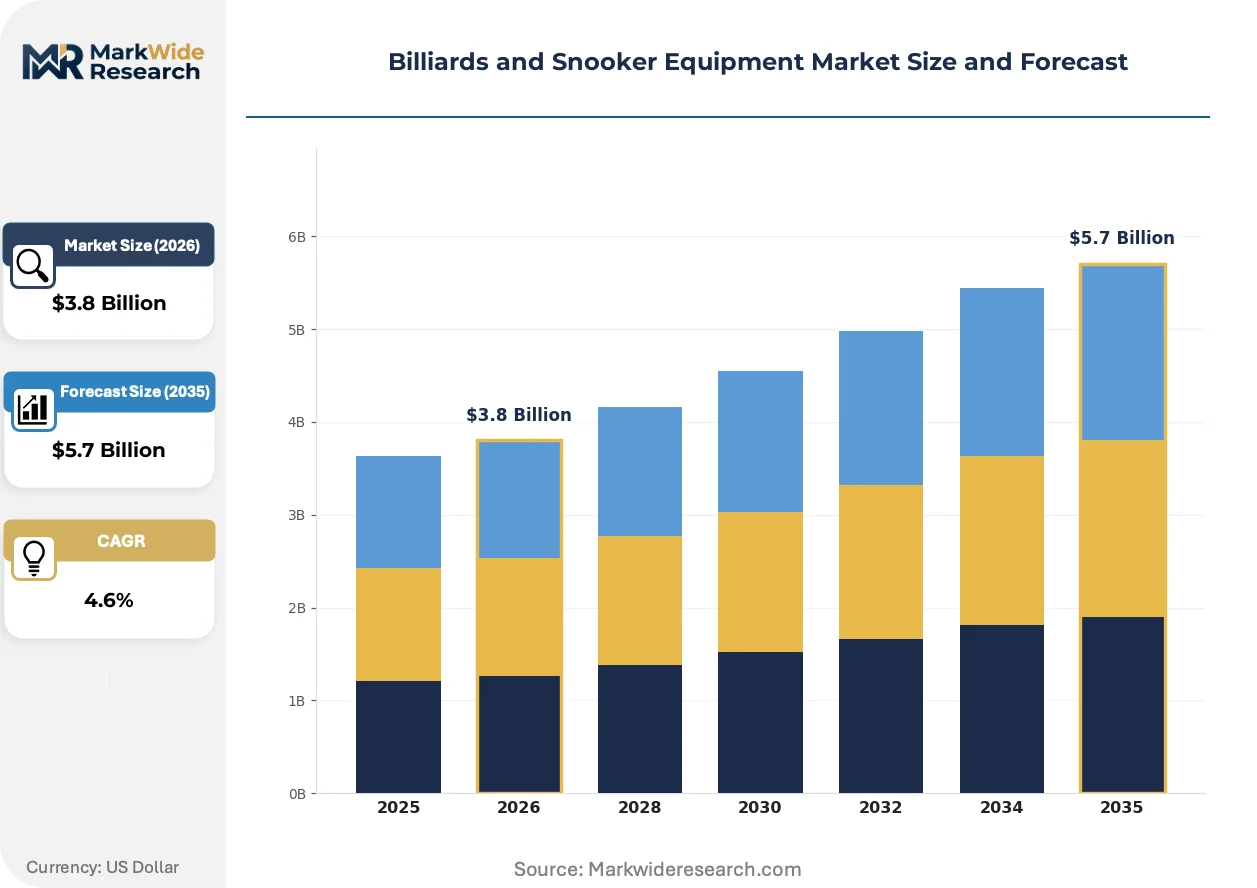
Carbon-fiber shaft technology is compressing traditional maple supply chains while EU chemical restrictions force material reformulation across premium table manufacturing. Tournament-grade procurement consolidation among professional circuits is simultaneously reshaping vendor qualification criteria and long-term contract structures.
Growth Catalysts
- REACH compliance mandates:European phenolic resin testing requirements are accelerating certified ball manufacturer consolidation, favoring producers with in-house laboratory capabilities over fragmented importers.
- China domestic league expansion:Provincial tournament circuits in Guangdong and Jiangsu provinces are driving standardized table procurement at scale, creating anchor demand for slate-curing facilities.
- Carbon-fiber composite shafts:Professional player adoption of tapered carbon structures is expanding the addressable premium cue segment beyond traditional hardwood limitations.
Market Restraints
- Slate quarry concentration:Premium table substrate sourcing depends on captive Italian and Brazilian slate extraction, exposing manufacturers to freight cost volatility and geopolitical supply interruption.
- EU F-Gas Regulation constraints:Climate-controlled venue infrastructure requirements limit equipment protection capabilities in humid subtropical markets, compressing addressable commercial installation geography.
- Wood adhesive VOC thresholds:EPA emission limits on formaldehyde-based bonding agents force curing process modifications that extend production cycles and elevate compliance overhead.
Strategic Opportunities
- India commercial entertainment venues:Underpenetrated metro markets in Mumbai and Bangalore present first-mover positioning for standardized table leasing models targeting hospitality chains.
- Digital streaming integration:Embedded sensor rail systems enabling real-time ball tracking and broadcast analytics represent unclaimed value capture in tournament infrastructure.
- EU Green Deal chemical transition timelines:Early water-based finish adoption creates certification differentiation for export-oriented manufacturers ahead of mandatory compliance deadlines.
Industry Challenges
- Slate grading expertise scarcity:Qualified geological assessment talent for bed flatness certification is concentrating among aging Italian craftspeople, constraining quality-controlled capacity expansion.
- Cross-jurisdiction chemical disclosure alignment:Reconciling EPA, REACH, and China GB standard testing protocols extends product launch timelines and elevates documentation overhead for multi-market portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Billiards and Snooker Equipment Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tables, Cues, Balls, Racks End User: Home Users, Clubs, Professional Players, Tournaments Material: Wood, Plastic, Fiber, Leather Distribution Channel: Online Retail, Specialty Stores, Wholesale, Importers |
| Companies Covered | Brunswick Corporation, Diamond Billiard Products, Olhausen Billiard Manufacturing, Predator Group, Valley-Dynamo, McDermott Cue Manufacturing, Berner Billiards, BCE Distributors, Aramith, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Billiards and Snooker Equipment Market Emerging Trajectories
Equipment specification is diverging between broadcast-optimized tournament infrastructure and compact residential formats, with material science and sensor integration driving parallel development tracks.
Carbon-fiber cue shaft manufacturing is modularizing around standardized taper geometries and interchangeable joint systems. Professional circuit players and serious amateurs are migrating toward multi-piece travel configurations that maintain competitive performance specifications. This standardization is modularizing aftermarket component ecosystems and compressing regional repair service dependencies.
REACH substance restriction expansions are forcing phenolic resin reformulation across ball production exported to European markets. Manufacturers with captive polymer chemistry capabilities are internalizing compliance testing to avoid third-party certification delays. Tournament-grade ball suppliers serving EU professional circuits face the steepest reformulation timelines and raw material substitution costs.
Commercial venue procurement is consolidating around bundled equipment-service contracts that unbundle traditional capital expenditure models. Hospitality operators in China and Southeast Asia are shifting toward performance-guaranteed leasing arrangements with maintenance-inclusive terms. This financing structure rotation is most visible in Shanghai and Shenzhen entertainment districts where venue turnover rates compress equipment depreciation schedules.
Billiards and Snooker Equipment Market Segmentation
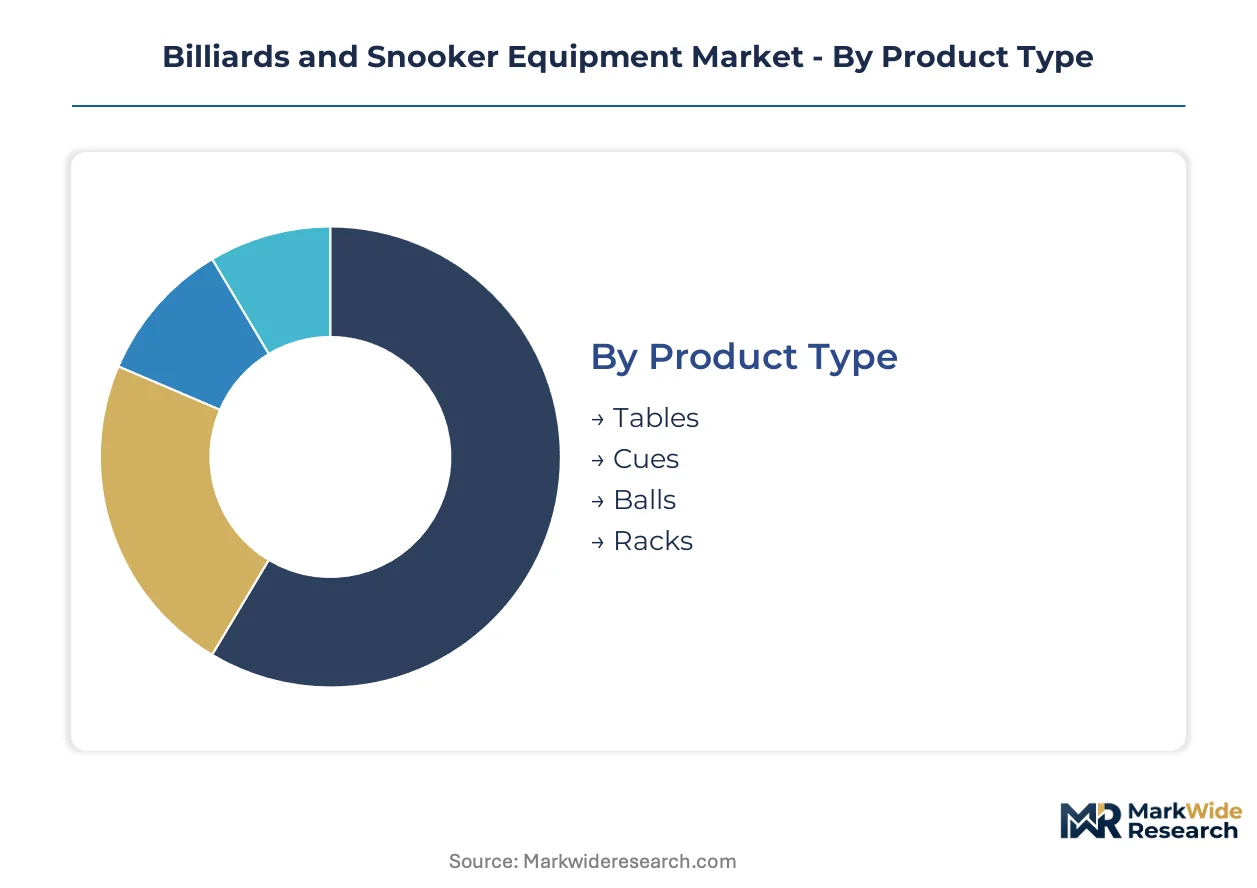
Equipment replacement cycles vary dramatically across user tiers, from residential impulse purchases to decade-long tournament infrastructure commitments. Understanding these divergent upgrade patterns illuminates where procurement budgets concentrate and where margin compression threatens.
Product Type:
Upgrade urgency concentrates in cues and balls, where competitive players chase incremental performance gains, while tables anchor decade-long capital planning with slate longevity driving minimal replacement frequency.
- Tables:Slate-bed substrates with hardwood or composite rail systems command the dominant margin pool due to freight-intensive logistics and geological sourcing complexity. Demand clusters in China's Guangdong and Jiangsu provinces, where provincial tournament circuits are standardizing procurement specifications and anchoring regional slate-curing facility investments.
- Cues:Tapered shafts in maple, carbon-fiber composite, or hybrid constructions represent the segment expanding most quickly as professional adoption of carbon structures displaces traditional hardwood limitations. Predator Group's carbon-fiber technology penetration across competitive tiers compresses regional maple supply chains while opening premium pricing headroom.
- Balls:Phenolic resin formulations engineered to exacting dimensional tolerances for consistent roll and rebound behavior.
- Racks:Precision-molded plastic or wooden triangle and diamond configurations for standardized ball positioning.
Tables sit at the top of the volume ranking, with cues climbing the fastest.
End User:
Cost tier stratification separates capital-intensive tournament infrastructure from discretionary residential purchases, with hospitality venues occupying a volatile middle ground sensitive to venue turnover rates.
- Home Users:Residential recreation purchases span compact formats and entry-to-mid-tier specifications, with replacement driven by lifestyle upgrades rather than competitive necessity.
- Clubs:Commercial entertainment venues in Shanghai and Shenzhen entertainment districts are shifting toward performance-guaranteed leasing arrangements with maintenance-inclusive terms, compressing traditional capital expenditure models.
- Professional Players:Tournament-specification equipment demands drive premium cue and ball procurement, with carbon-fiber shaft adoption concentrated among serious amateurs and circuit competitors seeking travel-configurable performance.
- Tournaments:Broadcast-optimized infrastructure procurement is consolidating among professional circuits, with vendor qualification criteria tightening around embedded sensor rail systems enabling real-time ball tracking.
Tournament procurement commands the highest per-unit spend, with club leasing models gaining share fastest.
Material:
Supply concentration for premium substrates constrains formulation flexibility as EU chemical restrictions force accelerated substitution timelines.
- Wood:Traditional maple and hardwood components face EPA formaldehyde emission limits on bonding agents, extending curing cycles for domestic manufacturers while carbon-fiber alternatives penetrate high-wear applications.
- Plastic:Phenolic resin ball production confronts REACH substance restriction expansions, with manufacturers internalizing polymer chemistry capabilities to avoid third-party certification delays in European export markets.
- Fiber:Carbon-fiber composite shafts are modularizing around standardized taper geometries and interchangeable joint systems, compressing aftermarket repair dependencies.
- Leather:Traditional tip materials hold steady among purist professional players despite synthetic alternatives, with demand concentrated in heritage-oriented competitive circuits.
Wood retains volume leadership, with fiber composites showing the steepest expansion trajectory.
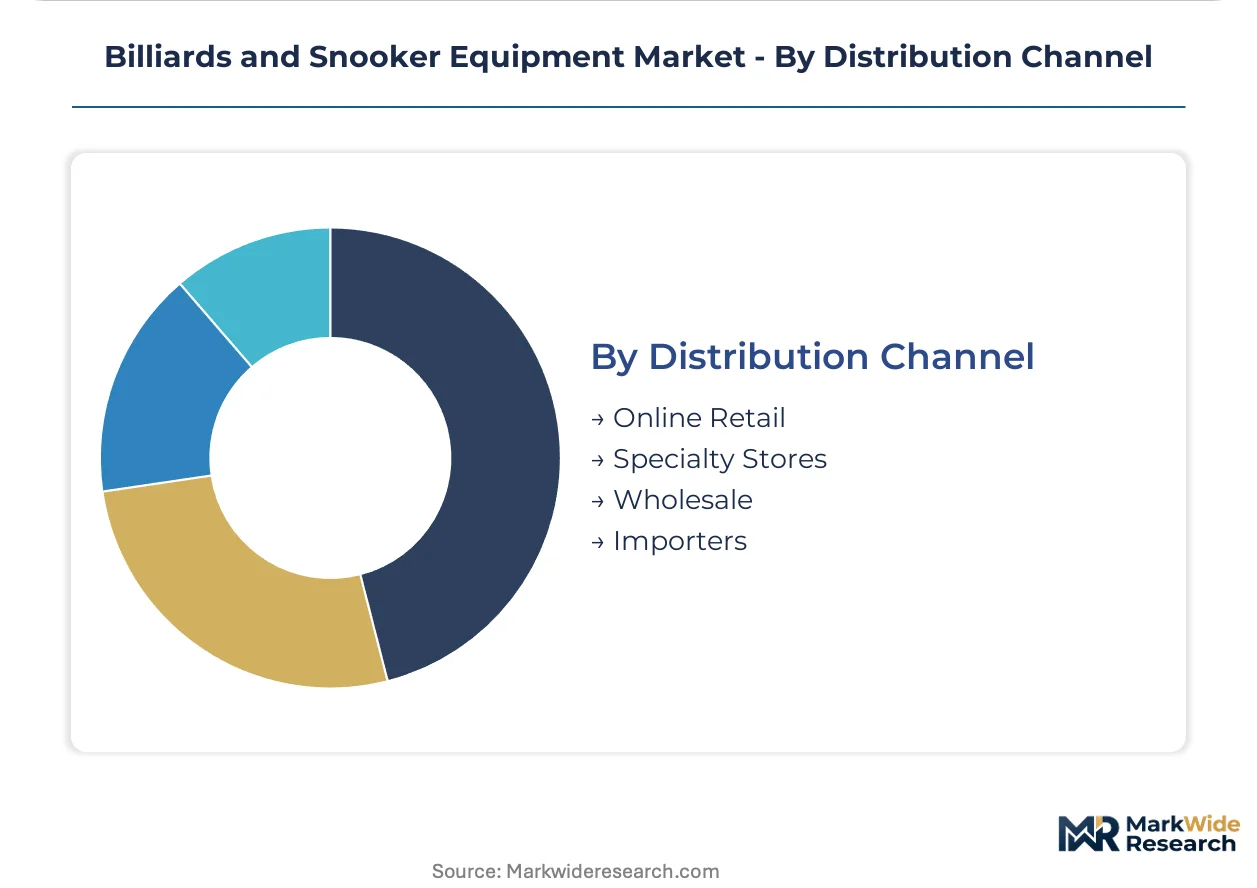
Distribution Channel:
Customer type divergence separates specification-heavy tournament procurement from convenience-driven residential transactions, with channel margins reflecting service intensity and technical consultation requirements.
- Online Retail:Direct-to-consumer platforms capture residential replacement demand and accessory replenishment, with logistics networks compressing delivery timelines for standard cue and ball configurations.
- Specialty Stores:Technical consultation and custom fitting services concentrate premium cue sales, with tactile evaluation remaining critical for professional player purchasing decisions.
- Wholesale:Bundled equipment-service contracts for hospitality chains in underpenetrated Indian metro markets present first-mover positioning for standardized table leasing models.
- Importers:Fragmented intermediaries face consolidation pressure as certified ball manufacturers with in-house laboratory capabilities capture European market share from testing-dependent competitors.
Specialty stores lead in value per transaction, with online retail expanding most quickly in unit terms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guangdong province anchors manufacturing capacity for slate-curing facilities and tournament-grade table assembly, while consumption clusters across China's provincial league circuits reshape procurement patterns worldwide.
China
Provincial tournament circuits in Jiangsu and Guangdong provinces drive standardized table procurement at scale, anchoring regional slate-curing facility investments. GB standards compliance for phenolic resin formulations shapes ball production export protocols. Manufacturing gravity concentrates in Dongguan and Shenzhen, where vertically integrated builders control material quality from raw input through finished assembly.
United States
EPA formaldehyde emission limits on wood adhesives extend curing cycles for domestic table manufacturers. Tournament-specification procurement consolidates among professional circuits, tightening vendor qualification criteria. Production clusters in Wisconsin and Texas sustain captive slate distribution networks and precision-machined rail system capabilities.
Italy
REACH substance restrictions on phenolic resin ball exports force reformulation timelines for manufacturers serving EU professional circuits. Slate quarry concentration in Lombardy and Tuscany exposes bed flatness certification to aging craftspeople scarcity. The Po Valley region hosts heritage-grade table finishing operations facing EU Green Deal chemical transition deadlines.
India
Commercial entertainment venues in Mumbai and Bangalore present first-mover positioning for standardized table leasing models targeting hospitality chains. BIS certification requirements for imported equipment create compliance barriers for fragmented intermediaries. Manufacturing activity concentrates in Maharashtra and Gujarat, where domestic assembly operations serve underpenetrated metro markets.
United Kingdom
Heritage-oriented competitive circuits sustain leather tip demand among purist professional players despite synthetic alternatives. CE marking requirements for climate-controlled venue infrastructure constrain equipment protection capabilities in humid subtropical installation geography. London and Manchester anchor specialty retail channels where tactile evaluation remains critical for professional player purchasing decisions.
Billiards and Snooker Equipment Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue carbon-fiber composite specialization and embedded sensor integration. The vendor base stratifies across three tiers: heritage manufacturers with captive raw material sources, precision engineering specialists serving tournament circuits, and volume-oriented assemblers targeting commercial hospitality chains. Dominant competitive moves include backward integration into slate quarrying and wood curing facilities, plus technology licensing agreements for modular shaft geometries.
Among heritage-tier fabricators, Brunswick Corporation exemplifies upstream control over material quality through captive supply networks. Diamond Billiard Products occupies a position within the precision-engineering archetype, while Predator Group represents the technology-forward segment pursuing composite material displacement of traditional hardwood. These three anchors illustrate how competitive positioning diverges between raw material security, manufacturing precision, and material science innovation vectors.
| Leading Market Players |
|---|
| Brunswick Corporation |
| Diamond Billiard Products |
| Olhausen Billiard Manufacturing |
| Predator Group |
| Valley-Dynamo |
| McDermott Cue Manufacturing |
| Berner Billiards |
| BCE Distributors |
| Aramith |
| Others |
Supply Flow & Price Mechanics
Italian slate block prices cascade through three distinct pricing tiers as freight-intensive logistics and geological scarcity concentrate margin capture among quarry-integrated table builders. EPA formaldehyde emission limits on wood adhesives extend domestic curing cycles, compressing mid-tier manufacturers while premium brands absorb compliance overhead through captive supply networks.
Pricing Analysis
Input-cost pass-through operates asymmetrically across the value chain. Three-tier pricing structure across premium, standard, and economy levels separates tournament-specification tables with embedded sensor rails from club-grade leasing configurations and compact residential formats. Price differentiation centers on certification grade and after-sales service bundling. Pricing pressure stems from carbon-fiber shaft modularization compressing regional repair premiums. Home users exhibit highest price sensitivity; professional tournament procurement shows lowest elasticity due to performance-guaranteed contract structures.
Supply Chain Analysis
Domestic-content mandates in India's BIS certification requirements for imported equipment reshape sourcing patterns for hospitality chains in Mumbai and Bangalore. Manufacturing gravity concentrates in China, Italy, and Brazil, with slate bed substrates drawing from Lombardy and Minas Gerais quarries. Raw material dependencies span phenolic resin formulations, carbon-fiber prepregs, and hardwood curing stock. Single-source vulnerability concentrates in aging Italian slate grading expertise. Distribution runs through specialty retail channels for professional fitting and direct-to-consumer platforms for standard configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EU Green Deal chemical transition timelines and China's GB standards compliance pathways, with water-based finish adoption costs diverging sharply across export jurisdictions.
For Market Incumbents: Hedge against carbon-fiber displacement by deepening backward integration into captive slate quarries and domestic wood curing facilities. Secure tournament circuit vendor qualification ahead of embedded sensor rail standardization. Prioritize in-house polymer chemistry capabilities to compress REACH certification timelines for phenolic resin ball exports.
For New Entrants and Emerging Players: Launch via performance-guaranteed leasing models targeting underpenetrated Indian commercial entertainment venues in Bangalore and Mumbai hospitality districts. White-space opportunities concentrate in bundled equipment-service contracts for provincial Chinese tournament circuits and compact residential sensor-integrated tables. Pursue direct-to-consumer carbon-fiber shaft configurations with interchangeable joint systems.
For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented importers lack in-house laboratory capabilities for REACH-compliant phenolic resin testing. Long-term viability favors vertically integrated manufacturers with captive raw material security and tournament circuit vendor lock-in. Acquisition target archetype: precision-engineering specialists with modular shaft geometry patents. Monitor carbon-fiber professional adoption rates as inflection indicator for hardwood supply chain displacement.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Slate Quarries | Brunswick Corporation's captive Italian and Brazilian extraction secures bed flatness certification capacity against craftspeople scarcity. |
| Carbon-Fiber Shaft Platform Standardization | Predator Group's modular taper geometries compress regional repair dependencies and expand premium pricing headroom. |
| REACH-Compliant Phenolic Resin Reformulation | Aramith's in-house polymer chemistry capabilities avoid third-party certification delays in EU professional circuits. |
| Embedded Sensor Rail System Development | Diamond Billiard Products' real-time ball tracking integration captures unclaimed broadcast analytics value in tournament infrastructure. |
| Performance-Guaranteed Leasing Model Expansion | Valley-Dynamo's bundled equipment-service contracts compress capital expenditure barriers for Shanghai and Shenzhen hospitality operators. |
Methodological Framework
Direct dialogue with table assembly plant managers, slate quarry operations directors, professional tournament procurement officers, carbon-fiber shaft R&D leads, and hospitality chain equipment buyers grounded qualitative findings. Secondary validation drew from EPA emission compliance filings, ECHA REACH substance restriction updates, China GB standards documentation, customs trade records for slate block imports, and SEC 10-K disclosures from publicly traded recreational equipment manufacturers. Bottom-up bill-of-materials costing and top-down tournament circuit procurement aggregation triangulated market sizing.
Bottom-up unit economics across product segments reconciled with top-down venue installation tracking and regional league expansion announcements across the analysis window. Segmentation dimensions modeled include product type, end-user tier, material composition, and distribution channel, with additional granularity on certification grade and climate-controlled infrastructure requirements. CAGRs derived from replacement cycle analysis, provincial tournament circuit procurement schedules, and carbon-fiber adoption curve extrapolation from professional player equipment surveys. Forecast inputs incorporated freight cost volatility indices and slate quarry capacity utilization estimates.
Several conditions sit outside the modeled scope, including unannounced regulatory acceleration of EU F-Gas Regulation constraints, geopolitical interruption of Brazilian slate extraction, and breakthrough displacement of phenolic resin by alternative ball substrates. Forecasts reflect documented assumptions regarding tournament circuit consolidation trajectories and China domestic league expansion continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sportswear
Cycling Wear Market
Sportswear
Casual Sportswear Market
Sportswear
Cricket Bowling Machine Market
Sportswear
Athleisure Market
Sportswear
Global Women Active Wear Market
Sportswear
Athleisure Wear Market
Sportswear
Europe Dancewear Market
Sportswear
Skateboard Grip Tapes Market
Sportswear
Bicycle Apparels Market
Sportswear
North America Dancewear Market
Sportswear
Workout Clothes Market
Sportswear
Cycling Apparel Market
Sportswear
Activewear Market
Sportswear
Sports Socks for Children Market