
 Casual Sportswear Market | 2026-2036
Casual Sportswear Market Size, Share, and Industry Trends Forecast 2026-2036
Casual Sportswear Market Analysis
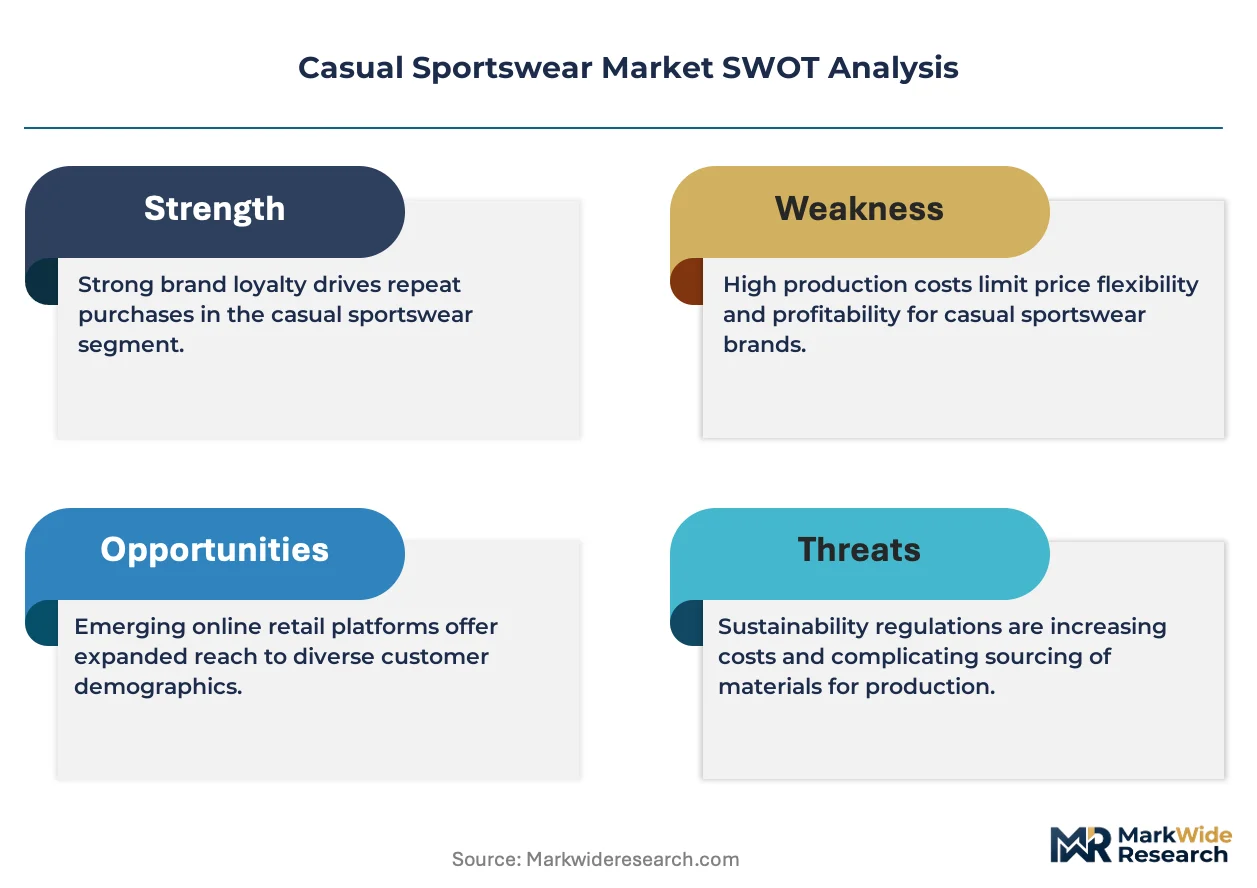
ISO 14001 environmental management certification is reorganizing supplier eligibility across the casual sportswear value chain, forcing factory upgrades before purchase orders flow. Nike Inc. leverages its scale to enforce compliance tiers across Asian contract manufacturers. Adidas AG sustains premium positioning through Bluesign-approved material sourcing. Li Ning Group anchors domestic growth with performance fabrics tailored to humid climates.
Casual sportswear encompasses apparel engineered for athletic-inspired daily wear, typically blending synthetic fibers such as recycled polyester with elastane for four-way stretch recovery and moisture-wicking performance. Hoodies and track pants dominate volume, while nylon-spandex blends command higher unit economics in the women's segment. Online retail channels are displacing department stores as the primary discovery mechanism, though specialty stores retain margin concentration through experiential fit technology. Cotton remains the baseline material for entry-price T-shirts, but spandex-infused fabrications are expanding fastest in unisex collections.
The EU Green Deal and REACH chemical restrictions are tightening dye discharge standards across European import supply chains, while China's GB standards enforce domestic labeling transparency on fiber content claims. The US EPA monitors per- and polyfluoroalkyl substance (PFAS) contamination in water-repellent finishes, pressuring brands to reformulate durable coatings. Stakeholders must track how regional regulatory divergence on synthetic microfiber shedding reshapes material specifications and sourcing geography decisions.
Market Dynamics
ISO 14001 certification is restructuring supplier eligibility across the casual sportswear value chain, forcing factory upgrades before purchase orders flow and concentrating procurement among compliant manufacturers.
Growth Catalysts
- EU Green Deal textile requirements:Mandates for recycled polyester and organic cotton sourcing are pulling brands toward certified supply chains and creating first-mover advantages for compliant producers.
- Gen Z and millennial consumption clusters:University campuses and urban co-working spaces are generating concentrated demand for athletic-inspired daily wear with performance fabric properties.
- Four-way stretch recovery technology:Elastane-infused fabrications are expanding addressable use cases from gym environments to workplace and social settings.
Market Restraints
- Recycled polyester feedstock volatility:Post-consumer PET bottle supply fluctuations create input cost instability for sustainable product lines.
- Asian contract manufacturer concentration:Heavy reliance on clustered production zones exposes brands to single-point disruption risks from climate events or labor actions.
- PFAS reformulation timelines:US EPA water-repellent finish restrictions are forcing extended R&D cycles before compliant coatings reach commercial scale.
Strategic Opportunities
- China tier-one city domestic label expansion:Shanghai and Beijing present white space for local brands to capture share from Western incumbents through climate-tailored performance fabrics.
- Experiential fit technology in specialty retail:3D body scanning and virtual try-on installations are creating margin concentration through service differentiation.
- Bluesign-approved material premiumization:Chemical safety certification is enabling pricing stratification in the women's nylon-spandex segment.
Industry Challenges
- ISO 14001 certification timelines:Factory audit and remediation cycles are extending supplier onboarding by 12-18 months, constraining capacity scaling.
- Synthetic microfiber shedding compliance:Divergent regional testing protocols on fiber release are fragmenting material specifications and complicating geographic sourcing decisions.
- Legacy dye house retrofit requirements:REACH-compliant discharge systems demand capital outlays that smaller suppliers cannot absorb without consolidation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Casual Sportswear Market |
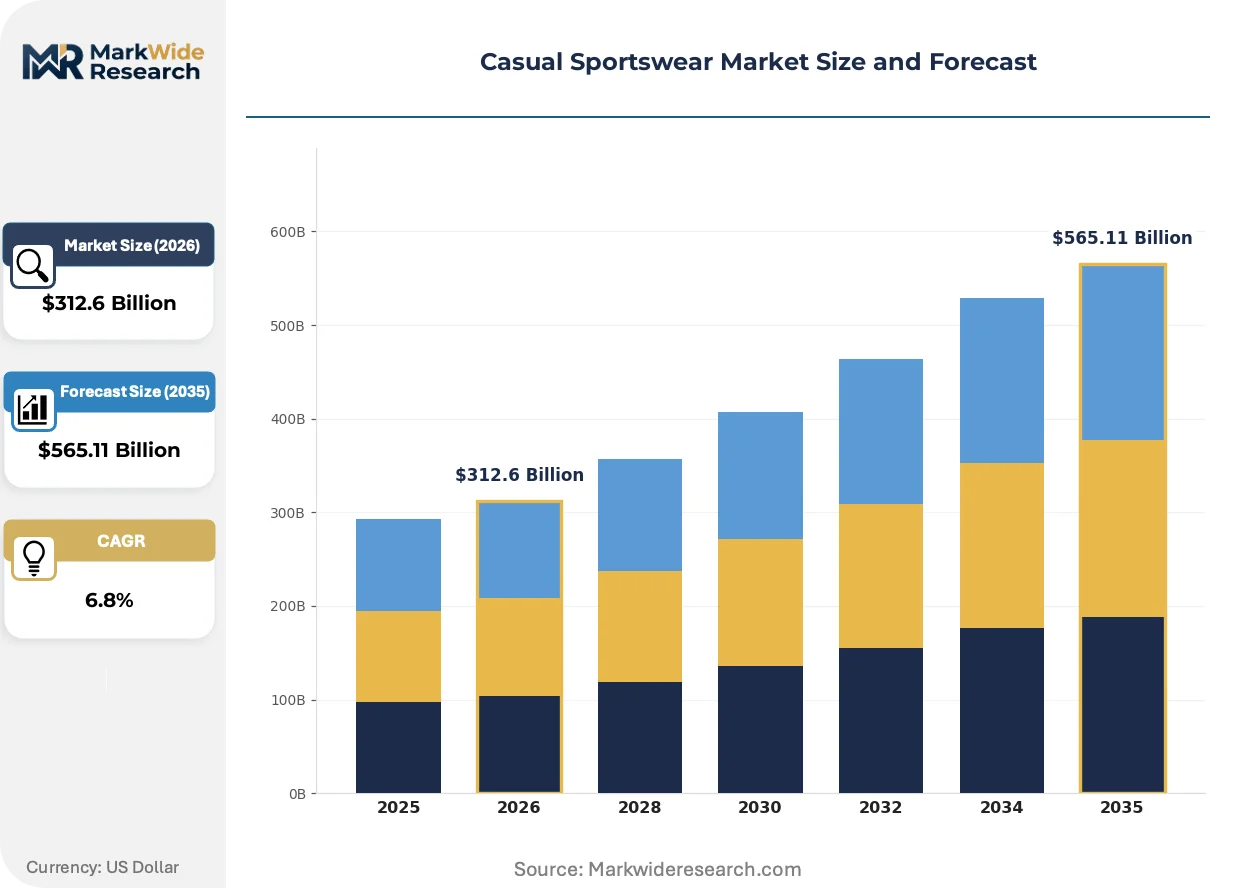
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $565.11 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: T-Shirts, Shorts, Hoodies, Track Pants Material: Cotton, Polyester, Nylon, Spandex Gender: Men, Women, Unisex, Children Distribution Channel: Online Retail, Specialty Stores, Department Stores, Sports Outlets |
| Companies Covered | Lululemon Athletica Inc., Li Ning Group, Nike Inc., The North Face, Under Armour Inc., Adidas AG, Columbia Sportswear Company, Anta Sports, Puma SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Casual Sportswear Market Emerging Trajectories
Material science advances and regulatory pressure are splitting the casual sportswear market into certified premium tiers and conventional mass production, with technology adoption curves diverging sharply between segments.
Recycled polyester mechanical recycling is bifurcating the supply base into fiber-to-fiber circular systems and downcycled bottle-to-fleece operations. Premium brands are adopting chemical recycling partnerships for quality parity with virgin feedstock, while mass-market labels remain locked in mechanical routes with shorter fiber lengths and performance degradation. This split is compressing margin structures in the mid-market as material costs diverge.
REACH chemical restrictions are tightening dye discharge standards across European import supply chains, forcing wet processing relocation or on-site effluent treatment investments. Brands serving EU markets are consolidating orders among vertically integrated dye houses with tertiary treatment capacity, while others are exiting the geography entirely. The women's segment, with its complex color palettes and nylon-spandex substrates, faces the steepest compliance burden.
Discovery behavior is rotating from department store browsing to algorithmic social commerce feeds, with fit uncertainty becoming the primary purchase friction. Specialty retailers are deploying 3D scanning and AR visualization to recover margin through service premiums, while pure-play digital brands absorb higher return rates. This channel tension is most visible in China's tier-one cities, where live-streaming commerce has compressed decision cycles to impulse timeframes.
Casual Sportswear Market Segmentation
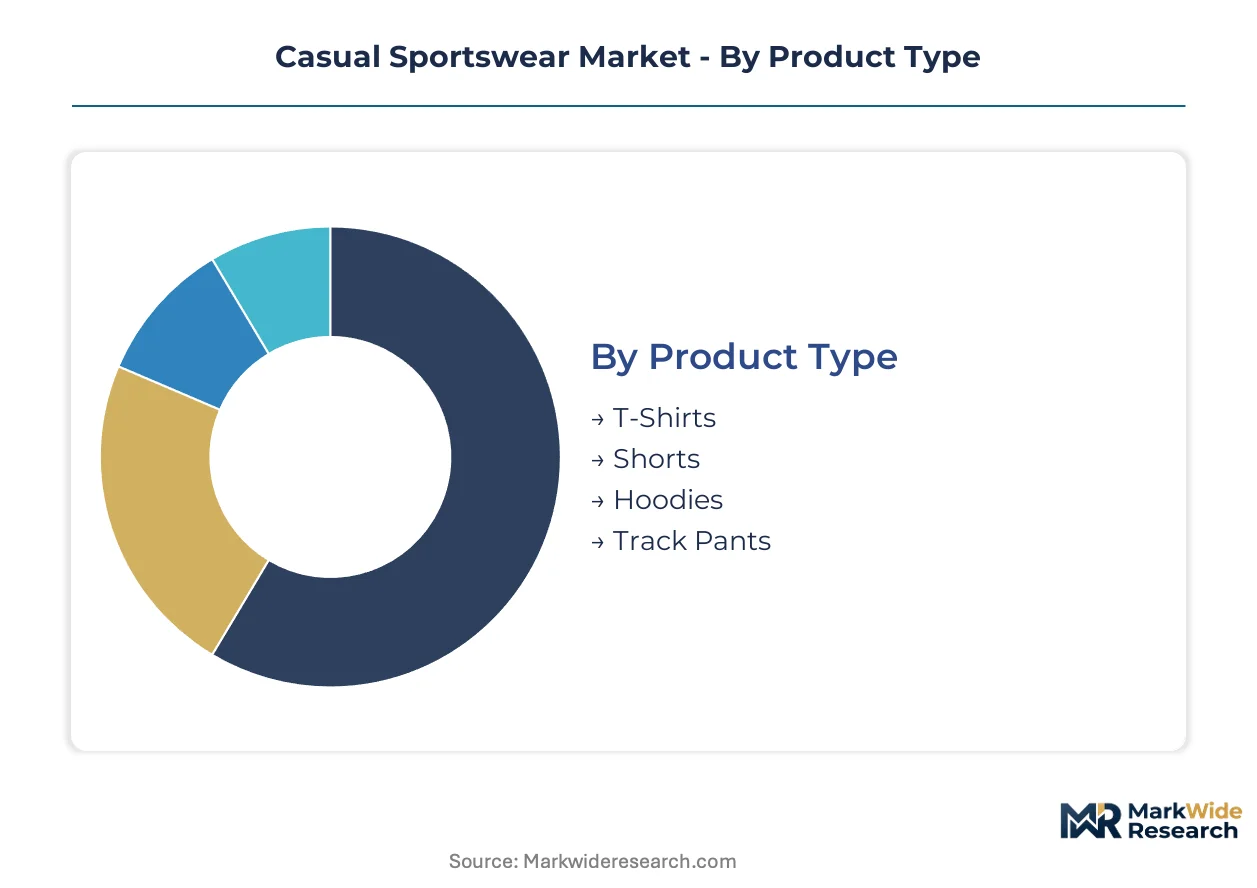
Casual sportswear segmentation reveals how material innovation, channel migration, and demographic targeting create distinct competitive arenas. Each dimension carries divergent margin profiles and compliance burdens that reshape supplier relationships and geographic strategy.
Product Type:
Hoodies and track pants anchor domestic production volumes in China and Vietnam, while T-shirts and shorts flow through export-oriented Bangladesh and Cambodia facilities.
- Hoodies:Engineered with brushed fleece interiors and elastane cuffs for thermal retention and shape recovery. Demand concentrates in China's tier-one cities and US university towns, where ISO 14001-certified factories capture premium placement through Bluesign-approved dye processes.
- Track Pants:Four-way stretch constructions blend recycled polyester with spandex for gym-to-street versatility. European co-working districts and Shanghai commercial zones drive specification tightening on moisture-wicking performance.
- T-Shirts:Cotton-polyester blends dominate entry-price positioning with shorter fiber mechanical recycling.
- Shorts:Lightweight nylon-spandex hybrids serve humid climate performance needs with faster inventory turns.
Hoodies command the established base. The steepest expansion runs through track pants.
Material:
Cost tier stratification splits the supply base between certified premium feedstocks and conventional mass-market inputs.
- Recycled Polyester:Chemical recycling partnerships yield fiber-to-fiber circularity with virgin-equivalent performance. EU Green Deal compliance mandates pull brands toward mechanically recycled bottle-to-fleece operations for entry-tier products.
- Organic Cotton:GOTS-certified sourcing commands 20-40% fiber premiums in European and North American channels. REACH dye restrictions fragment wet processing geography toward vertically integrated Indian and Turkish spinners.
- Nylon:Petroleum-derived base with highest unit economics in women's performance segments.
- Spandex:Elastane infusion rates determine stretch recovery grades across unisex collections.
Recycled polyester commands the established base. The steepest expansion runs through organic cotton.
Gender:
Application intensity varies by use-case breadth, with unisex collections compressing design cycles and women's lines carrying complex color compliance burdens.
- Women:Nylon-spandex blends with intricate dye palettes face steepest REACH effluent treatment requirements. Complex substrate handling consolidates orders among tertiary-capacity dye houses in Portugal and Italy.
- Unisex:Simplified sizing matrices and neutral colorways enable faster response to algorithmic social commerce demand spikes. China's live-streaming channels absorb highest volume concentration.
- Men:Standardized fit blocks support bulk production economies with lower return rates.
- Children:Flammability and chemical safety standards restrict supplier pools to certified facilities.
Women's lines command the established base. The steepest expansion runs through unisex.
Distribution Channel:
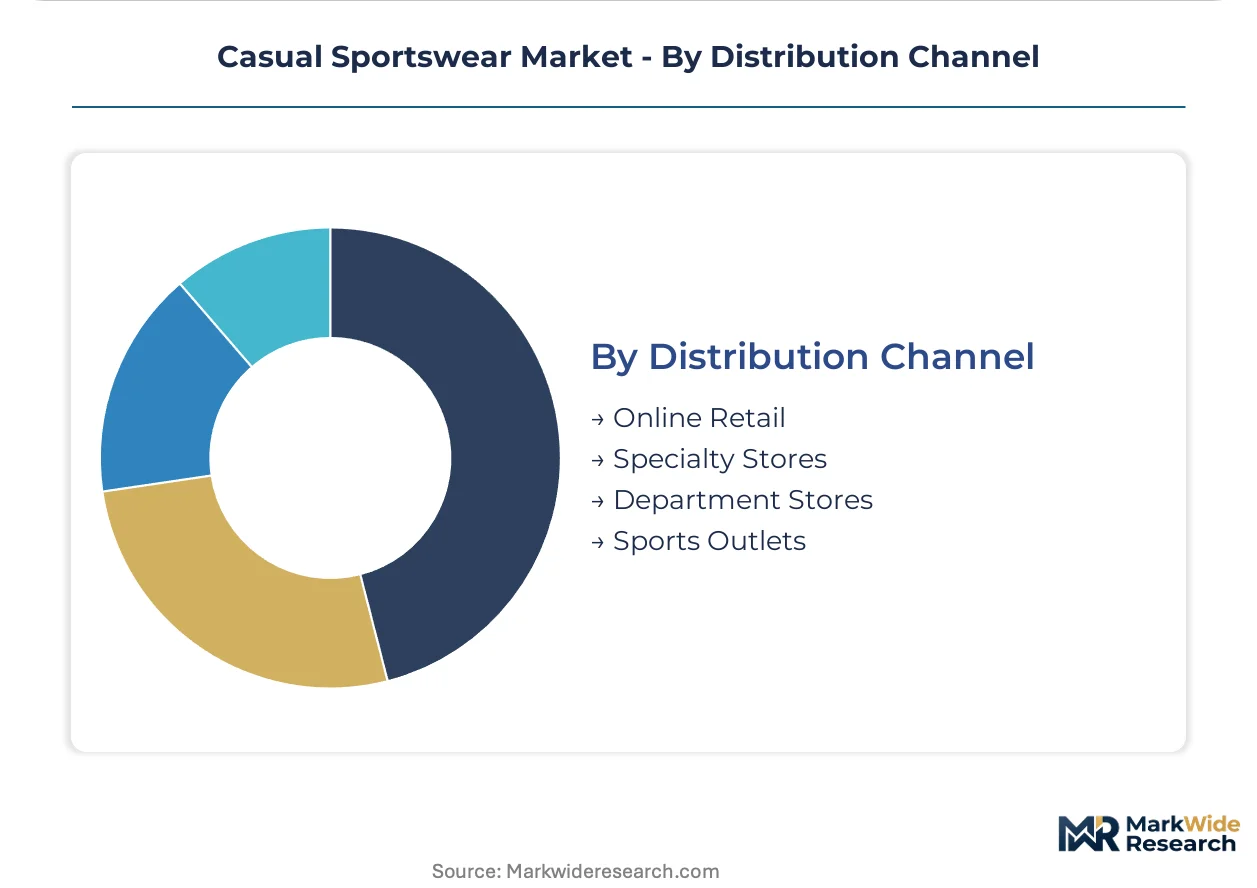
Customer type migration from department store browsers to digital-native discovery platforms restructures margin capture mechanisms.
- Online Retail:Algorithmic feeds and live-streaming commerce compress decision cycles to impulse timeframes. Pure-play digital brands absorb elevated return rates while specialty platforms deploy AR visualization to reduce fit friction.
- Specialty Stores:3D body scanning installations create service-premium pricing stratification. Experiential fit technology concentrates in China's tier-one cities and US coastal metropolitan zones.
- Department Stores:Legacy footprint faces channel displacement with inventory markdown pressure.
- Sports Outlets:Off-price positioning captures value-seeking segments with limited sustainability certification.
Specialty stores command the established base. The steepest expansion runs through online retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal textile sustainability mandates are redirecting procurement flows toward certified supply chains across major consumption zones. National regulations on chemical discharge and fiber transparency are reshaping where brands manufacture and sell.
United States
Gen Z consumption clusters on university campuses and in urban co-working spaces drive demand for four-way stretch performance fabrics. US EPA monitoring of PFAS contamination in water-repellent finishes pressures brands to reformulate durable coatings. Los Angeles and New York City concentrate specialty retail innovation through experiential fit technology installations.
China
Domestic labels capture share from Western incumbents in Shanghai and Beijing through climate-tailored performance fabrics for humid conditions. GB standards enforce domestic labeling transparency on fiber content claims. The Yangtze River Delta anchors production concentration for hoodies and track pants with ISO 14001-certified factory upgrades.
Germany
REACH chemical restrictions tighten dye discharge standards across import supply chains, consolidating orders among vertically integrated dye houses. Bluesign-approved material sourcing enables premium positioning in the women's nylon-spandex segment. Berlin and Munich drive demand for organic cotton-certified product lines through sustainability-conscious consumer segments.
Japan
METI guidelines on circular textile systems accelerate fiber-to-fiber recycling partnerships for quality parity with virgin feedstock. Technical performance standards elevate specifications for moisture-wicking unisex collections. The Kanto region around Tokyo concentrates specialty retail deployment of 3D body scanning technology.
India
GOTS-certified organic cotton sourcing from Indian spinners commands fiber premiums in export channels to Europe and North America. BIS labeling requirements intersect with state-level textile policies in Gujarat and Tamil Nadu. Tiruppur and Surat industrial clusters face REACH-compliant discharge system retrofit demands that favor consolidated wet processing operators.
Casual Sportswear Market Vendor Landscape
Player mix skews toward diversified sportswear conglomerates with multi-brand portfolios and vertical manufacturing control. Market structure concentrates procurement leverage among scale leaders capable of enforcing compliance tiers across Asian contract manufacturers. Three archetypes dominate: integrated conglomerates with captive supply chains, premium specialists anchored in technical fabric innovation, and domestic champions leveraging geographic proximity to tier-one city demand. Competitive moves center on sustainability certification racing and direct-to-channel digital infrastructure buildout.
Within the integrated conglomerate tier, Nike Inc. and Adidas AG occupy positions defined by global procurement scale and compliance enforcement capabilities. Among domestic champions, Li Ning Group and Anta Sports exemplify the archetype of climate-tailored product development for humid market conditions. Lululemon Athletica Inc. represents the premium specialist vector, sitting within a positioning tier where technical fabric performance commands service-premium pricing stratification. These named entities anchor industry-level commentary on how scale, geographic focus, and technical specialization distribute competitive advantage across the value chain.
| Leading Market Players |
|---|
| Lululemon Athletica Inc. |
| Li Ning Group |
| Nike Inc. |
| The North Face |
| Under Armour Inc. |
| Adidas AG |
| Columbia Sportswear Company |
| Anta Sports |
| Puma SE |
| Others |
Supply Flow & Price Mechanics
Recycled polyester's displacement of virgin petroleum-derived feedstock simultaneously pulls wet processing toward vertically integrated dye houses in Portugal and Italy while compressing margin structures for mid-market labels locked in mechanical recycling routes with shorter fiber degradation.
Pricing Analysis
Certification level creates the primary spread across the casual sportswear market. Three-tier pricing structure across premium, standard, and economy levels separates Bluesign-approved nylon-spandex blends from ISO 14001-compliant basics and uncertified entry-price cotton-polyester T-shirts. Cost compression in the mid-market intensifies because chemical recycling partnerships command fiber premiums while mechanical routes face performance degradation discounts. University campus buyers show highest price sensitivity, whereas sustainability-conscious segments in Berlin and Munich absorb certified organic cotton premiums.
Supply Chain Analysis
Inventory cycles for four-way stretch fabrications have elongated to 16-20 weeks as ISO 14001 factory audit queues extend supplier onboarding timelines. Production gravity centers on China's Yangtze River Delta for hoodies and track pants, Bangladesh for cotton-polyester T-shirts, and Vietnam for nylon-spandex women's lines. Feedstock draws from post-consumer PET bottle collection networks, GOTS-certified Indian cotton spinners, and petroleum-derived elastane producers. Single-source vulnerability concentrates in Asian contract manufacturer clusters exposed to climate disruption. Distribution runs through algorithmic social commerce feeds and experiential specialty retail with 3D body scanning installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Casual sportswear sits in early-cycle expansion as Gen Z and millennial adoption of athletic-inspired daily wear penetrates workplace and social contexts beyond traditional gym environments.
For Market Incumbents: Fortify compliance tier enforcement across Asian contract manufacturers before EU Green Deal textile mandates harden supplier eligibility requirements. Deepen backward integration into chemical recycling partnerships to secure fiber-to-fiber circularity with virgin-equivalent performance. Capture channel control through experiential fit technology installations in China's tier-one cities where live-streaming commerce compresses decision cycles.
For New Entrants and Emerging Players: Anchor in Shanghai and Beijing white space where domestic labels capture share from Western incumbents through climate-tailored performance fabrics for humid conditions. Target unisex collections with simplified sizing matrices for algorithmic social commerce velocity. Pursue Bluesign-approved material sourcing as the go-to-market angle for premium positioning in the women's nylon-spandex segment.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed domestic champions lacking chemical recycling capabilities or direct-to-channel digital infrastructure. Five-to-ten year viability hinges on certification racing completion and geographic diversification beyond clustered Asian production zones. Watch synthetic microfiber shedding compliance divergence as the signal for material specification fragmentation and sourcing geography restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| Bluesign Certification Investment | Chemical safety approval enables pricing stratification in women's nylon-spandex segments. |
| Chemical Recycling Partnership | Fiber-to-fiber circularity achieves virgin-equivalent performance for premium product lines. |
| Direct-to-Channel Digital Buildout | Algorithmic social commerce feeds capture Gen Z impulse purchase behavior in tier-one cities. |
| Experiential Fit Technology Deployment | 3D body scanning installations recover margin through service premiums in specialty retail. |
| Climate-Tailored Fabric Development | Moisture-wicking specifications for humid conditions differentiate domestic champions in China. |
Methodological Framework
The analysis maps hoodies and track pants, T-shirts and shorts, recycled polyester and organic cotton sourcing tiers, and online retail versus specialty store channels, each validated through brand sustainability officers, Asian contract manufacturer operations directors, European retail category buyers, and textile chemical compliance consultants. Primary interview findings triangulate against customs and trade data, EU ECHA REACH substance notifications, SEC 10-K supply chain disclosures, and GB standards fiber content labeling records. Bottom-up product-level volume builds reconcile with top-down category spend estimates across the analysis window.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, material certification tier, gender application, and distribution channel complexity. CAGRs derive from historical trajectory analysis adjusted for regulatory inflection points and technology adoption curves. Forecast inputs incorporate EU Green Deal textile mandate implementation timelines and PFAS reformulation cycle completion rates.
Material uncertainties — recycled polyester feedstock volatility, ISO 14001 certification queue extensions, and synthetic microfiber shedding protocol divergence — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory enforcement intensity and consumer willingness-to-pay for certified products. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sportswear
Billiards and Snooker Equipment Market
Sportswear
Sports Socks for Children Market
Sportswear
Skateboard Grip Tapes Market
Sportswear
Activewear Market
Sportswear
Workout Clothes Market
Sportswear
Athleisure Wear Market
Sportswear
Cricket Bowling Machine Market
Sportswear
North America Dancewear Market
Sportswear
Global Women Active Wear Market
Sportswear
Cycling Wear Market
Sportswear
Cycling Apparel Market
Sportswear
Europe Dancewear Market
Sportswear
Bicycle Apparels Market
Sportswear
Athleisure Market