
 Custom Cycling Clothing Market | 2026-2036
Custom Cycling Clothing Market Size, Share, and Industry Trends Forecast 2026-2036
Custom Cycling Clothing Market Analysis
Portuguese cut-and-sew capacity is realigning toward small-batch, quick-turn custom production for European cycling brands. Champion System leverages vertically integrated factories across Asia to sustain rapid delivery timelines for club and corporate accounts. DNA Cycling anchors its competitive position through deep specialization in dye-sublimation printing for regional amateur racing circuits.
Custom cycling clothing encompasses made-to-measure or made-to-order garments engineered from technical knitted fabrics with specified moisture-wicking rates, UPF ratings, and aerodynamic panel geometries, produced through sublimation printing or cut-and-sew assembly to deliver performance, fit precision, and visual identity for individual riders, teams, and retail programs. Polyester jerseys dominate volume due to cost-efficient sublimation compatibility and durability across wash cycles, while Lycra bibs command premium positioning through compression engineering and chamois integration that commands higher per-unit margins. Amateur cyclists represent the broadest addressable base, though professional teams concentrate purchasing power through annual sponsorship obligations that guarantee recurring revenue for specialized manufacturers.
REACH governs chemical inputs across European textile supply chains, compelling dye houses to reformulate colorants and eliminate restricted substances from custom production workflows. The EU Green Deal extends pressure through carbon accounting requirements that affect offshore manufacturing decisions for brands serving European clubs. Stakeholders must monitor how evolving extended producer responsibility frameworks reshape cost structures for custom kit producers reliant on synthetic fiber platforms.
Market Dynamics
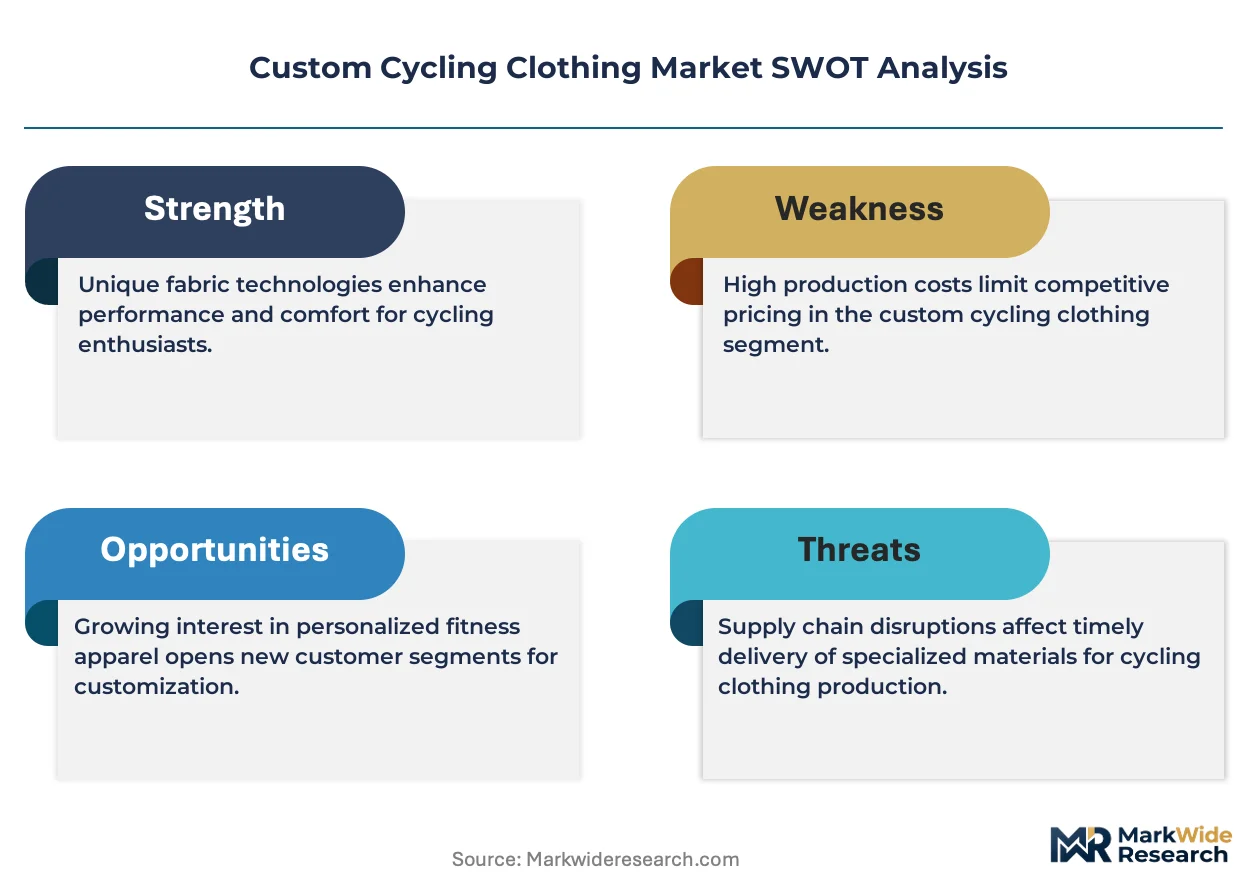
REACH compliance in Europe is forcing dye houses to reformulate colorants and eliminate restricted substances, compressing margins for custom kit producers while creating compliance moats for specialized manufacturers with in-house chemical testing.
Growth Catalysts
- EU Green Deal carbon accounting:Extended producer responsibility frameworks are accelerating demand for traceable synthetic fiber supply chains among European cycling clubs seeking documented sustainability credentials.
- Amateur racing circuit expansion:Regional amateur leagues across Italy, Belgium, and France are mandating annual kit refreshes, creating predictable replacement cycles for dye-sublimation specialists.
- Polyester sublimation compatibility:Advances in low-temperature sublimation inks are enabling faster production turnaround on recycled polyester bases, aligning cost efficiency with circular economy mandates.
Market Restraints
- Petrochemical input volatility:Polyester and Lycra feedstock prices fluctuate with crude oil indices, compressing per-unit margins for manufacturers locked into fixed-price club contracts.
- Treviso-Milan supply concentration:Historic Italian manufacturing clusters concentrate premium cut-and-sew expertise, creating geographic single-point-of-failure risk for WorldTour squad supply.
- Chamois integration complexity:Multi-density foam pad bonding requires specialized thermal pressing equipment that smaller dye-sublimation shops cannot economically deploy.
Strategic Opportunities
- Portuguese quick-turn capacity:Porto and Lisbon cut-and-sew facilities are repositioning toward sub-50-unit minimum order quantities, capturing boutique European cycling clubs abandoned by Asian volume producers.
- Corporate wellness program adoption:Technology sector employers are subsidizing custom team kits as employee retention instruments, opening B2B channels distinct from traditional club sponsorship models.
- CSRD disclosure requirements:The EU Corporate Sustainability Reporting Directive is creating tiered supplier preference for custom apparel vendors with verified Scope 3 emissions data.
Industry Challenges
- Dye-sublimation color matching:Achieving Pantone consistency across polyester lots requires skilled color technicians, a talent pool concentrated in northern Italian industrial districts.
- REACH documentation timelines:Chemical safety data sheet compilation for custom color formulations extends sample-to-production lead times by three to four weeks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Custom Cycling Clothing Market |
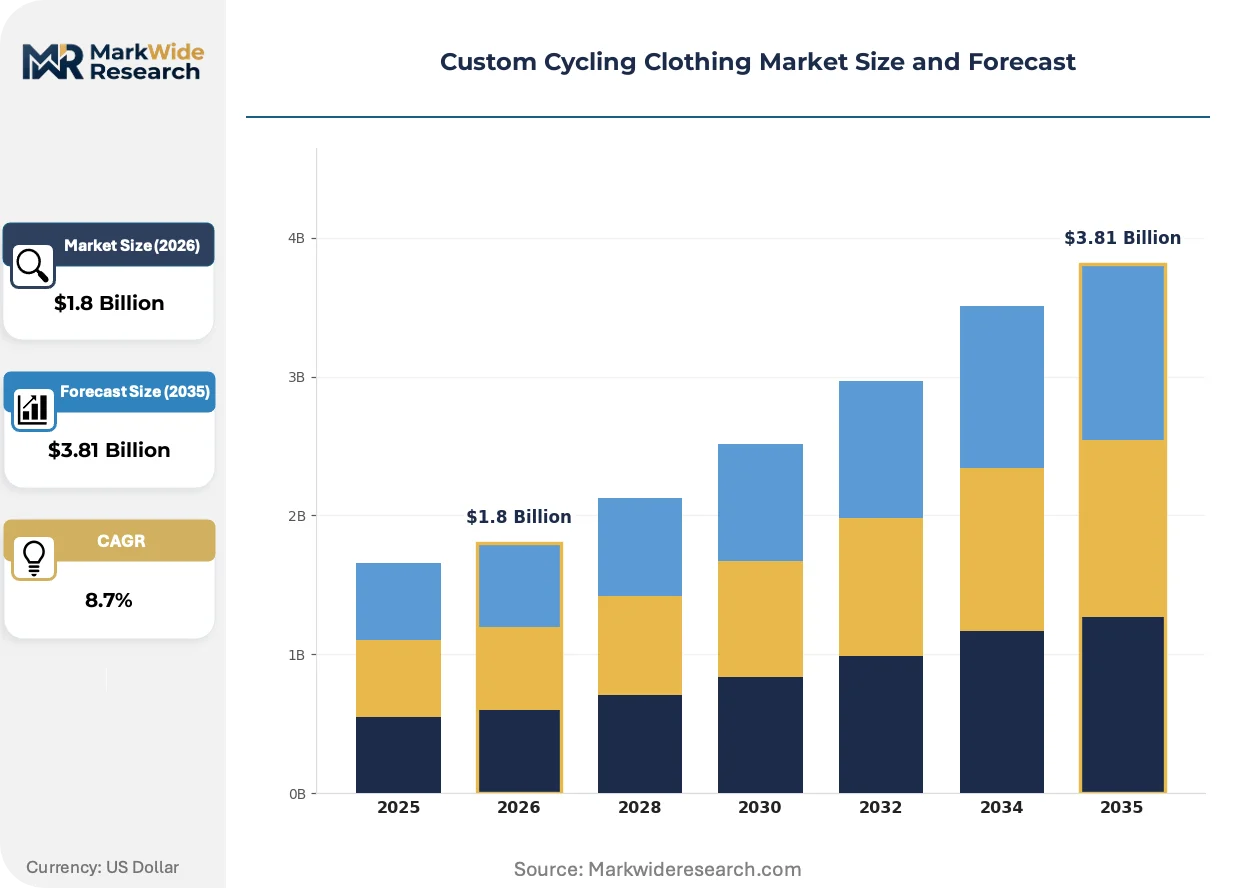
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Jerseys, Shorts, Bibs, Jackets Material: Polyester, Nylon, Merino Wool, Lycra End User: Amateur Cyclists, Professional Teams, Retail Consumers, Clubs Customization Type: Design, Fit, Branding, Sizing |
| Companies Covered | Champion System, DNA Cycling, Mega Sports Apparel, Primal Wear, Podiumwear Custom Sports Apparel, Pactimo, Verge Sports, Jakroo Custom Apparel, Manifattura Valcismon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Custom Cycling Clothing Market Emerging Trajectories
Technical fabric engineering and regulatory disclosure requirements are reshaping how custom cycling apparel is specified, produced, and procured across European and North American markets.
Bonded seam construction is integrating laser-cut panel edges with ultrasonic welding to eliminate stitch lines that create aerodynamic drag and skin irritation points. WorldTour squads are specifying these constructions for time trial suits and criterium jerseys. The technology is integrating into mid-tier club offerings as Portuguese and Italian manufacturers amortize equipment costs across broader production volumes.
REACH Annex XVII restrictions on perfluorinated compounds are compelling finish houses to develop paraffin-based water repellency treatments for custom rain jackets and thermal vests. The reformulation burden falls heaviest on small-batch producers serving regional amateur circuits, who lack dedicated compliance departments and must rely on third-party certification laboratories in Germany and the Netherlands.
Club procurement officers are consolidating vendor relationships to reduce administrative overhead, abandoning fragmented sourcing across separate jersey, bib, and accessory suppliers. This concentration favors full-line manufacturers with integrated design-to-delivery platforms. The shift is most visible in British and German cycling federations, where league administrators are negotiating master supply agreements on behalf of affiliated clubs.
Custom Cycling Clothing Market Segmentation
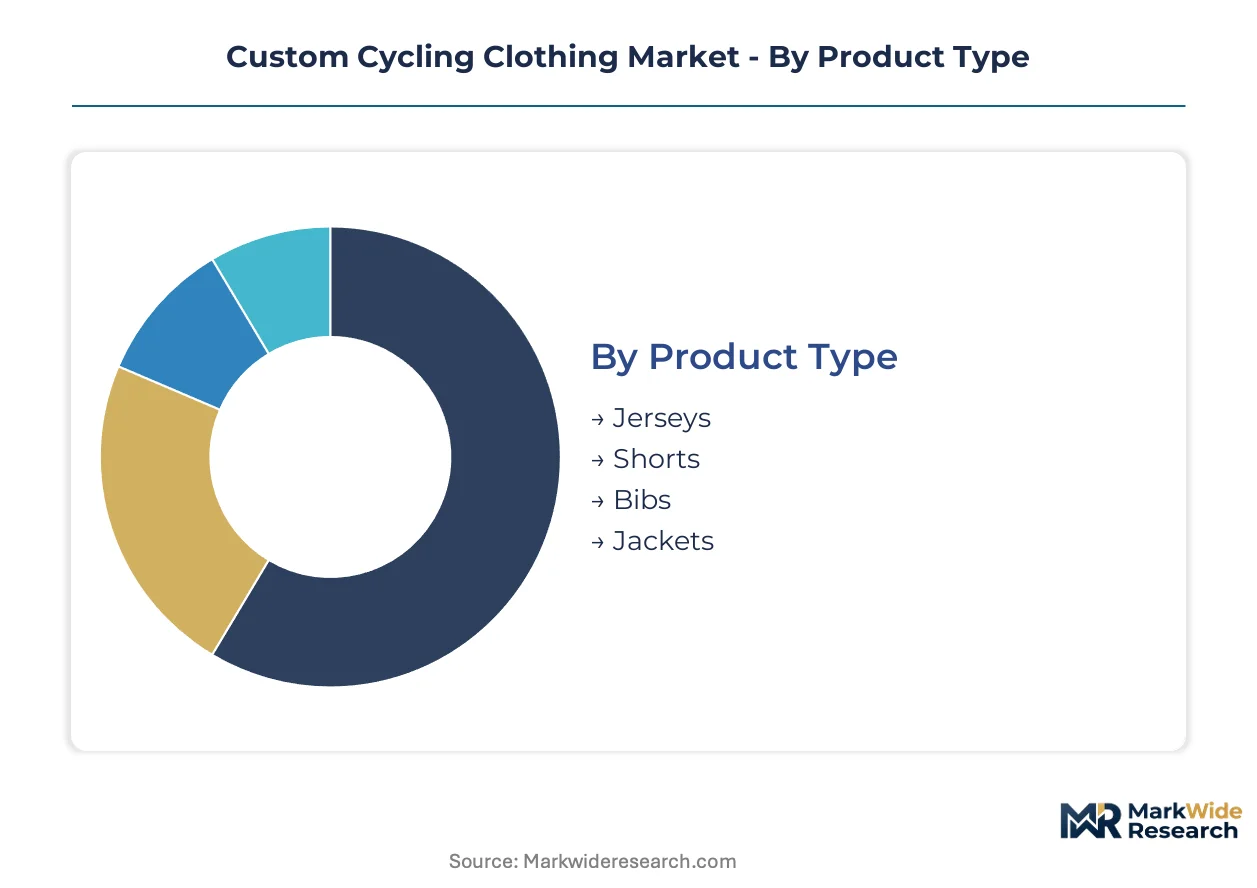
Segmentation in custom cycling clothing reflects divergent technical requirements across performance tiers. Product specifications, material choices, and customization depth vary sharply between WorldTour squads and regional amateur clubs.
Product Type:
Customization intensity decreases as garment complexity increases, with simpler panel geometries enabling faster turnaround.
- Jerseys:Polyester-based constructions with sublimation-printed graphics dominate volume. Demand concentrates among Italian amateur racing circuits where clubs mandate annual design refreshes to satisfy sponsor visibility requirements.
- Bibs:Multi-panel Lycra assemblies with integrated chamois demand specialized thermal bonding equipment. Professional teams in Belgium and France specify these for stage racing, driving premium positioning through compression engineering and pad density gradations.
- Shorts:Lower-compression alternatives serve recreational riders and training scenarios with reduced technical specifications.
- Jackets:Weather-protective outer layers require bonded seam construction and DWR finishes, limiting viable supplier pools to manufacturers with ultrasonic welding capability.
Most installed capacity flows through Jerseys. Expansion is steepest in Bibs.
Material:
Cost tiers separate commodity synthetics from performance-engineered fibers with certified sustainability credentials.
- Polyester:Recycled PET variants align with EU Green Deal carbon accounting mandates. Portuguese dye houses are reformulating low-temperature sublimation processes to accommodate these bases without color degradation.
- Lycra:Elastane content percentages determine compression gradation for race-fit applications. REACH compliance documentation for elastane finishing agents extends lead times for custom orders serving German cycling federations.
- Nylon:Abrasion-resistant face fabrics appear in overshorts and outer layers with lower printability than polyester alternatives.
- Merino Wool:Natural fiber thermal regulation commands niche positioning among gravel racing segments prioritizing odor resistance over sublimation compatibility.
Polyester absorbs the largest production share. Merino Wool is gaining share fastest among sustainability-positioned brands.
End User:
Procurement authority and volume concentration diverge across participant categories with distinct refresh cycles.
- Professional Teams:Annual sponsorship obligations guarantee recurring revenue with specified design windows. WorldTour squads based in Italy and Spain concentrate purchasing power through centralized kit procurement.
- Clubs:Aggregated amateur membership enables volume pricing with fragmented decision-making across regional committee structures. British Cycling federation master agreements are consolidating vendor relationships.
- Amateur Cyclists:Individual purchasers drive made-to-measure subsegments with higher per-unit margins and extended fulfillment timelines.
- Retail Consumers:Stock keeping unit purchases without customization represent a distinct channel with different margin structures.
Professional Teams anchor revenue stability. Clubs are climbing the fastest as federation procurement centralization accelerates.
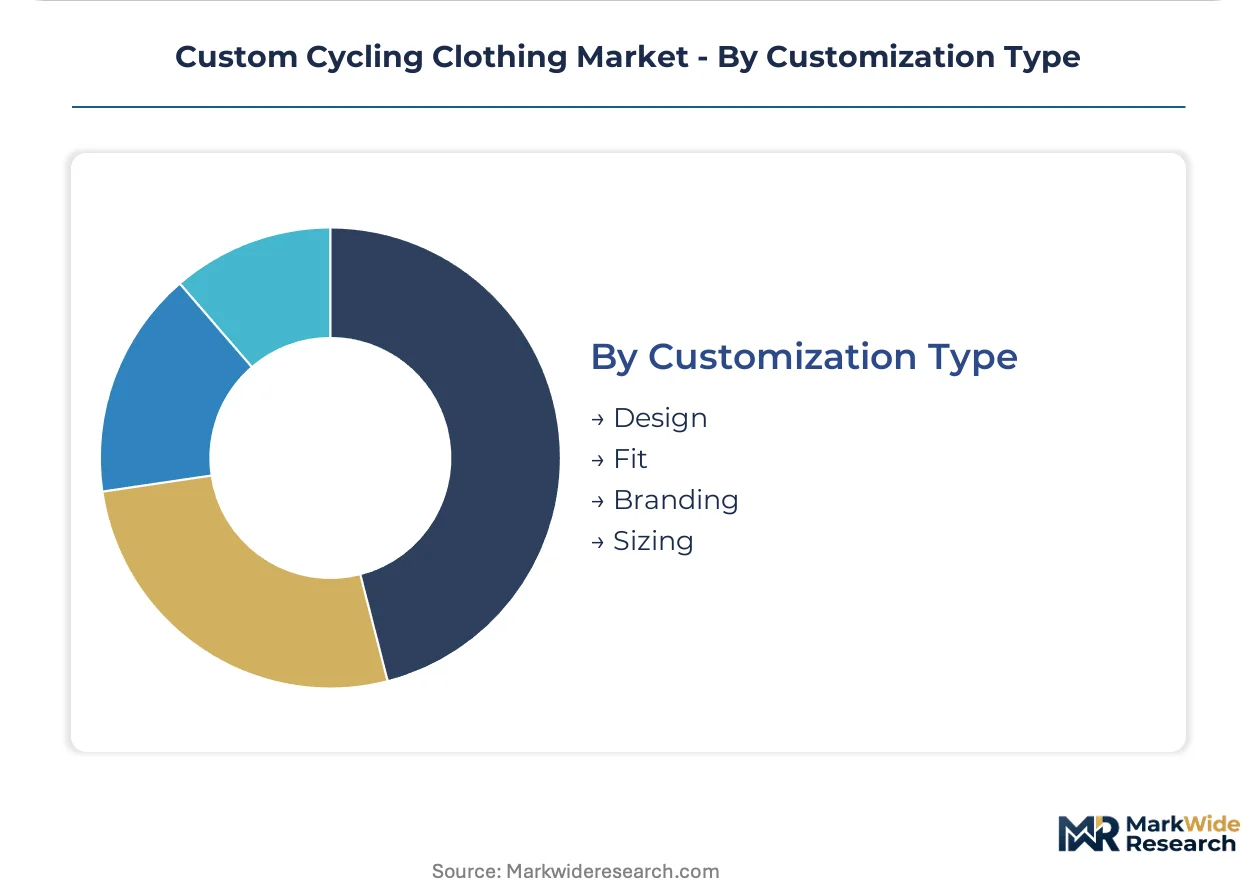
Customization Type:
Margin capture potential escalates with technical sophistication of customization delivery.
- Design:Sublimation artwork and colorway specification constitute baseline offerings with compressed differentiation. Portuguese quick-turn facilities compete on 48-hour digital proofing turnaround.
- Fit:Pattern grading and anatomical panel mapping require retained technical talent concentrated in northern Italian industrial districts.
- Branding:Sponsor logo integration and placement rules compliance add regulatory complexity for teams under UCI visibility mandates.
- Sizing:Extended size range development demands graded pattern libraries with associated inventory risk for small-batch producers.
Design commands the broadest deployment. Fit shows the steepest expansion trajectory as biometric scanning integration spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing custom cycling apparel production toward jurisdictions with manageable compliance costs, as REACH documentation burdens and carbon-accounting mandates reshape where European clubs source their kit.
Italy
WorldTour squad sponsorships and historic manufacturing clusters around Treviso and Milan sustain premium positioning for made-to-order kit. REACH Annex XVII enforcement through ECHA tightens chemical disclosure for dye houses serving amateur racing circuits. The Veneto region concentrates sublimation printing expertise that supplies both professional teams and boutique cycling clubs with rapid turnaround capabilities.
Belgium
Spring classics racing culture and dense amateur league structures generate consistent replacement-cycle demand for custom bibs and thermal layers. The EU Green Deal's extended producer responsibility frameworks pressure clubs to document supply chain emissions for federation procurement compliance. Flanders-based cut-and-sew workshops are upgrading ultrasonic welding equipment to capture bonded-seam construction orders from regional racing teams.
Portugal
Porto and Lisbon facilities are repositioning toward sub-50-unit minimum orders, capturing boutique European clubs abandoned by Asian volume producers. Domestic labor costs and EU regulatory alignment enable faster sample-to-production timelines than offshore alternatives. Portuguese dye houses are reformulating low-temperature sublimation processes to accommodate recycled polyester bases without color degradation.
United States
Corporate wellness program adoption by technology sector employers is subsidizing custom team kits as employee retention instruments, opening B2B channels distinct from traditional club sponsorship models. No federal equivalent to REACH exists, though California's Proposition 65 disclosure requirements affect textile finish formulations. Domestic dye-sublimation shops in Colorado and North Carolina are capturing amateur racing circuit demand through rapid digital proofing turnaround.
Germany
British Cycling federation-style procurement centralization is emerging among regional German cycling federations, consolidating vendor relationships for affiliated clubs. The CSRD disclosure requirements create tiered supplier preference for vendors with verified Scope 3 emissions data. Bavarian and North Rhine-Westphalian manufacturers are investing in in-house chemical testing to compress REACH documentation timelines that currently extend lead times by three to four weeks.
Custom Cycling Clothing Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue quick-turn, small-batch specialization for boutique club accounts. The vendor base stratifies across vertically integrated Asian manufacturers, Italian premium ateliers, and Portuguese quick-turn facilities. Three archetypes dominate: scale-driven sublimation houses, compliance-specialized European cut-and-sew operations, and design-intensive premium positioning specialists. Competitive moves concentrate on geographic capacity expansion and federation master agreement capture.
Among Asia-Pacific-based manufacturers, Champion System leverages factory networks to sustain rapid delivery timelines for volume accounts. DNA Cycling anchors the dye-sublimation specialist archetype through regional amateur racing circuit penetration. Italian heritage positioning is exemplified by Manifattura Valcismon, representing the premium-tier, WorldTour-supply concentration around historic manufacturing clusters. These three occupy distinct competitive vectors without direct functional overlap.
| Leading Market Players |
|---|
| Champion System |
| DNA Cycling |
| Mega Sports Apparel |
| Primal Wear |
| Podiumwear Custom Sports Apparel |
| Pactimo |
| Verge Sports |
| Jakroo Custom Apparel |
| Manifattura Valcismon |
| Others |
Supply Flow & Price Mechanics
EU Green Deal carbon accounting mandates are compelling European cycling clubs to demand documented supply chain emissions data, forcing manufacturers to requalify dye houses and extend lead times while absorbing compliance costs into contract pricing. This buyer-driven specification shift compresses margins for small-batch producers lacking in-house chemical testing infrastructure.
Pricing Analysis
Direct-to-club margins dominate revenue capture for custom kit producers, bypassing distributor markups that erode profitability in retail channels. Three-tier pricing structure across premium, standard, and economy levels separates WorldTour squad contracts with bonded-seam specifications from amateur club sublimation orders and entry-level corporate wellness programs. Pricing pressure stems from petrochemical input volatility that polyester and Lycra feedstock prices transmit from crude oil indices. Amateur racing circuits exhibit highest price sensitivity due to volunteer-led procurement committees with constrained annual budgets.
Supply Chain Analysis
Dual-sourcing requirements from British and German cycling federations are compelling clubs to qualify backup suppliers for critical kit components, extending vendor onboarding timelines. Manufacturing gravity centers on Italy, Portugal, and China, with Treviso-Milan clusters supplying premium cut-and-sew expertise while Porto-Lisbon facilities capture quick-turn sublimation demand. Raw material flows draw from Taiwanese polyester chip producers, Korean Lycra spinners, and German chemical finish suppliers. Single-source vulnerability concentrates in northern Italian dye houses with scarce color-matching technicians. Distribution runs through federation-coordinated master agreements and direct club procurement portals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where Portuguese manufacturers exploit EU regulatory alignment and lower labor costs to undercut Italian premium positioning while delivering faster turnaround than Asian volume producers.
For Market Incumbents: Deepen backward integration into recycled polyester fiber production to compress Scope 3 emissions documentation burdens and defend margin position against Portuguese quick-turn entrants. Champion System and Manifattura Valcismon should prioritize in-house chemical testing laboratories to eliminate third-party REACH certification delays that currently extend sample-to-production timelines. Capacity expansion in Porto-Lisbon corridors captures federation procurement centralization trends before competitors anchor exclusive supply agreements. For New Entrants and Emerging Players: Boutique cycling clubs in Belgium and France represent the most penetrable segment, abandoned by Asian volume producers unwilling to service sub-50-unit minimum orders. Corporate wellness programs at technology sector employers offer white-space expansion with B2B procurement cycles distinct from seasonal club refresh patterns. Go-to-market execution should prioritize 48-hour digital proofing turnaround and CSRD-ready emissions documentation to differentiate from established players with slower compliance workflows. For Investors and Strategic Acquirers: Asymmetric upside sits with Portuguese quick-turn facilities possessing ultrasonic welding capability and verified Scope 3 data infrastructure. Long-term viability in this market hinges on regulatory compliance moats rather than scale economies, favoring acquisition targets with in-house chemical testing and low-temperature sublimation expertise over pure-play dye houses. Watch for ECHA enforcement actions on perfluorinated compound restrictions as an inflection indicator that would accelerate consolidation toward compliant manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Low-Temperature Sublimation Process Investment | Portuguese dye houses capture recycled polyester demand without color degradation penalties under EU Green Deal mandates. |
| In-House Chemical Testing Laboratory Buildout | German and Italian manufacturers compress REACH documentation timelines that currently disadvantage smaller competitors. |
| Federation Master Agreement Capture | British Cycling and emerging German federation procurement centralization locks in multi-year revenue visibility. |
| Ultrasonic Welding Equipment Upgrade | Flanders-based workshops capture bonded-seam construction orders from regional racing teams specifying aerodynamic panel geometries. |
| Corporate Wellness Channel Development | Technology sector employers subsidize custom team kits as employee retention instruments outside traditional club sponsorship models. |
Methodological Framework
Direct dialogue with custom apparel procurement officers at cycling federations, technical directors at WorldTour squads, plant managers at Portuguese cut-and-sew facilities, and compliance leads at dye houses grounded qualitative insights. Secondary validation drew from ECHA REACH substance databases, EU Green Deal policy documents, British Cycling federation procurement disclosures, and customs records tracking polyester fiber trade flows. Bottom-up club membership estimates and top-down apparel spend benchmarks were triangulated to anchor market sizing.
Segment-level projections across product type, material composition, end-user category, and customization depth were generated through the analytical framework applied across the projection horizon. CAGRs were derived from regression analysis of historical sponsorship obligation cycles, amateur league expansion trajectories, and regulatory implementation timelines. Industry-specific inputs included dye-sublimation capacity utilization rates at Treviso industrial clusters and federation master agreement penetration rates in British and German markets.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA enforcement intensity on perfluorinated compound restrictions and crude oil price volatility transmitting through polyester feedstock costs. Deviation in EU Green Deal carbon accounting implementation timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Fanny Packs Market
Apparel & Footwear
Online Apparel Market
Apparel & Footwear
Children's Suits and Ensembles Market
Apparel & Footwear
Asia-Pacific Sports Apparel Market
Apparel & Footwear
Lingerie Market
Apparel & Footwear
New Smart Wardrobe Market
Apparel & Footwear
Football Jerseys Market
Apparel & Footwear
Men Shirts Market
Apparel & Footwear
Ice Hockey Apparel Market
Apparel & Footwear
Fast Fashion Market
Apparel & Footwear
Brazil Pet Clothing Market
Apparel & Footwear
Women's T-Shirts Market
Apparel & Footwear
Asia Pacific Hats Market
Apparel & Footwear
South Korea Denim Jeans Market
Apparel & Footwear
Maternity Intimate Wear Market
Apparel & Footwear
Sequins Apparels Market