
 Europe Dancewear Market | 2026-2036
Europe Dancewear Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Dancewear Market Insights
Modular outfit bundling is realigning how dance schools and academy buyers structure seasonal purchases. Freed of London leverages its heritage manufacturing base in the United Kingdom to sustain premium positioning in pointe shoe craftsmanship. Gaynor Minden differentiates through engineered polymer shank technology that extends product lifespan beyond traditional paste-construction alternatives.
Europe dancewear encompasses specialized performance apparel and footwear designed for ballet, contemporary, and theatrical dance disciplines, typically constructed from moisture-wicking cotton-spandex blends with reinforced seam architecture to withstand repetitive flexion and floor contact. The primary commercial purpose centers on enabling unrestricted biomechanical range while maintaining aesthetic uniformity across ensemble performances. Leotards and tights dominate volume flows due to their universal requirement across age groups and dance styles, while ballet shoes command concentrated margin pools given the technical precision and hand-finishing stages involved in their manufacture. Spandex-blend fabrics are displacing pure cotton in professional-tier products as choreographers demand greater compression recovery and silhouette retention through extended rehearsal cycles.
REACH regulations administered by ECHA restrict azo dyes and phthalate-based softeners in dancewear textiles, compelling suppliers to reformulate fabric treatments and validate compliance through third-party certification. The EU Green Deal's textile sector roadmap is pressuring manufacturers to document recycled content ratios and end-of-life recyclability, reshaping sourcing decisions for nylon and polyester inputs. Stakeholders must monitor how Ecodesign for Sustainable Products Regulation implementation timelines affect fiber certification costs and supplier qualification thresholds.
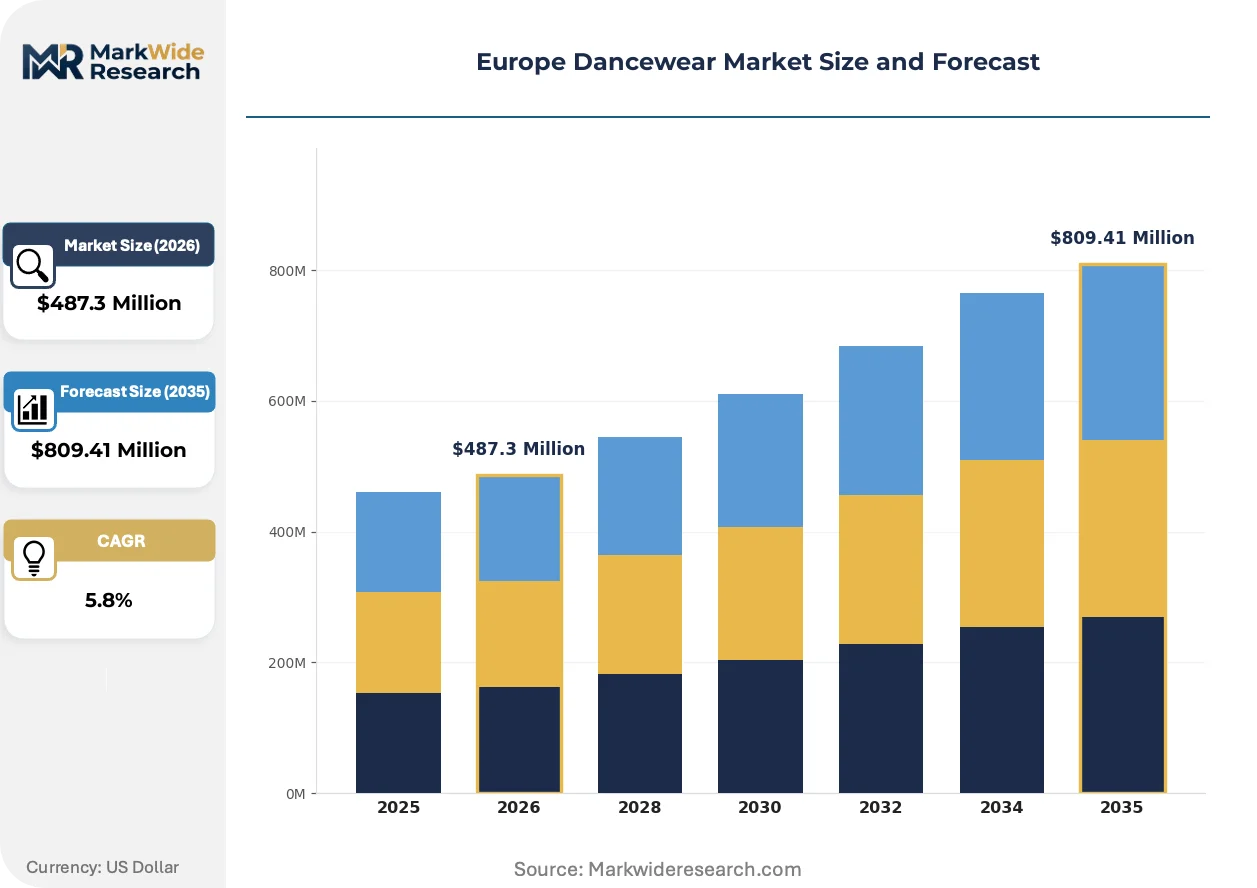
Market Dynamics
REACH compliance administered by ECHA is compressing supplier margins while elevating material certification costs across European dancewear manufacturing clusters.
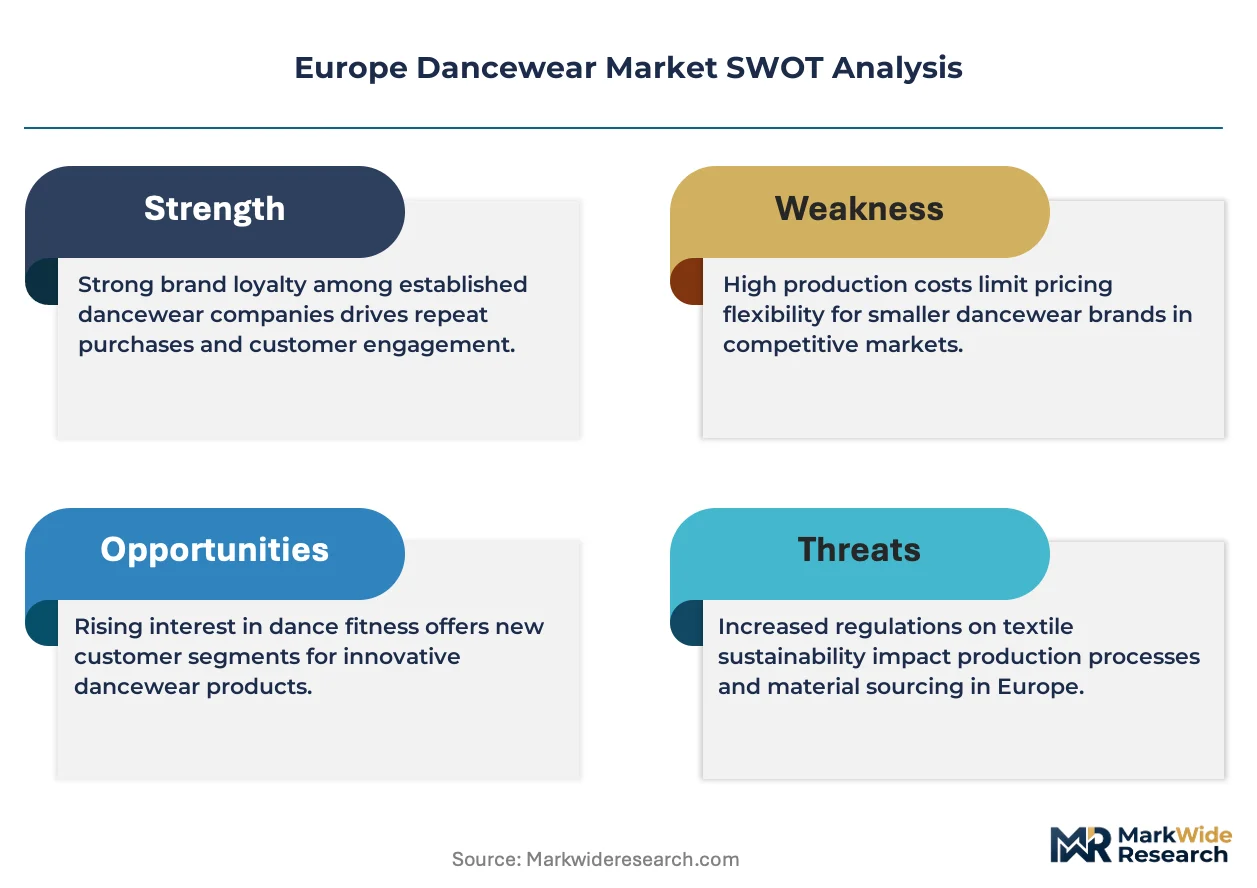
Growth Catalysts
- EU Green Deal textile roadmap:Mandates for recycled nylon documentation are pulling premium-tier suppliers toward certified fiber sourcing. German ballet academies now require sustainability disclosures in bulk procurement tenders.
- London theatre district expansion:West End production budgets for costume replacement cycles are extending order volumes for moisture-wicking performance tights. Associated dance education clusters in Greater London generate concentrated demand for youth leotard lines.
- Engineered polymer shank technology:Extended-lifespan pointe shoe construction is reducing replacement frequency for professional companies while commanding price premiums over traditional paste alternatives.
Market Restraints
- Spandex input cost volatility:Petrochemical derivative pricing fluctuations compress margin stability for stretch-fabric manufacturers dependent on synthetic elastomer supplies.
- Hand-finishing labor concentration:Ballet shoe production remains anchored to craft-specialist regions in England and France, limiting scale responsiveness to demand surges.
- REACH azo dye restrictions:Reformulation requirements for colorfastness compliance extend product development timelines and elevate third-party testing expenditures.
Strategic Opportunities
- Ecodesign for Sustainable Products Regulation:Early compliance with digital product passport requirements positions suppliers for preferred vendor status in French and German institutional procurement.
- Modular outfit bundling:Seasonal package structures for dance schools consolidate accessory, footwear, and apparel purchases into single-source contracts.
- Biomechanical customization:3D foot scanning integration with polymer injection molding enables made-to-measure pointe shoe production at mid-tier price accessibility.
Industry Challenges
- Master craftsperson scarcity:Pointe shoe hand-finishing expertise concentrates among aging workforces in traditional manufacturing regions, constraining quality-assured output expansion.
- Multi-standard certification complexity:Simultaneous OEKO-TEX, GOTS, and EU Ecolabel documentation creates administrative burden for cross-border distributors serving Netherlands and Belgium markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Dancewear Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $809.41 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ballet Shoes, Leotards, Tights, Dance Pants Gender: Women, Men, Unisex, Children Fabric Type: Cotton, Spandex, Nylon, Polyester Age Group: Adult, Teenager, Child, Infant |
| Companies Covered | Grishko, Freed of London, Move Dance, Mondor, Gaynor Minden, Dance Direct, Capezio, Dance World Europe, Bloch, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Dancewear Market Trends and Innovations
Digital measurement tools and sustainable fiber alternatives are restructuring how European dancewear manufacturers align production with institutional buyer specifications.
Biomechanical sensor integration is decentralizing fit assessment away from centralized retail flagships. Dance academies in Birmingham and Manchester are deploying pressure-mapping insoles to document pointe shoe wear patterns. This data is compressing replacement cycle uncertainty and enabling predictive inventory management for school administrators.
REACH restrictions on phthalate-based softeners are mandating silicone-alternative fabric treatments across EU-manufactured performance apparel. ECHA enforcement audits in 2024 elevated documentation requirements for textile chemical compliance. Italian and Spanish suppliers are accelerating water-based coating adoption to maintain CE marking eligibility for cross-border sales.
Direct-to-academy digital platforms are displacing traditional dance retail intermediaries in the United Kingdom. Consolidated purchasing cooperatives formed by independent dance schools now negotiate volume discounts previously reserved for national chains. This channel compression is most visible in Scotland and Northern England, where rural studio density favors centralized order aggregation over individual storefront relationships.
Europe Dancewear Market Segmentation
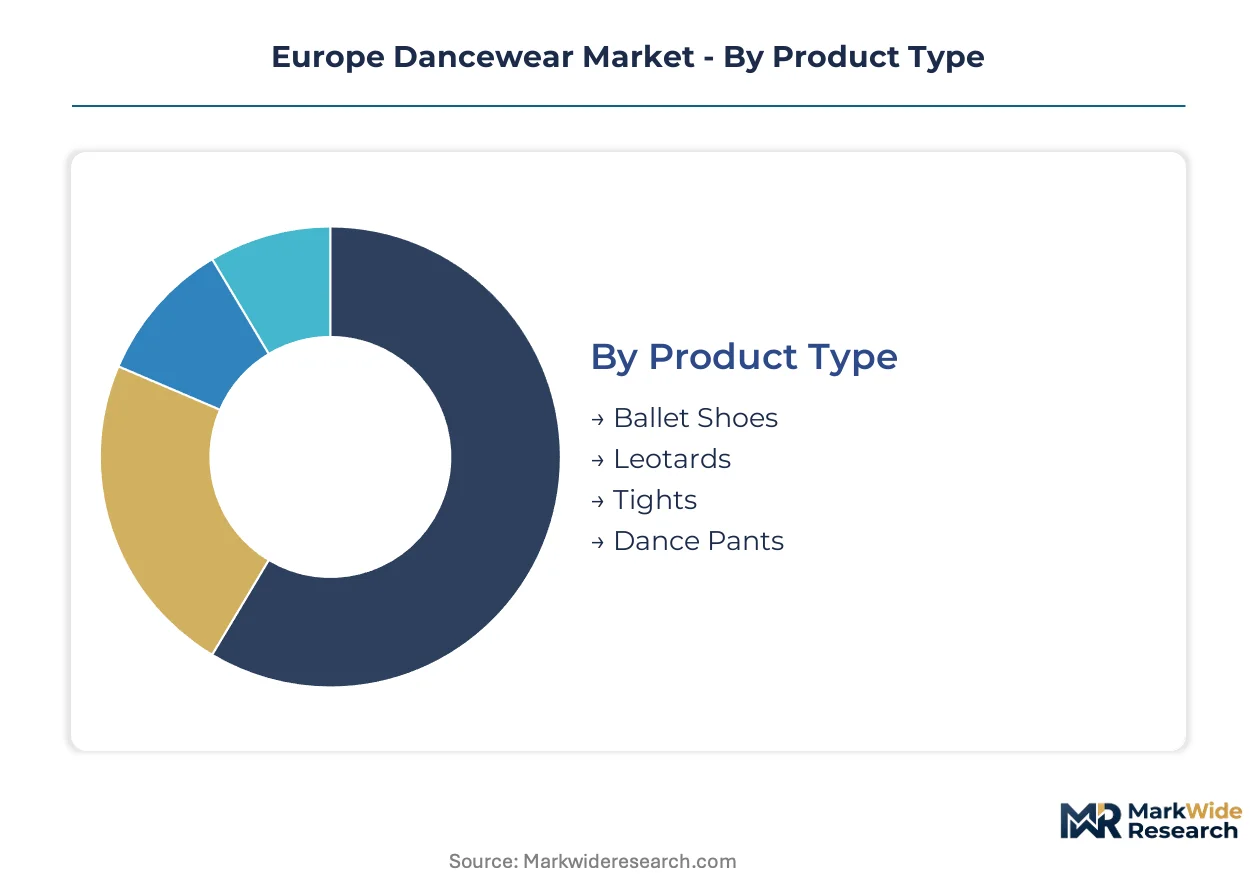
Dancewear purchasing in Europe follows distinct decision hierarchies across institutional buyers, professional companies, and individual consumers. Product specifications, demographic targeting, material compliance, and age-appropriate sizing each create separate commercial pathways with margin implications for suppliers.
Product Type:
Purchase volume correlates directly with replacement frequency and technical performance requirements across European dance institutions.
- Ballet Shoes:Hand-finished pointe shoes and demi-pointe variants utilize paste-construction or engineered polymer shanks to withstand repetitive flexion. German and French ballet companies concentrate procurement budgets here due to professional-grade durability standards. REACH-compliant adhesives and sustainable material sourcing now feature prominently in institutional tenders.
- Leotards:Moisture-wicking cotton-spandex blends with reinforced seam architecture dominate professional-tier products. London theatre district costume departments and associated dance education clusters drive concentrated demand for aesthetic uniformity across ensemble performances. Spandex-blend displacement of pure cotton accelerates as choreographers prioritize compression recovery through extended rehearsal cycles.
- Tights:Performance-grade hosiery constructed from nylon-spandex weaves with run-resistant knitting.
- Dance Pants:Loose-fitting rehearsal and warm-up apparel utilizing breathable natural-synthetic blends.
Ballet shoes lead on scale; leotards lead on momentum.
Gender:
Fit specifications and aesthetic conventions diverge sharply across gendered product lines, with unisex categories gaining traction in contemporary dance education settings.
- Women:Pointe shoe engineering and specialized leotard construction address biomechanical range requirements unique to female dancers. United Kingdom dance academies generate substantial volume through youth and adult female enrollment clusters.
- Men:Reinforced footwear and tailored warm-up apparel accommodate higher impact loading and distinct silhouette preferences.
- Unisex:Contemporary and theatrical dance disciplines increasingly specify gender-neutral cuts and sizing.
- Children:Rapid growth-phase sizing demands cost-efficient construction with durability trade-offs.
Women's lines anchor revenue concentration; children's categories expand most quickly through recreational enrollment growth.
Fabric Type:
Material selection directly determines REACH compliance pathways and EU Green Deal alignment for European manufacturers.
- Cotton:Natural fiber base with moisture absorption properties, now blended predominantly rather than used in pure form.
- Spandex:Petrochemical-derived elastomer providing compression recovery and silhouette retention. Italian and Spanish suppliers face input cost volatility while reformulating away from phthalate-based softeners under ECHA enforcement.
- Nylon:Recycled-content documentation requirements from the EU Green Deal textile roadmap pull premium-tier suppliers toward certified fiber sourcing.
- Polyester:Durable synthetic with end-of-life recyclability pressures reshaping sourcing decisions.
Spandex commands margin concentration; recycled nylon climbs the fastest on regulatory pull-through.
Age Group:
Growth-phase physiology and institutional versus recreational participation patterns segment demand across lifecycle stages.
- Adult:Professional and amateur dancers with stable sizing requirements and performance-tier purchasing power. Birmingham and Manchester dance academies deploy biomechanical sensor integration for predictive inventory management among adult cohorts.
- Teenager:Transitional sizing with accelerated replacement cycles during growth spurts.
- Child:High-volume, price-sensitive segment concentrated in recreational dance school enrollment across Greater London education clusters.
- Infant:Specialized early-movement apparel with minimal technical specification requirements.
Adult segments sustain premium pricing; child categories gain share fastest through dance school expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ballet shoe craftsmanship originated in nineteenth-century France and England, establishing manufacturing traditions that persist in specialized workshops across the Channel region. Contemporary demand clusters reflect this heritage, with procurement budgets concentrating in metropolitan theatre districts and affiliated academy networks.
United Kingdom
West End production houses sustain replacement-cycle orders for performance-grade tights and leotards, while Greater London education clusters drive youth segment volume. REACH enforcement through ECHA elevates documentation burdens for textile chemical compliance. Birmingham and Manchester academies deploy pressure-mapping technology to optimize pointe shoe inventory forecasting.
Germany
State ballet companies in Berlin, Munich, and Hamburg command premium procurement budgets for hand-finished footwear with engineered polymer shank construction. The EU Green Deal textile roadmap mandates recycled nylon disclosure in institutional tenders issued by German academies. Bavarian manufacturing clusters specialize in precision seam reinforcement for professional-tier apparel.
France
Paris Opéra Ballet and regional companies anchor demand for aesthetic uniformity in ensemble costume procurement. ANSM oversees cosmetic-grade textile treatments alongside ECHA REACH protocols for dancewear imports. Lyon and Marseille host specialized dye houses reformulating azo-free colorfast solutions for export-compliant production.
Italy
Contemporary dance theatres in Milan and Rome specify gender-neutral cuts for unisex rehearsal lines. ECHA enforcement audits in 2024 accelerated water-based coating adoption among Lombardy fabric finishers. Florence maintains craft-specialist workshops for leather sole hand-stitching in demi-pointe construction.
Spain
Barcelona's contemporary dance academies drive demand for moisture-wicking cotton-spandex blends with extended compression recovery. CE marking requirements govern cross-border sales to French and Portuguese institutional buyers. Valencia textile mills reformulate spandex treatments to eliminate phthalate-based softeners under ECHA restriction.
Europe Dancewear Market Competitive Landscape
Premium-margin players sit above commodity-margin players across material certification and hand-finishing intensity dimensions. The vendor base stratifies between heritage craft houses with generational expertise and scale-driven manufacturers optimizing synthetic fiber throughput. Three archetypes dominate: century-old ateliers preserving paste-construction methods, technology-integrated specialists deploying polymer engineering, and direct-to-academy platforms compressing distribution layers. Consolidation pressure operates through vertical acquisition of dye houses and strategic partnerships with biomechanical sensor providers.
Within the heritage-manufacturing tier, Freed of London and Grishko exemplify craft-specialist positioning anchored to traditional production geographies. Gaynor Minden occupies a distinct archetype as a technology-integrated challenger emphasizing engineered materials over conventional construction. These three entities collectively illustrate how competitive differentiation fragments across preservationist versus innovationist strategic vectors.
| Leading Market Players |
|---|
| Grishko |
| Freed of London |
| Move Dance |
| Mondor |
| Gaynor Minden |
| Dance Direct |
| Capezio |
| Dance World Europe |
| Bloch |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap craft houses concentrated in England and France anchor supply discipline through generational hand-finishing expertise, translating scarcity premiums into pricing power that resists commoditization pressure from synthetic-fiber competitors. Their ownership structure insulates margin maintenance against short-term cost volatility, while institutional buyers absorb REACH compliance premiums as non-negotiable qualification thresholds.
Pricing Analysis
Three-tier pricing structure across heritage craft, technology-integrated, and economy-import levels segments the market by certification grade and construction method. Price differentiation hinges on OEKO-TEX certification tier and hand-finishing intensity, with polymer-shank engineered products commanding premiums over paste-construction alternatives. Cost compression in economy tiers intensifies as direct-to-academy platforms consolidate volume purchasing. Children's recreational segments exhibit highest price sensitivity; German state ballet companies demonstrate lowest sensitivity due to performance-tier durability requirements.
Supply Chain Analysis
ECHA REACH qualification gates upstream fiber sourcing, compelling Italian and Spanish mills to reformulate treatments before CE marking eligibility. Raw material flows draw from petrochemical-derived spandex suppliers, recycled nylon certification programs in Germany, and cotton-blend weavers in Portugal. Single-source vulnerability concentrates in hand-finishing craftsperson pools across traditional English and French manufacturing regions. Distribution runs through direct-to-academy digital platforms displacing traditional retail intermediaries, particularly visible in Scotland and Northern England.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in European dancewear rests on two structural drivers: REACH compliance premiums becoming institutional table stakes, and biomechanical customization technology opening premium-tier accessibility. These forces compress commodity-tier returns while elevating certified-supplier profitability.
For Market Incumbents: Acquire dye house and finishing facility assets to secure backward integration into REACH-compliant colorfastness capabilities. Consolidate craft-specialist workshops in England and France to defend against polymer-engineering substitutes eroding paste-construction market share. Channel control through exclusive academy partnerships protects volume commitments against direct-to-platform disintermediation. For New Entrants and Emerging Players: EU Green Deal textile roadmap in Germany opens a window for recycled-content certification specialists to penetrate institutional procurement tenders. White-space targets include modular outfit bundling contracts for independent dance school cooperatives in Greater London education clusters, and biomechanical sensor integration services for predictive inventory management. Go-to-market positioning as sustainability-disclosure compliance partners accelerates vendor qualification. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier synthetic-fiber manufacturers lacking heritage brand equity but possessing scalable production infrastructure. Long-term viability favors entities with dual capability in craft-preservation and polymer-engineering technology portfolios. The signal to watch is Ecodesign for Sustainable Products Regulation implementation pace, which will accelerate consolidation pressure on non-compliant suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dye Houses | REACH-compliant colorfastness capabilities secure CE marking eligibility for cross-border sales. |
| Biomechanical Sensor Platform Launch | Pressure-mapping integration with pointe shoe production compresses replacement cycle uncertainty for academies. |
| Recycled Nylon Certification Program | EU Green Deal documentation requirements pull German institutional procurement toward verified fiber sourcing. |
| Direct-to-Academy Digital Platform | Consolidated purchasing cooperatives in Scotland and Northern England displace traditional retail intermediaries. |
| Craft Workshop Consolidation | Generational hand-finishing expertise concentration in England and France limits quality-assured output expansion. |
Research Methodology
Coverage spans the United Kingdom, Germany, France, Italy, and Spain, with primary inputs from each regional cluster combining executive interviews with ballet company procurement directors, dance academy administrators, textile mill technical managers, and ECHA compliance officers. Secondary validation draws from REACH enforcement audit disclosures, EU Green Deal textile sector roadmaps, OEKO-TEX certification databases, and customs trade records for synthetic fiber imports. Bottom-up demand modeling from institutional purchase order analysis triangulates against top-down market sizing from production capacity assessments.
Rate-of-change decomposition across the analysis window segments volume and value trajectories by product type, fabric certification tier, age group participation patterns, and regional regulatory adoption intensity. CAGRs derive from replacement frequency modeling for performance footwear, enrollment growth projections for youth segments, and compliance cost pass-through elasticity to institutional buyers. Industry-specific forecast inputs include West End production budget cycles, German state ballet company procurement calendars, and Ecodesign for Sustainable Products Regulation implementation timelines.
Revisions become necessary when ECHA enforcement intensity shifts, petrochemical derivative pricing volatility exceeds historical bands, or craft-specialist workforce attrition accelerates beyond replacement training capacity. Forecasts reflect assumptions about REACH compliance cost stability and recycled nylon certification program scalability. A model refresh is warranted upon material change in EU Green Deal textile sector enforcement priorities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sportswear
North America Dancewear Market
Sportswear
Athleisure Wear Market
Sportswear
Billiards and Snooker Equipment Market
Sportswear
Global Women Active Wear Market
Sportswear
Bicycle Apparels Market
Sportswear
Cricket Bowling Machine Market
Sportswear
Skateboard Grip Tapes Market
Sportswear
Activewear Market
Sportswear
Workout Clothes Market
Sportswear
Sports Socks for Children Market
Sportswear
Cycling Apparel Market
Sportswear
Athleisure Market
Sportswear
Casual Sportswear Market
Sportswear
Cycling Wear Market