
 Athleisure Wear Market | 2026-2036
Athleisure Wear Market Size, Share, and Industry Trends Forecast 2026-2036
Athleisure Wear Market Analytics
Apparel engineering talent is collapsing across traditional cut-and-sew manufacturing hubs, forcing brands to automate pattern-making and digital sampling. Nike Inc. leverages AI-driven demand forecasting to reduce inventory waste across its direct-to-consumer channels. Lululemon Athletica Inc. sustains premium positioning through vertical control over fabric innovation and in-house R&D labs. Adidas AG anchors European supply resilience with localized micro-factories and recycled material partnerships.
Athleisure wear denotes garments engineered with performance textiles—typically blends incorporating four-way stretch spandex, moisture-wicking polyester, or compression-grade nylon—designed to transition between athletic activity and casual social settings without aesthetic or functional compromise. Leggings dominate unit volume due to universal wearability across fitness and casual contexts, while sports bras command disproportionate margin pools through technical differentiation and repeat purchase frequency. The customer type dimension reveals fitness enthusiasts as the highest-engagement segment, though casual wearers represent the largest addressable expansion base through everyday wardrobe integration.
The US Federal Trade Commission enforces Green Guides standards that constrain unsubstantiated sustainability claims, while the EU REACH regulation restricts certain chemical finishes and dye compounds in imported textiles. California's SB 657 disclosure requirements and the EU Green Deal's circular textile targets are reshaping compliance costs and material sourcing protocols for multinational brands. Stakeholders must monitor how divergent chemical safety regimes between North America and Europe fragment product line architectures and complicate unified global assortment planning.
Market Dynamics
The athleisure wear sector is compressing around sustainability mandates and automation imperatives as legacy cut-and-sew labor pools evaporate across Asia-Pacific manufacturing corridors. Brands now face simultaneous pressure to decarbonize material flows while digitizing production workflows.
Growth Catalysts
- EU Green Deal compliance:REACH regulations and circular textile targets are forcing material substitutions toward recycled polyester and bio-based elastane, creating premium positioning for early adopters.
- Corporate wellness expansion:White-collar employers across the United States are subsidizing fitness apparel as employee benefit categories, embedding athleisure into professional wardrobe norms.
- Four-way stretch spandex blends:Technical fabric innovation is extending garment lifecycle and wash durability, driving repeat purchase compression and customer lifetime value expansion.
Market Restraints
- Petrochemical input volatility:Polyester and spandex feedstock costs fluctuate with crude oil derivatives, compressing margin predictability for mid-tier brands without captive polymer supply.
- Taiwanese and Vietnamese supply concentration:Technical knit manufacturing clusters in East Asia create single-point vulnerability for moisture-wicking fabric production during trade disruption or energy rationing.
- Chemical finish restrictions:EU REACH Annex XVII limitations on perfluorinated compounds constrain water-repellency performance in outdoor-crossover athleisure lines.
Strategic Opportunities
- India domestic market penetration:Tier-2 and Tier-3 Indian cities exhibit nascent athleisure adoption with rising disposable income and fitness culture expansion.
- AI-driven made-to-measure:Body-scanning and algorithmic pattern generation are converging to enable mass-customized leggings and sports bras at near-mass-production economics.
- California SB 657 disclosure alignment:Supply chain transparency mandates create first-mover advantage for brands with verified ethical sourcing documentation.
Industry Challenges
- Digital pattern-making talent scarcity:Apparel engineering programs are not producing sufficient 3D sampling and CLO3D software specialists to meet brand automation timelines.
- Micro-factory capex intensity:Nearshoring production to US or European micro-factories requires substantial upfront investment in automated cutting and robotic sewing cells.
- Cross-regional certification divergence:OEKO-TEX Standard 100, bluesign, and GOTS requirements vary by geography, forcing redundant testing and SKU fragmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Athleisure Wear Market |
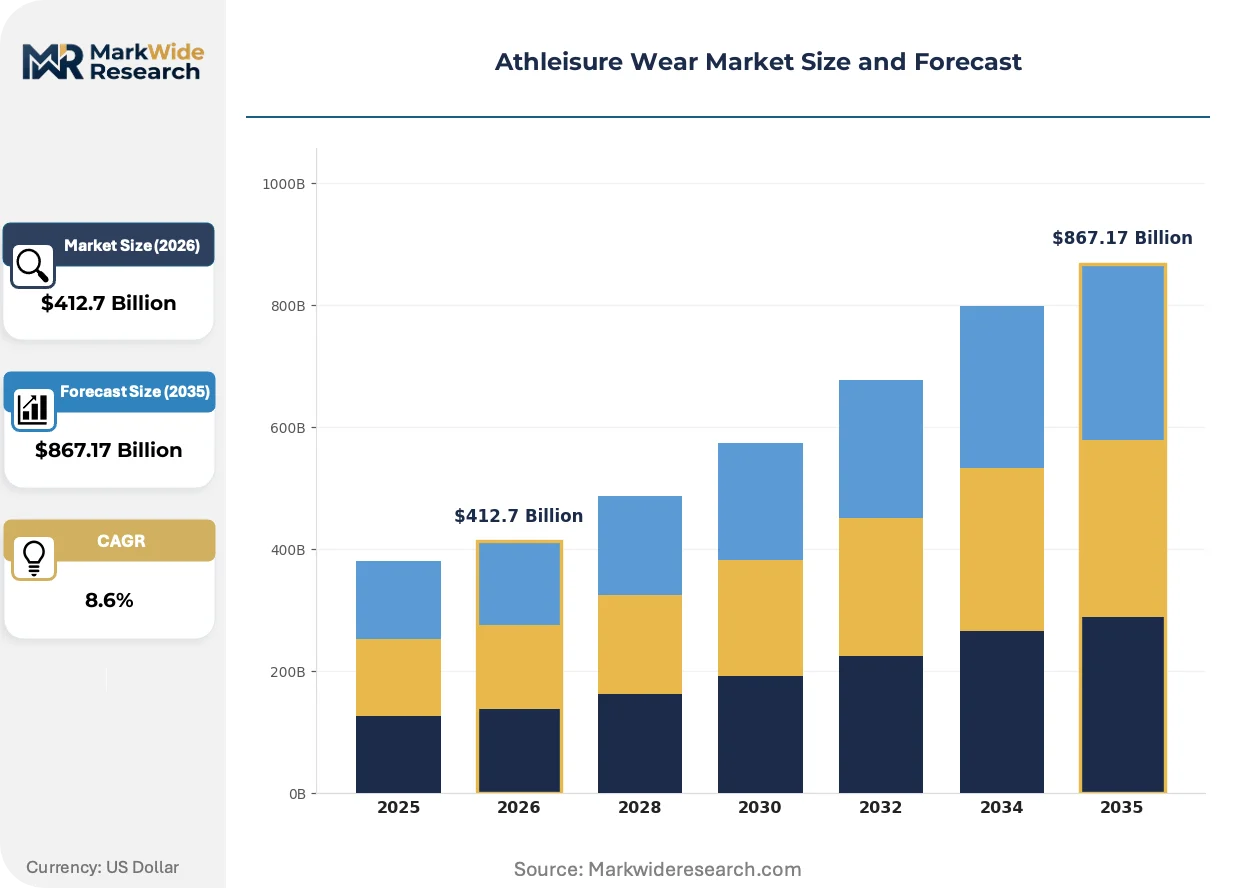
| Market Size in 2026 | $412.7 Billion |
| Market Size in 2035 | $867.17 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Leggings, Sports Bras, Hoodies, T-Shirts Customer Type: Fitness Enthusiasts, Casual Wearers, Athletes, Trendsetters Material: Polyester, Cotton, Spandex, Nylon Distribution Channel: Online Retail, Specialty Stores, Department Stores, Fitness Centers |
| Companies Covered | Nike Inc., Lululemon Athletica Inc., Adidas AG, Under Armour, Inc., PUMA SE, Vuori, Alo, LLC, Gymshark, Hanesbrands Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Athleisure Wear Market Evolving Landscape
Active compression and recovery garments are integrating biometric sensing layers that transform passive apparel into health-monitoring interfaces. This convergence of textile engineering and wearable electronics is redefining product value propositions.
Seamless knitting technology is miniaturizing garment construction by eliminating cut-and-sew assembly entirely. Fitness enthusiasts and professional athletes are adopting seamless compression leggings and sports bras at accelerating velocity. This compression of manufacturing steps is collapsing lead times from weeks to days while reducing material waste.
The EU Green Deal's circular textile targets are mandating recycled content minimums and extended producer responsibility schemes. Brands must now finance end-of-life garment collection and chemical recycling infrastructure. Premium European labels are responding by vertically integrating into polyester chemical recycling partnerships.
Direct-to-consumer subscription models are displacing traditional wholesale replenishment cycles for core wardrobe staples. Younger demographics in coastal US metropolitan clusters are prioritizing curated monthly deliveries over seasonal retail purchasing. This behavioral pivot concentrates customer data ownership with brands while compressing inventory risk.
Athleisure Wear Market Segmentation
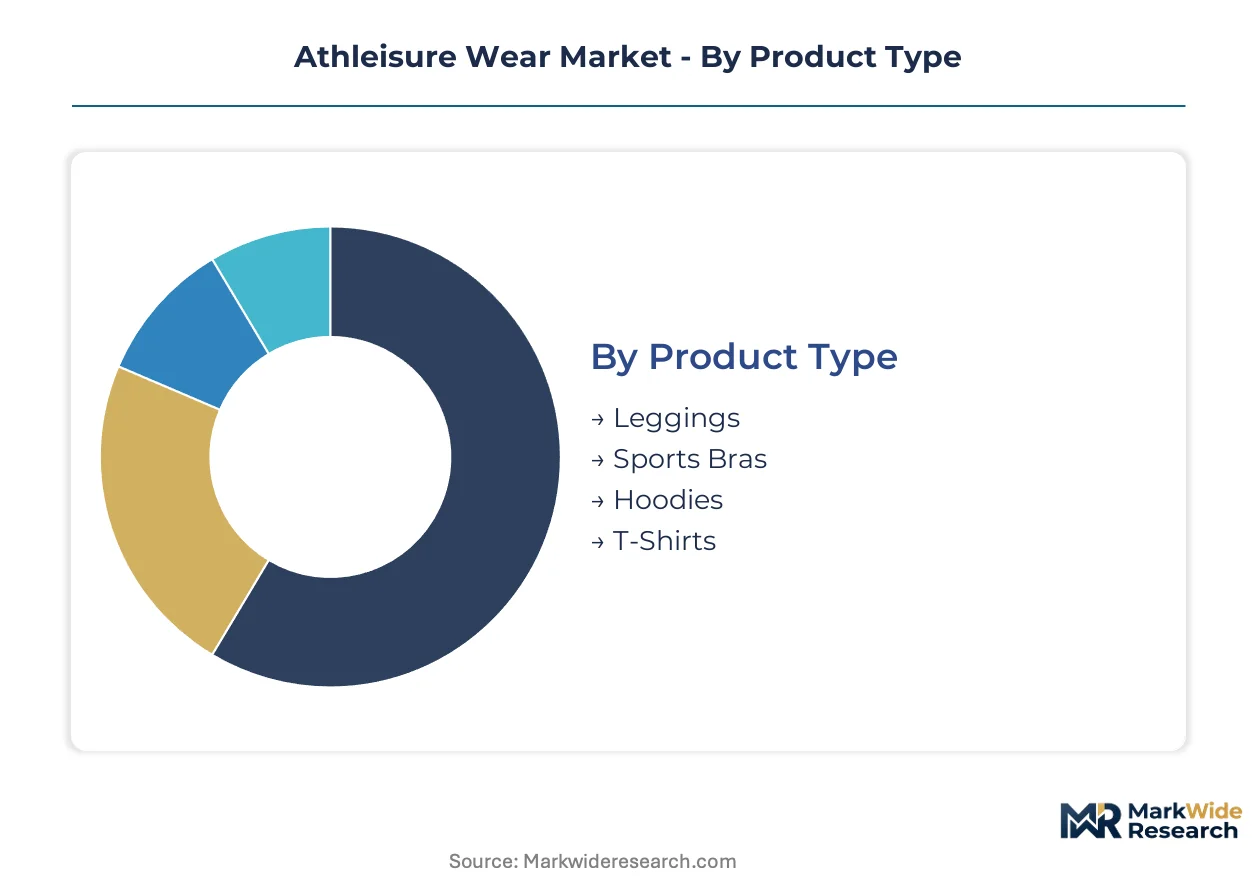
Athleisure brands calibrate assortment depth and margin architecture around four intersecting dimensions. Product type determines technical specification requirements, while customer type shapes channel allocation and pricing tiers.
Product Type:
Channel-mix patterns vary sharply across garment categories, with leggings and sports bras dominating direct-to-consumer velocity while hoodies and T-shirts sustain wholesale partnerships.
- Leggings:Engineered with four-way stretch spandex and moisture-wicking polyester blends for compression and recovery support. Demand concentrates in United States coastal metropolitan clusters where fitness-to-casual wardrobe transitions are routine. The EU Green Deal's recycled content mandates are elevating input costs for virgin polyester-dependent producers.
- Sports Bras:Technical differentiation centers on impact-gradation engineering and seam-free knitting construction. Repeat purchase frequency exceeds other categories due to elastic degradation from wash cycles. California SB 657 disclosure requirements create compliance premiums for brands with verified ethical sourcing.
- Hoodies:Cotton-polyester fleece blends dominate, with brushed interior surfaces for thermal retention. Branded co-ventures with corporate wellness programs are expanding B2B procurement volumes.
- T-Shirts:Basic moisture-wicking polyester or cotton-modal blends serve as entry-price acquisition tools. Mass-market penetration relies on seasonal color rotation and influencer collaboration drops.
By volume, leggings lead. By growth pace, sports bras are climbing the fastest.
Customer Type:
Margin concentration tracks engagement intensity, with fitness enthusiasts accepting premium pricing for technical performance while casual wearers demand value-engineered basics.
- Fitness Enthusiasts:Highest-engagement segment with demonstrated willingness to pay for biometric-integrated garments and recovery-compression engineering. Purchase frequency correlates with training volume and studio membership retention.
- Casual Wearers:Largest addressable expansion base through everyday wardrobe integration. Preference for versatile neutral palettes and machine-wash durability over technical specifications.
- Athletes:Professional and semi-professional competitors requiring competition-grade compression and thermoregulation. Procurement often flows through team sponsorship agreements and federation partnerships.
- Trendsetters:Early adopters of limited-edition designer collaborations and experimental fabrications. Social media visibility drives purchase decisions over functional attributes.
Fitness enthusiasts generate the highest per-customer lifetime value. Casual wearers are expanding most quickly as remote work normalizes comfort-first dress codes.
Material:
Input cost volatility and regulatory compliance burdens are fragmenting sourcing strategies across petrochemical and bio-based feedstocks.
- Polyester:Dominant fiber for moisture management and dimensional stability. Recycled PET supply chains are consolidating around European chemical recycling partnerships to satisfy EU circular textile targets.
- Spandex:Bio-based elastane formulations are emerging as REACH-compliant alternatives to petroleum-derived polyurethane. Taiwanese supply concentration creates vulnerability during energy rationing events.
- Nylon:Compression-grade variants serve medical-athletic crossover applications. PA6 and PA66 price spreads track caprolactam and adipic acid derivative costs.
- Cotton:Natural fiber demand persists in casual crossover segments despite water-intensity criticism. Organic certification premiums align with California disclosure mandates.
Polyester holds volume leadership. Bio-based spandex is gaining share fastest as brands decarbonize material portfolios.
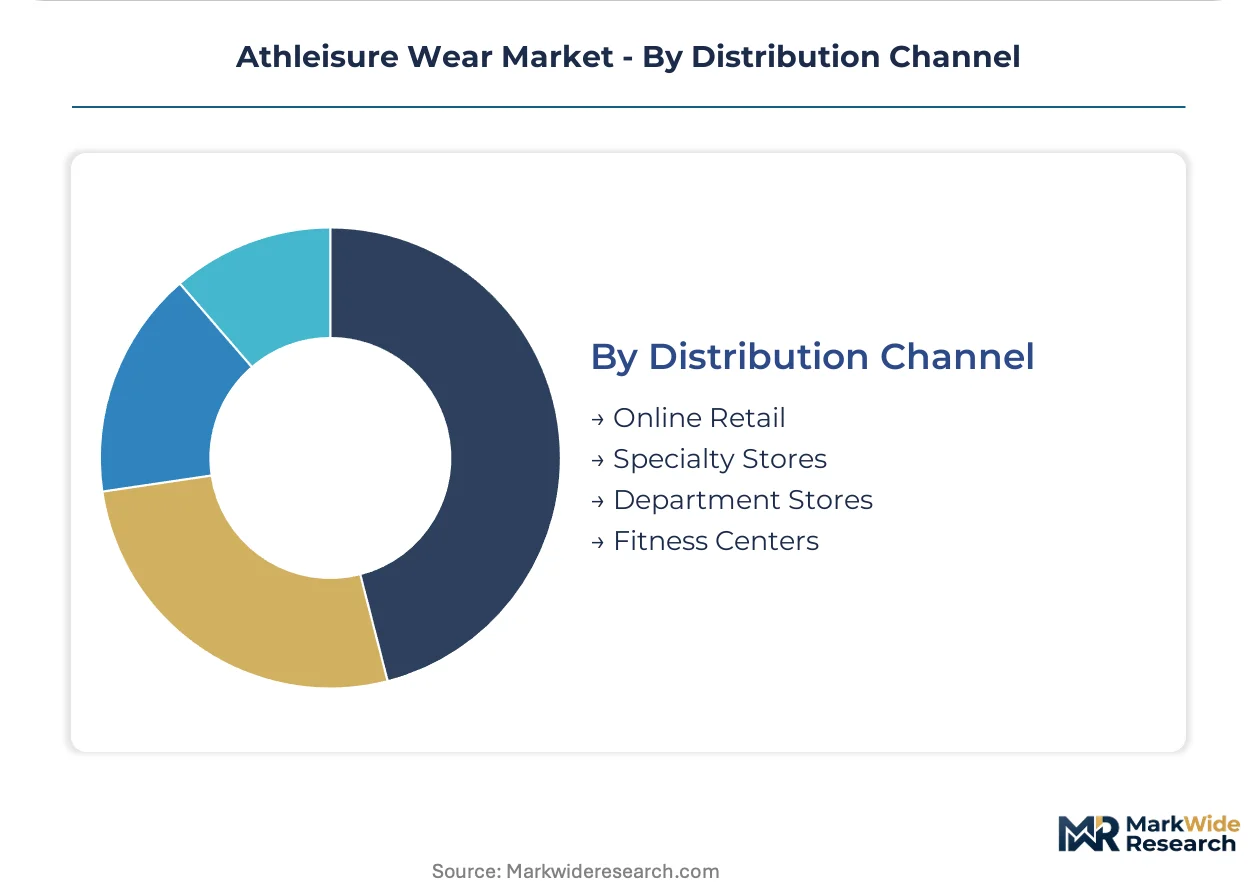
Distribution Channel:
Inventory risk allocation and customer data ownership are shifting power toward direct-to-consumer platforms and away from wholesale intermediaries.
- Online Retail:Subscription replenishment models and AI-driven size recommendation engines are compressing return rates. First-party data capture enables predictive demand forecasting.
- Specialty Stores:Curated experiential retail with in-store body scanning and fabric education. Community event programming drives brand loyalty in fitness corridor locations.
- Department Stores:Declining foot traffic is constraining square footage allocations. Athleisure brands are negotiating shop-in-shop concessions with dedicated staffing.
- Fitness Centers:Vertical integration through studio-owned apparel lines and exclusive co-branded collections. Proximity to workout context drives impulse purchase conversion.
Online retail leads by transaction volume. Fitness centers are expanding most quickly as boutique studios build captive merchandise ecosystems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in United States coastal metropolitan clusters while manufacturing cost advantages anchor in Vietnamese and Taiwanese technical knit corridors. This asymmetry shapes regional strategies across the forecast window.
United States
Fitness-to-casual wardrobe transitions drive demand in New York and Los Angeles metropolitan areas. The FTC enforces Green Guides standards that constrain unsubstantiated sustainability claims. Corporate wellness programs in Sun Belt fitness corridors subsidize employee athleisure procurement.
Germany
REACH regulations and EU Green Deal circular textile targets accelerate recycled polyester adoption. The ECHA restricts perfluorinated compounds in water-repellency finishes. Localized micro-factories in Bavaria and North Rhine-Westphalia shorten lead times for European distribution.
China
Domestic fitness culture expansion and rising disposable income propel tier-2 city adoption. The MIIT and dual carbon goals pressure manufacturers toward decarbonized material flows. Yangtze River Delta technical knit clusters face energy rationing vulnerability during peak demand periods.
India
Tier-2 and Tier-3 cities exhibit nascent athleisure adoption with fitness infrastructure expansion. BIS standards and PLI scheme incentives support domestic manufacturing scale-up. Maharashtra and Karnataka textile hubs attract polyester recycling investment for export compliance.
Japan
Aging demographics drive recovery-compression garment demand for wellness applications. METI guidelines shape sustainable textile certification requirements. Kanto and Kansai metropolitan areas concentrate premium direct-to-consumer channel development.
Athleisure Wear Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the athleisure wear sector. Vertically integrated specialists with captive fabric R&D command premium positioning while scale-driven manufacturers compete on unit economics. The market structure consolidates around three archetypes: innovation-led premium brands, fast-fashion volume players, and direct-to-consumer digital natives. Dominant competitive moves include strategic partnerships with recycled material suppliers and geographic expansion through localized micro-factory networks.
Among North American premium specialists, Nike Inc. and Lululemon Athletica Inc. exemplify technology-forward positioning through vertical control over performance textile development. Adidas AG anchors European supply resilience archetypes with regionalized production strategies. These three entities represent distinct competitive vectors: innovation velocity, premium community cultivation, and operational agility respectively.
| Leading Market Players |
|---|
| Nike Inc. |
| Lululemon Athletica Inc. |
| Adidas AG |
| Under Armour, Inc. |
| PUMA SE |
| Vuori |
| Alo, LLC |
| Gymshark |
| Hanesbrands Inc. |
| Others |
Value Network & Pricing Analysis
Capacity utilization rates above 85% in Taiwanese technical knit clusters compress margin elasticity for mid-tier brands lacking backward integration into polymer supply. This scale concentration simultaneously elevates price floors for virgin polyester-dependent producers and creates procurement leverage for vertically integrated specialists with captive recycled PET partnerships.
Pricing Analysis
Configured-to-order pricing for AI-driven made-to-measure leggings commands 40-60% premiums over standard SKUs, while mass-market basics face compression from fast-fashion volume players. Three-tier pricing structure across premium, standard, and economy levels stratifies by technical specification density and certification grade. Price erosion runs through entry-level cotton-modal T-shirts as direct-to-consumer subscription models displace wholesale replenishment cycles. Casual wearers exhibit highest price sensitivity, while fitness enthusiasts accept premium positioning for biometric-integrated recovery garments.
Supply Chain Analysis
Taiwan Strait maritime transit underwrites 70% of global four-way stretch spandex feedstock movement, creating single-point vulnerability during geopolitical friction or energy rationing events. Manufacturing concentrates in Vietnam, Taiwan, and China for technical knit fabrication, with India emerging as alternative capacity for polyester recycling. Raw material flows draw from petroleum-derived polyurethane, recycled PET flake, and bio-based elastane formulations. Tariff exposure on Chinese-origin textiles fragments product line architectures. Distribution runs through direct-to-consumer platforms, specialty retail, and fitness center verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The athleisure wear market constitutes a defensive moat anchored in regulatory entrenchment: EU REACH compliance and California SB 657 disclosure requirements create certification barriers that entrench incumbents with verified ethical sourcing documentation.
For Market Incumbents: Shield premium positioning through backward integration into polyester chemical recycling partnerships that satisfy EU Green Deal circular textile targets. Fortify supply resilience by anchoring micro-factory capacity in Bavaria and North Rhine-Westphalia to compress European lead times. Accelerate CLO3D talent acquisition before digital pattern-making scarcity constrains automation timelines. For New Entrants and Emerging Players: Recovery-compression garment white space in Japan's aging demographic corridor offers penetration velocity where incumbent presence remains thin. Tier-2 Indian cities present parallel expansion terrain with rising disposable income and nascent fitness infrastructure. Pursue biometric sensing layer partnerships to differentiate against established technical knit specialists. For Investors and Strategic Acquirers: Captive fabric R&D laboratories with in-house spandex formulation capabilities represent the highest-conviction acquisition archetype for long-term viability assessment. Monitor REACH Annex XVII expansion timelines as inflection indicators for bio-based elastane substitution economics. Track corporate wellness program procurement contract volumes as demand visibility signals.| Strategic Initiative | Industry Significance |
|---|---|
| Recycled Material Partnership | Vertical integration into European chemical recycling secures EU Green Deal compliance premiums. |
| AI-Driven Customization Platform | Body-scanning algorithms reduce return rates while capturing first-party customer data. |
| Micro-Factory Network Expansion | Localized Bavarian production shortens lead times for REACH-compliant European distribution. |
| Biometric Sensor Integration | Health-monitoring interfaces transform passive apparel into recurring revenue ecosystems. |
| Subscription Model Launch | Monthly replenishment cycles compress inventory risk and displace seasonal wholesale purchasing. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade databases, and retail audit data across the analysis window. Interviews with brand supply chain directors, technical knit manufacturers, corporate wellness procurement managers, and specialty retail buyers informed demand-side assumptions. Secondary validation drew from EU ECHA substance restriction updates, FTC Green Guides enforcement actions, and polyester feedstock customs records. Bottom-up SKU-level modeling triangulated against top-down category spend estimates.
Segmentation dimensions modeled include product type, customer engagement intensity, material composition, and distribution channel architecture across the projection horizon. CAGRs derived from regression analysis of historical adoption curves, adjusted for regulatory phase-in schedules and corporate wellness program expansion trajectories. Forecast inputs incorporated recycled PET supply elasticity, spandex feedstock cost volatility, and seamless knitting technology penetration rates.
Forecasts assume regulatory continuity in EU REACH and California SB 657 regimes; material policy shifts would require re-modeling of compliance cost burdens and material substitution timelines. Practitioners should keep alternative scenarios live as EU Green Deal circular textile target enforcement intensifies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sportswear
Cricket Bowling Machine Market
Sportswear
Casual Sportswear Market
Sportswear
Sports Socks for Children Market
Sportswear
Cycling Wear Market
Sportswear
Global Women Active Wear Market
Sportswear
Billiards and Snooker Equipment Market
Sportswear
Activewear Market
Sportswear
Cycling Apparel Market
Sportswear
Workout Clothes Market
Sportswear
Athleisure Market
Sportswear
North America Dancewear Market
Sportswear
Europe Dancewear Market
Sportswear
Skateboard Grip Tapes Market
Sportswear
Bicycle Apparels Market