
 North America Dancewear Market | 2026-2036
North America Dancewear Market Size, Share, and Industry Trends Forecast 2026-2036
North America Dancewear Market Insights
Subscription-based leasing of performance costumes is fragmenting traditional ownership models in the North America dancewear sector. Revolution Dancewear LLC leverages its vertically integrated domestic manufacturing to sustain margin control across mid-tier ballet academies. Capezio anchors its competitive position through century-old brand equity and deep specialty store penetration. BLOCH UK Ltd. competes via technical innovation in pointe shoe engineering, while Grishko Dance s.r.o. specializes in artisan-crafted footwear for professional companies.
Dancewear comprises fitted garments engineered from four-way stretch knit constructions—typically nylon-spandex blends with 15-20% elastane content—designed to permit full range of motion while maintaining aesthetic line visibility for instructors and adjudicators. Leotards and tights dominate volume throughput given their universal requirement across ballet, jazz, and contemporary training protocols, though costumes command disproportionate margin contribution due to embellishment labor and shorter production runs. Children's end-user demand leads absolute unit sales through parent-funded studio enrollment, while professional dancers concentrate value through technical-grade product specifications. Spandex-dominant material formulations lead performance positioning, though cotton blends retain share in children's segments where breathability and skin sensitivity drive parental selection criteria.
The U.S. Consumer Product Safety Commission enforces flammability standards under 16 CFR Part 1615/1616 that constrain costume design for youth performers, while ASTM International voluntary specifications govern stretch recovery and colorfastness in competitive athletic textiles. Canada's Competition Act and Textile Labelling Regulations mandate fiber content disclosure and performance claim substantiation, shaping cross-border product standardization requirements. Stakeholders must monitor evolving state-level chemical restriction proposals in California and New York that could cascade into reformulated dye processes and supply chain requalification burdens.
Market Dynamics
The U.S. Consumer Product Safety Commission's 16 CFR Part 1615/1616 flammability mandates are forcing costume manufacturers toward certified nylon-spandex blends, compressing design flexibility while elevating compliance costs across children's segments.
Growth Catalysts
- Boutique Studio Expansion:Parent-funded enrollment in specialized ballet and contemporary academies across California and New York concentrates unit demand for technical-grade leotards and tights.
- REACH-aligned Chemical Standards:Anticipated alignment with EU substance restrictions is accelerating reformulation of dye processes toward lower-toxicity alternatives in cross-border supply chains.
- Four-way Stretch Knit Engineering:Advances in 15-20% elastane nylon constructions are improving recovery durability, extending replacement cycles while maintaining aesthetic line visibility for instructors.
Market Restraints
- Petrochemical Input Volatility:Spandex and synthetic fiber prices fluctuate with crude oil derivatives, squeezing margin predictability for mid-tier manufacturers.
- Artisan Production Bottlenecks:Pointe shoe hand-crafting capacity concentrates in Eastern European ateliers, limiting scalable supply for North American professional companies.
- Substitution by Athletic Apparel:Generic compression wear from mainstream sportswear brands encroaches on recreational dance segments with lower price positioning.
Strategic Opportunities
- Subscription Costume Leasing:Performance wardrobe rental models reduce upfront parent expenditure while capturing recurring revenue from seasonal recital cycles.
- California Chemical Restriction Tailwinds:Proposed state-level dye and finish limitations create first-mover advantage for suppliers with pre-qualified compliant inventory.
- AI-assisted Size Matching:Computer vision fitting tools are hybridizing with e-commerce platforms to reduce return rates in direct-to-consumer channels.
Industry Challenges
- Pattern-Maker Talent Scarcity:Specialized draping expertise for dance-specific biomechanics is aging out of the workforce faster than vocational programs replenish supply.
- Multi-jurisdiction Labeling Complexity:Canada's Competition Act fiber disclosure rules diverge from U.S. FTC Textile Act requirements, forcing dual-SKU inventory management.
- Legacy ERP Integration Friction:Small-batch costume houses struggle to embed traceability systems required by major retail distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Dancewear Market |
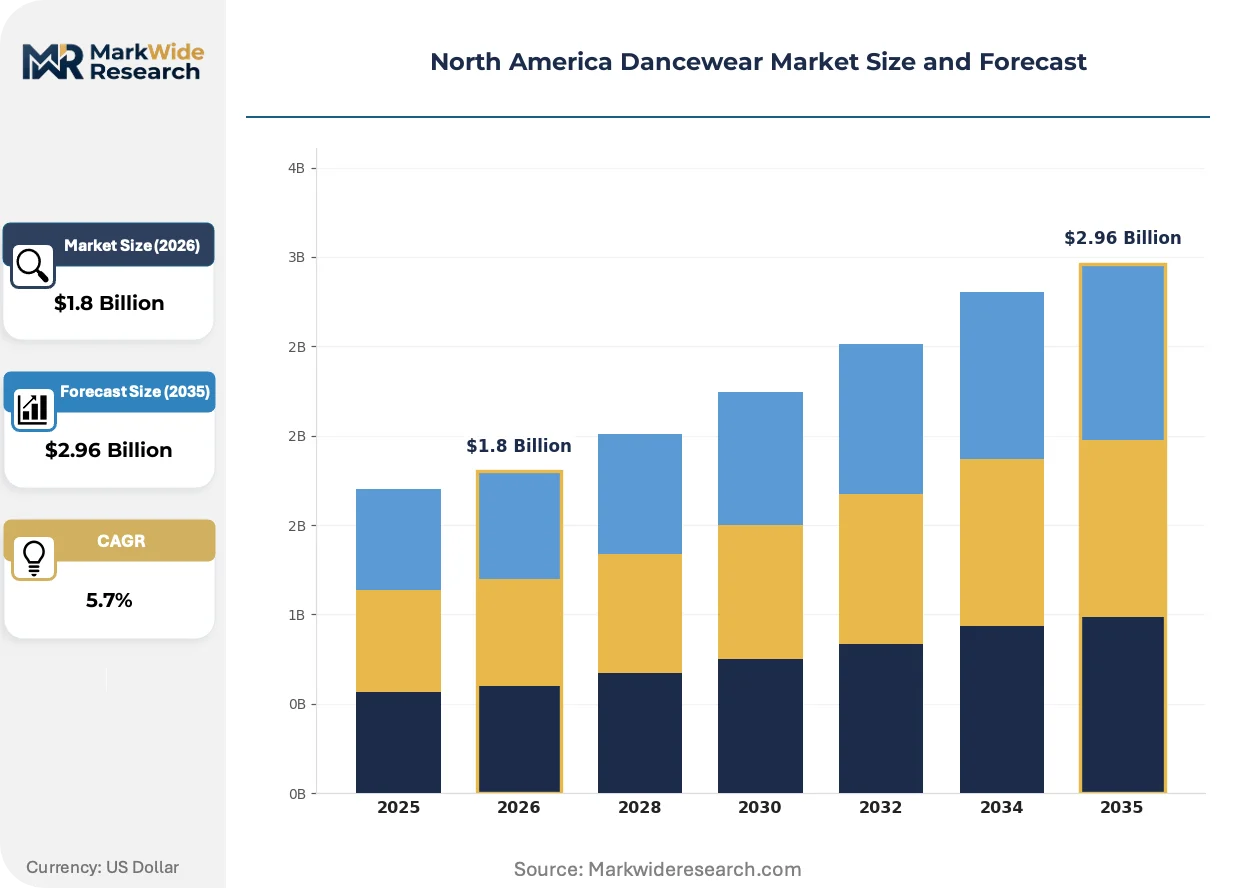
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Leotards, Tights, Skirts, Costumes End User: Children, Teens, Adults, Professional Dancers Material: Spandex, Cotton, Nylon, Polyester Distribution Channel: Online Retail, Specialty Stores, Department Stores, Boutiques |
| Companies Covered | ONWARD HOLDINGS Co., Ltd., Revolution Dancewear LLC, SF Dance Gear, Ballet Makers, Inc., BLOCH UK Ltd., Bullet Pointe, Flo Dancewear, Capezio, Grishko Dance s.r.o., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Dancewear Market Trends and Innovations
Material science convergence with digital commerce infrastructure is compressing traditional seasonal buying patterns while elevating technical performance specifications across training and performance categories.
Smart textile integration is hybridizing conventional nylon-spandex bases with embedded biometric monitoring threads that track muscle activation and alignment feedback. Competitive youth programs in Texas and Florida are piloting these garments for injury prevention protocols. The technology is compressing the boundary between apparel and wearable diagnostics, forcing traditional manufacturers to partner with sensor suppliers or cede premium positioning.
The U.S. Consumer Product Safety Commission's expanded interpretation of 16 CFR Part 1615/1616 to cover theatrical costume classifications is mandating flame-retardant treatment documentation for all youth performance wear. California's Department of Toxic Substances Control is separately advancing restrictions on per- and polyfluoroalkyl substances in textile finishes. Children's costume suppliers are responding by pre-qualifying fabric mills with third-party OEKO-TEX certification to accelerate downstream retail onboarding.
Studio-direct procurement is consolidating parent purchasing decisions through institutional bulk ordering portals that bypass traditional retail markup. Recreational program directors in Ontario and Quebec are negotiating volume contracts directly with distributors for standardized class uniform packages. This channel compression is most visible in metropolitan corridor markets where studio concentration enables route-density efficiencies for dedicated delivery logistics.
North America Dancewear Market Segmentation
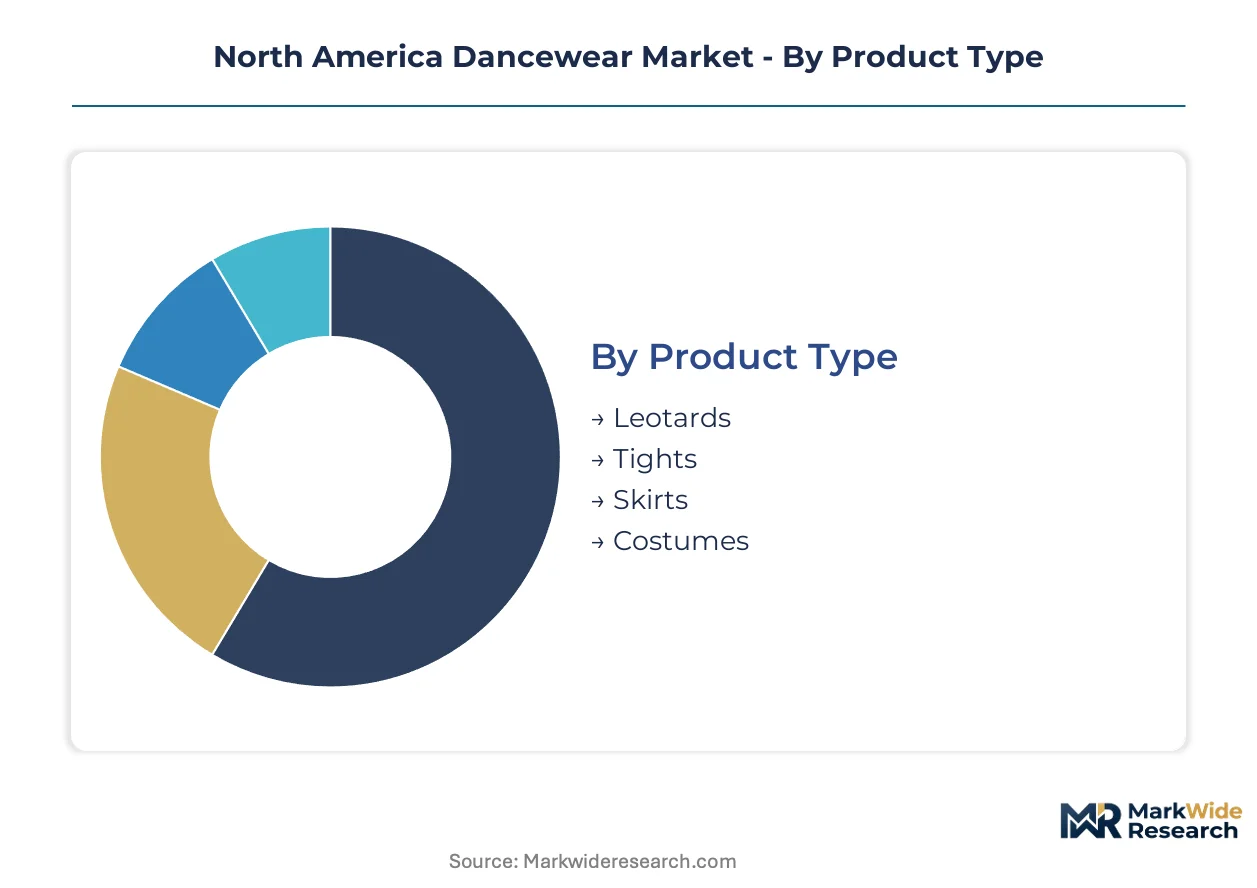
Segmentation in North American dancewear reveals how parent-funded studio enrollment, technical performance requirements, and channel compression reshape purchasing patterns across California's Los Angeles corridor and New York City's metropolitan cluster. Material specifications and distribution pathways diverge sharply between recreational children's programs and professional company procurement.
Product Type:
Cost tier stratification separates high-turnover training basics from margin-rich performance pieces with embellishment labor and shorter production runs.
- Leotards:Fitted bodysuits engineered from four-way stretch knit constructions with 15-20% elastane content permit full range of motion while maintaining aesthetic line visibility for instructors and adjudicators. California's boutique ballet academies concentrate unit demand for technical-grade specifications with reinforced seams and shelf-bra construction.
- Tights:Sheer-to-opaque leg coverings in convertible and footed variants dominate volume throughput given universal requirements across ballet, jazz, and contemporary training protocols. Parent-funded enrollment in recreational programs across Ontario and Quebec drives replacement cycles for this lowest-cost-per-wear category.
- Skirts:Wrap and pull-on styles in chiffon and georgette provide modesty layering for classical training environments.
- Costumes:Embellished performance garments with sequin, bead, and appliqué labor command disproportionate margin contribution due to artisan production requirements and single-season recital usage.
Leotards and tights command the established base. The steepest expansion runs through costumes as seasonal recital cycles elevate parent expenditure.
End User:
Customer type determines technical specification intensity, with professional dancers demanding biomechanical engineering that recreational segments bypass.
- Children:Breathable cotton blends retain share where skin sensitivity drives parental selection criteria. The U.S. Consumer Product Safety Commission's 16 CFR Part 1615/1616 flammability standards constrain costume design for youth performers, pushing suppliers toward certified fabric mills with third-party OEKO-TEX certification.
- Professional Dancers:Technical-grade product specifications concentrate value through pointe shoe engineering, custom fitting protocols, and recovery-durable stretch constructions. New York City's metropolitan studio cluster anchors demand for artisan-crafted footwear from Eastern European ateliers.
- Teens:Transitional sizing requirements bridge children's cotton blends toward adult performance synthetics.
- Adults:Recreational fitness dancers prioritize compression and moisture management over aesthetic line visibility.
Children's segments anchor volume throughput. Professional dancers generate the steepest value-per-unit trajectory through technical specification premiums.
Material:
Supply concentration in petrochemical derivatives creates margin volatility that shapes manufacturer formulation strategies across mid-tier producers.
- Spandex:Elastane-dominant formulations with 15-20% content lead performance positioning through superior recovery durability and shape retention. REACH-aligned chemical standards anticipated in cross-border supply chains are accelerating reformulation toward lower-toxicity alternatives.
- Cotton:Natural fiber blends retain share in children's segments where breathability and skin sensitivity drive parental selection criteria. California's Department of Toxic Substances Control restrictions on per- and polyfluoroalkyl substances in textile finishes favor untreated cotton for youth costume applications.
- Nylon:Synthetic base fiber provides four-way stretch foundation when blended with elastane.
- Polyester:Cost-competitive synthetic offers moisture-wicking properties for high-perspiration training environments.
Spandex commands technical performance positioning. Cotton is gaining share fastest through chemical restriction tailwinds in children's segments.
Distribution Channel:
Channel compression is fragmenting traditional retail markup as studio-direct procurement consolidates parent purchasing decisions through institutional bulk ordering portals.
- Specialty Stores:Deep product knowledge and professional fitting services anchor competitive positioning for pointe shoe procurement and technical-grade leotards. Century-old brand equity sustains foot traffic in metropolitan corridor markets where studio concentration enables route-density efficiencies.
- Online Retail:AI-assisted size matching through computer vision fitting tools is hybridizing with e-commerce platforms to reduce return rates in direct-to-consumer channels. Texas and Florida competitive youth programs pilot smart textile integration through digital-first purchasing pathways.
- Boutiques:Curated selection and studio relationship networks capture parent-funded enrollment in specialized academies.
- Department Stores:Mass-market positioning serves recreational entry-level demand with limited technical specification depth.
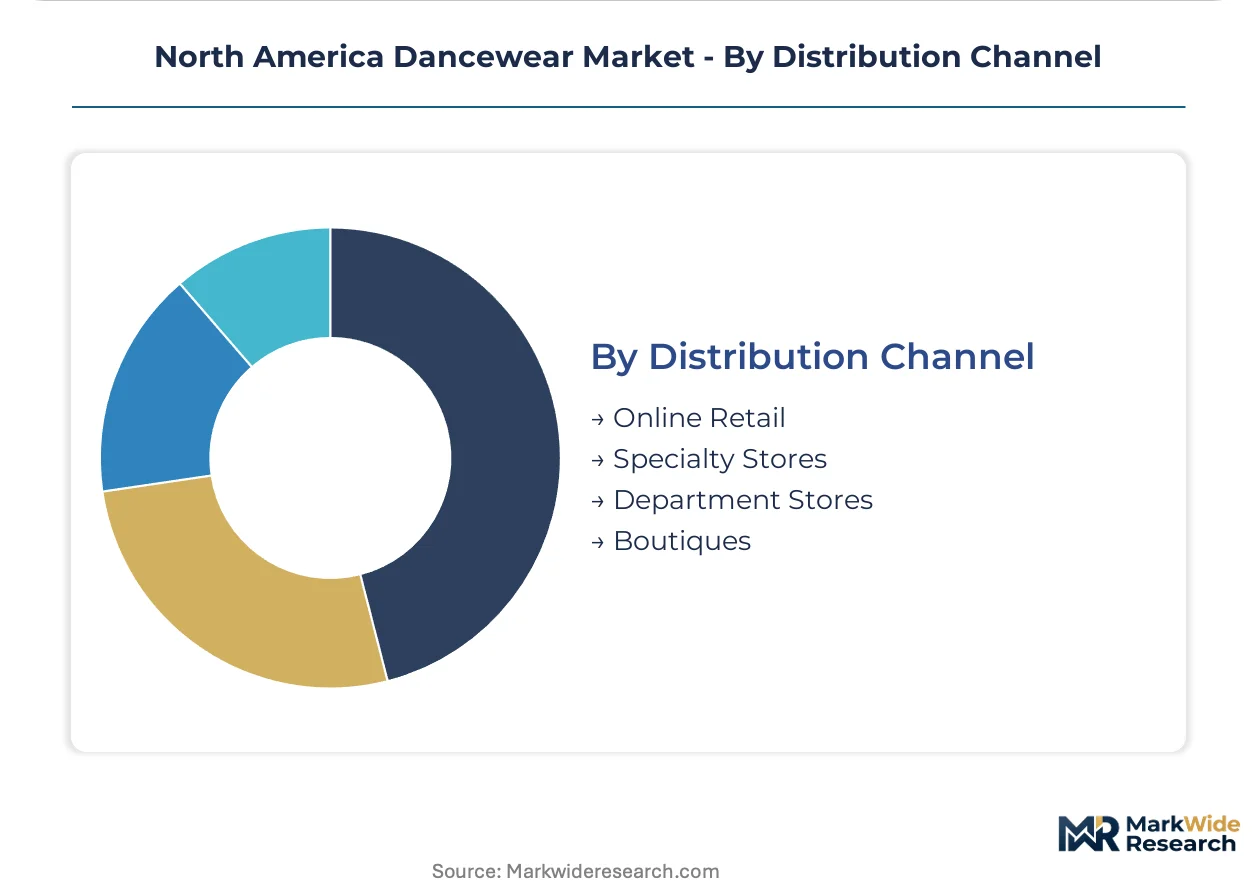
Specialty stores retain the established professional base. Online retail is climbing the fastest as computer vision tools compress fit-related return friction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North America dancewear trade flow shows modest import dependence for technical performance goods, with domestic manufacturing concentrated in vertically integrated producers serving studio-direct channels. Cross-border supply chains link Canadian distribution hubs to U.S. production facilities, while Mexican assembly operations handle lower-complexity garment finishing.
United States
California's Los Angeles dance corridor and New York City's metropolitan studio cluster concentrate absolute demand for technical-grade leotards and pointe shoes. The U.S. Consumer Product Safety Commission enforces 16 CFR Part 1615/1616 flammability standards that constrain costume design for youth performers. Texas and Florida competitive youth programs pilot smart textile integration for injury prevention protocols.
Canada
Ontario and Quebec recreational program directors negotiate volume contracts for standardized class uniform packages through institutional bulk ordering portals. Health Canada's Textile Labelling Regulations mandate fiber content disclosure that diverges from U.S. FTC requirements, forcing dual-SKU inventory management. Toronto and Montreal anchor distribution route-density efficiencies for cross-border fulfillment.
Mexico
Bajío Region assembly operations handle garment finishing for mid-tier nylon-spandex training basics exported to U.S. boutique studios. The country's national consumer protection agency monitors textile safety compliance for youth costume imports. Mexico City Metro concentrates retail distribution for recreational entry-level demand in Latin American export markets.
North America Dancewear Market Competitive Landscape
On the supply side, the industry is structured around three distinct tiers: century-old heritage brands with deep specialty store penetration, vertically integrated domestic manufacturers controlling margin through captive production, and artisan ateliers specializing in biomechanical footwear engineering. Strategic archetypes include brand-equity defenders leveraging historical reputation, scale operators optimizing route-density logistics for studio-direct channels, and technical specialists commanding premium positioning through custom fitting protocols. Dominant competitive moves encompass backward integration into fabric mill ownership and geographic expansion through metropolitan corridor cluster targeting.
Among heritage-positioned incumbents, Capezio exemplifies brand-equity defense through century-old market presence, while BLOCH UK Ltd. occupies the technical-specialist tier with pointe shoe engineering focus. Revolution Dancewear LLC represents the vertically integrated archetype with domestic manufacturing control. Grishko Dance s.r.o. anchors the artisan-craft segment for professional company procurement.
| Leading Market Players |
|---|
| ONWARD HOLDINGS Co., Ltd. |
| Revolution Dancewear LLC |
| SF Dance Gear |
| Ballet Makers, Inc. |
| BLOCH UK Ltd. |
| Bullet Pointe |
| Flo Dancewear |
| Capezio |
| Grishko Dance s.r.o. |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in Eastern European pointe shoe ateliers concentrates pricing power among artisan-craft suppliers while forcing North American distributors toward premium positioning for technical-grade footwear. This utilization asymmetry between hand-crafted capacity and mass-market synthetic production reshapes margin capture across the value chain.
Pricing Analysis
Parent-funded studio enrollment anchors a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on certification grade—OEKO-TEX compliant fabrics command measurable premiums—and volume scale through institutional bulk contracts. Cost compression in children's costumes is intensifying because California's Department of Toxic Substances Control restrictions force dye process reformulation. Recreational program directors exhibit highest price sensitivity, while professional companies tolerate premium positioning for biomechanical specifications.
Supply Chain Analysis
Petrochemical feedstock volatility in spandex and synthetic fiber production draws from crude oil derivative markets, creating margin unpredictability for mid-tier manufacturers. Geographic supply concentration centers on China's textile mill complexes for nylon-spandex base fabrics, Vietnam for garment assembly, and Eastern European ateliers for pointe shoe hand-crafting. Single-source vulnerability in artisan footwear capacity limits scalable supply for North American professional companies. Distribution runs through studio-direct procurement portals that bypass traditional retail markup in metropolitan corridor markets.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart textile integration with embedded biometric monitoring threads is disrupting competitive positioning across competitive youth programs, creating first-mover advantage for manufacturers that bridge apparel and wearable diagnostics.
For Market Incumbents: Pre-empt substitution by athletic compression wear brands through captive supply of certified fabric mills with pre-qualified OEKO-TEX inventory. Accelerate backward integration into dye process control to defend margin position against California chemical restriction tailwinds. Lock studio-direct channel relationships through route-density logistics investments in Los Angeles and New York corridor markets.
For New Entrants and Emerging Players: Pursue AI-assisted size matching technology partnerships with e-commerce platforms to reduce return rate friction in direct-to-consumer channels. Target subscription costume leasing models in Texas and Florida competitive youth programs where seasonal recital cycles concentrate parent expenditure. Anchor go-to-market strategy through boutique studio relationship networks rather than mass retail penetration.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across smart textile manufacturing as sensor supplier partnerships and biometric thread integration require specialized production equipment. Long-term viability favors acquisition targets with pre-qualified compliant inventory positioning ahead of anticipated REACH-aligned chemical standards. Monitor state-level chemical restriction proposal advancement in California and New York as inflection indicators for reformulation-driven supply chain requalification cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fabric Mill Ownership | Capezio and Revolution Dancewear LLC control margin through captive nylon-spandex supply. |
| Smart Textile Platform Integration | Biometric monitoring threads compress the boundary between apparel and wearable diagnostics. |
| Studio-Direct Procurement Portal Launch | Bulk ordering portals in Ontario and Quebec bypass traditional retail markup structures. |
| Subscription Costume Leasing Model | Seasonal recital cycles enable recurring revenue capture from parent-funded enrollment. |
| California Chemical Compliance Pre-Qualification | OEKO-TEX certification accelerates downstream retail onboarding ahead of state restrictions. |
Research Methodology
The analysis maps leotards, tights, costumes, and pointe shoes, each validated through studio directors, costume house production managers, specialty store buyers, and textile mill technical leads. Primary interviews with boutique academy owners and recreational program directors combined with secondary validation from U.S. Consumer Product Safety Commission flammability standard filings, ASTM International stretch recovery specifications, Health Canada Textile Labelling Regulations, and cross-border trade flow data. Bottom-up unit demand modeling and top-down value aggregation triangulate market sizing across product categories.
Assumptions held fixed include continued enforcement of 16 CFR Part 1615/1616 flammability mandates and stable parent-funded enrollment trends in California and New York metropolitan clusters. Variables tested across the analysis window encompass petrochemical input price volatility, state-level chemical restriction adoption timing, and smart textile penetration rates in competitive youth segments. CAGRs derive from segment-level volume trajectories weighted by price-per-unit evolution in technical-grade versus recreational specifications. Forecast inputs incorporate studio concentration density in corridor markets and pointe shoe artisan capacity constraints.
Macroeconomic conditions sit as an overlay; deviation in crude oil derivative pricing or consumer discretionary expenditure on children's enrichment activities would shift the trajectory. Cross-checking against U.S. Census Bureau retail trade data and Canadian textile import statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sportswear
Skateboard Grip Tapes Market
Sportswear
Activewear Market
Sportswear
Athleisure Market
Sportswear
Sports Socks for Children Market
Sportswear
Workout Clothes Market
Sportswear
Bicycle Apparels Market
Sportswear
Cycling Wear Market
Sportswear
Global Women Active Wear Market
Sportswear
Cricket Bowling Machine Market
Sportswear
Billiards and Snooker Equipment Market
Sportswear
Cycling Apparel Market
Sportswear
Casual Sportswear Market
Sportswear
Europe Dancewear Market
Sportswear
Athleisure Wear Market