
 Confectionery Packaging Market | 2026-2036
Confectionery Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Confectionery Packaging Market Analysis
Asia-Pacific is rewriting competitive dynamics in confectionery packaging as contract manufacturers scale capacity across India and Southeast Asia. Mondelez International leverages integrated chocolate-to-wrapper operations across multiple continents. Ferrero Group anchors its premium positioning through proprietary molded packaging formats. Nestlé S.A. differentiates via aggressive paperization roadmaps in European markets.
Confectionery packaging encompasses primary and secondary enclosures engineered to preserve organoleptic properties, prevent moisture ingress, and extend shelf stability through barrier films, sealed seams, and controlled atmosphere layers. Flexible packaging dominates volume flows for countline and bagged candies due to lightweighting and format versatility, while rigid boxes command margin pools in gift and seasonal segments where unboxing experience drives purchasing decisions. Paperboard is displacing conventional plastic laminates in premium tiers as brand owners respond to retailer sustainability scorecards.
The EU Green Deal and F-Gas Regulation constrain hydrocarbon-based film use in European confectionery operations, while FDA food-contact substance notifications govern barrier coating approvals in the United States. India's BIS packaging standards and PLI scheme for sustainable materials are reshaping supplier qualification criteria for export-oriented confectioners. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory in cross-border supply chains.
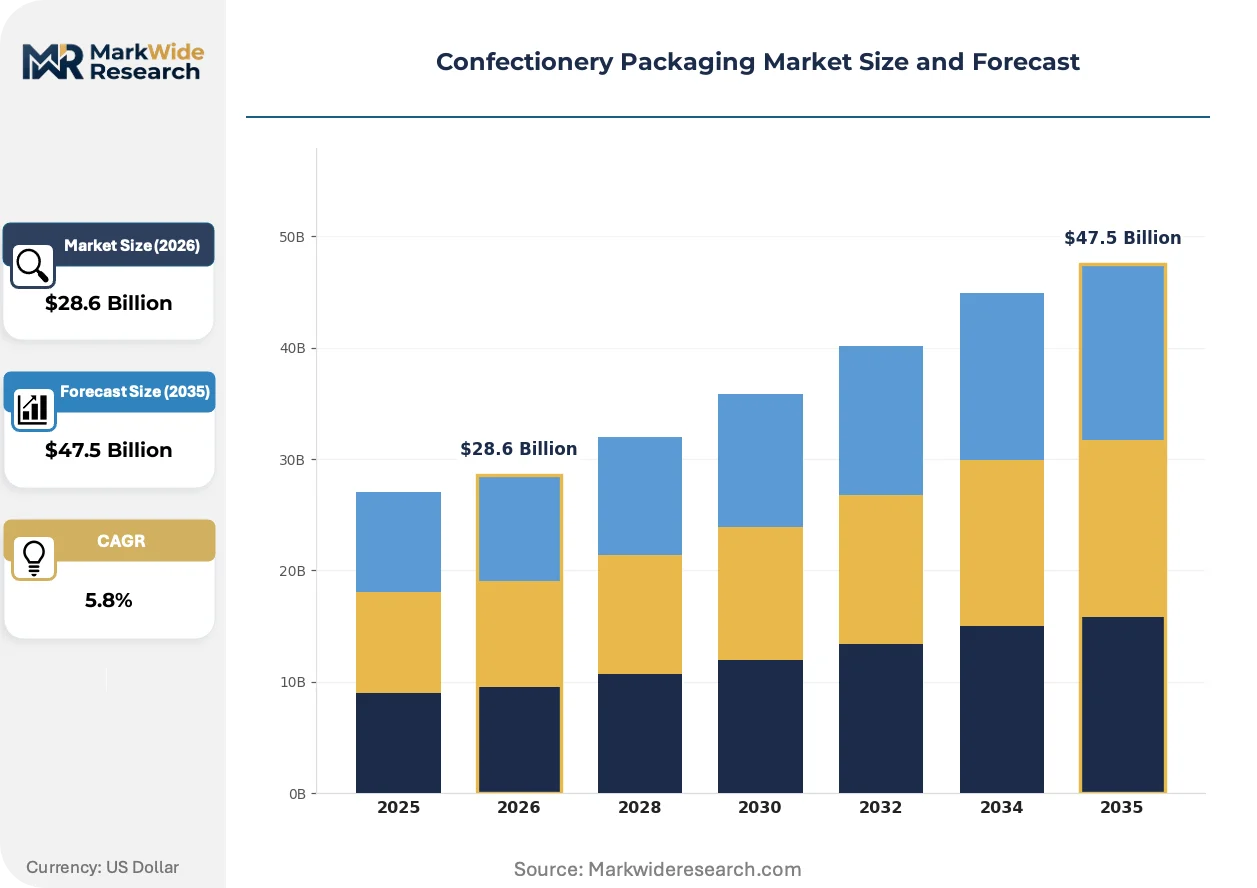
Market Dynamics
The EU Green Deal and Single-Use Plastics Directive are compressing hydrocarbon-based film availability across European confectionery operations, forcing accelerated material transitions before alternative supply chains mature.
Growth Catalysts
- REACH-compliant barrier coatings:European converters are qualifying cellulose-based laminates that maintain moisture barriers without fluorinated chemistry, opening shelf-stable formats for premium chocolate.
- India's PLI scheme for sustainable materials:Export-oriented confectioners are qualifying domestic suppliers under production-linked incentive thresholds, reducing import dependency for compostable wrappers.
- Molded fiber tooling advances:Thermoformed pulp technologies are achieving the dimensional precision required for rigid gift boxes, displacing plastic trays in seasonal assortments.
Market Restraints
- Ethylene-vinyl alcohol copolymer supply concentration:Barrier film production clusters in Northeast Asia create vulnerability to feedstock volatility and logistics disruption.
- F-Gas Regulation compliance timelines:European converters face stranded equipment investments as blowing agents for expanded polystyrene inserts face phase-down schedules.
- Technical limitations of mono-material structures:Current polyethylene-only laminates fail to match the oxygen transmission rates of multi-layer constructions for nut-containing confections.
Strategic Opportunities
- Direct-to-consumer subscription channels:Specialty chocolatiers are bypassing retail shelf-life requirements with shorter distribution cycles, enabling lighter barrier specifications.
- CSRD-aligned packaging disclosures:Corporate sustainability reporting mandates are creating procurement preference for suppliers with verified lifecycle data.
- Digital watermark integration:Invisible tracers embedded in paperboard are enabling automated sortation at materials recovery facilities, unlocking circular feedstock premiums.
Industry Challenges
- Migration modeling expertise:Food-contact substance safety assessments require specialized toxicologists and analytical chemists in short supply across contract packaging sectors.
- Legacy heat-seal equipment retrofit:Converting lines optimized for polyolefin films require substantial modification to run heat-sensitive bio-based sealants without throughput loss.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Confectionery Packaging Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Flexible Packaging, Rigid Packaging, Boxes, Pouches Material: Plastic, Paperboard, Glass, Metal End User: Retailers, Wholesalers, E-commerce, Foodservice Feature: Recyclable, Tamper-Proof, Waterproof, Biodegradable |
| Companies Covered | Ferrero Group, Lindt & Sprüngli AG, Mondelez International, Haribo GmbH & Co. KG, Perfetti Van Melle, Mars Incorporated, The Hershey Company, Pladis, Nestlé S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Confectionery Packaging Market Emerging Trajectories
Material science breakthroughs and regulatory compression are converging to redefine performance benchmarks across primary and secondary confectionery enclosures, with sustainability verification becoming a non-negotiable procurement filter.
High-barrier metallized films are migrating from conventional aluminum oxide deposition toward silicon oxide coatings applied through plasma-enhanced chemical vapor deposition. Premium chocolate manufacturers in Switzerland and Belgium are piloting these transparent barriers to preserve product aroma while satisfying retailer plastic-reduction commitments. This migration from metalized to clear oxide barriers is enabling windowed packaging formats previously incompatible with shelf-life requirements.
The EU F-Gas Regulation is accelerating phase-out schedules for hydrofluorocarbon blowing agents used in expanded polystyrene chocolate tray production. Confectionery operations in Germany and France are qualifying carbon dioxide-based physical foaming for molded pulp alternatives, though dimensional tolerances for automated packing lines remain tighter than legacy specifications. Mid-tier seasonal producers face compressed timelines to validate new tray materials before 2025 holiday production cycles.
Retail sustainability scorecards are rewriting supplier qualification protocols for private-label confectionery programs. Major European grocery chains are mandating packaging footprint reductions as a condition of shelf placement, with some operators unbundling conventional annual contracts into shorter cycles tied to verified material transitions. This behavioral shift is most pronounced in German and UK markets where discounter competition has intensified transparency requirements.
Confectionery Packaging Market Segmentation
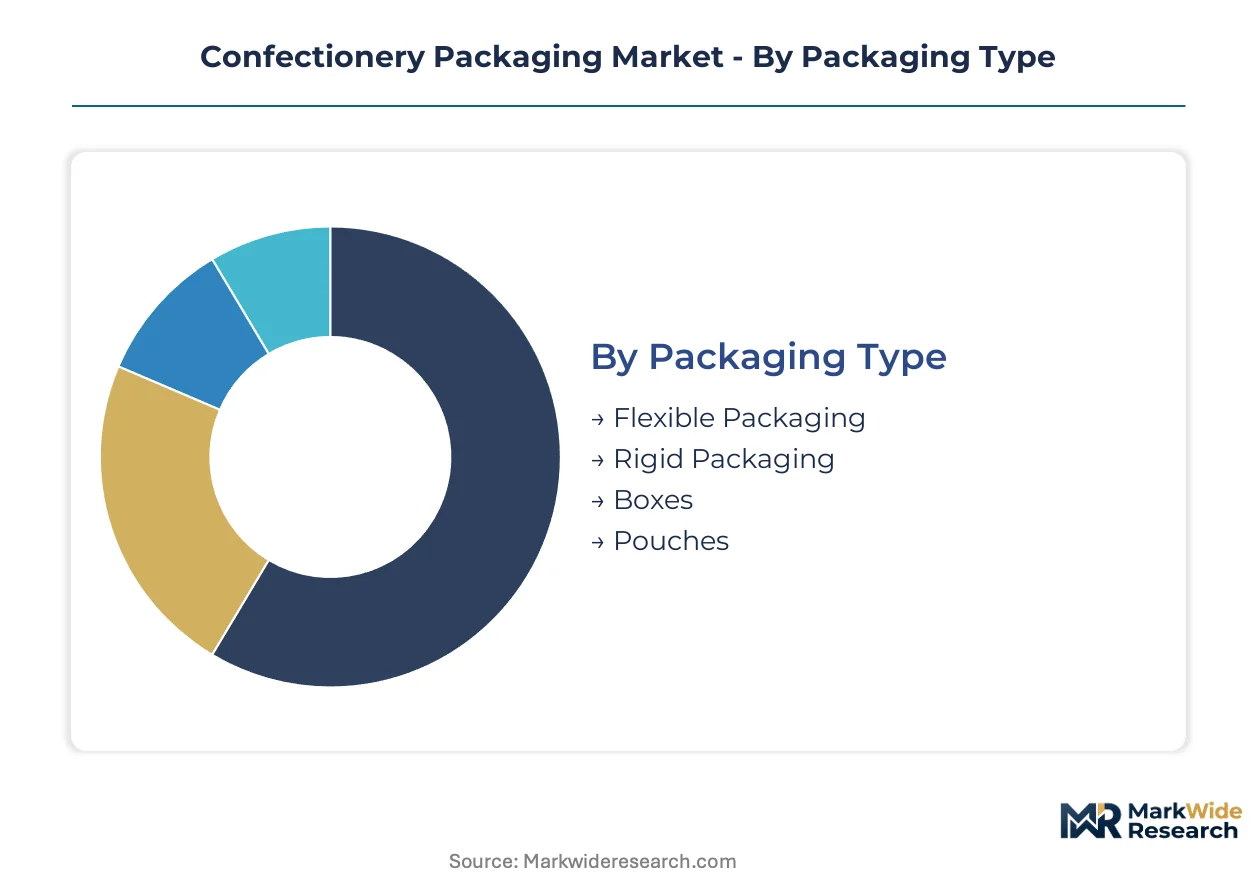
Confectionery packaging segmentation reveals how material science, distribution channel requirements, and regulatory compliance intersect to create distinct performance tiers. Each dimension carries procurement implications that reshape supplier qualification protocols and capital allocation decisions across the value chain.
Packaging Type:
Cost tier differentiation separates high-volume commodity formats from engineered solutions commanding premium positioning through structural complexity and barrier performance.
- Flexible Packaging:Multi-layer films and laminates deliver lightweight moisture barriers for countline bars and bagged candies. German retailers are consolidating procurement around mono-material polyethylene structures to satisfy EU Green Deal sorting requirements, though oxygen transmission rates for nut inclusions remain unresolved.
- Rigid Packaging:Thermoformed trays, tubs, and clamshells provide dimensional protection for molded chocolates and premium assortments. Swiss and Belgian chocolatiers are qualifying molded fiber alternatives to displace expanded polystyrene ahead of F-Gas Regulation phase-down schedules.
- Boxes:Folding carton and rigid board constructions dominate gift and seasonal segments where unboxing experience drives purchasing decisions. Paperboard is displacing plastic laminates in European premium tiers responding to retailer sustainability scorecards.
- Pouches:Stand-up and flat pouch formats offer format versatility for sharing bags and resealable candy packs. Southeast Asian contract manufacturers are scaling pouch converting capacity to capture export demand from European brand owners.
Flexible packaging commands the established base. The steepest expansion runs through rigid fiber alternatives as regulatory pressure accelerates material transitions.
Material:
Application requirements dictate material selection, with barrier performance, printability, and end-of-life pathways creating distinct procurement trade-offs across confectionery categories.
- Plastic:Polyethylene, polypropylene, and PET films provide moisture and oxygen barriers through multi-layer coextrusion or metallization. REACH-compliant cellulose-based laminates are opening shelf-stable formats for premium chocolate without fluorinated chemistry.
- Paperboard:Solid bleached sulfate and folding boxboard deliver print quality and structural rigidity for secondary packaging. Digital watermark integration is enabling automated sortation at materials recovery facilities, unlocking circular feedstock premiums.
- Glass:Premium jars and bottles preserve aroma for chocolate spreads and specialty confections. High logistics costs and breakage rates constrain adoption to ultra-premium positioning and domestic distribution.
- Metal:Tinplate and aluminum cans, tins, and foils provide complete light and oxygen barriers for long-life products. Seasonal gift tins retain collector value that extends packaging lifecycle beyond single use.
Plastic retains volume leadership. Paperboard is gaining share fastest as brand owners respond to CSRD-aligned procurement mandates.
End User:
Customer type determines packaging performance specifications, with shelf-life requirements and handling intensity varying sharply across distribution channels.
- Retailers:Supermarkets, hypermarkets, and convenience stores demand extended shelf stability and shelf-ready display formats. Major European grocery chains are unbundling annual contracts into shorter cycles tied to verified material transitions.
- Wholesalers:Bulk distribution to independent retailers and institutional buyers prioritizes cube efficiency and case-level protection over primary pack aesthetics. Pallet-level specifications dominate procurement negotiations.
- E-commerce:Direct-to-consumer shipment requires enhanced crush resistance and temperature stability through last-mile distribution. Specialty chocolatiers are bypassing retail shelf-life requirements with shorter distribution cycles, enabling lighter barrier specifications.
- Foodservice:Hotels, restaurants, and catering operations demand portion-control formats and bulk dispensers with hygiene safeguards. Quick-serve integration drives single-serve wrapper standardization.
Retailers anchor current demand. E-commerce is climbing the fastest as subscription channels reshape distribution economics.
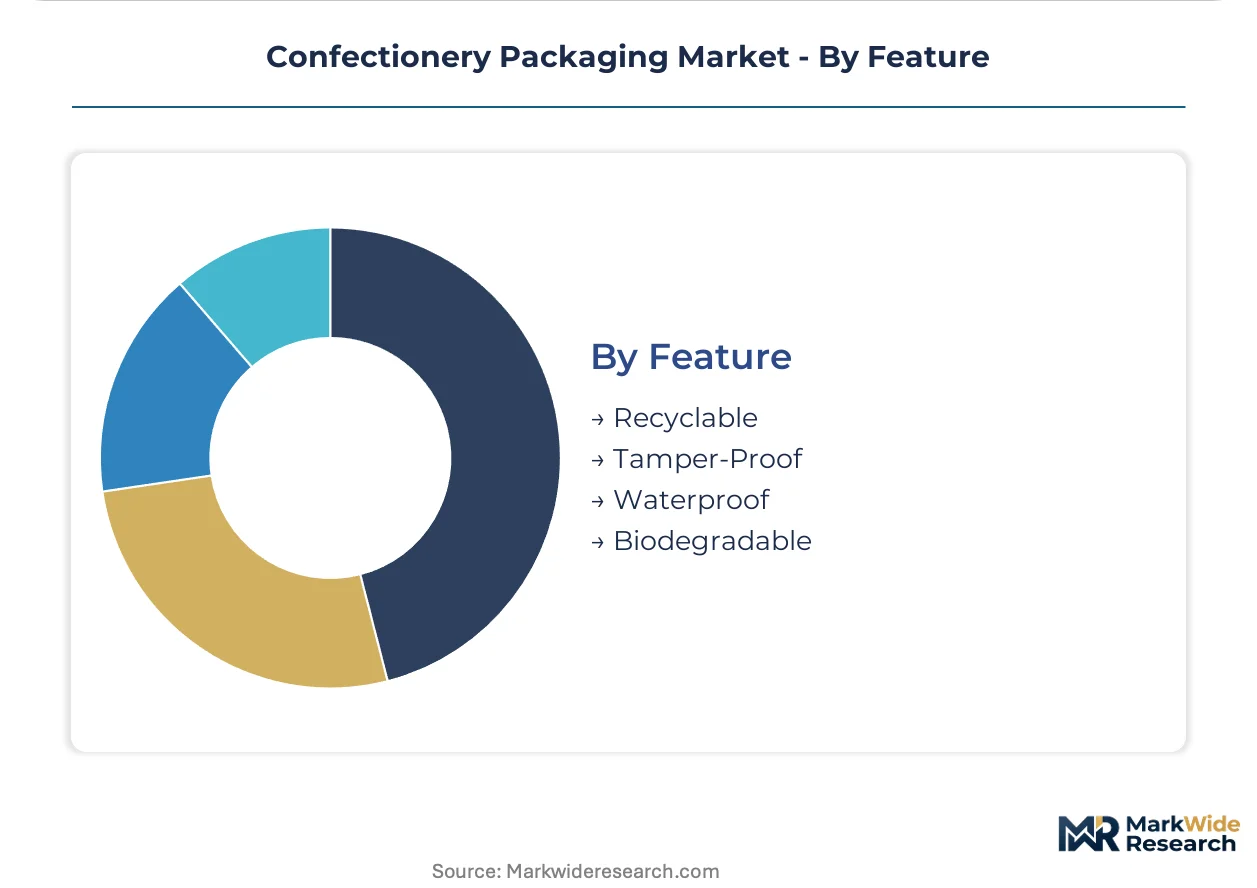
Feature:
Margin premiums attach to certified functional attributes, with sustainability verification becoming a non-negotiable procurement filter alongside traditional performance characteristics.
- Recyclable:Mono-material or widely collected multi-material structures designed for existing municipal streams. India's BIS packaging standards are reshaping supplier qualification criteria for export-oriented confectioners targeting circular claims.
- Tamper-Proof:Breakaway seals, shrink bands, and induction-sealed closures protect product integrity through distribution. Pharmaceutical-adjacent standards are migrating into premium chocolate gift formats.
- Waterproof:Wax coatings, laminated barriers, and sealed seam constructions prevent moisture ingress in humid climates. Tropical distribution requirements drive specification divergence from temperate-market designs.
- Biodegradable:Certified compostable films and molded pulp engineered for industrial or home composting environments. India's PLI scheme for sustainable materials is accelerating domestic supply chain development for compostable wrappers.
Recyclable features dominate current procurement. Biodegradable certification is expanding most quickly as regulatory timelines compress conventional plastic availability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA's REACH framework governs barrier chemistry approvals across the European confectionery packaging corridor, while divergent regulatory timelines in Asia-Pacific and North America create compliance complexity for multinational brand owners.
Germany
Export-oriented confectioners in Cologne and Hamburg drive demand for high-barrier mono-material films compliant with EU Green Deal sorting requirements. The F-Gas Regulation accelerates phase-out schedules for expanded polystyrene blowing agents in chocolate tray production. Baden-Württemberg hosts precision tooling clusters advancing molded fiber dimensional tolerances for automated packing lines.
United States
FDA food-contact substance notifications govern barrier coating approvals for premium chocolate imports and domestic production. Mid-Atlantic contract packagers are retrofitting heat-seal equipment to accommodate bio-based sealants without throughput degradation. Chicago-area logistics hubs concentrate cold-chain distribution infrastructure for temperature-sensitive confections.
India
BIS packaging standards and the PLI scheme for sustainable materials reshape supplier qualification criteria for export-oriented confectioners targeting European markets. Maharashtra's converting corridors scale compostable wrapper capacity to capture production-linked incentive thresholds. Gujarat chemical clusters develop cellulose-based laminate feedstocks for barrier film applications.
Switzerland
Swissmedic-adjacent quality protocols migrate into premium chocolate gift formats demanding pharmaceutical-grade tamper-evidence. Geneva-based brand owners pilot silicon oxide transparent barriers through plasma-enhanced chemical vapor deposition. Zurich packaging engineering centers refine unboxing experience specifications for seasonal rigid box segments.
China
GB standards and MIIT industrial policy guide domestic barrier film production for both internal consumption and export manufacturing. Yangtze River Delta converters supply multi-layer laminates to European brand owners seeking cost-competitive alternatives to regional production. Pearl River Delta mold fabrication clusters advance thermoformed pulp tooling for rigid gift applications.
Confectionery Packaging Market Vendor Landscape
Integrated multinationals and specialized regional converters split the market into distinct capability tiers. Consolidation pressure concentrates around barrier film supply agreements and molded fiber tooling access. Three archetypes dominate: vertically integrated confectionery-brand owners with captive packaging operations; independent flexible film specialists serving private-label programs; and rigid packaging engineers focused on seasonal gift formats. Competitive moves center on backward integration into barrier coating production and strategic partnerships with pulp molding technology licensors.
Among European-headquartered conglomerates, Ferrero Group and Lindt & Sprüngli AG exemplify premium-tier positioning through proprietary molded formats and controlled supply chain architecture. Mondelez International occupies a position spanning mass-market scale with integrated chocolate-to-wrapper operations across multiple continents. These three entities represent divergent strategic paths: family-owned premium specialization, publicly traded global scale, and hybrid portfolio diversification across confectionery categories.
| Leading Market Players |
|---|
| Ferrero Group |
| Lindt & Sprüngli AG |
| Mondelez International |
| Haribo GmbH & Co. KG |
| Perfetti Van Melle |
| Mars Incorporated |
| The Hershey Company |
| Pladis |
| Nestlé S.A. |
| Others |
Supply Flow & Price Mechanics
Yangtze River Delta converters anchor global flexible film capacity, and their expansion dynamics directly shape pricing power for European brand owners negotiating annual supply agreements. Cost compression in bio-based sealants is intensifying because REACH-compliant chemistry commands scarcity premiums while conventional polyolefin contracts face downward pressure from oversupply in Asian production clusters.
Pricing Analysis
Geographic price spreads between Northeast Asian contract manufacturers and European domestic converters have widened to their largest differential in recent cycles. Three-tier pricing structure across premium, standard, and economy levels separates Swissmedic-adjacent gift formats from private-label bagged candies and commodity countline wrappers. Certification grade and volume scale drive price differentiation, with compostable wrapper premiums contracting as India's PLI scheme matures. Brand owners in Germany and Switzerland exhibit lowest price sensitivity due to sustainability scorecard mandates, while Southeast Asian contract manufacturers face acute margin pressure from feedstock volatility.
Supply Chain Analysis
Upstream ethylene-vinyl alcohol copolymer production draws from concentrated Northeast Asian petrochemical clusters, with secondary anchor points in Germany and the US Gulf Coast. Cellulose-based laminate feedstocks and silicon oxide barrier coatings represent critical material dependencies for premium chocolate formats. Single-source vulnerability in expanded polystyrene blowing agents creates disruption risk ahead of F-Gas Regulation phase-down schedules. Distribution runs through integrated brand-owner captive operations, independent flexible film specialists, and seasonal rigid packaging engineering houses serving gift assortment programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Confectionery packaging sits in early-cycle expansion as regulatory compression across Europe accelerates material transitions before alternative supply chains achieve cost parity. CSRD-aligned procurement mandates are creating procurement preference tailwinds for verified lifecycle data providers.
For Market Incumbents: Entrench barrier coating capabilities through backward integration into cellulose-based laminate production or exclusive partnerships with Yangtze River Delta converters. Capture molded fiber tooling access ahead of F-Gas Regulation deadlines. Defend against emerging contract manufacturers in Maharashtra and Gujarat by locking multi-year offtake agreements with European retail chains. For New Entrants and Emerging Players: Establish a beachhead in direct-to-consumer subscription channels where shorter distribution cycles enable lighter barrier specifications and bypass incumbent retail shelf-life requirements. Target e-commerce fulfillment packaging for specialty chocolatiers in North American markets. Lead with digital watermark integration enabling automated sortation premiums at materials recovery facilities. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors rigid packaging engineers with molded pulp dimensional precision capabilities and flexible film specialists with REACH-compliant coating qualifications. Five-to-ten year viability hinges on regulatory compliance infrastructure rather than commodity scale. Acquisition targets should demonstrate validated migration modeling expertise and retrofitted heat-seal equipment for bio-based sealants. Watch India's PLI scheme disbursement velocity as inflection indicator for compostable wrapper cost competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Barrier Coatings | Captures REACH-compliant chemistry margins and secures supply for premium chocolate formats. |
| Molded Fiber Capacity Expansion | Positions ahead of F-Gas Regulation phase-down schedules for expanded polystyrene alternatives. |
| Digital Watermark Integration | Unlocks circular feedstock premiums through automated sortation at European recovery facilities. |
| Direct-to-Consumer Channel Development | Bypasses retail shelf-life requirements and enables lighter barrier specifications for subscription chocolatiers. |
| India PLI Scheme Qualification | Reduces import dependency for compostable wrappers serving export-oriented European confectioners. |
Methodological Framework
Initial hypotheses were tested against primary input from packaging procurement managers at European retail chains, technical directors at flexible film converters, sustainability officers at premium chocolate brand owners, and equipment engineering leads at thermoformed pulp specialists and refined through secondary validation. Regulatory filings from ECHA, FDA food-contact substance notifications, and BIS packaging standards provided compliance boundary conditions. Trade data, customs records, and production-linked incentive disbursement reports supplied volume anchors. Bottom-up capacity assessments and top-down demand modeling were triangulated to reconcile segment-level outputs.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include packaging type, material chemistry, end-user channel, and certified functional attributes. CAGRs were derived from elasticity-adjusted volume projections and value-per-unit trajectories. Forecast inputs incorporated ESG disclosure mandate timelines, F-Gas Regulation phase-down schedules, and molded fiber tooling advancement curves.
Stress conditions across feedstock price volatility, regulatory enforcement intensity, and alternative material adoption rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding barrier performance parity timelines and equipment retrofit adoption curves. Cross-checking against customs trade flow data and disclosed supplier qualification protocols is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Packaging
Fashion Accessories Packaging Market
Specialty Packaging
Speciality Vials Market
Specialty Packaging
Gift Boxes Market
Specialty Packaging
Party Latex Balloon Market
Specialty Packaging
Luxury Boxes Market
Specialty Packaging
Senior Friendly Packaging Market
Specialty Packaging
Luxury Packaging Market
Specialty Packaging
Decorative Mylar Balloons Market
Specialty Packaging
Anti-Counterfeit Clothing and Accessories Packaging Market
Specialty Packaging
Middle East and Africa Latex Foil Balloons Market
Specialty Packaging
Gift Packaging Market
Specialty Packaging
Tipping Foils Market
Specialty Packaging
Global in Store Theater Packaging Market
Specialty Packaging
Promotion Bins Market
Specialty Packaging
Customized E-Commerce Packaging Market
Specialty Packaging
Mil-Spec Packaging Market