
 Crash Mat Market | 2026-2036
Crash Mat Market Size, Share, and Industry Trends Forecast 2026-2036
Crash Mat Market Outlook
CE certification under EN 12503 is unwinding competitive access for crash mat suppliers serving European sports facilities. Black Diamond leverages its alpine equipment heritage to anchor premium positioning in outdoor crash pad categories. Petzl sustains technical credibility through rigorous UIAA safety protocol integration across its bouldering mat line.
A crash mat is a shock-absorbing surface assembly, typically constructed from multi-density polyurethane or cross-linked polyethylene foam layers bonded to reinforced vinyl or rubber substrates, engineered to dissipate kinetic energy from falls in athletic, military, or recreational settings. Foam mats dominate volume shipments across indoor sports installations, while vinyl mats command margin premiums in commercial gymnastics facilities requiring sanitizable surfaces. Military training applications represent the fastest-growing end-user segment as defense programs modernize obstacle course infrastructure with standardized impact protection.
REACH compliance in Europe and EPA foam emissions guidelines in the United States shape material selection thresholds, compelling suppliers to reformulate away from legacy PVC binders toward certified EVA compounds. The EU AI Act introduces emerging liability frameworks for smart-sensor-enabled training mats that track impact metrics. Stakeholders must monitor how evolving chemical disclosure mandates across multiple jurisdictions will reshape supplier qualification timelines and raw material sourcing flexibility.
Market Dynamics
The EU's REACH chemical restrictions on foam formulations are compressing supplier margins while simultaneously accelerating material substitution timelines across European manufacturing clusters.
Growth Catalysts
- School district equipment refresh cycles:Public education budgets in the United States allocate capital for gymnastics program infrastructure upgrades on predictable replacement schedules.
- REACH compliance migration:European manufacturers reformulating toward certified EVA compounds unlock premium positioning in regulated markets.
- Defense modernization programs:Military obstacle course standardization mandates in Germany and the United States drive bulk procurement of impact-rated training surfaces.
Market Restraints
- Petrochemical input volatility:Polyurethane foam feedstock costs fluctuate with crude oil derivatives, squeezing contract manufacturer margins.
- Rhineland supplier concentration:Germany's industrial cluster dominates high-performance foam substrate production, creating geographic single-source risk.
- Legacy PVC binder phase-out friction:Existing tooling and adhesive processes require capital-intensive retooling for EVA transition.
Strategic Opportunities
- Smart-sensor integration:Impact-metric tracking technology converges with crash mat substrates, opening performance analytics subscriptions for training facilities.
- Sanitizable surface premium tier:Commercial gymnastics facilities in France and Italy prioritize vinyl-top mats for hygiene compliance.
- Outdoor bouldering expansion:Alpine recreation zones in Austria and Switzerland generate demand for weather-resistant portable crash pads.
Industry Challenges
- CE certification timeline compression:EN 12503 testing protocols extend supplier qualification periods for European facility tenders.
- Cross-border chemical disclosure alignment:Divergent EPA emissions guidelines and REACH substance restrictions complicate multi-jurisdictional product line management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crash Mat Market |
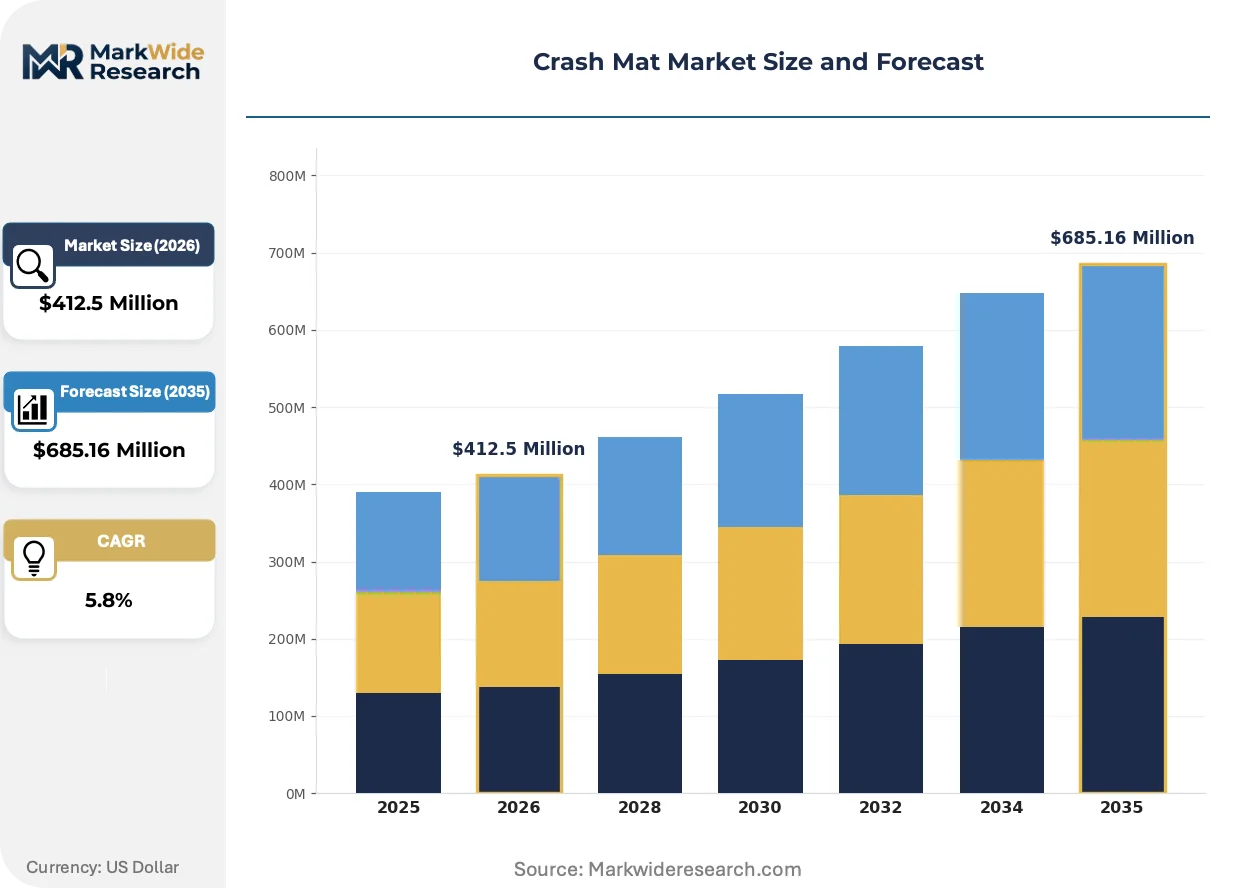
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $685.16 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foam Mats, Vinyl Mats, Rubber Mats, Carpet Mats End User: Sports Facilities, Gymnasiums, Childcare Centers, Military Training Material: EVA, Polyethylene, PVC, Neoprene Application: Indoor Sports, Outdoor Sports, Recreational Activities, Training Sessions |
| Companies Covered | Organic Climbing, Mad Rock Climbing, Black Diamond, Resilite, EDELRID, Petzl, Evolv, Tumbl Trak, Metolius, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crash Mat Market Strategic Shifts
Material science advances and regulatory chemistry mandates are restructuring competitive advantage around certified compound sourcing and embedded sensor capabilities.
Cross-linked polyethylene foam cores are displacing conventional polyurethane assemblies in high-impact training environments. Military procurement offices in the United States specify these substrates for obstacle course installations. The shift is compressing legacy foam converter margins while rewarding compounders with certified polymer supply chains.
REACH Annex XVII restrictions on phthalate plasticizers are forcing vinyl substrate reformulation across European supply chains. Manufacturers serving German school districts must certify alternative binders or exit tender eligibility. French and Italian facility operators now specify EVA-top mats as procurement default.
Facility operators increasingly unbundle crash mat purchases from full equipment packages, sourcing impact surfaces through specialized distributors rather than turnkey gymnasium contractors. This channel fragmentation concentrates volume with regional foam fabricators possessing direct CE certification. The pattern is most pronounced in Benelux municipal procurement.
Crash Mat Market Segmentation
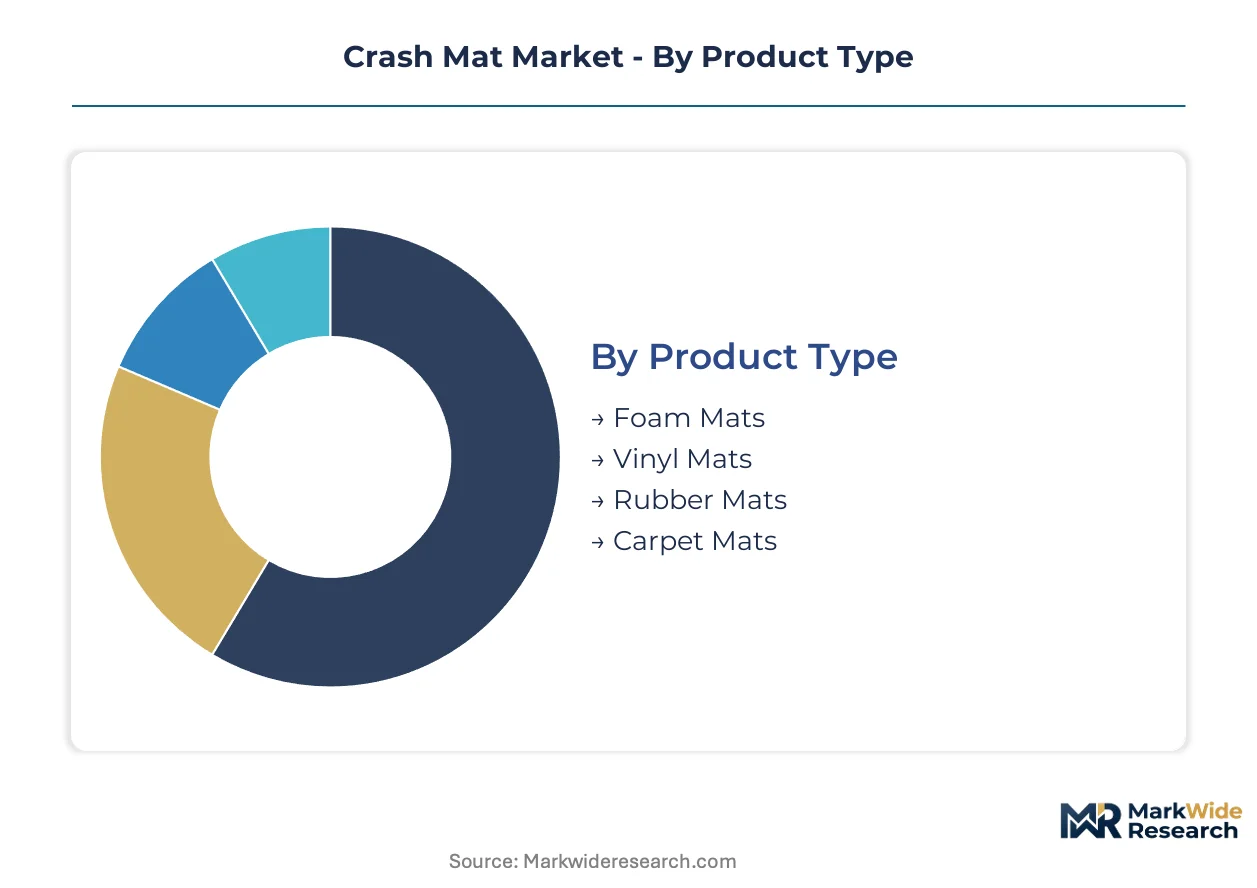
Segmentation in the crash mat market reveals distinct procurement patterns across institutional buyers, with material compliance and surface sanitization driving category-level premiums. Facility operators segment purchases by end-use intensity, creating divergent margin structures for high-impact military specifications versus standard educational installations.
Product Type:
Foam mats anchor domestic procurement across North American school districts, while vinyl and rubber variants concentrate in export-led commercial contracts serving European gymnastics federations.
- Foam Mats:Multi-density polyurethane or cross-linked polyethylene cores bonded to reinforced substrates dominate volume shipments across indoor sports installations. U.S. school districts refresh these on predictable capital cycles, though petrochemical feedstock volatility compresses contract manufacturer margins.
- Vinyl Mats:Sanitizable vinyl-top surfaces command premium positioning in commercial gymnastics facilities requiring hygiene compliance. French and Italian procurement offices now specify these as default for municipal tenders, with REACH Annex XVII phthalate restrictions accelerating EVA-top reformulation timelines.
- Rubber Mats:Natural and synthetic rubber compounds serve outdoor military obstacle courses and alpine bouldering zones.
- Carpet Mats:Lower-impact textile-faced assemblies address childcare center budgets and recreational entry-level segments.
Foam mats hold the largest share; momentum sits with vinyl mats as European chemical disclosure mandates reshape procurement defaults.
End User:
Cost tier stratification separates defense procurement with standardized impact ratings from budget-constrained childcare operators prioritizing basic fall protection.
- Sports Facilities:Professional training centers and competitive venues specify EN 12503-certified surfaces with documented impact attenuation metrics. Germany's Rhineland industrial cluster supplies these high-performance substrates, creating geographic concentration risk for facility operators dependent on CE-marked imports.
- Military Training:Obstacle course standardization mandates in the United States and Germany drive bulk procurement of cross-linked polyethylene assemblies. Defense modernization programs represent the steepest expansion trajectory as procurement offices prioritize standardized impact protection across training infrastructure.
- Gymnasiums:Educational institutions balance capital budget constraints against predictable replacement schedules.
- Childcare Centers:Regulatory compliance with surface sanitization and fall-height ratings shapes purchasing decisions.
Sports facilities command the highest unit economics; military training is climbing the fastest on defense infrastructure commitments.
Material:
Volume concentration favors legacy compounds, while margin expansion concentrates with certified EVA suppliers navigating REACH and EPA emissions frameworks.
- EVA:Ethylene-vinyl acetate compounds displace legacy PVC binders across European supply chains. Manufacturers serving German school districts must certify alternative binders or exit tender eligibility, with French facility operators accelerating specification shifts.
- Polyethylene:Cross-linked variants specified by U.S. military procurement for obstacle course durability.
- PVC:Phasing out across REACH jurisdictions; retained in price-sensitive domestic segments.
- Neoprene:Weather-resistant performance for outdoor alpine applications in Austria and Switzerland.
Polyethylene retains volume leadership; EVA is gaining share fastest on regulatory compliance premiums.
Application:
Customer type divergence separates institutional buyers with multi-year replacement schedules from recreational consumers purchasing through specialized distributors.
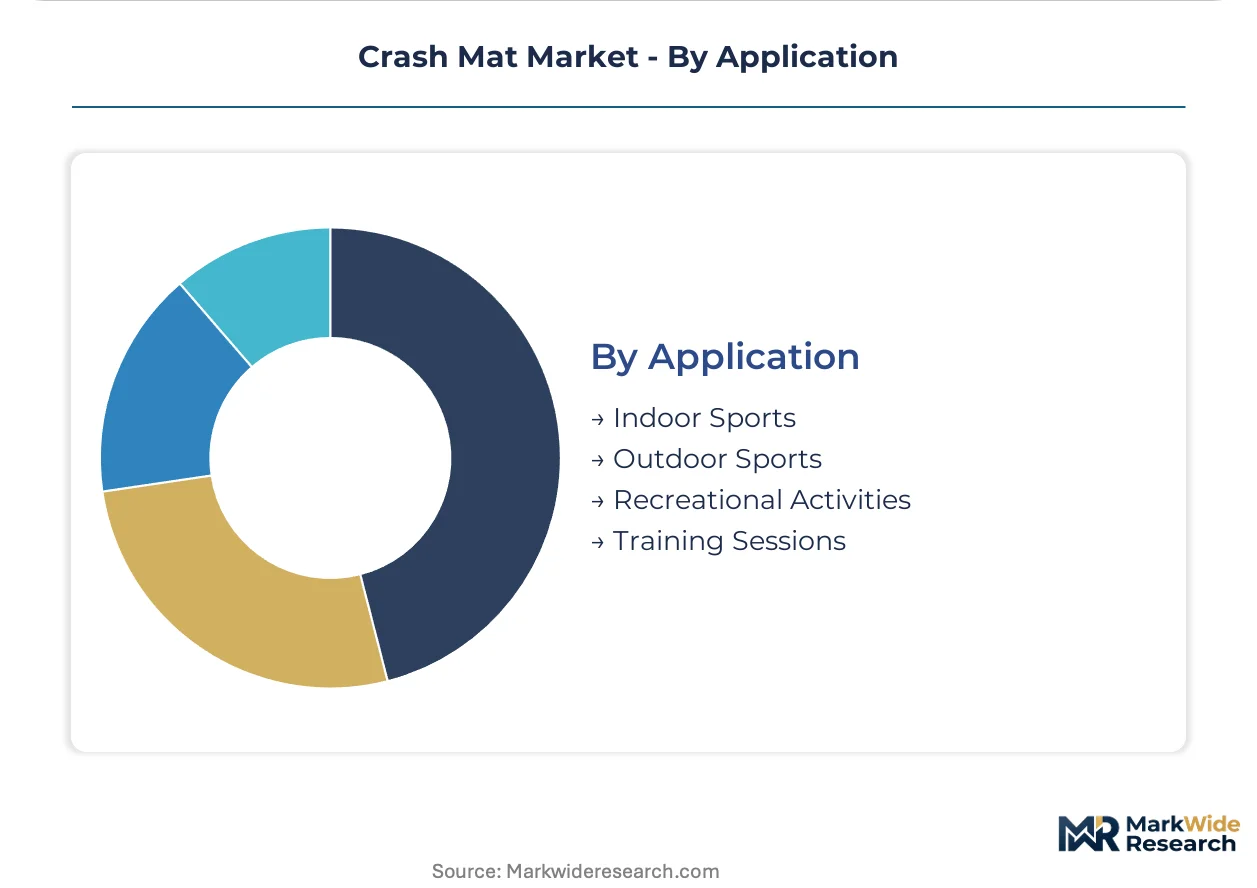
- Indoor Sports:Gymnastics programs and competitive training facilities drive specification-grade procurement with embedded sensor integration emerging for performance analytics. Smart-sensor-enabled mats tracking impact metrics introduce emerging liability frameworks under the EU AI Act.
- Outdoor Sports:Alpine recreation zones in Austria and Switzerland generate demand for weather-resistant portable crash pads. Black Diamond and Petzl anchor premium positioning through alpine equipment heritage and UIAA safety protocol integration.
- Recreational Activities:Consumer bouldering and home gym installations fragment through direct-to-channel distribution.
- Training Sessions:Military and professional athletic programs standardize on certified impact surfaces.
Indoor sports holds the largest share; outdoor sports is expanding most quickly on alpine recreation infrastructure investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
School districts and defense procurement offices concentrate crash mat demand across distinct national markets, each shaped by local safety certification regimes and industrial cluster configurations.
United States
Military obstacle course modernization and public education capital cycles drive procurement volumes. EPA foam emissions guidelines compel manufacturers toward certified EVA formulations. The Southeast industrial corridor hosts contract fabricators supplying defense training installations with cross-linked polyethylene assemblies.
Germany
Gymnastics federation equipment standards and Bundeswehr training infrastructure refresh programs sustain demand. REACH Annex XVII phthalate restrictions accelerate PVC binder phase-outs across Rhineland manufacturing clusters. Cologne-Düsseldorf foam compounders dominate high-performance substrate supply for CE-certified installations.
France
Municipal sports facility hygiene mandates prioritize sanitizable vinyl-top surfaces for gymnastics tenders. The country's national chemical regulator enforces disclosure timelines that compress supplier qualification periods. Lyon-based fabricators capture premium positioning in commercial facility segments.
Italy
Regional gymnastics consortiums consolidate purchasing through specialized distributors rather than turnkey contractors. EU AI Act liability frameworks emerge for smart-sensor-enabled training surfaces. Emilia-Romagna hosts mid-scale foam converters serving Mediterranean facility operators.
Switzerland
Alpine recreation infrastructure investment generates demand for weather-resistant portable crash pads. Swissmedic-equivalent technical standards for recreational equipment align with UIAA safety protocols. Zurich-Geneva corridor distributors anchor premium outdoor bouldering supply chains.
Crash Mat Market Competitive Environment
Player mix skews toward specialized foam fabricators and alpine equipment heritage brands competing across distinct certification tiers. Market structure fragments between regional CE-certified converters and vertically integrated outdoor recreation specialists. Strategic archetypes include defense-focused compounders, school district contract manufacturers, and premium alpine equipment providers. Competitive moves concentrate on material certification acceleration and smart-sensor technology licensing.
Among heritage alpine equipment providers, Black Diamond and Petzl occupy premium positioning vectors in outdoor crash pad categories. EDELRID represents the European technical equipment specialist archetype with established UIAA protocol integration. These three exemplify how safety certification credibility transfers across adjacent verticals to anchor bouldering mat market presence.
| Leading Market Players |
|---|
| Organic Climbing |
| Mad Rock Climbing |
| Black Diamond |
| Resilite |
| EDELRID |
| Petzl |
| Evolv |
| Tumbl Trak |
| Metolius |
| Others |
Value Chain & Pricing Dynamics
CE certification under EN 12503 gates both supplier qualification and price differentiation simultaneously, compressing tender eligibility for uncertified converters while enabling certified compounders to capture margin premiums across European gymnastics procurement.
Pricing Analysis
Cost-plus contracts with crude oil derivative indexation dominate military and school district procurement, tying mat pricing to polyurethane feedstock volatility. Price differentiation stems from certification tier—CE-marked surfaces command premiums over uncertified alternatives—and surface sanitization grade, with vinyl-top assemblies priced above standard foam cores. Cost compression in standard foam tiers is intensifying because petrochemical input volatility squeezes contract manufacturer margins. School districts exhibit highest price sensitivity due to capital budget constraints, while defense procurement offices prioritize standardized impact ratings over unit cost.
Supply Chain Analysis
Germany and the United States anchor high-performance foam substrate production, with Rhineland compounders supplying CE-certified assemblies and Southeast U.S. fabricators serving defense installations. Raw material dependencies center on isocyanates for polyurethane cores, ethylene-vinyl acetate granules for REACH-compliant binders, and reinforced vinyl sheeting for sanitizable surfaces. Single-source vulnerability concentrates in Rhineland industrial clusters, where geographic concentration creates procurement risk for facility operators dependent on German imports. Distribution runs through specialized foam fabricators with direct certification rather than turnkey gymnasium contractors, fragmenting channel control toward regional converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Performance analytics subscriptions for sensor-enabled training mats represent a service-attach opportunity expanding faster than hardware shipments, as facilities seek impact-metric data to justify premium equipment spend and reduce injury liability exposure.
For Market Incumbents: Fortify certification moats by accelerating EVA compound sourcing partnerships ahead of REACH Annex XVII enforcement deadlines, while consolidating distribution relationships with municipal procurement offices in France and Italy where channel fragmentation threatens volume concentration. Threat substitution from cross-linked polyethylene assemblies in military segments demands backward integration into certified polymer supply chains to defend margin position. For New Entrants and Emerging Players: Smart-sensor calibration and data platform services represent a service-layer gap where incumbents under-serve, creating white-space for specialized software providers to attach recurring revenue to mat hardware deployments. The most penetrable segment sits with mid-scale commercial gymnastics facilities in Benelux municipal procurement, where CE certification requirements have disqualified legacy converters. A direct-to-facility technical sales model bypassing traditional equipment distributors accelerates initial traction. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across sensor-integrated mat sub-segments as embedded electronics commoditize and software development costs amortize across hardware volumes. Long-term viability over the coming decade favors compounders with certified EVA supply chains and established CE marking pathways. The signal to watch is Bundeswehr and U.S. Department of Defense standardization mandates for cross-linked polyethylene specifications, which would revalue substrate specialists with military procurement relationships.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Compound Sourcing | EVA certification unlocks tender eligibility across German school districts and French municipal facilities. |
| Smart-Sensor Platform Development | Impact-metric tracking introduces EU AI Act liability frameworks requiring software governance investment. |
| Military Procurement Certification | U.S. Department of Defense standardization mandates drive bulk cross-linked polyethylene assembly contracts. |
| Regional Distribution Consolidation | Direct CE-certified fabricator relationships capture volume shifting away from turnkey gymnasium contractors. |
| Alpine Equipment Brand Extension | UIAA safety protocol credibility transfers to weather-resistant portable crash pad premium positioning. |
Study Parameters
The analysis maps foam mat, vinyl mat, rubber mat, and carpet mat sub-sectors, each validated through procurement officers at school districts, facility managers at commercial gymnastics centers, defense training infrastructure planners, and foam compound technical directors. Primary interviews combined with secondary validation from customs trade data, SEC filings of publicly listed equipment manufacturers, REACH Annex XVII substance restriction databases, and EN 12503 certification registries. Bottom-up shipment estimates triangulated against top-down facility installation capacity across the analysis window.
Consistency checks validated volume and value outputs against defense modernization budget disclosures, municipal sports facility capital expenditure patterns, and alpine recreation infrastructure investment announcements. Segmentation dimensions modeled include product type, end-user category, material compound, and application intensity across the projection horizon. CAGRs derived from replacement cycle analysis, regulatory phase-out timelines, and sensor adoption curves in competitive training environments.
Forecasts assume regulatory continuity in REACH Annex XVII and EPA foam emissions frameworks; material policy shifts would require re-modeling substitution timelines and supplier qualification periods. Specific risks include petrochemical price volatility, CE certification backlog extensions, and EU AI Act liability interpretation divergence across member states. Recalibration cycles align with material shifts in defense procurement standardization mandates and municipal hygiene regulation enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Global Sports Bottle Market
Household Items
Wipes Market
Household Items
Dry and Wet Wipes Market
Household Items
Air Mattress Market
Household Items
Smart Fork Market
Household Items
Europe Handheld Vacuum Cleaners Market
Household Items
Thermos Drinkware Market
Household Items
Smart Spin Mop Market
Household Items
Multi Pocket Holders Market
Household Items
Memory Foam Market
Household Items
Cookware Market
Household Items
Permanent Marker Market
Household Items
Umbrella Market
Household Items
Smart Bathroom Products Market
Household Items
Mosquito Trap Market
Household Items
Dishwasher Detergent Market