
 Dishwasher Detergent Market | 2026-2036
Dishwasher Detergent Market Size, Share, and Industry Trends Forecast 2026-2036
Dishwasher Detergent Market Analytics
Buyer concentration across the commercial segment is rebalancing as institutional foodservice operators consolidate purchasing through national supply contracts. Henkel leverages its European manufacturing footprint to serve large-scale hospitality chains with specialized enzymatic formulations. Procter & Gamble sustains brand loyalty in North American residential channels through concentrated pod formats. Ecolab dominates the industrial application segment with on-site dispensing systems tied to water-treatment service contracts.
Dishwasher detergent comprises surfactant blends, alkaline builders, enzymes, and rinse aids engineered to remove food soils, hard-water minerals, and grease from dishware in automated washing systems. Pod and tab formats now lead value generation due to precise dosing control and reduced packaging waste, while liquid formulations retain volume share among price-sensitive residential buyers. The enzymatic formulation segment captures expanding margin pools as protease and amylase additives enable lower-temperature wash cycles that reduce energy consumption in commercial operations.
EPA Safer Choice labeling in the United States and REACH chemical registration in Europe constrain phosphate content and volatile organic compound thresholds, compelling reformulation investments across manufacturers. The EU Green Deal's packaging waste directives are accelerating shifts from plastic bottles to dissolvable film pouches and cardboard-based sachets. Stakeholders must monitor evolving biodegradability certification requirements and water-temperature regulations that determine enzyme efficacy specifications and product positioning strategies.
Market Dynamics
Enzymatic formulation chemistry is compressing wash-cycle temperatures in commercial kitchens, forcing incumbent suppliers to retool manufacturing lines for protease and amylase stability while EU packaging directives accelerate film-dissolvable pod adoption.
Growth Catalysts
- EU Green Deal packaging mandates:Dissolvable PVA film pouches replace rigid plastic containers in German and French institutional procurement, eliminating disposal costs for hospitality operators.
- Low-temperature enzymatic washing:Protease-amylase blends enable 45°C commercial cycles, cutting energy expenditure for hotel chains facing utility price volatility.
- China:Rapid expansion of centralized foodservice facilities in tier-one cities concentrates demand for bulk concentrated liquids with automated dispensing.
Market Restraints
- Phosphate raw material constraints:REACH authorization lists restrict sodium tripolyphosphate sourcing, elevating reformulation costs for legacy alkaline builder systems.
- Enzyme supply concentration:Three specialty chemical producers control industrial protease fermentation capacity, creating single-source vulnerability for mid-tier formulators.
- Technical performance floor:Enzymatic systems fail below 40°C water temperature, excluding deployment in facilities with inconsistent boiler infrastructure.
Strategic Opportunities
- India institutional segment:Underpenetrated commercial dishwasher base in quick-service restaurant chains offers first-mover advantage for pod-format entrants.
- Water-treatment service bundling:Detergent dispensing systems paired with reverse-osmosis maintenance contracts lock in multi-year hospitality procurement.
- US EPA Safer Choice certification:Federal purchasing preference programs create guaranteed offtake channels for phosphate-free formulations in government cafeterias.
Industry Challenges
- Enzyme stability expertise gap:Formulation chemists with protease encapsulation experience command premium compensation, constraining R&D velocity at regional manufacturers.
- Biodegradability certification timelines:OECD 301B testing protocols require 28-day validation cycles, delaying product launches for reformulated surfactant blends.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dishwasher Detergent Market |
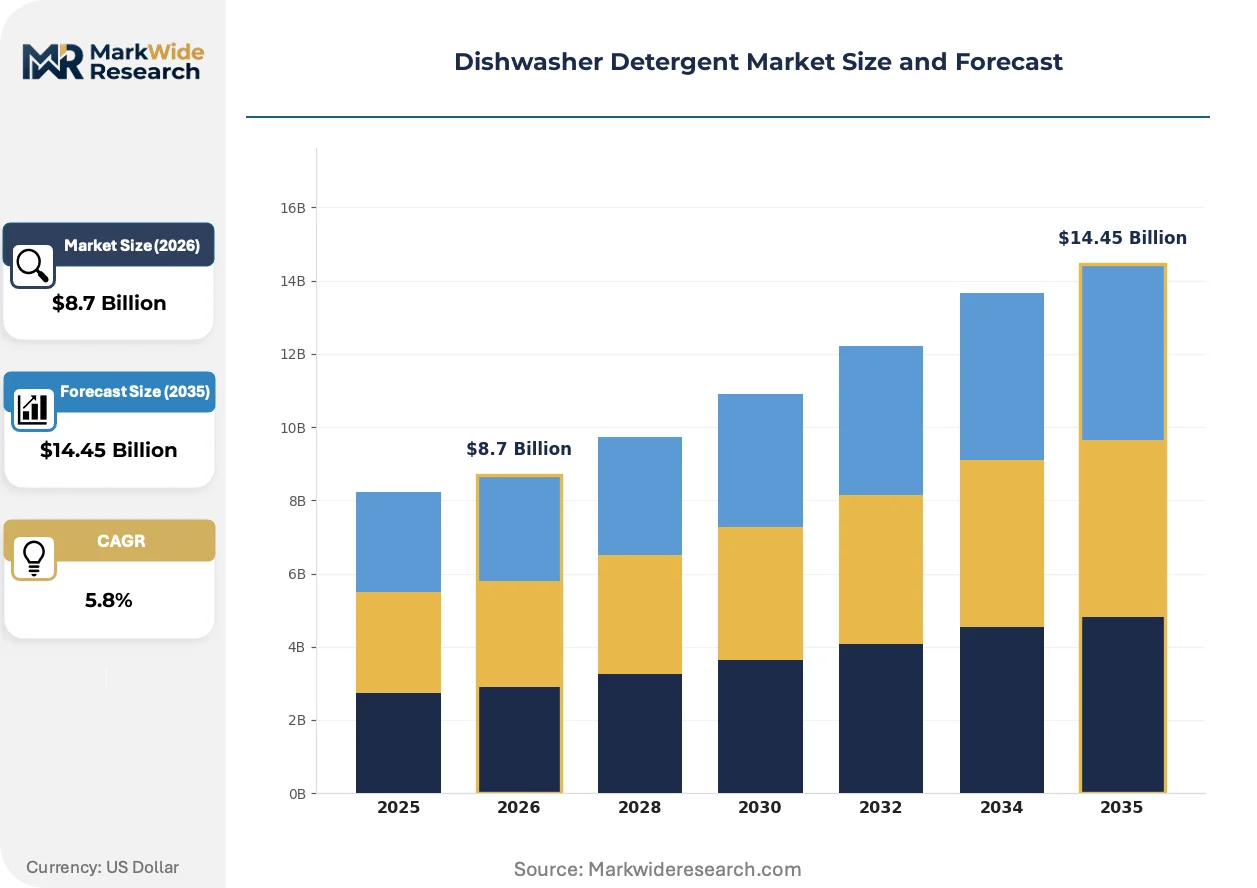
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pods, Liquid, Powder, Tabs Formulation: Non-toxic, Enzymatic, Biodegradable, All-in-one Application: Residential, Commercial, Industrial, Institutional Packaging Type: Bottles, Pouches, Buckets, Sachets |
| Companies Covered | Henkel, Dongguan UFine Daily Chemical, Procter & Gamble, Colgate-Palmolive, Sunshine Industrial Corporation, Reckitt Benckiser, Ecolab, Finice, Unilever, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dishwasher Detergent Market Evolving Landscape
Automation in dispensing hardware and film-based packaging is converging with biological cleaning chemistry to redefine how commercial kitchens contract for warewashing consumables.
Dissolvable film pod technology is modularizing detergent delivery architecture. Multi-chamber pouches separate enzymes, builders, and rinse aids until water contact, preserving efficacy in extended storage. Institutional buyers in Germany and France are transitioning procurement to these formats at pace. The technology is modularizing supplier relationships, enabling chemical providers to bypass traditional janitorial distribution and contract directly with hospitality groups.
REACH authorization procedures for phosphates are tightening formulation constraints across European manufacturing. ECHA's sunset date approach for tripolyphosphate derivatives forces accelerated substitution with citrate and silicate builders. Commercial segment buyers in Italy and Spain face compressed supplier qualification timelines as legacy stocks deplete, shifting volume toward pre-certified enzymatic alternatives.
Foodservice operators are consolidating purchasing through group procurement organizations, displacing decentralized restaurant-level ordering. National hospitality chains in the United States now mandate uniform detergent specifications across property portfolios, eliminating regional supplier fragmentation. This concentration is most visible in the limited-service restaurant vertical, where procurement directors negotiate master service agreements covering chemicals, equipment, and technical support.
Dishwasher Detergent Market Segmentation
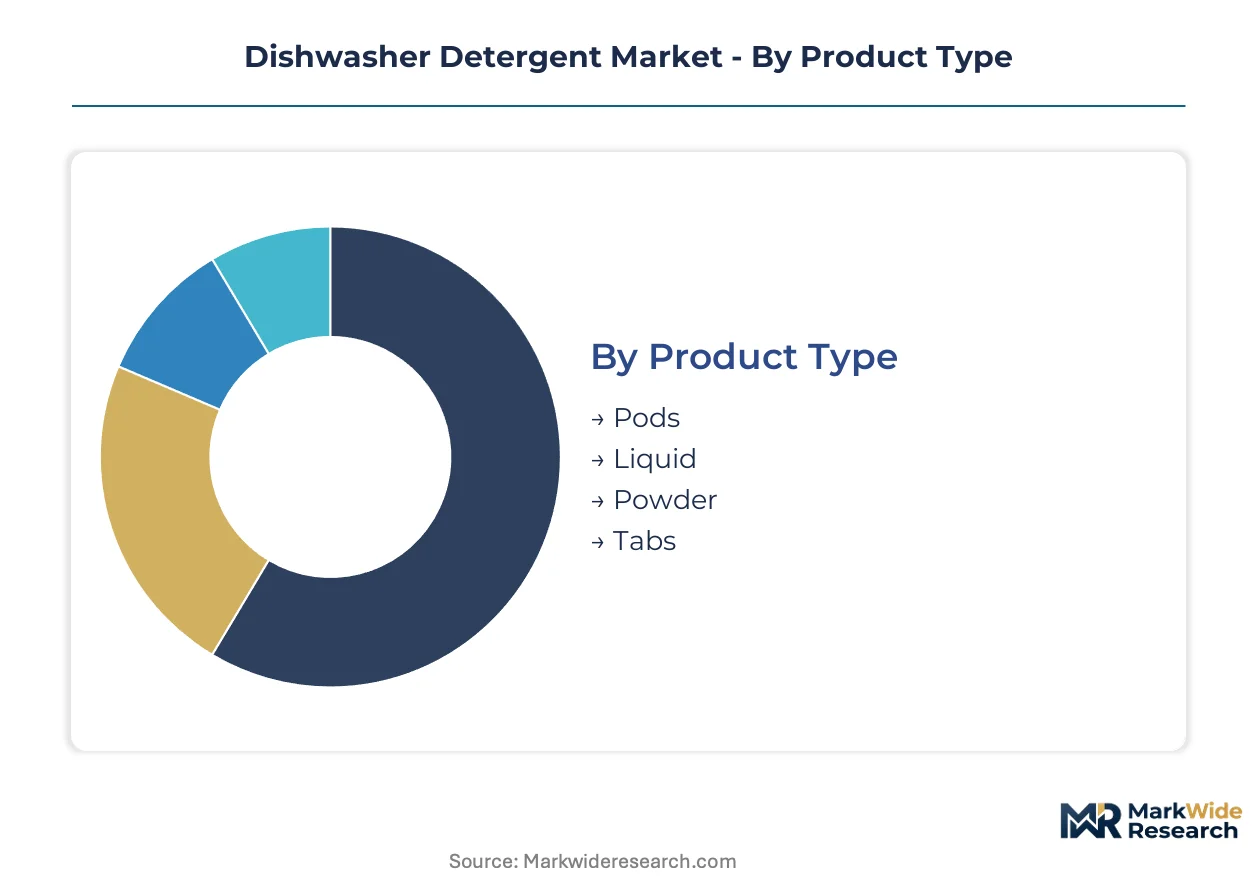
Dishwasher detergent segmentation reflects divergent performance requirements across temperature regimes, dosing precision needs, and regulatory compliance thresholds. Format and chemistry choices directly determine energy consumption, water treatment compatibility, and procurement contract structures in institutional channels.
Product Type:
Standardization dominates pod and tab formats with fixed dosing protocols, while liquids and powders permit user-adjusted concentration flexibility for variable soil loads.
- Pods:Pre-measured PVA film pouches encapsulate multi-chamber chemistries separating enzymes, builders, and rinse aids until dissolution. German hospitality chains favor these for labor elimination and reduced packaging waste under EU Green Deal mandates.
- Liquid:Pump-dispensed or pour formats allow concentration adjustment for hard-water conditions and heavy soil loads. Price-sensitive residential buyers in North America sustain volume demand despite pod encroachment.
- Powder:Granular alkaline builders with surfactant coatings require manual scoop dosing. Budget institutional buyers with on-site water softening maintain procurement for bulk economy.
- Tabs:Compressed solid blocks dissolve gradually through wash cycles. Commercial kitchens with single-rack machines prefer these for simplified inventory management.
Leading the category by volume: Liquid. Growing fastest: Pods.
Formulation:
Cost tiers stratify from commodity alkaline builders through premium enzymatic systems with protease stability engineering.
- Enzymatic:Protease-amylase blends hydrolyze protein and starch soils at 45°C wash temperatures, cutting energy expenditure for hotel operators facing utility volatility. REACH phosphate restrictions in Europe accelerate substitution toward these systems.
- All-in-one:Integrated builder-enzyme-rinse aid chemistries eliminate separate additive procurement. French and German institutional buyers consolidate specifications to reduce supplier qualification overhead.
- Biodegradable:Surfactant chains meeting OECD 301B degradation protocols command certification premiums. EPA Safer Choice labeling in the United States creates federal procurement preference channels.
- Non-toxic:Elimination of chlorine bleach and synthetic fragrances targets childcare and healthcare facilities with indoor air quality protocols.
Steepest expansion trajectory: Enzymatic. Largest installed base: All-in-one.
Application:
Customer type determines contract structure, from transactional retail purchases to multi-year service agreements bundling chemicals and equipment maintenance.
- Commercial:Hotels, restaurants, and catering operations contract through group purchasing organizations for standardized specifications across property portfolios. Ecolab dominates with on-site dispensing systems tied to water-treatment service contracts.
- Residential:Individual households select formats through retail or e-commerce channels. Brand loyalty concentrates in North American markets with concentrated pod preferences.
- Institutional:Schools, hospitals, and government cafeterias mandate phosphate-free formulations under federal purchasing guidelines. EPA Safer Choice certification gates supplier eligibility.
- Industrial:Food processing and pharmaceutical manufacturing require validated cleaning protocols with documentation for audit trails. Specialized alkaline chemistries target equipment-specific soil profiles.
Highest contract value concentration: Commercial. Fastest policy-driven conversion: Institutional.
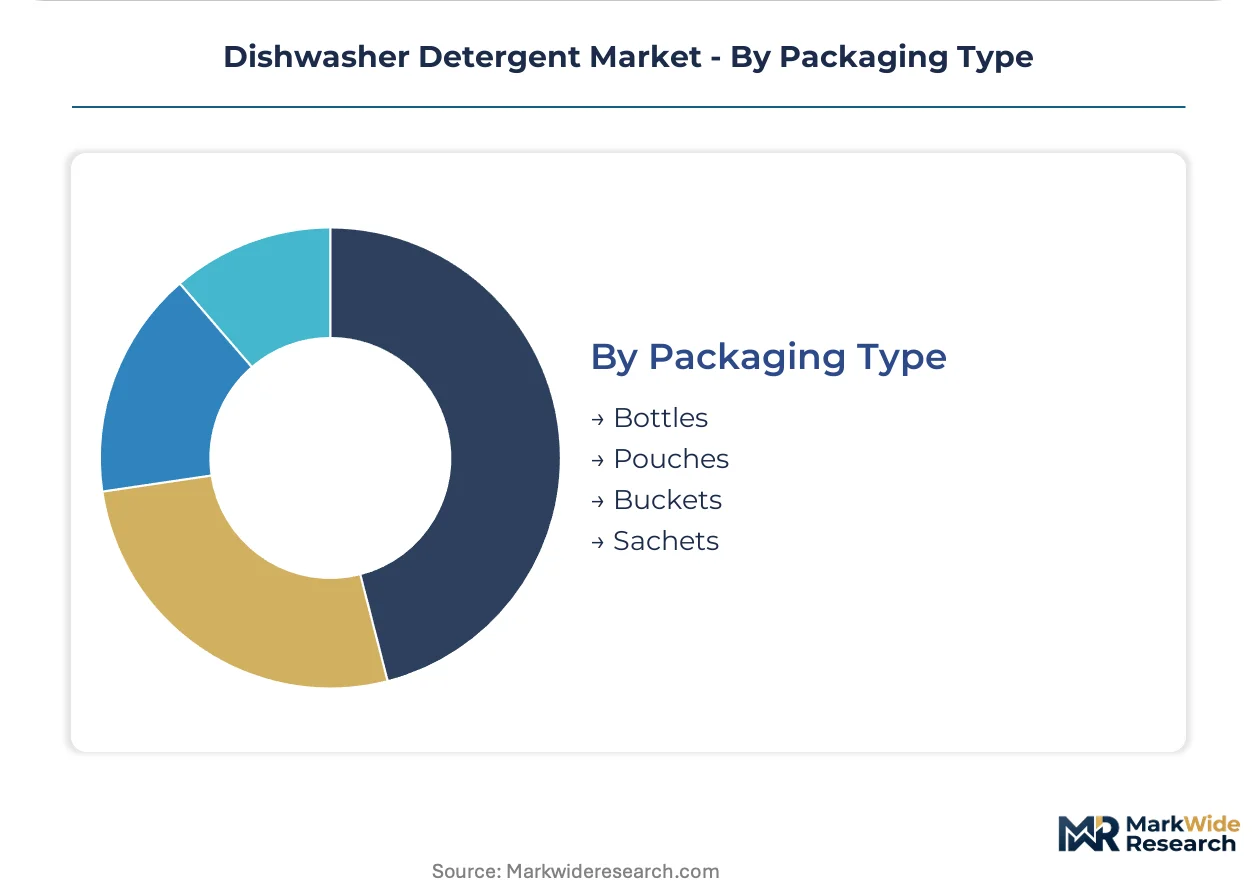
Packaging Type:
Supply concentration in film extrusion and blow-molding capacity shapes format availability and cost structures across geographies.
- Pouches:Flexible plastic or dissolvable film formats reduce shipping cube and disposal mass. EU packaging waste directives accelerate PVA film adoption in Germany and France.
- Bottles:HDPE containers dominate liquid detergent retail distribution. Recycling infrastructure gaps in emerging markets sustain format persistence despite regulatory pressure.
- Sachets:Single-dose paper or film packets target hospitality amenity programs and trial-size marketing. Water-soluble formats eliminate guest-facing plastic disposal.
- Buckets:Industrial-scale polyethylene containers serve commercial kitchens with high-volume automated dispensing systems. Refill protocols reduce per-use packaging intensity.
Dominant procurement format by volume: Bottles. Regulatory displacement target: Pouches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Phosphate rock deposits in Morocco and Florida anchor raw-material sourcing for alkaline builder chemistries, while fermentation capacity for industrial enzymes concentrates in Danish and Dutch biotech corridors. Manufacturing and formulation activity clusters around major detergent consumption centers where hospitality procurement and regulatory mandates intersect.
United States
EPA Safer Choice labeling drives federal cafeteria procurement toward phosphate-free enzymatic systems, while hospitality chains consolidate purchasing through group procurement organizations. The Southeast corridor from Atlanta to Orlando concentrates commercial kitchen equipment deployment for hotel and restaurant chains. California's Title 22 water discharge regulations accelerate adoption of low-temperature enzymatic formats in institutional facilities.
Germany
EU Green Deal packaging directives push hospitality operators toward dissolvable PVA film pouches, eliminating rigid plastic disposal costs. REACH sunset dates for tripolyphosphate derivatives force rapid reformulation toward citrate and silicate builders. The Rhine-Ruhr industrial belt hosts concentrated enzymatic fermentation capacity serving Central European formulators.
China
Centralized foodservice facilities in Shanghai and Beijing tier-one cities drive demand for bulk concentrated liquids with automated dispensing systems. The country's national chemical regulator enforces GB standards for surfactant biodegradability in industrial applications. Yangtze River Delta manufacturing clusters supply both domestic hospitality chains and export markets with powder and liquid formats.
India
Quick-service restaurant expansion in Mumbai and Delhi-NCR creates first-mover opportunities for pod-format entrants in underpenetrated commercial dishwasher bases. Bureau of Indian Standards certification requirements for cleaning chemicals constrain import channels. Gujarat chemical manufacturing corridors supply alkaline builders to domestic formulators serving institutional buyers.
France
ANSM and environmental agency oversight of chemical product registration compresses supplier qualification timelines as legacy phosphate stocks deplete. Institutional buyers in Paris and Lyon hospitality clusters consolidate specifications toward all-in-one enzymatic systems. The country's packaging waste extended producer responsibility schemes accelerate shifts from bottles to dissolvable film formats.
Dishwasher Detergent Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized enzymatic formulations and regional hospitality contracts. The vendor base stratifies between multinational chemical conglomerates with fermentation capabilities and regional formulators serving price-sensitive institutional channels. Three archetypes dominate: integrated enzyme manufacturers with captive detergent production, hospitality-focused service bundlers combining chemicals with equipment maintenance, and private-label specialists supplying retail concentration. Capacity expansion in protease fermentation and strategic partnerships for film-extrusion technology represent the dominant competitive vectors.
Within the integrated manufacturer tier, Henkel and Procter & Gamble exemplify archetypes combining enzymatic R&D with European and North American production footprints. Ecolab occupies a distinct position anchoring the service-bundling archetype through on-site dispensing systems tied to water-treatment contracts. Among Asia-Pacific-based formulators, Dongguan UFine Daily Chemical represents regional specialists targeting concentrated liquid formats for commercial kitchen automation.
| Leading Market Players |
|---|
| Henkel |
| Dongguan UFine Daily Chemical |
| Procter & Gamble |
| Colgate-Palmolive |
| Sunshine Industrial Corporation |
| Reckitt Benckiser |
| Ecolab |
| Finice |
| Unilever |
| Others |
Value Network & Pricing Analysis
Protease and amylase fermentation costs cascade through enzymatic formulation tiers, compressing margins for mid-tier formulators while concentrated pod formats capture premium positioning in German hospitality procurement.
Pricing Analysis
Service-bundling separates Ecolab's water-treatment-integrated dispensing contracts from unbundled chemical-only transactions. Three-tier pricing structure across premium enzymatic pods, standard all-in-one tablets, and economy alkaline powders reflects certification grade and volume scale. Pricing pressure stems from REACH-mandated phosphate reformulation elevating raw material substitution costs. Budget institutional buyers in Southern Europe exhibit highest price sensitivity, while North American hospitality chains prioritize performance consistency over unit economics.
Supply Chain Analysis
REACH authorization and EPA Safer Choice certification gate supplier eligibility for European and North American institutional channels. Enzyme fermentation capacity concentrates in Denmark and the Netherlands, while alkaline builder sourcing draws from Moroccan phosphate rock and Chinese silicate processing. Single-source vulnerability in industrial protease supply creates structural risk for formulators lacking captive fermentation. Distribution runs through janitorial supply houses in fragmented retail channels and direct national contracts in consolidated hospitality procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around formulators with captive enzyme production and certified sustainable chemistry, as REACH sunset dates and EPA procurement mandates force exit of legacy phosphate-dependent suppliers.
For Market Incumbents: To counter mid-tier erosion from private-label enzymatic entrants, Henkel and Procter & Gamble should deepen backward integration into protease encapsulation technology and lock in multi-year hospitality contracts through equipment-lease bundling. Securing OECD 301B pre-certification for surfactant blends ahead of EU Green Deal packaging enforcement preserves pricing power in institutional channels.
For New Entrants and Emerging Players: Launch via direct-to-hospitality contracting models targeting underpenetrated quick-service restaurant chains in India and Southeast Asia with compact pod formats bypassing established janitorial distribution. White-space concentration exists in tier-two Chinese cities where centralized foodservice facilities lack automated dispensing integration. Water-treatment service partnerships provide the most viable go-to-market angle against entrenched chemical-only incumbents.
For Investors and Strategic Acquirers: Distressed-cycle entries favor regional formulators with validated enzymatic pipelines and BIS certification in India, where Bureau of Indian Standards barriers constrain import competition. Long-term viability hinges on fermentation asset ownership rather than toll-manufacturing arrangements. Watch for ECHA tripolyphosphate authorization withdrawals as the inflection signal accelerating consolidation toward pre-certified biodegradable alternatives.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Enzyme Fermentation | Captive protease production insulates Ecolab and Henkel from Novozymes supply concentration. |
| PVA Film Extrusion Partnership | Dissolvable pouch capacity secures German hospitality procurement under EU Green Deal mandates. |
| Water-Treatment Service Bundling | On-site dispensing contracts lock in multi-year revenue visibility for institutional chemical suppliers. |
| OECD 301B Pre-Certification | Biodegradability validation accelerates supplier qualification timelines as legacy phosphate stocks deplete. |
| India BIS Certification Investment | Regulatory compliance opens quick-service restaurant procurement channels in underpenetrated commercial kitchen base. |
Research Methodology
Multi-period observation of enzyme price indices, REACH authorization timelines, and hospitality procurement contract structures anchored the trend analysis, supplemented by interviews with formulation R&D directors, institutional procurement managers at hotel chains, janitorial supply distributors, and ECHA regulatory affairs specialists. Secondary validation drew from customs trade data for surfactant imports, SEC 10-K chemical segment disclosures, EU packaging waste directive implementation reports, and OECD biodegradability testing protocols. Bottom-up volume modeling across pod, liquid, powder, and tablet formats triangulated against top-down spending estimates from national hospitality association procurement surveys.
Segment-weighting applied differential growth assumptions across enzymatic, all-in-one, biodegradable, and non-toxic formulation tiers, with format-level projections for PVA film pouches, HDPE bottles, and industrial buckets. CAGRs were derived from regression analysis of historical volume trends against regulatory enforcement schedules and energy price volatility indices. Forecast inputs included commercial kitchen equipment installation rates, group purchasing organization contract renewal cycles, and boiler infrastructure upgrade pipelines affecting low-temperature wash adoption.
REACH sunset date acceleration, EPA Safer Choice program expansion, and protease fermentation supply disruptions are the dominant revision risks to modeled outcomes. Forecasts reflect assumptions about regulatory enforcement consistency and enzyme stability technology maturation. A model refresh is warranted upon material change in ECHA authorization timelines or hospitality sector utility cost trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Multi Pocket Holders Market
Household Items
Powered Lawn Mowers Market
Household Items
Desktop Air Purifier Market
Household Items
Brush Cover Market
Household Items
Global Wet Vacuum Cleaner Market
Household Items
Home Scales Market
Household Items
Stick Vacuum Cleaner Market
Household Items
Smart Drying Racks Market
Household Items
Drinkware Accessories Market
Household Items
GCC Gas Hobs Market
Household Items
Range Hood Cleaning Service Market
Household Items
Enameled Cookware Market
Household Items
Ironing Boards Market
Household Items
Book Light Market
Household Items
Canada Digital Showers Market
Household Items
Smart Toilet Market