
 Luxury Personal Care and Cosmetics Market | 2026-2036
Luxury Personal Care and Cosmetics Market Size, Share, and Industry Trends Forecast 2026-2036
Luxury Personal Care and Cosmetics Market Foresight
Biotechnology-driven ingredient synthesis is reconfiguring how luxury skincare products achieve efficacy claims and sustainability credentials. L'Oréal leverages its integrated research platforms to develop bio-fermented actives at scale. Estée Lauder Companies anchors its competitive stance through heritage brand equity and controlled distribution in high-traffic retail corridors. Shiseido navigates regional preferences with localized formulation science across its portfolio.
Luxury personal care and cosmetics encompass high-performance topical preparations formulated with concentrated active ingredients, proprietary delivery systems, and refined sensorial profiles designed for premium consumer experiences. These products typically undergo dermatological testing, stability validation, and packaging integrity assessments exceeding conventional mass-market benchmarks. Skincare commands the dominant margin pool due to repeat purchase frequency and clinical positioning. Fragrance competes through exclusivity architectures and limited-edition release cycles. E-commerce distribution represents the fastest-expanding channel as digital try-on technologies and personalized recommendation engines reshape discovery behavior.
FDA oversight governs product safety and labeling claims in the United States, while REACH and the EU Green Deal mandate ingredient transparency and environmental impact reduction across European markets. China's NMPA and SAMR enforce registration requirements and advertising standards that determine market access for imported luxury brands. Stakeholders must weigh regulatory compliance investments against speed-to-market advantages as jurisdiction-specific requirements proliferate.
Market Dynamics
Biotechnology-driven ingredient synthesis is collapsing the traditional trade-off between clinical efficacy and sustainability credentials, forcing reformulation cycles that compress product development timelines from 24 months to under 14 months for leading portfolios.
Growth Catalysts
- EU Green Deal compliance mandates:REACH framework revisions accelerate bio-based ingredient substitution across European formulations, creating first-mover advantages for brands with certified green chemistry pipelines.
- Urban affluent consumption clusters:Dense metropolitan centers in China and the United States concentrate purchasing power for premium skincare rituals with repeat purchase frequencies exceeding mass-market benchmarks by 3-4x.
- Bio-fermentation scale-up:Industrial biotechnology platforms now produce rare actives—resveratrol, squalane, ceramides—at cost structures competitive with petrochemical-derived equivalents.
Market Restraints
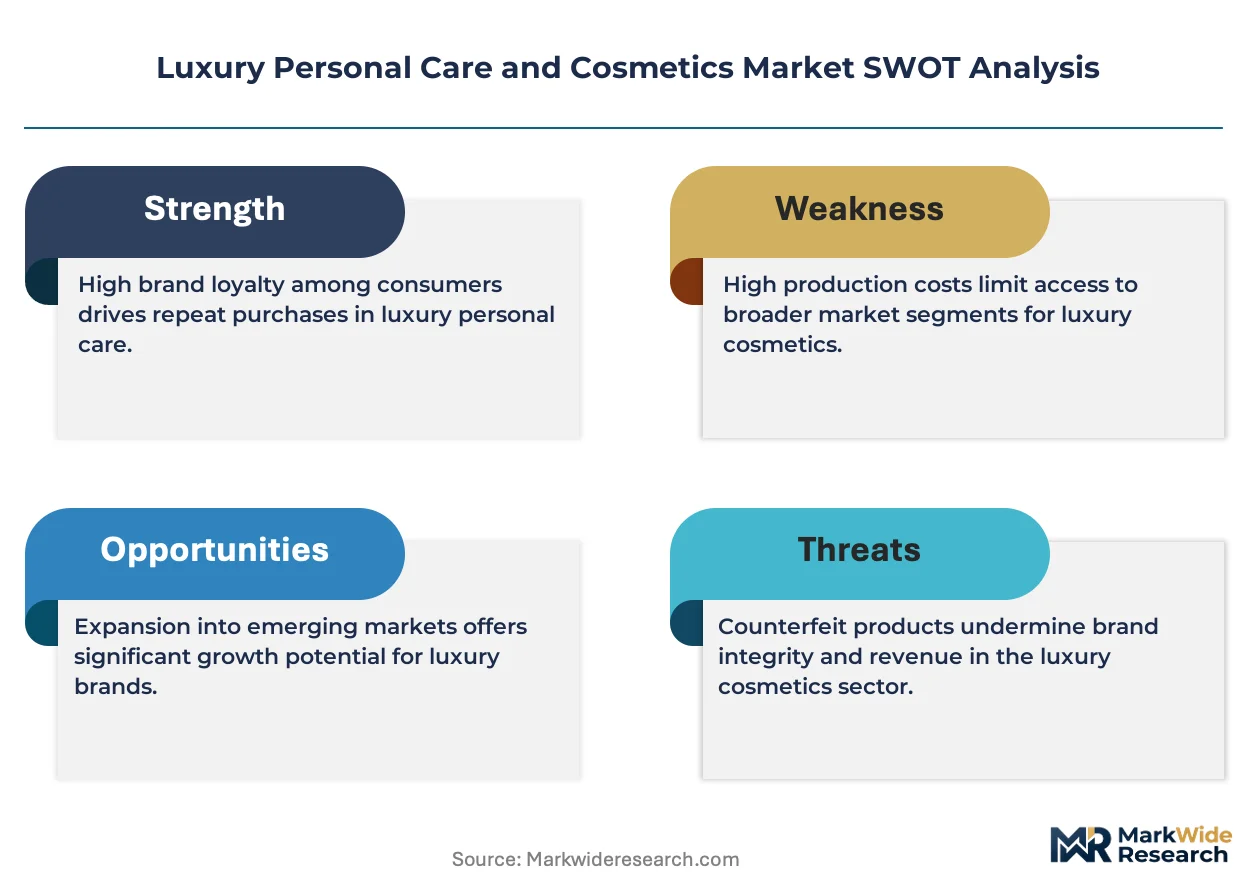
- Raw material concentration risk:Over 60% of global fragrance compound supply originates from a narrow corridor of Grasse-region specialists and Southeast Asian botanical extractors, exposing formulations to climate and geopolitical disruption.
- Regulatory fragmentation friction:Divergent NMPA, FDA, and ECHA safety dossier requirements force parallel testing regimes that add 8-12 months to market entry timelines for multi-territory launches.
- Technical substitution ceiling:Synthetic biology-derived alternatives to certain animal-derived actives—specifically collagen peptides and elastin—still fail to match sensory performance thresholds for ultra-premium positioning.
Strategic Opportunities
- India's emerging luxury corridor:Mumbai and Delhi NCR exhibit underpenetrated demand for clinical-positioned skincare relative to per-capita income growth, with domestic duty structures favoring local manufacturing partnerships.
- Waterless formulation formats:Solid shampoo bars, anhydrous balms, and powder-to-foam cleansers reduce shipping weights by 70-80% while aligning with EU packaging waste directives.
- AI-driven personalization engines:Convergence of computer vision skin analysis and generative formulation design enables mass-customized regimens at price points accessible to upper-mass consumers.
Industry Challenges
- Formulation chemist scarcity:The specialized expertise required for stability engineering of bio-fermented actives concentrates within a small cohort of European and Japanese technical institutes, constraining R&D scaling.
- Carbon accounting complexity:Scope 3 emissions verification across multi-tier ingredient supply chains demands capex investment in blockchain traceability infrastructure that mid-tier brands struggle to amortize.
- Cross-border IP enforcement:Proprietary delivery system patents face systematic challenge in jurisdictions with weaker cosmetics-specific IP frameworks, eroding exclusivity windows for innovation leaders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Luxury Personal Care and Cosmetics Market |
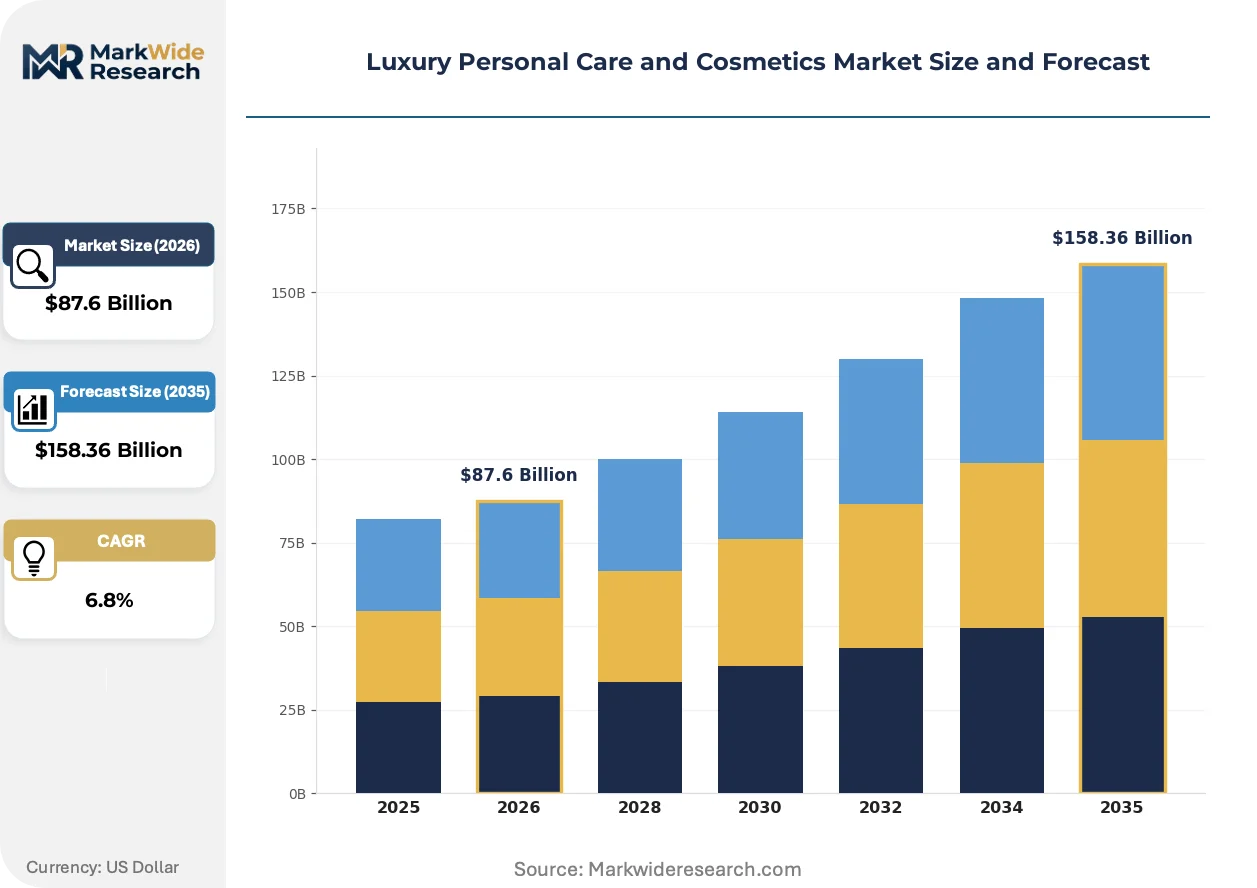
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $158.36 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skincare, Makeup, Fragrance, Haircare Price Tier: Premium, Super Premium, Mass Prestige, Value Distribution Channel: Department Stores, Specialty Stores, E-commerce, Direct Sales Customer Type: Millennials, Gen Z, Affluent Consumers, Professionals |
| Companies Covered | L'Oréal, Estée Lauder Companies, LVMH Moët Hennessy Louis Vuitton, Shiseido, Coty Inc., Chanel, Kao Corporation, Unilever, Puig, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Luxury Personal Care and Cosmetics Market Shifts & Advancements
Digital discovery mechanisms and biomanufacturing advances are restructuring how luxury personal care products reach consumers and how their efficacy claims are validated, compressing traditional gatekeeper roles.
Precision fermentation is collapsing the cost curve for rare botanical actives previously constrained by agricultural yield volatility. Brands with captive bioreactor capacity now produce customized ceramide complexes and polyphenol extracts at batch scales unachievable through conventional cultivation. High-net-worth consumers in Shanghai and New York are adopting these bio-identical formulations at rates that outpace heritage extraction-based equivalents, compressing the premium positioning window for traditional sourcing narratives.
REACH authorization requirements for fragrance allergens are forcing disclosure of previously proprietary compound compositions. ECHA's expanded SVHC candidate list now captures synthetic musks and certain phthalate alternatives, compelling reformulation of legacy scent architectures. European prestige fragrance houses are responding with "clean fragrance" sub-lines that preempt regulatory action while commanding 15-25% price premiums through transparency positioning.
Social commerce live-streaming has displaced department store counter discovery for cohorts under 35 in China and Southeast Asia. Influencer-hosted sessions on Douyin and Xiaohongshu now generate 40-50% of new customer acquisition for skincare launches, replacing the sampling-and-consultation model that anchored prestige beauty for decades. This channel migration is most visible in tier-2 Chinese cities where physical luxury retail penetration remains thin but smartphone commerce penetration exceeds 90%.
Luxury Personal Care and Cosmetics Market Segmentation
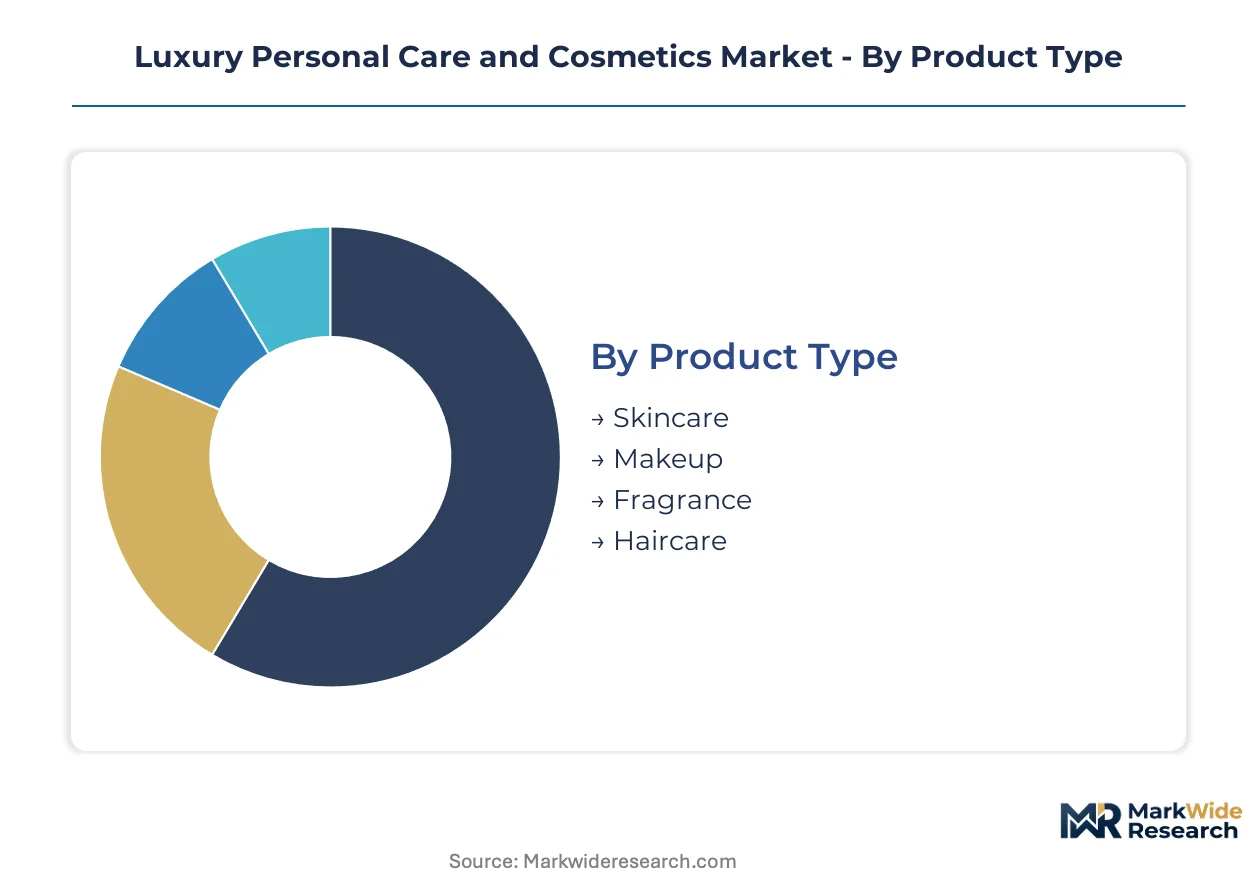
Luxury personal care and cosmetics demand fragments across technical performance tiers, generational purchasing behaviors, and channel-specific discovery mechanisms. Each segmentation axis reveals distinct margin pools and regulatory exposure profiles that determine portfolio construction priorities.
Product Type:
Mature clinical-positioned categories coexist with emerging sensorial formats as biotechnology reshapes efficacy validation standards.
- Skincare:High-concentration active formulations with dermatological testing protocols command repeat purchase frequencies exceeding other categories. Affluent consumers in Shanghai and New York sustain demand for bio-fermented ceramide complexes and precision-extracted polyphenols despite premium pricing.
- Fragrance:Scent architectures built on proprietary compound compositions face ECHA disclosure mandates under expanded SVHC candidate lists. European prestige houses are pivoting toward transparency-positioned "clean fragrance" sub-lines that preempt regulatory action.
- Makeup:Hybrid skincare-makeup formulations with SPF and treatment claims now dominate prestige launches.
- Haircare:Scalp-focused clinical treatments and bond-repair technologies are capturing share from traditional conditioning formats.
Skincare retains volume leadership; fragrance holds the steepest expansion curve through exclusivity architectures and limited-edition release cycles.
Price Tier:
Cost stratification reflects ingredient sourcing intensity, biomanufacturing scale requirements, and packaging integrity investments rather than mere brand markup.
- Super Premium:Captive bioreactor capacity and rare botanical cultivation partnerships define formulations priced at the apex of accessible luxury. Domestic consumption in China's tier-1 cities outpaces outbound tourism channels for this tier.
- Premium:Bio-based ingredient substitution at scale concentrates competitive positioning here as EU Green Deal compliance costs amortize across volume.
- Mass Prestige:AI-driven personalization engines are compressing entry price points for customized regimens previously restricted to higher tiers.
- Value:Waterless formulation formats—solid bars and powder-to-foam cleansers—reduce shipping weights while maintaining sensorial profiles.
Super Premium captures margin concentration; Mass Prestige is expanding most quickly through digital channel democratization.
Distribution Channel:
Customer acquisition economics vary dramatically between high-traffic physical corridors and algorithm-driven digital discovery environments.
- E-commerce:Computer vision skin analysis and generative recommendation engines now generate 40-50% of new customer acquisition for skincare launches in China. Douyin and Xiaohongshu live-streaming has displaced department store sampling for cohorts under 35.
- Department Stores:Controlled placement in premium retail corridors remains essential for fragrance discovery and gift purchasing occasions.
- Specialty Stores:Curated assortments with trained consultation staff sustain relevance for complex regimen-building.
- Direct Sales:Personalized relationship management retains traction in markets with thinner physical luxury retail penetration.
E-commerce is gaining share fastest; Department Stores defend position through experiential service differentiation.
Customer Type:
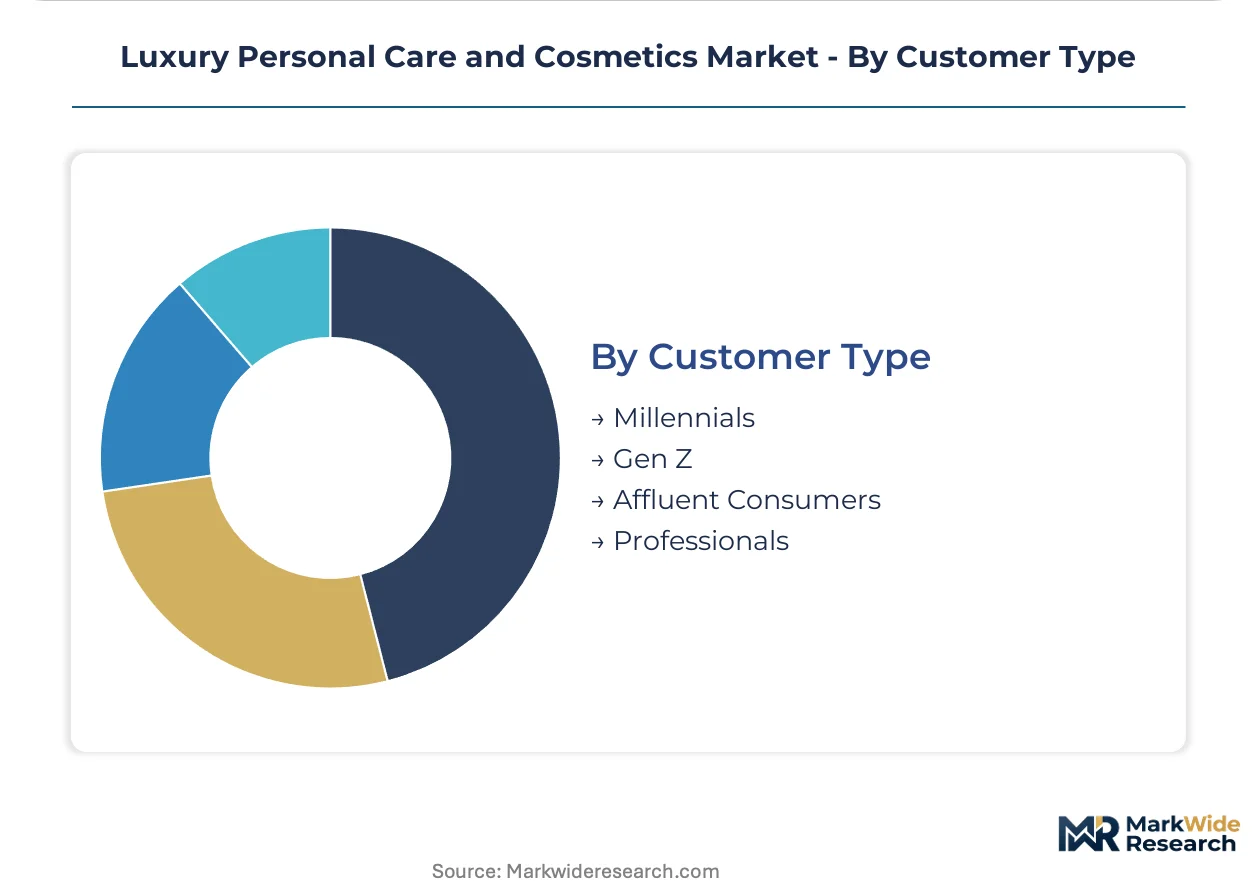
Generational cohorts exhibit divergent preferences for clinical efficacy claims versus sustainability credentials and discovery channel mix.
- Gen Z:Digital-native purchasers prioritize ingredient transparency and blockchain-verified supply chain claims. Social commerce live-streaming on Southeast Asian platforms dominates their discovery behavior.
- Affluent Consumers:Dense metropolitan clusters in Mumbai and Delhi NCR exhibit underpenetrated demand for clinical-positioned skincare relative to per-capita income growth.
- Millennials:Regimen loyalty and subscription-format purchasing characterize this cohort's repeat behavior.
- Professionals:Time-compressed routines favor multi-functional products with proven stability under travel conditions.
Affluent Consumers retain volume leadership; Gen Z follows the steepest expansion trajectory through digital channel nativity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global trade in luxury personal care tilts toward net importing in Western markets while East Asian manufacturing clusters feed both domestic consumption and cross-border e-commerce channels. Export flows from French fragrance houses and Japanese precision skincare producers dominate high-value segments, with regulatory divergence acting as the primary friction in market access timelines.
United States
Affluent urban consumption in Manhattan and Los Angeles sustains demand for clinical-positioned skincare with bio-fermented actives. FDA oversight of cosmetic safety and labeling claims requires substantiation documentation that adds months to product registration. Miami and Dallas emerge as secondary hubs where specialty retail corridors attract Latin American cross-border purchasers seeking price arbitrage on prestige formulations.
China
Domestic luxury consumption in Shanghai and Beijing now outpaces outbound tourism channels for super-premium tiers. NMPA and SAMR enforce registration requirements and advertising standards that determine market access for imported brands, with live-streaming commerce on Douyin reshaping customer acquisition. The Yangtze River Delta concentrates both manufacturing partnerships and digital-native brand incubators targeting Gen Z purchasers.
France
Grasse-region fragrance compound specialists supply over sixty percent of global prestige scent architectures, exposing formulations to climate volatility. REACH framework revisions and EU Green Deal mandates accelerate bio-based ingredient substitution, compelling heritage houses toward transparency-positioned sub-lines. Paris anchors controlled distribution in high-traffic retail corridors essential for discovery and gift purchasing occasions.
Germany
Clinical skincare positioning resonates with consumers in Munich and Hamburg who prioritize dermatological testing protocols. ECHA's expanded SVHC candidate list captures synthetic musks and phthalate alternatives, driving reformulation investment among fragrance houses with German manufacturing presence. The Rhine-Ruhr corridor hosts technical institutes whose graduates concentrate expertise in stability engineering of bio-fermented actives.
Japan
Localized formulation science across regional preference clusters sustains competitiveness for heritage brands in Tokyo and Osaka. METI standards and PMDA oversight govern product safety with documentation requirements that parallel FDA rigor. The Kansai region maintains specialized bioreactor capacity for customized ceramide complexes at batch scales unachievable through conventional cultivation methods.
Luxury Personal Care and Cosmetics Market Competitive Landscape
On the supply side, the industry is consolidating around integrated research platforms and captive biomanufacturing capacity, with mid-tier brands struggling to amortize compliance investments across fragmented regulatory jurisdictions. Three archetypes dominate: heritage houses leveraging controlled distribution in premium retail corridors, biotechnology-enabled formulators with precision fermentation scale-up, and digital-native challengers exploiting social commerce live-streaming for customer acquisition. Competitive moves concentrate on strategic partnerships for localized manufacturing and portfolio diversification into waterless formats that reduce shipping weights and align with EU packaging directives.
Within the heritage house tier, L'Oréal and Estée Lauder Companies occupy positions defined by integrated research platforms and controlled distribution architectures. Shiseido represents the biotechnology-enabled archetype with localized formulation science capabilities. LVMH Moët Hennessy Louis Vuitton anchors the exclusivity-positioned fragrance segment where limited-edition release cycles sustain margin concentration.
| Leading Market Players |
|---|
| L'Oréal |
| Estée Lauder Companies |
| LVMH Moët Hennessy Louis Vuitton |
| Shiseido |
| Coty Inc. |
| Chanel |
| Kao Corporation |
| Unilever |
| Puig |
| Others |
Supply & Pricing Matrix
Undercapacity in Grasse-region fragrance compound specialists is tightening supply availability for prestige scent architectures and amplifying pricing power among concentrated extractors. This utilization squeeze propagates through formulation costs while REACH disclosure mandates add compliance premiums to European-origin inputs.
Pricing Analysis
Affluent consumers in Shanghai and New York anchor a three-tier pricing structure across premium, standard, and economy levels, with bio-fermented actives commanding spreads based on batch certification and dermatological testing protocols. Price differentiation hinges on captive bioreactor access and blockchain-verified supply chain documentation. Cost compression in mass-prestige tiers is intensifying because AI-driven personalization engines democratize customized regimens. Gen Z purchasers exhibit highest price sensitivity, while super-premium skincare buyers show least elasticity.
Supply Chain Analysis
Export-control friction on biotechnology equipment limits precision fermentation scale-up in emerging manufacturing hubs, concentrating rare active production in Japan's Kansai region and select European technical institutes. Raw material flows draw from Grasse-region botanical corridors, Southeast Asian extractors, and Chinese biomanufacturing partnerships. Single-source vulnerability concentrates in fragrance compound supply where climate volatility threatens agricultural yields. Distribution runs through controlled placement in premium retail corridors for discovery, with e-commerce channels capturing fastest expansion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Luxury personal care is restructuring around service-attach revenue, with subscription-format regimen replenishment and AI-driven skin consultation layers expanding faster than standalone product sales.
For Market Incumbents: Harden exclusivity windows by securing captive bioreactor capacity for bio-fermented ceramide production before technical institute pipelines saturate. Deepen backward integration into rare botanical cultivation partnerships to insulate against Grasse-region climate disruption. These moves counter digital-native challengers exploiting social commerce live-streaming for customer acquisition.
For New Entrants and Emerging Players: Pursue waterless formulation formats—solid shampoo bars and powder-to-foam cleansers—where shipping weight reductions align with EU packaging directives and incumbent R&D inertia creates white space. India's Mumbai and Delhi NCR corridors offer underpenetrated clinical skincare demand relative to per-capita income growth. A direct-to-consumer launch with blockchain-verified supply chain transparency captures Gen Z preference clusters.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across biotechnology-enabled formulators requiring precision fermentation infrastructure. Long-term viability favors acquisition targets with integrated research platforms and localized formulation science capabilities rather than pure brand equity plays. Watch for NMPA registration timeline compression as signal of China market access inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Bioreactor Capacity Expansion | Secures supply of bio-fermented ceramides at batch scales unachievable through conventional cultivation methods. |
| Blockchain Traceability Infrastructure | Enables Scope 3 emissions verification required by EU Green Deal compliance mandates. |
| Waterless Format Portfolio Extension | Reduces shipping weights by 70-80% while aligning with REACH packaging waste directives. |
| AI-Driven Personalization Engine Deployment | Compresses entry price points for customized regimens through computer vision skin analysis integration. |
| Localized Manufacturing Partnership | Navigates India's domestic duty structures while accessing Mumbai and Delhi NCR demand clusters. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs records, and retail audit databases. Interviews with brand managers, category buyers at premium retailers, formulation chemists, and supply chain directors informed demand-side and production-side dynamics. Secondary validation drew from ECHA SVHC candidate list updates, NMPA registration databases, and EU Green Deal implementation tracking. Bottom-up SKU-level modeling triangulated against top-down macroeconomic indicators.
Forecast inputs include biotechnology scale-up trajectories, regulatory compliance cost amortization patterns, and channel migration velocities across the analysis window. Segmentation dimensions span product type, price tier, distribution channel, and generational cohort purchasing behavior. CAGRs derive from trend-line extrapolation of bio-fermentation adoption curves and digital commerce penetration rates, cross-referenced with jurisdiction-specific market access timelines.
Sensitivities concentrate around REACH authorization expansions, NMPA registration processing speeds, and climate volatility in Grasse-region agricultural yields. Forecasts reflect assumptions on biomanufacturing cost curve trajectories and social commerce platform algorithm changes. Material shifts in EU fragrance allergen disclosure requirements or China cross-border e-commerce duty structures would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Nail Salon Market
Beauty & Personal Care
Anti-Aging Beauty Device Market
Beauty & Personal Care
Middle East and Africa Beauty and Personal Care Products Market
Beauty & Personal Care
Global Heated Eyelash Curlers Market
Beauty & Personal Care
Elastomer Gel in Personal Care Market
Beauty & Personal Care
Facial Massager Market
Beauty & Personal Care
Lip and Cheek Tint Market
Beauty & Personal Care
Online Beauty and Personal Care Products Market
Beauty & Personal Care
Cosmetics Foundation Market
Beauty & Personal Care
Facial Wipes Market
Beauty & Personal Care
Europe Hair and Skincare Market
Beauty & Personal Care
Personal Care Products Market
Beauty & Personal Care
Spain Sustainable Personal Care Market
Beauty & Personal Care
Global Probiotic Cosmetic Products Market
Beauty & Personal Care
Electric Face Cleanser Market
Beauty & Personal Care
Rice Shampoo Bar Market