
 North America Hydrogen Peroxide Market | 2026-2036
North America Hydrogen Peroxide Market Size, Share, and Industry Trends Forecast 2026-2036
North America Hydrogen Peroxide Market Insights
Food-grade and semiconductor-grade specifications is collapsing the gap with industrial grades as buyers upgrade purity requirements across disinfection and electronics applications. FMC Corporation leverages captive peroxide-to-derivatives integration across its North American manufacturing footprint. Evonik Industries AG anchors its position through R&D intensity in high-purity formulations for electronics clients. Kemira Oyj dominates pulp and paper bleaching supply with specialized logistics networks serving Canadian and US mills.
Hydrogen peroxide is an aqueous solution of hydrogen peroxide (H₂O₂) typically manufactured through the anthraquinone auto-oxidation process, with commercial grades ranging from dilute solutions to concentrated forms exceeding 70% by weight; it functions primarily as a powerful oxidizer, bleaching agent, and disinfectant across industrial and consumer applications. The 50% solution segment leads value contribution due to its versatility in chemical synthesis and wastewater oxidation, while the 35% solution segment registers the fastest expansion driven by healthcare disinfection protocols and food processing sanitation standards. Pulp and paper end users occupy the largest demand pool, though electronics sector consumption is accelerating fastest as semiconductor fabrication expands in Arizona and Texas.
EPA effluent guidelines and OSHA permissible exposure limits govern industrial handling and discharge practices, while Health Canada and PMRA coordinate cross-border standards for agricultural and food-contact applications. The US Department of Transportation regulates concentrated solution transport through hazmat classification requirements that shape distribution network design. Stakeholders must monitor evolving state-level PFAS contamination rules that could redirect hydrogen peroxide demand toward alternative oxidation-based remediation technologies.
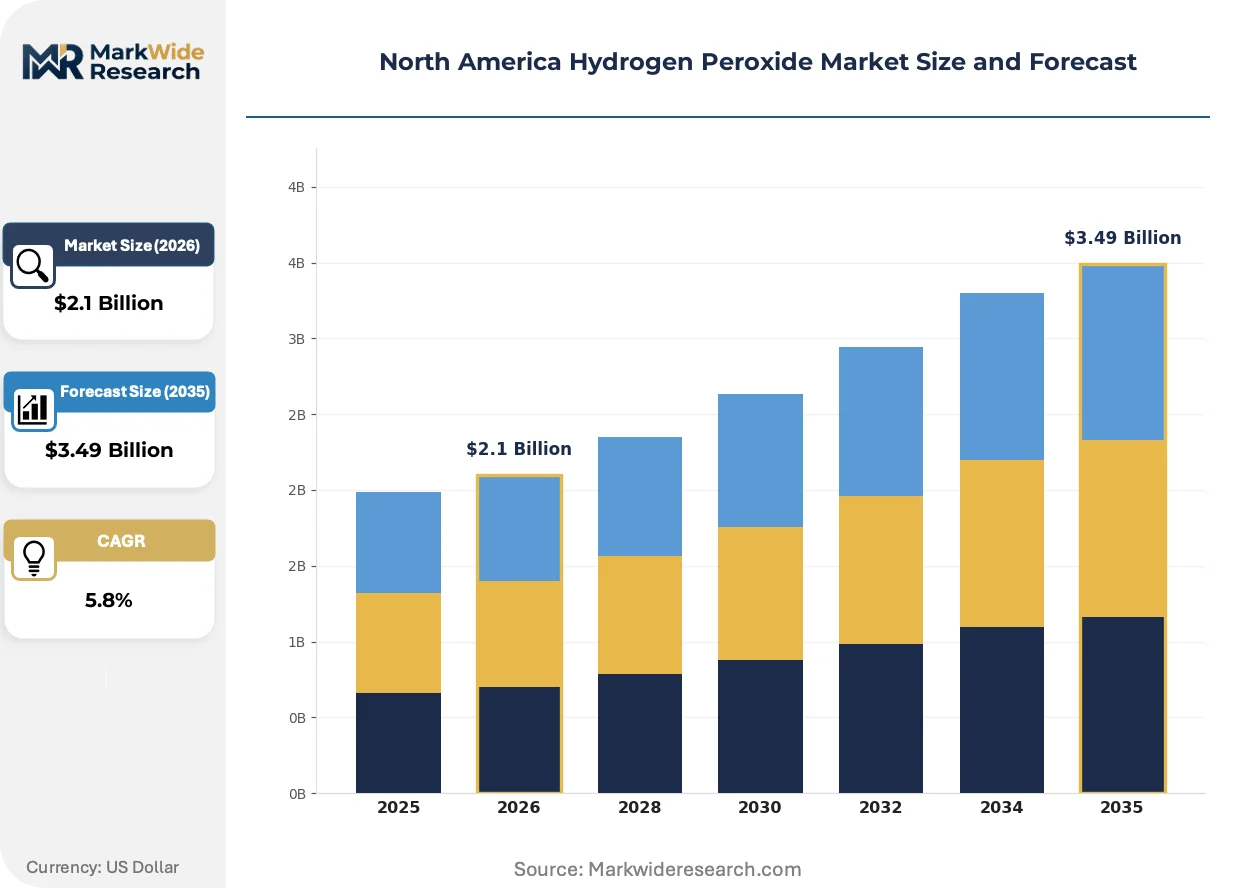
Market Dynamics
The EPA's Clean Water Act enforcement is tightening discharge standards across industrial corridors, redirecting chemical oxidation demand toward hydrogen peroxide as chlorine alternatives face regulatory pressure. This structural shift compresses procurement timelines and elevates purity specifications across end-use verticals.
Growth Catalysts
- Pulp and Paper Bleaching Conversion:Canadian and US mills are substituting elemental chlorine with hydrogen peroxide in bleaching sequences to meet EPA Cluster Rule effluent limits. This substitution accelerates demand for 50% technical-grade solutions.
- REACH-Aligned Purity Standards:Electronics fabricators in Arizona and Texas now require semiconductor-grade specifications that exceed legacy industrial grades, creating specification upgrades across the supply base.
- Wastewater Oxidation Mandates:The US Gulf Coast chemical manufacturing corridor faces intensifying discharge scrutiny, positioning hydrogen peroxide as the preferred oxidant for cyanide and sulfide destruction in refinery effluent.
Market Restraints
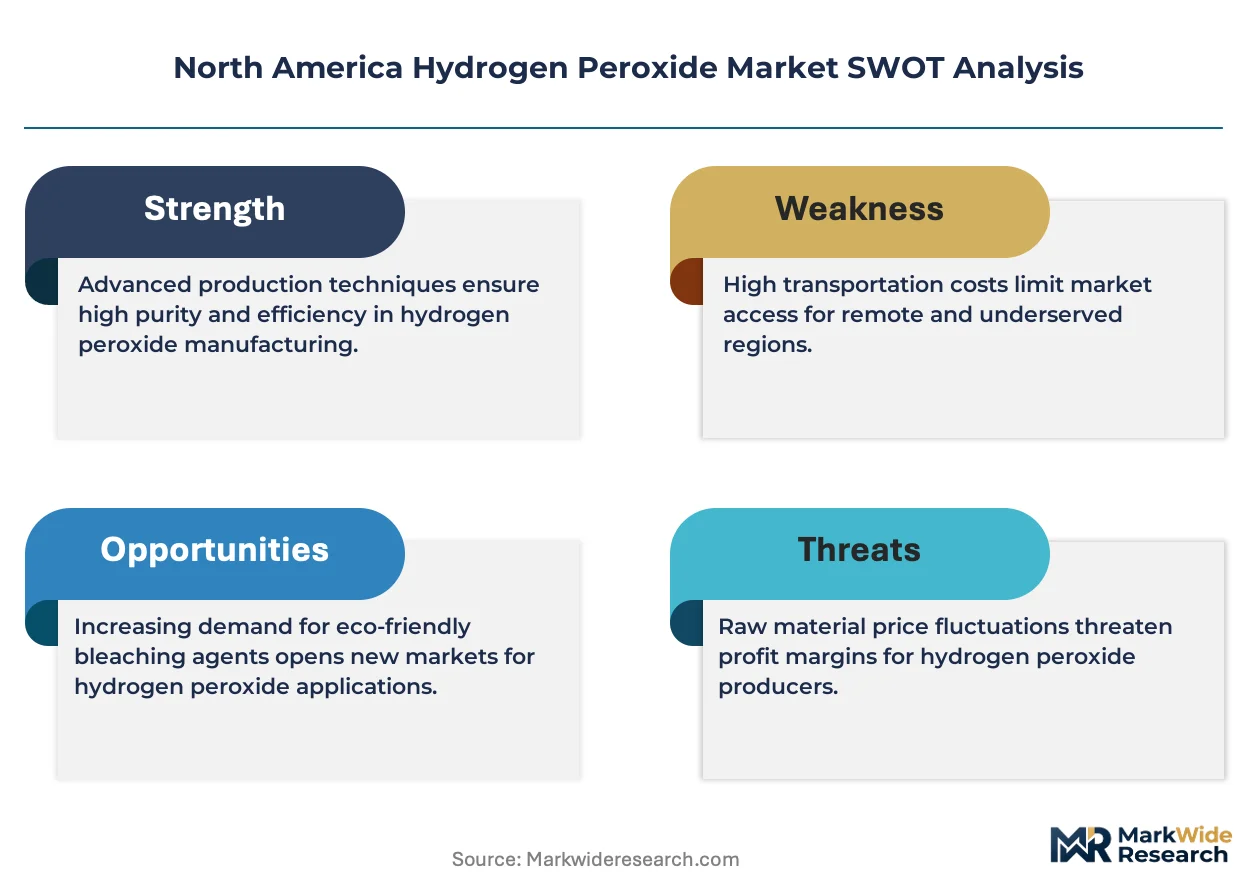
- Anthraquinone Feedstock Concentration:Production of hydrogen peroxide depends on captive anthraquinone supply chains concentrated among integrated chemical majors, limiting new entrant participation.
- Concentrated Solution Transport Economics:DOT hazmat classification for solutions exceeding 52% concentration restricts distribution radius and elevates logistics costs for remote industrial users.
- Peracetic Acid Substitution:Food processing sanitation applications increasingly specify peracetic acid blends for cold aseptic filling, constraining hydrogen peroxide volume in beverage packaging.
Strategic Opportunities
- PFAS Remediation Deployment:State-level PFAS contamination rules in Michigan and North Carolina are redirecting remediation budgets toward advanced oxidation processes using hydrogen peroxide as the primary oxidant.
- Electronics Cluster Expansion:Semiconductor fabrication investments in Texas create localized demand for ultra-high-purity formulations that command specification premiums over standard industrial grades.
- On-Site Generation Systems:Modular electrolytic hydrogen peroxide generation units are enabling pulp mills to reduce transport dependency and inventory holding costs.
Industry Challenges
- High-Purity Certification Timeline:Semiconductor-grade qualification requires 18-24 month validation cycles with individual fabs, compressing supplier revenue recognition.
- Specialized Logistics Workforce:Concentrated solution handling demands certified hazmat drivers and terminal operators, creating recruitment bottlenecks in the US Gulf Coast corridor.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Hydrogen Peroxide Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.49 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 30% Solution, 35% Solution, 50% Solution, 70% Solution End User: Pulp & Paper, Textile, Electronics, Chemicals Application: Disinfection, Bleaching, Oxidizing Agent, Waste Treatment Packaging Type: Drum, Tote, Bulk, Canister |
| Companies Covered | FMC Corporation, Kemira Oyj, Evonik Industries AG, Akzo Nobel NV, Nouryon, Solvay S.A., Chang Chun Group, National Peroxide Ltd., Arkema S.A., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Hydrogen Peroxide Market Trends and Innovations
Membrane electrolysis and direct synthesis routes are challenging the century-old anthraquinone process, while regulatory pressure on chlorine chemistry accelerates specification migration across industrial oxidation applications.
Direct synthesis technology from syngas-derived hydrogen is displacing conventional anthraquinone auto-oxidation in pilot installations. Electronics-grade producers in Texas are evaluating this route for its potential to eliminate organic solvent contamination risks. The technology is displacing capital-intensive quinone recovery systems and enabling modular production footprints closer to point-of-use.
The EPA's forthcoming effluent limitation guidelines for organic chemicals, plastics and synthetic fibers will mandate best available technology for toxic pollutant removal. This regulatory pressure elevates hydrogen peroxide demand in chemical synthesis wastewater treatment. Pulp and paper mills in the Pacific Northwest are pre-positioning oxidation capacity to secure discharge permits under anticipated rulemaking.
Specification-driven procurement now dominates electronics and food-grade segments, with buyers unbundling technical service from commodity supply. Distributors serving Arizona semiconductor fabs are consolidating toward authorized partnerships with integrated producers who control captive purification assets. This pattern concentrates supply relationships and compresses spot market participation in high-purity categories.
North America Hydrogen Peroxide Market Segmentation
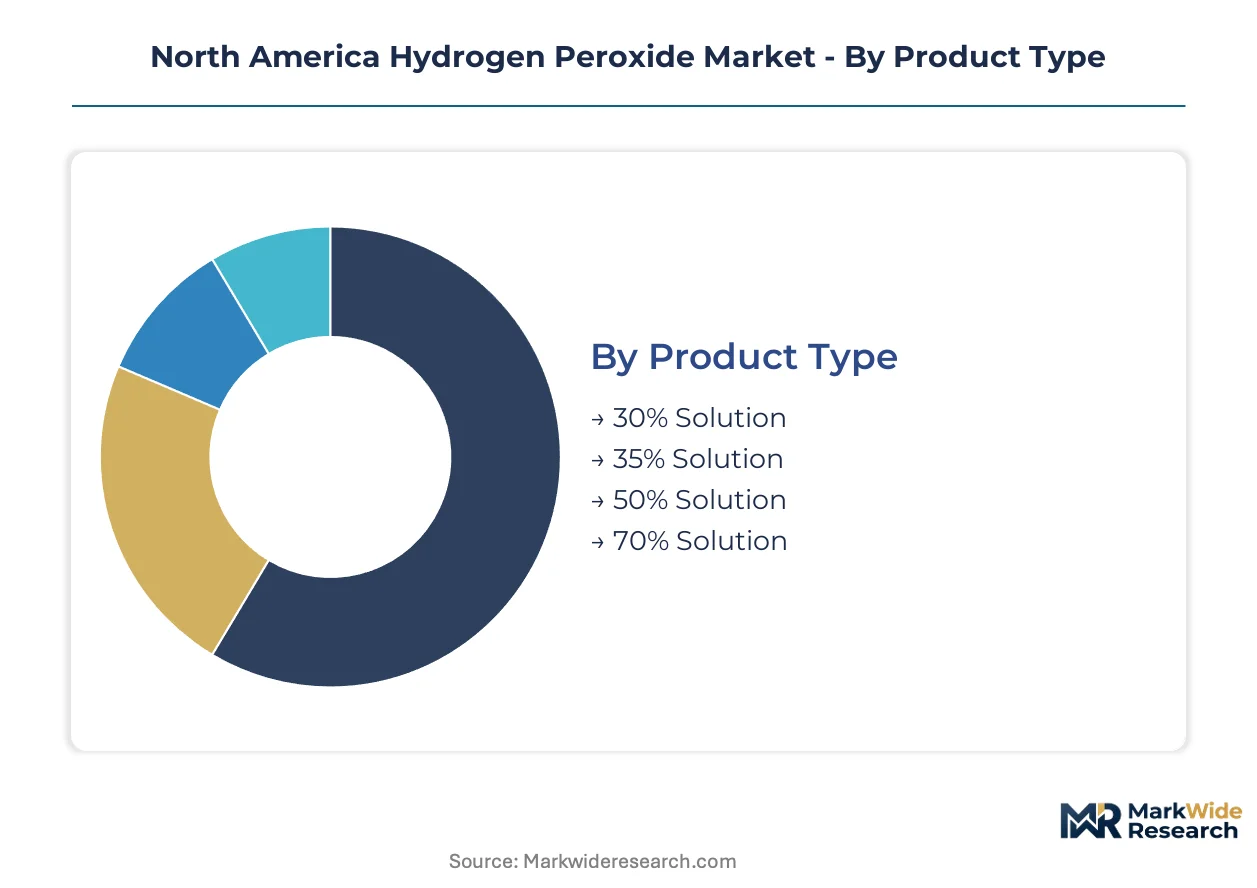
Segmentation reveals how hydrogen peroxide specifications diverge across regulatory environments and end-use intensity. Each dimension exposes distinct margin structures and supply chain requirements that shape procurement strategy.
Product Type:
Domestic consumption concentrates in mid-concentration grades serving US Gulf Coast chemical manufacturing and Canadian pulp mills, while export flows favor concentrated solutions crossing into Mexico for industrial oxidation applications.
- 50% Solution:This concentration balances reactivity with handling safety across chemical synthesis and refinery wastewater oxidation. US Gulf Coast chemical manufacturers specify this grade for cyanide destruction in effluent treatment, driven by EPA Clean Water Act enforcement tightening discharge permits.
- 35% Solution:Healthcare disinfection protocols and food processing sanitation standards are accelerating procurement of this grade. Arizona and Texas semiconductor fabs require semiconductor-grade 35% solutions exceeding legacy industrial purity specifications.
- 30% Solution:Consumer and light industrial applications favor this accessible concentration for surface disinfection and small-scale bleaching operations.
- 70% Solution:Highly concentrated form restricted by DOT hazmat transport rules to captive production or specialized logistics corridors serving aerospace and defense oxidation needs.
50% Solution holds the largest share; momentum sits with 35% Solution.
End User:
Cost tier segmentation separates commodity-grade buyers in mature industries from specification-driven purchasers in emerging technology verticals.
- Pulp & Paper:Canadian and US mills dominate volume consumption, substituting elemental chlorine with hydrogen peroxide bleaching sequences to meet EPA Cluster Rule effluent limits. Kemira Oyj maintains specialized logistics networks serving this concentrated demand base across the Great Lakes and Pacific Northwest.
- Electronics:Semiconductor fabrication expansion in Arizona and Texas creates localized demand for ultra-high-purity formulations commanding specification premiums. Qualification cycles with individual fabs extend 18-24 months, compressing supplier revenue recognition timelines.
- Chemicals:Organic synthesis and specialty chemical manufacturers in the US Gulf Coast corridor utilize hydrogen peroxide as a selective oxidant in pharmaceutical intermediate production.
- Textile:Bleaching operations in Mexico and southeastern US states consume technical-grade solutions for cotton and synthetic fiber processing, though peracetic acid blends are gaining share in cold aseptic applications.
Pulp & Paper commands the dominant volume position; Electronics displays the steepest expansion trajectory.
Application:
Volume concentration tracks regulatory enforcement intensity, with wastewater oxidation and bleaching applications expanding fastest where discharge standards tighten.
- Bleaching:Pulp and paper mills across Canada and the US Pacific Northwest are pre-positioning oxidation capacity to secure discharge permits under anticipated EPA effluent limitation guidelines for organic chemicals and synthetic fibers.
- Waste Treatment:Refinery and chemical plant effluent in the US Gulf Coast corridor requires hydrogen peroxide for sulfide and cyanide destruction as EPA enforcement intensifies.
- Disinfection:Healthcare facilities and food processing plants specify food-grade and semiconductor-grade purity levels for surface and equipment sanitation.
- Oxidizing Agent:Chemical synthesis applications in pharmaceutical and specialty chemical manufacturing demand consistent reactivity and minimal organic contamination.
Bleaching retains the largest application share; Waste Treatment is climbing the fastest on regulatory drivers.
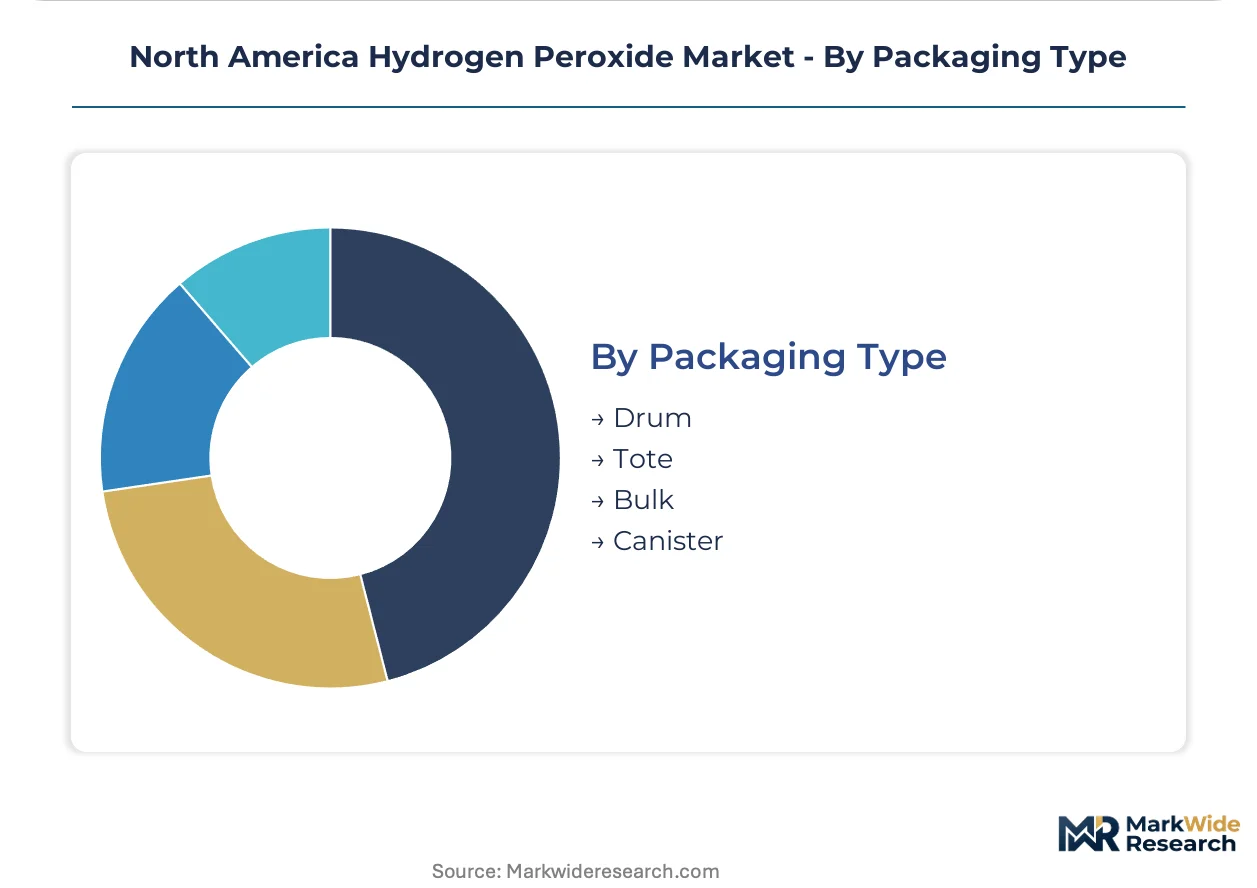
Packaging Type:
Customer type segmentation separates integrated chemical producers with bulk receiving infrastructure from distributed users requiring smaller unit sizes.
- Bulk:Integrated pulp mills and Gulf Coast chemical manufacturers receive railcar and tank truck deliveries, minimizing per-unit logistics costs and inventory holding requirements.
- Drum:Mid-scale industrial users in electronics and specialty chemicals favor 55-gallon steel drums for manageable handling and storage footprint.
- Tote:Food processing and healthcare facilities specify intermediate bulk containers for disinfection applications requiring moderate volume with reduced handling frequency.
- Canister:Consumer and small commercial users purchase retail-format canisters for surface disinfection and light bleaching tasks.
Bulk packaging dominates industrial procurement; Tote formats are gaining share fastest in food and healthcare verticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows within North America favor concentrated hydrogen peroxide exports from US Gulf Coast production hubs into Mexican industrial oxidation markets, while Canadian mills source primarily through dedicated supply contracts with integrated North American producers.
United States
EPA Clean Water Act enforcement tightens discharge permits across chemical manufacturing corridors, redirecting oxidation demand toward hydrogen peroxide. The US Gulf Coast corridor hosts concentrated production capacity serving refinery effluent treatment and pulp bleaching operations. Arizona and Texas semiconductor fabrication clusters drive specification upgrades for ultra-high-purity formulations.
Canada
Health Canada and PMRA coordinate cross-border standards for food-contact and agricultural applications, aligning purity requirements with US FDA benchmarks. Pulp and paper mills across British Columbia and the Prairie Provinces substitute elemental chlorine with hydrogen peroxide bleaching sequences. Great Lakes logistics networks enable efficient bulk delivery to integrated mill complexes.
Mexico
Industrial oxidation applications in chemical synthesis and textile processing absorb concentrated hydrogen peroxide imports from US production centers. The Bajío Region and northern border states concentrate manufacturing demand for bleaching and wastewater treatment. Mexican regulators align hazmat transport classifications with US DOT standards to facilitate cross-border supply chain integration.
North America Hydrogen Peroxide Market Competitive Landscape
Concentration sits with integrated chemical majors possessing captive anthraquinone supply chains and specialized logistics infrastructure. Three to four producers command the majority of North American production capacity, creating tiered supply relationships with specification-driven end users. Strategic archetypes separate integrated producers with backward control over feedstocks from specialty distributors serving high-purity electronics and food-grade segments. Dominant competitive moves include capacity expansion in semiconductor corridor proximity and strategic partnerships with pulp mill operators for on-site generation systems.
Among integrated producers with captive derivatives integration, FMC Corporation exemplifies the diversified chemical major archetype, while Kemira Oyj occupies a position within the pulp and paper specialization tier. Evonik Industries AG represents the high-purity formulation specialist archetype serving electronics fabrication clusters.
| Leading Market Players |
|---|
| FMC Corporation |
| Kemira Oyj |
| Evonik Industries AG |
| Akzo Nobel NV |
| Nouryon |
| Solvay S.A. |
| Chang Chun Group |
| National Peroxide Ltd. |
| Arkema S.A. |
| Others |
Pricing and Supply Chain Analysis
Chlorine-to-peroxide substitution across US and Canadian pulp mills simultaneously concentrates procurement leverage with integrated anthraquinone producers and compresses pricing power for spot-market distributors. This input transition reshapes supply geography toward Gulf Coast production hubs while elevating specification premiums for semiconductor-grade formulations.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across the North American hydrogen peroxide market. Pricing stratifies across semiconductor-grade, food-grade, and technical industrial tiers, with certification level and volume scale driving differentiation. Cost compression in standard industrial grades is intensifying because captive producers leverage backward integration into anthraquinone feedstocks. Pulp and paper mills exhibit highest price sensitivity due to commodity product margins, while electronics fabricators show least sensitivity given qualification-locked supply relationships.
Supply Chain Analysis
Inventory holding periods extend for remote industrial users dependent on railcar deliveries from Texas and Louisiana production centers. Supply concentrates in the United States, Canada, and Mexico, with raw material flows drawing from captive anthraquinone manufacturing and specialized hydrogen feedstock networks. Single-source vulnerability sits with concentrated anthraquinone supply chains controlled by integrated chemical majors. Distribution runs through dedicated bulk terminals, rail spurs, and specialized hazmat trucking corridors serving Gulf Coast chemical manufacturers and Pacific Northwest pulp complexes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized logistics workforce scarcity constrains capacity expansion timelines, as certified hazmat operators and qualified semiconductor-grade technicians remain concentrated with incumbent producers. This capability gap favors established players with training infrastructure while raising barriers for new entrants seeking high-purity qualification.
For Market Incumbents: Secure captive anthraquinone supply positions through long-term feedstock agreements or selective capacity additions in Texas corridor proximity. Defend against direct synthesis technology disruption by accelerating R&D investment in electrolytic generation systems. Prioritize certification maintenance with Arizona and Texas semiconductor fabs to sustain specification premiums. For New Entrants and Emerging Players: Differentiate on modular on-site generation systems for pulp mills seeking inventory reduction and transport cost elimination. Target underpenetrated PFAS remediation applications in Michigan and North Carolina with advanced oxidation process expertise. Pursue authorized distributor partnerships with established producers rather than greenfield production investment. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed specialty chemical distributors lacking captive production integration. Long-term viability hinges on backward integration depth and electronics-grade qualification status. Monitor EPA effluent guideline finalization timing as demand inflection signal for wastewater oxidation applications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Anthraquinone | Captive feedstock control neutralizes supply risk from concentrated precursor markets. |
| Semiconductor-Grade Capacity Expansion | Texas and Arizona fab proximity captures specification premiums from advanced node manufacturing. |
| On-Site Generation System Deployment | Modular electrolytic units at pulp mills reduce transport dependency and inventory carrying costs. |
| PFAS Remediation Technology Partnership | Advanced oxidation process alliances with environmental contractors redirect state remediation budgets. |
| Specialized Logistics Workforce Development | Hazmat certification programs with Gulf Coast technical colleges alleviate driver and operator shortages. |
Research Methodology
Desk research of trade flow databases, EPA enforcement records, and semiconductor fab construction permits preceded structured interviews with pulp mill procurement directors, Gulf Coast chemical plant managers, electronics-grade technical sales leads, and specialized hazmat logistics operators. Primary fieldwork with Kemira and FMC distribution partners cross-validated volume estimates against customs data and railcar loading records. Bottom-up facility capacity tallies triangulated with top-down end-use consumption models.
Variance decomposition across concentration grades, end-use industries, packaging formats, and regional production hubs informed the analytical framework over the projection horizon. CAGRs derived from segment-level demand elasticity modeling and substitution rate assumptions for chlorine displacement in bleaching applications. Forecast inputs incorporated EPA rulemaking timelines, semiconductor fab buildout schedules, and pulp mill capital expenditure patterns.
The analysis sits within stated boundaries; outcomes outside sustained EPA enforcement intensity or accelerated direct synthesis commercialization would require recalibration. Forecasts reflect documented assumptions regarding feedstock cost trajectories and qualification timeline stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Disinfectants and Preservatives
Chlorinators Market
Disinfectants and Preservatives
Disinfectants Market
Disinfectants and Preservatives
Disinfectant Chemicals Market
Disinfectants and Preservatives
Middle East and Africa Surface Disinfectants Market
Disinfectants and Preservatives
Clean Label Preservatives Market
Disinfectants and Preservatives
Sterilization Markers Market
Disinfectants and Preservatives
Hypochlorous Acid Market
Disinfectants and Preservatives
India Air Treatment Products Market
Disinfectants and Preservatives
Surface Disinfectant Products Market
Disinfectants and Preservatives
Global Fumigation Products Market
Disinfectants and Preservatives
US Surface Disinfectant Market
Disinfectants and Preservatives
Disinfection Cap Market
Disinfectants and Preservatives
Europe Disinfectant Wipes Market
Disinfectants and Preservatives
Clinical Grade Disinfectant Market
Disinfectants and Preservatives
Diquat Dibromide Market
Disinfectants and Preservatives
Sulfuryl Fluoride Market