
 Liposome in Cosmetics Market | 2026-2036
Liposome in Cosmetics Market Size, Share, and Industry Trends Forecast 2026-2036
Liposome in Cosmetics Market Insights
Multilamellar vesicle engineering is reconfiguring active ingredient penetration depths across cosmetic formulations. Croda leverages captive phospholipid sourcing to sustain formulation consistency at scale. Lucas Meyer Cosmetics anchors European supply through specialized lecithin-derived liposome platforms. Nippon Fine Chemical dominates Asian technical-grade lipid production for regional cosmetic houses.
Liposomes in cosmetics are phospholipid bilayer vesicles, typically 50 to 500 nanometers in diameter, engineered to encapsulate hydrophilic actives within aqueous cores and lipophilic compounds within membrane lamellae, primarily serving to enhance dermal bioavailability and protect unstable ingredients from oxidative degradation. Facial creams and anti-aging products concentrate margin pools as consumers prioritize clinically positioned delivery systems over basic moisturizers. Water-based formulations lead volume given compatibility with hyaluronic acid and peptide actives, while gel-based formats are gaining traction in professional channels for controlled-release applications.
EMA cosmetic ingredient guidelines, REACH registration mandates from ECHA, and ISO 16128 natural origin standards collectively elevate compliance costs for liposome suppliers entering European markets. FDA oversight of cosmetic active claims under the Modernization of Cosmetics Regulation Act tightens substantiation requirements for penetration-enhancement marketing in the United States. Stakeholders must monitor evolving nanomaterial classification debates, as regulatory reclassification of sub-100nm vesicles would force reformulation investments across existing product portfolios.
Market Dynamics
Multilamellar vesicle engineering is compressing formulation development cycles as brands demand deeper dermal penetration from phospholipid delivery systems. REACH registration mandates from ECHA are forcing suppliers to document lipid sourcing chains, reshaping procurement priorities across cosmetic houses.
Growth Catalysts
- ECHA REACH transparency mandates:Ingredient disclosure requirements are accelerating clean-label liposome adoption as brands preempt regulatory scrutiny with documented phospholipid provenance.
- South Korea beauty manufacturing corridor:Concentrated production of K-beauty exports is sustaining specialized lipid demand for sheet-mask and essence formulations targeting Asian and Western markets.
- Peptide-hyaluronic acid co-encapsulation:Dual-core liposome architectures are enabling single-serum delivery of incompatible actives, expanding premium anti-aging portfolio breadth.
Market Restraints
- Phospholipid input cost volatility:Soy and sunflower lecithin prices fluctuate with agricultural commodity cycles, compressing margin stability for mid-tier suppliers without captive sourcing.
- European supply concentration:Technical-grade lipid production clusters in Germany and Netherlands create geographic vulnerability to energy cost shocks and logistics disruptions.
- Sub-100nm vesicle regulatory uncertainty:Pending nanomaterial reclassification debates threaten forced reformulation of existing product portfolios without grandfathering provisions.
Strategic Opportunities
- India domestic cosmetic manufacturing:PLI scheme incentives for local production create entry points for liposome suppliers establishing technical-grade lipid compounding capacity.
- Professional channel gel formats:Controlled-release liposome gels for clinic-administered treatments command premium positioning above retail skincare price bands.
- ISO 16128 natural origin certification:Plant-derived phospholipid platforms qualify for rising clean-beauty positioning, differentiating formulations in premium segments.
Industry Challenges
- Phospholipid chemistry specialization gap:Formulation chemists with vesicle engineering expertise remain scarce, extending R&D timelines for novel delivery architectures.
- EMA cosmetic ingredient dossier preparation:Extended documentation timelines for novel liposome variants delay market entry by 18-24 months versus conventional emulsions.
- Legacy emulsion system integration:Retrofitting existing manufacturing lines for sterile liposome production requires cleanroom investments that strain mid-cap facility budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liposome in Cosmetics Market |
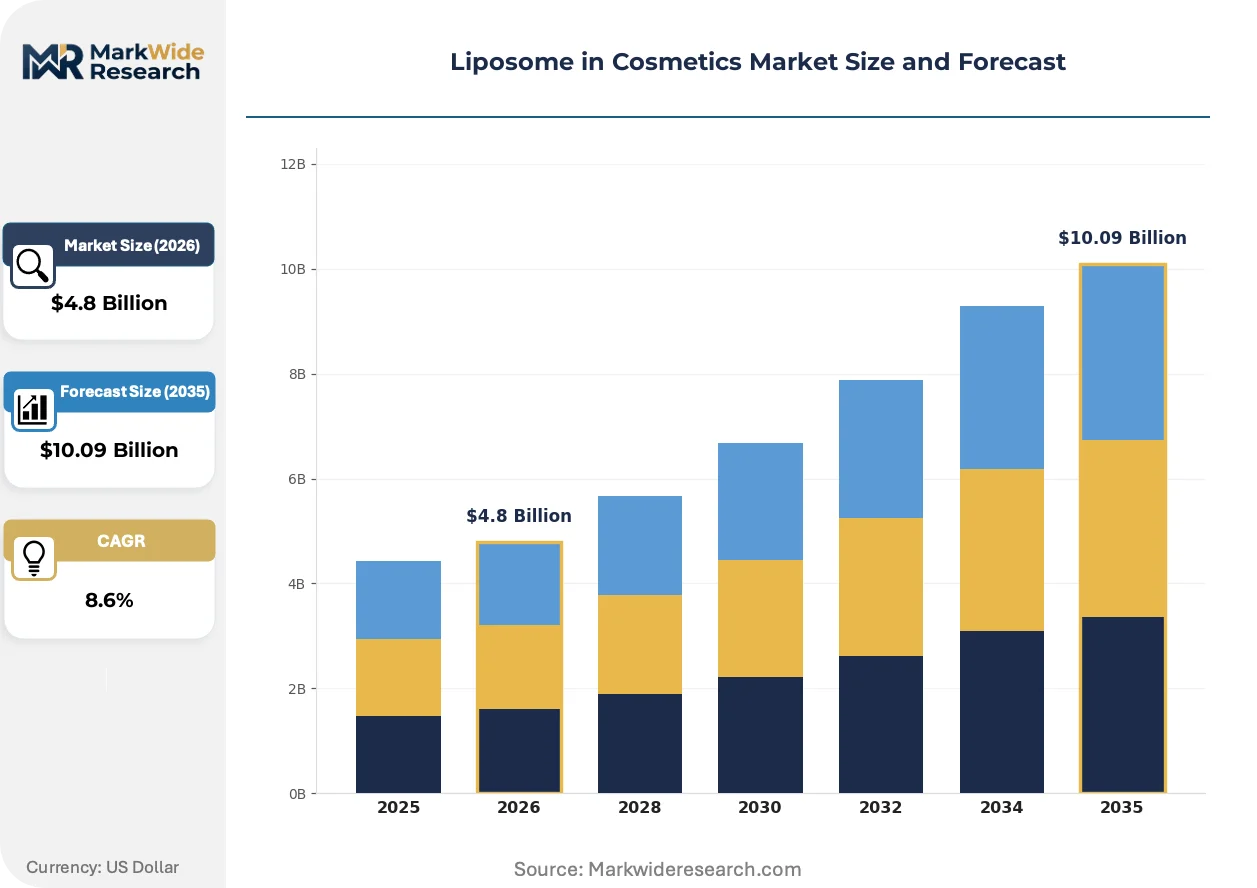
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.09 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Facial Creams, Serums, Anti-Aging Products, Moisturizers Formulation Type: Water-Based, Oil-Based, Gel-Based, Emulsion End User: Women, Men, Unisex, Professionals Distribution Channel: Online Retailers, Specialty Stores, Supermarkets, Pharmacies |
| Companies Covered | Nanohealth Biotech, Nanovec, Lipoid Kosmetik, H&A Pharmachem, Enoc Pharma, Lucas Meyer Cosmetics, Croda, BioSpectrum, Nippon Fine Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liposome in Cosmetics Market Trends and Innovations
Process analytical technology is penetrating liposome manufacturing floors as quality-by-design principles displace batch-release testing. Real-time vesicle size monitoring and lamellarity control are compressing deviation rates and accelerating scale-up timelines for new formulations.
Microfluidic manufacturing platforms are digitizing liposome production workflows through continuous-flow processing that replaces traditional thin-film hydration batch methods. Premium skincare manufacturers in South Korea and Switzerland are adopting these systems for peptide-encapsulated serums. Real-time particle size distribution control is digitizing quality assurance, reducing batch-to-batch variability that previously required extensive rework.
ECHA nanomaterial definition consultations are forcing cosmetic houses to pre-register sub-100nm vesicle variants ahead of potential mandatory safety dossier requirements. The regulatory uncertainty is compressing R&D investment timelines as brands accelerate reformulation of borderline-size products. Water-based anti-aging serums with 80-120nm mean diameters face the highest exposure to reclassification-driven portfolio disruption.
Direct-to-consumer subscription channels are fragmenting traditional wholesale purchasing for liposome-based skincare, with clinic-grade brands bypassing department store intermediaries. Professional aesthetic chains in Germany and California are building captive patient bases through membership models. This channel compression is most visible in premium anti-aging segments where education-heavy purchasing decisions favor sustained brand relationships over impulse retail discovery.
Liposome in Cosmetics Market Segmentation
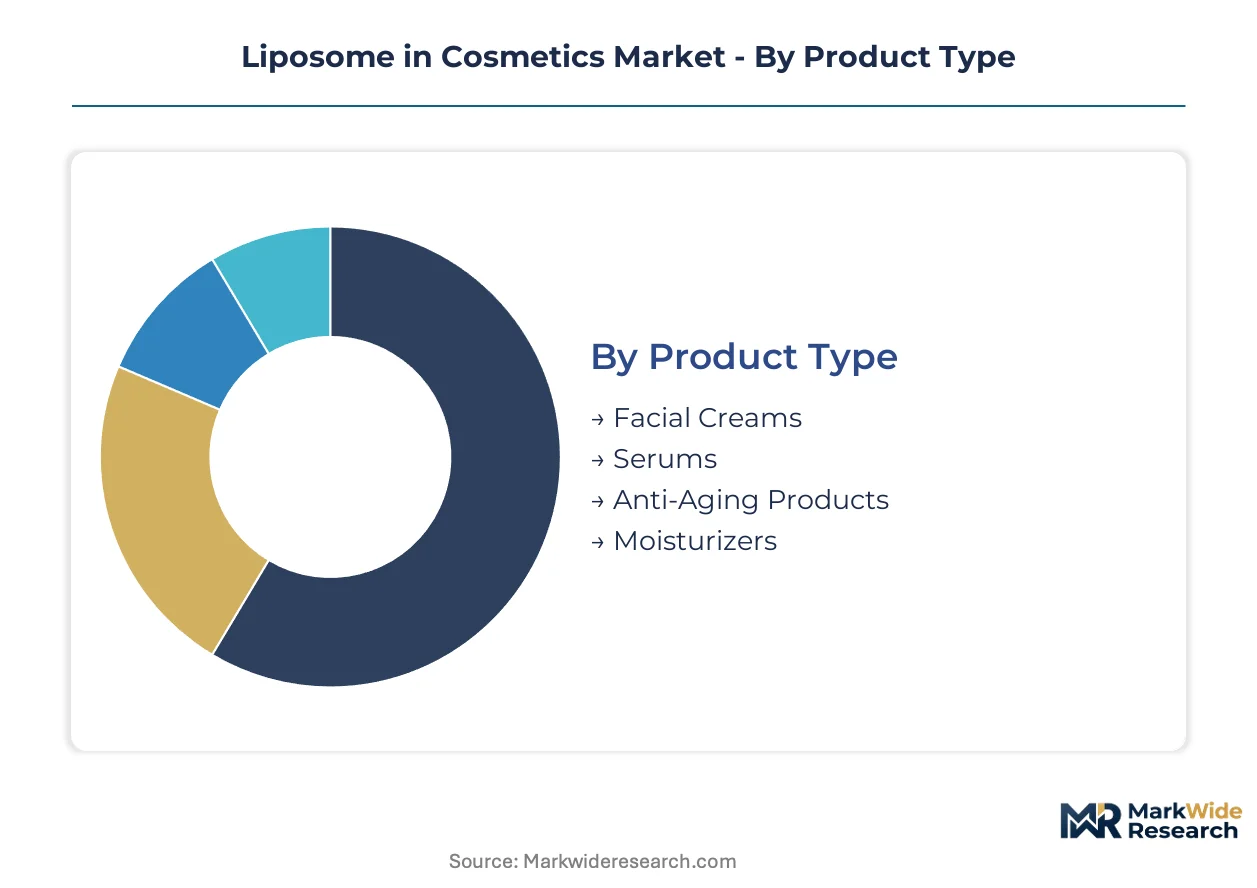
Liposome engineering priorities diverge sharply across cosmetic applications, with formulation viscosity and active stability dictating vesicle architecture choices. Each segment commands distinct phospholipid grades and manufacturing protocols that reshape supplier qualification requirements.
Product Type:
Anti-aging portfolios concentrate premium R&D investment as brands compete on bioavailability claims.
- Facial Creams:Multilamellar vesicles in occlusive bases deliver sustained retinol release across epidermal layers. Demand clusters in South Korea's export-oriented manufacturing houses serving North American direct-to-consumer brands.
- Serums:Unilamellar architectures with 80-120nm mean diameters optimize peptide penetration for clinic-positioned brands. Water-based formats dominate as hyaluronic acid co-encapsulation becomes standard.
- Anti-Aging Products:Dual-core liposomes combining antioxidants with signal peptides command the highest phospholipid purity grades.
- Moisturizers:Basic lamellar structures emphasize barrier repair over active delivery, sourcing technical-grade lecithin.
The dominant share belongs to Anti-Aging Products, while Serums are closing the gap fastest.
Formulation Type:
Manufacturing complexity scales with aqueous-phase compatibility requirements.
- Water-Based:Hydrophilic-core vesicles encapsulate hyaluronic acid and vitamin C derivatives in low-viscosity vehicles. South Korean sheet-mask producers consume bulk volumes of hydrogenated phospholipids for essence formulations.
- Gel-Based:Viscoelastic matrices enable controlled-release kinetics for professional channel applications. Swiss clinic-grade manufacturers specify carbomer-thickened liposome gels for post-procedure recovery protocols.
- Oil-Based:Lipophilic actives embed within membrane bilayers for anhydrous balm formats.
- Emulsion:Vesicle-stabilized oil-in-water systems bridge compatibility gaps between hydrophilic and lipophilic actives.
Water-Based formulations hold the volume lead, with Gel-Based formats expanding most quickly through aesthetic clinic channels.
End User:
Gender-positioned marketing reshapes liposome size specifications and sensory profiles.
- Women:Fine-particle vesicles in fragrance-compatible bases target daily skincare rituals. K-beauty export formulations prioritize this segment with multi-step essence protocols.
- Unisex:Neutral-positioned minimalist formulations emphasize clean-label phospholipid sourcing for shared household purchasing.
- Men:Rapid-absorption architectures with matte finish requirements drive smaller vesicle diameters.
- Professionals:Clinic-administered treatments specify sterile liposome production with documented lamellarity for liability protection.
Women's products retain the largest position, though Unisex lines are gaining share fastest as gender-neutral positioning displaces traditional segmentation.
Distribution Channel:
Channel selection determines packaging stability requirements and education intensity.
- Specialty Stores:Staff-assisted consultation justifies complex multi-active liposome systems with premium positioning. German pharmacy chains specify cold-chain integrity for peptide-encapsulated inventory.
- Online Retailers:Direct-to-consumer subscription models favor airless pump packaging that extends vesicle shelf stability through variable shipping conditions.
- Supermarkets:Mass-market penetration requires cost-optimized phospholipid grades with simplified claims.
- Pharmacies:Dermo-cosmetic positioning demands EMA-aligned documentation for penetration-enhancement marketing.
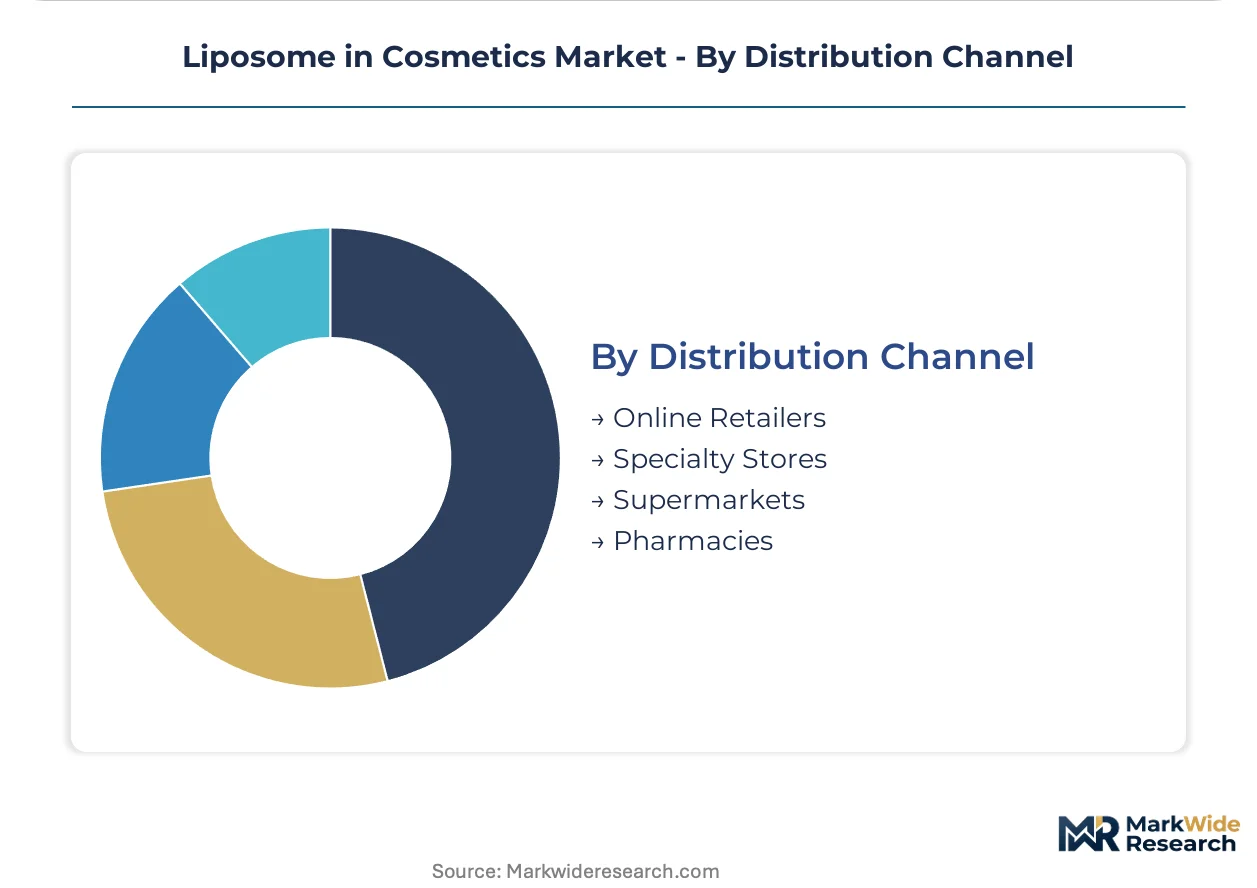
Specialty Stores command the margin premium, while Online Retailers are climbing the fastest as clinic-grade brands bypass traditional wholesale intermediaries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium skincare buyers cluster in South Korea's manufacturing corridor, Germany's pharmacy networks, and California's direct-to-consumer subscription hubs. Clinic-grade brands in Switzerland and Japan sustain specialized lipid demand for post-procedure protocols. Regional regulatory divergence is fragmenting formulation strategies across these demand centers.
South Korea
K-beauty export manufacturing drives bulk phospholipid consumption for sheet-mask essences and multi-step skincare rituals. MFDS cosmetic safety assessments mandate stability documentation for liposome-encapsulated actives in export-bound formulations. Seoul Capital Area production houses supply North American direct-to-consumer brands with hydrogenated phospholipid grades optimized for airless pump packaging.
Germany
Pharmacy chain dermo-cosmetic positioning elevates EMA-aligned penetration-enhancement claims for clinic-grade liposome systems. ECHA REACH registration mandates force lipid suppliers to document soy and sunflower lecithin provenance chains. North Rhine-Westphalia technical-grade lipid compounding facilities serve continental European cosmetic houses with REACH-registered phospholipid platforms.
United States
California-based subscription skincare brands bypass traditional wholesale intermediaries through direct-to-consumer peptide-encapsulated serums. FDA Modernization of Cosmetics Regulation Act oversight tightens substantiation requirements for bioavailability marketing claims. Greater Los Angeles formulation labs specialize in sterile liposome production for professional aesthetic clinic channels.
Switzerland
Swissmedic-regulated clinic-grade manufacturers command premium positioning for post-procedure recovery liposome gels with documented lamellarity. ISO 16128 natural origin certification requirements elevate plant-derived phospholipid sourcing standards for clean-beauty export formulations. Basel-region specialty chemical houses supply carbomer-thickened controlled-release systems to German and French aesthetic chains.
Japan
MATSUI and PMDA cosmetic ingredient guidelines shape liposome size specifications for fragrance-compatible daily skincare rituals. METI industrial standards influence manufacturing equipment specifications for vesicle size distribution control. Osaka-based cosmetic houses integrate microfluidic production platforms for peptide-hyaluronic acid co-encapsulation serums targeting domestic pharmacy channels.
Liposome in Cosmetics Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented supply tiers. The vendor base spans captive phospholipid producers, specialized lecithin-derived platform developers, and regional technical-grade lipid compounders. Three archetypes dominate: vertically integrated multinationals with backward sourcing control, mid-scale specialists with vesicle engineering expertise, and regional compounders serving geographic manufacturing clusters. Competitive moves concentrate on sterile production capacity expansion and REACH registration dossier preparation for novel liposome variants.
Among European specialists, Lipoid Kosmetik and Lucas Meyer Cosmetics occupy positions within the lecithin-derived platform tier, while Croda exemplifies the vertically integrated archetype with captive phospholipid sourcing. These three entities anchor distinct competitive vectors across premium formulation supply.
| Leading Market Players |
|---|
| Nanohealth Biotech |
| Nanovec |
| Lipoid Kosmetik |
| H&A Pharmachem |
| Enoc Pharma |
| Lucas Meyer Cosmetics |
| Croda |
| BioSpectrum |
| Nippon Fine Chemical |
| Others |
Pricing and Supply Chain Analysis
German and Dutch technical-grade lipid compounding clusters anchor phospholipid supply for European cosmetic houses, concentrating margin capture upstream while formulation brands downstream compete on bioavailability positioning. REACH-registered hydrogenated lecithin grades command premium spreads over technical-grade alternatives, with cost-plus contracts indexed to agricultural commodity futures transferring volatility risk to mid-tier suppliers lacking captive sourcing.
Pricing Analysis
Cost-plus contracts indexed to soy and sunflower lecithin futures dominate phospholipid procurement, with hydrogenated grades carrying ISO 16128 certification premiums over standard technical offerings. Price differentiation hinges on lamellarity documentation and REACH registration status, with sterile production protocols adding further tier separation. Pricing pressure stems from agricultural commodity cycles compressing mid-tier margins, while premium clinic-grade buyers show lowest price sensitivity given liability-driven specification requirements.
Supply Chain Analysis
Tariff exposure between European Union member states and third-country lecithin sources dominates supply chain risk planning for cosmetic houses. Production clusters in Germany, the Netherlands, and South Korea feed regional formulation demand, with soy and sunflower lecithin feedstocks and hydrogenation catalysts as critical dependencies. Single-source vulnerability in technical-grade lipid compounding creates geographic concentration risk, while distribution runs through specialty chemical distributors serving pharmacy chains and direct-to-consumer subscription fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemists with vesicle engineering expertise remain scarce across the industry, extending R&D timelines and compressing competitive response rates for novel delivery architectures. This capability gap rewards early investments in specialized talent pipelines and sterile production infrastructure.
For Market Incumbents: Insulate margin pools by securing captive phospholid sourcing through backward integration into hydrogenated lecithin production, countering agricultural commodity volatility that threatens mid-tier suppliers. Accelerate REACH dossier preparation for sub-100nm vesicle variants ahead of potential nanomaterial reclassification, converting regulatory uncertainty into competitive moats against less-resourced rivals.
For New Entrants and Emerging Players: Establish a beachhead in India's domestic cosmetic manufacturing corridor, where PLI scheme incentives reduce capital barriers for technical-grade lipid compounding capacity. Target professional channel gel formats for clinic-administered treatments, where controlled-release positioning commands premium spreads above retail price bands and education-heavy purchasing decisions favor sustained brand relationships.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale specialists with documented vesicle engineering expertise and existing sterile production infrastructure, as these assets compound scarcity value across the projection horizon. Watch ECHA nanomaterial definition consultations as the critical inflection signal: mandatory safety dossier requirements would force portfolio-wide reformulation and consolidate advantage among pre-registered suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phospholipid Sourcing | Captive hydrogenated lecithin production insulates Croda and Lucas Meyer Cosmetics from agricultural commodity cycles. |
| REACH Registration Dossier Preparation | Pre-registration of sub-100nm vesicle variants ahead of ECHA nanomaterial reclassification protects existing portfolio value. |
| Microfluidic Manufacturing Platform Adoption | South Korean and Swiss manufacturers deploy continuous-flow processing to reduce batch-to-batch variability in peptide encapsulation. |
| Professional Channel Gel Format Expansion | Swiss clinic-grade manufacturers build carbomer-thickened controlled-release systems for post-procedure recovery protocols. |
| ISO 16128 Natural Origin Certification | Plant-derived phospholipid platforms qualify for clean-beauty positioning in premium German pharmacy and subscription channels. |
Research Methodology
Operator-level perspectives from formulation chemists, sterile production facility managers, cosmetic regulatory affairs leads, and specialty chemical procurement directors anchored the qualitative base for this study. Primary interview insights combined with secondary validation from ECHA REACH registration databases, MFDS cosmetic safety assessment filings, ISO 16128 certification records, and customs trade data for phospholipid imports. Bottom-up triangulation across manufacturing capacity estimates and top-down reconciliation against end-use demand patterns ensured cross-verified outputs.
Scenario-bracketing around regulatory reclassification timelines and agricultural commodity price bands structured the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, formulation viscosity class, end-user gender positioning, and distribution channel type, with CAGRs derived from trend extrapolation against documented capacity expansion announcements. Peptide-hyaluronic acid co-encapsulation adoption curves and microfluidic platform penetration rates served as industry-specific demand indicators.
Stress conditions across ECHA nanomaterial definition outcomes, phospholipid input cost volatility bands, and professional channel growth trajectories were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory timelines and technology adoption rates, with continuous validation against operating reality the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Chemicals
Minoxidil Market
Cosmetic Chemicals
Gemstone Cosmetics Powder Market
Cosmetic Chemicals
Ethylhexylglycerin for Cosmetics Market
Cosmetic Chemicals
Cosmetic Based Preservatives Market
Cosmetic Chemicals
Cosmetic Ingredients Polymers Market
Cosmetic Chemicals
Cosmetic Dropper Market
Cosmetic Chemicals
Arbutin for Cosmetics Market
Cosmetic Chemicals
Global Mineral Cosmetics Market
Cosmetic Chemicals
Personal Care Chemicals Market
Cosmetic Chemicals
Cosmetic UV Absorbers Market
Cosmetic Chemicals
UV Nail Gel Polish Market
Cosmetic Chemicals
US Dead Sea Mud Cosmetics Market
Cosmetic Chemicals
Cosmetic Grade Warming Agents Market
Cosmetic Chemicals
Cosmetic Kaolin Powder Market
Cosmetic Chemicals
Global Hyaluronic Acid Based Dermal Fillers Market
Cosmetic Chemicals
Canada Eyeshadow Stick and Blush Stick Market