
 Continuously Sterilized Product Market | 2026-2036
Continuously Sterilized Product Market Size, Share, and Industry Trends Forecast 2026-2036
Continuously Sterilized Product Market Insights
Hospital purchasing of continuously sterilized surgical instruments is recalibrating toward disposable-ready formats that eliminate onsite reprocessing bottlenecks. STERIS Corporation leverages its installed base of sterilization equipment to anchor recurring consumable revenue streams. Getinge AB competes through integrated workflow systems that bridge sterile processing departments with operating room logistics.
Continuously sterilized products are medical devices terminally sterilized by validated processes such as steam at 121°C–134°C, ethylene oxide gas, or gamma irradiation at 25–45 kGy, then sealed in barrier packaging to maintain sterility until point of use. Syringes and catheters dominate volume due to high-frequency consumption in infusion therapy and surgical access, while surgical instruments command premium positioning through complex geometries requiring ethylene oxide or radiation methods. Steam sterilization retains cost leadership for heat-stable commodities, though radiation is displacing ethylene oxide for temperature-sensitive polymers amid residue concerns.
FDA enforcement of updated 510(k) sterilization validation requirements and EU MDR technical documentation for reusable device reprocessing shape product development timelines and market access conditions. EPA air emissions rules for ethylene oxide sterilization facilities in the United States and REACH authorization pressures in Europe redirect facility investment toward electron beam and x-ray alternatives. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded capacity in sterilization infrastructure.
Market Dynamics
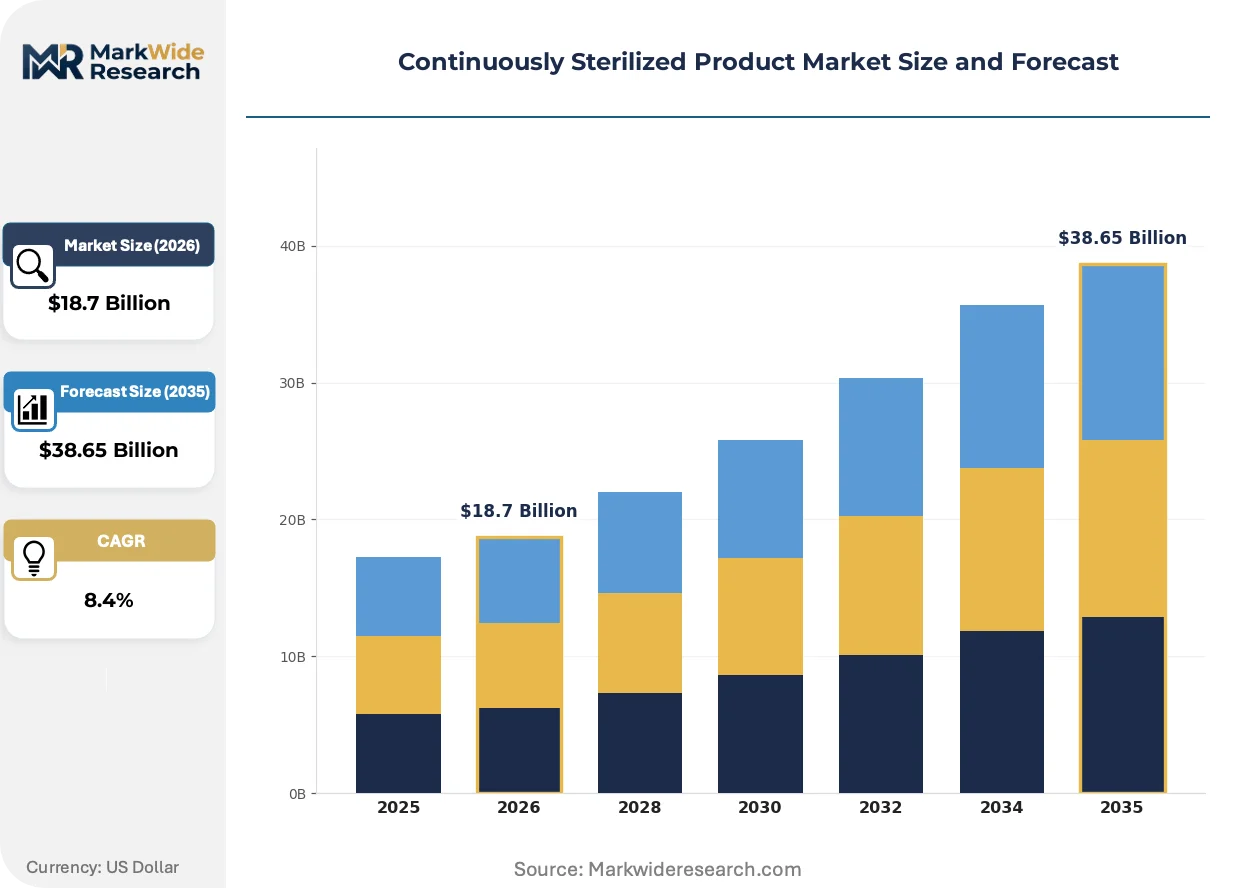
The Continuously Sterilized Product Market pivots on the EPA's ethylene oxide emissions crackdown, which forces sterilization facilities toward electron beam and x-ray alternatives while hospitals accelerate single-use procurement to eliminate onsite reprocessing liabilities.
Growth Catalysts
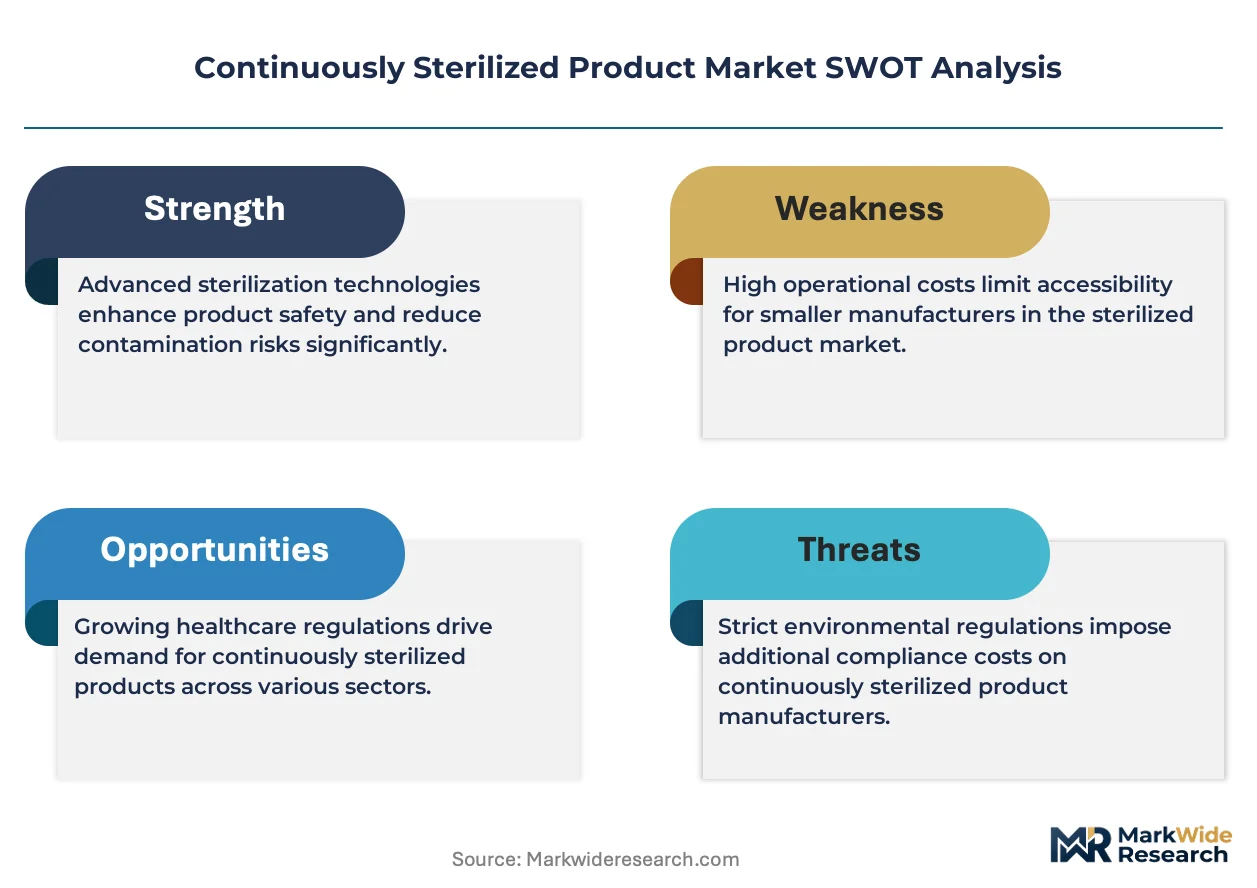
- EPA Facility Standards:The EPA's tightened National Emission Standards for Hazardous Air Pollutants for commercial sterilizers is redirecting capital toward electron beam infrastructure, expanding capacity for temperature-sensitive polymer devices.
- EU MDR Technical Documentation:The Medical Device Regulation's reprocessing validation requirements for reusable instruments is driving terminal sterilization preference for complex surgical instruments in German and French hospitals.
- Centralized Healthcare Procurement:China's National Healthcare Security Administration volume-based purchasing is consolidating demand for pre-sterilized syringes and catheters among tier-three hospital networks.
Market Restraints
- Cobalt-60 Supply Concentration:Gamma irradiation dependence on Canadian and Russian cobalt-60 isotope supply creates vulnerability for radiation-sterilized polymer device manufacturers.
- Ethylene Oxide Residue Limits:EU ECHA REACH authorization thresholds for residual ethylene oxide in medical devices below 0.5 ppm is forcing process revalidation and extended aeration cycles.
- Steam Sterilization Temperature Constraints:Heat-labile bioresorbable polymers in advanced wound care cannot withstand 121°C steam sterilization, restricting commodity sterilization method application.
Strategic Opportunities
- X-ray Sterilization Infrastructure:Underdeveloped electron beam and x-ray sterilization capacity in India presents first-mover advantage for contract sterilization operators serving domestic medical device manufacturers.
- Home Infusion Therapy Expansion:Ambulatory care migration is creating demand for unit-dose pre-sterilized infusion sets and closed-system transfer devices outside acute care settings.
- ISO 11137-1 Harmonization:Global convergence on radiation sterilization dose-setting standards is reducing multi-market validation burden for multinational device manufacturers.
Industry Challenges
- Sterilization Process Engineer Shortage:Specialized expertise in electron beam dose mapping and validation protocol development is scarce relative to facility expansion timelines.
- Legacy Ethylene Oxide Facility Stranded Assets:EPA-mandated abatement system retrofits on aging EtO infrastructure in the US Midwest is compressing facility utilization rates during compliance transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Continuously Sterilized Product Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Syringes, Catheters, Surgical Instruments, IV Sets End User: Hospitals, Clinics, Research Labs, Pharmacies Application: Surgical, Diagnostic, Infusion Therapy, Wound Care Technology: Steam Sterilization, Ethylene Oxide, Radiation, Chemical Agents |
| Companies Covered | STERIS Corporation, Getinge AB, Solventum, Fortive, Advanced Sterilization Products, 3M Company, Sotera Health, Cardinal Health, MMM Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Continuously Sterilized Product Market Trends and Innovations
Electron beam sterilization is rewriting competitive positioning in polymer-intensive device categories while regulatory divergence between EPA emissions enforcement and EU MDR documentation requirements is fragmenting validation strategies across Atlantic markets.
Nitrogen oxide-based low-temperature sterilization is rewriting terminal sterilization feasibility for temperature-sensitive biologics and drug-device combination products. Cell and gene therapy manufacturers are piloting NO2-based processes for personalized medicine delivery systems. The technology is rewriting capital allocation patterns as venture-backed sterilization service providers build NO2 capacity adjacent to biopharma clusters.
The EU F-Gas Regulation phase-down of hydrofluorocarbon-based sterilization alternatives is compressing options for heat-sensitive devices that cannot tolerate radiation. Medical device manufacturers with EU market exposure are accelerating validation of electron beam processes for previously EtO-dependent product lines. German notified bodies are experiencing backlog in novel sterilization method equivalency assessments.
Hospital supply chain managers are consolidating vendor relationships for pre-sterilized procedure kits rather than maintaining parallel sterile processing departments. Integrated delivery networks in the United States are negotiating multi-year sole-source agreements with sterilization service providers for complete category management. The shift is most pronounced in cardiovascular and orthopedic procedure kits where kit complexity favors outsourced sterilization expertise.
Continuously Sterilized Product Market Segmentation
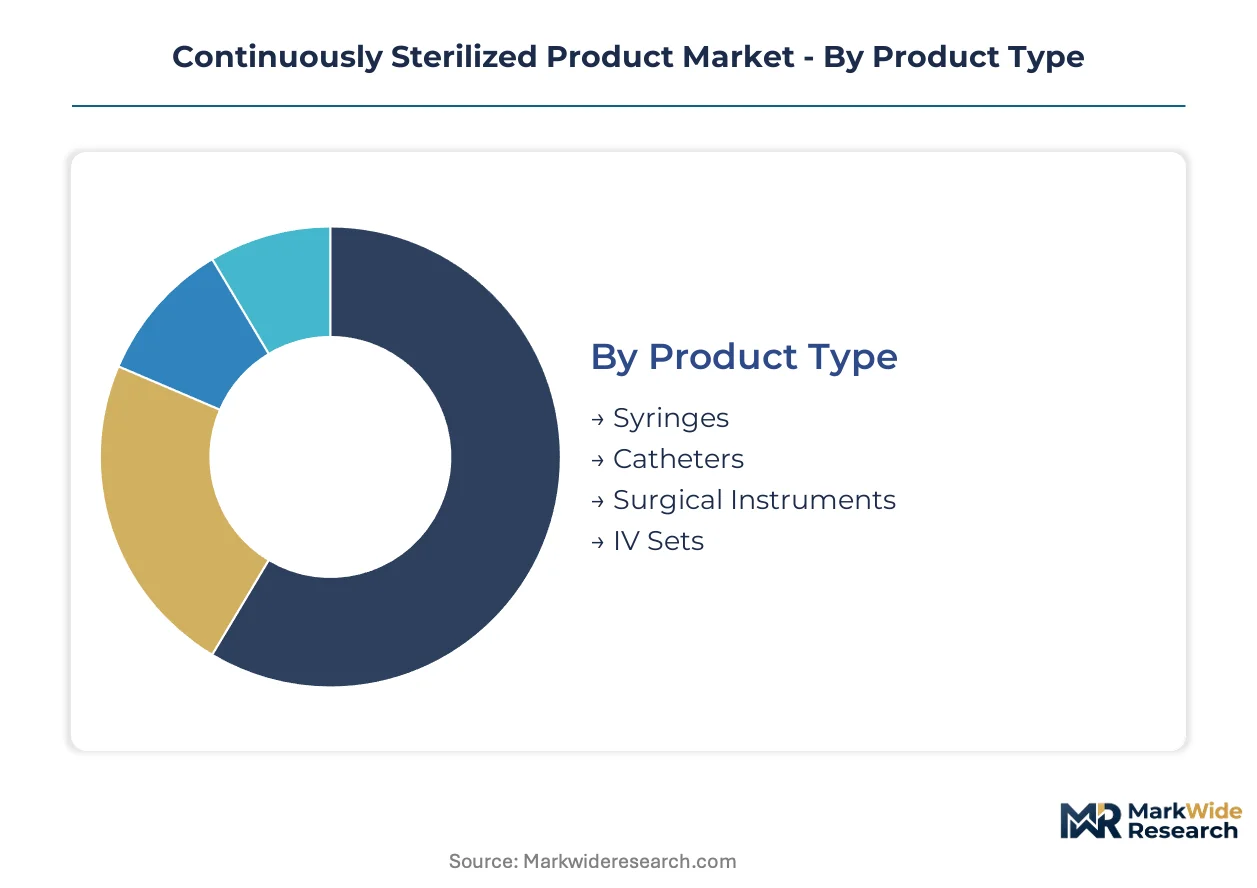
Segmentation in continuously sterilized products reveals how procurement patterns diverge between high-volume commodity devices and complex instrument categories requiring specialized sterilization validation. Product managers must align sterilization modality selection with each segment's thermal tolerance, regulatory pathway, and end-user workflow constraints.
Product Type:
Standardization dominates syringe and catheter manufacturing, while surgical instruments demand customization for procedural-specific geometries and material compositions.
- Syringes:Polypropylene barrels and rubber plungers withstand gamma irradiation at 25–45 kGy, enabling terminal sterilization without residue concerns. China's National Healthcare Security Administration volume-based purchasing concentrates procurement among three domestic manufacturers supplying tier-three hospital networks.
- Catheters:Polyurethane and silicone extrusions for vascular and urinary access require ethylene oxide or radiation methods due to temperature sensitivity. German hospitals are consolidating procurement of pre-sterilized catheter kits to eliminate onsite sterile processing department bottlenecks.
- Surgical Instruments:Complex geometries in stainless steel and polymer composites necessitate ethylene oxide or radiation validation protocols.
- IV Sets:Tubing assemblies with multiple connection points leverage gamma sterilization for polymer compatibility.
Most installed capacity flows through syringes. Expansion is steepest in surgical instruments.
End User:
Cost tier separation distinguishes capital-intensive hospital procurement from price-sensitive clinic and pharmacy purchasing patterns.
- Hospitals:Integrated delivery networks in the United States negotiate multi-year sole-source agreements for complete category management of procedure kits. STERIS Corporation anchors recurring consumable revenue through installed sterilization equipment bases in surgical centers.
- Clinics:Ambulatory surgery centers prioritize disposable-ready formats that eliminate reprocessing infrastructure investment. Outpatient migration is creating demand for unit-dose pre-sterilized infusion sets outside acute care settings.
- Research Labs:Cell and gene therapy manufacturers pilot nitrogen oxide-based sterilization for personalized medicine delivery systems.
- Pharmacies:Home infusion therapy expansion drives retail procurement of closed-system transfer devices.
Hospital procurement absorbs the majority of sterilization service capacity. Pharmacy channels are gaining share fastest through home infusion expansion.
Application:
Volume concentration in infusion therapy contrasts with margin concentration in surgical applications requiring complex kit configurations.
- Surgical:Cardiovascular and orthopedic procedure kits favor outsourced sterilization expertise due to component complexity. EU MDR technical documentation requirements for reusable instrument reprocessing drive terminal sterilization preference in French and German facilities.
- Diagnostic:Specimen collection devices and biopsy instruments require validated sterile barriers for point-of-care testing workflows.
- Infusion Therapy:High-frequency consumption of syringes and IV sets dominates unit volume across all geographies.
- Wound Care:Heat-labile bioresorbable polymers restrict commodity sterilization method application.
Infusion therapy commands the largest volume throughput. Surgical applications show the steepest margin expansion trajectory.
Technology:
Supply concentration in gamma irradiation contrasts with emerging capacity buildout in electron beam and x-ray alternatives.
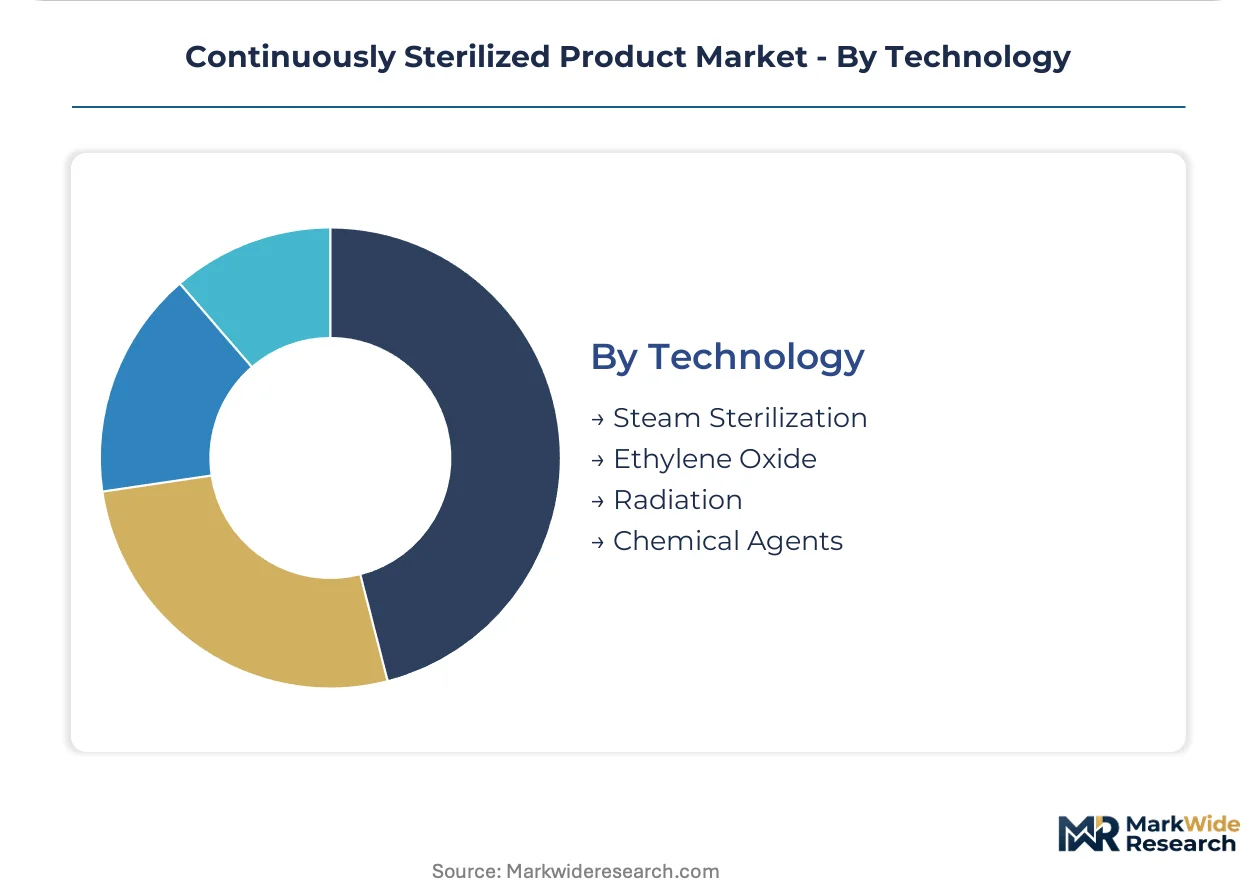
- Steam Sterilization:Cost leadership for heat-stable commodities at 121°C–134°C retains dominance in syringe and metal instrument categories. EPA emissions enforcement does not constrain steam infrastructure.
- Ethylene Oxide:Residual limits below 0.5 ppm under EU ECHA REACH authorization force extended aeration cycles and process revalidation. EPA National Emission Standards for Hazardous Air Pollutants are redirecting US capital toward alternatives.
- Radiation:Gamma irradiation at 25–45 kGy serves temperature-sensitive polymers, though Canadian and Russian cobalt-60 isotope supply creates vulnerability. Electron beam displacement is accelerating for previously EtO-dependent product lines.
- Chemical Agents:Nitrogen oxide-based low-temperature processes are rewriting feasibility for biologics and drug-device combinations.
Steam sterilization retains the largest installed base. Electron beam and x-ray alternatives are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sterilization service providers are relocating capacity across jurisdictions to exploit gaps in EPA enforcement timelines and EU MDR documentation requirements. The United States, Germany, and China absorb the majority of pre-sterilized device procurement, though emerging capacity buildouts in India and Mexico are redirecting contract manufacturing flows.
United States
Integrated delivery networks in Texas and Florida are consolidating vendor relationships for cardiovascular procedure kits. EPA National Emission Standards for Hazardous Air Pollutants enforcement is forcing Midwest sterilization facilities toward abatement retrofits or closure. Minneapolis-St. Paul hosts STERIS Corporation's equipment manufacturing base, anchoring recurring consumable revenue streams across surgical center networks.
Germany
University hospitals in Bavaria and North Rhine-Westphalia are eliminating onsite sterile processing departments through pre-sterilized kit procurement. EU MDR technical documentation requirements for reusable instrument reprocessing drive terminal sterilization preference in Frankfurt and Stuttgart clusters. Getinge AB competes through integrated workflow systems bridging sterile processing with operating room logistics.
China
Tier-three hospital networks in Jiangsu and Zhejiang provinces concentrate demand under National Healthcare Security Administration volume-based purchasing. Domestic syringe manufacturers in the Yangtze River Delta are scaling gamma irradiation capacity for polypropylene device exports. Shanghai's contract sterilization infrastructure serves multinational device makers seeking cost-advantaged terminal processing.
India
Domestic medical device manufacturers in Maharashtra and Karnataka are underserved by electron beam sterilization capacity. CDSCO medical device rules are converging toward ISO 11137-1 harmonization, reducing multi-market validation burdens for exporters. Hyderabad's biopharma corridor is attracting venture-backed sterilization service providers building NO2 capacity adjacent to cell therapy manufacturing.
Mexico
Maquiladora operations in Baja California and Chihuahua are expanding catheter and IV set assembly for US market access. COFEPRIS medical device registration alignment with FDA 510(k) pathways accelerates cross-border sterilization validation. Tijuana's contract manufacturers are integrating terminal sterilization to capture value previously exported to US facilities.
Continuously Sterilized Product Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with equipment-anchored recurring revenue models dominating hospital procurement while pure-play sterilization services capture ambulatory surgery center volume. Market structure tilts toward consolidation among integrated sterilization equipment and consumable providers, with fragmentation persisting in regional contract sterilization services. Three archetypes define competitive positioning: capital equipment incumbents with captive consumable streams, pure-play contract sterilization operators, and diversified healthcare conglomerates with sterilization divisions. Capacity expansion in electron beam infrastructure and strategic partnerships bridging sterile processing with operating room logistics represent the dominant competitive moves.
Among US-based diversified healthcare conglomerates, 3M Company and Cardinal Health occupy positions spanning multiple sterilization-adjacent categories. STERIS Corporation exemplifies the equipment-anchored archetype through its installed base of sterilization systems. Getinge AB represents Swedish-based integrated workflow specialists competing across sterile processing department automation.
| Leading Market Players |
|---|
| STERIS Corporation |
| Getinge AB |
| Solventum |
| Fortive |
| Advanced Sterilization Products |
| 3M Company |
| Sotera Health |
| Cardinal Health |
| MMM Group |
| Others |
Pricing and Supply Chain Analysis
Hospital procurement consolidation under China's National Healthcare Security Administration volume-based purchasing is forcing sterilization service providers to absorb margin compression while scaling electron beam capacity to meet residue-free specifications. This demand-side pressure reshapes how contract manufacturers in India and Mexico price terminal sterilization services relative to legacy ethylene oxide infrastructure.
Pricing Analysis
Distributor markups on pre-sterilized procedure kits compress as integrated delivery networks negotiate direct-to-manufacturer contracts for cardiovascular and orthopedic categories. Price differentiation rests on ISO 11137-1 validation tier and gamma irradiation dose-mapping certification, with premium positioning attached to electron beam alternatives. Cost compression in standard syringe and catheter tiers intensifies because of Chinese domestic manufacturer oversupply. Ambulatory surgery centers exhibit highest price sensitivity, while German university hospitals prioritize validated sterile barriers over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from tier-three hospital networks in Jiangsu and Zhejiang provinces, bypassing traditional distribution layers. Manufacturing concentrates in China for polypropylene syringes, Germany for complex surgical instruments, and Mexico for catheter assembly serving US market access. Raw material flows draw from Canadian and Russian cobalt-60 isotope supply for gamma irradiation, polypropylene resin from Saudi petrochemical complexes, and polyurethane extrusions from US specialty chemical producers. Single-source vulnerability in cobalt-60 creates concentration risk for radiation-sterilized polymer device manufacturers. Distribution runs through sterilization service providers co-located with device manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The continuously sterilized product market represents a late-cycle quality story as EU MDR technical documentation requirements and EPA emissions enforcement elevate premium specifications for residue-free sterilization validation.
For Market Incumbents: Deepen backward integration into electron beam infrastructure to offset stranded asset risk in legacy ethylene oxide facilities facing EPA-mandated abatement retrofits. Anchor recurring consumable revenue through sole-source agreements with integrated delivery networks for complete procedure kit category management. For New Entrants and Emerging Players: Contract sterilization operators in India present the most penetrable white-space target, given underdeveloped electron beam capacity relative to Maharashtra and Karnataka medical device manufacturing growth. Pursue CDSCO-aligned ISO 11137-1 validation pathways to reduce multi-market registration burdens for domestic exporters. For Investors and Strategic Acquirers: Asymmetric upside sits with venture-backed sterilization service providers building nitrogen oxide capacity adjacent to Hyderabad's cell therapy manufacturing corridor. Long-term viability hinges on regulatory divergence arbitrage between EPA enforcement timelines and EU MDR documentation requirements. Monitor German notified body backlog in novel sterilization method equivalency assessments as inflection indicator for electron beam displacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Electron Beam Infrastructure Buildout | EPA emissions enforcement redirects capital toward residue-free alternatives for temperature-sensitive polymers. |
| Hospital System Partnership | Integrated delivery networks consolidate vendor relationships for complete pre-sterilized procedure kit categories. |
| CE Marking Pathway Investment | EU MDR technical documentation requirements drive terminal sterilization preference in German and French facilities. |
| Backward Integration into Cobalt-60 Supply | Canadian and Russian isotope concentration creates vulnerability for gamma-dependent device manufacturers. |
| Software Companion Development | Dose mapping and validation protocol automation addresses scarce electron beam process engineering expertise. |
Research Methodology
Multiple input streams — sterilization facility operators, hospital procurement committees, biomedical engineers, GPO contracts managers, and regulatory affairs specialists — were reconciled against FDA 510(k) filings, EPA emissions compliance databases, EU MDR technical documentation, and hospital procurement contract records. Bottom-up demand modeling across syringe, catheter, surgical instrument, and IV set categories was cross-validated with top-down capacity assessments from gamma irradiation and electron beam facility operators.
Historical volume trajectories were cross-referenced against panel input from sterile processing department directors and contract sterilization executives to anchor growth assumptions across the projection horizon. Segmentation dimensions modeled include product type, end user tier, application workflow, sterilization technology modality, and regional regulatory cluster. CAGRs were derived from weighted capacity expansion schedules and procurement volume commitments, with specific incorporation of EPA National Emission Standards compliance timelines and EU ECHA REACH authorization thresholds.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to cobalt-60 supply disruptions, electron beam process engineer scarcity, and regulatory divergence between EPA enforcement and EU MDR implementation. Outputs reflect documented assumptions regarding sterilization modality substitution rates and hospital procurement consolidation velocity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Disinfectants and Preservatives
Antimicrobial Chemicals Market
Disinfectants and Preservatives
Latin America Cosmetic Preservatives Market
Disinfectants and Preservatives
Global Fusidic Acid Market
Disinfectants and Preservatives
United States Hydrogen Peroxide Market
Disinfectants and Preservatives
North America Hydrogen Peroxide Market
Disinfectants and Preservatives
Surface Disinfectant Products Market
Disinfectants and Preservatives
Diquat Dibromide Market
Disinfectants and Preservatives
MMA Triazine Market
Disinfectants and Preservatives
Global Sodium Metabisulphite Market
Disinfectants and Preservatives
Europe Hydrogen Peroxide Market
Disinfectants and Preservatives
Disinfection Cap Market
Disinfectants and Preservatives
Surface Disinfectants Market
Disinfectants and Preservatives
North America Disinfectant Wipes Market
Disinfectants and Preservatives
Halogen Biocides Market
Disinfectants and Preservatives
Sodium Bisulphite Market
Disinfectants and Preservatives
Global Potassium Sorbate Market